
 Biological Control Market | 2026-2036
Biological Control Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Control Market Analysis
Modular biocontrol service bundling is recalibrating how commercial growers procure pest management solutions. Bayer Crop Science leverages its seed treatment integration to anchor microbial delivery systems across major row-crop regions. Certis Biologicals specializes in niche biofungicide formulations for high-value fruit and vegetable segments. Koppert Biologicals dominates beneficial insect production capacity in European greenhouse corridors.
Biological control encompasses living organisms or their derivatives deployed to suppress pest populations below economic injury thresholds, with formulations typically requiring viability preservation within specified temperature ranges and shelf-life windows. The approach serves primary agricultural and horticultural systems by reducing synthetic pesticide dependency while maintaining yield protection. Microbial biopesticides occupy the largest value pool due to scalable fermentation manufacturing and broader regulatory familiarity, while beneficial insects command premium positioning in controlled-environment agriculture where labor-intensive release protocols are economically justified. Biofungicides are gaining structural traction in organic and transition-acreage segments where residue restrictions tighten procurement standards.
The EPA registers microbial pesticides under distinct data requirements compared to conventional chemicals, while the EU's Sustainable Use Regulation phases out priority hazardous substances and elevates biocontrol substitution mandates. India's Central Insecticides Board adapts registration pathways under evolving PLI scheme incentives for domestic biological manufacturing. Stakeholders must monitor how regulatory equivalence agreements between jurisdictions reshape export market access for regionally produced biocontrol agents.
Market Dynamics
Resistance pressure from synthetic pesticide overuse is compressing grower tolerance thresholds and forcing accelerated biocontrol integration into standard agronomic protocols across major agricultural corridors.
Growth Catalysts
- EU Green Deal substitution mandates:The Farm to Fork strategy imposes binding reduction targets for chemical pesticide application, compelling large-scale acreage conversion to microbial and macrobial biocontrol systems.
- Brazilian soybean resistance protocols:Tightening rotation requirements for synthetic chemistries in the Cerrado and southern states is expanding contract biocontrol service adoption among integrated producers.
- California specialty crop labor dynamics:Rising hand-weeding costs and restricted fumigant access in Central Valley tree nut and vegetable operations is elevating beneficial insect release economics.
Market Restraints
- Cold chain infrastructure gaps:Viable microbial formulations require uninterrupted temperature-controlled distribution, which remains underdeveloped in interior agricultural regions of India and sub-Saharan Africa.
- Technical shelf-life limitations:Living organism stability windows constrain inventory holding periods and complicate distributor stocking strategies for seasonal application timing.
- Registration pathway fragmentation:Divergent data requirements between EPA microbial pesticide standards and EU 1107/2009 equivalence protocols generate duplicative compliance costs for multi-territory launches.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Domestic production subsidies under the Production Linked Incentive framework for biologicals reduce import dependency and enable cost-competitive export positioning toward Southeast Asian markets.
- Greenhouse controlled-environment expansion:Protected cultivation acreage growth in the Netherlands, Spain, and Mexico creates concentrated demand nodes where labor-intensive beneficial insect protocols achieve unit economic viability.
- Seed treatment integration convergence:Coating technologies combining microbial inoculants with conventional fungicides are opening row-crop penetration pathways previously resistant to standalone biocontrol adoption.
Industry Challenges
- Entomological expertise scarcity:Commercial-scale beneficial insect rearing and field release timing requires specialized technical knowledge that outpaces current agricultural extension training capacity in expanding biocontrol markets.
- Integration complexity with precision application equipment:Existing spray infrastructure calibrated for synthetic chemistries demands retrofit or replacement to handle living organism sensitivity to pressure, temperature, and tank-mix compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Control Market |
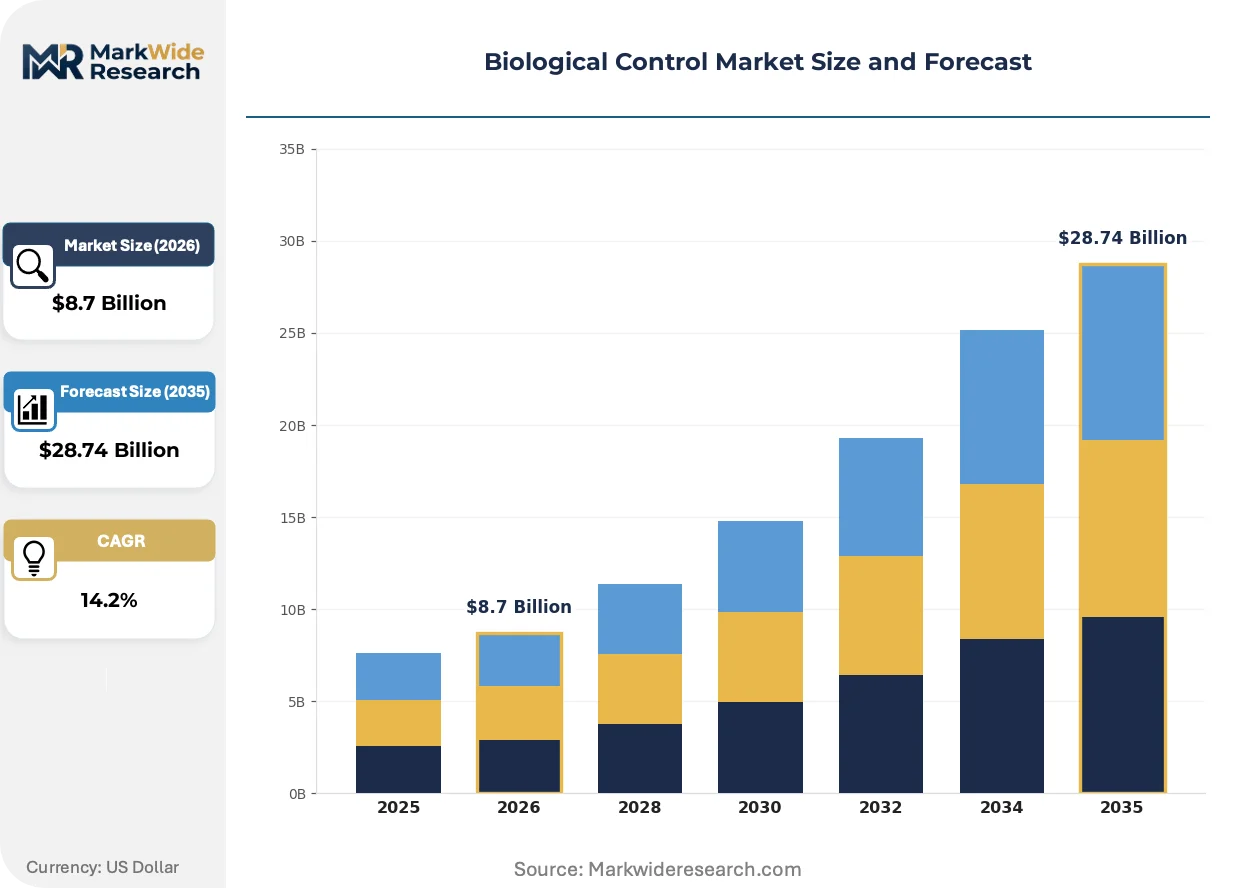
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Biopesticides, Beneficial Insects, Biofungicides, Bioherbicides Application: Agricultural Crops, Greenhouse Cultivation, Horticulture, Forestry End User: Farmers, Commercial Growers, Landscaping Companies, Research Institutions Distribution Channel: Online Retail, Conventional Stores, Distributors, Agricultural Cooperatives |
| Companies Covered | Bayer Crop Science, Certis Biologicals, Koppert Biological Systems, Corteva Agriscience, Valent BioSciences, Biobest Group, Syngenta, Marrone Bio Innovations, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Control Market Emerging Trajectories
Formulation science advances are extending organism viability windows and enabling biocontrol deployment through channels previously restricted to synthetic chemistry. These developments are compressing the performance gap that has historically limited biological adoption in broad-acre row crops.
RNA interference biopesticides are absorbing research investment from major agrochemical pipelines as a precision-targeted modality with reduced off-target ecological impact. Large-scale corn and soybean operators in the US Midwest are piloting foliar applications at scale. The technology is absorbing regulatory scrutiny from EPA and EFSA as novel food/feed residue questions delay commercialization timelines.
REACH authorization restrictions on candidate list substances are accelerating biocontrol substitution in European horticulture. The regulation forces withdrawal of several conventional fungicide actives from vine and orchard applications. Greenhouse operators in Almería and Huelva are restructuring procurement to secure multi-year microbial supply contracts ahead of anticipated further substance prioritization.
Service-based contracting is displacing product-only transactions as dominant commercial terms in high-value crop segments. Integrated pest management providers in California and Florida are bundling monitoring, release, and efficacy guarantee provisions into annual agreements. This model concentrates buyer relationships with technical service-capable suppliers and marginalizes commodity biocontrol distributors.
Biological Control Market Segmentation
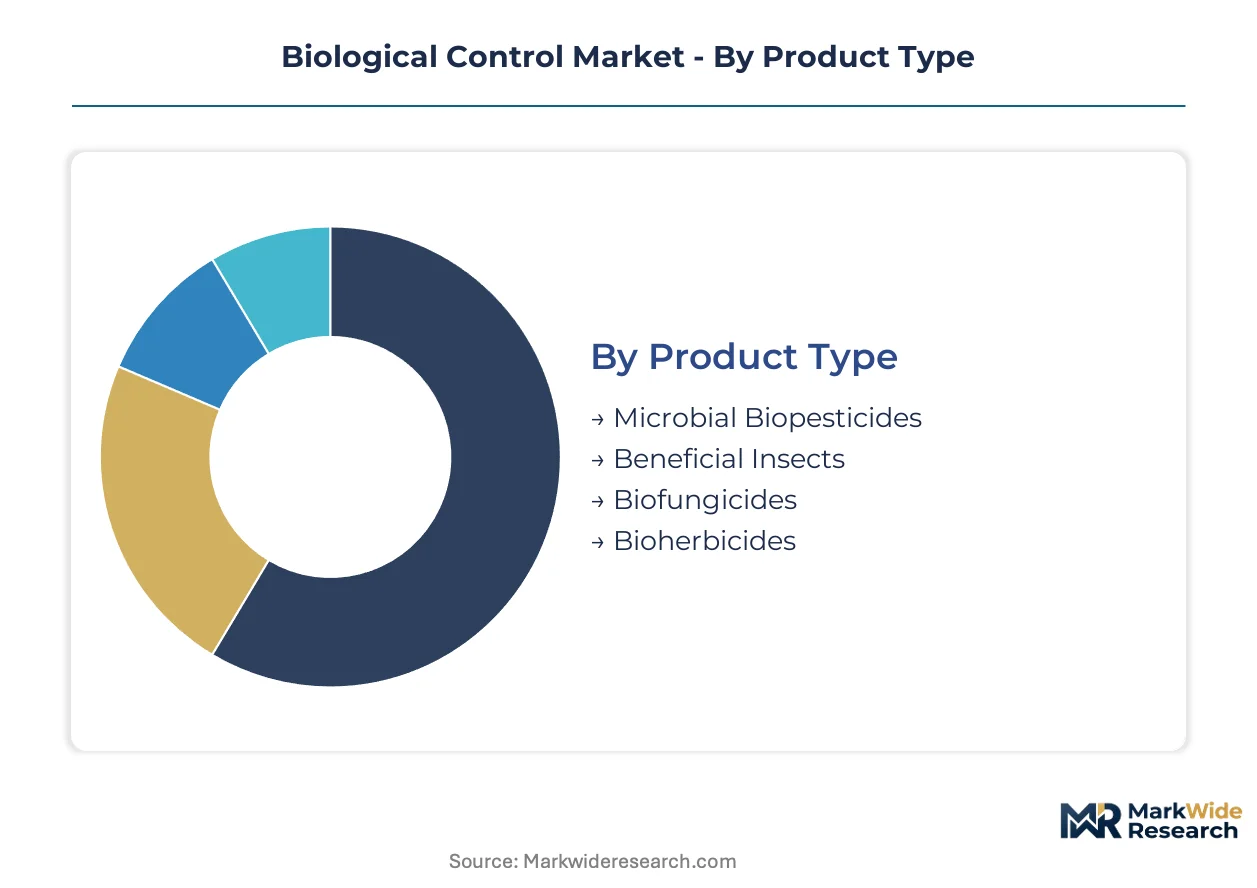
Biological control procurement patterns diverge sharply across product formats, application environments, and buyer sophistication levels. Segmentation reveals where fermentation-scale manufacturing meets labor-intensive field protocols, and which distribution channels can sustain cold-chain viability requirements.
Product Type:
Technical specifications governing organism viability, storage temperature windows, and application methodology define competitive positioning across product categories.
- Microbial Biopesticides:Bacterial and fungal formulations produced through scalable fermentation processes dominate volume deployment. Demand concentrates in Brazil's soybean belt where Bayer Crop Science integrates microbial seed treatments into resistance management protocols. EPA registration familiarity accelerates multi-territory launches compared to macrobial alternatives.
- Beneficial Insects:Mass-reared parasitoids and predators require specialized rearing facilities and precise release timing. Koppert Biologicals commands European greenhouse corridors where labor costs justify intensive protocols in Almería and Huelva vegetable operations. Shelf-life constraints limit distribution radius from production facilities.
- Biofungicides:Microbial antagonists targeting soilborne and foliar pathogens gain traction in organic transition acreage. REACH authorization restrictions on conventional fungicides accelerate substitution in European vineyard and orchard applications.
- Bioherbicides:Phytopathogenic fungi and bacteria deployed for weed suppression remain commercially underdeveloped. Technical challenges in host-range specificity and environmental persistence constrain adoption beyond niche organic segments.
Mature deployment sits with microbial biopesticides. Newer deployment is concentrated in beneficial insects as greenhouse controlled-environment acreage expands.
Application:
Economic injury thresholds and labor cost structures determine where biological control unit economics achieve viability against synthetic alternatives.
- Agricultural Crops:Row-crop integration advances through seed treatment coating technologies that merge microbial inoculants with conventional chemistries. Large-scale corn and soybean operators in the US Midwest pilot foliar RNA interference applications.
- Greenhouse Cultivation:Protected environment agriculture creates concentrated demand nodes where release protocols achieve precision. Netherlands, Spain, and Mexico expansion drives contract biocontrol service bundling with monitoring and efficacy guarantees.
- Horticulture:High-value fruit and vegetable segments prioritize residue compliance over per-hectare input costs. Certis Biologicals specializes in niche biofungicide formulations for this price-insensitive segment.
- Forestry:Long rotation cycles and limited intervention frequency restrict biological control economics. Public land management agencies deploy microbial formulations for invasive pest suppression in limited outbreak scenarios.
Revenue concentration aligns with greenhouse cultivation. Steepest expansion trajectory is emerging in agricultural crops as formulation science compresses the performance gap with synthetic chemistry.
End User:
Technical capability and capital access differentiate buyer segments capable of managing living organism applications from those requiring full-service provision.
- Farmers:Owner-operators in California's Central Valley expand beneficial insect releases as hand-weeding costs rise and fumigant access tightens. Technical knowledge gaps limit adoption without agricultural extension support.
- Commercial Growers:Integrated producers in Brazil's Cerrado adopt contract biocontrol services under tightening synthetic chemistry rotation requirements. Annual agreements bundle monitoring, release, and efficacy guarantees.
- Landscaping Companies:Urban and suburban maintenance operations face municipal pesticide restrictions. Limited technical expertise in entomology constrains in-house beneficial insect deployment.
- Research Institutions:University and government laboratories drive strain discovery and field efficacy validation. Public funding supports early-stage development that private manufacturers commercialize.
Procurement sophistication peaks with commercial growers. Emerging demand is concentrating among farmers as service-based contracting reduces technical barriers.
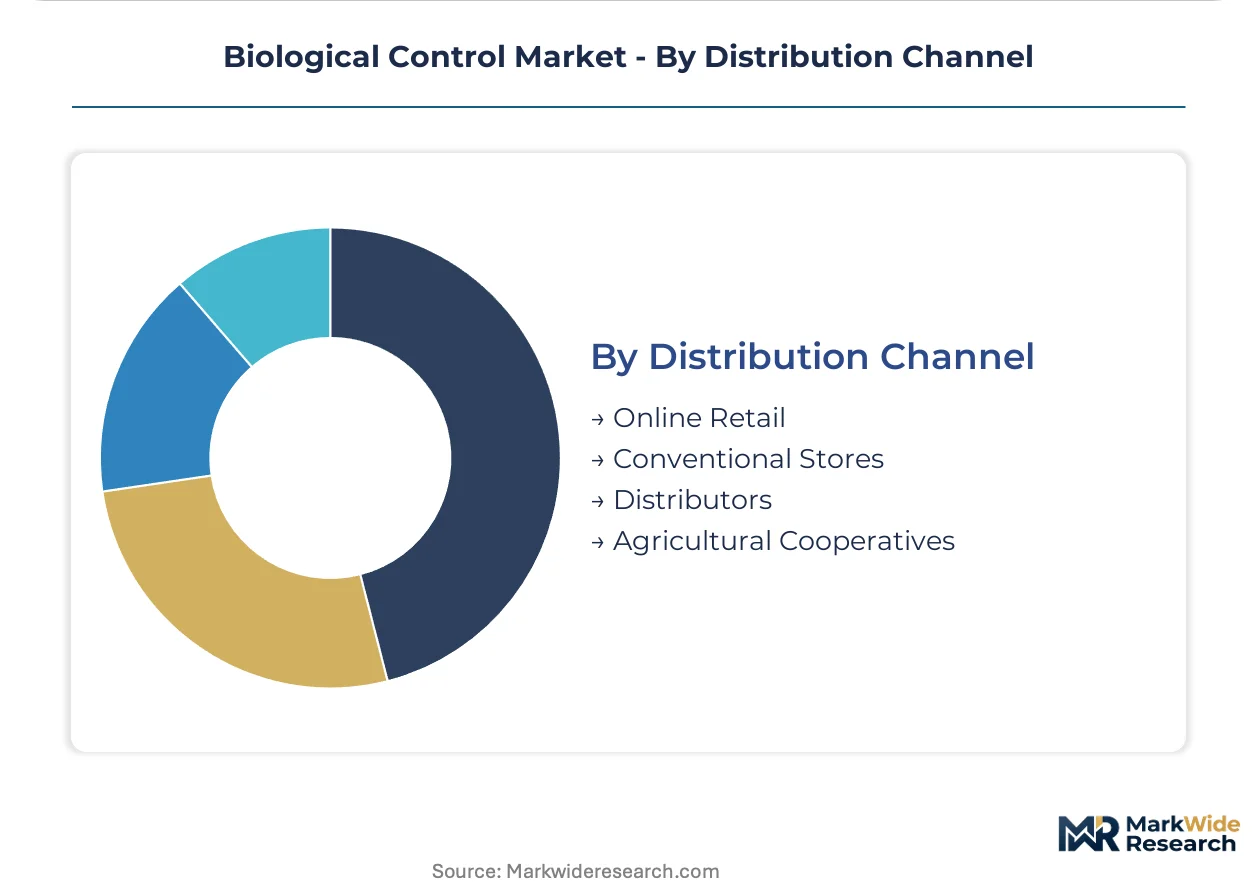
Distribution Channel:
Cold-chain infrastructure availability and inventory turnover velocity determine which channels can sustain viable organism distribution.
- Online Retail:Direct-to-grower platforms expand in developed markets with reliable logistics networks. Temperature-controlled shipping constraints limit reach to interior agricultural regions.
- Conventional Stores:Brick-and-mortar agricultural supply retailers stock limited shelf-stable formulations. Living organism products remain absent due to technical shelf-life limitations.
- Distributors:Specialized biocontrol distributors dominate beneficial insect and microbial product flows. Inventory holding periods and seasonal application timing complicate working capital requirements.
- Agricultural Cooperatives:Member-owned purchasing organizations aggregate demand for volume pricing. California and Florida cooperatives increasingly bundle integrated pest management services.
Channel concentration favors distributors. Emerging penetration is accelerating through agricultural cooperatives as member education reduces perceived risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biological control production concentrates in temperate-climate fermentation corridors, while consumption tilts toward pesticide-regulated agricultural belts in Brazil, the European Union, and California. Manufacturing scale advantages in the Netherlands and Germany supply greenhouse operators across Mediterranean Europe and Mexico.
United States
California's Central Valley specialty crop growers expand beneficial insect releases as hand-weeding costs escalate and soil fumigant access tightens. The EPA registers microbial pesticides under distinct data requirements that accelerate multi-territory launches compared to conventional chemistries. Fresno and Kern counties anchor contract biocontrol service bundling for tree nut and vegetable operations.
Brazil
Soybean belt integrated producers adopt microbial seed treatments under tightening synthetic chemistry rotation requirements in Mato Grosso and Paraná. ANVISA adapts registration pathways for biologicals as the national agricultural regulator accelerates import substitution incentives. The Cerrado region drives contract biocontrol service adoption among large-scale operators managing resistance protocols.
Germany
REACH authorization restrictions on candidate list substances accelerate biocontrol substitution in horticultural applications across Bavaria and Baden-Württemberg. The EU Green Deal's Farm to Fork strategy imposes binding reduction targets for chemical pesticide application. Almería and Huelva greenhouse operators in neighboring Spain source microbial supply contracts from German fermentation capacity.
India
Maharashtra and Gujarat horticultural clusters expand domestic biological manufacturing under PLI scheme production subsidies for agricultural inputs. The Central Insecticides Board adapts registration pathways to reduce import dependency on beneficial insects and microbial formulations. Karnataka's protected cultivation expansion creates concentrated demand nodes for technical service-capable suppliers.
Netherlands
Westland greenhouse corridors drive premium beneficial insect consumption where labor costs justify intensive release protocols. EFSA equivalence protocols with EPA standards enable Dutch manufacturers to serve North American specialty crop segments. Koppert Biological Systems anchors European production capacity for parasitoid and predator mass-rearing facilities.
Biological Control Market Vendor Landscape
The competitive structure tilts toward integrated agrochemical conglomerates with seed treatment platforms and specialized biologicals firms with fermentation expertise. Bayer Crop Science leverages seed treatment integration to anchor microbial delivery systems, while Certis Biologicals and Koppert Biologicals occupy niche formulation and beneficial insect tiers. Strategic moves concentrate on seed treatment coating convergence and multi-year microbial supply contracting ahead of regulatory phase-outs.
Within the integrated agrochemical tier, Bayer Crop Science and Corteva Agriscience represent scale-driven archetypes combining conventional chemistry portfolios with biological delivery platforms. Among specialized biologicals manufacturers, Koppert Biologicals exemplifies beneficial insect production concentration, while Certis Biologicals occupies niche biofungicide positioning for high-value horticultural segments. Marrone Bio Innovations and Valent BioSciences sit within the microbial fermentation specialist category serving row-crop and specialty crop applications respectively.
| Leading Market Players |
|---|
| Bayer Crop Science |
| Certis Biologicals |
| Koppert Biological Systems |
| Corteva Agriscience |
| Valent BioSciences |
| Biobest Group |
| Syngenta |
| Marrone Bio Innovations |
| BASF |
| Others |
Supply Flow & Price Mechanics
Entomological expertise concentration in the Netherlands and California creates labor-cost differentials that widen pricing-tier spreads between premium beneficial insect protocols and commodity microbial formulations. Cold-chain viability requirements and shelf-life constraints further stratify procurement economics across geographic corridors.
Pricing Analysis
Margin tightening in microbial biopesticide tiers reflects fermentation-scale manufacturing expansion in India and Brazil under PLI scheme incentives. Three-tier pricing structure across premium, standard, and economy levels separates Koppert's greenhouse parasitoid contracts from generic bacterial formulations. Price differentiation hinges on strain certification under EPA microbial pesticide standards and cold-chain integrity guarantees. Smallholder farmers in sub-Saharan Africa exhibit highest price sensitivity, while Dutch greenhouse operators absorb premium positioning for technical service bundling.
Supply Chain Analysis
Beneficial insect production rests on specialized mass-rearing facilities concentrated in the Netherlands, Spain, and California's Central Valley. Microbial formulation feedstocks draw from agricultural fermentation substrates and pharmaceutical-grade nutrient media. Single-source vulnerability sits with temperature-controlled distribution networks spanning interior agricultural regions of India and Brazil. Distribution runs through specialized biocontrol distributors holding inventory risk for seasonal application timing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beneficial insect production capacity constraints prop pricing premiums as greenhouse expansion outpaces entomological training pipeline output. Supply scarcity in technical service-capable suppliers concentrates buyer relationships with integrated pest management providers.
For Market Incumbents: Extend seed treatment integration platforms to capture row-crop microbial adoption accelerating through Brazil's Cerrado. Defend against RNA interference biopesticide substitution by accelerating strain patent filings. Prioritize backward integration into fermentation capacity in Maharashtra and Gujarat to reduce import dependency exposure.
For New Entrants and Emerging Players: Agricultural cooperatives in California and Florida represent the most penetrable channel archetype for service-based contracting models. White-space opportunity concentrates in sub-Saharan Africa where cold-chain gaps exclude established distributors. Pursue joint development agreements with precision application equipment manufacturers to overcome tank-mix compatibility barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with microbial fermentation specialists given EU Green Deal substitution mandates accelerating demand visibility. Long-term viability framing favors manufacturers with EPA-EFSA equivalence protocol navigation capabilities. Watch ANVISA registration pathway acceleration in Brazil as inflection indicator for import substitution momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Seed Treatment Integration | Bayer Crop Science anchors microbial delivery through coating convergence with conventional fungicides. |
| Multi-Year Supply Contracting | Almería greenhouse operators secure strain availability ahead of REACH authorization phase-outs. |
| Domestic Manufacturing Scale-Up | India PLI scheme subsidies enable cost-competitive export positioning toward Southeast Asian markets. |
| Technical Service Bundling | California IPM providers concentrate buyer relationships through monitoring and efficacy guarantee provisions. |
| RNA Interference Pipeline Investment | Major agrochemical R&D absorbs regulatory scrutiny from EPA and EFSA delaying commercialization timelines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with biocontrol manufacturing executives, agricultural extension specialists, greenhouse operations managers, and integrated pest management service providers. EPA microbial pesticide registration databases, EU 1107/2009 equivalence protocols, and ANVISA biological pathway filings supplied regulatory validation. Bottom-up strain-level production estimates triangulated against top-down agricultural input expenditure flows.
Segmentation granularity modeled product type at strain-viability level, application environment at labor-cost threshold, and end-user at technical capability tier across the projection horizon. CAGRs derived from fermentation capacity expansion curves, greenhouse acreage growth trajectories, and regulatory substitution mandate timelines. Industry-specific inputs incorporated beneficial insect shelf-life decay functions and cold-chain infrastructure penetration rates.
Several conditions sit outside the modeled scope, including public land forestry applications with limited intervention frequency and bioherbicide segments constrained by host-range specificity challenges. Forecasts reflect stated policy implementation assumptions without contingency for regulatory delay or trade barrier introduction. A small set of named triggers warrants ongoing watch: EFSA novel food residue determinations, India PLI scheme extension decisions, and Brazilian resistance protocol enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
West Africa Biostimulants Market