
 Europe Biofertilizer Market | 2026-2036
Europe Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biofertilizer Market Intelligence
Fragmentation among commercial growers and greenhouse operators is recalibrating procurement patterns across the value chain. Koppert Biological Systems Inc. leverages its Dutch research infrastructure to dominate beneficial microbe distribution in protected cultivation. Lallemand Inc. anchors European fermentation capacity for nitrogen-fixing bacterial strains. Novonesis extends its biosolutions portfolio into rhizosphere-specific formulations for high-value horticulture.
Biofertilizers contain living microorganisms—primarily bacteria, fungi, or algae—that colonize plant rhizospheres to enhance nutrient availability through biological nitrogen fixation, phosphate solubilization, or phytohormone production. These formulations typically require cell counts exceeding 10^8 CFU per gram and carrier matrices that maintain viability across storage temperatures from 4°C to 30°C for six to twenty-four months. Liquid biofertilizers command premium positioning in precision fertigation systems, while solid and carrier-based variants sustain broader penetration among conventional agricultural producers. Organic farming applications generate the fastest-growing demand pool, though horticulture and greenhouse end users concentrate margin capture through technical support bundling.
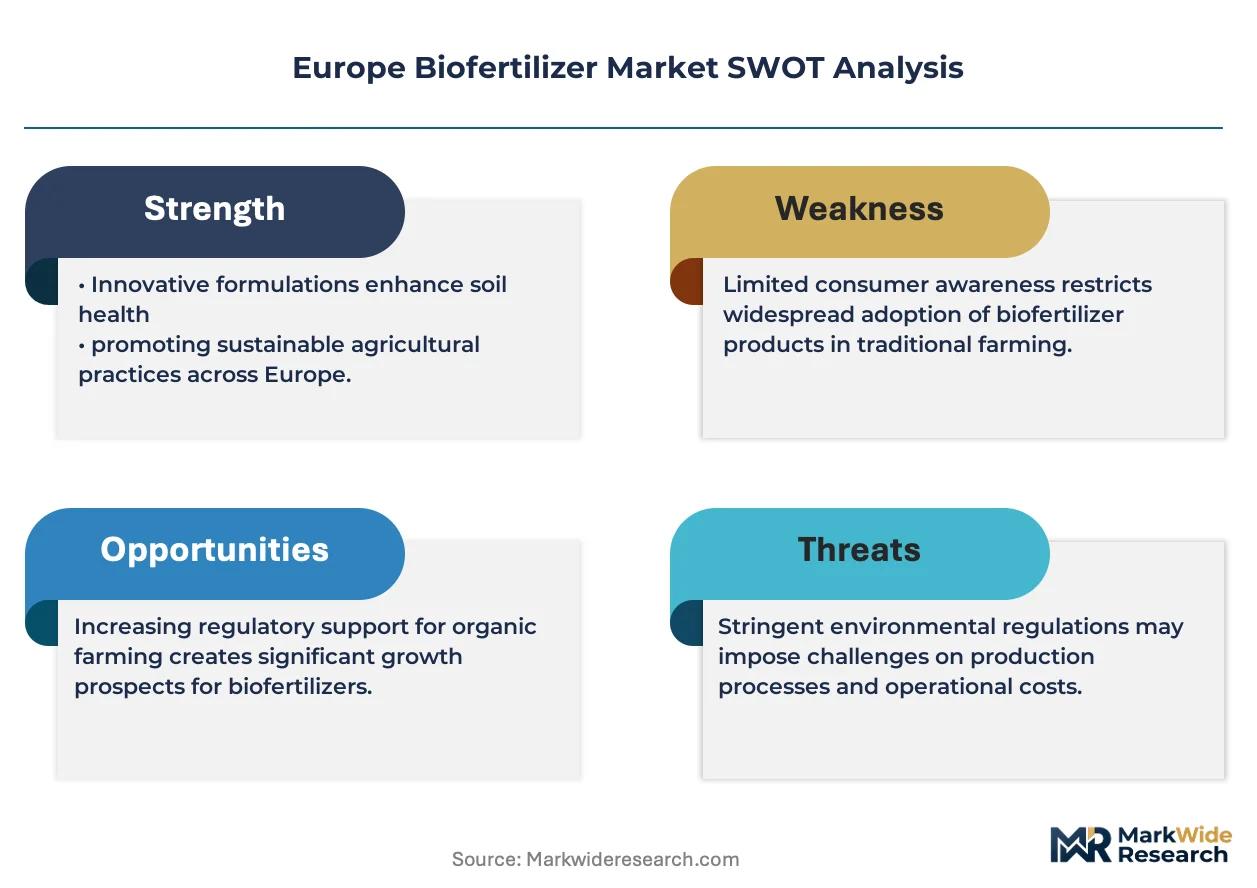
The EU Green Deal and Farm to Fork Strategy are tightening synthetic nitrogen restrictions, while EFSA and national regulators under REACH enforce strict microbial strain safety documentation for product registration. CE marking requirements for agricultural inputs create compliance thresholds that favor established formulators with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving strain patent landscapes and national subsidy mechanisms for biological inputs as the competitive field intensifies between specialized microbial houses and diversified agricultural biotechnology platforms.
Market Dynamics
Synthetic nitrogen restrictions under the EU Green Deal are forcing agricultural input suppliers to reconfigure their product portfolios toward microbial alternatives, while greenhouse operators in Spain and Italy accelerate technical validation programs for rhizosphere-specific formulations.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory 50% synthetic fertilizer reduction targets by 2030 are creating guaranteed offtake for nitrogen-fixing bacterial inoculants across arable farming regions.
- Protected cultivation expansion:Almería's greenhouse cluster is retrofitting fertigation infrastructure to accommodate liquid biofertilizer dosing systems at commercial scale.
- Soil microbiome diagnostics:Rapid on-farm testing kits are enabling precision matching of microbial strains to specific rhizosphere conditions, accelerating adoption in high-value horticulture.
Market Restraints
- Strain viability logistics:Cold chain requirements for maintaining 10^8 CFU/g cell counts across distribution networks inflate delivered costs by 15-25% versus synthetic equivalents.
- REACH microbial registration:ECHA safety dossier requirements for novel bacterial strains extend product launch timelines by 18-36 months and favor incumbents with dedicated regulatory affairs teams.
- Peat carrier supply concentration:Baltic states supply 70% of European peat substrates, exposing formulators to extraction permit volatility under EU wetland conservation directives.
Strategic Opportunities
- Poland's conventional arable sector:Large-scale wheat and rapeseed operations remain underpenetrated by microbial inoculants, presenting volume expansion potential for phosphate-solubilizing formulations.
- Carbon farming incentive stacking:Member state CAP strategic plans are beginning to credit biological nitrogen fixation toward soil carbon accumulation targets, creating dual revenue streams for growers.
- Biostimulant-biofertilizer convergence:Combined formulations integrating nitrogen-fixing bacteria with seaweed extracts are commanding premium positioning in organic viticulture across Bordeaux and Tuscany.
Industry Challenges
- Microbial strain characterization:Standardized efficacy protocols for rhizosphere colonization rates remain under development at EFSA, creating uncertainty in product performance claims and grower trust building.
- Technical agronomist scarcity:Field support capacity for advising growers on inoculant application timing, compatibility with pesticide programs, and storage protocols is concentrating among Dutch and German suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biofertilizer Market |
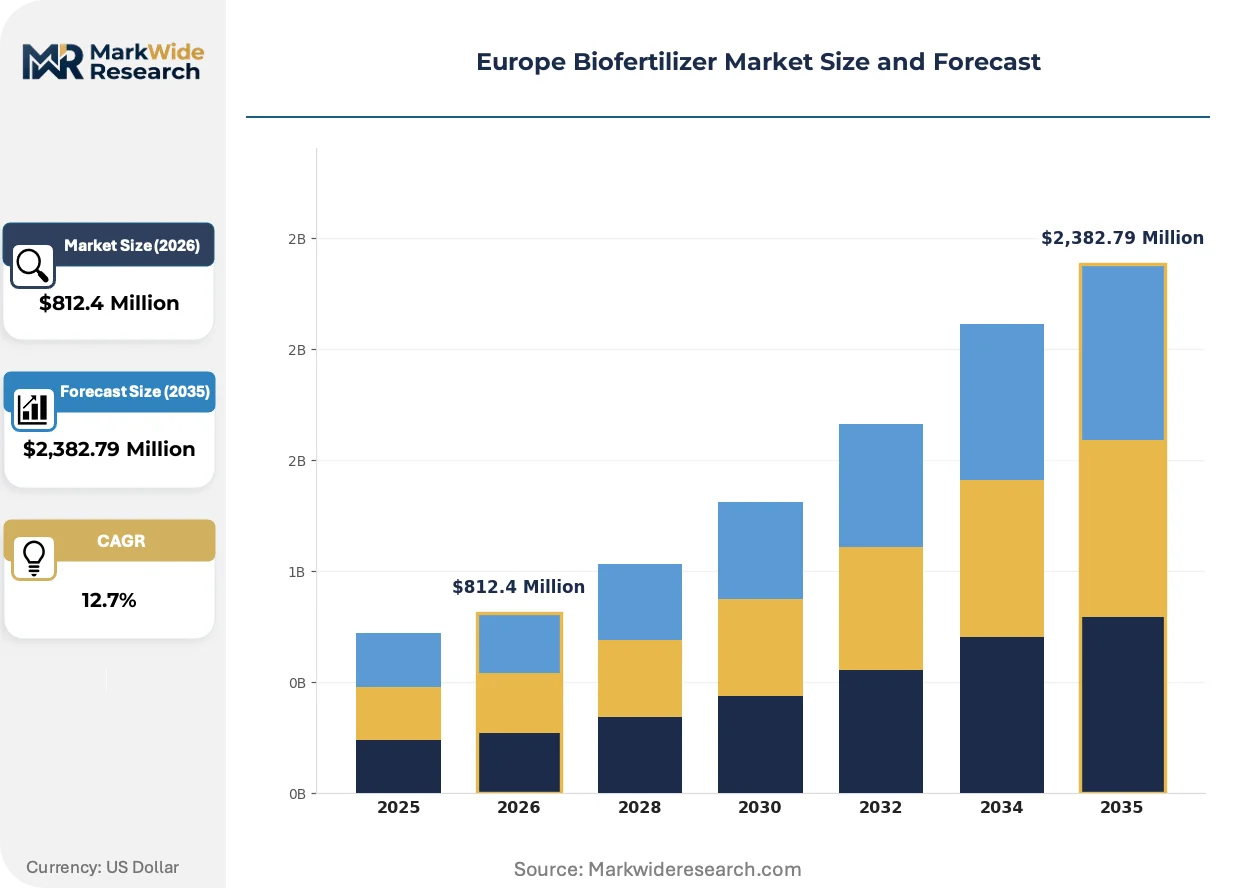
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $2,382.79 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Solid Biofertilizers, Carrier-Based Biofertilizers, Biofertilizer Coatings Application: Crops, Horticulture, Landscaping, Organic Farming End User: Agricultural Producers, Home Gardeners, Commercial Growers, Greenhouses Distribution Channel: Online Stores, Retail Outlets, Distributors, Direct Sales |
| Companies Covered | Agronutrition, Biolchim SPA, Koppert Biological Systems Inc., Lallemand Inc., Symborg, Inc., ASB Greenworld, Novonesis, Andermatt Group AG, Atlántica Agrícola, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biofertilizer Market Strategic Shifts & Innovations
Formulation science and digital agriculture tools are compressing the gap between laboratory strain selection and field-scale performance consistency, while regulatory frameworks mature to accommodate novel microbial inputs.
Encapsulation technologies using alginate and polymeric matrices are extending shelf stability of nitrogen-fixing bacteria beyond 24 months at ambient temperatures. Dutch greenhouse operators are piloting these formulations in precision fertigation systems. This stability breakthrough is converging with variable-rate application hardware to enable subscription-based input models that displace bulk commodity purchasing.
EFSA's 2023 guidance on qualified presumption of safety for microbial strains is streamlining registration pathways for well-characterized bacterial species. The industrial consequence is accelerated market entry for consortia formulations combining multiple functional traits. High-value horticulture segments in Spain and Italy are responding fastest, integrating these multi-strain products into integrated pest and nutrient management protocols.
Spanish vegetable cooperatives are consolidating procurement decisions for biological inputs through centralized technical committees. This buyer concentration is displacing distributor-led sales relationships with direct manufacturer partnerships. The Murcia region exhibits the most advanced contracting structures, with multi-season performance guarantees now standard in tomato and pepper production agreements.
Europe Biofertilizer Market Segmentation
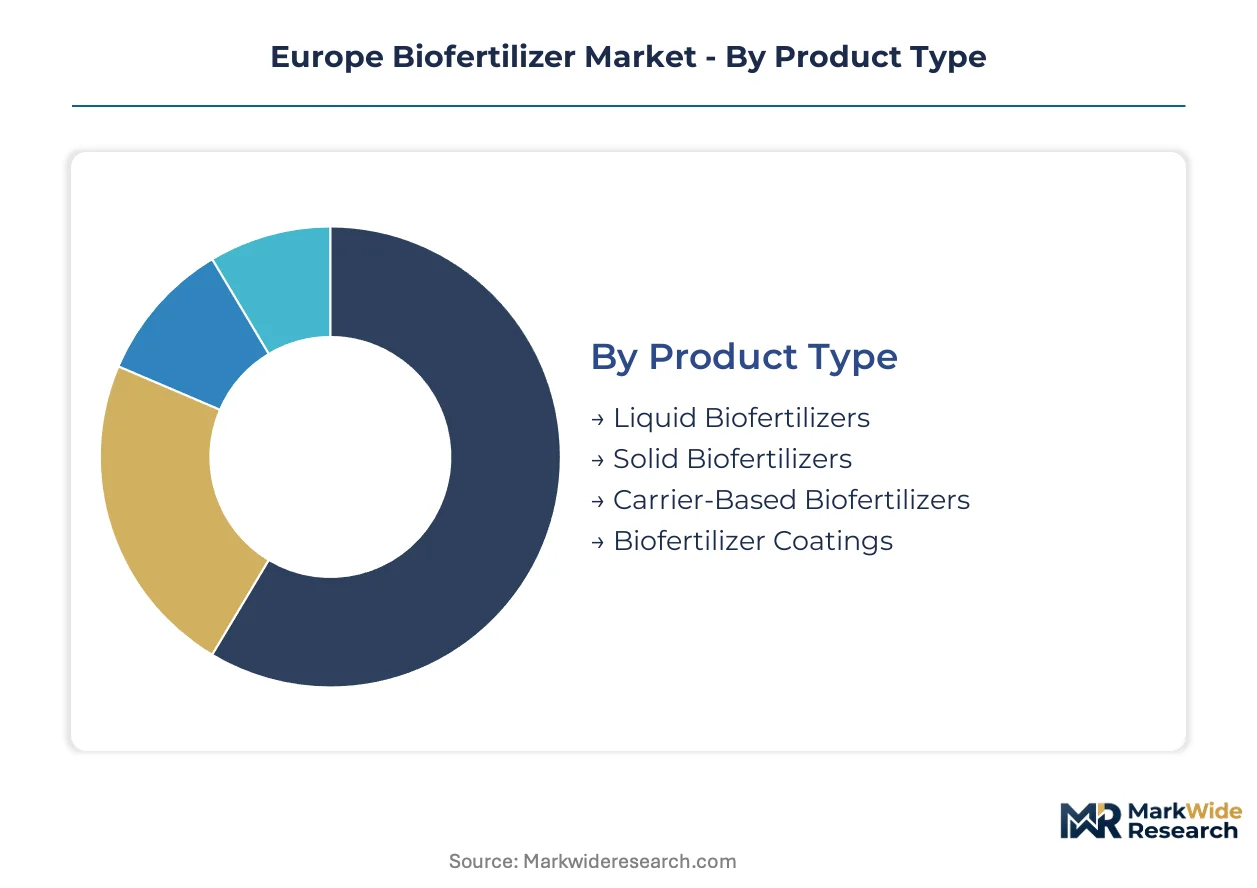
Segmentation in the European biofertilizer market reveals how formulation chemistry, application infrastructure, and buyer sophistication intersect to create distinct competitive arenas. Each dimension carries implications for cold chain requirements, technical support intensity, and regulatory documentation burdens.
Product Type:
Integration depth varies sharply: liquid formulations embed directly into precision fertigation systems, while carrier-based products operate as standalone soil amendments requiring separate application equipment.
- Liquid Biofertilizers:Suspensions of nitrogen-fixing bacteria or phosphate-solubilizing fungi in aqueous carriers, typically dosed at 10^8-10^9 CFU per milliliter. Spanish greenhouse operators around Almería are retrofitting drip irrigation infrastructure to accommodate these formulations, driven by EU Farm to Fork synthetic nitrogen reduction mandates.
- Carrier-Based Biofertilizers:Microbial cultures immobilized on peat, lignite, or inert mineral substrates, packaged for dry broadcast or seed treatment. French organic wheat producers in the Île-de-France basin favor these for compatibility with existing drill equipment, though Baltic peat supply volatility under EU wetland directives creates input cost uncertainty.
- Solid Biofertilizers:Granulated or powdered formulations with extended ambient stability, suited to broadacre arable operations lacking refrigerated storage.
- Biofertilizer Coatings:Microbial layers applied directly to seed surfaces, eliminating separate inoculant handling during sowing windows.
Carrier-based biofertilizers lead volumes today; liquid formulations are gaining share fastest.
Application:
Margin structure diverges by cultivation intensity: protected horticulture commands technical support premiums, while broadacre cropping rewards logistics efficiency at scale.
- Crops:Arable applications on wheat, barley, and oilseed rape across Poland and Germany, where phosphate-solubilizing bacteria address legacy phosphorus fixation in calcareous soils. The segment climbs fastest as conventional growers respond to rising synthetic fertilizer costs and carbon farming incentive stacking under national CAP strategic plans.
- Horticulture:High-value vegetable and fruit production in Italy's Po Valley and Spain's Murcia region, where rhizosphere-specific formulations integrate into integrated pest and nutrient management protocols. Growers here demand strain-specific efficacy documentation and multi-season performance guarantees.
- Landscaping:Turf and ornamental applications across municipal parks and golf courses, with specifications emphasizing rapid establishment and visual uniformity.
- Organic Farming:Certification-constrained applications where synthetic input prohibitions create guaranteed offtake, though volumes concentrate in Germany and France where operator density supports distribution economies.
Horticulture captures premium pricing today; crop applications are expanding most quickly.
End User:
Procurement sophistication separates volume buyers with technical agronomist support from price-sensitive operators relying on distributor recommendations.
- Commercial Growers:Large-scale vegetable cooperatives in Spain consolidating procurement through centralized technical committees, displacing distributor relationships with direct manufacturer partnerships and demanding multi-season performance guarantees.
- Greenhouses:Dutch and Italian protected cultivation operators piloting encapsulation technologies and variable-rate application hardware, enabling subscription-based input models that displace bulk commodity purchasing.
- Agricultural Producers:Conventional arable farmers across Poland and eastern Germany, underpenetrated by microbial inoculants but responding to synthetic nitrogen restriction timelines.
- Home Gardeners:Retail-packaged consumer segment with limited technical support requirements and price elasticity constraining premium positioning.
Commercial growers dominate revenue today; greenhouse operators are scaling fastest.
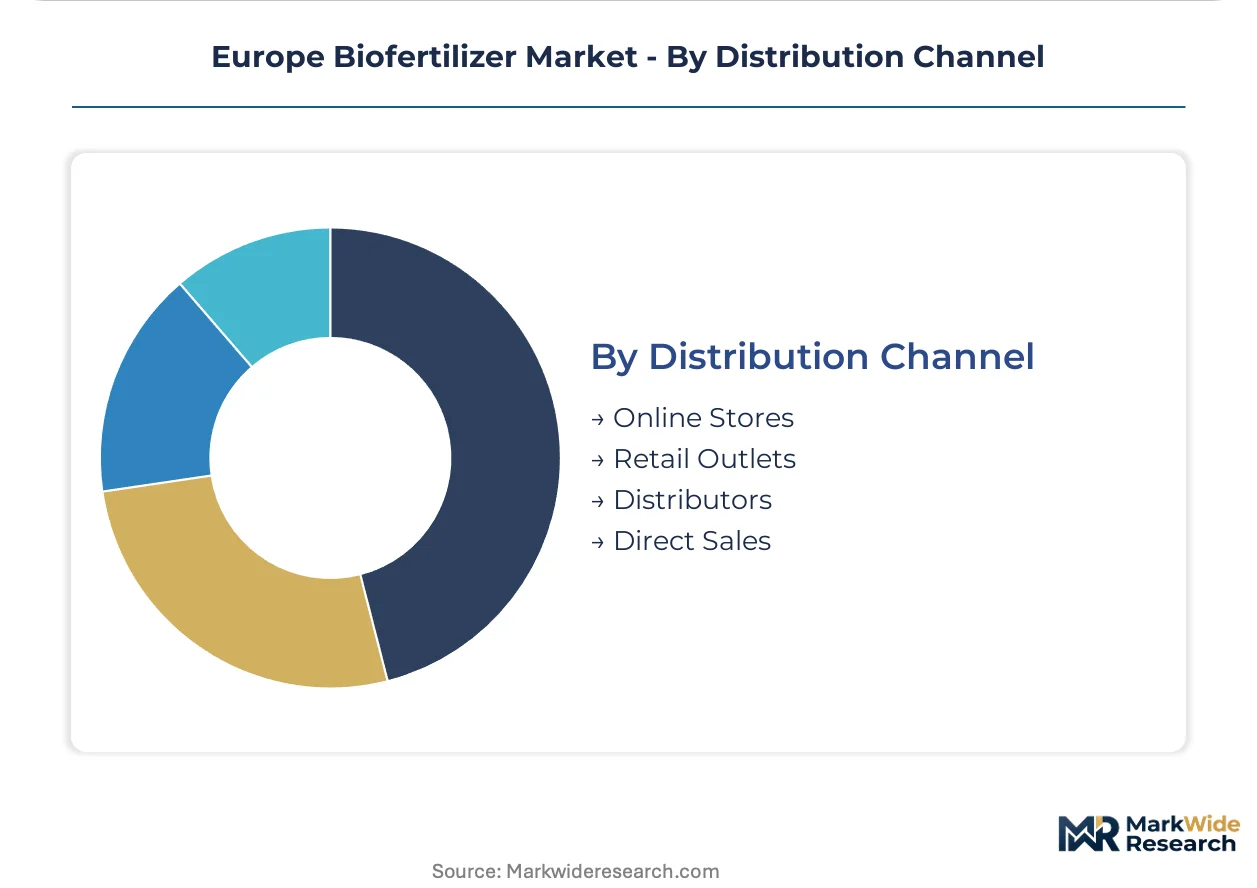
Distribution Channel:
Channel selection reflects buyer scale and technical complexity: complex formulations require field support capacity that concentrates among Dutch and German suppliers.
- Distributors:Regional agricultural supply networks carrying inventory risk and providing last-mile logistics to conventional producers, though Spanish cooperatives are consolidating procurement decisions and reducing distributor relevance.
- Direct Sales:Manufacturer relationships with large greenhouse operators and cooperative buying groups, enabling technical service bundling and performance-based contracting structures now standard in Murcia tomato and pepper production.
- Online Stores:E-commerce platforms serving home gardeners and small-scale organic operators with standardized formulations and limited technical support.
- Retail Outlets:Garden center and farm supply store presence for consumer and small-producer segments, constrained by cold chain requirements for viable product.
Distributors move the most volume today; direct sales channels are growing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch microbial research clusters and Spanish agronomist networks anchor European biofertilizer development. Technical talent concentrates around Wageningen University corridors and Almería greenhouse cooperatives.
Germany
Organic wheat producers in the Île-de-France basin source carrier-based formulations compatible with existing drill equipment. The EU Farm to Fork Strategy's synthetic nitrogen reduction mandates accelerate procurement of phosphate-solubilizing bacteria. Bavarian research institutes advance strain characterization protocols for rhizosphere-specific applications.
France
Organic farming operations in the Île-de-France basin expand procurement of microbial inoculants for cereal production. REACH enforcement through ECHA demands rigorous safety dossiers for novel bacterial strains. The Bordeaux wine region integrates biostimulant-biofertilizer combinations into organic viticulture protocols.
Spain
Vegetable cooperatives around Almería and Murcia retrofit fertigation systems for liquid biofertilizer dosing. Centralized technical committees consolidate procurement decisions, displacing traditional distributor relationships. Murcia's tomato and pepper producers now require multi-season performance guarantees in direct manufacturer contracts.
Italy
Protected cultivation operators in the Po Valley pilot encapsulation technologies for ambient-stable nitrogen-fixing bacteria. EFSA's 2023 qualified presumption of safety guidance streamlines registration for multi-strain consortia. Tuscany's organic wine sector commands premium pricing for combined bacterial-seaweed formulations.
Poland
Large-scale wheat and rapeseed operations remain underpenetrated by microbial inoculants despite rising synthetic fertilizer costs. National CAP strategic plans credit biological nitrogen fixation toward soil carbon targets. The country's conventional arable sector presents volume expansion potential for phosphate-solubilizing formulations.
Europe Biofertilizer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for positioning across formulation tiers. The vendor base separates into three strategic archetypes: microbial research houses with dedicated fermentation infrastructure, agricultural biotechnology platforms extending biosolutions portfolios, and regional distributors consolidating last-mile logistics. Dominant competitive moves include backward integration into strain development capabilities and direct partnerships with large greenhouse operators displacing traditional distribution channels.
Among Netherlands-based specialists, Koppert Biological Systems Inc. and Lallemand Inc. exemplify the research-intensive archetype with dedicated European fermentation capacity. Novonesis occupies a position bridging industrial biotechnology and agricultural applications. These three anchors demonstrate how regulatory affairs capabilities and cold chain logistics differentiate sustainable market presence from commodity positioning.
| Leading Market Players |
|---|
| Agronutrition |
| Biolchim SPA |
| Koppert Biological Systems Inc. |
| Lallemand Inc. |
| Symborg, Inc. |
| ASB Greenworld |
| Novonesis |
| Andermatt Group AG |
| Atlántica Agrícola |
| Others |
Cost & Logistics Intelligence
Spanish cooperative procurement consolidation is forcing manufacturers to absorb cold chain logistics costs while maintaining cell count viability guarantees, compressing margins across liquid formulation tiers. Suppliers must choose between premium direct partnerships with technical committees or distributor networks with higher working capital requirements.
Pricing Analysis
Capacity additions in Dutch fermentation facilities are reshaping price floors for nitrogen-fixing bacterial strains across the continent. Three-tier pricing structure across premium, standard, and economy levels separates multi-strain consortia with EFSA registration from single-species formulations and generic peat-carried products. Cost compression in standard tiers is intensifying because Baltic peat supply volatility under EU wetland directives feeds raw material uncertainty. Conventional arable operators in Poland exhibit highest price sensitivity, while Dutch greenhouse operators accept premium positioning for subscription-based precision dosing systems.
Supply Chain Analysis
Reverse logistics for expired biofertilizer batches and recalled strain formulations remain underdeveloped across European distribution networks, creating liability exposure for retailers holding temperature-compromised inventory. Production gravity centers on the Netherlands, France, and Spain, with Dutch research clusters supplying strain development and Spanish cooperatives anchoring demand concentration. The supply chain draws from Baltic peat substrates, aqueous fermentation media, and polymeric encapsulation materials. Single-source vulnerability in peat extraction permits under EU conservation directives threatens carrier-based formulation continuity. Distribution runs through regional agricultural supply networks, though direct manufacturer partnerships with large cooperatives are displacing traditional distributor relationships in Murcia and Almería.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe biofertilizer market compounds steadily as regulatory mandates under the EU Green Deal create guaranteed offtake trajectories for microbial alternatives to synthetic nitrogen.
For Market Incumbents: To counter cooperative procurement consolidation in Spain, deepen technical agronomist staffing in greenhouse clusters and secure multi-season performance guarantee contracts that lock out competitor strain trials. Backward integration into Baltic peat sourcing or synthetic carrier development hedges against extraction permit volatility under EU wetland directives. For New Entrants and Emerging Players: Capture Poland's conventional wheat and rapeseed sector where phosphate-solubilizing formulations remain underdeployed despite rising synthetic fertilizer costs. Field-based technical support partnerships with existing agricultural machinery distributors overcome incumbent cold chain logistics advantages without capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap microbial houses possessing EFSA-registered strain portfolios and established fermentation capacity in Benelux. Five-to-ten year viability hinges on regulatory affairs capabilities rather than commodity formulation scale. Monitor member state CAP strategic plan implementations for biological nitrogen fixation crediting mechanisms as inflection signals for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Registration Acceleration | EFSA qualified presumption of safety pathways compress 18-36 month launch timelines for consortia formulations. |
| Encapsulation Technology Licensing | Alginate and polymeric matrix patents enable ambient-stable products that displace refrigerated supply chains. |
| Direct Cooperative Partnerships | Murcia technical committee relationships displace distributor margins and capture multi-season contract structures. |
| Carbon Farming Incentive Stacking | National CAP plans crediting biological nitrogen fixation create dual revenue streams for grower adoption. |
| Biostimulant Convergence R&D | Bacterial-seaweed combination formulations command premium positioning in organic viticulture across Bordeaux and Tuscany. |
Research Approach
Bottom-up greenhouse operator and arable farmer modeling reconciled against top-down fermentation capacity and strain registration tracking forms the analytical core of this study. Primary interviews with technical agronomists at Spanish cooperatives, regulatory affairs directors at microbial houses, Dutch greenhouse operations managers, and Polish cereal producers combined with secondary validation from EFSA guidance documents, ECHA safety dossier filings, EU Farm to Fork Strategy implementation reports, and national CAP strategic plans. Triangulation across these sources ensures demand-side procurement patterns align with supply-side formulation availability.
Input-output matrices map nitrogen-fixing bacteria and phosphate-solubilizing fungi deployment across liquid, carrier-based, solid, and coating formulation types, intersecting with horticulture, arable cropping, and organic farming applications throughout the projection horizon. CAGRs derive from segment-level adoption curves calibrated to synthetic nitrogen restriction timelines and carbon farming incentive rollouts. Strain viability logistics costs and REACH registration pipeline durations serve as industry-specific forecast inputs.
EU Green Deal implementation delays, EFSA efficacy protocol finalization, and Baltic peat extraction permit volatility are the dominant revision risks to modeled trajectories. Practitioners should monitor these triggers for early signals of demand acceleration or supply constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Plant Based Biosurfactants Market