
 Global Bio-Organic Acid Market | 2026-2036
Global Bio-Organic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio-Organic Acid Market Foresight
Petrochemical-derived adipic acid is recalibrating cost benchmarks as bio-succinic acid scales through continuous fermentation. Jungbunzlauer Suisse AG leverages its Swiss fermentation heritage to dominate crystalline citric acid supply for European pharmaceutical formulators. Cargill Incorporated anchors North American lactic acid output through integrated corn-processing infrastructure. DSM competes on specialty-grade bio-acids for high-purity nutraceutical applications.
Bio-organic acids comprise carboxylic compounds synthesized via microbial fermentation of carbohydrate feedstocks, typically achieving purity grades between 99.0% and 99.9% through downstream crystallization or membrane filtration; these acids function as acidulants, preservatives, chelating agents, and platform chemicals across industrial formulations. Citric acid occupies the largest volume share due to its ubiquity in food and beverages, while succinic acid registers the fastest structural expansion as a drop-in replacement for petroleum-derived butanediol precursors. The powder form commands premium positioning in pharmaceutical and nutraceutical supply chains where handling precision and shelf stability determine procurement decisions.
The EPA's renewable fuel standard pathways and REACH registration requirements for bio-based chemical intermediates are tightening feedstock traceability and lifecycle emissions documentation, compelling producers to certify fermentation-derived inputs through mass-balance accounting. China's NMPA and the EU's EFSA maintain divergent purity thresholds for acidulants used in active pharmaceutical ingredients, fragmenting compliance architectures for multinational suppliers. Stakeholders must monitor how carbon border adjustment mechanisms and bioplastics mandates redirect capital between first-generation sugar fermentation and second-generation lignocellulosic processing platforms.
Market Dynamics
Fermentation process intensification is compressing unit economics for bio-organic acid producers, forcing capital deployment toward continuous bioreactor systems and integrated downstream recovery that slashes energy inputs per ton of purified output.
Growth Catalysts
- EU Green Deal bioeconomy targets:Binding mandates for renewable chemical feedstocks redirect petrochemical capacity toward fermentation-derived platform chemicals across member states.
- Food acidulant reformulation:Clean-label priorities in beverage manufacturing pull crystalline citric acid into expanded preservative and pH-control roles.
- German industrial biotechnology clusters:Concentrated biorefinery infrastructure in Baden-Württemberg and North Rhine-Westphalia enables scaled succinic acid output for polymer precursors.
Market Restraints
- Corn feedstock price volatility:First-generation sugar fermentation remains exposed to agricultural commodity swings that destabilize lactic acid cost structures.
- Chinese supply concentration:Bulk citric acid crystallization capacity clusters in Shandong and Jiangsu provinces, creating single-source vulnerability for European formulators.
- REACH registration complexity:Bio-based chemical intermediates face extended dossier preparation timelines that delay market entry for novel acid variants.
Strategic Opportunities
- Brazilian sugarcane feedstock expansion:Second-generation lignocellulosic processing platforms can anchor low-cost fermentation in the Center-South region's existing ethanol infrastructure.
- Japan's nutraceutical grade demand:PMDA purity thresholds for active pharmaceutical ingredients create premium positioning for specialty-grade bio-acids in functional food formulations.
- Carbon border adjustment mechanisms:EU CBAM implementation favors certified low-emission fermentation routes over petrochemical adipic acid imports.
Industry Challenges
- Continuous fermentation talent scarcity:Bioprocess engineering expertise for steady-state bioreactor operation remains concentrated in academic and industrial research centers.
- Downstream membrane filtration capex:Ceramic and polymeric separation systems for 99.9% purity grades require substantial capital deployment with extended depreciation horizons.
- Mass-balance certification complexity:Producers must document feedstock traceability across blended sugar and lignocellulosic inputs to satisfy EFSA and EPA pathway requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio-Organic Acid Market |
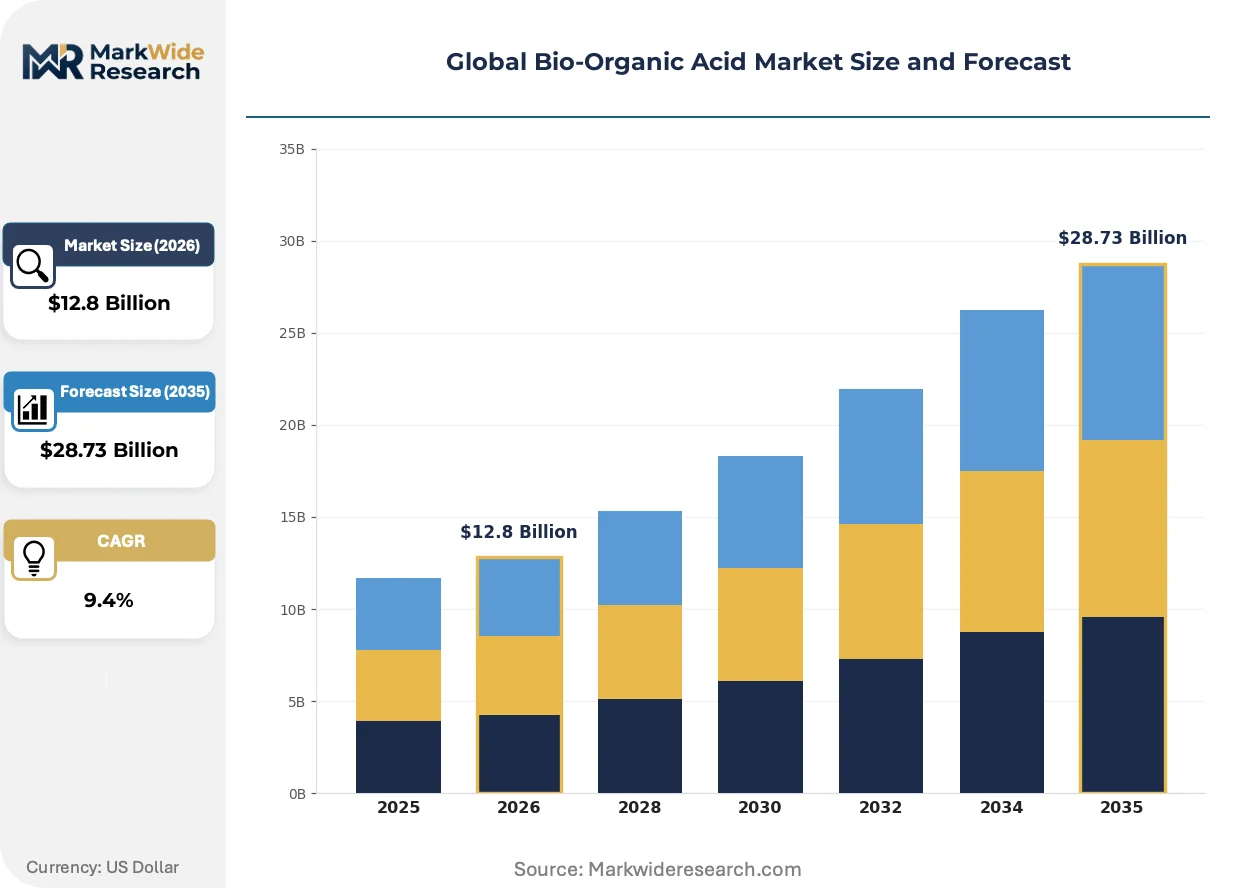
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Acetic Acid, Malic Acid, Succinic Acid Application: Food & Beverages, Pharmaceuticals, Personal Care, Agrochemicals, Animal Feed End User Industry: Biotechnology Firms, Nutraceutical Manufacturers, Cosmetic Companies, Agrochemical Enterprises Form: Liquid, Powder, Granular, Crystalline |
| Companies Covered | Mitsubishi Chemical Corporation, Jungbunzlauer Suisse AG, Cargill Incorporated, Evonik Industries AG, DuPont de Nemours Inc., Archer-Daniels-Midland Company, Corbion N.V., DSM, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio-Organic Acid Market Shifts & Advancements
Bioprocess intensification is collapsing the historical trade-off between fermentation titer and productivity, enabling commercial-scale continuous systems that were previously confined to pilot demonstrations. Three developments are compressing technology adoption cycles.
Cell-retention perfusion bioreactor technology is modularizing succinic acid production economics by decoupling biomass growth from product formation. Specialty chemical formulators in the Netherlands and Belgium are piloting these systems for pharmaceutical-grade outputs. The shift collapses capital intensity per annual ton of installed capacity.
REACH registration requirements for bio-based intermediates are tightening lifecycle emissions documentation obligations. Chemical producers must now certify fermentation-derived inputs through third-party mass-balance accounting. European acidulant suppliers face the steepest compliance burden as EFSA purity thresholds diverge from NMPA specifications.
Buyer concentration among multinational food and beverage manufacturers is compressing supplier qualification timelines. Procurement teams now mandate simultaneous certification to FDA, EFSA, and FSSAI standards before contract execution. This pattern is most visible in citric acid sourcing for global carbonated beverage formulations.
Global Bio-Organic Acid Market Segmentation
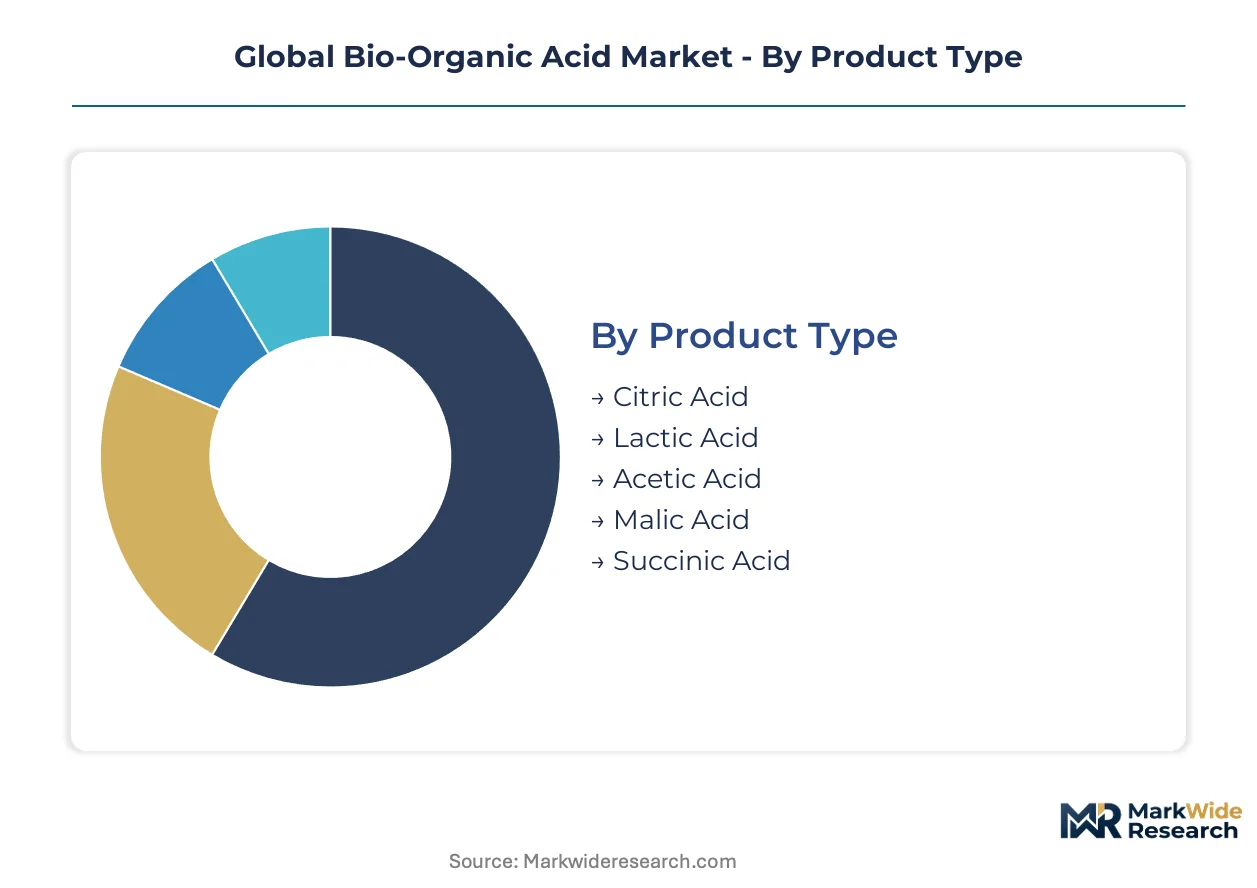
Segmentation in bio-organic acids reveals how fermentation economics, purity thresholds, and end-use specifications fragment procurement patterns across industrial buyers. Understanding these divides exposes where margin concentrates and which technology platforms command pricing power.
Product Type:
Supply concentration varies sharply by acid chemistry, with crystallization infrastructure and feedstock flexibility determining which molecules achieve commercial scale.
- Citric Acid:Achieves 99.9% purity through downstream crystallization of Aspergillus niger fermentation broth. Food and beverage formulators in Germany and the Netherlands anchor procurement volumes, though Shandong province crystallization clusters create single-source vulnerability for European buyers.
- Succinic Acid:Synthesized via engineered yeast or bacterial strains on glucose or lignocellulosic substrates. German industrial biotechnology clusters in Baden-Württemberg enable scaled output for polymer precursors replacing petrochemical butanediol.
- Lactic Acid:Corn-processing infrastructure in the US Midwest supports integrated fermentation-to-purification economics for polylactic acid feedstock and food acidulant applications.
- Acetic Acid:Bacterial fermentation of ethanol yields food-grade vinegar and chemical intermediates, with capacity clustering near beverage manufacturing hubs.
- Malic Acid:Fumaric acid bioconversion or direct fermentation produces this less common acidulant for specialty beverage tartness modulation.
Today's leader: Citric Acid. Tomorrow's challenger: Succinic Acid.
Application:
End-use specifications fragment demand by purity grade, with pharmaceutical and nutraceutical applications commanding 2-3x the unit economics of commodity food acidulants.
- Food & Beverages:Clean-label reformulation drives crystalline citric acid and lactic acid into expanded preservative roles. EFSA and FDA acidulant specifications diverge on heavy metal limits, complicating multinational sourcing.
- Pharmaceuticals:USP and EP grade requirements for active pharmaceutical ingredient acidulants concentrate procurement among certified fermentation specialists. PMDA thresholds in Japan add a premium tier for Asian supply chains.
- Personal Care:Cosmetic formulators leverage malic and lactic acids for pH adjustment and mild exfoliation in premium skincare lines.
- Agrochemicals:Chelating agent applications for micronutrient fertilizers utilize lower-purity acid grades with less stringent fermentation documentation.
- Animal Feed:Acidification for gut health and mold inhibition in poultry and swine operations consumes price-sensitive liquid acid volumes.
Food & Beverages commands current volume leadership. Pharmaceuticals delivers the steepest margin expansion trajectory.
End User Industry:
Buyer sophistication around mass-balance certification and REACH dossier requirements stratifies supply relationships by compliance capability.
- Biotechnology Firms:Platform chemical offtake agreements for bio-succinic and bio-adipic acids anchor long-term fermentation capacity investments. These buyers mandate third-party lifecycle emissions verification.
- Nutraceutical Manufacturers:Purity thresholds for functional food formulations in Japan and Switzerland create premium positioning for specialty-grade bio-acids with documented fermentation genealogy.
- Cosmetic Companies:Clean beauty marketing drives demand for fermentation-derived acids with natural positioning and COSMOS certification compatibility.
- Agrochemical Enterprises:Volume buyers of technical-grade acids for chelate manufacturing, with procurement decisions driven by landed cost rather than certification depth.
Biotechnology firms set the compliance bar. Nutraceutical manufacturers pay the purity premium.
Form:
Physical state determines handling infrastructure, shelf stability, and formulation precision across downstream applications.
- Powder:Spray-dried or milled crystalline material enables precise dosing in pharmaceutical tableting and powdered beverage mixes. Premium positioning reflects handling precision and extended stability.
- Crystalline:High-purity citric acid monohydrate and anhydrous grades dominate food and pharmaceutical supply chains where dissolution kinetics and visual clarity matter.
- Liquid:Fermentation broth concentrates or purified solutions suit large-scale food processing and feed acidification where tankage infrastructure exists.
- Granular:Intermediate flow properties for industrial formulations requiring controlled release or reduced dust generation during handling.
Powder and crystalline forms capture margin. Liquid volumes absorb commodity pricing pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's industrial biotechnology corridor anchors European bio-organic acid fermentation capacity, with specialized bioreactor clusters supplying polymer-grade succinic acid to automotive and packaging converters across the continent.
Germany
Automotive sector demand for bio-based polymer precursors pulls succinic acid volumes into Baden-Württemberg and North Rhine-Westphalia. EU Green Deal bioeconomy targets mandate renewable chemical feedstock quotas by 2030. BASF and Evonik fermentation facilities in Ludwigshafen and Marl anchor scaled production for butanediol replacement chemistry.
United States
Corn-belt processing infrastructure supports integrated lactic acid output for polylactic acid and food acidulant applications. EPA renewable fuel standard pathways require mass-balance certification for fermentation-derived inputs. Cargill's Nebraska and Iowa facilities leverage captive corn supply chains to compress unit economics for North American buyers.
China
Shandong and Jiangsu province crystallization clusters dominate bulk citric acid supply for global food and beverage formulators. NMPA purity thresholds for pharmaceutical acidulants diverge from EFSA specifications, fragmenting export compliance architectures. State-backed biorefinery investments in Shandong's Binzhou Chemical Industry Park expand fermentation-to-purification integration.
Brazil
Center-South sugarcane ethanol infrastructure enables second-generation lignocellulosic processing platforms for low-cost organic acid fermentation. ANVISA regulatory frameworks for food acidulants align with Mercosur technical standards. São Paulo state's Piracicaba biotech corridor hosts pilot-scale succinic acid operations leveraging bagasse feedstock integration.
Japan
PMDA purity thresholds for active pharmaceutical ingredients create premium demand for specialty-grade bio-acids in functional food and nutraceutical formulations. METI bioplastics mandates redirect chemical sector investment toward fermentation-derived platform molecules. Osaka-Kobe industrial zone concentrates pharmaceutical acidulant purification capacity for Asian export markets.
Global Bio-Organic Acid Market Competitive Landscape
Global majors compete with regional champions across fermentation scale and feedstock integration depth. The vendor base stratifies into three tiers: petrochemical conglomerates diversifying into bio-based platforms, dedicated fermentation specialists with captive carbohydrate supply chains, and regional sugar processors backward-integrating into acid purification. Dominant competitive moves include bioreactor capacity expansion in industrial biotechnology clusters and strategic partnerships between fermentation operators and polymer converters seeking drop-in chemical replacements.
Within the fermentation specialist tier, Jungbunzlauer Suisse AG exemplifies Swiss heritage in crystalline acid production, while Cargill Incorporated anchors North American positioning through integrated grain-processing infrastructure. DSM occupies a position in specialty-grade bio-acids where nutraceutical purity thresholds command pricing premiums over commodity food acidulants.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Jungbunzlauer Suisse AG |
| Cargill Incorporated |
| Evonik Industries AG |
| DuPont de Nemours Inc. |
| Archer-Daniels-Midland Company |
| Corbion N.V. |
| DSM |
| BASF SE |
| Others |
Supply & Pricing Matrix
Multinational food and beverage procurement teams concentrate acidulant buying power through consolidated supplier qualification programs, compressing pricing negotiations into three-tier structures across premium, standard, and economy levels. This buyer concentration feeds back into fermentation capacity planning, where producers must pre-certify to FDA, EFSA, and FSSAI standards before contract execution.
Pricing Analysis
Corn feedstock price volatility passes through directly to lactic acid cost structures, with US Midwest grain futures anchoring regional contract negotiations. Price differentiation separates pharmaceutical-grade crystalline citric acid from technical-grade liquid acidulants, with heavy metal certification thresholds determining tier placement. Cost compression in commodity food acidulants is intensifying because Chinese crystallization clusters absorb volume demand. Animal feed formulators exhibit the highest price sensitivity, while Japanese nutraceutical manufacturers accept premium positioning for PMDA-compliant specialty grades.
Supply Chain Analysis
Dual-sourcing requirements from European formulators mandate simultaneous qualification of German fermentation specialists and Chinese crystallization suppliers to mitigate single-source vulnerability. Geographic supply concentration centers on China for bulk citric acid, Germany for polymer-grade succinic acid, and the United States for corn-integrated lactic acid. Raw material dependencies draw from Brazilian sugarcane bagasse, US yellow dent corn, and European wheat starch. Single-source vulnerability clusters in Shandong province crystallization capacity. Distribution runs through integrated biorefinery complexes with captive downstream purification infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
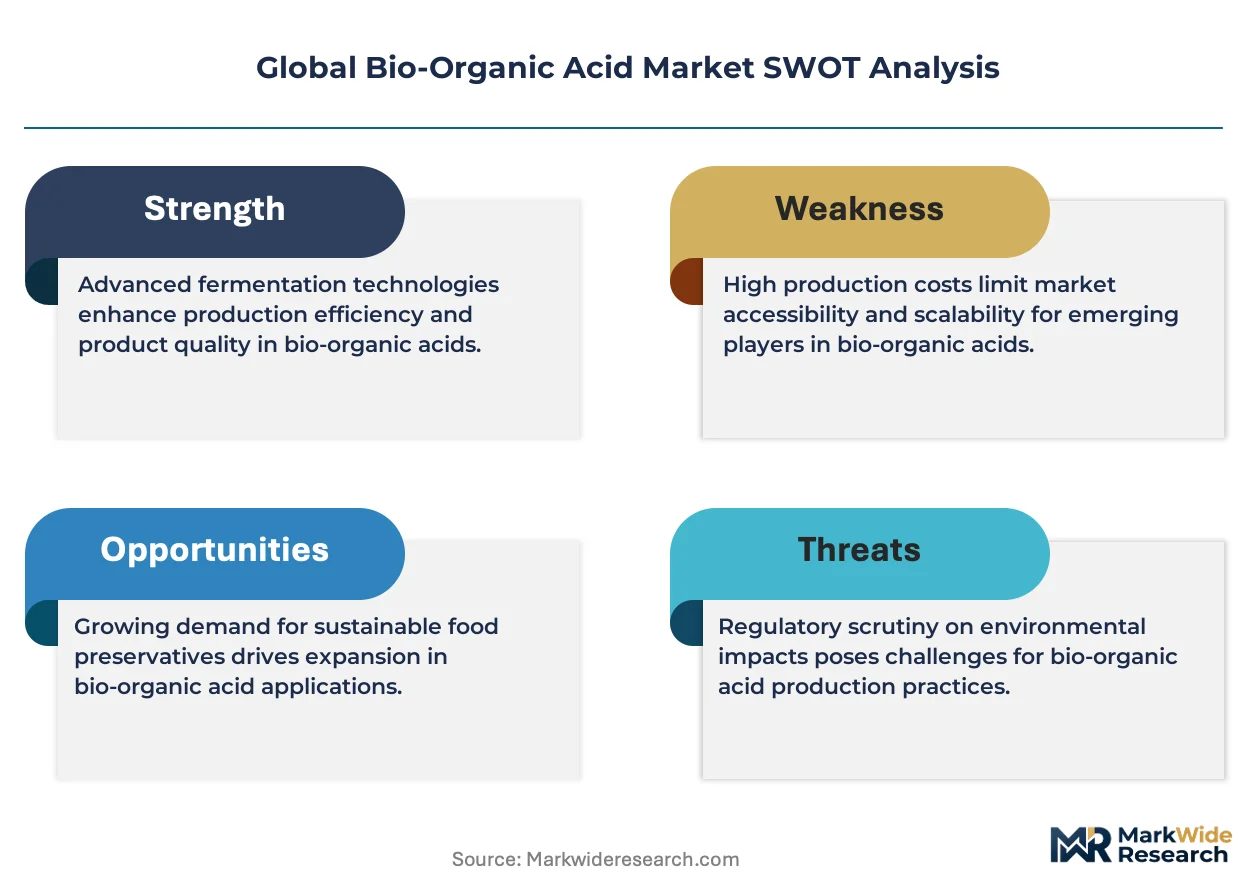
The Global Bio-Organic Acid Market functions as a stable compounder, with EU Green Deal bioeconomy mandates providing predictable demand pull for renewable chemical feedstocks across the projection horizon.
For Market Incumbents: Cement fermentation capacity leadership through backward integration into captive corn-processing infrastructure in the US Midwest, insulating lactic acid cost structures from agricultural commodity swings. Expand continuous bioreactor deployment in Baden-Württemberg industrial clusters to defend polymer-grade succinic acid positioning against emerging lignocellulosic entrants. For New Entrants and Emerging Players: Begin with Brazilian Center-South sugarcane feedstock platforms, leveraging existing ethanol infrastructure for second-generation lignocellulosic acid fermentation at cost parity with first-generation routes. Target Japan's PMDA-certified nutraceutical segment, where purity premiums reward documented fermentation genealogy and COSMOS certification compatibility. For Investors and Strategic Acquirers: Petrochemical conglomerates diversifying into bio-based platforms are the most active acquirer in this space, seeking fermentation specialists with REACH-registered product portfolios. Over a multi-year horizon, prioritize targets with mass-balance certification capabilities and integrated downstream crystallization assets. Watch EU carbon border adjustment mechanism implementation timing as the inflection indicator for bio-succinic acid demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioreactor Capacity Expansion | Cell-retention perfusion systems in Dutch and Belgian pilot facilities collapse capital intensity per ton of pharmaceutical-grade output. |
| Backward Integration into Feedstock Supply | Cargill's captive corn supply chains in Nebraska and Iowa compress unit economics for North American lactic acid buyers. |
| Mass-Balance Certification Investment | Third-party accounting for fermentation-derived inputs satisfies EFSA and EPA pathway requirements for multinational suppliers. |
| Long-term Polymer Converter Partnership | BASF and Evonik fermentation facilities in Ludwigshafen anchor butanediol replacement chemistry offtake agreements. |
| Specialty-Grade Purity Tier Development | DSM's nutraceutical-grade bio-acid positioning captures pricing premiums over commodity food acidulants in Swiss and Japanese markets. |
Research Methodology
Direct dialogue with fermentation plant managers, procurement leads at downstream biotechnology firms, distribution channel partners, and technical R&D directors grounded qualitative assessment of continuous bioreactor adoption timelines. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration dossiers. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Bottom-up modeling tracked installed fermentation capacity by molecule and geography, while top-down analysis calibrated against EU Green Deal bioeconomy targets and automotive sector polymer precursor demand. Segmentation dimensions included acid chemistry, purity grade tier, end-use industry, physical form, and regional production hub. CAGRs were derived from trend extrapolation of fermentation process intensification adoption curves, weighted by feedstock cost trajectory assumptions and regulatory mandate implementation schedules.
Several conditions sit outside the modeled scope, including breakthroughs in electrochemical acid synthesis, abrupt shifts in corn or sugarcane commodity pricing, and unilateral regulatory divergence beyond current EFSA-NMPA fragmentation. Deviation in EU carbon border adjustment mechanism implementation timing or bioplastics mandate stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Brazil Agricultural Biologicals Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Red Algae Market