
 Bioethanol Yeast Market | 2026-2036
Bioethanol Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Bioethanol Yeast Market Intelligence
The development of genetically modified yeast strains with enhanced stress tolerance is reconfiguring production economics for biofuel producers. These advanced microbes improve ethanol yields and fermentation efficiency under harsh industrial conditions. Novozymes leverages its expertise in enzyme and yeast co-development to offer integrated solutions. Lesaffre sustains a significant market share through its extensive global manufacturing and distribution network, while AngelYeast Co., Ltd. specializes in high-performance yeast for various fermentation processes.
Bioethanol yeast consists of specific strains of Saccharomyces cerevisiae engineered for converting sugars into ethanol with high efficiency. These strains exhibit superior tolerance to high temperatures, osmotic pressure, and elevated ethanol concentrations during industrial fermentation. Their primary function is to facilitate the large-scale bioprocessing of feedstocks like corn and sugarcane into fuel-grade ethanol. Dry yeast formats dominate the market due to their extended shelf life and logistical advantages over liquid yeast, with fermentation being the principal application.
Regulatory frameworks are fundamental to market structure, with mandates like the US EPA's Renewable Fuel Standard and the EU's Renewable Energy Directive setting volume targets for biofuels. Brazil's RenovaBio program further incentivizes decarbonization, directly influencing yeast demand. These policies establish a baseline for efficient yeast strains required to meet production quotas. Consequently, yeast strain selection increasingly hinges on its ability to process diverse and challenging second-generation feedstocks.
Market Dynamics
The bioethanol yeast market's structure is defined by the intense pressure on biofuel producers to maximize conversion efficiency and reduce carbon intensity. This pressure originates from regulatory mandates and feedstock cost volatility, forcing a shift from commodity yeast to specialized, high-performance microbial solutions engineered for specific industrial processes.
Growth Catalysts
- Regulatory Mandates:Policies such as the US Renewable Fuel Standard and the EU's Renewable Energy Directive create legally binding targets for biofuel blending, securing long-term demand for efficient yeast strains required by producers to meet these quotas.
- Feedstock Diversification:The global push to utilize non-food, lignocellulosic biomass for second-generation ethanol production necessitates advanced yeast strains capable of fermenting a wider array of complex sugars under harsh conditions, expanding the market's technical scope.
- Genetic Engineering Advances:Developments in synthetic biology and CRISPR gene-editing enable the creation of yeast with superior tolerance to inhibitors, high temperatures, and ethanol concentrations, directly improving fermentation yields and lowering operational costs for biorefineries.
Market Restraints
- Feedstock Price Volatility:The market is heavily dependent on the price and availability of agricultural commodities like corn and sugarcane. Fluctuations in these feedstock costs can squeeze ethanol producer margins, slowing investment in premium yeast technologies.
- High Capital Costs:The substantial capital expenditure required to build new biorefineries or retrofit existing ones for advanced feedstocks acts as a barrier to market expansion, limiting the overall installed capacity for ethanol fermentation.
- Technical Hurdles in Lignocellulose Conversion:Despite progress, efficiently breaking down and fermenting lignocellulosic materials at an industrial scale remains a significant technical challenge, constraining the growth of the second-generation bioethanol segment and its associated yeast demand.
Strategic Opportunities
- Sustainable Aviation Fuel (SAF) Production:Yeast-based fermentation pathways are emerging for the production of alcohol-to-jet fuel. This creates an opportunity for yeast developers to formulate strains optimized for producing precursors for SAF, a high-value, policy-supported market.
- Expansion in Southeast Asia:Nations in Southeast Asia with abundant agricultural residues and developing biofuel policies represent an underpenetrated geographic market for advanced fermentation technologies, including specialized bioethanol yeast strains.
- Bio-based Chemical Production:Yeast can be engineered to produce a variety of high-value bio-based chemicals from renewable sugars. This diversification beyond fuel allows producers to enter new markets and hedge against fuel price volatility.
Industry Challenges
- Strain Performance Consistency:Maintaining the stability and consistent performance of genetically modified yeast strains in large-scale, variable industrial fermentation environments is a persistent operational challenge for biofuel producers.
- Logistical Complexities:Distributing and storing live biological products, particularly temperature-sensitive liquid yeast, to biorefineries in remote agricultural regions requires a specialized and costly cold chain infrastructure, posing logistical hurdles.
- Intellectual Property Management:The development of proprietary, high-performance yeast strains involves significant R&D investment, creating challenges around intellectual property protection, licensing agreements, and the risk of patent infringement disputes between technology providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioethanol Yeast Market |
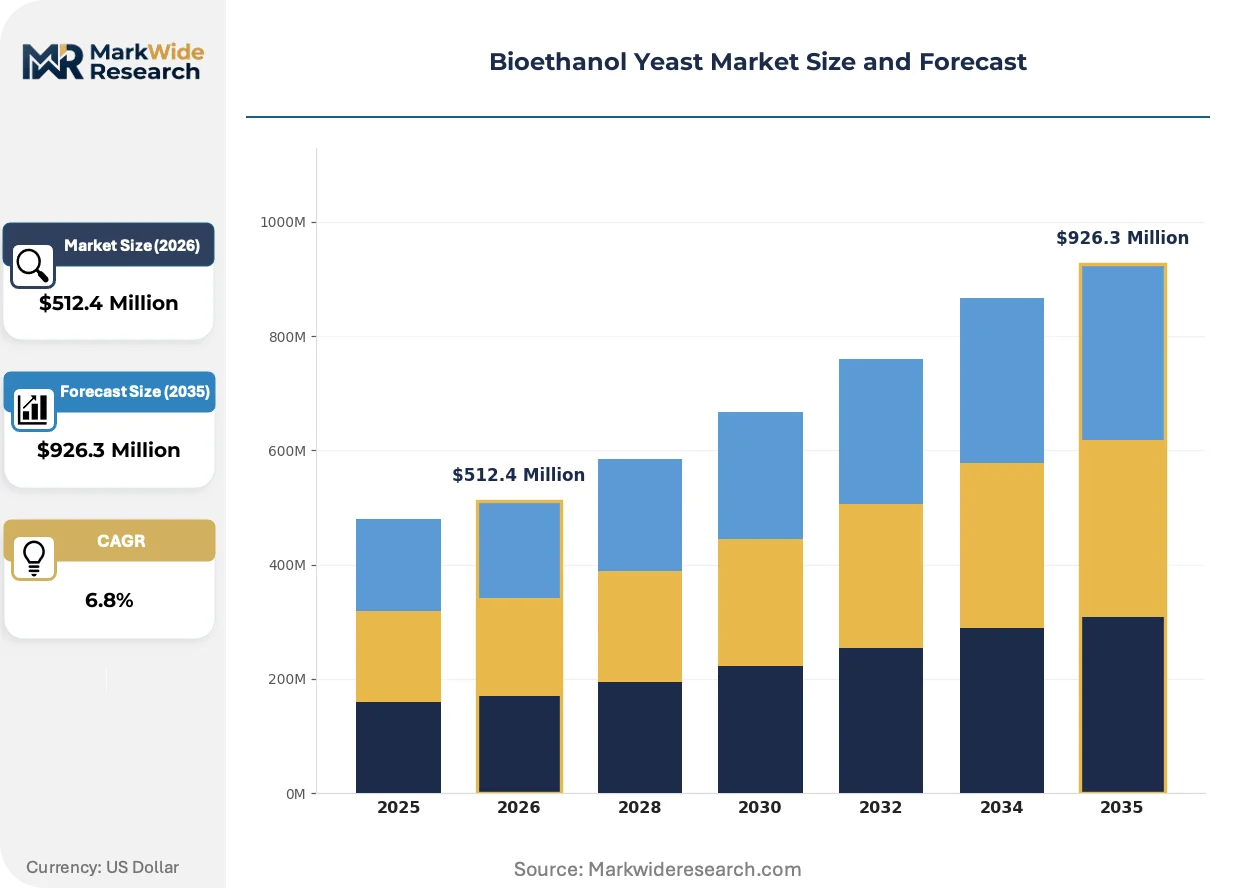
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $926.3 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Yeast, Dry Yeast, Active Dry Yeast, Instant Yeast Application: Fermentation, Distillation, Bioprocessing, Feed Additives Delivery Mode: Bulk Supply, Packaged Supply, Custom Orders, Direct Sale End User: Biofuel Producers, Breweries, Distilleries, Food Industry |
| Companies Covered | Novozymes, Associated British Foods plc, DSM, AB Mauri, Cargill, Inc., AngelYeast Co., Ltd., LALLEMAND Inc., Lesaffre, Leiber GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioethanol Yeast Market Strategic Shifts & Innovations
The market is undergoing a transformation driven by the convergence of synthetic biology and industrial bioprocessing. This alignment is turning yeast from a simple fermentation agent into a sophisticated, programmable biocatalyst designed to meet specific economic and environmental performance targets set by regulators and producers.
CRISPR-based gene editing allows for the precise and rapid development of custom yeast strains. Biofuel producers are increasingly adopting these engineered microbes to unlock higher ethanol yields from diverse and challenging feedstocks. This targeted genetic modification is rendering obsolete the slower, less predictable methods of random mutagenesis and selective breeding that previously dominated strain improvement programs.
Brazil's RenovaBio program is altering the competitive landscape by creating a carbon credit market for biofuels. The policy directly rewards ethanol producers for reducing the carbon intensity of their production process, creating a financial incentive for higher efficiency. Yeast suppliers serving the Brazilian market are now compelled to demonstrate how their strains contribute to a lower carbon intensity score to secure contracts with ethanol mills.
A notable shift in procurement involves biofuel producers favoring integrated technology packages over standalone component purchases. This model, which bundles high-performance yeast with tailored enzyme cocktails and dedicated technical support, displaces traditional, transactional sales of yeast as a commodity. This trend is most pronounced in the mature corn ethanol sector in the United States, where operators seek comprehensive solutions to maximize plant efficiency.
Bioethanol Yeast Market Segmentation
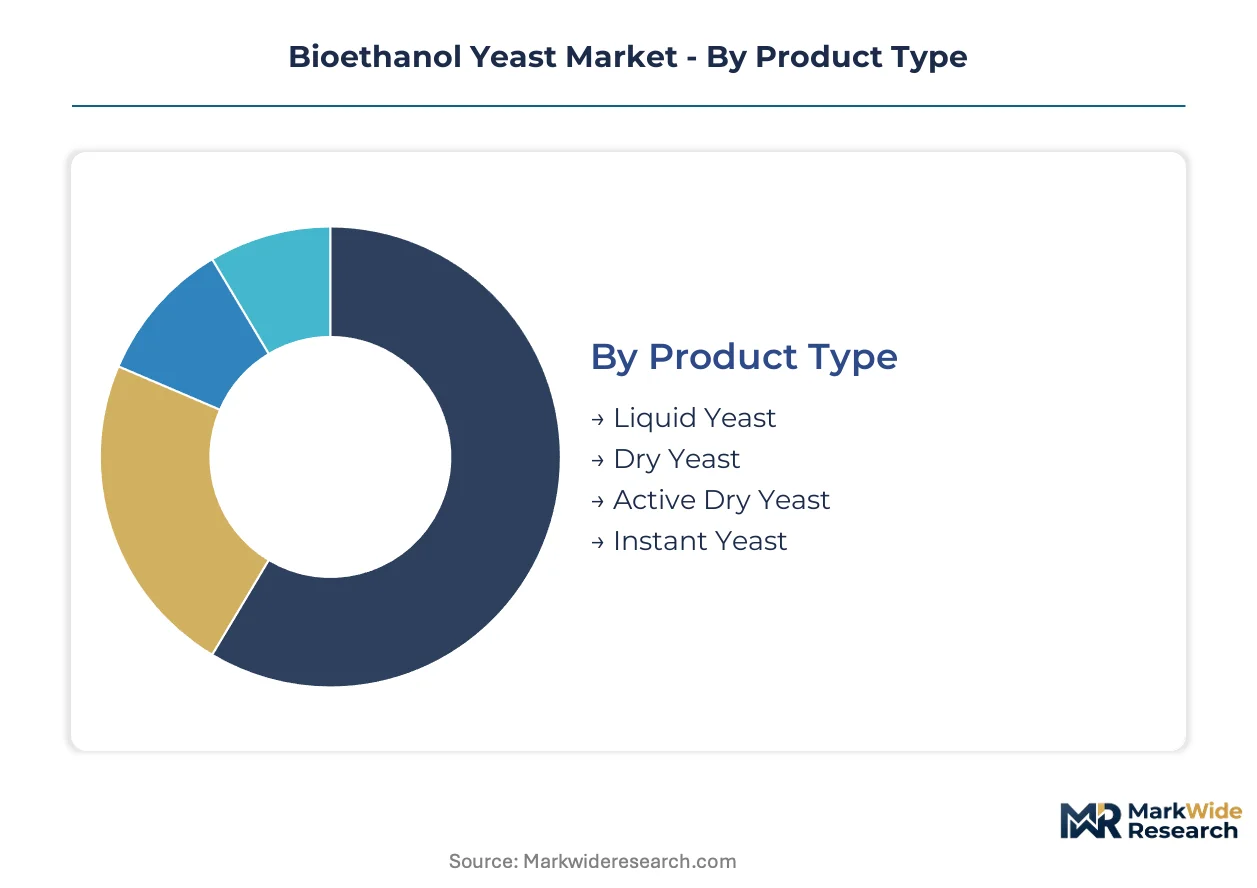
The bioethanol yeast market’s segmentation provides a granular view of product forms, application areas, delivery mechanisms, and end-user profiles. This detailed breakdown helps identify specific demand drivers and technological preferences across various industrial sectors. Understanding these segments is crucial for strategic market positioning.
Product Type:
The product type dimension delineates the physical forms in which bioethanol yeast is supplied to industrial users.
- Dry Yeast:This format involves yeast cells dehydrated to a low moisture content, offering extended shelf life and reduced transportation costs. Demand concentrates in large-scale ethanol plants in Brazil, driven by logistical advantages for remote facilities.
- Active Dry Yeast:Active dry yeast contains viable yeast cells ready for immediate rehydration and fermentation, providing consistent performance. Biofuel producers in the United States increasingly favor this type for its reliability and efficiency in corn ethanol production.
- Liquid Yeast:Liquid yeast consists of a suspension of live yeast cells, requiring careful temperature control during transport and storage.
- Instant Yeast:Instant yeast is a highly active, finely granulated dry yeast that dissolves quickly, primarily used in smaller-scale or specialized fermentation processes.
Dry Yeast holds installed capacity. Active Dry Yeast is rotating up the share rankings.
Application:
The functional utility of bioethanol yeast is categorized by its primary application within industrial processes.
- Fermentation:This is the core application where yeast converts sugars from feedstocks like corn and sugarcane into ethanol. Biofuel producers globally prioritize yeast strains optimized for high ethanol yield and stress tolerance during this critical stage.
- Bioprocessing:Bioprocessing applications involve using yeast for broader industrial biotechnology, including the production of various chemicals or advanced biofuels. Research institutions and specialized chemical manufacturers drive demand for highly engineered yeast strains in this segment.
- Distillation:While not a direct yeast application, this segment refers to the post-fermentation separation process where yeast efficiency impacts overall product purity.
- Feed Additives:Yeast byproducts or inactivated yeast cells find use as nutritional supplements in animal feed formulations.
Fermentation dominates current usage. Bioprocessing applications are expanding most quickly.
Delivery Mode:
The supply concentration for bioethanol yeast reflects how producers distribute their products to industrial clients.
- Bulk Supply:This mode involves large-volume deliveries of yeast, often in tankers or large containers, directly to major industrial facilities. Ethanol refineries in the United States and Brazil predominantly rely on bulk supply for continuous, high-volume operations.
- Custom Orders:Custom orders involve tailor-made yeast formulations or specific delivery schedules to meet unique client requirements. Advanced biofuel developers and specialized bioprocessing plants often leverage custom orders for niche applications.
- Packaged Supply:Packaged supply includes yeast delivered in smaller, standardized units suitable for medium-sized operations or specific batch processes.
- Direct Sale:Direct sale involves manufacturers selling yeast directly to end-users, bypassing intermediaries, which allows for closer customer relationships.
Bulk Supply represents the largest volume. Custom Orders are gaining share rapidly.
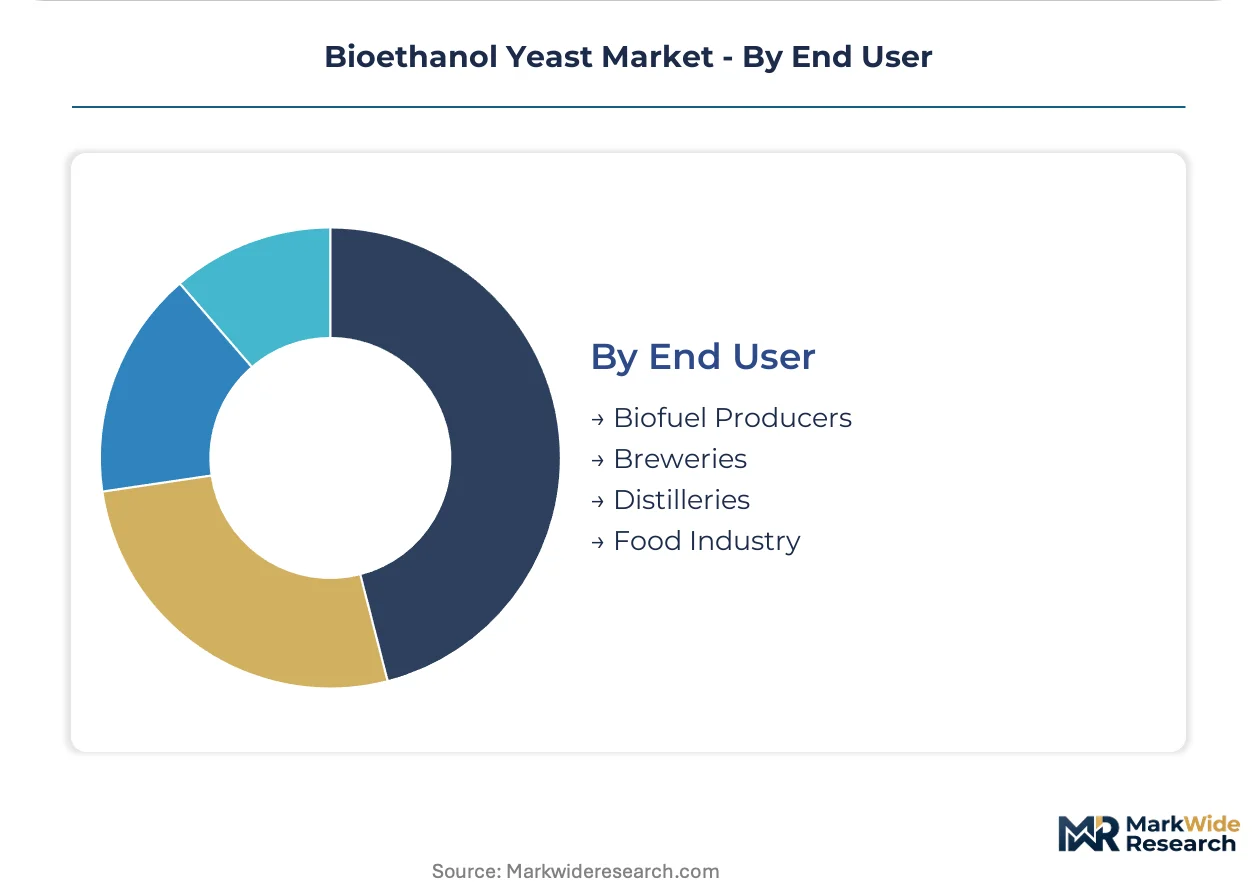
End User:
Customer type segmentation reveals the diverse industrial sectors that utilize bioethanol yeast for their production needs.
- Biofuel Producers:This segment includes large-scale facilities converting agricultural feedstocks into fuel-grade ethanol, representing the primary demand driver. Regulatory mandates like the US EPA's Renewable Fuel Standard consistently stimulate demand from these producers.
- Distilleries:Distilleries use specific yeast strains for fermenting grains to produce alcoholic beverages, including spirits like whiskey and vodka. Demand in this sector focuses on flavor profile and fermentation consistency alongside ethanol yield.
- Breweries:Breweries employ specialized yeast for fermenting malted barley and other grains to produce beer, with focus on specific flavor characteristics.
- Food Industry:The food industry utilizes yeast in various applications beyond ethanol production, including baking, food flavoring, and nutritional supplements.
Biofuel Producers consume the majority of bioethanol yeast. Breweries represent a stable, significant consumer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bioethanol yeast market exhibits a complex export-import balance, with major biofuel-producing nations often serving as both significant consumers and technology innovators. Demand for advanced yeast strains is concentrated in regions with established agricultural feedstocks and robust biofuel mandates, driving localized production and specialized supply chains. This dynamic creates distinct regional market characteristics, influencing investment and technological adoption patterns.
United States
Demand for bioethanol yeast in the United States stems from its vast corn ethanol industry and stringent biofuel blending requirements. The US EPA's Renewable Fuel Standard (RFS) mandates significant volumes of renewable fuels, securing consistent demand for high-efficiency yeast. Major corn-producing states like Iowa and Illinois host numerous ethanol plants, forming a dense industrial cluster for yeast suppliers.
Brazil
Brazil's bioethanol yeast market is driven by its dominant sugarcane ethanol production and progressive decarbonization policies. The RenovaBio program incentivizes lower carbon intensity, prompting ethanol mills to adopt advanced yeast for improved yields. Production facilities in São Paulo and Minas Gerais states represent key centers of demand for specialized fermentation solutions.
China
China's growing bioethanol yeast demand is fueled by its national biofuel development plans and the push to utilize agricultural residues. Government initiatives promote ethanol production from diverse feedstocks, requiring robust yeast strains. Industrial parks in provinces such as Henan and Shandong are expanding their biofuel capacities, creating new market opportunities.
India
India's market for bioethanol yeast is expanding due to ambitious ethanol blending targets and abundant sugarcane and rice feedstocks. The National Biofuel Policy aims to reduce crude oil imports, stimulating investment in new ethanol distilleries. States like Uttar Pradesh and Maharashtra, with their strong agricultural bases, are emerging as significant consumption hubs.
Germany
Germany's bioethanol yeast sector is influenced by the European Union's Renewable Energy Directive (RED) and its focus on advanced biofuels from non-food feedstocks. German policy supports sustainable biofuel production, driving the need for yeast strains capable of fermenting lignocellulosic biomass. Research and industrial facilities in regions like Bavaria and North Rhine-Westphalia are at the forefront of this technological shift.
Bioethanol Yeast Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with a few large integrated bio-ingredient companies alongside specialized biotech firms. These players employ diverse strategies to capture market share, ranging from broad portfolio offerings to niche, high-performance solutions. Strategic partnerships and continuous R&D investment represent dominant competitive moves, driving product innovation and market penetration.
Among diversified ingredient suppliers, Associated British Foods plc and DSM exemplify global reach and broad product portfolios, offering yeast solutions across various fermentation industries. AngelYeast Co., Ltd. represents a specialist archetype, focusing on high-performance yeast for specific fermentation processes and catering to evolving industrial requirements. These companies anchor the market through their technological expertise and established distribution networks.
| Leading Market Players |
|---|
| Novozymes |
| Associated British Foods plc |
| DSM |
| AB Mauri |
| Cargill, Inc. |
| AngelYeast Co., Ltd. |
| LALLEMAND Inc. |
| Lesaffre |
| Leiber GmbH |
| Others |
Cost & Logistics Intelligence
Iowa's dense ethanol production cluster significantly influences bioethanol yeast pricing, as its large-scale capacity drives volume-based procurement. This concentration of demand creates leverage for biofuel producers seeking cost-effective microbial solutions.
Pricing Analysis
Biofuel producers anchor value-based pricing for advanced bioethanol yeast strains. Pricing stratifies across premium, standard, and economy tiers based on strain performance and technical support bundles. Feedstock price volatility exerts downward pressure on commodity yeast pricing for large-volume contracts, forcing suppliers to optimize production costs. Large-scale ethanol plants exhibit high price sensitivity for standard strains, while specialized bioprocessing applications prioritize performance over cost.
Supply Chain Analysis
The bioethanol yeast supply chain relies heavily on the availability of agricultural feedstocks like corn and sugarcane, primarily sourced from the United States and Brazil. Yeast manufacturers depend on stable access to these raw materials and specific fermentation nutrients for their own production. Commodity price volatility for these feedstocks represents a significant structural risk for the entire value chain. Distribution runs through bulk supply directly to large-scale biorefineries, with custom orders gaining share for specialized applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioethanol yeast market is in an early-cycle expansion phase, driven by increasing global mandates for renewable fuels. Regulatory frameworks like the US EPA's Renewable Fuel Standard consistently stimulate demand for efficient fermentation solutions.
For Market Incumbents: Harden market position through continuous investment in synthetic biology and CRISPR gene-editing for superior strain performance. Develop integrated technology packages combining yeast with enzyme cocktails to mitigate feedstock price volatility for biofuel producers. Strengthen direct distribution channels to secure long-term contracts with major biorefineries. Invest in certifications demonstrating lower carbon intensity to align with policies like Brazil's RenovaBio program.
For New Entrants and Emerging Players: Niche applications in bio-based chemical production represent the most penetrable entry point. Focus on developing specialized yeast strains for second-generation lignocellulosic feedstocks, addressing current technical hurdles. Target expansion in Southeast Asia, leveraging abundant agricultural residues and developing biofuel policies. Offer custom formulations and dedicated technical support to advanced biofuel developers seeking tailored solutions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified ingredient suppliers seeking to divest non-core fermentation assets. The market demonstrates long-term viability over a 5-10 year horizon, driven by global decarbonization mandates. Seek specialized biotech firms with proprietary gene-editing platforms or strong regional distribution in high-growth areas like India. Increased M&A activity in integrated bioprocessing solutions will signal market consolidation and maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in CRISPR Gene-Editing | Enables rapid development of custom yeast strains for diverse feedstocks, enhancing ethanol yields. |
| Integrated Technology Package Development | Bundles high-performance yeast with enzyme cocktails, maximizing plant efficiency for US corn ethanol operators. |
| Expansion into Sustainable Aviation Fuel | Optimizes yeast strains for producing precursors for SAF, a high-value, policy-supported market. |
| Geographic Market Entry in Southeast Asia | Leverages abundant agricultural residues and developing biofuel policies to access new demand. |
| Vertical Integration into Feedstock Processing | Secures raw material supply and reduces exposure to price volatility for bioethanol producers. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary validation. Primary insights were gathered from biofuel producers, yeast manufacturers, enzyme suppliers, and regulatory affairs specialists. Secondary research involved reviewing US EPA reports, EU Renewable Energy Directive documents, company financial filings, and industry trade association publications. A combination of bottom-up and top-down triangulation ensured data accuracy and comprehensive market sizing.
Forecast inputs considered historical market trends, regulatory mandates, and technological advancements across the analysis window. The analytical framework modeled market dynamics by product type, application, delivery mode, end user, and primary feedstock type. Compound Annual Growth Rates were derived from historical performance and projected impacts of global decarbonization policies, with biofuel blending targets and lignocellulosic conversion rates serving as key industry-specific forecast inputs.
Stress conditions across feedstock price volatility and policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented regarding stable regulatory environments and sustained R&D investment, though unforeseen geopolitical events or rapid technological disruption could revise these projections. Cross-checking against national energy agency reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
Fish Vaccines Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
Asia-Pacific Biostimulants Market