
 Morocco Automotive OEM Coatings Market | 2026-2036
Morocco Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Automotive OEM Coatings Market Insights
Multi-source procurement among Moroccan automotive plants is consolidating around a tighter supplier base with certified technical capabilities. PPG Industries leverages its global color-matching infrastructure to serve Renault's B0 platform production in Tangier. Akzo Nobel N.V. anchors its position through waterborne technology leadership aligned with European export requirements. Facop Peintures competes on proximity advantages and localized logistics for tier-one Moroccan suppliers.
Automotive OEM coatings constitute engineered polymer film systems applied to vehicle bodies and components, typically comprising 15-25 micron multilayer stacks of primer, base coat, and clear coat that provide corrosion protection, aesthetic finish, and UV durability. Their primary purpose is to protect substrate integrity while delivering specified gloss and color stability under harsh operating conditions. Waterborne technology leads volume adoption in Morocco's export-oriented plants due to European regulatory alignment, while UV-curable formulations represent the fastest-growing segment for specialized component finishing. Base coat applications command margin concentration given color complexity and OEM brand differentiation requirements, whereas primer demand scales directly with vehicle production volumes.
Morocco's Ministry of Industry and Trade enforces progressive environmental standards through its industrial acceleration plans, while the country's adherence to EU REACH and RoHS frameworks governs chemical composition in coatings destined for European markets. The national standardization body, IMANOR, coordinates technical compliance with these dual regulatory layers. Stakeholders must monitor the pace of electric vehicle platform localization and its associated coating specification shifts to align R&D investments with evolving OEM requirements.
Market Dynamics
Waterborne base coat systems are displacing solvent-borne formulations across Morocco's export-oriented assembly plants as Renault-Nissan's Tangier facility enforces EU-aligned REACH chemical standards on its supplier base.
Growth Catalysts
- EU REACH Alignment:Morocco's IMANOR adoption of European chemical safety frameworks is mandating low-VOC coating formulations for vehicles destined for European markets.
- Tangier Automotive City:The industrial cluster's concentration of Renault-Nissan stamping and assembly operations is generating localized demand for just-in-time coating supply.
- Waterborne Technology Maturation:Advances in waterborne base coat drying efficiency are closing the productivity gap with solvent-borne systems at Morocco's high-volume plants.
Market Restraints
- Titanium Dioxide Volatility:Pigment input costs fluctuate with global mining supply disruptions, compressing margin predictability for local formulation houses.
- European Supplier Dominance:PPG Industries and Akzo Nobel control color-matching IP and global technical support, limiting indigenous supplier expansion.
- UV-Curable Throughput Limits:Curing lamp infrastructure constraints restrict adoption of fast-cure clear coats beyond specialized component finishing.
Strategic Opportunities
- Kenitra Electric Vehicle Hub:Stellantis' planned battery-electric platform localization will require thermally stable coatings for battery enclosure protection.
- Casablanca-Rabat Corridor Expansion:Tier-one supplier densification in Morocco's industrial heartland enables captive blending facility economics.
- Digital Color Matching:Cloud-based spectrophotometry networks are converging with local technical service capabilities to reduce OEM color approval cycles.
Industry Challenges
- Formulation Chemist Scarcity:Morocco's technical education pipeline produces insufficient polymer chemists trained in waterborne resin synthesis and stability testing.
- Dual Certification Burden:Suppliers must simultaneously satisfy IMANOR national standards and EU REACH documentation requirements, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Automotive OEM Coatings Market |
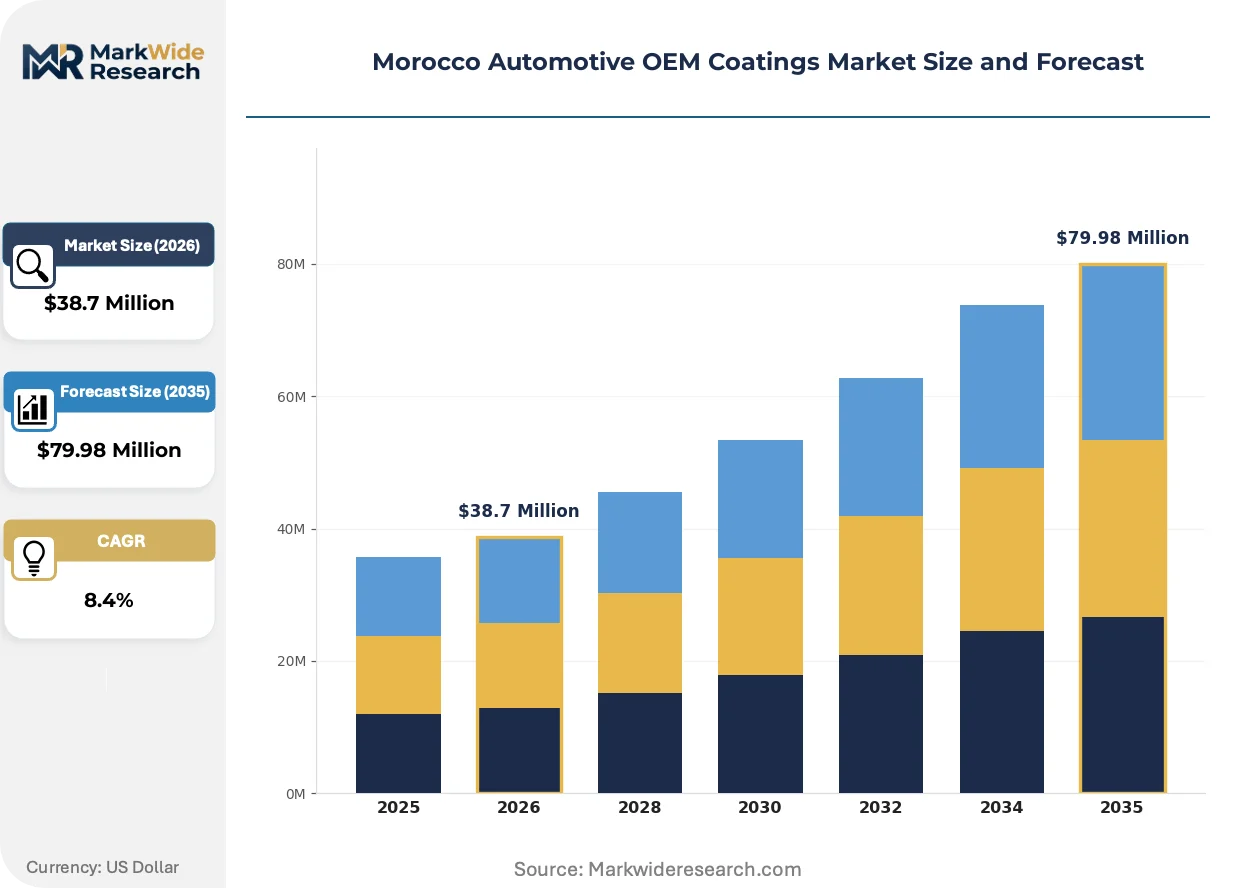
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $79.98 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primer, Clear Coat, Base Coat, Specialty Coatings Application: Exterior, Interior, Chassis, Engine Components Technology: Waterborne, Solventborne, UV-Curable, Powder Coating End User: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | PPG Industries, Inc., Kansai Paint Co., Ltd., Akzo Nobel N.V., Facop Peintures, Durr Group, BASF SE, Nippon Paint Holdings Co., Ltd., El Gammal, Axalta Coating Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Automotive OEM Coatings Market Trends and Innovations
Coating specification shifts are accelerating as electric vehicle architectures demand thermal management films and Morocco's regulatory alignment with Europe tightens chemical compliance windows.
Self-healing clear coat technologies are converging with nanoceramic additive systems to deliver scratch-recovery properties for premium vehicle segments. Renault's Tangier plant is piloting these formulations on its Dacia Sandero export lines. The convergence is compressing traditional warranty claim rates while elevating technical service requirements for local applicators.
REACH Annex XVII restrictions on chromium VI compounds are forcing reformulation of corrosion-resistant primers across Morocco's supplier base. The industrial consequence is a wholesale shift to zirconium-based pretreatment systems. Tier-one Moroccan suppliers serving the Casablanca-Rabat corridor are retooling pretreatment lines to meet the compliance deadline.
Consolidated supplier agreements are replacing fragmented multi-source procurement as Renault-Nissan and Stellantis centralize coating specifications across their Moroccan operations. Technical service integration is displacing spot-buy relationships. The Tangier plant's vendor reduction program exemplifies this concentration most visibly.
Morocco Automotive OEM Coatings Market Segmentation
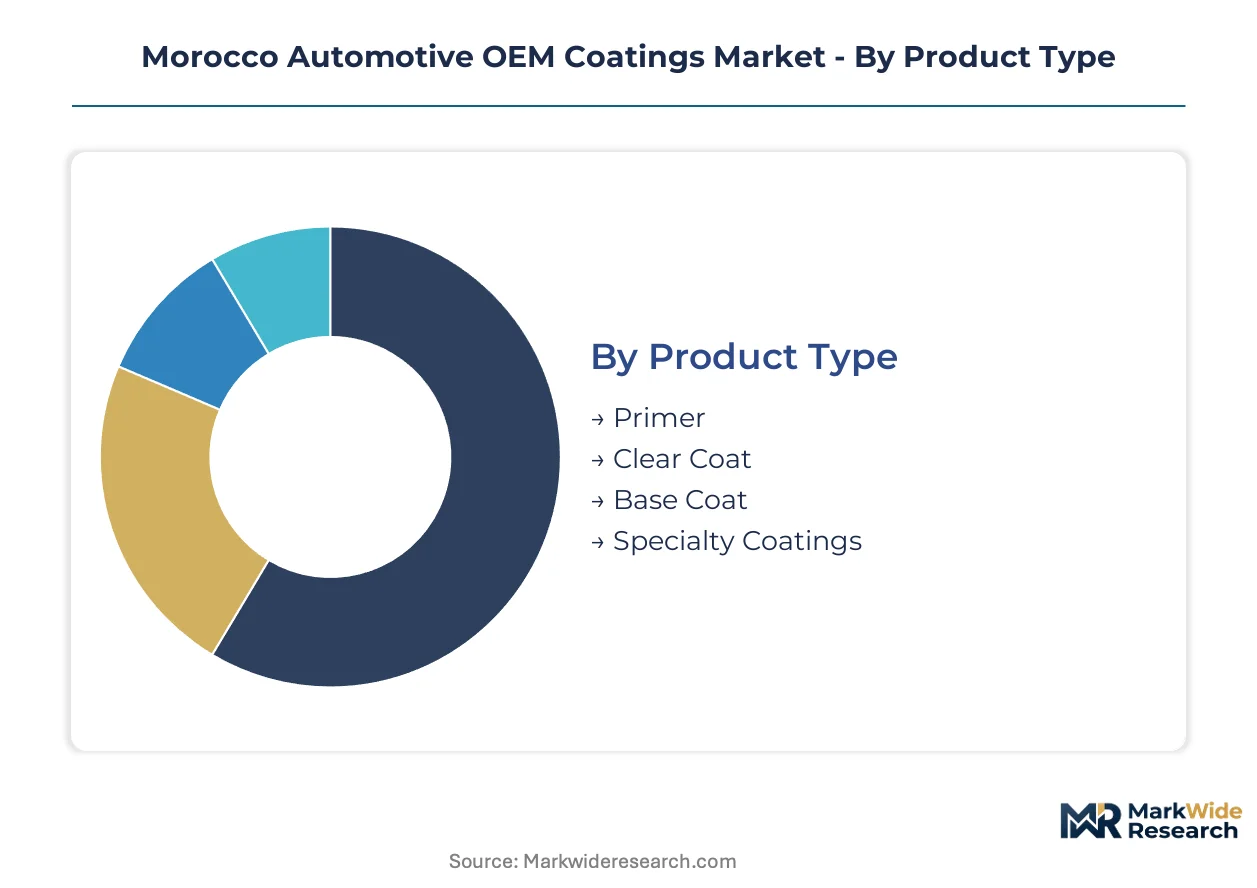
Coating specification divergence across Morocco's automotive assembly plants reflects divergent OEM platform requirements and export-market regulatory pressures. Segmentation clarity enables suppliers to align formulation investments with the highest-velocity demand pockets in Tangier and Kenitra production corridors.
Product Type:
Coating layer functionality determines specification complexity and margin structure across Morocco's OEM supplier base.
- Base Coat:Pigmented polymer systems delivering color fidelity and aesthetic finish, typically 10-15 microns thick. Renault-Nissan's Tangier facility drives concentrated demand for metallic and pearlescent variants that must survive Mediterranean salt-spray exposure during export shipping.
- Clear Coat:Transparent polyurethane or acrylic top layers providing UV resistance and gloss retention. Waterborne clear coat adoption is accelerating fastest here as REACH VOC limits tighten on vehicles destined for EU markets.
- Primer:Corrosion-blocking adhesion promoters applied directly to electrocoated metal substrates.
- Specialty Coatings:Functional films including anti-chip stone guards and acoustic dampening layers for underbody applications.
Base Coat leads on scale; Clear Coat leads on momentum.
Application:
Vehicle zone exposure severity dictates coating performance specifications and reapplication frequency in Moroccan assembly operations.
- Exterior:Full-body surface protection against UV degradation, chemical etching, and mechanical abrasion. The Tangier plant's coastal location intensifies salt-corrosion specifications for all exterior formulations.
- Interior:Dashboard, trim, and cabin surface finishes prioritizing scratch resistance and volatile organic compound emission control. Stellantis' Kenitra electric vehicle hub is driving low-odor waterborne interior specifications for battery platform production.
- Chassis:Underbody structural protection against gravel impact and road salt exposure.
- Engine Components:Thermal-resistant finishes for powertrain heat management and fluid resistance.
Exterior coatings dominate volume absorption; Interior specifications are climbing fastest.
Technology:
Formulation chemistry alignment with EU export standards is restructuring procurement priorities across Morocco's coating supply base.
- Waterborne:Low-VOC resin systems using water as primary carrier solvent. Renault-Nissan's supplier mandate for REACH compliance has made this the default specification at Tangier Automotive City.
- Solventborne:Traditional hydrocarbon-based formulations offering faster drying and superior adhesion on difficult substrates. Declining share reflects regulatory pressure rather than technical inferiority.
- UV-Curable:Photoinitiator-activated systems curing instantly under ultraviolet lamps. Specialized component finishing at Casablanca-Rabat tier-one suppliers represents the primary adoption vector.
- Powder Coating:Thermoset polymer powders applied electrostatically and oven-cured. Limited to wheels and underhood brackets in Moroccan OEM operations.
Waterborne systems anchor volume; UV-Curable formats are expanding most quickly.
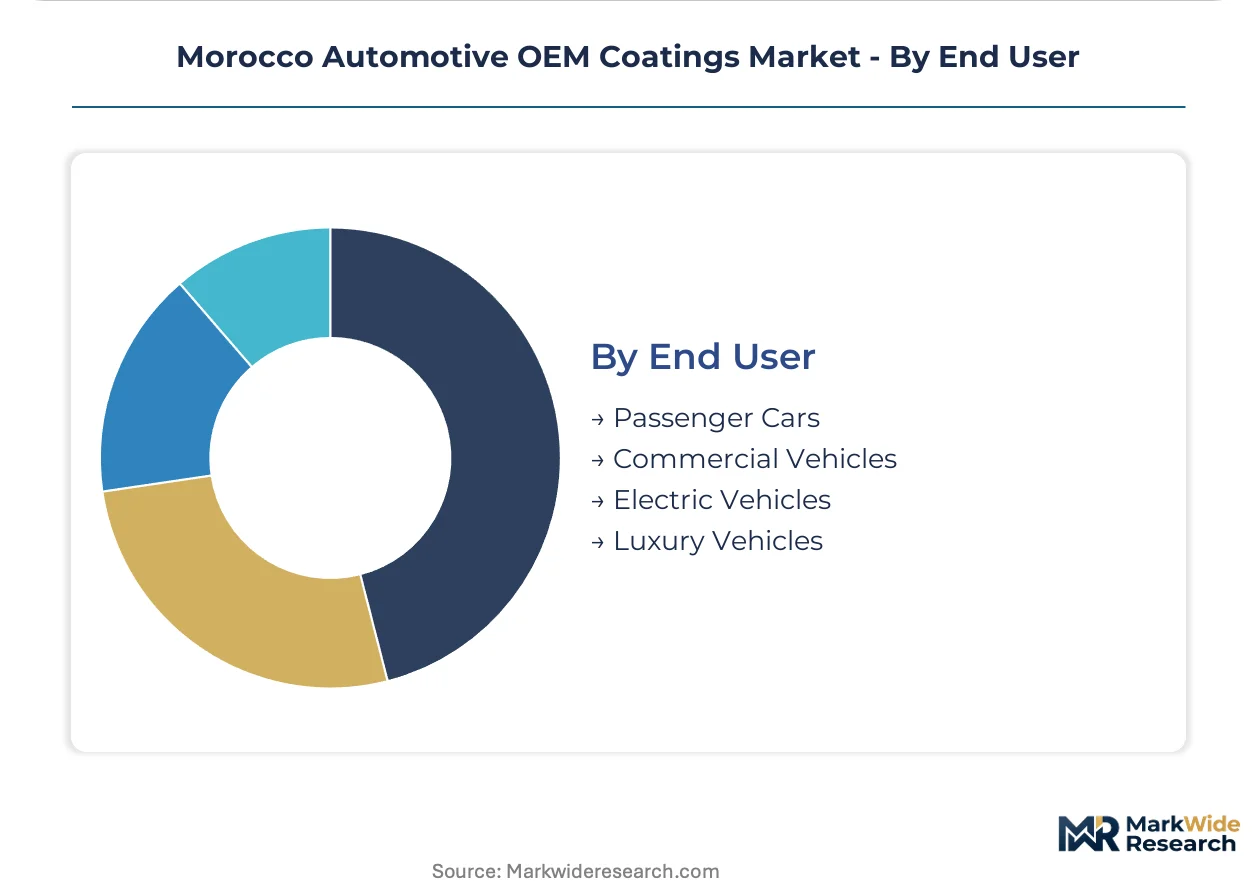
End User:
Vehicle platform architecture determines coating thermal specifications, color complexity, and application automation requirements.
- Passenger Cars:High-volume Dacia and Renault models from Tangier requiring standardized color palettes and rapid line-change flexibility. This segment absorbs the majority of Morocco's OEM coating throughput.
- Electric Vehicles:Battery enclosure thermal management films and lightweight substrate adhesion promoters. Stellantis' planned Kenitra BEV platform is catalyzing formulation R&D for flame-retardant specifications.
- Commercial Vehicles:Heavy-duty durability requirements for Moroccan-assembled vans and light trucks.
- Luxury Vehicles:Premium finish depth and self-healing clear coat specifications for limited export volumes.
Passenger Cars command absolute volume; Electric Vehicles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage toward lower-compliance-cost jurisdictions is restructuring coating procurement patterns across North Africa. Morocco's REACH-aligned regulatory framework attracts European OEM assembly seeking chemical-standard continuity without EU labor overhead. Tangier Automotive City and Kenitra anchor this migration with integrated supplier parks.
Tangier-Tetouan-Al Hoceima
Renault-Nissan's stamping and paint operations at the Tangier Med industrial zone consume the majority of Morocco's OEM coating throughput. IMANOR's adoption of EU REACH chemical safety frameworks mandates low-VOC waterborne formulations for all vehicles destined for European markets. The Tanger Automotive City cluster concentrates tier-one coating logistics within 15 kilometers of the assembly plant.
Casablanca-Settat
Stellantis' Kenitra electric vehicle hub is catalyzing demand for thermally stable battery enclosure coatings and lightweight substrate adhesion promoters. The national standardization body coordinates technical compliance with dual regulatory layers covering both domestic and export specifications. Industrial densification along the A1 highway corridor enables just-in-time coating supply to multiple OEM facilities.
Rabat-Sale-Kenitra
Stellantis' planned battery-electric platform localization requires flame-retardant coating specifications for high-voltage component protection. Morocco's Ministry of Industry and Trade enforces progressive environmental standards through industrial acceleration plans targeting the northern production corridor. The Kenitra Atlantic Free Zone is emerging as a secondary coating blending and distribution node.
Fez-Meknes
Component supplier migration from traditional Casablanca-Rabat concentration is creating satellite demand for primer and specialty coating applications. Regional industrial development agencies offer tax incentives for coating formulation facilities serving tier-two automotive suppliers. The Meknes industrial zone hosts emerging metal pretreatment operations supporting upstream coating adhesion requirements.
Morocco Automotive OEM Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized component niches and localized service capabilities. The supplier base concentrates around multinational coating houses with certified color-matching infrastructure and indigenous distributors leveraging proximity logistics. Three archetypes dominate: global technology leaders with integrated R&D platforms, regional formulation houses with European regulatory expertise, and local distributors capturing tier-two supply relationships. Competitive dynamics center on technical service integration and strategic vendor reduction programs by major OEMs.
Among multinational coating specialists, PPG Industries, Inc., Akzo Nobel N.V., and Facop Peintures exemplify the tiered competitive structure. PPG Industries represents the global technology leadership archetype with integrated color-matching platforms. Akzo Nobel N.V. occupies a position emphasizing waterborne formulation expertise aligned with European export requirements. Facop Peintures anchors the indigenous supplier tier through proximity-based logistics and localized technical service capabilities for Moroccan tier-one suppliers.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Kansai Paint Co., Ltd. |
| Akzo Nobel N.V. |
| Facop Peintures |
| Durr Group |
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| El Gammal |
| Axalta Coating Systems |
| Others |
Pricing and Supply Chain Analysis
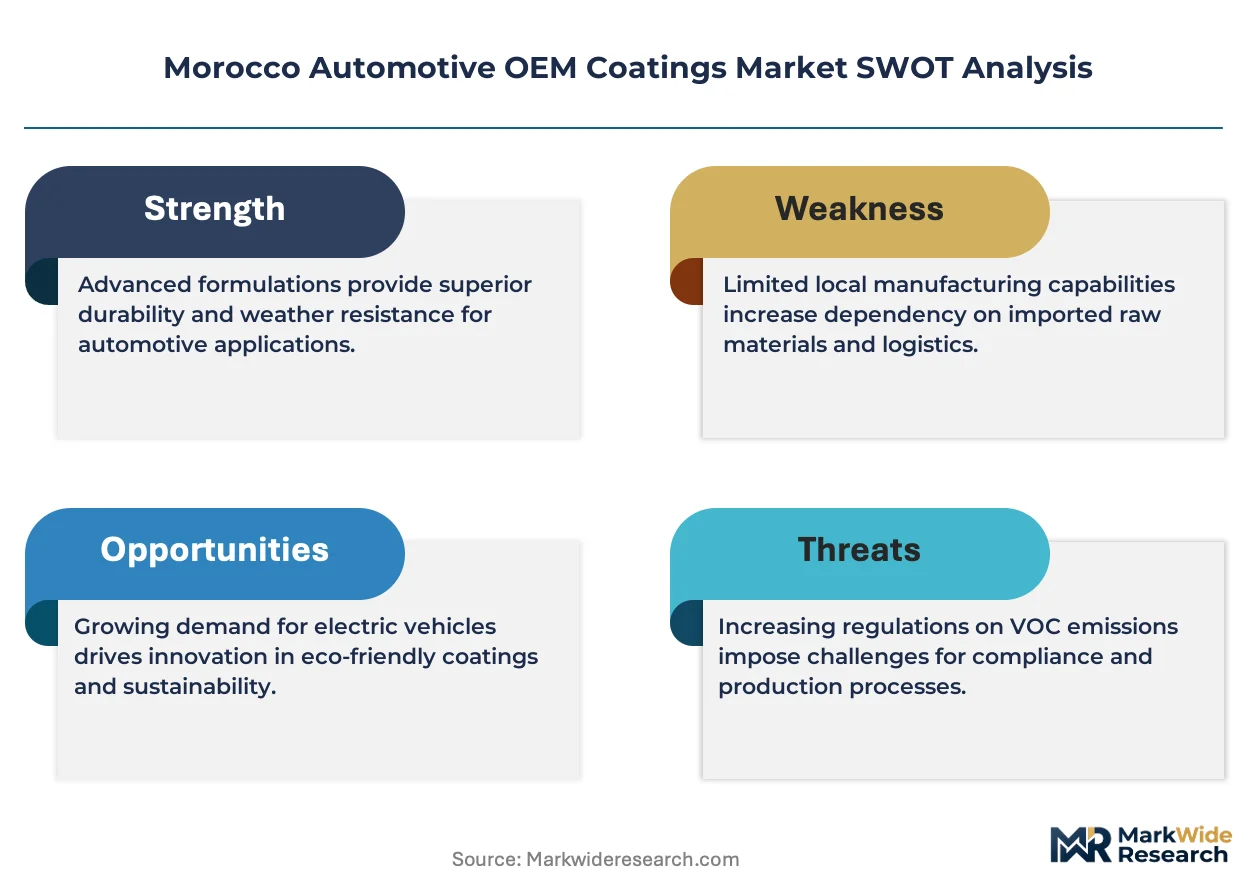
Titanium dioxide pigment costs cascade through Morocco's coating value chain from global mining operations to localized formulation margins, with REACH compliance premiums layering atop raw material volatility to stratify pricing tiers across export-bound and domestic-only supply streams.
Pricing Analysis
Input-cost pass-through from titanium dioxide and specialty resin suppliers governs margin compression at Moroccan formulation houses. Three-tier pricing structure across premium, standard, and economy levels separates PPG and Akzo Nobel's certified color-matching platforms from regional European houses and indigenous distributors like Facop Peintures. Pricing pressure stems from IMANOR's progressive environmental enforcement tightening formulation windows. Tier-one OEM buyers exhibit lowest price sensitivity given warranty integration requirements, while tier-two component suppliers absorb maximum cost compression.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch specialty chemical suppliers dominating waterborne resin feedstocks for Morocco's REACH-aligned plants. The supply chain draws from Belgium, France, and Spain for pretreatment chemicals, with zirconium-based conversion coatings replacing chromium VI systems. Tariff exposure on EU-imported raw materials poses structural risk given Morocco's EU association agreement dependencies. Distribution runs through Tangier Med port logistics and captive blending facilities within 15 kilometers of Renault-Nissan's assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's automotive coatings market functions as a regulatory compounder where IMANOR's REACH alignment deadlines and Stellantis' Kenitra electric vehicle hub are forcing simultaneous formulation and thermal specification investments across the supplier base.
For Market Incumbents: Extend technical service integration beyond color-matching into digital spectrophotometry networks to compress OEM approval cycles. Defend against emerging regional European houses by anchoring waterborne platform standardization across Renault-Nissan and Stellantis operations. Capacity addition in Kenitra's Atlantic Free Zone captures electric vehicle coating demand before competitor localization.
For New Entrants and Emerging Players: Tier-two Moroccan component suppliers serving the Casablanca-Rabat corridor represent the most penetrable buyer archetype given incumbent neglect of sub-scale logistics. Specialized UV-curable formulations for underbody acoustic dampening layers offer white-space entry with lower certification burden than full exterior systems. Go-to-market through Fez-Meknes industrial zone tax incentives enables pretreatment chemical bundling before coating specification.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual IMANOR-REACH certification burdens exceed indigenous technical education pipeline output. Long-term viability favors acquisition targets with captive zirconium pretreatment capabilities and established OEM technical service relationships. The signal to watch is Stellantis' Kenitra battery platform localization pace and its associated flame-retardant coating specification releases.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Platform Standardization | Renault-Nissan's Tangier supplier mandate locks in low-VOC specifications across Moroccan export production. |
| Zirconium Pretreatment Line Retooling | Tier-one Casablanca-Rabat suppliers are converting chromium VI systems ahead of REACH Annex XVII deadlines. |
| Kenitra Blending Facility Localization | Stellantis' electric vehicle hub proximity enables just-in-time thermal coating supply for battery enclosures. |
| Digital Color Matching Infrastructure | Cloud-based spectrophotometry networks reduce OEM approval cycles from weeks to days at Tangier Automotive City. |
| Flame-Retardant Formulation R&D | Battery platform high-voltage protection specifications are opening specialized coating development partnerships. |
Research Methodology
Coverage spans Morocco's northern production corridor, Casablanca-Rabat industrial zone, and emerging Fez-Meknes satellite clusters, with primary inputs from each. The analysis combines interviews with OEM platform engineers, tier-one procurement leads, IMANOR standardization officials, and coating formulation chemists with secondary validation from customs trade data, vehicle production databases, and REACH regulatory filings. Bottom-up coating volume modeling triangulates against top-down OEM assembly forecasts.
Granularity-level framing applies vehicle propulsion architecture, coating layer functionality, and technology chemistry as core segmentation dimensions across the projection horizon. CAGRs derive from production volume elasticity to coating content per vehicle and technology substitution curves. Forecast inputs include Renault-Nissan Tangier utilization rates and Stellantis Kenitra platform localization milestones.
Underlying measurement precision varies by segment; waterborne base coat volumes carry tighter precision than emerging UV-curable specialty applications. Forecasts reflect assumptions on EU-Morocco trade continuity and electric vehicle platform localization pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
North America Epoxy Powder Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Marine Nanocoating Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
North America Coil Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Sol-Gel Coatings Market
Coatings
Global Coil Coatings Market