
 Oil Country Tubular Goods (OCTG) Market | 2026-2036
Oil Country Tubular Goods (OCTG) Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Country Tubular Goods (OCTG) Market Intelligence
A scarcity of metallurgists and certified welders proficient in premium alloy steels is reorganizing manufacturing priorities toward automation and process control. Tenaris leverages its global service center network to support complex drilling projects with just-in-time inventory. Vallourec differentiates through its proprietary premium connection technology for demanding applications, while Nippon Steel Corporation competes on its extensive portfolio of high-grade steel formulations for sour service and deepwater wells.
Oil Country Tubular Goods (OCTG) encompass a range of steel pipes, including casing, tubing, and drill pipe, used in oil and gas exploration and production. These products are engineered to withstand extreme pressures, high tensile loads, and corrosive downhole environments. While casing products constitute the largest market segment by volume, premium alloy steel grades represent the fastest-growing category. This growth supports drilling applications in complex geological formations requiring superior material properties.
Product specifications are governed by American Petroleum Institute (API) standards, which function as a global benchmark for market access. Concurrently, environmental regulations from bodies like the US EPA and frameworks such as the EU Green Deal influence drilling activity. The key decision for producers and exploration companies involves balancing the upfront cost of standard casing against the long-term operational security provided by premium alloy grades in harsh environments.
Market Dynamics
The central dynamic is a technical bifurcation, where demand for standard-grade OCTG stagnates while exploration in complex geologies like pre-salt and shale gas formations creates intense demand for advanced, high-margin premium alloy steel grades.
Growth Catalysts
- Unconventional Drilling:Sustained activity in North American shale plays like the Permian Basin and Argentina's Vaca Muerta requires casing designed for horizontal wells and hydraulic fracturing.
- Premium Alloy Development:Metallurgical advances are yielding new grades with superior resistance to sour service and CO2 corrosion, enabling production from challenging reservoirs.
- Energy Security Policies:Government initiatives in India and Brazil to increase domestic oil and gas production support long-term exploration, directly benefiting OCTG demand.
Market Restraints
- Alloy Price Volatility:The cost of inputs like nickel and chromium is subject to sharp fluctuations, complicating production costing and eroding margins on premium grades.
- Seamless Pipe Capacity:Production of high-quality seamless pipes for deepwater applications is concentrated among a few global producers, creating potential bottlenecks.
- Substitution from Composites:In certain low-pressure and corrosive applications, composite pipes are emerging as a niche alternative, threatening a segment of the steel OCTG market.
Strategic Opportunities
- Geothermal and CCUS Wells:Adapting OCTG products for emerging energy applications like high-temperature geothermal wells and carbon dioxide injection opens a new, non-cyclical market segment.
- Digital Integration:Embedding sensors into casing to create "smart pipes" for real-time downhole monitoring presents a high-value service opportunity beyond the physical product.
- Frontier Exploration:New offshore discoveries in Guyana and the Eastern Mediterranean will require significant investment in deepwater-rated OCTG as these fields develop.
Industry Challenges
- Skilled Labor Shortages:A scarcity of metallurgists and certified welders for advanced, high-alloy steels constrains manufacturing capacity and increases labor costs for premium products.
- API Certification Delays:The process of achieving American Petroleum Institute (API) certification for new, proprietary grades can be lengthy, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Country Tubular Goods (OCTG) Market |
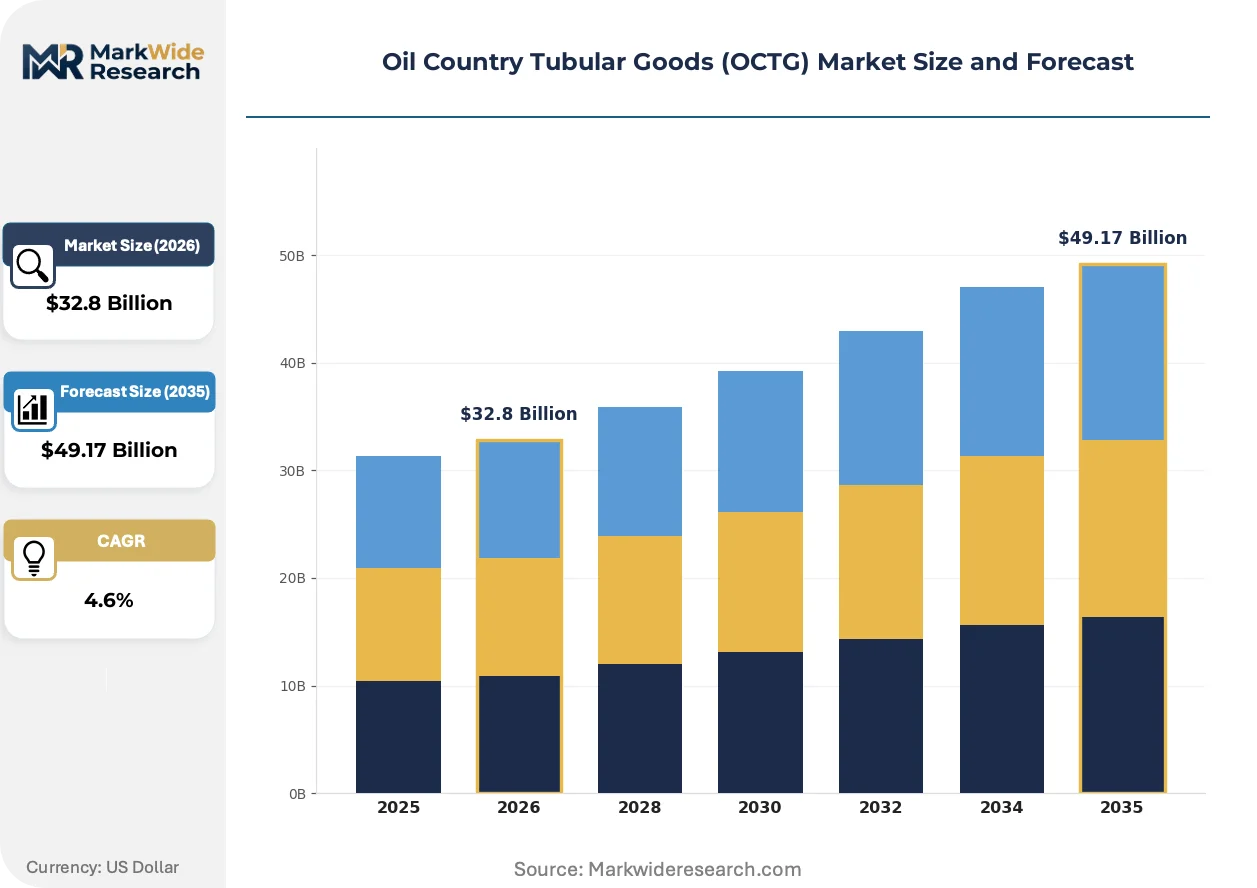
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casing, Tubing, Drill Pipe, Pup Joints, Unions Steel Grade: Carbon Steel, Alloy Steel, Stainless Steel, Premium Alloy, Microalloyed Steel Application: Drilling, Well Completion, Well Intervention, Production, Pipeline Transportation End User: Exploration & Production Companies, Service Providers, Engineering Firms, Contractors |
| Companies Covered | U.S. Steel Corporation, ArcelorMittal, Tenaris, JFE Steel Corporation, Nippon Steel Corporation, TMK, National Oilwell Varco, EVRAZ North America, Vallourec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Country Tubular Goods (OCTG) Market Strategic Shifts & Innovations
Material science and data are converging to redefine OCTG performance. The industry is moving beyond simple commodity pipe toward engineered systems designed for specific well challenges while navigating stricter environmental oversight from regulators.
Proprietary premium connection technology provides a gas-tight, metal-to-metal seal critical for high-pressure and high-temperature (HPHT) wells. Exploration and production companies are standardizing these connections for deepwater and complex unconventional plays. This advanced connection technology is supplanting older, less reliable API-threaded couplings that pose a risk of failure under extreme downhole conditions.
The EU Green Deal and related regulations like the Carbon Border Adjustment Mechanism (CBAM) are introducing carbon accounting into procurement. This forces steelmakers to invest in lower-emission production and document the carbon footprint of their products. OCTG producers supplying European projects are now evaluated on environmental performance, affecting sourcing decisions for operators.
A significant shift is occurring from transactional pipe sales to comprehensive well-integrity service contracts. Under this model, OCTG suppliers provide not just the physical product but also design consultation and on-site installation support. This integrated approach is most prevalent in complex offshore projects in Brazil and the Gulf of Mexico.
Oil Country Tubular Goods (OCTG) Market Segmentation
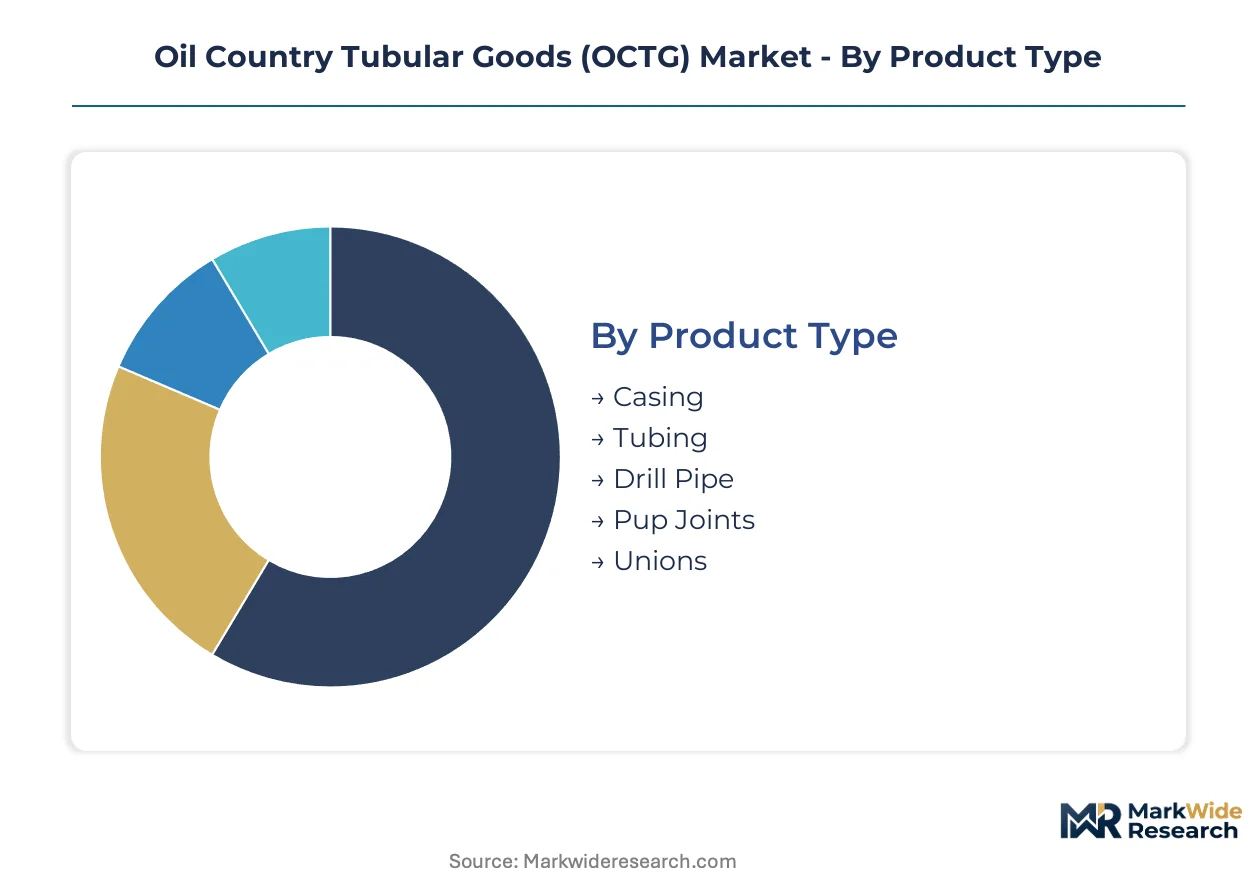
The Oil Country Tubular Goods (OCTG) market segments across product types, steel grades, applications, and end-users, reflecting diverse operational demands within oil and gas exploration. Understanding these distinct categories clarifies where specific engineering requirements and investment priorities converge across the value chain.
Product Type:
Product type segmentation highlights the varying needs for downhole integrity across different drilling and production phases, with some products seeing more localized demand while others are exported globally.
- Casing:These large-diameter pipes line the borehole, preventing collapse and isolating different geological formations. Demand for casing concentrates in North American shale plays like the Permian Basin, where extensive horizontal drilling requires high volumes.
- Drill Pipe:Heavy-duty seamless tubes transmit rotational power and drilling fluid to the drill bit. Complex deepwater projects in Brazil and the Gulf of Mexico drive demand for specialized drill pipe capable of handling extreme torque and pressure.
- Tubing:Smaller diameter pipes transport oil and gas from the production zone to the surface. Tubing products are essential for maintaining well flow in mature fields and new developments alike.
- Pup Joints:Short lengths of pipe used to adjust the length of a pipe string or to space out downhole tools. These are critical for precise wellbore assembly.
- Unions:Connectors used to join pipe sections, particularly in surface equipment and smaller bore applications. Unions ensure leak-proof connections in various field operations.
Casing holds the largest market share by volume; momentum sits with drill pipe for advanced drilling operations.
Steel Grade:
Steel grade differentiation reflects the material science advancements required to operate in increasingly hostile downhole environments, directly impacting the performance and longevity of OCTG products.
- Premium Alloy:These high-performance steels offer superior resistance to sour gas (H2S), CO2 corrosion, and high temperatures, crucial for challenging pre-salt and deepwater reservoirs. Exploration companies in the Eastern Mediterranean require these alloys for long-term well integrity.
- Carbon Steel:The most common and cost-effective grade, suitable for conventional wells with less severe corrosive conditions and moderate pressures. Standard carbon steel pipes are widely used in onshore conventional drilling.
- Alloy Steel:These grades provide enhanced strength and toughness over carbon steel, suitable for moderately demanding well conditions. Alloy steels find use in intermediate depth wells and some unconventional plays.
- Stainless Steel:Chosen for its excellent corrosion resistance in highly aggressive environments, though at a higher cost. Stainless steel is deployed in specific corrosive zones within a well.
- Microalloyed Steel:Steels with small additions of alloying elements to improve strength and toughness without significant weight increase. These grades are gaining traction for optimized performance in specific applications.
Premium alloy grades command significant pricing power for extreme conditions, while carbon steel remains the foundational material for bulk requirements.
Application:
Application segmentation illustrates the specific operational phases where OCTG products are deployed, with each stage presenting unique demands on material properties and connection technologies.
- Drilling:This phase involves the initial creation of the wellbore, requiring drill pipe to rotate the bit and casing to stabilize the hole. Unconventional drilling in North America drives substantial demand for robust drilling OCTG.
- Well Completion:This involves preparing the well for production, including setting production casing and tubing, and installing downhole equipment. Complex well completions in deepwater fields necessitate high-integrity OCTG.
- Production:The ongoing phase where hydrocarbons are extracted from the reservoir to the surface, primarily utilizing tubing and production casing. Long-term production in mature fields relies on durable OCTG.
- Well Intervention:Operations to maintain or enhance well productivity, such as workovers or re-completions, which may involve specialized tubing and tools. These activities extend the lifespan of existing wells.
- Pipeline Transportation:While not direct downhole OCTG, certain tubular goods are used for transporting produced fluids from the wellhead to processing facilities. This application demands specific pressure ratings and corrosion resistance.
Drilling applications represent the largest volume segment; well completion activities require specialized premium products.
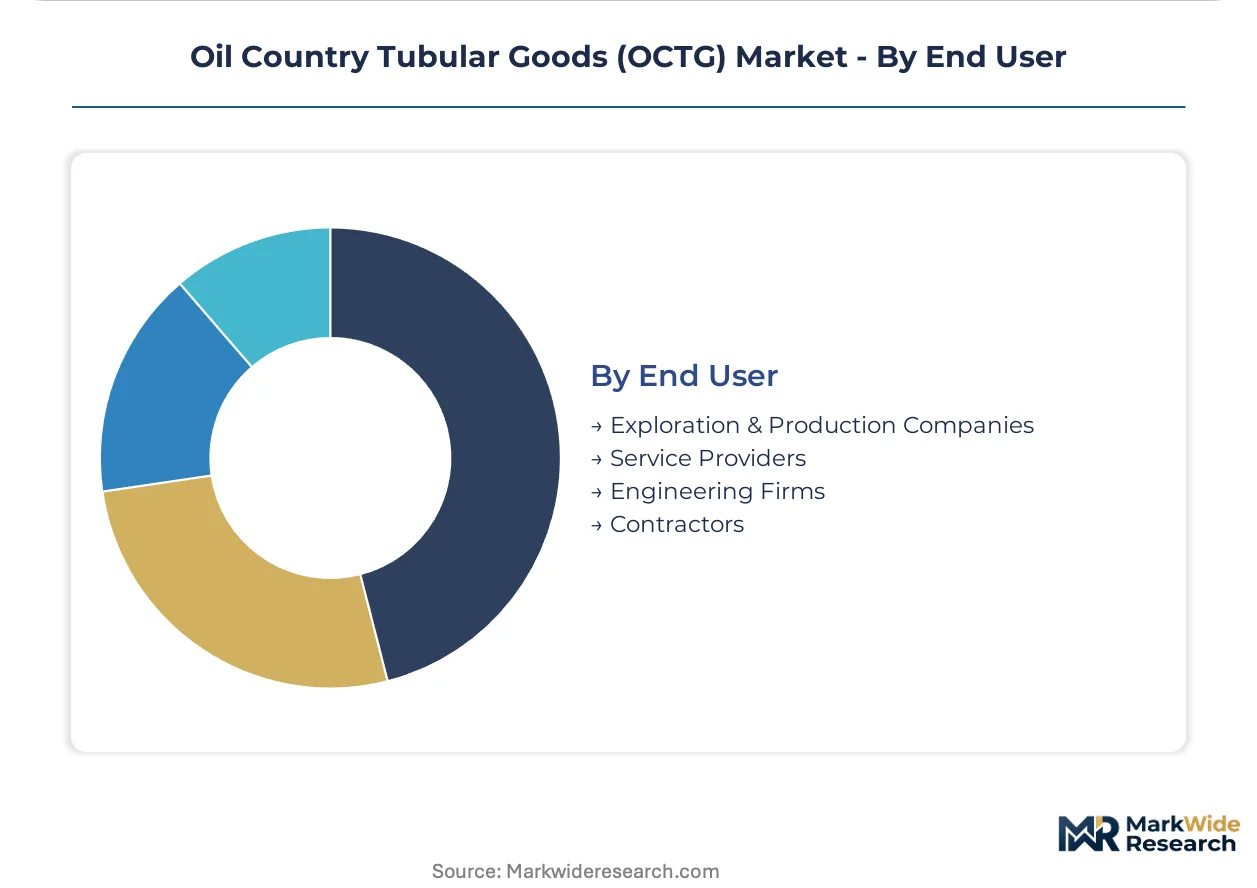
End User:
End-user segmentation highlights the primary entities driving procurement and deployment of OCTG, influencing purchasing patterns and demand for integrated services.
- Exploration & Production Companies:These operators directly own and manage oil and gas assets, making primary decisions on OCTG procurement and specifications. Major E&P firms in Brazil and the United States are significant purchasers.
- Service Providers:Companies offering specialized services like drilling, well completion, and intervention, often procuring OCTG on behalf of E&P companies. These providers leverage global service center networks for just-in-time inventory.
- Engineering Firms:These firms design well architectures and specify material requirements, indirectly influencing OCTG selection. Their expertise is crucial for complex projects requiring custom solutions.
- Contractors:Companies executing specific project components, such as drilling or construction, often purchasing OCTG based on project specifications. Contractors play a vital role in project implementation and logistics.
Exploration & Production Companies dictate the overall demand; Service Providers influence the logistical and technical deployment of OCTG.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global OCTG market exhibits distinct regional consumption patterns. North America, particularly the United States, focuses heavily on unconventional drilling, driving demand for specialized casing and drill pipe. In contrast, South American nations like Brazil prioritize deepwater and pre-salt exploration, requiring premium alloy grades for extreme conditions.
United States
Unconventional drilling in the Permian Basin drives substantial demand for casing and drill pipe. US EPA regulations influence drilling activity, pushing for environmentally compliant materials and processes. Houston, Texas, anchors a vast network of oilfield service companies and OCTG suppliers.
Brazil
Deepwater exploration in pre-salt fields creates intense demand for premium alloy grades. ANVISA regulations ensure material compliance for offshore operations, aligning with government energy security policies. Rio de Janeiro serves as a critical hub for offshore drilling and related OCTG logistics.
India
Government initiatives to increase domestic oil and gas production stimulate demand for various OCTG products. India's PLI scheme supports local manufacturing of energy equipment, including specialized tubular goods. The Gujarat region sees substantial investment in refining and petrochemicals, impacting OCTG consumption.
China
Expanding shale gas development and deep well projects require advanced OCTG solutions. China's dual carbon goals push steelmakers towards greener production methods for tubular goods. The Sichuan Basin is a focal point for unconventional gas exploration, driving local OCTG procurement.
Saudi Arabia
Sustained oil production and exploration in challenging reservoirs generate consistent OCTG demand. SFDA regulations and national content programs influence procurement decisions for tubular products. The Eastern Province concentrates major oil fields and associated supply chain infrastructure.
Oil Country Tubular Goods (OCTG) Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the OCTG market, which is characterized by technical complexity. The competitive structure features a blend of global steel giants and specialized tubular goods manufacturers. Strategic archetypes include large-scale integrated steel producers, premium alloy specialists, and service-oriented solution providers. Companies pursue capacity expansion, strategic partnerships, and technology licensing to strengthen their competitive positioning and address evolving customer needs.
Leading players often differentiate through specialized product portfolios and integrated service models. Tenaris exemplifies a global service center network approach, supporting complex drilling projects with just-in-time inventory and technical expertise. Vallourec occupies a position as a specialist in proprietary premium connection technology, critical for demanding applications like high-pressure and high-temperature wells. Nippon Steel Corporation anchors the high-grade steel formulations segment, offering extensive portfolios for sour service and deepwater wells. These companies invest in metallurgical innovation and advanced manufacturing processes, continuously adapting to the complex requirements of modern oil and gas exploration.
| Leading Market Players |
|---|
| U.S. Steel Corporation |
| ArcelorMittal |
| Tenaris |
| JFE Steel Corporation |
| Nippon Steel Corporation |
| TMK |
| National Oilwell Varco |
| EVRAZ North America |
| Vallourec |
| Others |
Cost & Logistics Intelligence
Composite pipe substitution, while niche, simultaneously reshapes supply geography for certain applications and introduces new pricing economics for steel OCTG. This dynamic forces steelmakers to differentiate further on performance and service to maintain market share.
Pricing Analysis
Long-term contract-based pricing dominates for premium alloy grades, reflecting the specialized manufacturing and integrated service requirements. Price differentiation stems from the specific steel grade's performance characteristics and the level of API certification achieved. Margin erosion on premium grades is a concern due to the inherent volatility in raw material costs like nickel and chromium. Exploration & Production companies purchasing standard casing are more price-sensitive, while those requiring premium alloys for harsh environments prioritize operational security.
Supply Chain Analysis
Port congestion in key shipping lanes and fluctuating container availability affect the inbound logistics costs for specialized OCTG inputs. Geographic supply concentration for high-quality seamless pipes rests with producers in China, Japan, and parts of Europe. Raw material dependencies center on critical alloying elements such as nickel and chromium. A structural risk exists from potential bottlenecks in seamless pipe production capacity among a few global manufacturers. Distribution runs through a global service center network model, supporting just-in-time inventory for complex drilling projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The OCTG market faces substitution defense, with composite pipes emerging as a threat that incumbents must strategically navigate.
For Market Incumbents: Secure intellectual property around proprietary premium connection technology and advanced metallurgical formulations. Invest in expanding API certification for new high-performance alloy grades to counter emerging material threats. Enhance digital integration capabilities, such as smart pipes, to offer high-value monitoring services. This approach mitigates the long-term risk of commoditization from standard products and addresses skilled labor shortages.
For New Entrants and Emerging Players: Specialized well-integrity service gaps exist where incumbents under-serve, particularly for geothermal and CCUS applications. Target these emerging energy sectors with tailored OCTG solutions and advanced material science. A go-to-market angle focusing on rapid API certification for niche, high-temperature, or corrosive-resistant alloys can create market entry points. Penetration is most feasible in applications requiring unique material properties beyond conventional oil and gas.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with smaller, specialized tubular goods manufacturers possessing unique metallurgical expertise or proprietary connection technologies. The long-term viability of the OCTG market hinges on the sustained demand for premium alloys in challenging reservoirs and new energy applications. An acquisition target archetype should include firms with proven R&D capabilities in corrosion-resistant materials or digital well-monitoring solutions. The signal to watch is the successful commercialization of advanced OCTG for geothermal or carbon capture projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Premium Alloys | Increases supply of high-performance materials crucial for complex well completions in Brazil and the Permian Basin. |
| Technology Licensing for Proprietary Connections | Expands market reach for advanced gas-tight seals, critical for high-pressure and high-temperature wells. |
| Strategic Partnerships for Integrated Services | Leverages combined expertise to offer comprehensive well-integrity solutions, particularly in complex offshore projects. |
| Acquisition of Digital Integration Specialists | Enhances capabilities in "smart pipe" technology, providing real-time downhole monitoring for operational security. |
| Green Manufacturing Transition Investment | Addresses EU Green Deal carbon accounting requirements, affecting sourcing decisions for European projects. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from market intelligence. Stakeholder roles included E&P company procurement managers, OCTG manufacturing R&D directors, drilling service company operations leads, and metallurgical engineers. Secondary sources comprised API standards documents, US EPA regulations, EU Green Deal policy papers, and company annual reports, triangulated through bottom-up and top-down approaches.
The forecasting boundary extends across the analysis window, modeling market dynamics without specific year references. Segmentation dimensions included product types, steel grades, applications, end-users, and regional demand patterns. Compound annual growth rates were derived through a multi-variable regression model, incorporating industry-specific forecast inputs like global energy demand projections and unconventional drilling activity forecasts in North America.
Underlying assumptions cover a stable geopolitical environment and consistent regulatory frameworks, with deviation risk concentrated in alloy price volatility or accelerated composite adoption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Large Scale LNG Terminal Market