
 Spain Agricultural Machinery Market | 2026-2036
Spain Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Agricultural Machinery Market Analytics
Steel-to-aluminum substitution in chassis and implement frames is expanding design flexibility for mid-horsepower tractors without sacrificing load ratings. John Deere leverages its Seville-area assembly presence to sustain rapid fulfillment timelines for Iberian dealers. CNH Industrial anchors its position through extensive service networks across Castile-La Mancha and Aragon. AGCO Corporation competes via specialized hay and forage configurations tuned to Spanish dairy and beef systems.
Agricultural machinery encompasses powered and towed equipment engineered to execute soil tillage, seed placement, crop harvesting, and residue management with defined power outputs, draft forces, and operating widths measured in meters. Tractors dominate installed base value given their role as prime movers for implements across all tillage and transport operations. Harvesters command concentrated margin pools in specialty segments where olive, almond, and vineyard mechanization lags manual labor substitution. Precision Farming technology represents the fastest-expanding capability layer as GPS-guided steering and variable-rate application reduce input waste on fragmented Spanish plots.
Spain's Ministry of Agriculture enforces EU Stage V emission standards through type-approval requirements administered in coordination with Madrid's national motor vehicle registry. The EU Common Agricultural Policy direct-payment framework shapes equipment investment timing as farmers align capital expenditures with subsidy disbursement cycles. Stakeholders must monitor how the EU AI Act classification rules affect autonomous tractor deployment timelines and liability structures in shared-cropping arrangements.
Market Dynamics
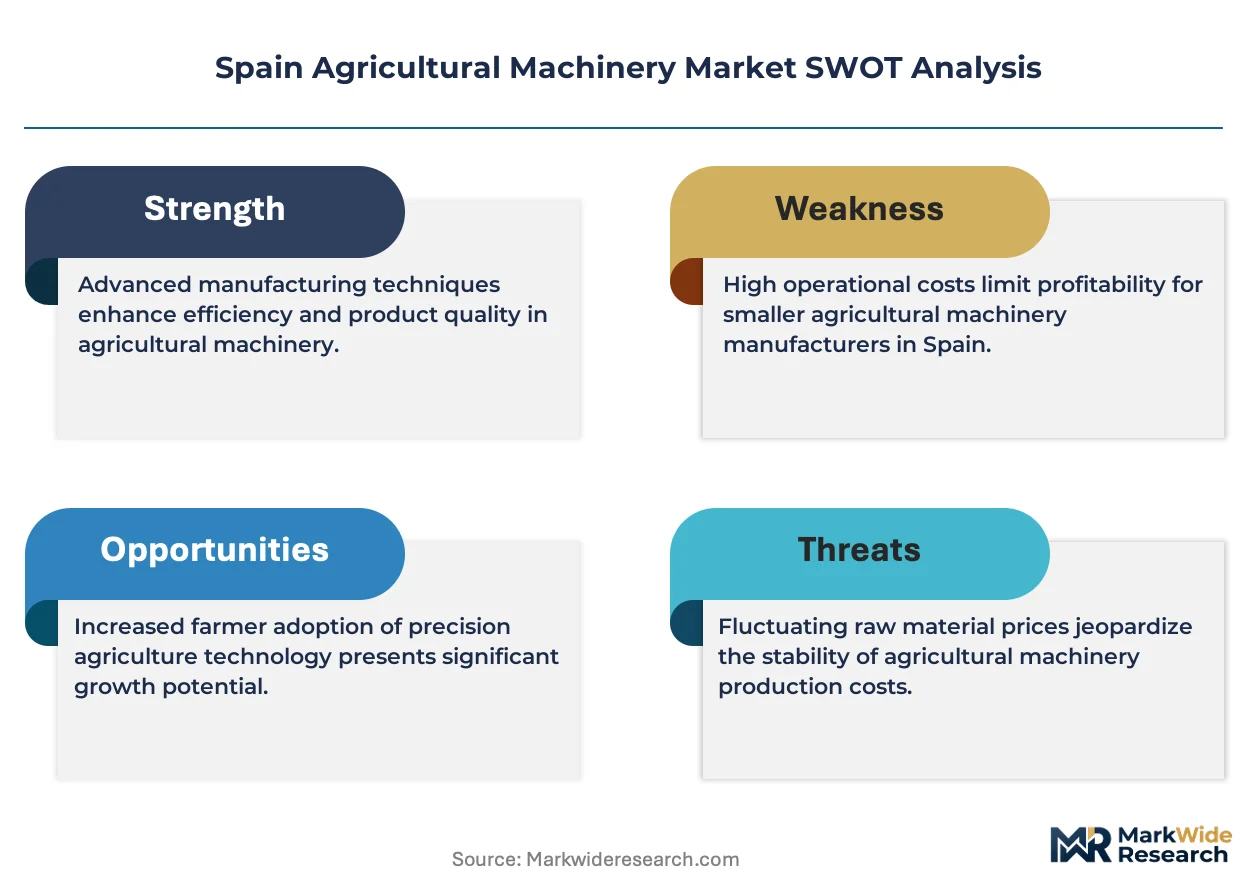
EU Stage V emission standards are compressing replacement cycles for diesel-powered tractors across Spain's irrigated horticulture belts, forcing cooperatives to accelerate capital deployment before 2027 registration deadlines.
Growth Catalysts
- EU Farm to Fork alignment:Spain's national emission thresholds for new tractor registrations are tightening, creating regulatory pull for precision-capable equipment that minimizes input waste on fragmented plots.
- Specialty crop mechanization:Olive, almond, and vineyard operations in Andalusia are substituting manual labor with harvester systems, expanding addressable equipment demand.
- Steel-to-aluminum substitution:Chassis and implement frames now deploy aluminum alloys, expanding design flexibility for mid-horsepower tractors without sacrificing load ratings.
Market Restraints
- Stage V compliance costs:After-treatment systems for diesel engines add capital burden to tractor purchases, compressing margin pools for dealers in Castile-La Mancha.
- Fragmented landholding structure:Small plot sizes across Murcia and Valencia limit economies of scale for large-format equipment deployment.
- Skilled technician scarcity:Precision farming systems require diagnostic expertise that rural service networks struggle to retain.
Strategic Opportunities
- Autonomous tractor deployment:EU AI Act classification rules will clarify liability structures for shared-cropping arrangements, opening deployment timelines.
- Hay and forage specialization:Spanish dairy and beef systems present unmet demand for configurations tuned to Mediterranean pasture conditions.
- Variable-rate application convergence:GPS-guided steering combined with sensor-based input modulation creates white space for retrofit kits on existing installed base.
Industry Challenges
- EU AI Act compliance timelines:Autonomous system certification delays deployment roadmaps for cooperative fleet operators.
- Legacy equipment integration:Precision farming retrofits face compatibility friction with 15-20 year old tractor electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Agricultural Machinery Market |
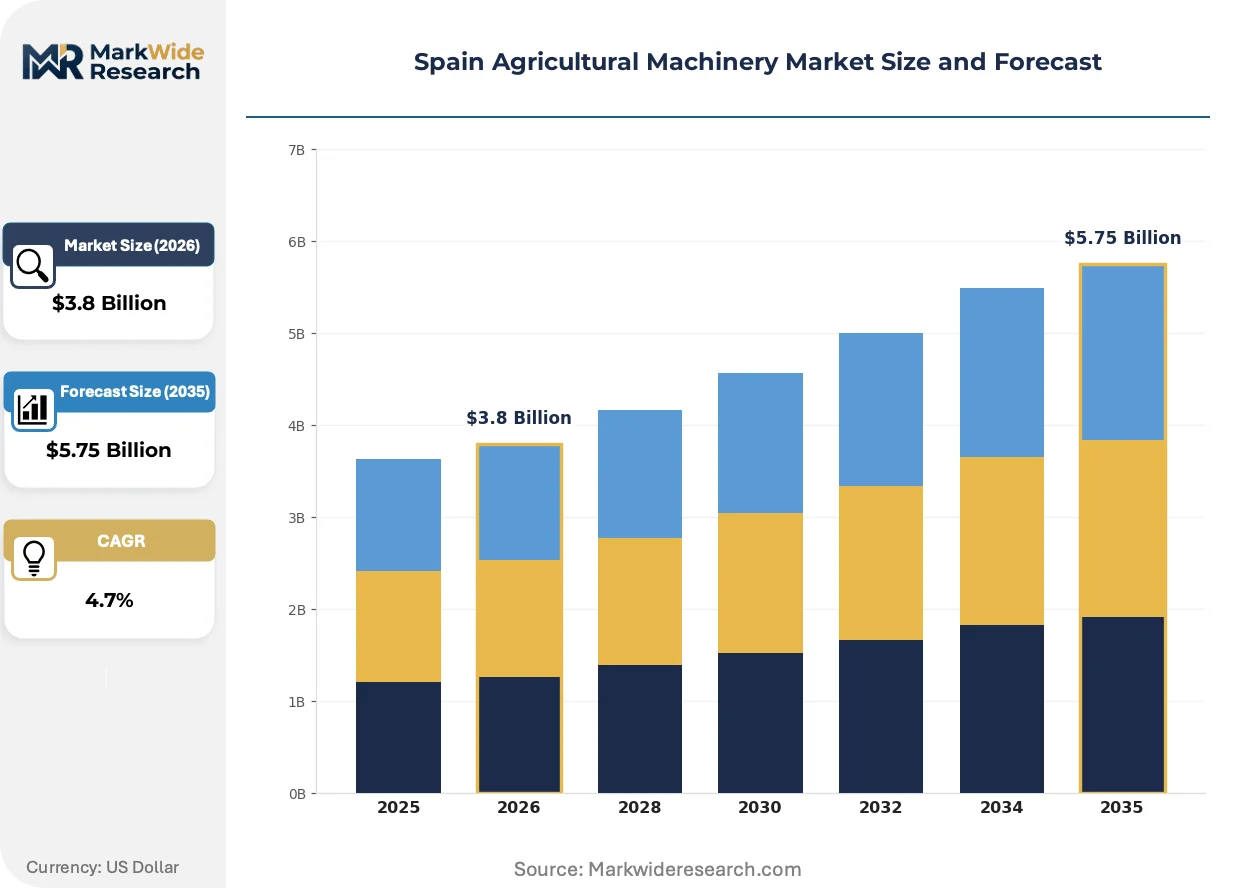
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Ploughs, Seeders Application: Crop Production, Soil Preparation, Planting, Irrigation End User: Farmers, Cooperatives, Agricultural Enterprises, Contractors Technology: Automation, Precision Farming, GPS, IoT |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Claas, SDF Group, Kuhn Group, Landini, Fendt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Agricultural Machinery Market Evolving Landscape
Active innovation in Spain's agricultural machinery sector centers on emission-compliant powertrains, lightweight materials engineering, and precision agriculture integration. These developments are reshaping competitive positioning among equipment suppliers.
Telematics-enabled fleet management systems are modularizing service delivery for cooperative operators. Dairy and beef producers in Aragon are adopting subscription-based diagnostics at accelerating pace. This architecture is compressing traditional dealer service revenue models while enabling remote troubleshooting of variable-rate application faults.
Spain's Ministry of Agriculture enforces EU Stage V emission standards through type-approval requirements coordinated with Madrid's national motor vehicle registry. After-treatment system mandates are elevating development costs for domestic assembly operations. Mid-horsepower tractor segments face the steepest compliance burden as price-sensitive buyers resist premium positioning.
Cooperative procurement committees are consolidating equipment purchasing decisions across multiple member farms. Traditional dealer relationships in Valencia are yielding to direct manufacturer negotiations for fleet-scale orders. This concentration is most visible among irrigated horticulture operations in Murcia seeking standardized precision configurations.
Spain Agricultural Machinery Market Segmentation
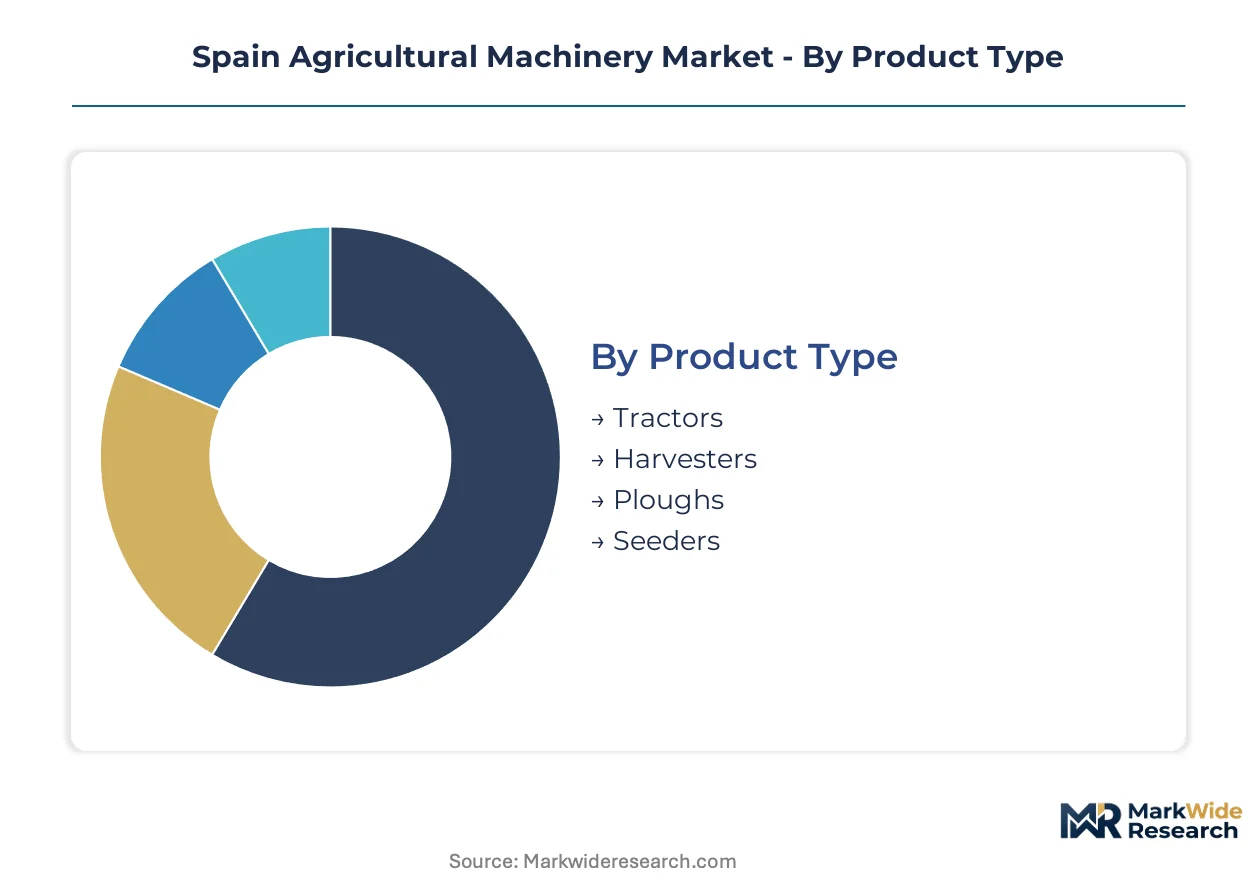
Equipment segmentation in Spain reveals how fragmented landholdings and cooperative purchasing reshape machinery specifications across power classes and precision tiers. Understanding these divisions exposes where standardization yields procurement leverage versus where customization commands premium positioning.
Product Type:
Customization intensity varies sharply across this category, from mass-produced mid-horsepower tractors to specialized harvesters engineered for Mediterranean specialty crops.
- Tractors:Prime movers spanning 50-300 horsepower serve as the universal platform for implement attachment across tillage, transport, and PTO-driven operations. Demand concentrates most visibly in Castile-La Mancha and Aragon where extensive cereal operations favor 120-180hp configurations for draft efficiency on large plots.
- Harvesters:Self-propelled systems engineered for grain, forage, or specialty crop recovery with integrated threshing, cleaning, and residue handling modules. Olive and almond mechanization in Andalusia is accelerating replacement of manual labor with trunk-shaker and canopy-contact harvester systems.
- Ploughs:Towed implements for primary soil inversion with reversible or semi-mounted configurations.
- Seeders:Precision placement equipment ranging from mechanical drills to pneumatic row-crop units.
Most installed capacity flows through Tractors. Expansion is steepest in Harvesters as labor substitution economics improve for specialty crops.
Application:
Margin structures diverge by application maturity, with established soil operations yielding thinner returns than precision-dependent planting and variable-rate irrigation.
- Crop Production:Integrated field operations spanning cultivation through harvest with equipment configurations tuned to crop-specific residue and timing requirements. Murcia's intensive horticulture belt generates concentrated demand for multi-crop capable systems that switch between leafy vegetables and stone fruit operations.
- Soil Preparation:Primary and secondary tillage operations using discs, cultivators, and rollers to establish seedbed conditions. Cooperatives in Castile-La Mancha are consolidating tillage fleets across member farms to amortize high-horsepower tractor investments.
- Planting:Seed and transplant placement with depth and spacing precision critical to establishment uniformity.
- Irrigation:Water application systems including center-pivot, drip, and linear-move configurations with integrated pumping and filtration.
Equipment deployment concentrates heaviest in Crop Production. Precision technology integration is climbing fastest in Planting as GPS-guided systems reduce seed waste on irregular Spanish plots.
End User:
Purchasing sophistication scales with operational scale, from individual farmers negotiating single-unit discounts to cooperative procurement committees orchestrating fleet-standardized tenders.
- Farmers:Owner-operators managing sub-100 hectare holdings with equipment selections driven by immediate cash-flow constraints and dealer financing availability. Valencia's citrus and vegetable growers prioritize proven reliability over cutting-edge precision given limited technical support access.
- Cooperatives:Member-owned enterprises pooling capital for shared machinery fleets with centralized maintenance and seasonal allocation systems. Andalusian olive cooperatives are accelerating replacement cycles for Stage V-compliant tractors ahead of registration deadlines.
- Agricultural Enterprises:Large-scale commercial operations with dedicated equipment managers and lifecycle cost analytics.
- Contractors:Independent service providers offering tillage, planting, or harvesting on per-hectare fee structures.
Transaction volume flows predominantly through Farmers. Technology adoption velocity runs highest among Cooperatives where pooled capital absorbs precision equipment premiums.
Technology:
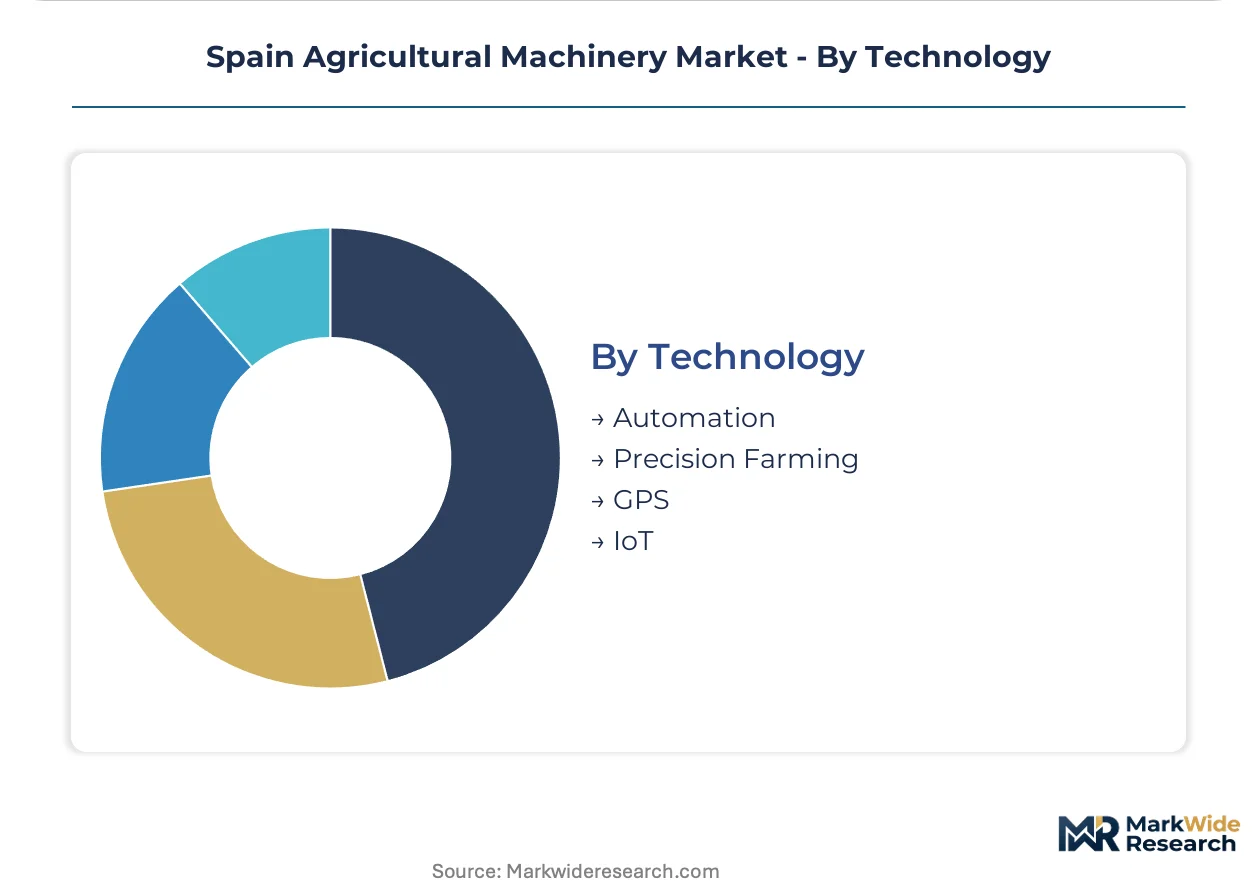
Capability layering follows a cost-versus-control gradient, from basic automation reducing operator fatigue to fully integrated IoT architectures enabling remote fleet orchestration.
- Automation:Operator-assist functions including auto-steer, implement control, and headland management reducing repetitive task burden. Mid-horsepower tractors across Aragon's dairy belt are adopting automation packages as standard equipment to address skilled labor scarcity.
- Precision Farming:Variable-rate input application and yield mapping systems optimizing resource allocation at sub-field resolution. Catalonia's vineyard operations are deploying precision viticulture configurations to modulate water and nutrient delivery by vine vigor zones.
- GPS:Satellite-based positioning enabling pass-to-pass accuracy for reduced overlap and input savings.
- IoT:Connected sensor networks transmitting machine health, field conditions, and operational telemetry to cloud platforms.
Installed technology base concentrates in Automation. Capability expansion is sharpest in IoT as telematics-enabled diagnostics compress service response times for cooperative fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andalusia's olive and almond processing clusters generate concentrated demand for specialty harvester systems across southern Spain.
Andalusia
Trunk-shaker and canopy-contact harvester systems displace manual labor in olive cooperatives around Jaén and Córdoba. Spain's Ministry of Agriculture enforces EU Stage V emission standards through Madrid's national motor vehicle registry, accelerating tractor replacement cycles ahead of 2027 deadlines. The Guadalquivir Valley concentration of processing facilities pulls precision-capable equipment into shared cooperative fleets.
Catalonia
Vineyard mechanization drives variable-rate viticulture equipment demand across Priorat and Penedès zones. EU AI Act classification rules shape autonomous tractor deployment timelines for shared-cropping arrangements in the region. Barcelona's precision agriculture technology suppliers cluster around diagnostic and retrofit service capabilities for fragmented plot structures.
Valencia
Intensive horticulture belts generate concentrated demand for multi-crop capable systems switching between leafy vegetables and stone fruit. The EU Common Agricultural Policy direct-payment framework shapes equipment investment timing as farmers align capital expenditures with subsidy disbursement cycles. Murcia's irrigated operations neighboring Valencia share procurement standardization through cooperative fleet consolidation.
Castile-La Mancha
Extensive cereal operations favor 120-180 horsepower tractor configurations for draft efficiency on large plots. EU Stage V after-treatment system mandates elevate development costs for dealers serving price-sensitive mid-horsepower segments. Toledo and Albacete service networks anchor CNH Industrial's extensive maintenance infrastructure across the region.
Aragon
Dairy and beef systems present unmet demand for hay and forage configurations tuned to Mediterranean pasture conditions. Skilled technician scarcity in rural networks complicates precision farming system diagnostics and retention. Zaragoza's logistics position supports rapid fulfillment timelines for Iberian equipment distribution.
Spain Agricultural Machinery Market Competitive Landscape
Service network expansion dominates the current landscape as manufacturers compress response times for cooperative fleet operators. The vendor base organizes around three distinct tiers: premium-positioned full-line suppliers, mid-market regional specialists, and component-focused niche fabricators. Strategic archetypes include telematics-enabled fleet management providers and aluminum chassis engineering specialists. Geographic anchoring through assembly presence and backward integration into powertrain after-treatment systems represent the dominant competitive moves.
Among full-line manufacturers, John Deere, CNH Industrial, and AGCO Corporation exemplify distinct strategic positioning within the Spanish market. Deere leverages its Seville-area assembly footprint to sustain rapid fulfillment timelines for Iberian dealers. CNH Industrial anchors its competitive position through extensive service networks across Castile-La Mancha and Aragon. AGCO Corporation occupies a specialization-focused position via hay and forage configurations tuned to Spanish dairy and beef systems.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Claas |
| SDF Group |
| Kuhn Group |
| Landini |
| Fendt |
| Others |
Value Network & Pricing Analysis
Aluminum alloy chassis engineering costs cascade from German and Italian specialty mills through Seville-area assembly operations into mid-horsepower tractor pricing tiers, with EU Stage V after-treatment system mandates compressing margin pools for price-sensitive buyers in Castile-La Mancha.
Pricing Analysis
Input-cost pass-through from steel-to-aluminum substitution and emission after-treatment systems stratifies pricing across premium, standard, and economy tiers. John Deere's Iberian assembly presence commands brand premium positioning, while CNH Industrial competes on service bundling. Pricing pressure intensifies in mid-horsepower segments as cooperatives consolidate fleet procurement and squeeze dealer margins. Individual farmers in Valencia exhibit highest price sensitivity, whereas Andalusian olive cooperatives absorb precision equipment premiums through pooled capital structures.
Supply Chain Analysis
EU domestic-content thresholds for Farm to Fork alignment incentives are reshaping sourcing patterns for precision agriculture components. Germany, Italy, and France anchor component supply for powertrain and hydraulic systems. High-strength aluminum alloys, precision GPS modules, and Stage V-compliant diesel engines constitute critical input dependencies. Single-source vulnerability concentrates in satellite positioning chipsets from limited qualified suppliers. Distribution runs through manufacturer-direct negotiations with cooperative procurement committees, bypassing traditional dealer networks in Murcia and Valencia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain Agricultural Machinery Market functions as a regulatory compounder where EU Stage V emission deadlines and AI Act classification timelines are forcing accelerated capital deployment across cooperative fleets.
For Market Incumbents: Deepen backward integration into aluminum chassis fabrication and after-treatment system production to defend margin position against Stage V compliance cost compression. Anchor service network density in Aragon and Castile-La Mancha where skilled technician scarcity threatens retention of precision farming diagnostics capabilities. For New Entrants and Emerging Players: Capture retrofit kit white space for GPS-guided steering and variable-rate application systems compatible with 15-20 year old tractor electronics in Murcia's irrigated horticulture belt. Target cooperative fleet standardization tenders with subscription-based telematics diagnostics that compress traditional dealer service revenue models. For Investors and Strategic Acquirers: Roll-up economics work for precision agriculture technology specialists because fragmented plot structures across Catalonia and Valencia sustain demand for sensor-based input modulation and diagnostic retrofit capabilities. Monitor EU AI Act liability structure clarifications as the inflection signal for autonomous tractor deployment timelines in shared-cropping arrangements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Chassis Production | Captures lightweighting cost savings for mid-horsepower tractors without sacrificing load ratings. |
| Precision Agriculture Retrofit Kit Development | Addresses legacy equipment integration friction across 15-20 year old tractor installed base. |
| Telematics-Enabled Fleet Management Platform | Compresses service response times for cooperative operators in Andalusia and Valencia. |
| EU AI Act Compliance Certification Investment | Clarifies liability structures for autonomous deployment in shared-cropping arrangements. |
| Cooperative Procurement Committee Direct Sales Channel | Bypasses traditional dealer networks where fleet-scale standardization tenders concentrate. |
Research Methodology
Multiple input streams — cooperative fleet managers, precision agriculture technology suppliers, dealer service network heads, and Madrid motor vehicle registry officials — were reconciled with secondary validation from EU Common Agricultural Policy disbursement records, national agricultural census data, and equipment type-approval filings. Primary interviews captured procurement timing, replacement cycle acceleration, and precision technology adoption barriers. Bottom-up unit economics and top-down sectoral expenditure patterns were triangulated to anchor volume estimates.
Data-stream reconciliation across product type, application, end user archetype, and technology tier segmentation generated consistent value outputs over the projection horizon. CAGRs were derived from fitted trend extrapolation moderated by regulatory milestone impacts. Modeled inputs included EU Stage V registration deadline effects, cooperative capital pooling velocity, and aluminum substitution adoption curves in chassis engineering.
Regulatory timeline delays, commodity price volatility in aluminum alloys, and cooperative membership attrition are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Agricultural Drum Mowers Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Germany Agricultural Machinery Market