
 Global Agricultural Sprayer Market | 2026-2036
Global Agricultural Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Sprayer Market Analysis
Subscription-based telemetry and predictive maintenance packages is broadening the recurring revenue base for equipment vendors. John Deere leverages its Operations Center platform to lock in multi-year service contracts alongside hardware sales. AGCO Corporation anchors its Fuse Connected Services across North American and European dealer networks. Kubota Corporation competes through regionally priced connectivity bundles tailored to Southeast Asian smallholder cooperatives.
Agricultural sprayers are mechanical or electro-mechanical devices designed to distribute liquid crop inputs through pressurized nozzles, booms, or rotary atomizers at calibrated flow rates measured in liters per hectare; their primary commercial purpose is the uniform application of agrochemicals to maximize field efficacy while minimizing input waste and off-target drift. Tractor-mounted sprayers still occupy the dominant share of revenue given their compatibility with existing farm mechanization, though drone sprayers represent the fastest-expanding product category as payload capacities and battery endurance improve. Smart spraying technology commands premium positioning due to real-time variable-rate capabilities and weed-detection sensors that reduce chemical volumes.
The EPA governs aerial and ground application standards under the Federal Insecticide, Fungicide, and Rodenticide Act, while EASA and national aviation authorities across Germany, France, and Spain are establishing beyond-visual-line-of-sight frameworks for agricultural drones. China's MEE enforces stricter nozzle-efficiency standards under GB codes that limit drift potential near watersheds. Stakeholders must monitor evolving unmanned aerial system flight permissions and chemical registration timelines as these determine which technology platforms gain commercial traction in each jurisdiction.
Market Dynamics
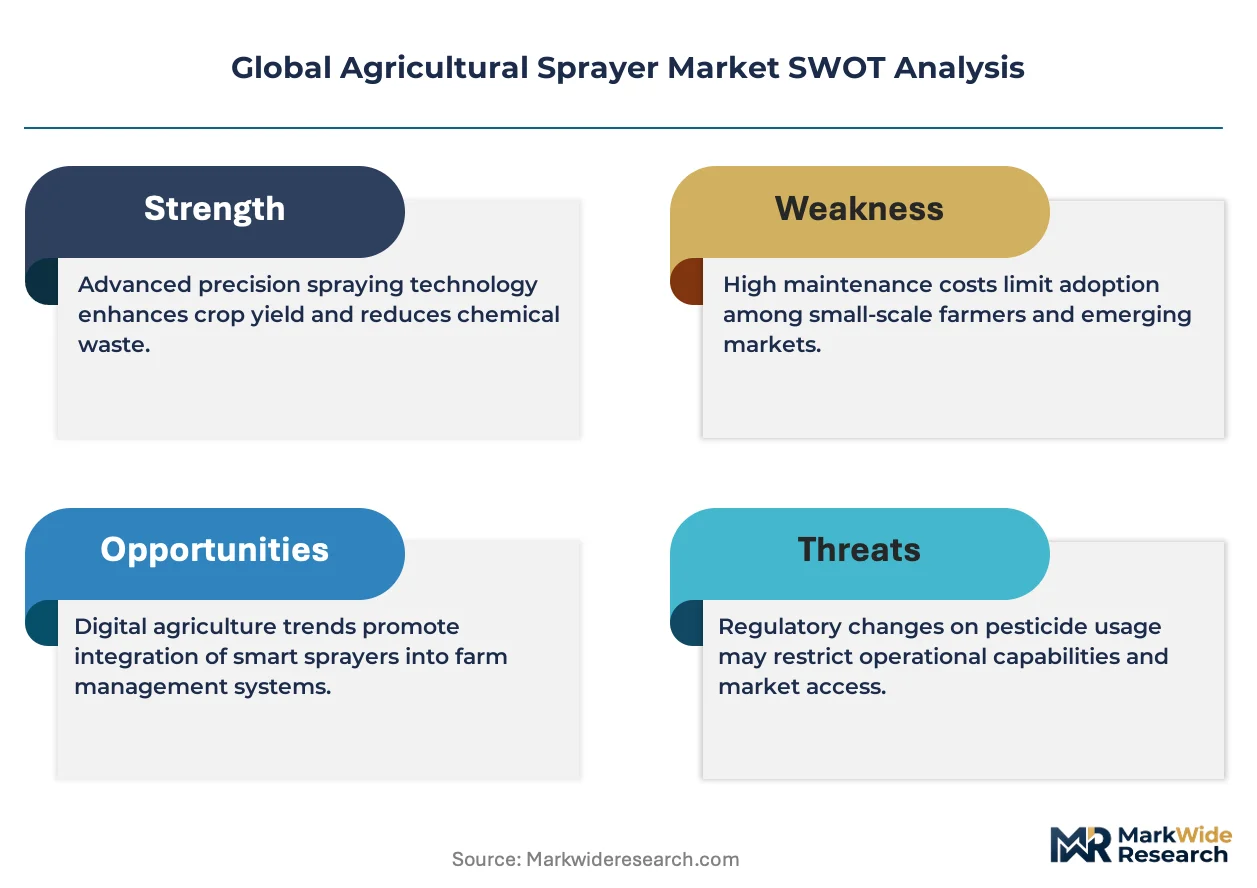
Precision agriculture is compressing equipment replacement cycles as commercial growers face yield optimization mandates and input cost volatility. Variable-rate application technology is now a baseline procurement criterion rather than a premium feature, forcing vendors to restructure hardware margins around recurring telemetry revenue.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for hydrofluorocarbon propellants are accelerating farmer migration from pneumatic to electro-mechanical spraying systems. Equipment vendors report retrofit demand clustering in Germany and France.
- Drone payload engineering:Lithium-sulfur battery advances are extending unmanned aerial system flight endurance above 25 minutes with 15-liter chemical loads. Brazil's Cerrado soybean belt is absorbing early commercial deployments.
- Smallholder cooperative consolidation:India's Punjab wheat corridor is witnessing machinery pooling arrangements that aggregate demand for tractor-mounted boom sprayers across 500+ hectare blocks.
Market Restraints
- Steel and aluminum input costs:Boom fabrication materials represent 18-22% of finished equipment cost, exposing manufacturers to London Metal Exchange volatility that compresses gross margins during price spikes.
- Nozzle supplier concentration:Ceramic atomizer production concentrates in German and Italian specialty ceramics firms, creating single-source vulnerabilities for Asian equipment assemblers.
- Drone payload ceiling regulations:EASA's 25-kilogram maximum takeoff weight limit for uncertified agricultural drones restricts chemical capacity below economic thresholds for broadacre cereal applications.
Strategic Opportunities
- Indonesia palm oil estates:Mechanization rates below 15% in Sumatra and Kalimantan plantations present untapped demand for self-propelled high-clearance sprayers adapted to tropical humidity.
- AI-weed recognition convergence:Computer vision modules paired with PWM nozzle control enable spot-spray applications reducing herbicide volumes 60-80% below broadcast rates.
- FAA Part 137 waivers:Expanded beyond-visual-line-of-sight permissions for agricultural drones in US corn-soy regions are unlocking subscription-based aerial application services.
Industry Challenges
- Embedded systems engineering talent:Shortage of firmware developers capable of integrating ISOBUS protocols with real-time kinematic GPS correction is delaying smart sprayer product launches.
- Multi-jurisdiction certification timelines:Parallel EPA, ECHA, and ANVISA chemical registration processes extend time-to-market for novel biological formulations by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Sprayer Market |
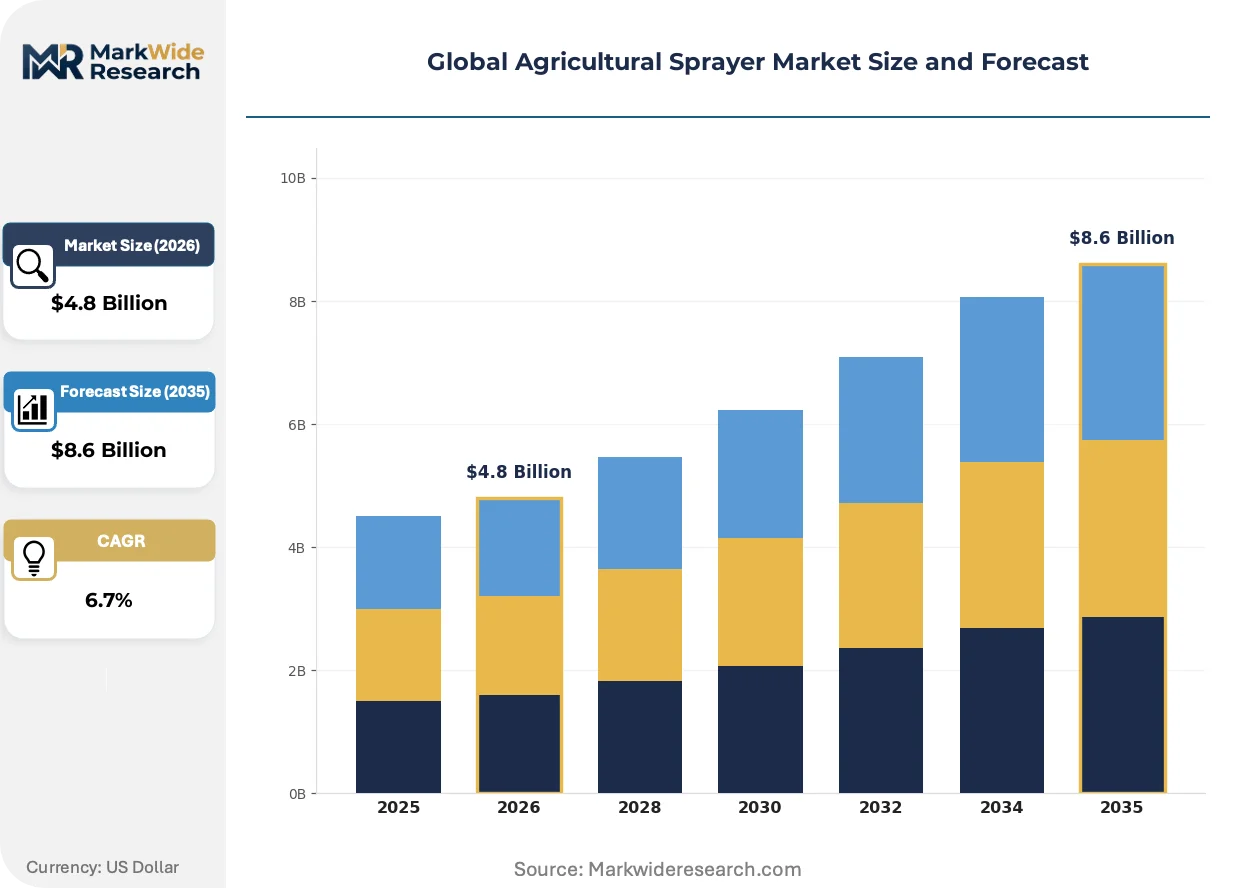
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Sprayers, Backpack Sprayers, Tractor-Mounted Sprayers, Drone Sprayers Application: Crop Protection, Fertilization, Pest Control, Herbicide Application End User: Farmers, Agricultural Cooperatives, Landscaping Services, Commercial Growers Technology: Manual Spraying, Automated Spraying, Smart Spraying, Pressure Spraying |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, Exel Industries, Amazone, STIHL, DJI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Sprayer Market Emerging Trajectories
Electrification and autonomy are converging to redefine field application economics, compressing labor requirements while elevating data capture intensity. Equipment vendors are repositioning around software-defined spraying platforms.
Real-time kinematic GPS fused with ultrasonic boom height sensors is unifying terrain-following accuracy with drift minimization. Large-scale grain operations in Ukraine and Argentina are retrofitting existing tractor-mounted units at accelerating pace. This convergence is compressing the performance gap between premium OEM systems and aftermarket precision agriculture kits.
The EU F-Gas Regulation's 2030 phase-down targets are forcing reformulation of pressure-propelled backpack and handheld sprayers. Equipment manufacturers serving European horticulture and vineyard segments are redesigning around battery-powered diaphragm pumps. Specialty crop producers in Spain and Italy are absorbing price premiums for compliant equipment ahead of enforcement deadlines.
Cooperative machinery rings are fragmenting individual farm capital commitment across pooled ownership structures. Dealer networks in France and Germany are unbundling equipment sales from maintenance contracts to serve these collective buyers. This reconfiguration is most visible in Poland's sugar beet and rapeseed districts where 200+ member cooperatives now dominate tractor-mounted sprayer procurement.
Global Agricultural Sprayer Market Segmentation
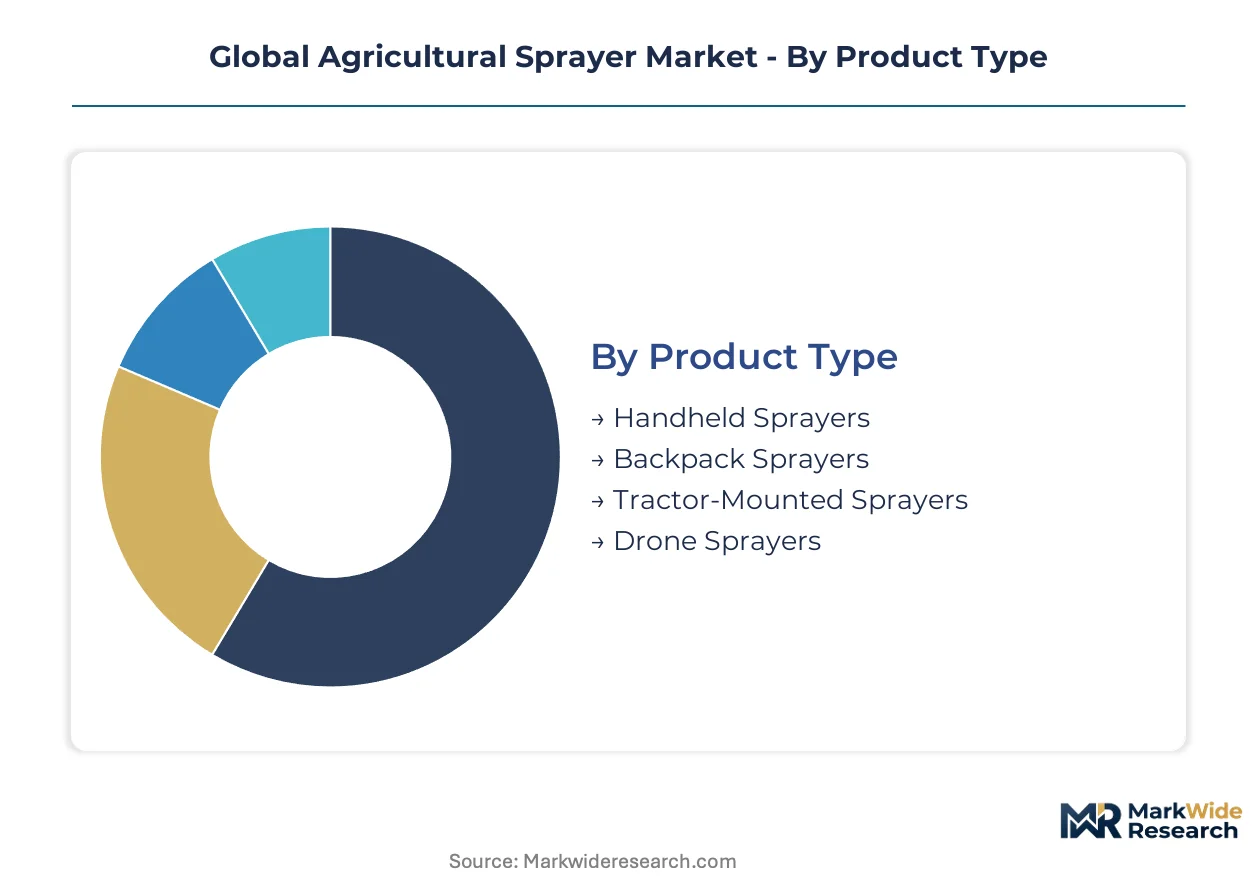
Equipment procurement patterns diverge sharply across farm scale and input intensity. Segmentation reveals how precision agriculture compresses replacement cycles for commercial operators while smallholders prioritize mechanical durability over digital connectivity.
Product Type:
Customization spans from standardized handheld units to fully integrated self-propelled systems with ISOBUS compatibility and variable-rate control.
- Tractor-Mounted Sprayers:Boom widths range from 12 to 42 meters with stainless steel or polyethylene tank configurations from 1,000 to 6,000 liters. Brazil's Cerrado soybean belt and India's Punjab wheat corridor concentrate demand as cooperative machinery pools aggregate procurement across 500+ hectare blocks. ISOBUS integration is now baseline for units above 2,000-liter capacity.
- Drone Sprayers:Rotary-wing unmanned aerial systems carry 10-30 liter payloads with lithium-sulfur battery architectures extending endurance beyond 25 minutes. Early commercial deployments cluster in Brazilian broadacre operations where FAA-equivalent beyond-visual-line-of-sight permissions reduce labor costs in inaccessible terrain.
- Handheld Sprayers:Polyethylene tank units from 5-20 liters serve vineyard and horticulture maintenance in Spain and Italy where EU F-Gas Regulation is forcing battery-powered diaphragm pump redesigns.
- Backpack Sprayers:Steel or reinforced plastic frames with piston or diaphragm pumps dominate smallholder vegetable production across Southeast Asian cooperatives where terrain limits mechanized access.
Leading the category by volume: Tractor-Mounted Sprayers. Expanding most quickly: Drone Sprayers.
Application:
Input chemistry determines equipment corrosion specifications and nozzle material selection across this dimension.
- Crop Protection:Fungicide and insecticide applications require ceramic or stainless steel nozzles resistant to abrasive suspensions. Variable-rate prescription maps from satellite imagery now standard for commercial grain operations in Ukraine and Argentina.
- Herbicide Application:Glyphosate and dicamba formulations drive demand for drift-reduction nozzles and boom recirculation systems. Spot-spray computer vision modules reducing chemical volumes 60-80% below broadcast rates are gaining fastest adoption in North American corn-soy rotations.
- Fertilization:Liquid nitrogen and micronutrient delivery demands corrosion-resistant pump seals and flow meters calibrated for high-density solutions.
- Pest Control:Orchard and greenhouse fogging applications concentrate in Mediterranean citrus belts and Dutch glasshouse complexes requiring specialized atomizer configurations.
Dominant by input volume: Crop Protection. Gaining share fastest: Herbicide Application with smart spot-spray integration.
End User:
Capital commitment intensity separates individual owner-operators from pooled cooperative structures with dedicated machinery managers.
- Agricultural Cooperatives:Machinery rings in France, Germany, and Poland fragment individual farm capital commitment across 200+ member ownership structures. Dealer networks unbundle equipment sales from maintenance contracts to serve these collective buyers.
- Commercial Growers:Large-scale grain operations above 2,000 hectares drive telemetry subscription adoption and predictive maintenance contracts. John Deere's Operations Center platform locks in multi-year service agreements alongside hardware sales.
- Farmers:Individual owner-operators below 200 hectares prioritize mechanical reliability over digital connectivity, sourcing through regional dealer networks with financing packages.
- Landscaping Services:Municipal and golf course maintenance contracts demand compact tow-behind units with rapid tank cleanout systems for multi-chemical rotation.
Generating highest equipment revenue per hectare: Commercial Growers. Fastest machinery pool expansion: Agricultural Cooperatives.
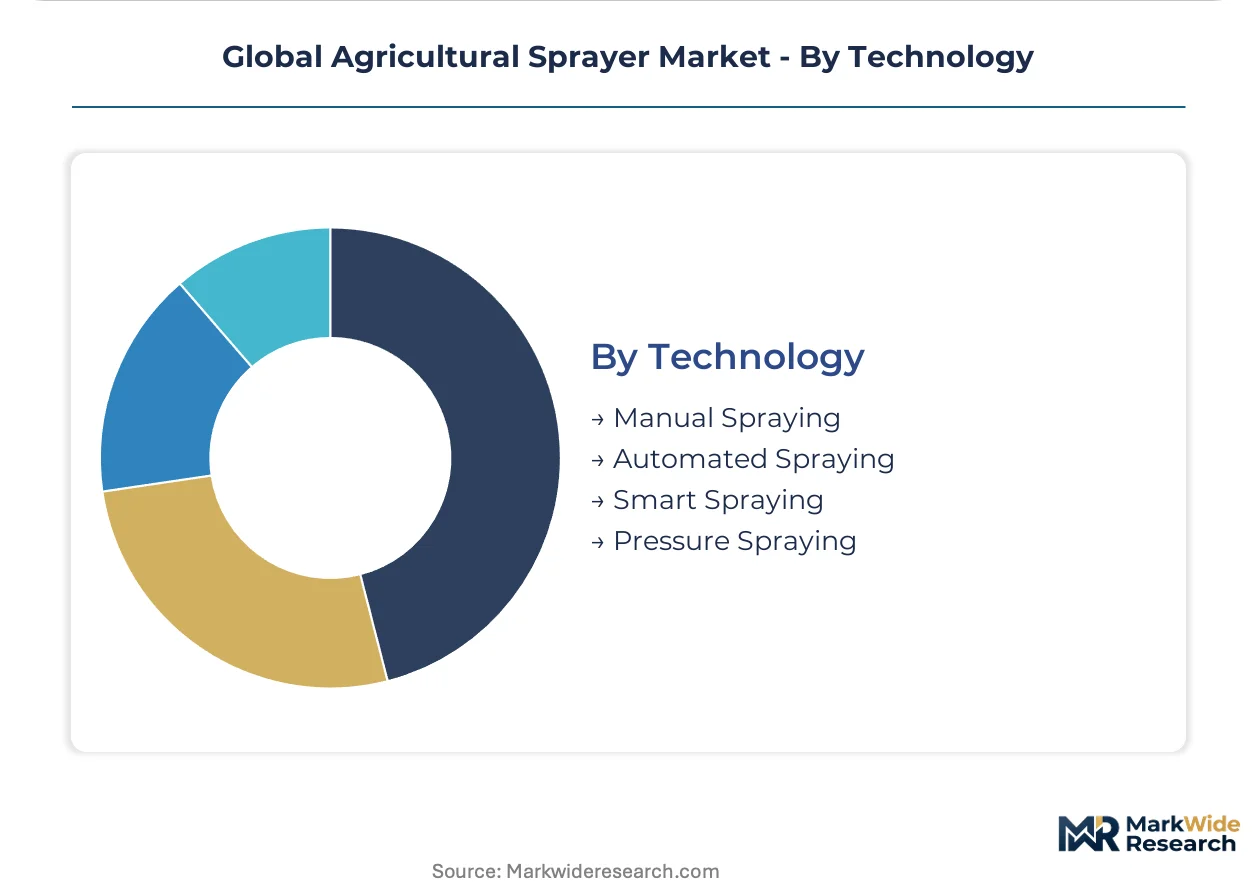
Technology:
Margin structure inverts from hardware-only sales toward recurring telemetry revenue as automation penetration deepens.
- Smart Spraying:Real-time kinematic GPS fused with ultrasonic boom height sensors and PWM nozzle control enables centimeter-accurate terrain following. AI-weed recognition modules from Bosch and XAG integrate with OEM platforms to trigger individual nozzle actuation.
- Automated Spraying:Pre-programmed path planning with automatic section control reduces operator fatigue in large-field applications. Retrofit kits from Trimble and Raven Industries compress the performance gap against premium OEM systems.
- Pressure Spraying:Conventional hydraulic systems with manual rate adjustment dominate replacement demand in emerging markets where precision agriculture infrastructure remains underdeveloped.
- Manual Spraying:Basic lever-operated pumps persist in subsistence farming contexts across Sub-Saharan Africa and South Asia where electrification and connectivity are limited.
Commanding steepest price premiums: Smart Spraying. Climbing fastest from small base: Automated Spraying.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado soybean belt anchors commercial sprayer deployment, with precision agriculture adoption accelerating equipment replacement cycles across Latin America's largest grain economy.
United States
Corn-soy rotations across Iowa and Illinois drive demand for smart spraying systems with AI-weed recognition. The FAA's Part 137 waivers for beyond-visual-line-of-sight drone operations are unlocking subscription-based aerial application services. Early commercial deployments cluster in the Mississippi River Valley where labor scarcity elevates automation premiums.
Germany
Bavarian and Lower Saxon grain cooperatives are retrofitting tractor-mounted units with ISOBUS-compatible variable-rate technology. The EU F-Gas Regulation's 2030 phase-down targets are forcing migration from pneumatic to electro-mechanical systems. Equipment vendors report concentrated retrofit demand across the Rhine-Ruhr industrial corridor.
India
Punjab's wheat corridor is witnessing machinery pooling arrangements that aggregate demand for tractor-mounted boom sprayers across 500+ hectare cooperative blocks. The central government's PLI scheme for agricultural mechanization is subsidizing precision equipment procurement. Dealer networks in Haryana and Uttar Pradesh are unbundling sales from maintenance contracts to serve collective buyers.
China
Yangtze River Delta horticulture operations are absorbing battery-powered handheld units redesigned under stricter MEE nozzle-efficiency standards. GB codes limiting drift potential near watersheds are reshaping product certification requirements for domestic manufacturers. Zhejiang and Jiangsu provinces concentrate demand for compact sprayers adapted to fragmented paddy field geometries.
Brazil
Mato Grosso's soybean frontier is absorbing early commercial drone deployments as lithium-sulfur battery advances extend flight endurance above 25 minutes. ANVISA's parallel chemical registration processes with EPA and ECHA are extending time-to-market for novel biological formulations. Self-propelled high-clearance sprayers dominate procurement in Goiás and Bahia where plantation scale exceeds 10,000 hectares.
Global Agricultural Sprayer Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor base. Full-line agricultural equipment manufacturers anchor the premium segment through integrated telemetry platforms and multi-year service contracts. Specialty sprayer fabricators occupy mid-market positions with regionally optimized boom configurations and dealer network density. Component suppliers and aftermarket precision agriculture kit vendors compete on retrofit economics, compressing the performance gap against OEM systems. Consolidation pressure is intensifying through strategic partnerships between drone hardware developers and established ground equipment distributors, alongside geographic expansion by Asian manufacturers into Southeast Asian cooperative markets.
Among full-line equipment manufacturers, John Deere, AGCO Corporation, and Kubota Corporation exemplify the platform-anchored archetype. John Deere leverages its Operations Center to lock in recurring telemetry revenue alongside hardware sales. AGCO Corporation anchors Fuse Connected Services across North American and European dealer networks. Kubota Corporation competes through regionally priced connectivity bundles tailored to Southeast Asian smallholder cooperatives. These three represent divergent geographic emphases within the same strategic tier—North American, transatlantic, and Asia-Pacific respectively—while sharing a common pivot toward software-defined spraying platforms and predictive maintenance subscriptions.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| Exel Industries |
| Amazone |
| STIHL |
| DJI |
| Others |
Supply Flow & Price Mechanics
Firmware developers capable of integrating ISOBUS protocols with real-time kinematic GPS correction concentrate in Germany's Rhine-Ruhr corridor and California's Central Valley, creating labor-cost differentials that widen pricing-tier spreads between premium smart-spraying platforms and basic pressure-based systems.
Pricing Analysis
Yield-per-hectare guarantees anchor value-based pricing for smart spraying platforms, with John Deere and AGCO Corporation bundling telemetry subscriptions that monetize uptime assurance and chemical savings rather than hardware alone. Three-tier pricing structure across premium, standard, and economy levels separates ISOBUS-compatible variable-rate systems from basic boom sprayers and handheld units. Price differentiation hinges on certification grade (CE marking for EU F-Gas compliance) and after-sales service bundling. Cost compression in the standard tier is intensifying because steel and aluminum input volatility squeezes fabricator margins. Smallholder cooperatives in Southeast Asia exhibit highest price sensitivity, while commercial growers above 2,000 hectares absorb premium positioning for predictive maintenance contracts.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from agricultural cooperatives and plantation operators, while regional dealer networks serve fragmented smallholder procurement. Ceramic atomizer production concentrates in Germany, Italy, and Japan, drawing from specialty ceramics expertise developed in automotive and aerospace supply chains. Boom fabrication feeds from steel and aluminum sheet stock anchored in Chinese, German, and Turkish mill capacity. Single-source vulnerability in precision nozzle supply creates exposure to German and Italian specialty ceramics firms. Distribution runs through authorized dealer networks with captive service departments in North America and Europe, and through cooperative machinery rings in India and Poland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision agriculture mandates are compressing equipment replacement cycles and forcing vendor consolidation as telemetry subscription economics separate platform-anchored incumbents from hardware-only assemblers.
For Market Incumbents: Deepen backward integration into ceramic nozzle manufacturing to neutralize single-source vulnerabilities from German and Italian specialty suppliers. Anchor predictive maintenance subscriptions through ISOBUS-compatible platform lock-in, defending against drone-spraying entrants exploiting FAA Part 137 waiver expansion. Capacity addition in Southeast Asian dealer networks counters Kubota's regionally priced connectivity bundles. For New Entrants and Emerging Players: The 40-60% price-point gap between premium smart-spraying platforms and economy pressure sprayers creates entry space for mid-tier automated retrofit kits. Indonesia's palm oil estates in Sumatra and Kalimantan offer the most penetrable geography given mechanization rates below 15%. Partner with established ground equipment distributors to bypass dealer network buildout costs. For Investors and Strategic Acquirers: Re-rating potential sits with precision agriculture retrofit specialists given convergence of AI-weed recognition and PWM nozzle control reducing chemical volumes 60-80%. Five-to-ten year viability favors vendors with embedded systems engineering talent capable of integrating computer vision modules with OEM platforms. Watch EASA beyond-visual-line-of-sight framework finalization as inflection indicator for drone-spraying service model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | John Deere's Operations Center locks multi-year service contracts alongside hardware sales. |
| Drone Payload Engineering Partnership | Lithium-sulfur battery advances extend ANVISA-registered aerial application endurance above 25 minutes. |
| Regional Dealer Network Expansion | Kubota's Southeast Asian connectivity bundles capture smallholder cooperative procurement aggregation. |
| EU F-Gas Compliance Redesign | Battery-powered diaphragm pumps reposition handheld sprayers ahead of 2030 enforcement deadlines. |
| AI-Weed Recognition Licensing | Bosch and XAG computer vision modules enable spot-spray applications reducing broadcast chemical volumes. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with equipment procurement managers at agricultural cooperatives, precision agriculture specialists at commercial grain operations, and aftermarket service heads at dealer networks. Secondary validation drew from EPA aerial application standards, EASA unmanned aerial system frameworks, ANVISA chemical registration databases, and EU F-Gas Regulation implementation reports. Bottom-up equipment shipment analysis and top-down input-cost modeling were triangulated against telemetry subscription revenue disclosures.
Data-stream reconciliation across product type, application chemistry, end-user scale, and technology tier generated volume and value outputs over the projection horizon. Segmentation dimensions modeled include tractor-mounted versus drone versus handheld configurations, crop protection versus herbicide versus fertilization applications, cooperative versus commercial grower versus individual farmer end users, and smart versus automated versus pressure versus manual spraying technologies. CAGRs were derived from replacement cycle compression rates and precision agriculture adoption curves, with chemical registration timeline delays and battery endurance improvement trajectories as industry-specific forecast inputs.
Inputs from OEM dealer networks and cooperative machinery rings were available through the study window; gaps in smallholder informal procurement data introduce uncertainty bands in Southeast Asian volume estimates. Forecasts reflect assumptions around regulatory waiver expansion and chemical formulation approval timelines. Periodic stress-testing of base assumptions is recommended given multi-jurisdiction certification volatility and commodity input price swings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Crawler Tractors Market