
 Germany Agricultural Tractor Market | 2026-2036
Germany Agricultural Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Agricultural Tractor Market Foresight
Smallholder-to-mid-scale farm demand is collapsing as consolidated agricultural cooperatives and rental services capture an expanding share of new tractor procurement. CLAAS Group dominates premium hay and forage tractor segments through its Harsewinkel manufacturing base. Deere & Company competes via precision agriculture integration and dealer network density across northern Germany. SAME Deutz-Fahr anchors its position in the utility tractor tier, leveraging Italian-German engineering heritage for mixed-cropping operations.
An agricultural tractor is a self-propelled vehicle engineered to deliver tractive power for pulling or powering agricultural implements, typically featuring diesel engines ranging from 20 to 600+ horsepower, hydraulic three-point hitch systems, and power-take-off (PTO) shafts rated at standard speeds of 540 or 1000 rpm. Its primary commercial purpose is to mechanize soil preparation, planting, cultivation, and harvesting operations across arable and livestock farming systems. Utility tractors and row crop tractors together constitute the structural core of the German market, with the 100-150 HP power rating band capturing the densest margin pool as farmers seek versatile machines capable of both field work and transport duties. GPS Technology and autonomous systems represent the fastest-expanding technology segments, though fuel-efficient engines retain the largest installed base due to total cost-of-ownership calculations on fuel-intensive operations.
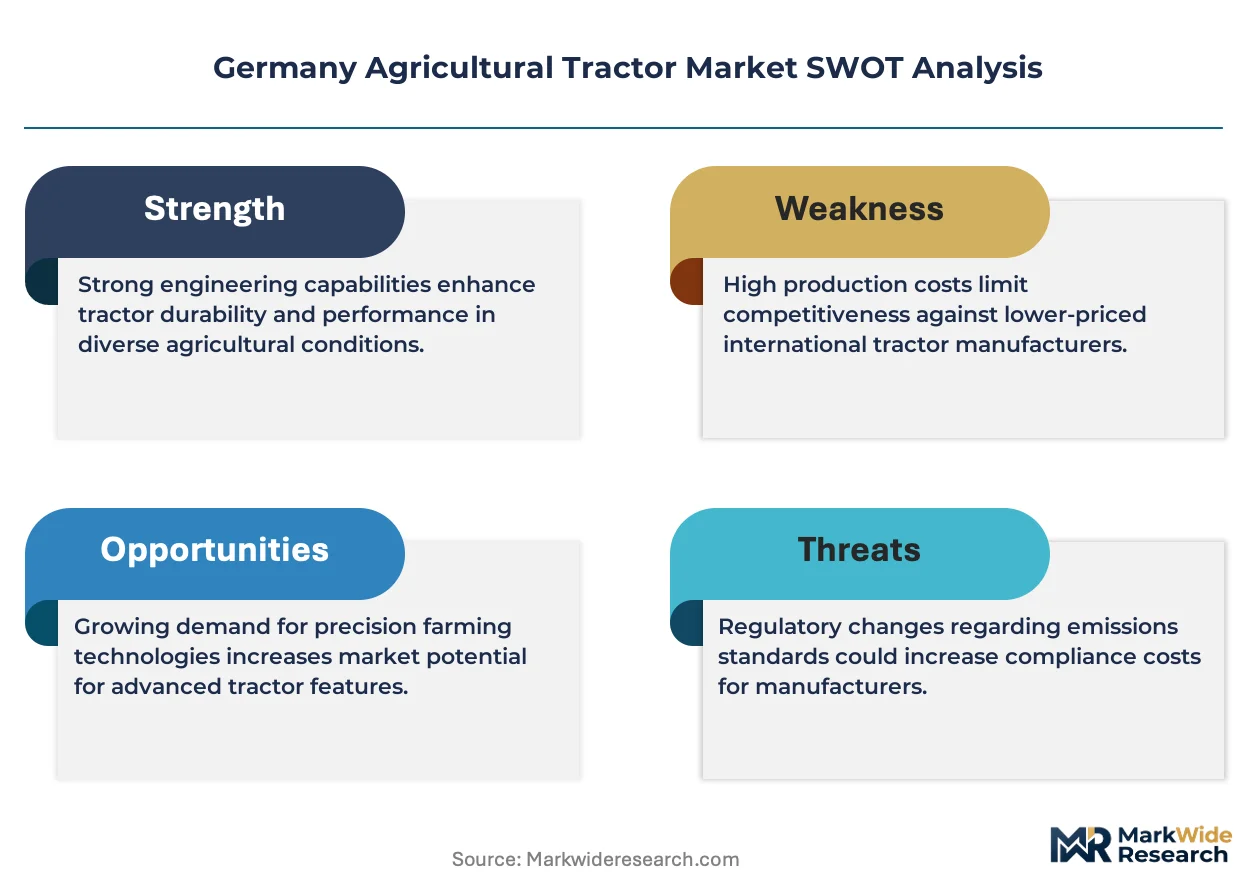
Germany's Federal Motor Transport Authority (KBA) enforces type-approval standards for agricultural tractors under EU machinery directives, while the EU F-Gas Regulation and Stage V emissions standards from the European Commission constrain engine architecture and after-treatment system design. These regulatory frameworks elevate engineering costs for domestic and imported manufacturers while creating compliance barriers for lower-tier suppliers. Stakeholders must monitor the intersection of autonomous system liability frameworks and subsidy eligibility under the EU Common Agricultural Policy's technology modernization incentives.
Market Dynamics
Precision agriculture adoption is compressing replacement cycles across Lower Saxony and Bavaria, while KBA type-approval standards under EU machinery directives force engineering redesigns that favor established manufacturers with compliance infrastructure.
Growth Catalysts
- EU Common Agricultural Policy technology modernization incentives:Subsidy eligibility for GPS-equipped and autonomous-capable tractors accelerates fleet upgrades among dairy cooperatives in northern Germany.
- Stage V emissions standards:Mandates for after-treatment systems and engine architecture changes create replacement demand as pre-compliant machinery ages out of certification.
- Consolidated agricultural cooperatives:Larger procurement volumes from centralized buying entities in intensive arable zones drive premium equipment uptake.
Market Restraints
- Steel and semiconductor input volatility:Engine component and hydraulic system manufacturing faces margin pressure from commodity price swings and foundry capacity constraints.
- Technical limitation in autonomous liability frameworks:Unclear fault attribution for unmanned field operations delays full commercial deployment of driverless systems.
- Substitution threat from equipment rental services:Cooperative-owned machinery pools reduce individual farm capital expenditure requirements.
Strategic Opportunities
- Underpenetrated mixed-cropping regions in eastern Germany:Smaller farms in Brandenburg and Saxony-Anhalt remain underserved by precision agriculture service networks.
- Technology convergence of telematics and predictive maintenance:Real-time diagnostics bundled with dealer service contracts create recurring revenue streams.
- Regulatory tailwind from F-Gas Regulation phase-down:Transition to lower-global-warming-potential refrigerants in cab climate systems opens retrofit and new-equipment positioning.
Industry Challenges
- Certification timeline compression under KBA procedures:EU machinery directive amendments accelerate approval deadlines while test protocol complexity increases.
- Integration complexity with legacy farm management software:Proprietary data formats from existing precision agriculture platforms obstruct seamless equipment interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Agricultural Tractor Market |
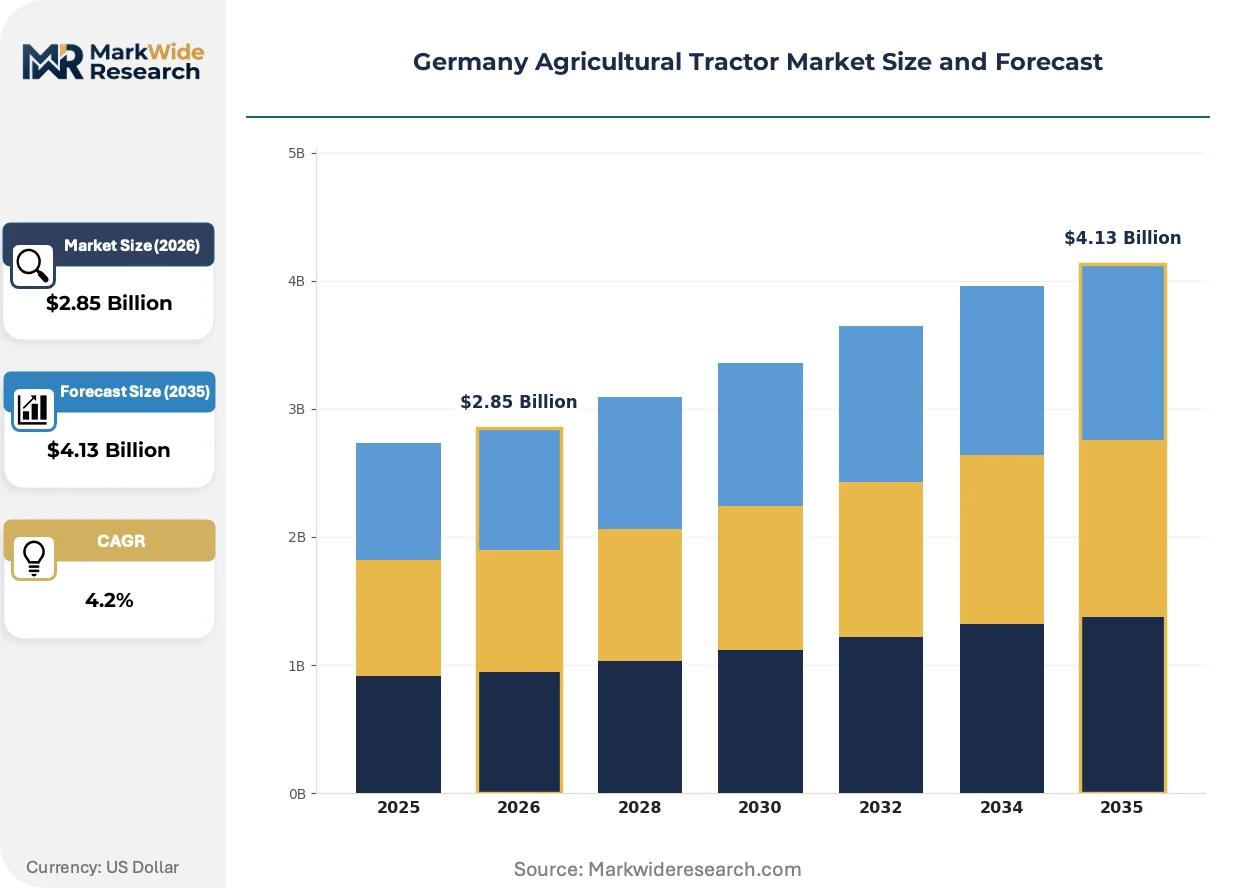
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, Garden Tractors Power Rating: Less than 50 HP, 50-100 HP, 100-150 HP, Above 150 HP End User: Farmers, Agricultural Co-operatives, Rental Services, Government Entities Technology: Hybrid Technology, GPS Technology, Autonomous Systems, Fuel-Efficient Engines |
| Companies Covered | AGCO Corporation, SAME Deutz-Fahr, CLAAS Group, Zetor Tractors, Argo Tractors, Deere & Company, Kubota Corporation, Lindner, CNH Industrial NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Agricultural Tractor Market Shifts & Advancements
Electrification and autonomous control architectures are redefining tractor engineering priorities, while procurement centralization among cooperatives reshapes distribution economics.
Variable-rate application systems paired with real-time soil sensing is supplanting uniform broadcast methods across large arable operations in Lower Saxony. Dairy and grain cooperatives with capital reserves are deploying these systems at replacement cycle points. This technology is supplanting manual input calibration and reducing fertilizer over-application penalties under Düngeverordnung compliance monitoring.
The EU F-Gas Regulation mandates progressive reduction in hydrofluorocarbon use for cab air-conditioning systems, forcing redesigns of thermal management architecture. Manufacturers must certify alternative refrigerants under KBA type-approval procedures before market entry. The 100-150 HP utility segment, where cab comfort specifications are standard, faces the steepest engineering cost adjustments.
Equipment-as-a-service contracting is displacing outright purchase among mid-scale farms with irregular cash flows. Dealer networks in Bavaria are piloting hour-based utilization agreements that bundle maintenance and telemetry. This model concentrates most visibly among livestock operations with seasonal workload spikes.
Germany Agricultural Tractor Market Segmentation
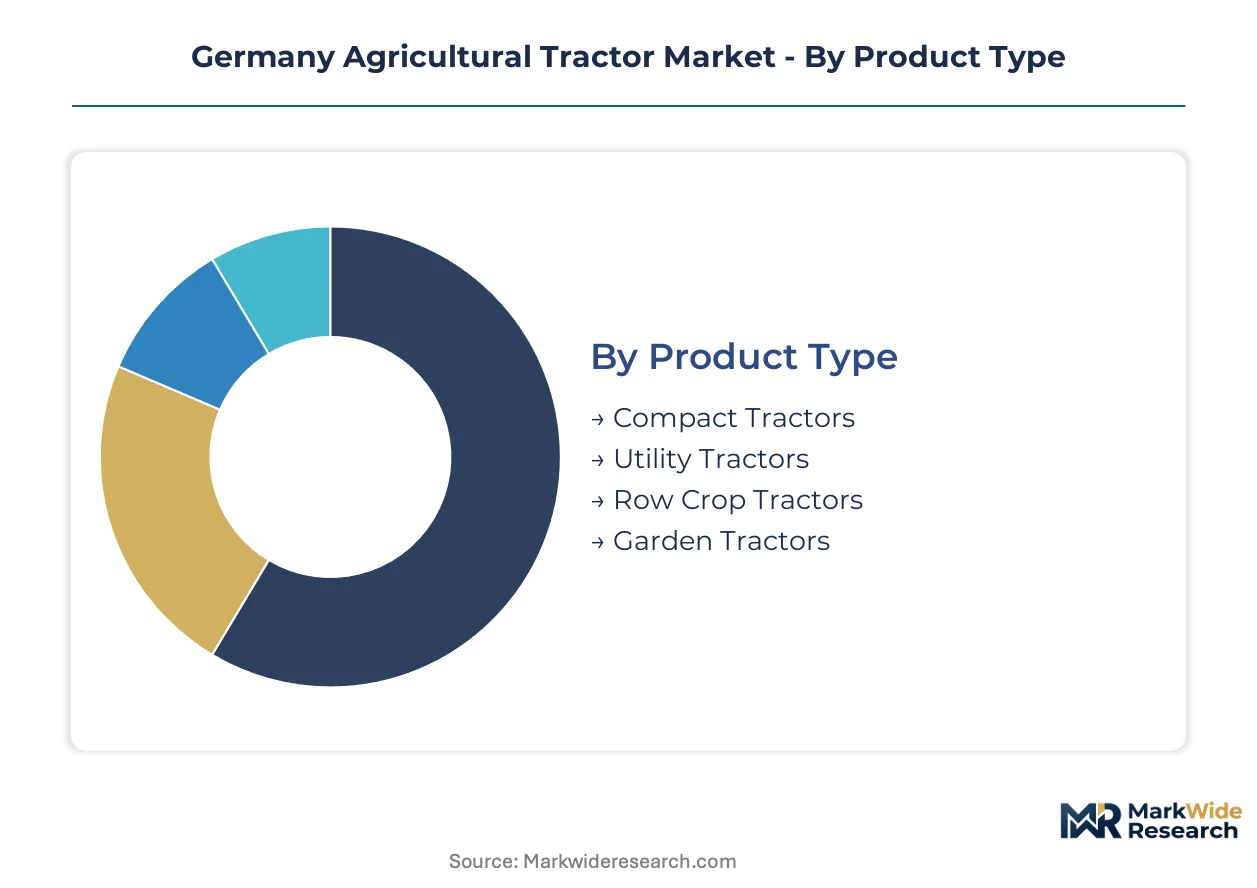
Tractor procurement in Germany fragments across power bands, ownership models, and technology tiers that KBA type-approval standards treat with varying stringency. Each segment carries distinct compliance burdens and subsidy eligibility profiles under EU Common Agricultural Policy modernization incentives.
Product Type:
KBA certification timelines and Stage V after-treatment requirements differentiate tractor categories by engineering complexity and approval cost.
- Utility Tractors:These machines dominate the 100-150 HP band with three-point hitch systems and PTO shafts rated at 540 or 1000 rpm. Dairy cooperatives in Lower Saxony concentrate replacement demand here, driven by Düngeverordnung compliance requirements for precision fertilizer application.
- Row Crop Tractors:High-clearance designs with adjustable axle widths accommodate intensive arable operations. Bavarian grain cooperatives deploy these for variable-rate seeding, where GPS integration justifies capital expenditure against CAP technology subsidies.
- Compact Tractors:Sub-50 HP units serve vineyard and orchard operations in Baden-Württemberg with narrow chassis configurations.
- Garden Tractors:Light-duty machines target hobby farms and municipal maintenance with limited hydraulic capacity.
Established volume favors Utility Tractors; emerging adoption favors Row Crop Tractors.
Power Rating:
Engine displacement determines Stage V after-treatment architecture and total cost-of-ownership calculations across German farming systems.
- 100-150 HP:This band captures the densest margin pool with versatile field-to-transport capability. Intensive arable farms in Lower Saxony standardize procurement here, balancing implement pull requirements with road registration efficiency under KBA procedures.
- Above 150 HP:High-horsepower units integrate advanced emissions after-treatment and telematics platforms. Large dairy operations in Bavaria absorb these costs through cooperative procurement volumes and CAP modernization incentives.
- 50-100 HP:Mixed-cropping farms in eastern Germany favor this tier for capital efficiency on mid-scale holdings.
- Less than 50 HP:Specialty producers and smallholders dominate this segment with limited precision agriculture integration.
Margin concentration sits with 100-150 HP; technology migration accelerates most quickly above 150 HP.
End User:
Procurement centralization is restructuring distribution economics and service contract bundling across German dealer networks.
- Agricultural Co-operatives:Centralized buying entities in northern Germany aggregate fleet orders for precision-equipped machines. These organizations negotiate telemetry-enabled service contracts that lock in dealer maintenance revenue.
- Farmers:Individual owner-operators in mixed-cropping regions retain price sensitivity and irregular replacement cycles. Brandenburg and Saxony-Anhalt holdings under 200 hectares delay upgrades absent subsidy triggers.
- Rental Services:Machinery pools reduce individual capital expenditure through hour-based utilization agreements.
- Government Entities:Municipal and research procurement drives limited volume for demonstration and conservation programs.
Volume leadership belongs to Agricultural Co-operatives; fragmentation persists among Farmers.
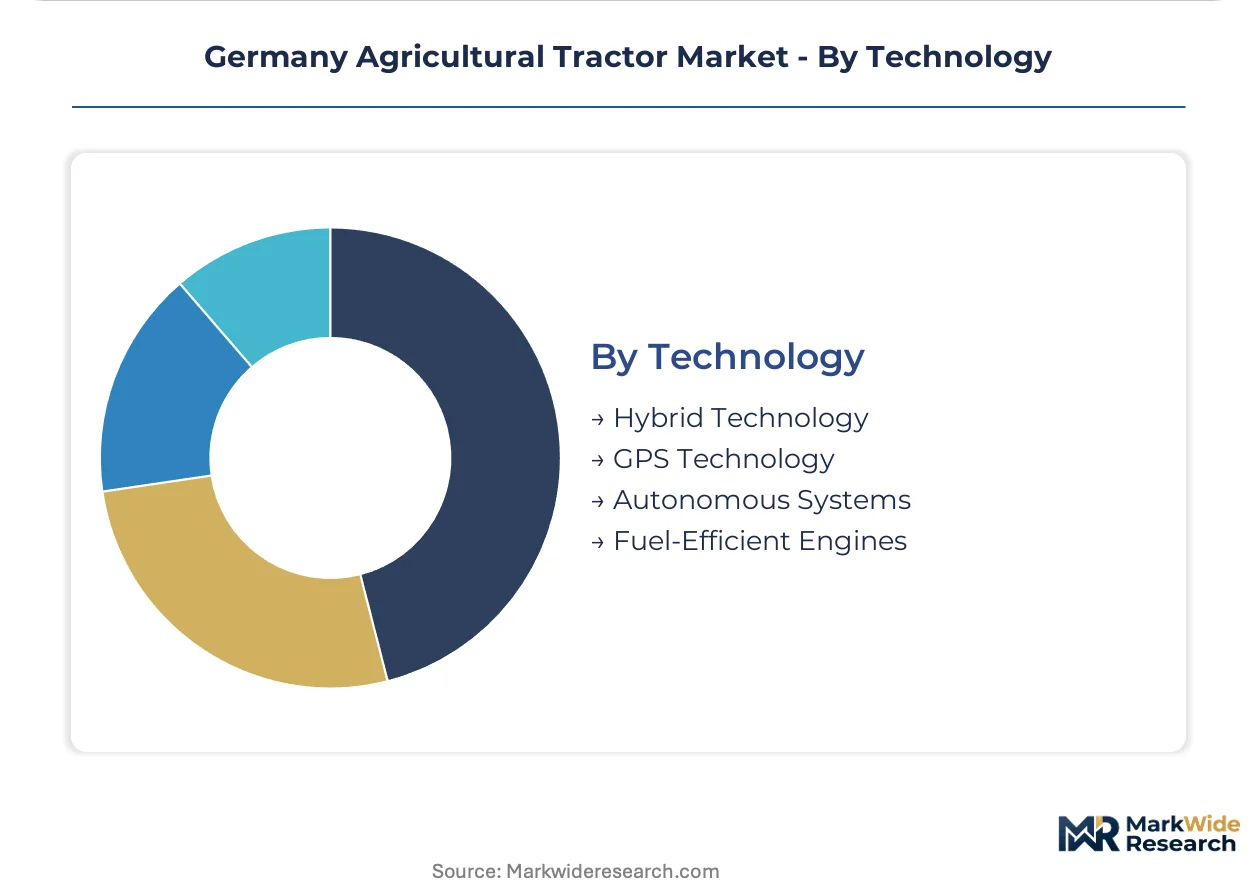
Technology:
EU F-Gas Regulation and autonomous liability frameworks segment equipment by refrigerant compliance and operational risk profiles.
- GPS Technology:Real-time kinematic positioning enables variable-rate application with sub-inch accuracy. Lower Saxony arable operations deploy these systems to minimize fertilizer over-application penalties under Düngeverordnung monitoring.
- Autonomous Systems:Driverless field operations face delayed commercial deployment due to unclear fault attribution. KBA has yet to finalize type-approval protocols for unmanned machinery, constraining manufacturer investment.
- Fuel-Efficient Engines:Stage V compliant powertrains retain the largest installed base through total cost-of-ownership optimization on fuel-intensive operations.
- Hybrid Technology:Diesel-electric architectures remain nascent with limited German field validation beyond demonstration programs.
Installed base dominance rests with Fuel-Efficient Engines; regulatory tailwinds favor GPS Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tractor manufacturers export precision-equipped machinery across the European Union, with Austria, Switzerland, and the Benelux countries absorbing the majority of cross-border sales volumes.
Lower Saxony
Dairy cooperatives in the Emsland and Oldenburg regions drive replacement demand for 100-150 HP utility tractors with GPS-enabled variable-rate application systems. KBA type-approval procedures for Stage V emissions compliance extend procurement timelines for fleet operators. Claas maintains its Harsewinkel manufacturing base here, supplying hay and forage equipment to northern European markets.
Bavaria
Grain cooperatives in the Munich hinterland and Danube basin concentrate procurement of high-horsepower row crop tractors above 150 HP. EU Common Agricultural Policy technology modernization incentives subsidize GPS integration and telematics platforms. Deere & Company operates its densest German dealer network across this region, capturing cooperative fleet orders through precision agriculture bundling.
Baden-Württemberg
Vineyard and orchard operations in the Stuttgart basin and Lake Constance district favor compact tractors below 50 HP with narrow chassis configurations. The F-Gas Regulation mandates refrigerant transitions in cab climate systems, elevating engineering costs for specialty equipment. Lindner produces mountain-adapted tractors in Kundl, Austria, with significant cross-border sales into this southwestern German market.
North Rhine-Westphalia
Mixed-farming enterprises in the Münsterland and Lower Rhine districts balance arable and livestock operations with mid-range 50-100 HP equipment. SAME Deutz-Fahr leverages its Italian-German engineering heritage to serve this diversified customer base. Equipment rental services headquartered in Düsseldorf and Cologne reduce individual farm capital expenditure through cooperative machinery pools.
Brandenburg
Post-reunification agricultural restructuring leaves smaller holdings in the Uckermark and Prignitz regions underserved by precision agriculture service networks. Farmers here delay tractor upgrades absent explicit subsidy triggers from federal or EU programs. Eastern German machinery dealers struggle to match the service contract bundling available through northern cooperative networks.
Germany Agricultural Tractor Market Competitive Landscape
Player mix skews toward diversified agricultural machinery conglomerates with established compliance infrastructure for KBA type-approval and Stage V emissions certification. Market structure concentrates procurement influence among three to five integrated manufacturers capable of bundling precision agriculture hardware with dealer service networks. Strategic archetypes include premium precision-technology specialists, utility-tier mixed-cropping suppliers, and compact-equipment vineyard specialists. Dominant competitive moves center on telemetry-enabled service contract bundling and geographic consolidation of dealer maintenance coverage.
Within the premium-tier precision-technology segment, Deere & Company and CLAAS Group anchor positions through integrated GPS and autonomous system roadmaps. SAME Deutz-Fahr occupies a distinct utility-tier position serving mixed-cropping operations with capital-efficient equipment specifications. Among compact-specialist fabricators, Lindner exemplifies mountain-adapted engineering for vineyard and orchard topography.
| Leading Market Players |
|---|
| AGCO Corporation |
| SAME Deutz-Fahr |
| CLAAS Group |
| Zetor Tractors |
| Argo Tractors |
| Deere & Company |
| Kubota Corporation |
| Lindner |
| CNH Industrial NV |
| Others |
Supply & Pricing Matrix
Foundry capacity utilization at major European engine component suppliers shapes both manufacturing concentration and price floors for German tractor OEMs, with Stage V after-treatment system costs establishing minimum viable pricing thresholds across the 100-150 HP utility segment.
Pricing Analysis
Stage V-compliant powertrains command a technology-generation pricing gap of approximately fifteen to twenty percent above pre-compliant machinery, while GPS-integrated precision packages and autonomous-ready architectures widen spreads further at the premium tier. Three-tier pricing structure across premium precision-specification, standard utility-configuration, and economy mixed-cropping levels dominates procurement, with certification grade under KBA type-approval and cooperative volume scale serving as primary differentiation drivers. Cost compression in the sub-100 HP compact segment is intensifying because rental service substitution erodes individual farm willingness-to-pay. Individual owner-operators in eastern German mixed-cropping regions exhibit highest price sensitivity, whereas consolidated dairy cooperatives in Lower Saxony absorb premium positioning through CAP modernization incentive offsets.
Supply Chain Analysis
Inbound logistics costs from Italian and Austrian component corridors have tightened delivery windows for hydraulic system and transmission assemblies serving Harsewinkel and Mannheim manufacturing clusters. Geographic supply concentration centers on Germany, Italy, and Austria for precision transmission and axle systems, with steel foundry capacity and semiconductor sensor modules drawing from Czech and Hungarian feeder plants. Raw material dependencies rest on high-grade steel alloys, hydraulic fluid formulations, and emissions after-treatment catalyst substrates. Single-source vulnerability in semiconductor-based telematics controllers presents structural risk given automotive sector competition for foundry allocation. Distribution runs through cooperative-aligned dealer networks with bundled service contracting, concentrating aftermarket parts flow through Bavarian and Lower Saxony logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment rental services and autonomous machinery-as-a-service platforms threaten capital-equipment incumbents with substitution, compelling defensive repositioning around telemetry-enabled recurring revenue.
For Market Incumbents: Shield core fleet positions by deepening backward integration into precision sensor manufacturing and securing exclusive service contract bundling with Lower Saxony dairy cooperatives. Prioritize KBA certification pipeline investment to compress approval timelines against rental service fleet refresh cycles. Vertical control over telematics platform development reduces interoperability risk with legacy farm management software. For New Entrants and Emerging Players: Anchor in eastern German mixed-cropping territories where precision agriculture service networks remain underdeveloped and cooperative procurement concentration is weakest. Target Brandenburg and Saxony-Anhalt smallholders with capital-efficient 50-100 HP utility specifications and subsidy-triggered financing structures. Deploy dealer partnership models emphasizing field demonstration and seasonal rental conversion rather than direct fleet sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telemetry-integrated precision agriculture specialists with established KBA type-approval infrastructure and cooperative service contract backlogs. Long-term viability across the analysis window favors manufacturers capable of bundling hardware with predictive maintenance subscriptions. Acquisition target archetype: mid-scale German OEMs with Stage V compliance certification and underpenetrated eastern German dealer footprints. Signal to watch: KBA finalization of autonomous system liability protocols as inflection indicator for driverless fleet investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Bundles real-time diagnostics with dealer service contracts, locking in recurring revenue from Lower Saxony cooperatives. |
| Stage V Certification Acceleration | Compresses KBA approval timelines to capture replacement demand as pre-compliant machinery ages out of eligibility. |
| Eastern German Dealer Expansion | Extends precision agriculture service networks into underserved Brandenburg and Saxony-Anhalt smallholder territories. |
| Autonomous System Liability Preparation | Pre-positions engineering and legal frameworks ahead of KBA unmanned machinery type-approval finalization. |
| Rental Service Partnership Structure | Converts outright sales risk into hour-based utilization agreements with Bavarian livestock operations. |
Research Methodology
The analysis maps utility tractor, row crop tractor, compact tractor, and garden tractor sub-sectors, each validated through procurement directors at agricultural cooperatives, fleet managers at dairy operations, aftermarket service heads at dealer networks, and precision agriculture integration specialists. Primary interview findings triangulated against KBA registration databases, EU Common Agricultural Policy subsidy disbursement records, Stage V emissions certification filings, and agricultural machinery trade association production statistics. Bottom-up unit shipment estimates reconciled with top-down value projections across power rating and technology tier segmentations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled dimensions spanning product type, power rating band, end user procurement archetype, and technology integration level. CAGRs derived from fitted growth curves incorporating replacement cycle compression rates, subsidy eligibility phase-ins, and emissions compliance transition timelines. Industry-specific forecast inputs included Düngeverordnung enforcement intensity indices and cooperative consolidation trajectories in northern Germany.
Material uncertainties — steel and semiconductor input volatility, autonomous liability framework delays, and CAP subsidy recalibration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory stability and cooperative procurement continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Canada Agricultural Machinery Market