
 Global Chemical Vapor Deposition (CVD) Market | 2026-2036
Global Chemical Vapor Deposition (CVD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Vapor Deposition (CVD) Market Foresight
A capital-intensity divergence between integrated equipment giants and specialized reactor builders is unwinding competitive dynamics across the CVD landscape. Applied Materials Inc. leverages its sprawling process equipment portfolio to bundle deposition tools with etch and inspection systems, locking in fab-level procurement contracts. Aixtron SE specializes in metal-organic CVD systems for compound semiconductors, anchoring its position in gallium nitride and silicon carbide epitaxy for power electronics.
Chemical vapor deposition constitutes a thin-film manufacturing process wherein precursor gases react or decompose on a heated substrate surface to deposit materials with angstrom-level thickness control, typically operating at temperatures between 300°C and 1100°C depending on the film chemistry and reactor design. Plasma-enhanced CVD dominates volume shipments for interlayer dielectrics in semiconductor fabrication due to its lower thermal budget compatibility with copper interconnects, while atomic layer deposition captures expanding share in advanced node gate stacks and 3D NAND string formation where sub-nanometer precision proves essential. Thermal CVD retains maturity in polysilicon and silicon nitride applications where established throughput economics resist displacement.
EPA emission standards and REACH chemical authorization requirements in the United States and Europe are forcing equipment redesigns around precursor containment and exhaust abatement, elevating compliance costs for reactor suppliers while creating specification premiums for certified low-emission platforms. Japan's METI maintains jurisdiction over fluorinated gas controls affecting CVD cleaning chemistries, with JIS standards governing equipment safety certifications for domestic fab deployments. Stakeholders must weigh precursor toxicity profiles against deposition performance as regulatory timelines compress for next-generation chemistries.
Market Dynamics
Equipment suppliers face intensifying pressure to reconcile thermal budget constraints with throughput demands as logic nodes shrink below 3nm and 3D NAND layer counts exceed 300 tiers. Plasma-enhanced CVD tools now dominate new fab construction, displacing thermal CVD in dielectric applications where copper interconnect compatibility determines process selection.
Growth Catalysts
- Advanced Node Migration:Logic manufacturers below 5nm require atomic layer deposition precision for gate stack formation, pulling high-margin equipment into production lines. Taiwan and South Korea fabs anchor this demand concentration.
- REACH Chemical Authorization:Europe's phased restrictions on fluorinated precursors are accelerating qualification of alternative chemistries for chamber cleaning cycles. Equipment makers capturing certified low-emission designs command specification premiums.
- Power Electronics Epitaxy:Silicon carbide and gallium nitride device fabrication for electric vehicle inverters requires metal-organic CVD systems with specialized reactor geometries. Automotive qualification timelines compress deployment windows.
Market Restraints
- Precursor Supply Concentration:High-purity tungsten hexafluoride and silane production concentrates among Japanese and German chemical suppliers. Geopolitical friction elevates input cost volatility and qualification risk for alternative sources.
- Technical Limitation at Scale:Atomic layer deposition throughput remains an order of magnitude below plasma-enhanced CVD for thick dielectric applications. Deposition rate constraints limit ALD penetration in volume manufacturing steps.
- Regulatory Friction:EPA New Source Performance Standards for semiconductor fabrication impose exhaust abatement capital requirements that extend payback periods for reactor investments by 18-24 months.
Strategic Opportunities
- India Semiconductor Mission:Subsidized fab construction under India's PLI scheme creates greenfield equipment demand without incumbent supplier lock-in. First-mover qualification advantages apply for deposition tool vendors.
- Photonics Integration:Silicon photonics manufacturing for datacenter interconnects requires low-temperature silicon nitride deposition on non-native substrates. Emerging applications escape commoditization pressures affecting mainstream logic.
- EU Green Deal Alignment:Carbon border adjustment mechanisms favor equipment with documented energy efficiency and precursor recovery systems. Certified platforms access preferential procurement scoring in European tenders.
Industry Challenges
- Process Engineer Scarcity:Specialized expertise in plasma physics and precursor kinetics concentrates among experienced fab operators. Equipment vendors struggle to staff field service and applications engineering roles.
- Legacy Tool Integration:Brownfield fab expansions require deposition systems to communicate with 200mm-era manufacturing execution systems. Retrofit complexity extends commissioning timelines.
- Qualification Compression:Advanced node tape-out schedules leave 12-18 months for new chemistry and equipment qualification. Concurrent process development elevates technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Vapor Deposition (CVD) Market |
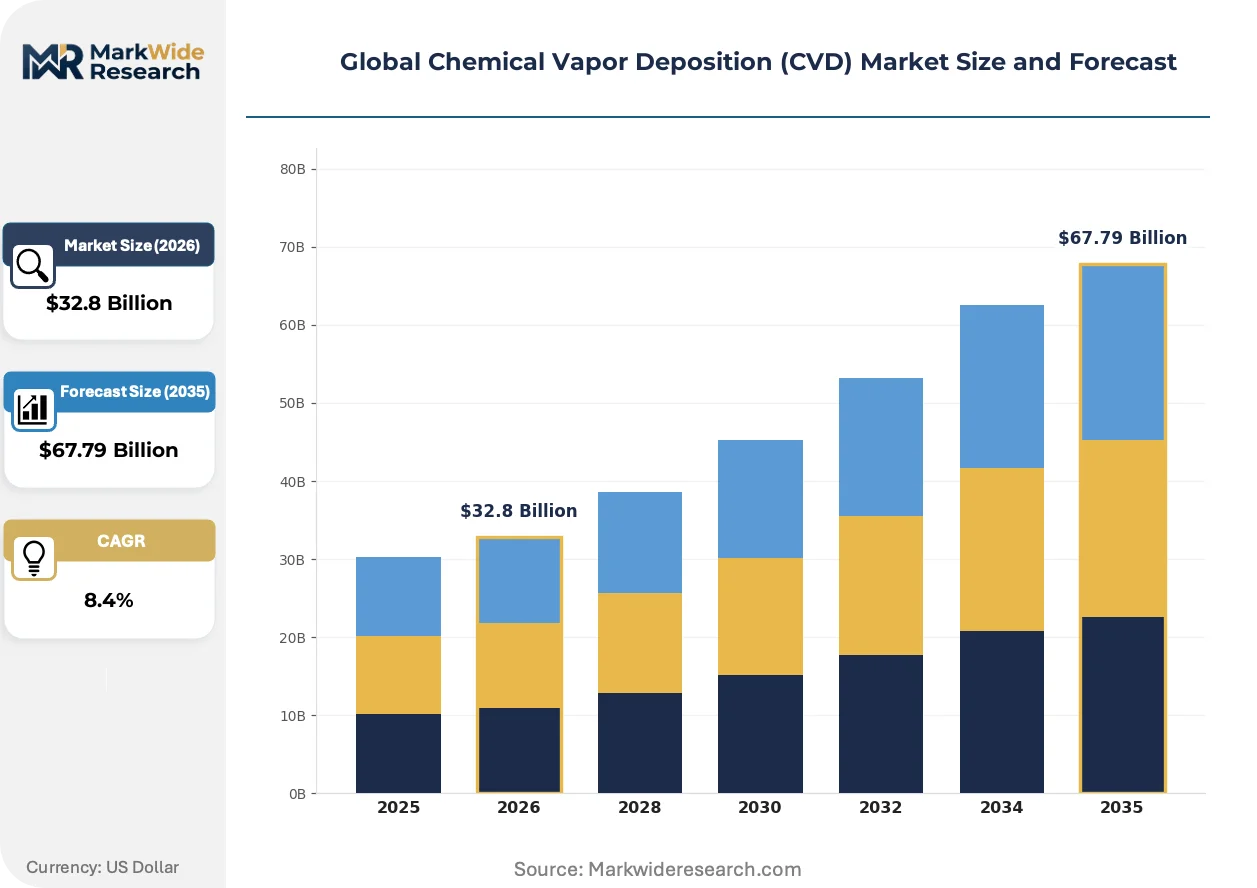
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal CVD, Plasma-Enhanced CVD, Low-Pressure CVD, Atomic Layer Deposition, Metal-Organic CVD Application: Semiconductor Fabrication, Solar Cells Manufacturing, Optical Coatings, Energy Storage Devices, MEMS Production End User Industry: Electronics Manufacturers, Photovoltaic Companies, Coating Specialists, Battery Producers, Microdevice Fabricators Technology: Gas Phase Reaction, Surface Reaction, Hot-Wall Reactor, Cold-Wall Reactor, Pulsed CVD |
| Companies Covered | Veeco Instruments Inc., Applied Materials Inc., CVD Equipment Corporation, ULVAC Inc., Aixtron SE, Tokyo Electron Limited, ASM International NV, Plasma-Therm LLC, IHI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Vapor Deposition (CVD) Market Shifts & Advancements
Deposition technology is bifurcating between extreme precision for atomic-scale control and high-throughput platforms for commodity dielectric stacks. Equipment architecture, precursor chemistry, and service models are all undergoing simultaneous recalibration.
Remote plasma CVD is decomposing precursor gases at lower substrate temperatures than conventional thermal methods, enabling deposition on temperature-sensitive substrates including polymers and compound semiconductors. Memory manufacturers in South Korea and Japan are adopting these systems for 3D NAND string formation where thermal budget constraints intensify with stacking depth. The technology is decomposing the traditional boundary between front-end and back-end process equipment, allowing deposition steps to migrate into packaging flows.
Japan's METI fluorinated gas controls are forcing systematic replacement of nitrogen trifluoride and sulfur hexafluoride in chamber cleaning protocols with fluorine-based alternatives or in-situ plasma cleaning. Equipment suppliers must redesign gas delivery systems and exhaust handling to accommodate corrosive byproducts. Domestic Japanese fabs face the most compressed compliance timelines, with JIS certification requirements adding 6-9 months to equipment qualification.
Consolidated procurement consortia among foundry operators are unbundling after-sales service contracts from initial equipment purchases. Leading logic manufacturers now negotiate multi-fab service agreements with specialized third-party maintenance providers, bypassing OEM service organizations. This restructuring is most advanced in Taiwan, where foundry scale permits dedicated captive service teams.
Global Chemical Vapor Deposition (CVD) Market Segmentation
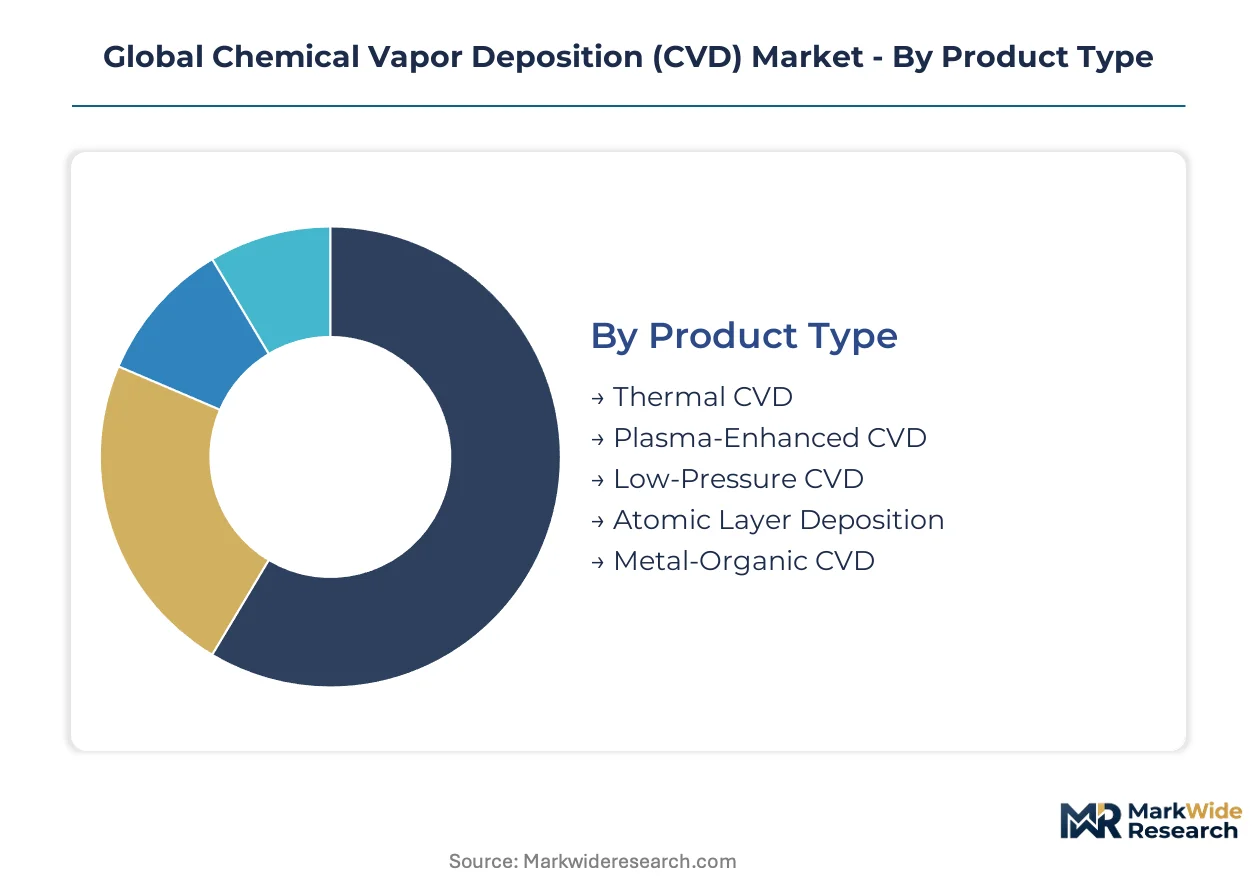
CVD equipment selection hinges on thermal budget constraints, film thickness precision, and substrate compatibility. Segmentation reveals how process requirements fragment procurement patterns across logic, memory, and power device fabrication.
Product Type:
EPA New Source Performance Standards and Japan's METI fluorinated gas controls are forcing equipment redesigns around exhaust abatement and precursor containment, with certified low-emission platforms commanding specification premiums in regulated markets.
- Plasma-Enhanced CVD:Deposition occurs through gas-phase plasma activation rather than thermal decomposition, enabling processing below 400°C for copper interconnect compatibility. Taiwan and South Korea logic fabs anchor demand as interlayer dielectric deposition migrates from thermal methods. PECVD systems dominate new fab construction for dielectric applications.
- Atomic Layer Deposition:Sequential self-limiting surface reactions achieve angstrom-level thickness control through discrete precursor pulses. Advanced node gate stacks and 3D NAND string formation in Taiwan and South Korea drive adoption where sub-nanometer precision proves essential. Throughput constraints limit penetration in thick dielectric steps.
- Thermal CVD:High-temperature gas-phase decomposition deposits polysilicon and silicon nitride films with established throughput economics.
- Low-Pressure CVD:Reduced operating pressure enhances film uniformity across batch-loaded wafers for mature semiconductor processes.
- Metal-Organic CVD:Organometallic precursors deposit compound semiconductor epitaxial layers for silicon carbide and gallium nitride power electronics.
Plasma-Enhanced CVD handles the majority of throughput; Atomic Layer Deposition is the fastest mover on share.
Application:
Cost tier differentiation separates high-margin precision applications from commodity deposition steps, with advanced logic and memory commanding equipment premiums while solar and coating applications prioritize throughput economics.
- Semiconductor Fabrication:Front-end wafer processing deposits gate dielectrics, interconnect barriers, and capacitor electrodes with nanometer-scale control. Taiwan, South Korea, and Japan concentration drives equipment specification intensity as logic nodes shrink below 3nm and 3D NAND exceeds 300 tiers. Process migration from thermal to plasma-enhanced methods accelerates.
- Solar Cells Manufacturing:Anti-reflection coatings and passivation layers on crystalline silicon wafers require high-throughput deposition with relaxed thickness tolerances. China and Southeast Asia manufacturing clusters prioritize capital efficiency over precision. Equipment specifications diverge sharply from semiconductor-grade systems.
- Optical Coatings:Precision interference filters and anti-reflective surfaces for lenses, mirrors, and display panels.
- Energy Storage Devices:Solid-state battery electrolytes and thin-film electrode coatings for next-generation cell architectures.
- MEMS Production:Structural and sacrificial layer deposition for microelectromechanical sensors and actuators.
Semiconductor Fabrication captures the dominant equipment spend; Solar Cells Manufacturing represents the steepest expansion trajectory for system shipments.
End User Industry:
Customer type fragmentation separates captive fab operators from merchant equipment purchasers, with foundry scale enabling consolidated procurement consortia and dedicated service agreements.
- Electronics Manufacturers:Integrated device manufacturers and foundries operate captive deposition equipment for logic, memory, and analog device production. Taiwan Semiconductor Manufacturing and Samsung Electronics anchor global demand concentration through multi-fab capital deployment. Consolidated procurement unbundles service contracts from initial equipment purchases.
- Photovoltaic Companies:Solar cell producers operate high-throughput coating lines with rapid technology refresh cycles. China-based manufacturers dominate capacity expansion with price-sensitive equipment selection criteria.
- Coating Specialists:Merchant optical and decorative coating providers serving industrial and consumer applications.
- Battery Producers:Solid-state and thin-film battery manufacturers piloting CVD for next-generation cell architectures.
- Microdevice Fabricators:Specialized MEMS and sensor producers with small-batch, high-mix production requirements.
Electronics Manufacturers account for the preponderance of equipment revenue; Photovoltaic Companies are climbing the fastest on installation growth.
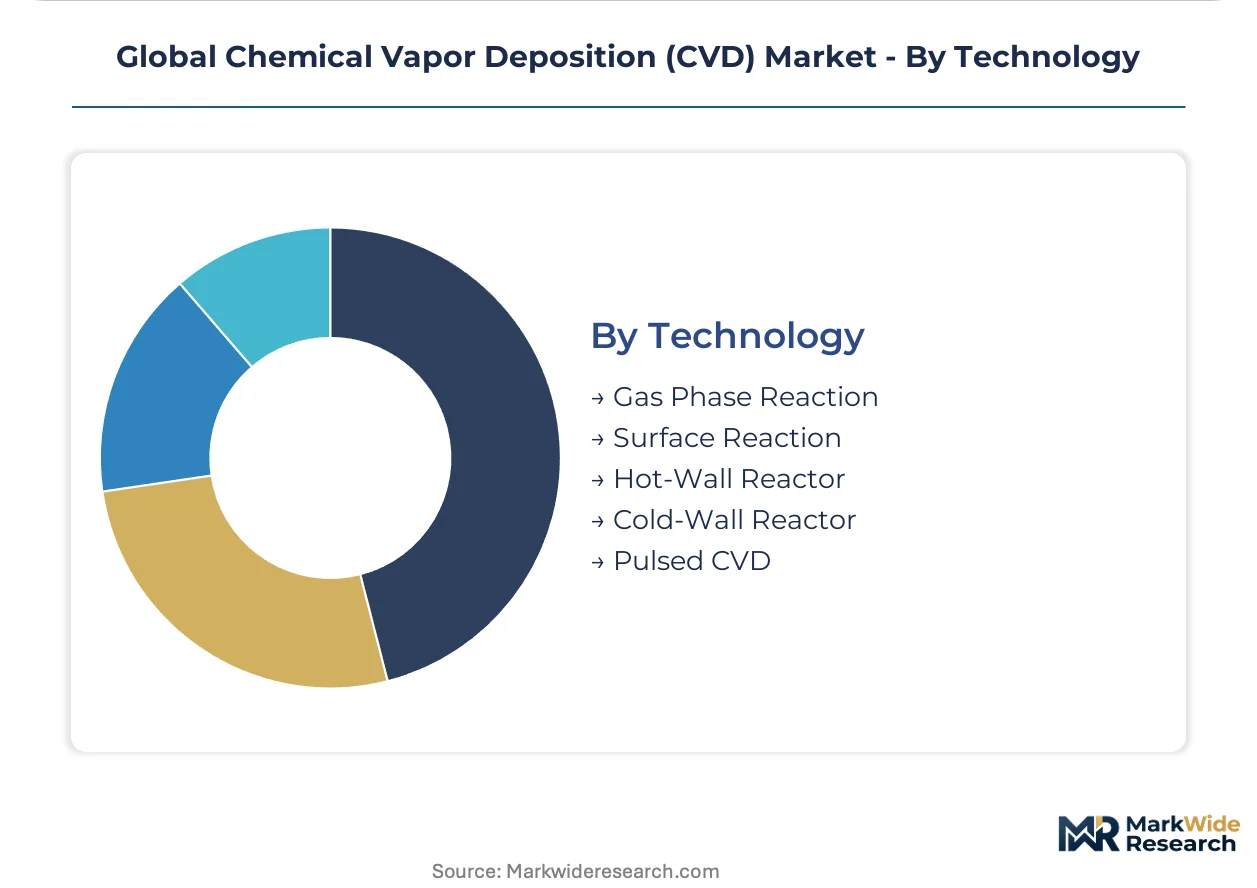
Technology:
Reactor geometry and reaction mechanism determine thermal uniformity, precursor efficiency, and film conformality across substrate topographies.
- Hot-Wall Reactor:Heated chamber walls ensure uniform temperature distribution across batch-loaded wafers, maximizing precursor utilization efficiency for polysilicon and silicon nitride deposition. Mature semiconductor processes in Japan and Europe retain these systems for established throughput economics.
- Surface Reaction:Precursor chemisorption and decomposition limited to the substrate surface enable self-limiting growth control essential for atomic layer deposition precision. Taiwan and South Korea advanced node production drives qualification intensity.
- Gas Phase Reaction:Homogeneous precursor decomposition in the vapor phase prior to substrate arrival.
- Cold-Wall Reactor:Heated susceptors with cooled chamber walls reduce unwanted deposition on reactor surfaces.
- Pulsed CVD:Time-modulated precursor delivery sequences approach atomic layer deposition precision with enhanced deposition rates.
Hot-Wall Reactor retains installed base dominance for mature applications; Surface Reaction is gaining share fastest through ALD adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwan and South Korea where advanced logic and memory fabs cluster, while equipment vendors in Germany and Japan capture specification premiums through regulatory compliance advantages. This asymmetry shapes procurement patterns across major manufacturing geographies.
Taiwan
TSMC's 3nm and 2nm ramp drives atomic layer deposition tool demand for gate stack precision. The National Development Council's semiconductor subsidy programs accelerate fab construction timelines. Hsinchu Science Park anchors the densest equipment procurement cluster globally, with suppliers maintaining dedicated field engineering teams.
South Korea
Samsung Electronics and SK Hynix expand 3D NAND beyond 300 tiers, pulling plasma-enhanced CVD systems for interlayer dielectrics. Korea's Ministry of Trade, Industry and Energy enacts local content requirements under the K-Semiconductor Belt initiative. Pyeongtaek and Yongin complexes concentrate new equipment installations with compressed qualification windows.
United States
CHIPS Act subsidies stimulate greenfield fab construction in Arizona and Texas, creating demand for EPA-certified low-emission platforms. The EPA's New Source Performance Standards impose exhaust abatement capital requirements extending payback periods. Intel's Ohio and Arizona sites anchor domestic equipment procurement with stringent emission compliance specifications.
Japan
Tokyo Electron and Shin-Etsu maintain captive demand for thermal CVD in mature polysilicon processes. METI's fluorinated gas controls force nitrogen trifluoride replacement with alternative chamber cleaning chemistries. Kyushu's Kumamoto and Hiroshima prefectures concentrate memory and logic production facing compressed JIS certification timelines.
Germany
Infineon and Bosch expand silicon carbide power device capacity, driving metal-organic CVD system demand for automotive qualification. ECHA's REACH chemical authorization restricts fluorinated precursor imports, elevating specification premiums for certified low-emission designs. Dresden's Silicon Saxony cluster anchors European equipment procurement with dual compliance requirements.
Global Chemical Vapor Deposition (CVD) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the CVD equipment landscape. The market structures around three tiers: integrated process equipment giants bundling deposition with etch and inspection tools; specialized reactor builders focusing on single-process precision; and regional fabricators serving photovoltaic and coating applications with price-competitive platforms. Consolidation pressure intensifies as foundry procurement consortia unbundle service contracts and demand multi-fab maintenance agreements.
Within the integrated equipment tier, Applied Materials Inc. and Tokyo Electron Limited exemplify archetypes leveraging sprawling process portfolios to lock in fab-level contracts through bundled system procurement. Among specialized reactor builders, Aixtron SE and ASM International NV occupy positions anchored in compound semiconductor epitaxy and atomic layer deposition precision respectively. Veeco Instruments Inc. sits within the precision deposition segment serving compound semiconductor and data storage applications.
| Leading Market Players |
|---|
| Veeco Instruments Inc. |
| Applied Materials Inc. |
| CVD Equipment Corporation |
| ULVAC Inc. |
| Aixtron SE |
| Tokyo Electron Limited |
| ASM International NV |
| Plasma-Therm LLC |
| IHI Corporation |
| Others |
Supply & Pricing Matrix
Nine-month lead times for specialized reactor chambers concentrate pricing power with Japanese and German component suppliers, while fab operators in Taiwan and South Korea absorb premiums for EPA-certified and REACH-compliant configurations. Equipment vendors face compressed margins on standard platforms as procurement consortia unbundle after-sales contracts, yet customization premiums for low-emission designs and multi-fab service agreements sustain margin pools at the high end.
Pricing Analysis
Configured-to-order pricing for specialized reactor geometries commands spreads exceeding standard thermal CVD platforms by significant multiples, with atomic layer deposition systems capturing premiums for sub-nanometer precision. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified low-emission platforms from baseline equipment and refurbished legacy tools. Cost compression in standard PECVD segments intensifies as Chinese photovoltaic manufacturers drive volume procurement, while foundry operators in Taiwan and South Korea show lowest price sensitivity for advanced node gate stack deposition tools.
Supply Chain Analysis
Strategic stockpiling of high-purity tungsten hexafluoride and silane precursors dominates inventory strategy among Japanese and German chemical suppliers facing METI fluorinated gas controls and REACH authorization timelines. Manufacturing concentration in Japan, Germany, and the United States for critical gas delivery systems and exhaust abatement modules creates single-source vulnerability for EPA-compliant platforms. Distribution runs through consolidated procurement consortia anchored by TSMC and Samsung Electronics, bypassing traditional OEM service organizations for multi-fab maintenance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling from initial equipment purchases accelerates faster than hardware revenue growth, as foundry procurement consortia negotiate captive field engineering teams and predictive maintenance contracts spanning multiple fabrication sites.
For Market Incumbents: Fortify service attach rates by embedding predictive maintenance algorithms into reactor control systems, creating switching costs that resist third-party maintenance encroachment. Deepen backward integration into high-purity precursor distribution networks to capture margin pools currently held by Japanese and German chemical suppliers. Vertical integration into exhaust abatement module production addresses EPA New Source Performance Standards compliance premiums. For New Entrants and Emerging Players: Aftermarket service capacity shortages among incumbent OEMs present white-space entry points for specialized third-party maintenance providers targeting brownfield fab expansions. India's Semiconductor Mission subsidies create penetrable greenfield demand without incumbent supplier lock-in, particularly for metal-organic CVD systems serving silicon carbide power electronics. Lead with qualification acceleration services that compress JIS certification timelines for Japanese market entry. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH and EPA emission standards continuously elevate specification premiums for certified low-emission platforms while compressing returns on legacy equipment. Acquisition targets should display captive service revenue streams and compound semiconductor epitaxy exposure. Watch METI fluorinated gas control enforcement intensity as inflection signal for alternative chemistry equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Unbundling | Foundry procurement consortia in Taiwan bypass OEM service organizations for multi-fab agreements. |
| Exhaust Abatement Integration | EPA New Source Performance Standards extend payback periods for reactor investments without certified platforms. |
| Precursor Supply Backward Integration | Equipment vendors capturing tungsten hexafluoride distribution reduce input cost volatility from Japanese suppliers. |
| Remote Plasma CVD Qualification | South Korean 3D NAND manufacturers adopt lower-temperature deposition for thermal budget-constrained string formation. |
| India Greenfield Market Entry | PLI scheme subsidies create first-mover qualification advantages without incumbent equipment lock-in. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with equipment procurement directors, process engineering leads, and aftermarket service heads at logic and memory fabs, combined with secondary validation through SEC 10-K filings, customs equipment import records, and METI fluorinated gas control disclosures. Bottom-up triangulation across reactor shipment volumes, precursor consumption patterns, and fab construction timelines anchored value estimates, while top-down cross-checks against capital expenditure disclosures from TSMC, Samsung Electronics, and Intel verified segmentation splits.
Across the analysis window, the forecasting framework modeled equipment demand by product type, application node, end-user industry, and regional regulatory compliance tier. CAGRs were derived from equipment shipment trajectories correlated with foundry capacity expansion schedules and 3D NAND layer count roadmaps. Inputs included EPA New Source Performance Standards implementation timelines, REACH chemical authorization phase-outs, and automotive qualification windows for silicon carbide power devices.
Forecasts assume regulatory continuity in EPA emission standards, REACH authorization protocols, and METI fluorinated gas controls; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Arginine Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Acesulfame K Market