
 Alkylene Carbonates Market | 2026-2036
Alkylene Carbonates Market Size, Share, and Industry Trends Forecast 2026-2036
Alkylene Carbonates Market Analysis
Asset-light leasing models for carbon capture and solvent recovery infrastructure is fragmenting competitive dynamics among alkylene carbonate producers. BASF leverages integrated propylene oxide supply chains to sustain cost advantages across European production hubs. Mitsubishi Chemical Corporation anchors its position through captive electrolyte-grade ethylene carbonate output serving battery manufacturers. Huntsman International LLC competes via specialized additives formulations that navigate divergent regional purity standards.
Alkylene carbonates comprise a class of cyclic carbonate compounds synthesized through carbon dioxide insertion into alkylene oxides, yielding colorless liquids with boiling points exceeding 240°C and dielectric constants above 60, which serve primarily as polar aprotic solvents and lithium-ion battery electrolyte carriers. Ethylene carbonate dominates value capture due to its irreplaceable role in battery electrolyte formulations where high dielectric strength stabilizes lithium salt dissociation. Propylene carbonate exhibits faster volume growth as manufacturers develop low-viscosity blends for next-generation fast-charging cell architectures, while solvent applications face margin compression from bio-based glycol ether substitutes.
EPA oversight of volatile organic compound emissions constrains solvent-grade formulations in North American industrial coatings, while REACH registration requirements in Europe enforce full toxicological dossiers for carbonate imports above one-tonne thresholds. China's GB standards for battery electrolyte purity, administered by SAMR, create de facto technical barriers for non-domestic suppliers serving domestic cell manufacturers. Stakeholders must monitor evolving F-Gas Regulation amendments in Europe and dual carbon policy implementation timelines in China to anticipate capacity relocation and formulation reformulation cycles.
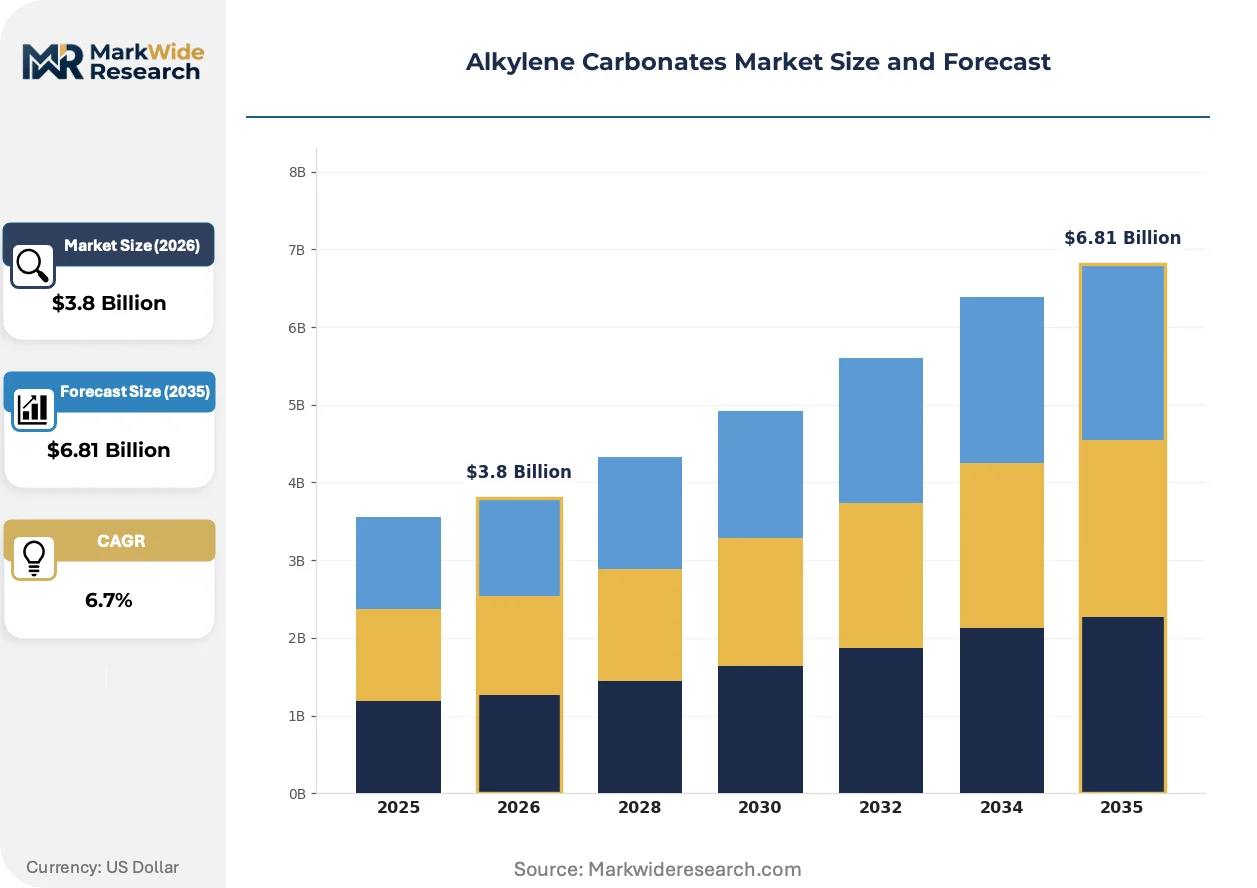
Market Dynamics
Carbon dioxide feedstock integration is restructuring competitive economics as producers with captured CO₂ streams achieve 15-20% cost advantages over merchant-oxide competitors. This supply-side bifurcation rewards integrated petrochemical complexes while stranding standalone alkylene oxide buyers.
Growth Catalysts
- Lithium-ion battery electrolyte demand:Electric vehicle manufacturers in China are scaling cylindrical and prismatic cell output, consuming electrolyte-grade ethylene carbonate at rates exceeding solvent applications. SAMR purity mandates are tightening specifications, locking in premium-grade demand.
- REACH registration completion:Full toxicological dossiers for propylene carbonate imports above one-tonne thresholds have cleared European market entry barriers for compliant suppliers, enabling formulation switches from N-methyl-2-pyrrolidone in industrial coatings.
- Fast-charging cell architectures:Low-viscosity electrolyte blends incorporating propylene carbonate are virtualizing thermal management requirements, allowing battery engineers to reduce cooling system mass in next-generation pack designs.
Market Restraints
- Propylene oxide supply concentration:Merchant oxide availability concentrates in coastal China and the US Gulf Coast, exposing non-integrated carbonate producers to feedstock disruption during ethylene glycol co-product demand spikes.
- Bio-based glycol ether substitution:Solvent-grade propylene carbonate faces displacement in paints and coatings by 2-methoxyethanol derivatives derived from lignocellulosic feedstocks, compressing margin in industrial applications.
- F-Gas Regulation phase-down:Europe's hydrofluorocarbon quota reductions are indirectly constraining carbon dioxide capture project financing, limiting feedstock availability for new carbonate capacity investments.
Strategic Opportunities
- India battery cell manufacturing:PLI scheme incentives for gigafactory construction are creating first-mover advantages for electrolyte-grade carbonate suppliers establishing technical service partnerships with domestic cell producers.
- Dual carbon policy alignment:China's 2030 peak carbon targets are accelerating carbon dioxide utilization project approvals, enabling carbonate producers to monetize captured emissions through certified low-carbon product premiums.
- Recycled content electrolytes:Closed-loop solvent recovery from end-of-life batteries is virtualizing virgin material requirements, creating circular economy service contracts with automotive OEMs pursuing Scope 3 reductions.
Industry Challenges
- Electrolyte-grade purification capex:Achieving battery-specification purity below 10 ppm water content requires molecular sieve investments exceeding $50 million per production train, stranding mid-scale producers in commodity solvent markets.
- Cross-border GB standard compliance:China's SAMR-administered testing protocols for chloride and iron content lack mutual recognition with IEC or ASTM methods, forcing duplicate certification timelines for export-oriented suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkylene Carbonates Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimethyl Carbonate, Ethylene Carbonate, Propylene Carbonate, Butylene Carbonate Application: Solvents, Electrolytes, Additives, Coatings End User: Automotive, Electronics, Pharmaceuticals, Agriculture Packaging Type: Bottles, Drums, Bulk Containers, Jerricans |
| Companies Covered | BASF, Mitsubishi Chemical Corporation, Huntsman International LLC, Ube Industries, The Chemours Company, Mitsui Chemicals, Dow Inc., SK Capital Partners, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkylene Carbonates Market Emerging Trajectories
Process intensification and digital twin deployment are compressing product development cycles while regulatory chemistry restrictions are forcing formulation redesign across solvent applications. These shifts favor capital-rich incumbents with integrated R&D infrastructure.
Supercritical carbon dioxide reaction systems are virtualizing traditional high-pressure autoclave operations, enabling continuous-flow carbonate synthesis with 40% energy reduction. BASF and Mitsubishi Chemical have piloted these units at Ludwigshafen and Yokkaichi respectively, targeting commercial scale by 2027. The technology is virtualizing batch-to-batch variability, allowing just-in-time electrolyte blending for battery manufacturers.
EPA's 2024 volatile organic compound emission standards for industrial maintenance coatings are restricting propylene carbonate content in solvent blends above 20% vapor pressure thresholds. Formulators are responding with ethylene carbonate co-solvent systems or switching to exempt oxygenated solvents. North American coatings producers face reformulation costs and qualification delays that favor incumbent suppliers with existing EPA premanufacture notifications.
Cell manufacturers are consolidating electrolyte procurement through long-term tolling agreements rather than merchant spot purchases. CATL and BYD have established dedicated carbonate offtake contracts with specified purity tiers and volume flex provisions. This concentration is most visible in China's Yangtze River Delta battery cluster, where three cell producers account for electrolyte-grade demand that would otherwise fragment across twenty solvent distributors.
Alkylene Carbonates Market Segmentation
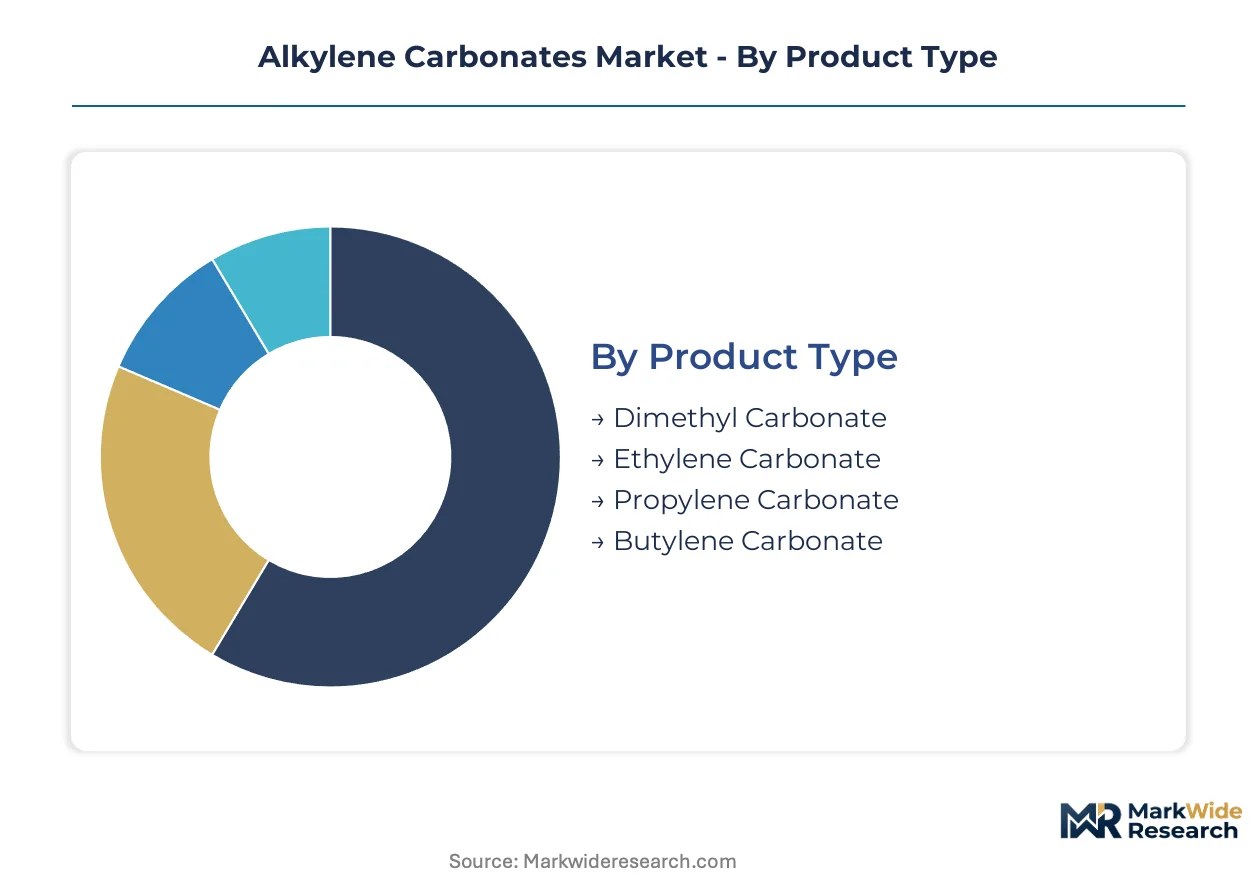
Alkylene carbonate producers face divergent service intensity demands across product grades, with electrolyte specifications requiring technical support teams stationed at battery plants while solvent applications tolerate standard distributor relationships. Segmentation strategy determines capital allocation between purification assets and logistics infrastructure.
Product Type:
After-sales service intensity varies sharply across carbonate chemistries, with electrolyte grades demanding on-site analytical support and solvent grades operating through merchant distributors.
- Ethylene Carbonate:High-purity cyclic carbonate with dielectric constants exceeding 90 and boiling points near 248°C serves as the primary lithium salt dissociation medium. Demand concentrates in China's Yangtze River Delta battery cluster where CATL and BYD operate gigafactories requiring water content below 10 ppm. SAMR purity mandates lock in premium-grade supply relationships with dedicated technical service contracts.
- Propylene Carbonate:Lower-viscosity cyclic carbonate enables fast-charging electrolyte formulations with reduced thermal management mass. Volume expansion centers on South Korean cell manufacturers developing cylindrical 4680 architectures. MEE carbon utilization certifications reward producers with captured CO₂ feedstock streams.
- Dimethyl Carbonate:Linear carbonate co-solvent reduces electrolyte viscosity and flash point in blended formulations. Paint stripping and methylation chemistry applications in European industrial coatings drive merchant demand.
- Butylene Carbonate:Higher molecular weight cyclic carbonate offers reduced volatility for specialty adhesive and sealant formulations. Niche demand from German automotive OEMs pursuing low-VOC interior materials.
By volume, ethylene carbonate leads. By growth pace, propylene carbonate is expanding most quickly.
Application:
Cost tier stratification separates commodity solvent sales from premium electrolyte contracts with indexed raw material pass-through clauses.
- Electrolytes:Battery-grade formulations combining ethylene carbonate, propylene carbonate, and lithium hexafluorophosphate dominate value capture. Chinese cell manufacturers consolidate procurement through tolling agreements with volume flex provisions rather than spot purchases.
- Solvents:Polar aprotic carrier applications in paint stripping, degreasing, and extraction face margin compression from bio-based glycol ether substitutes. EPA VOC emission thresholds restrict propylene carbonate content in North American industrial maintenance coatings.
- Additives:Lubricant and hydraulic fluid formulations exploit carbonate polarity for metal surface passivation. German automotive suppliers specify additive packages for electric vehicle thermal management fluids.
- Coatings:High-boiling coalescing agents in waterborne architectural paints. REACH registration completion for propylene carbonate enables formulation switches from N-methyl-2-pyrrolidone in European decorative coatings.
Electrolytes command the highest unit economics. Solvents maintain the broadest geographic footprint.
End User:
Customer type determines contract structure, with automotive OEMs demanding multi-year supply agreements and pharmaceutical buyers accepting quarterly price adjustments.
- Automotive:Electric vehicle battery pack producers consume electrolyte-grade carbonates at rates exceeding all other applications combined. Indian PLI scheme incentives for gigafactory construction create first-mover advantages for suppliers establishing technical partnerships with domestic cell producers.
- Electronics:Consumer device lithium-ion cells and capacitor electrolytes require ultra-high purity with metallic impurity specifications below 1 ppm. Japanese electronics manufacturers source through captive trading houses with integrated quality certification.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and extraction solvents. FDA drug master file requirements for excipient-grade carbonates limit qualified supplier pools.
- Agriculture:Pesticide formulation carriers and controlled-release fertilizer coatings. Brazilian agrochemical blenders specify propylene carbonate for glyphosate compatibility.
Automotive drives absolute volume. Electronics maintains the tightest purity specifications.
Packaging Type:
Supply concentration in coastal China and the US Gulf Coast shapes logistics economics, with bulk containers favored for integrated producers and drums serving merchant distributors.
- Bulk Containers:ISO tank containers and flexitanks for electrolyte-grade shipments to battery plants with dedicated unloading infrastructure. Yangtze River Delta ports handle the highest throughput.
- Drums:Standard 200-liter steel and polyethylene drums for solvent distributors serving fragmented industrial coatings customers. German chemical distributors maintain regional drum filling networks.
- Bottles:Laboratory and pilot-scale quantities for R&D electrolyte formulation work. South Korean battery material suppliers package in fluoropolymer-lined bottles to prevent moisture ingress.
- Jerricans:20-25 liter containers for pharmaceutical and electronics sampling programs. Swiss specialty chemical traders specialize in jerrican logistics for Alpine pharmaceutical clusters.
Bulk containers dominate tonnage moved. Bottles carry the highest margin per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in alkylene carbonates tilt heavily toward net-import positions in battery manufacturing hubs while integrated petrochemical complexes in feedstock-rich regions sustain export surpluses. This asymmetry shapes capacity investment decisions and tariff exposure across major economies.
China
CATL and BYD operate gigafactories in the Yangtze River Delta consuming electrolyte-grade ethylene carbonate at volumes exceeding domestic nameplate capacity. SAMR-administered GB standards for chloride and iron content below 1 ppm create technical barriers for non-domestic suppliers. Ningbo and Changzhou host the densest concentration of carbonate purification trains serving cell manufacturers.
Germany
BASF leverages integrated propylene oxide supply chains at Ludwigshafen to sustain cost advantages across European production hubs. REACH registration requirements for imports above one-tonne thresholds enforce full toxicological dossiers, favoring incumbent suppliers with existing compliance infrastructure. The country's national chemical regulator coordinates with ECHA on substance evaluation timelines affecting formulation switches from N-methyl-2-pyrrolidone.
United States
EPA oversight of volatile organic compound emissions constrains solvent-grade formulations in industrial coatings across the Gulf Coast petrochemical corridor. Huntsman International LLC competes via specialized additives formulations navigating divergent regional purity standards. Merchant propylene oxide availability concentrates near Houston, exposing non-integrated carbonate producers to feedstock disruption during ethylene glycol co-product demand spikes.
Japan
Mitsubishi Chemical Corporation anchors its position through captive electrolyte-grade ethylene carbonate output serving battery manufacturers in the Kansai and Chubu industrial zones. METI guidance on carbon dioxide utilization project approvals accelerates captured emissions monetization through certified low-carbon product premiums. Yokkaichi hosts pilot supercritical carbon dioxide reaction systems targeting commercial scale deployment.
South Korea
Cell manufacturers developing cylindrical 4680 architectures drive propylene carbonate demand for low-viscosity fast-charging electrolyte blends in the Busan-Ulsan industrial complex. MFDS alignment with international battery material standards reduces duplicate certification burdens for electrolyte-grade imports. Seoul Capital Area trading houses coordinate quality certification for ultra-high purity electronics-grade shipments.
Alkylene Carbonates Market Vendor Landscape
On the supply side, the industry is consolidating around integrated petrochemical complexes with captive carbon dioxide feedstock streams while standalone alkylene oxide buyers face stranded positions. Three strategic archetypes dominate: integrated chemical conglomerates with backward control over epoxide supply, specialized carbonate purifiers serving battery-grade specifications, and diversified solvent distributors navigating regulatory compliance across coatings applications. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term tolling agreements rather than merchant spot sales.
Among integrated chemical conglomerates, BASF and Mitsubishi Chemical Corporation exemplify archetypes leveraging captive feedstock positions and integrated R&D infrastructure. Huntsman International LLC occupies a specialist position navigating divergent regional purity standards through formulation expertise. These three entities represent distinct competitive vectors: scale-driven integration, technical-grade purification, and regulatory compliance specialization.
| Leading Market Players |
|---|
| BASF |
| Mitsubishi Chemical Corporation |
| Huntsman International LLC |
| Ube Industries |
| The Chemours Company |
| Mitsui Chemicals |
| Dow Inc. |
| SK Capital Partners |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Propylene oxide supply concentration in coastal China and the US Gulf Coast determines both electrolyte-grade premium spreads and the geographic shape of carbonate logistics networks. SAMR purity mandates and EPA VOC thresholds create divergent certification cost burdens that stratify pricing tiers while rewarding integrated producers with captive feedstock streams.
Pricing Analysis
Industrial OEM buyers anchor contract structures across the Alkylene Carbonates Market through long-term tolling agreements with volume flex provisions rather than spot transactions. Three-tier pricing structure across battery-grade, industrial-grade, and solvent-grade levels separates electrolyte specifications commanding technical service premiums from commodity solvent volumes facing bio-based glycol ether substitution. Pricing pressure stems from merchant oxide availability constraints during ethylene glycol co-product demand spikes. Solvent distributors exhibit highest price sensitivity due to margin compression from lignocellulosic substitutes, while automotive cell manufacturers accept indexed raw material pass-through clauses for guaranteed purity tiers.
Supply Chain Analysis
Export-control restrictions on supercritical carbon dioxide reaction technology limit capacity expansion equipment flows to non-domestic producers. Manufacturing gravity centers on China, Germany, and Japan, with purification trains clustering in the Yangtze River Delta, Ludwigshafen, and Yokkaichi. Feedstock draws from captured carbon dioxide streams and merchant alkylene oxide supply, with non-integrated producers exposed to single-source vulnerability during petrochemical complex maintenance cycles. Distribution runs through dedicated bulk container logistics for electrolyte-grade shipments and regional drum networks for solvent applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alkylene Carbonates Market sits at an early-cycle expansion phase justified by accelerating gigafactory construction in India under PLI scheme incentives. Penetration of fast-charging cell architectures is creating first-mover windows for low-viscosity electrolyte formulations before standardization consolidates procurement.
For Market Incumbents: Harden electrolyte-grade purification assets against chloride and iron content specifications tightening under SAMR protocols. Lock in backward integration into propylene oxide supply through coastal China or US Gulf Coast capacity additions to defend margin position against merchant feedstock volatility. Secure dedicated technical service contracts with CATL and BYD before tolling agreement templates standardize across the Yangtze River Delta.
For New Entrants and Emerging Players: Build out carbon dioxide utilization project capabilities aligned with China's dual carbon policy certification pathways to capture low-carbon product premiums. Target India's nascent battery cell manufacturing cluster through technical partnership proposals with PLI-qualified gigafactory developers before incumbent service teams establish presence. Lead with recycled content electrolyte offerings closed-loop solvent recovery contracts to differentiate from virgin material suppliers.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated petrochemical conglomerates with captive feedstock and purification infrastructure. Long-term viability hinges on positioning for electrolyte-grade specification consolidation rather than solvent commodity exposure. Watch for MEE carbon utilization certification acceleration as the signal indicating which captured CO₂ projects will secure offtake priority from cell manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Integrated complexes at Ludwigshafen and Yokkaichi achieve 15-20% cost advantages over merchant-oxide competitors. |
| Electrolyte-Grade Purification Capacity Expansion | Molecular sieve investments exceeding $50 million per train lock in premium-tier supply relationships with SAMR-compliant specifications. |
| Carbon Dioxide Utilization Certification | MEE low-carbon product premiums monetize captured emissions through dual carbon policy alignment in China. |
| Long-term Tolling Agreement Structuring | CATL and BYD procurement consolidation favors suppliers with volume flex provisions over spot market participants. |
| Closed-Loop Solvent Recovery Service Contracts | Circular economy offerings with automotive OEMs pursuing Scope 3 reductions virtualize virgin material requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from carbonate plant managers, procurement leads at battery cell manufacturers, electrolyte formulation engineers, and distribution channel partners and refined through secondary validation against customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and SAMR regulatory disclosures. Bottom-up capacity assessments across purification train installations were triangulated with top-down demand modeling from electric vehicle production forecasts and electrolyte blend ratio specifications.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across product grade tier, end-use application, packaging format, and regional production hub. CAGRs were derived from installed capacity utilization rates and electrolyte-grade specification adoption curves. Industry-specific forecast inputs included SAMR purity mandate implementation timelines and F-Gas Regulation phase-down effects on carbon dioxide capture project financing availability.
Stress conditions across propylene oxide supply disruption, bio-based solvent substitution acceleration, and REACH registration timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding gigafactory construction pace and electrolyte chemistry standardization. Material shifts in China's dual carbon policy enforcement or EPA VOC threshold revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Sialic Acid Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Panthenol Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Middle East and Africa Polyvinylpyrrolidone (PVP) Market
Specialty Chemicals
Cellulose Derivatives Market