
 Global Acrylic Processing Aid Market | 2026-2036
Global Acrylic Processing Aid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Processing Aid Market Intelligence
The adoption of high-molecular-weight acrylic processing aids for enhanced PVC fusion and melt strength is reorganizing material selection criteria in plastic modification. Arkema specializes in developing specialty additives for complex polymer systems, targeting high-margin applications. Kaneka Corporation leverages its extensive polymer science expertise to offer solutions for rigid and flexible PVC applications. Dow Chemical Company sustains a broad portfolio catering to large-volume construction and packaging end-users.
Acrylic processing aids are acrylic-based polymers used as additives to improve the processing characteristics of other polymers, primarily PVC. These additives function by accelerating fusion, increasing melt strength, and enhancing the homogeneity of the polymer melt. The plastic modifiers application segment constitutes the largest share of consumption, driven by demand from the PVC pipe and profile industry. Within deployment modes, water-based systems are gaining traction over solvent-based systems due to stricter environmental regulations on VOC emissions.
Regulatory frameworks such as the EU's REACH and the US EPA's rules on volatile organic compounds directly influence product formulation. In China, compliance with GB standards for building materials and packaging is mandatory for market access. These regulations compel manufacturers to innovate toward safer and more environmentally benign additive chemistries. Consequently, navigating the fragmented landscape of regional chemical control laws remains a critical competency for suppliers.
Market Dynamics
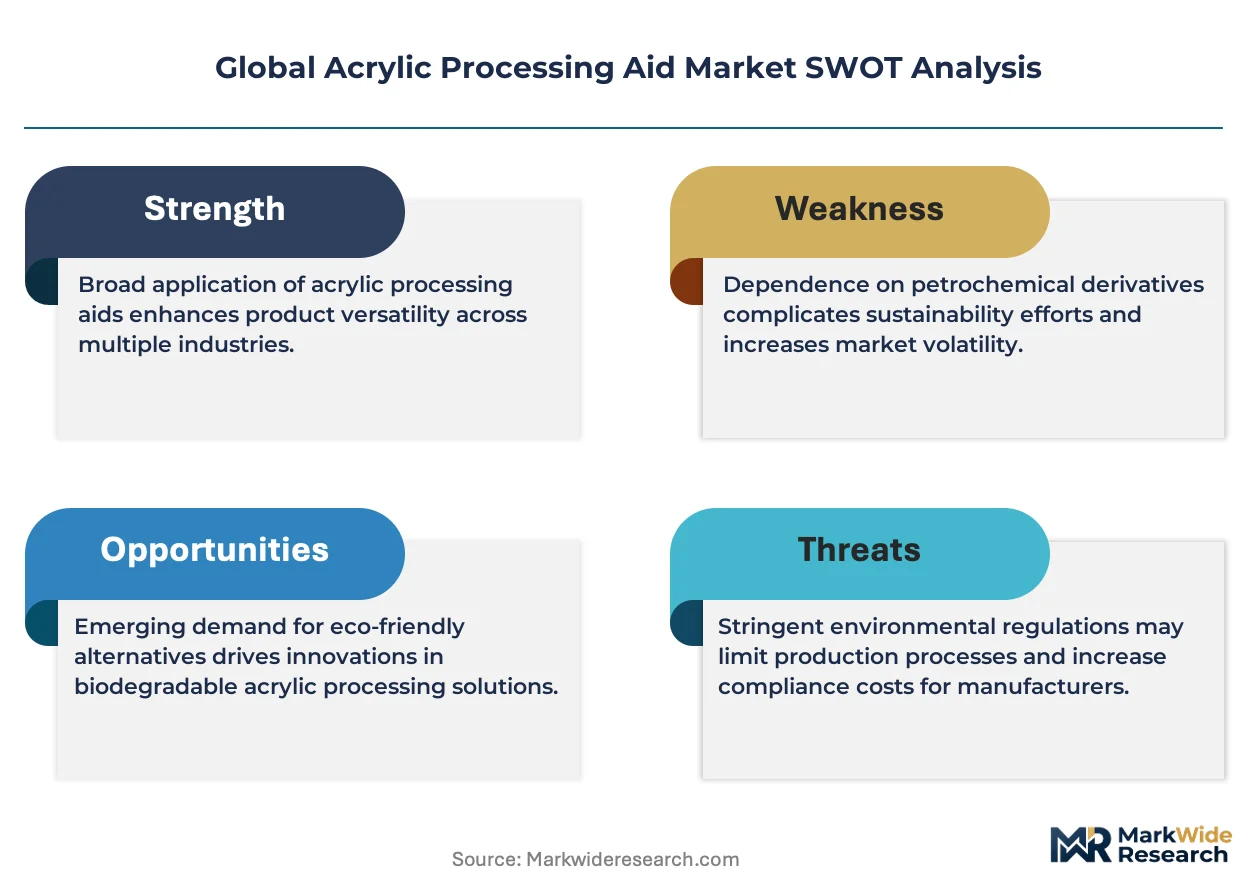
The market's central dynamic is the tension between the construction industry's demand for high-performance PVC modification and intensifying global environmental regulations. This forces additive manufacturers to innovate formulations that enhance melt strength and fusion without increasing volatile organic compound emissions.
Growth Catalysts
- Low-VOC Formulations:Environmental standards, including the EU's REACH framework and US EPA rules, are accelerating the transition from solvent-based to water-based systems, creating demand for compliant acrylic processing aids in paints and coatings.
- Construction Sector Expansion:Sustained activity in the building and construction industry, particularly for PVC pipes, window profiles, and siding, drives volume consumption of processing aids to improve extrusion and molding efficiency.
- Demand Concentration in China:China's vast manufacturing and construction base acts as a primary consumption hub, with mandatory compliance to national GB standards for building materials solidifying demand for qualified additives.
Market Restraints
- Petrochemical Feedstock Volatility:Prices for key raw materials like methyl methacrylate, derived from crude oil, are subject to significant fluctuations, directly impacting the production cost and margin stability for acrylic processing aid manufacturers.
- Substitution from Alternative Polymers:In certain non-critical applications, compounders may opt for lower-cost processing solutions or alternative polymers like chlorinated polyethylene (CPE) that reduce the required loading levels of acrylic aids, capping market penetration.
- Fragmented Regulatory Landscape:Navigating the complex and divergent chemical control laws, such as REACH in Europe, TSCA in the US, and various GB standards in China, increases compliance costs and can delay market entry for new products.
Strategic Opportunities
- Additives for Recycled Content:Developing specialized acrylic processing aids tailored for recycled PVC (rPVC) streams presents a significant opportunity, as these materials have inconsistent melt behavior and require advanced modification to ensure quality.
- Single-Pack Additive Systems:Offering "one-pack" solutions that combine processing aids with other additives like stabilizers, lubricants, and impact modifiers simplifies procurement and production for PVC converters, creating value beyond component supply.
- Bio-based Polymer Modification:The emergence of bio-based polymers like PLA creates a new frontier for processing aid development, requiring novel chemistries to improve their melt strength and processability for applications in packaging and consumer goods.
Industry Challenges
- Lengthy Product Qualification Cycles:Gaining approval from large PVC compounders and extruders is a time-intensive process, often requiring extensive testing and trial runs that can delay revenue generation from new formulations.
- Formulation Expertise Scarcity:Customizing acrylic processing aids for specific applications and polymer grades demands a high level of technical expertise in polymer science, a skill set that remains a critical and often scarce resource for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Processing Aid Market |
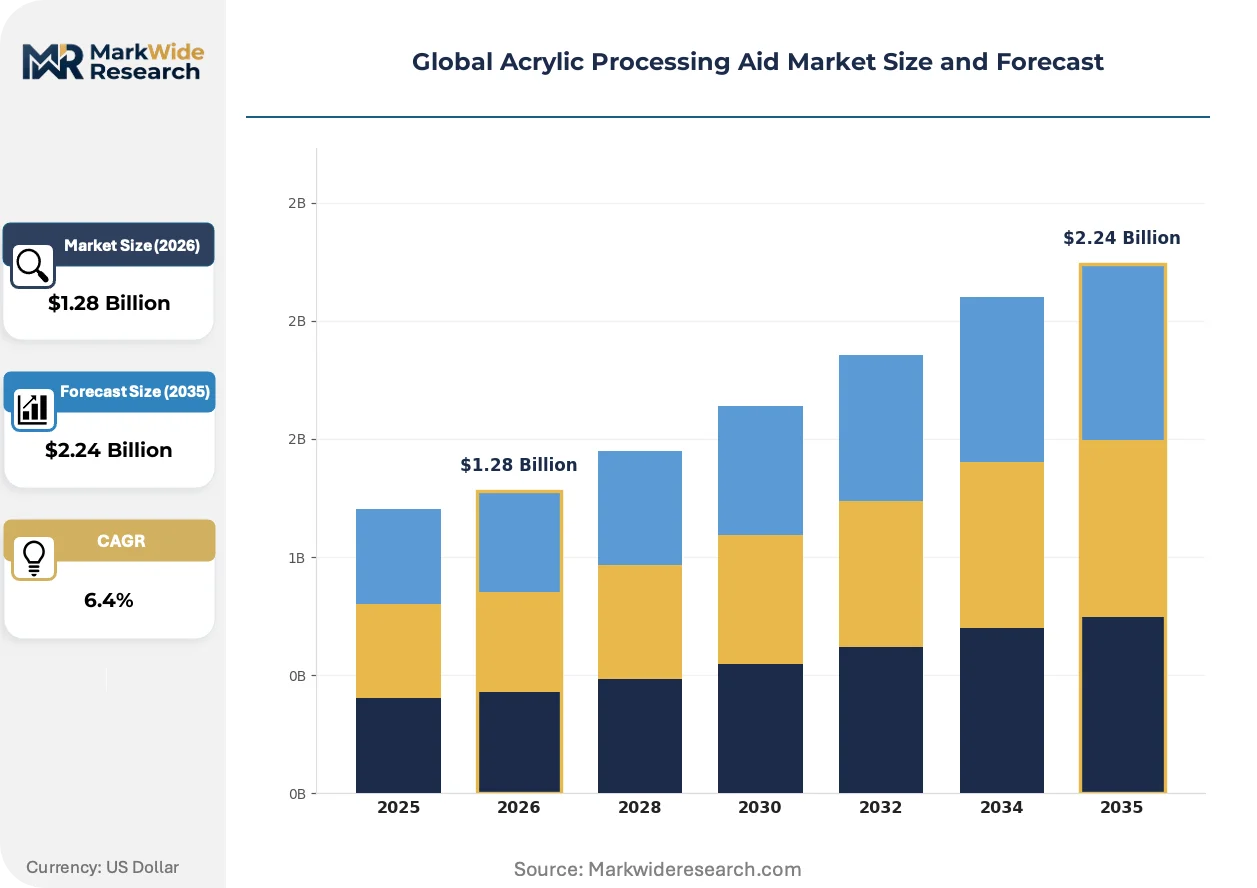
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Emulsions, Acrylic Copolymers, Coatings Additives, Dispersion Aids, Film Formers Application: Paints & Coatings, Adhesives, Sealants, Construction Chemicals, Plastic Modifiers End User Industry: Automotive OEMs, Packaging Manufacturers, Textile Producers, Electronics Fabricators, Consumer Goods Makers Deployment Mode: Water-based Systems, Solvent-based Systems, Powder Coatings, UV Curable, Thermal Curing |
| Companies Covered | Dow Chemical Company, BASF, LG Chem, Akdeniz Chemson, Shandong Ruifeng Chemical Co. Ltd., Kaneka Corporation, Mitsubishi Chemical Corporation, Novista Group, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Processing Aid Market Strategic Shifts & Innovations
Innovation in the acrylic processing aid market is defined by the pursuit of enhanced PVC processability within the tightening constraints of environmental health and safety regulations. Material science advancements focus on creating more efficient additives that deliver superior performance at lower concentrations.
High-molecular-weight acrylic processing aids are advanced polymers designed to drastically improve the fusion, melt elasticity, and surface finish of PVC compounds. Rigid PVC manufacturers, especially in the pipe and profile sectors, are adopting these grades to achieve faster extrusion speeds and reduce defect rates. This technology is displacing less efficient, general-purpose aids, particularly in high-performance applications where process stability is critical.
The European Union's REACH regulation continues to shape product development by requiring comprehensive data on chemical safety and environmental impact. This mandate compels manufacturers to reformulate products, phasing out substances of very high concern and investing in safer alternatives. Water-based systems and solid-grade additives are gaining traction as producers innovate to meet these stringent compliance demands without compromising performance.
A notable shift in customer behavior is the move toward performance-based specifications rather than purely chemical-based purchasing. PVC converters are increasingly providing suppliers with target outcomes, such as a specific melt strength or surface gloss, and relying on the additive supplier's expertise to deliver a customized solution. This trend is most prominent in the European automotive and North American building materials sectors.
Global Acrylic Processing Aid Market Segmentation
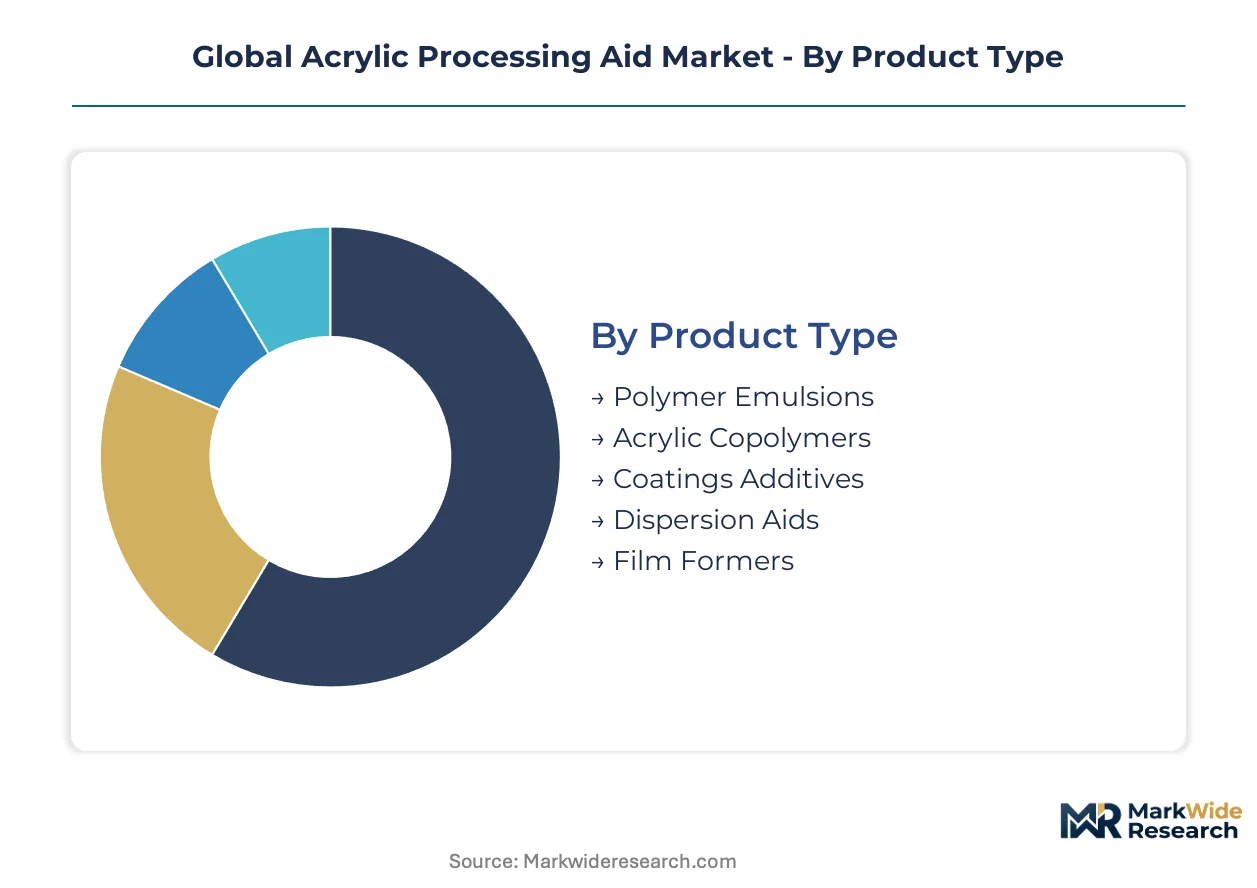
The global acrylic processing aid market's intricate structure reflects diverse chemical compositions and varied end-use requirements. Understanding this segmentation is critical for suppliers to tailor product development and market strategies effectively. Each segment represents distinct performance needs and regulatory compliance challenges across numerous industrial applications.
Product Type:
Margin pools within product types often concentrate in advanced formulations that offer superior performance under stringent environmental regulations.
- Polymer Emulsions:These aqueous dispersions of acrylic polymers provide excellent film formation and adhesion, crucial for water-based paints and coatings. Demand is high in architectural coatings, driven by strict VOC emission standards in Europe.
- Acrylic Copolymers:Composed of multiple acrylic monomers, these materials offer customizable properties like flexibility or chemical resistance. Their adoption is significant in high-performance adhesives for automotive and construction applications.
- Coatings Additives:Specialized acrylic processing aids improve flow, leveling, and pigment dispersion in various coating formulations.
- Dispersion Aids:Acrylic dispersion aids stabilize pigment particles, preventing agglomeration and ensuring uniform color development.
- Film Formers:Acrylic film formers create durable, protective, and aesthetically pleasing layers on surfaces.
The dominant share belongs to Polymer Emulsions, while Acrylic Copolymers represent the fastest-growing trajectory due to their versatile performance profiles.
Application:
Application segments focus on specific performance outcomes, driving the selection of acrylic processing aids optimized for distinct material interactions.
- Plastic Modifiers:Acrylic processing aids enhance PVC processability, improving melt strength, fusion characteristics, and surface finish for pipes and profiles. The PVC pipe industry in China drives substantial volume consumption.
- Paints & Coatings:These additives improve rheology, adhesion, and durability in various paint and coating formulations, supporting the shift to low-VOC systems. US EPA and EU REACH influence product development.
- Adhesives:Acrylic processing aids enhance the tack, peel strength, and overall cohesion of adhesive formulations for packaging.
- Sealants:These additives improve flexibility, durability, and weather resistance of sealant products for building envelopes.
- Construction Chemicals:Acrylic processing aids integrate into concrete admixtures, flooring compounds, and waterproofing agents to enhance performance.
Plastic Modifiers command the largest segment, with Construction Chemicals expanding most quickly due to infrastructure development.
End User Industry:
End user industries segment the market by customer type and their specific quality requirements, influencing additive formulation and supply chain dynamics.
- Automotive OEMs:Acrylic processing aids are critical for interior and exterior components, enhancing durability and aesthetic finish of plastics in vehicles. Specifications from manufacturers in Germany dictate performance.
- Packaging Manufacturers:These companies utilize acrylic processing aids to improve clarity, impact resistance, and barrier properties of plastic films. Demand from food packaging in North America remains high.
- Textile Producers:Acrylic processing aids improve hand feel, durability, and printability of fabrics, especially synthetic fibers.
- Electronics Fabricators:Manufacturers use acrylic additives in housings and components for flame retardancy and improved processing of engineering plastics.
- Consumer Goods Makers:Acrylic processing aids enhance appearance, haptics, and longevity of household items and personal care packaging.
Packaging Manufacturers hold a significant share, and Consumer Goods Makers are experiencing rapid growth driven by product innovation.
Deployment Mode:
Deployment modes are differentiated by their environmental compliance and operational efficiency, significantly impacting formulation choices for manufacturers.
- Water-based Systems:These systems use water as the primary solvent, drastically reducing VOC emissions and aligning with stringent environmental regulations like the EU's Industrial Emissions Directive. Adoption accelerates in coatings across Europe.
- Solvent-based Systems:Historically dominant, these systems employ organic solvents, offering excellent wetting and fast drying. They face increasing regulatory pressure due to VOC content.
- Powder Coatings:Applied as a dry powder, these systems offer durable finishes with zero VOCs, used in industrial applications.
- UV Curable:These systems cure rapidly under ultraviolet light, enabling high-speed production and offering energy efficiency without solvent emissions.
- Thermal Curing:Acrylic processing aids in thermal curing systems activate upon heat application, forming robust films for protective purposes.
Water-based Systems lead the market, while UV Curable technologies are gaining share fastest due to rapid processing benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of acrylic processing aid manufacturing in specific regions significantly influences global supply dynamics. This geographic distribution impacts raw material sourcing, production costs, and logistical efficiencies for downstream industries. Key production hubs often align with major consumption markets, streamlining the value chain.
China
China's extensive construction and manufacturing sectors drive substantial demand for acrylic processing aids, particularly in PVC pipe and profile production. Compliance with GB standards for building materials ensures quality and safety across the market. The Yangtze River Delta region, a major industrial hub, concentrates much of this consumption and production activity.
United States
The United States market sees strong demand from construction and packaging industries for high-performance acrylic processing aids. US EPA regulations on VOC emissions push manufacturers towards water-based and low-VOC formulations. Chemical complexes along the Gulf Coast remain critical for both raw material supply and finished product manufacturing.
Germany
Germany's advanced manufacturing sector, especially in automotive and specialty chemicals, requires sophisticated acrylic processing aids. The EU's REACH framework mandates rigorous safety and environmental compliance for all chemical products. The Rhineland region, a traditional chemical industry stronghold, continues to be a hub for additive innovation.
India
India's rapid urbanization and infrastructure development fuel significant demand for acrylic processing aids in construction chemicals. BIS standards for building materials ensure quality and safety in diverse applications. Major metropolitan areas like Mumbai and Delhi-NCR represent concentrated consumption points for these essential additives.
Japan
Japan's automotive and electronics sectors demand high-performance acrylic processing aids for precision plastic modification. METI guidelines encourage innovation in environmentally benign additive chemistries. Major industrial centers in the Tokyo and Osaka metropolitan areas drive specialized product development and consumption.
Global Acrylic Processing Aid Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global acrylic processing aid market. The market exhibits a tiered structure, with a few large integrated chemical companies at the top and numerous specialized manufacturers. Strategic archetypes include global diversified chemical giants, regional specialists, and niche innovators. Competitive moves frequently involve geographic expansion and portfolio diversification to capture new end-use applications.
On the premium-tier vector, Dow Chemical Company and Arkema exemplify global chemical leaders offering a broad range of high-performance processing aids. These entities leverage extensive R&D capabilities and global distribution networks to serve diverse end-user industries worldwide with advanced solutions. Shandong Ruifeng Chemical Co. Ltd., a China-based entity, sits within the cohort of regional specialists, focusing on the specific demands of the Asian market, particularly for PVC modification and adherence to local standards. These players collectively anchor different segments of the market, from high-volume general-purpose to niche high-performance applications, demonstrating varied strategic approaches.
| Leading Market Players |
|---|
| Dow Chemical Company |
| BASF |
| LG Chem |
| Akdeniz Chemson |
| Shandong Ruifeng Chemical Co. Ltd. |
| Kaneka Corporation |
| Mitsubishi Chemical Corporation |
| Novista Group |
| Arkema |
| Others |
Cost & Logistics Intelligence
EU REACH framework significantly gates supply qualification for acrylic processing aids, simultaneously influencing price differentiation for compliant, high-performance formulations. Compliance costs and performance demands shape both market access and premium pricing across European markets.
Pricing Analysis
EU REACH dictates the pricing tier structure for acrylic processing aids, favoring specialized, compliant formulations. The dominant pricing model is contract-based long-term offtake for large volume buyers, with value-based pricing for niche, high-performance applications. Price differentiation stems from certification level, particularly for low-VOC products, and customization for specific polymer grades. Pricing softness reflects petrochemical feedstock volatility, impacting margins for standard-grade products, making packaging manufacturers highly price-sensitive compared to automotive OEMs.
Supply Chain Analysis
Container availability and rising freight costs across key Asian-European trade lanes impact the inbound logistics for acrylic processing aid manufacturers. Geographic supply concentration primarily rests in China and the United States, with Germany also contributing specialized products. Raw material dependencies center on methyl methacrylate and other petrochemical derivatives. Commodity price volatility for crude oil represents a significant structural risk for production costs. Distribution runs through a network of specialized chemical distributors and direct sales channels to large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic processing aid market is experiencing a significant shift in buyer power, driven by the consolidation of large PVC compounders and extrusion firms. These larger entities increasingly dictate performance specifications and pricing terms.
For Market Incumbents:Consolidate market position by deepening vertical integration into key raw material supply chains to mitigate petrochemical feedstock volatility. Invest in advanced R&D for bio-based polymer modification to counter substitution from alternative polymers. Expand manufacturing capacity in high-demand regions like the Yangtze River Delta to capture volume growth. Offer single-pack additive systems to simplify procurement for PVC converters, addressing the lengthy product qualification cycles.
For New Entrants and Emerging Players:Customization expertise scarcity represents a significant service-layer gap where incumbents under-serve specific application needs. Target the recycled PVC (rPVC) modification segment in Europe, which requires specialized processing aids due to inconsistent melt behavior. Develop agile, performance-based solutions for smaller, innovative compounders seeking rapid product qualification. Leverage digital platforms for streamlined technical support and accelerated market entry.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across specialty additive manufacturing, driven by the need for advanced production technologies for low-VOC formulations. Long-term viability remains strong, particularly for firms developing high-performance aids for construction chemicals. Acquire mid-sized regional specialists with strong R&D capabilities in water-based systems and bio-based chemistries. Watch for increased M&A activity among firms with proprietary formulation expertise as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production volume for high-demand regions like China, securing market share in PVC applications. |
| Green Manufacturing Transition | Aligns with EU REACH and US EPA regulations, reducing environmental impact and enhancing product marketability. |
| Product Launch (Single-Pack Systems) | Simplifies procurement and application for PVC converters, adding value beyond component supply. |
| R&D Investment (Bio-based Chemistries) | Develops novel solutions for emerging bio-based polymers, opening new application frontiers. |
| Acquisition of Specialist Firm | Gains proprietary formulation expertise and accelerates market entry into niche high-performance segments. |
Research Approach
Initial hypotheses were tested against primary input from technical R&D directors, procurement leads at downstream OEMs, distribution channel partners, and plant managers. This involved combining qualitative insights from industry stakeholders with quantitative validation from secondary sources. Secondary data included customs/trade data, ACC/Cefic reports, and SEC 10-K filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Variance decomposition guided the analytical framework, isolating the impact of market drivers and restraints on future growth across the analysis window. The model segmented the market by grade tier, end-use industry, deployment mode, and regional production hub. Compound Annual Growth Rates were derived from historical trends and projected demand shifts. Key forecast inputs included construction spending forecasts and regulatory compliance timelines.
Forecasts assume regulatory continuity in EU REACH and US EPA guidelines; material policy shifts would require re-modeling. Geopolitical events impacting petrochemical supply chains and unexpected technological breakthroughs represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Bismaleimide Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Sophorolipids Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Multimodal Chromatography Columns Market