
 United States Adult Diaper Market | 2026-2036
United States Adult Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
United States Adult Diaper Market Intelligence
The split between premium and commodity tiers is shifting as absorbency performance, skin-sensitivity formulations, and discreet design become the concrete dividing lines. Kimberly-Clark Corporation leverages its North American manufacturing footprint to sustain reliable pharmacy and retail shelf presence. First Quality Enterprises, LLC anchors its position through private-label partnerships with major medical supply distributors. Ontex competes by specializing in European-engineered superabsorbent polymer platforms adapted for US sizing standards.
Adult diapers constitute absorbent hygiene garments engineered with superabsorbent polymers, acquisition distribution layers, and breathable backsheet films to manage moderate-to-heavy urinary and fecal incontinence in non-infant populations. These products typically achieve fluid retention capacities of 800–3500 mL depending on construction grade, with thermal-bonded or spunbond-meltblown-spunbond nonwoven topsheets determining skin dryness performance. Disposable formats lead volume throughput due to institutional preference for infection control and reduced laundering burden, while reusable cotton and bamboo constructions capture margin pools among environmentally conscious home caregivers. Pull-up designs represent the fastest-growing type segment as mobility-enabled seniors reject tape-tab stigma in favor of underwear-like aesthetics.
The FDA regulates adult absorbent products marketed with therapeutic claims as medical devices under 21 CFR 876.5900, while the EPA oversees flushability and wastewater impact standards for certain disposal formats. OSHA's bloodborne pathogen standards indirectly shape institutional purchasing protocols for staff-handled incontinence care in skilled nursing facilities. Stakeholders must monitor how CMS reimbursement rate adjustments and state-level Medicaid managed care contract structures alter channel economics between retail, home delivery, and direct institutional supply.
Market Dynamics
Medicare Advantage expansion into incontinence benefits is restructuring procurement channels, pulling volume from retail pharmacies toward institutional home healthcare networks and specialized medical distributors serving Florida, California, and Texas.
Growth Catalysts
- Demographic Concentration:Senior population density in Florida, California, and Texas creates localized demand clusters that justify dedicated distribution infrastructure and specialized product formulations.
- CMS Reimbursement Expansion:Medicare Advantage plans broadening incontinence supply coverage convert out-of-pocket retail purchases into reimbursable medical expenses, unlocking institutional procurement scale.
- Superabsorbent Polymer Advances:European-engineered SAP platforms adapted to US sizing standards enable thinner cores with higher retention capacity, reducing bulk stigma while maintaining clinical performance.
Market Restraints
- Petrochemical Input Volatility:Polypropylene and polyethylene resin prices tied to crude oil fluctuations compress margin predictability for breathable backsheet film production.
- FDA Medical Device Classification:Products marketed with therapeutic claims fall under 21 CFR 876.5900, imposing labeling burdens and extended approval timelines that deter rapid product iteration.
- Reusable Substitute Competition:Cotton and bamboo cloth alternatives capture environmentally conscious home caregivers, fragmenting volume away from disposable formats in certain demographic segments.
Strategic Opportunities
- Bariatric Format Underpenetration:Texas and Florida skilled nursing facilities show rising demand for extended-size products that current retail assortments inadequately serve.
- Pull-Up Aesthetic Convergence:Mobility-enabled seniors rejecting tape-tab stigma create white space for underwear-like designs with premium positioning in pharmacy channels.
- Home Healthcare Channel Expansion:Direct institutional supply relationships bypass retail markup structures while capturing recurring subscription volume from agency procurement.
Industry Challenges
- OSHA Compliance Integration:Bloodborne pathogen standards in skilled nursing facilities require staff training protocols and disposal infrastructure that raise operational overhead.
- State Medicaid Contract Fragmentation:Managed care contract structures vary across California, Texas, and Florida, forcing manufacturers to maintain multiple pricing and eligibility systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Adult Diaper Market |
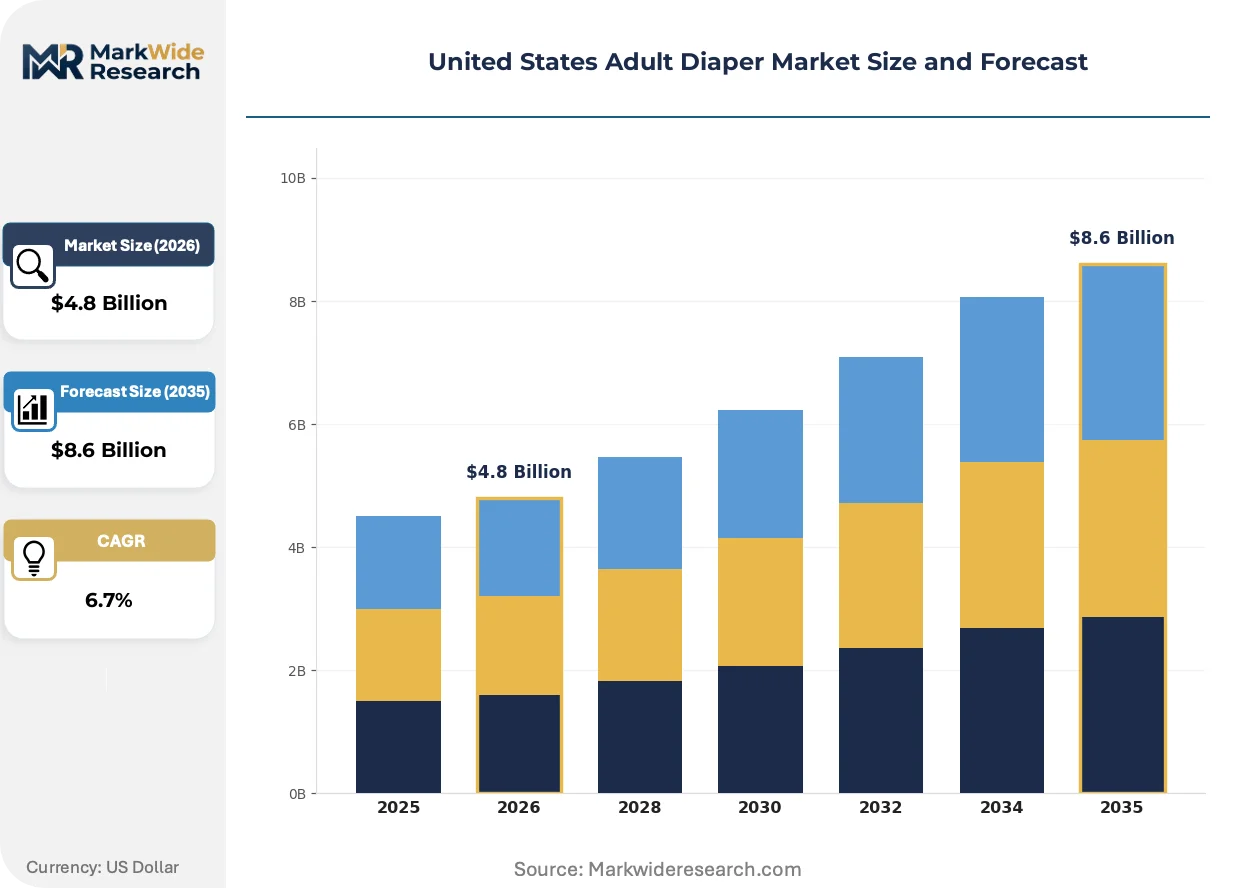
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Disposable, Reusable, Bariatric, Pull-Up Material: Polymer, Cotton, Superabsorbent, Bamboo End User: Seniors, Patients, Disabled Individuals, Caregivers Distribution Channel: Online, Pharmacies, Supermarkets, Medical Supply Stores |
| Companies Covered | First Quality Enterprises, LLC, Ontex, Kimberly-Clark Corporation, Attends Healthcare Products, Inc., Principle Business Enterprises, Inc., Procter & Gamble Company, Drylock Technologies, TZMO Group, Essity AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Adult Diaper Market Strategic Shifts & Innovations
Product differentiation is migrating from absorbency claims toward skin-sensitivity formulations and discreet industrial design, while regulatory labeling requirements and reimbursement pathway complexity reshape competitive positioning.
Superabsorbent polymer platforms with optimized cross-linking density are absorbing fluid volumes previously requiring substantially thicker core constructions. Home healthcare agencies in Florida and Texas are adopting these advanced cores at accelerated pace to reduce per-change labor burden. The technology is absorbing market share from conventional pulp-based constructions by enabling thinner profiles that maintain clinical performance standards.
FDA's medical device classification under 21 CFR 876.5900 imposes therapeutic claim restrictions that limit marketing language for products seeking reimbursement eligibility. Manufacturers must navigate dual pathways: general wellness positioning for retail shelves versus clinical labeling for institutional procurement. Pull-up formats targeting Medicare Advantage beneficiaries face the most stringent documentation requirements, compressing time-to-market for design innovations.
Agency procurement directors are consolidating supplier relationships around distributors offering inventory management and staff training support. Retail pharmacy volume in California and Florida is fragmenting as home healthcare networks capture recurring orders through direct institutional contracts. The shift is most visible in Texas, where rural senior populations depend on agency-delivered supplies rather than retail access.
United States Adult Diaper Market Segmentation
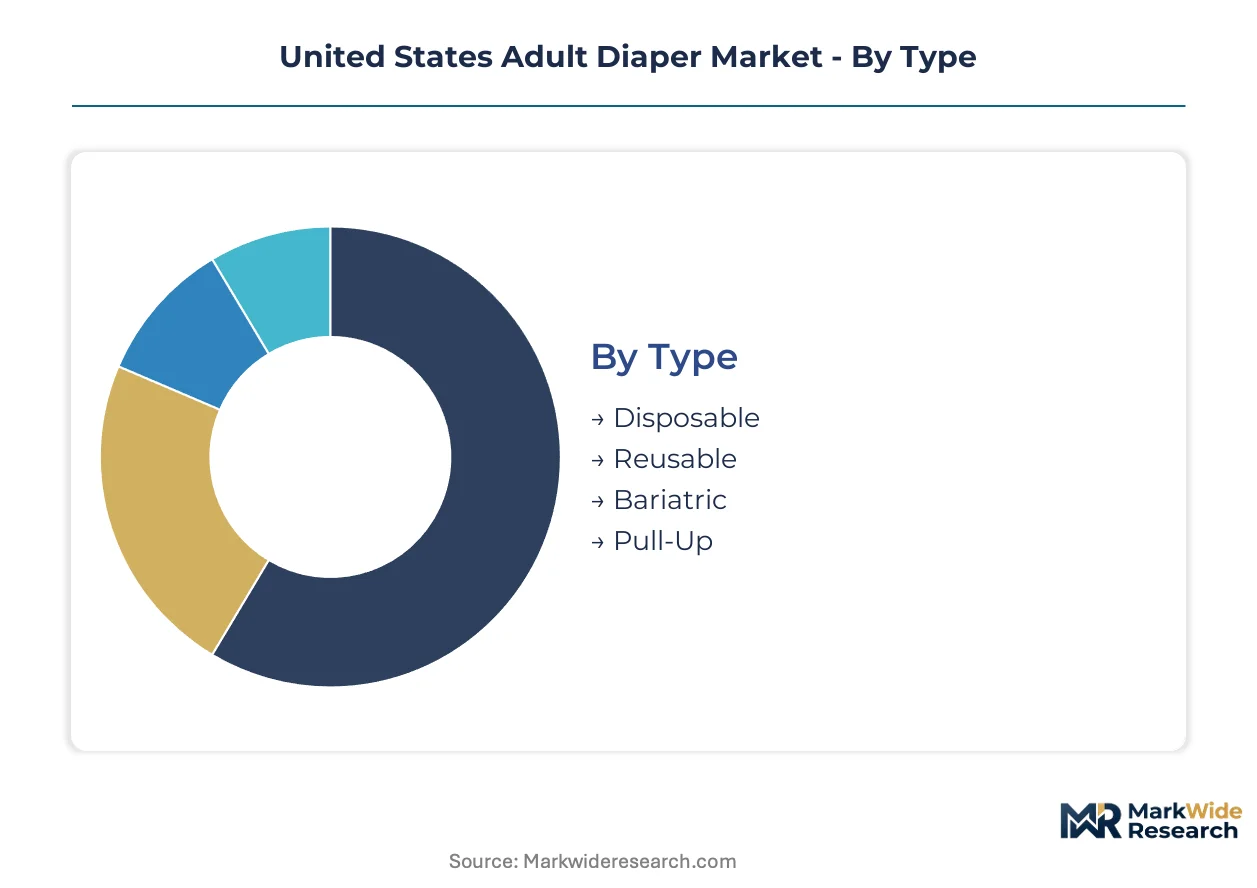
Adult diaper segmentation in the United States tracks how procurement channels, material science, and user mobility status fragment demand across distinct product architectures. Manufacturers align production lines to these divisions because reimbursement pathways and caregiver workflows differ materially by segment.
Type:
Supply concentration in disposable formats dominates manufacturing capacity allocation, with polymer supply chains anchored to Gulf Coast petrochemical infrastructure.
- Disposable:Polypropylene nonwoven topsheets bonded to polyethylene breathable backsheets form the construction standard. Florida home healthcare agencies and Texas skilled nursing facilities drive volume concentration as Medicare Advantage incontinence benefits convert retail purchases to institutional procurement.
- Pull-Up:Spandex-reinforced waistbands and standing leg cuffs replicate underwear aesthetics while maintaining 1500-2500 mL retention capacity. California's mobility-enabled senior population rejects tape-tab stigma fastest, pulling pharmacy channel assortment toward this format.
- Reusable:Cotton and bamboo multi-layer constructions with waterproof PUL barriers target environmentally conscious home caregivers in urban California markets.
- Bariatric:Extended waist circumference specifications (60-80 inches) with reinforced fastening systems address underserved demand in Texas and Florida long-term care.
Today's leader: Disposable. Tomorrow's challenger: Pull-Up.
Material:
Cost tier stratification separates commodity pulp-based cores from premium superabsorbent polymer platforms, with European-engineered SAP commanding institutional preference.
- Superabsorbent:Cross-linked sodium polyacrylate granules with optimized gel strength enable 3000+ mL retention in sub-8mm core profiles. Florida and Texas agency procurement directors specify SAP-dominant constructions to reduce per-change labor burden.
- Polymer:Polypropylene spunbond-meltblown-spunbond laminates provide skin dryness performance through capillary action. California retail pharmacy volume concentrates here for standard absorbency tiers.
- Cotton:Bleached natural fiber absorbent cores with moderate wicking speed capture price-sensitive home caregiver segments in rural Texas.
- Bamboo:Viscose-derived fiber blends marketed for antimicrobial and thermal regulation properties serve niche premium positioning in coastal California markets.
Volume concentrates in superabsorbent. Margin expansion concentrates in bamboo.
End User:
Customer type determines packaging configuration, with institutional bulk formats diverging sharply from retail consumer units.
- Seniors:Age-related urinary incontinence in the 75+ demographic drives core demand concentration across all four covered states, with pull-up preference strongest among independent living populations.
- Patients:Post-surgical and acute care discharge populations require heavy absorbency tape-tab designs for immobilized handling by skilled nursing staff.
- Disabled Individuals:Neurogenic bladder and bowel conditions in younger adult populations create sustained demand for specialized sizing and skin-sensitivity formulations.
- Caregivers:Family and professional care providers function as proxy purchasers, with institutional caregivers prioritizing change-efficiency and home caregivers prioritizing discretion and odor control.
Institutional procurement targets patients. Direct-to-consumer growth targets seniors.
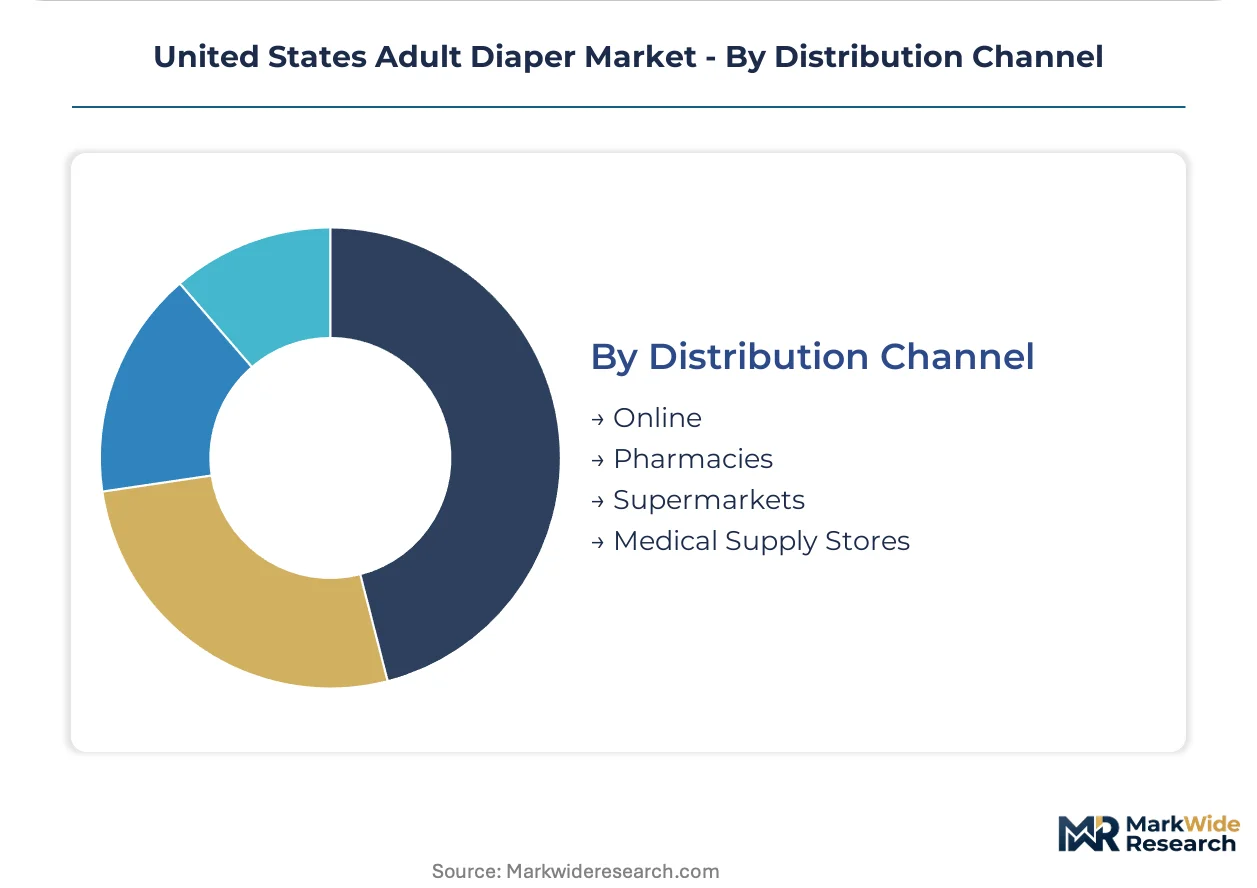
Distribution Channel:
Geography of demand shapes channel viability, with rural Texas markets underserved by retail density and dependent on agency delivery models.
- Medical Supply Stores:Durable medical equipment dealers with Medicare billing capabilities capture recurring subscription volume from Florida home healthcare networks, bundling diapers with wound care and mobility products.
- Online:Direct-to-consumer platforms with discreet packaging and auto-replenishment algorithms gain share among California caregivers managing supply for remote seniors.
- Pharmacies:Chain and independent drugstores with Medicare Advantage contract participation retain pull-up and light absorbency volume in urban and suburban markets.
- Supermarkets:Mass retail shelf space concentrates on economy-tier disposable formats for price-sensitive self-purchasers in high-traffic Florida locations.
Medical supply stores anchor institutional volume. Online channels claim the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida and Texas generate comparable institutional procurement volumes, yet California's retail pharmacy channel retains stronger pull-up format penetration among independent seniors.
Florida
Medicare Advantage incontinence benefits and home healthcare agency density drive concentrated demand. CMS reimbursement rate adjustments favor institutional procurement over retail purchases. The Tampa-Orlando corridor anchors distribution infrastructure serving Gulf Coast senior populations.
California
Mobility-enabled seniors in urban coastal markets reject tape-tab stigma fastest, accelerating pull-up adoption. State Medicaid managed care contract structures fragment pricing systems across county lines. Los Angeles and San Francisco Bay Area pharmacies stock premium skin-sensitivity formulations for discerning caregivers.
Texas
Rural senior populations and skilled nursing facility expansion create bariatric format underpenetration opportunities. OSHA bloodborne pathogen compliance raises operational overhead for institutional providers. Dallas-Fort Worth and Houston medical supply distributors consolidate supplier relationships around inventory management services.
New York Metro
High-density urban caregiving and professional home health aide employment sustain steady tape-tab demand for immobilized patients. State-level Medicaid reimbursement policies lag Medicare Advantage expansion timelines. The five-borough area and Westchester County concentrate durable medical equipment dealer networks.
Southeast (Georgia/Carolinas)
Retirement migration patterns and lower cost-of-living attract senior population inflows from Northeast corridors. Medicare Advantage plan penetration rates trail Florida but accelerate annually. Atlanta anchors regional distribution serving Carolinas long-term care facility construction.
United States Adult Diaper Market Key Industry Players
Top-tier vendors anchor North American manufacturing footprints, while mid-tier specialists compete through private-label partnerships and European-engineered material platforms. The vendor base separates into three strategic archetypes: multinational hygiene conglomerates with integrated polymer supply chains, regional specialists with distributor-anchored relationships, and private-label manufacturers serving institutional procurement channels. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure Medicare Advantage contract eligibility.
Among North American hygiene conglomerates, Kimberly-Clark Corporation exemplifies scale-driven manufacturing presence, while First Quality Enterprises, LLC occupies a position within private-label institutional supply. Ontex represents European-engineered material specialization adapted to US sizing standards. These three anchors illustrate how competitive positioning stratifies across manufacturing scale, distributor relationships, and material science differentiation.
| Leading Market Players |
|---|
| First Quality Enterprises, LLC |
| Ontex |
| Kimberly-Clark Corporation |
| Attends Healthcare Products, Inc. |
| Principle Business Enterprises, Inc. |
| Procter & Gamble Company |
| Drylock Technologies |
| TZMO Group |
| Essity AB |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap manufacturers with multi-generational Gulf Coast petrochemical ties anchor raw material sourcing discipline, while private-equity-rolled-up distributors consolidate purchasing power across Florida and Texas home healthcare networks. This ownership concentration enables volume-tier contracting that squeezes commodity pulp-based producers while rewarding superabsorbent polymer innovators with pricing premiums.
Pricing Analysis
Bundled institutional procurement contracts that wrap diapers with wound care and mobility equipment dominate Medicare Advantage channels, while unbundled retail pharmacy transactions persist among California's independent seniors. Pricing stratifies across premium SAP-dominant cores, standard polymer constructions, and economy-tier pulp-based alternatives. Cost compression in economy tiers is intensifying because Gulf Coast resin volatility feeds through to polyethylene backsheet film production. Home healthcare agencies show least price sensitivity due to CMS reimbursement pass-through, while rural Texas self-purchasers exhibit highest elasticity.
Supply Chain Analysis
Freight cost escalation from Gulf Coast petrochemical hubs to Florida distribution centers is reshaping inventory positioning, with Dallas-Fort Worth emerging as a consolidation node. Manufacturing draws from Texas and Louisiana polymer production, with European-engineered SAP platforms imported through East Coast ports. Single-source vulnerability concentrates in superabsorbent polymer supply, where three specialized producers serve institutional specifications. Distribution runs through medical supply distributors with Medicare billing capabilities, bypassing retail markup for recurring agency volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States adult diaper market functions as a stable compounder, with Medicare Advantage demographic tailwinds generating predictable reimbursement-backed demand expansion across Florida, California, and Texas.
For Market Incumbents: To counter private-label encroachment from First Quality Enterprises and regional distributors, Kimberly-Clark and Essity should deepen backward integration into Gulf Coast polypropylene resin production while securing exclusive Medicare Advantage formulary status in Florida's Tampa-Orlando corridor. Channel control through inventory management partnerships with Texas skilled nursing facilities offers defensive moat construction. For New Entrants and Emerging Players: Bariatric format demand in Texas and Florida skilled nursing facilities represents the most penetrable white space, with current retail assortments inadequately serving extended-waist specifications. A direct institutional supply model bypassing distributor markup, paired with OSHA-compliant staff training protocols, unlocks agency procurement relationships. California's bamboo fiber niche offers premium positioning for sustainability-focused entrants. For Investors and Strategic Acquirers: Home healthcare platform operators are the most active acquirer in this space, rolling up regional distributors to capture Medicare Advantage contract eligibility. The 5-10 year viability window favors targets with established GPO relationships and SAP-dominant product portfolios. The signal to watch is CMS reimbursement rate compression, which would accelerate channel consolidation toward scaled institutional suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Medicare Advantage Contract Eligibility | Unlocks institutional procurement scale in Florida and Texas agency networks. |
| Superabsorbent Polymer Platform Licensing | European-engineered SAP adaptations differentiate premium tier positioning. |
| Home Healthcare Channel Integration | Direct supply relationships bypass retail markup and capture recurring subscription volume. |
| Bariatric Format Capacity Expansion | Extended-size production addresses underserved Texas and Florida long-term care demand. |
| OSHA Compliance Training Programs | Staff certification protocols differentiate institutional suppliers in skilled nursing procurement. |
Research Approach
Direct dialogue with home healthcare agency procurement directors, skilled nursing facility administrators, Medicare Advantage plan managers, and medical supply distributor executives grounded qualitative findings, validated against CMS reimbursement databases, FDA 510(k) filings, hospital procurement records, and GPO contract repositories. Bottom-up and top-down triangulation cross-checked volume estimates across channel-specific data streams.
Bottom-up modeling aggregated segment-level volume and value projections across the analysis window, with top-down macro validation against demographic forecasts and reimbursement policy trajectories. Segmentation dimensions included product format, absorbency tier, material composition, end-user mobility status, and distribution channel. CAGRs were derived from fitted growth curves incorporating Medicare Advantage penetration rates and SAP technology adoption curves.
Inputs from CMS reimbursement schedules and state Medicaid managed care contracts were available through the study window; gaps in private-label distributor financial disclosures introduce uncertainty bands around market share allocations. Forecasts reflect assumptions about continued Medicare Advantage benefit expansion and stable petrochemical input costs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Smart Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
Pet Diapers Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Diaper Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Adult Diapers Market
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Cat Diapers Market