
 Europe Diaper Market | 2026-2036
Europe Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Diaper Market Intelligence
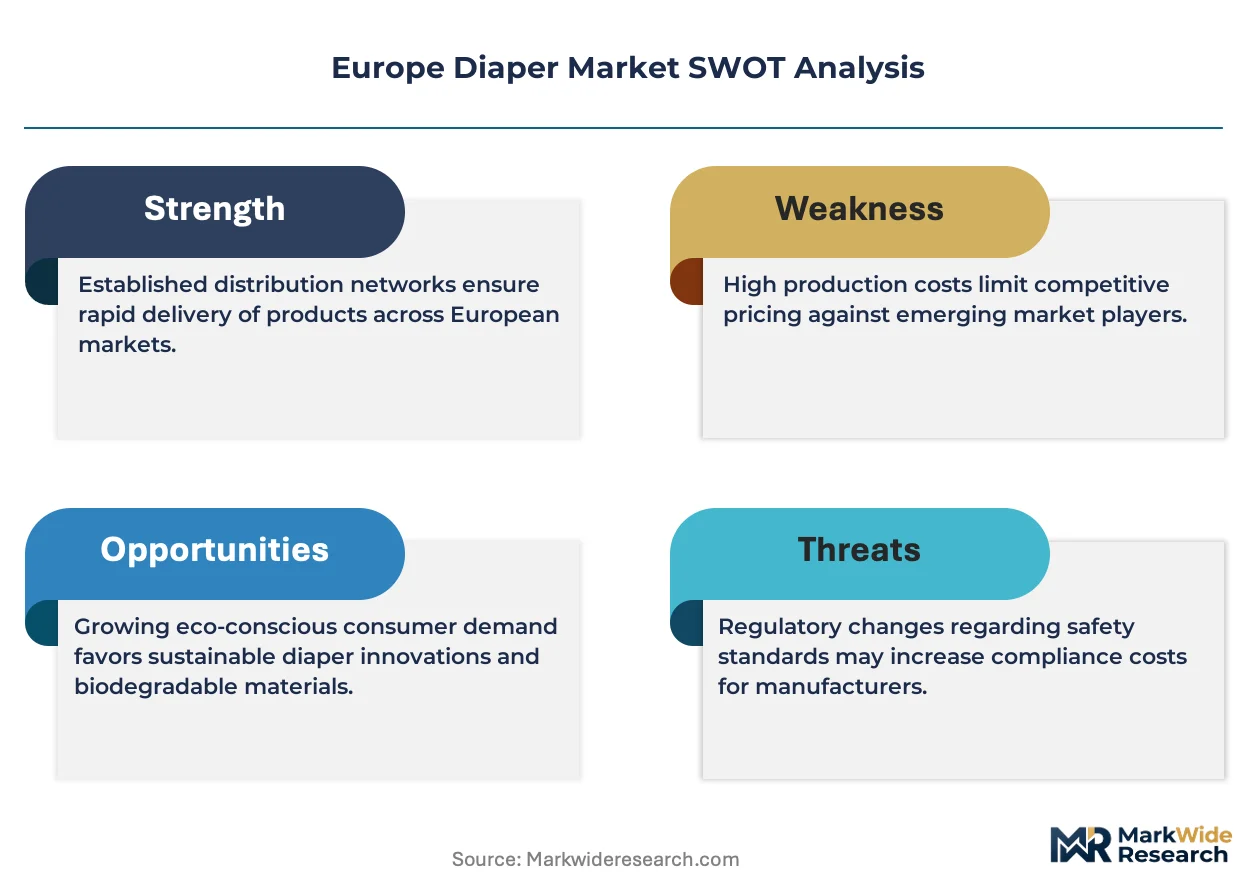
CE marking under the EU Medical Devices Regulation is bifurcating which manufacturers can supply dermatologically tested infant hygiene products across the single market. Procter & Gamble leverages its extensive European manufacturing footprint to sustain shelf dominance in mass retail channels. Essity AB anchors its position through private-label partnerships with major pharmacy chains, while Ontex Group specializes in sustainable product lines that navigate tightening chemical compliance thresholds.
Europe diapers comprise multi-layer absorbent garments engineered with superabsorbent polymer cores, nonwoven topsheets, and elasticized leg cuffs designed for fluid retention and skin barrier protection in infant and incontinence care. Disposable products lead volume shipments across the region, though biodegradable segments are capturing margin pools as REACH restrictions on petrochemical inputs harden. Online retail channels are expanding fastest among distribution pathways, while pharmacy-based sales retain premium pricing power for hypoallergenic and dermatologically certified formulations.
EMA dermatological safety guidelines, REACH chemical substance restrictions, and the EU Green Deal circular economy framework collectively shape product formulation, packaging recyclability mandates, and market access conditions for non-EU suppliers. National regulators in France, Germany, and Italy enforce additional labeling and waste-sorting requirements that fragment compliance obligations. Stakeholders must monitor pending revisions to absorbent hygiene product standards and assess whether localized production or strategic supplier restructuring offers stronger compliance insulation.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing absorbent hygiene manufacturers to reengineer supply chains around biodegradable pulp and plant-based superabsorbent polymers, creating a compliance-driven restructuring of raw material sourcing across the single market.
Growth Catalysts
- REACH chemical restrictions:Petrochemical input limits under ECHA oversight are accelerating R&D investment in bio-based absorbent cores among German and French producers seeking regulatory insulation.
- Dual-income household expansion:Premium infant care adoption is concentrating demand for dermatologically certified products in urban France, Germany, and the United Kingdom.
- Biodegradable polymer commercialization:Pilot-scale production of corn-starch and bamboo-derived SAP alternatives is reducing reliance on fossil-based inputs ahead of 2030 circular economy targets.
Market Restraints
- Fluff pulp supply concentration:Nordic and North American softwood pulp suppliers control 70% of EU diaper-grade fiber input, exposing converters to freight and currency volatility.
- Superabsorbent polymer technical ceiling:Bio-based SAP alternatives currently deliver 15-20% lower fluid retention capacity versus petrochemical equivalents, limiting premium product performance parity.
- CE marking friction under MDR:Dermatological safety certification timelines for infant hygiene products now extend 18-24 months, gating market access for non-EU suppliers.
Strategic Opportunities
- Poland and Romania underpenetration:Birth rate stability combined with rising disposable income in Eastern EU member states is opening pharmacy and modern trade expansion corridors for hypoallergenic lines.
- EU Green Deal packaging mandates:Recyclable mono-material pouch requirements are creating first-mover advantage for converters with integrated film extrusion and printing capabilities.
- Online subscription channel innovation:Direct-to-consumer auto-replenishment models are capturing margin pools previously held by mass retail distributors in the United Kingdom and Netherlands.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation expertise bridging petrochemical and bio-based absorbent science is concentrated among retiring specialists at BASF, Evonik, and academic institutes in Germany.
- Legacy line retrofit capex intensity:Converting existing thermal-bonding equipment to handle lower-melt biodegradable nonwovens requires 8-12 million euro per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Diaper Market |
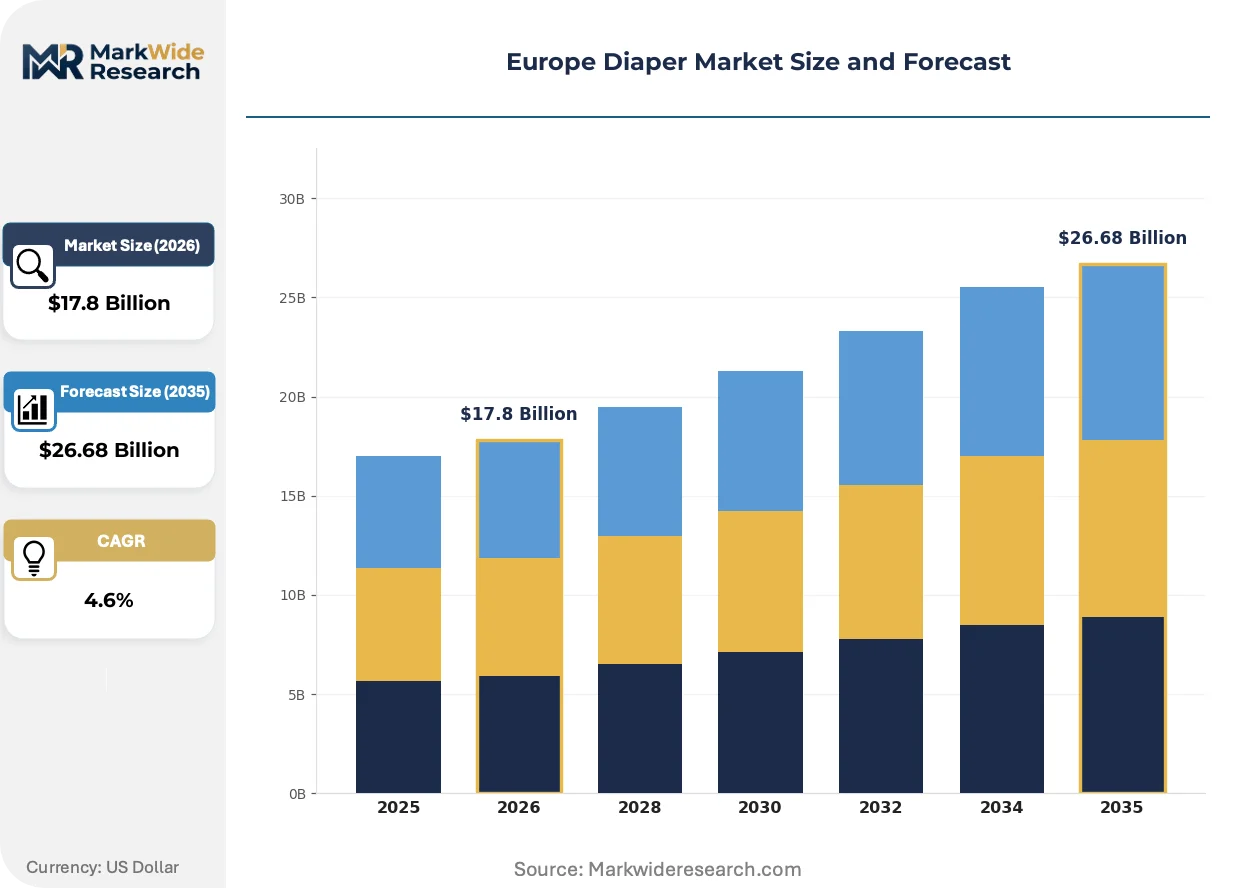
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Biodegradable, Training Pants Age Group: Newborn, Infants, Toddlers, Preschoolers Gender: Unisex, Male, Female, Gender Neutral Distribution Channel: Supermarkets, Online Retail, Pharmacies, Specialty Stores |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Unicharm Corporation, Essity AB, Ontex Group, Hengan International Group, Kao Corporation, Johnson & Johnson, The Honest Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Diaper Market Strategic Shifts & Innovations
Plant-based material science and digital distribution infrastructure are compressing traditional competitive moats in European absorbent hygiene, while regulatory chemistry restrictions are redefining permissible product architectures.
Superabsorbent polymer core technology is miniaturizing. Thin-core designs using surface-crosslinked sodium polyacrylate granules now achieve equivalent retention at 40% reduced bulk versus conventional fluff-pulp composites. Premium infant and light incontinence segments in Germany and France are adopting these profiles fastest. The structural compression is miniaturizing packaging cube and logistics cost, enabling direct-to-consumer fulfillment economics previously unviable for bulky hygiene categories.
REACH Annex XVII restrictions on petrochemical monomers are tightening formulation freedom. ECHA's 2023-2025 restriction roadmap targets acrylamide residuals and formaldehyde-releasing preservatives in absorbent articles. Manufacturers serving the single market are accelerating bio-SAP pilot programs and submitting updated safety dossiers. The regulatory pressure is most acute for private-label suppliers lacking dedicated toxicology departments, favoring integrated producers with in-house analytical capabilities.
Subscription-based replenishment is displacing periodic retail stock-up behavior. Millennial and Generation Z parents in the United Kingdom and Netherlands are consolidating diaper purchasing into automated delivery cycles with flexible sizing algorithms. Pharmacy chains and mass retailers are responding with loyalty-integrated digital platforms. The channel migration is most visible in urban conurbations where same-day or next-day fulfillment infrastructure is densest.
Europe Diaper Market Segmentation
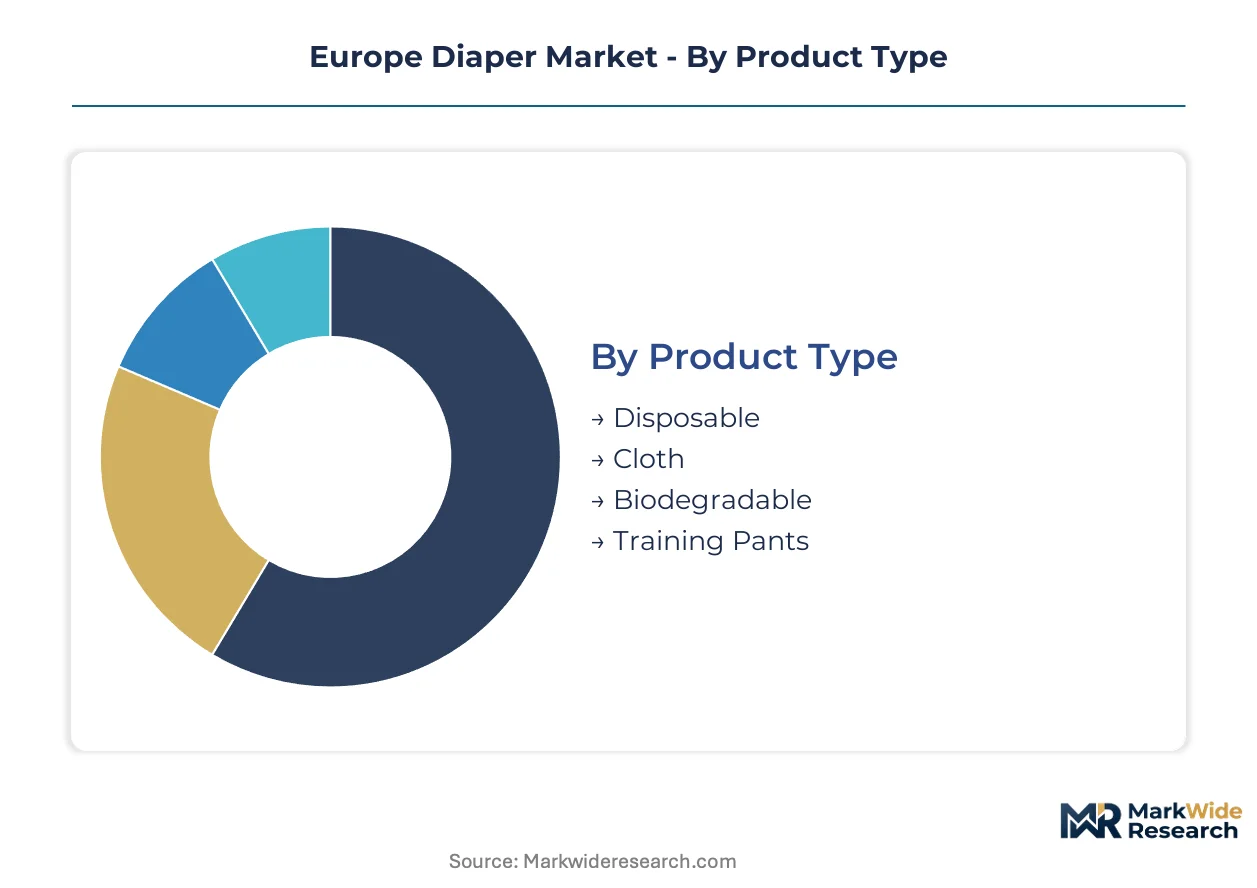
Segmentation in the Europe diaper market reveals how REACH compliance tiers and dermatological certification requirements create distinct competitive battlegrounds. Manufacturers must align product architecture with distribution channel regulations and end-use performance specifications.
Product Type:
REACH Annex XVII chemical restrictions and the EU Green Deal circular economy framework are bifurcating product development pathways between petrochemical-dependent legacy formats and bio-based alternatives.
- Disposable:Multi-layer absorbent garments with sodium polyacrylate cores and thermal-bonded nonwoven topsheets dominate pharmacy and supermarket channels across Germany and France. CE marking under MDR requirements for dermatological safety certification now extends 18-24 months, favoring integrated producers with in-house toxicology capabilities.
- Biodegradable:Corn-starch and bamboo-derived superabsorbent polymer alternatives are advancing through pilot-scale production in response to fossil-based input restrictions. Fluid retention capacity currently trails petrochemical equivalents by 15-20%, limiting premium product performance parity in high-absorbency infant segments.
- Cloth:Reusable cotton and hemp-based designs with snap or hook-and-loop closures serve sustainability-focused households in the Netherlands and Scandinavian urban centers.
- Training Pants:Elasticized waistband designs with tear-away side seams bridge diaper-to-underwear transition for toddlers aged 2-4 years.
Established volume favors Disposable; emerging adoption favors Biodegradable.
Age Group:
Per-capita spending intensity and product performance requirements vary sharply across developmental stages, with dual-income household premiumization concentrating in urban France and the United Kingdom.
- Newborn:Ultra-soft topsheets with umbilical cord cutouts and wetness indicators command premium pricing in pharmacy channels. German and French birth-rate stability sustains demand for dermatologically certified formulations with hypoallergenic claims.
- Infants:High-frequency change requirements (8-12 daily) drive volume concentration in supermarket and subscription channels. Thin-core SAP designs achieving equivalent retention at 40% reduced bulk are gaining share fastest in this segment.
- Toddlers:Higher fluid capacity requirements and mobility accommodation shift demand toward pull-up configurations with standing leak guards.
- Preschoolers:Overnight absorbency specialization and discreet profile designs address bedwetting management in children aged 3-5 years.
Volume concentration sits with Infants; margin expansion targets Newborn.
Gender:
Product architecture differentiation and marketing positioning strategies reflect evolving parental preferences across Northern and Southern European markets.
- Unisex:Standardized absorbent core placement and neutral color palettes dominate mass retail procurement specifications across EU member states. Pharmacy chains in Germany and France increasingly specify unisex formats to streamline inventory and reduce SKU complexity.
- Male:Front-loaded absorbent zones address urinary concentration patterns in infant and toddler segments.
- Female:Centered core designs with extended rear protection serve anatomical requirements in higher-age brackets.
- Gender Neutral:Minimalist packaging and earth-tone aesthetics target millennial and Generation Z parents in the United Kingdom and Netherlands subscription channels.
Procurement standardization favors Unisex; brand differentiation explores Gender Neutral.
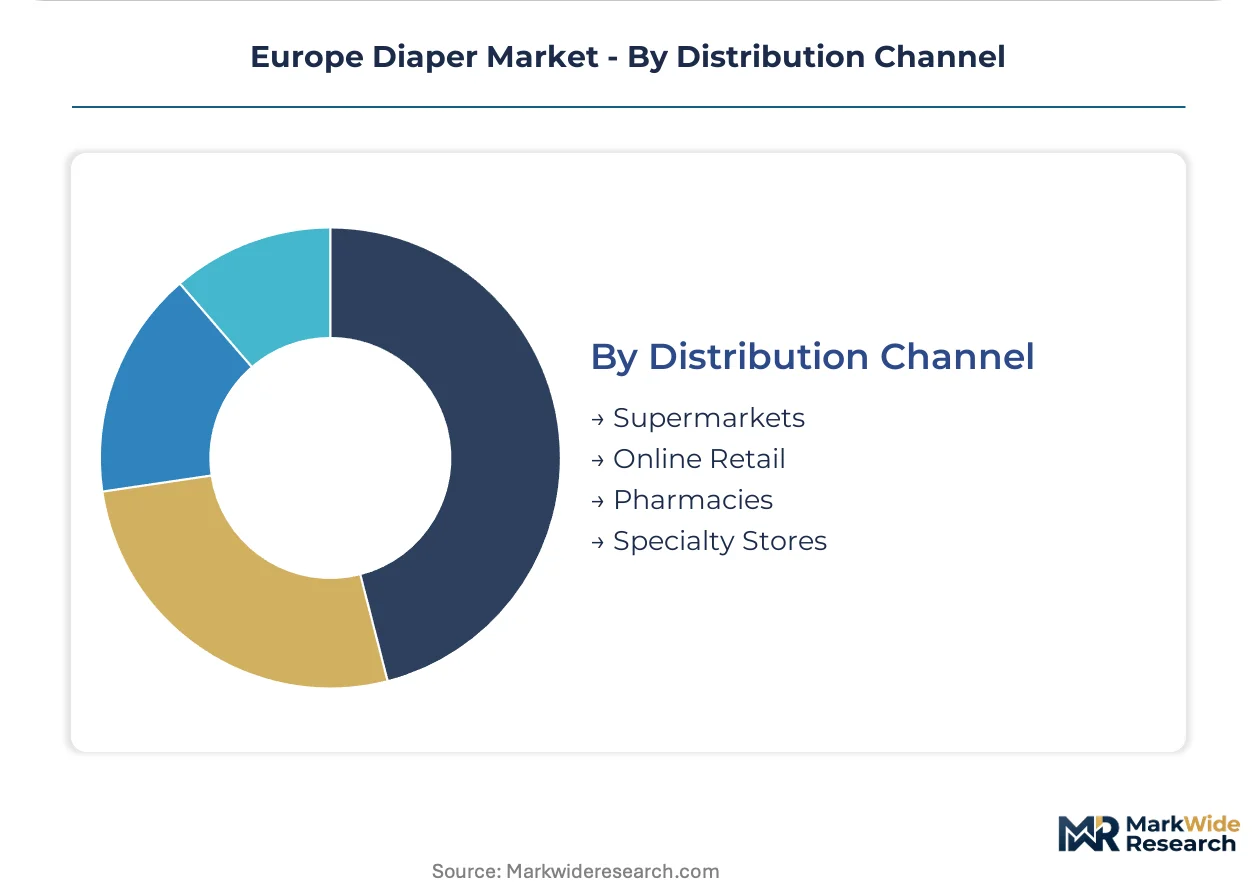
Distribution Channel:
Fulfillment infrastructure density and regulatory compliance obligations determine channel economics, with online subscription models capturing margin pools previously held by mass retail distributors.
- Online Retail:Direct-to-consumer auto-replenishment platforms with flexible sizing algorithms are expanding fastest in the United Kingdom and Netherlands. Same-day and next-day fulfillment infrastructure in urban conurbations enables bulky category economics previously unviable for home delivery.
- Pharmacies:Hypoallergenic and dermatologically certified formulations retain premium pricing power through pharmacist recommendation authority. CE marking and EMA dermatological safety guidelines create compliance barriers that favor established suppliers with dedicated regulatory affairs departments.
- Supermarkets:Mass retail shelf space competition concentrates volume in standardized unisex formats with promotional pricing cycles.
- Specialty Stores:Boutique organic and eco-focused retailers serve sustainability-segmented demand in Scandinavian and Benelux urban centers.
Volume legacy resides with Supermarkets; steepest expansion trajectory belongs to Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income households with premium infant care preferences cluster in urban centers across Germany, France, and the United Kingdom, while Eastern EU member states present volume expansion corridors for standardized formats.
Germany
Birth-rate stability and elevated per-capita hygiene spending sustain demand for dermatologically certified newborn products. ECHA REACH restrictions on petrochemical inputs accelerate bio-based superabsorbent polymer pilot programs among domestic converters. The Rhine-Ruhr industrial corridor hosts integrated manufacturing facilities supplying pharmacy and supermarket channels across the single market.
France
Pharmacy-based distribution retains premium pricing power through ANSM-backed hypoallergenic certification requirements. EU Green Deal circular economy mandates drive recyclable mono-material packaging adoption among Paris Basin converters. Lyon and Grenoble clusters concentrate formulation expertise bridging petrochemical and bio-based absorbent science.
United Kingdom
Millennial and Generation Z parents consolidate purchasing into online subscription models with flexible sizing algorithms. MHRA dermatological safety guidelines align with CE marking timelines under MDR, extending certification cycles for non-EU suppliers. London and Southeast England logistics infrastructure enables same-day fulfillment economics for bulky hygiene categories.
Poland
Rising disposable income combined with birth rate stability opens modern trade expansion corridors for standardized infant formats. National waste-sorting requirements under EU circular economy frameworks create compliance complexity for imported products. Warsaw and Łódź manufacturing zones attract converting capacity serving Central European distribution networks.
Netherlands
Sustainability-focused households in Amsterdam and Rotterdam urban centers drive adoption of biodegradable and cloth diaper alternatives. Digital distribution infrastructure density supports direct-to-consumer auto-replenishment platform growth. Rotterdam port logistics facilitate Nordic fluff pulp import for regional converting operations.
Europe Diaper Market Key Industry Players
Player mix skews toward integrated multinational hygiene conglomerates with dedicated regulatory affairs capabilities. Market structure concentrates shelf presence among mass retail suppliers while private-label specialists capture pharmacy channel volume. Three archetypes dominate: vertically integrated producers with in-house toxicology departments, sustainability-focused converters with bio-material expertise, and subscription-platform operators with direct-to-consumer fulfillment infrastructure. Competitive moves center on M&A for regional regulatory capabilities and capacity expansion into Eastern EU member states.
Within the integrated multinational tier, Procter & Gamble and Kimberly-Clark Corporation occupy positions defined by extensive European manufacturing footprints and mass retail channel dominance. Essity AB and Ontex Group represent the private-label and sustainability-specialist archetypes respectively, with the former anchoring pharmacy chain partnerships and the latter exemplifying bio-based product line navigation of REACH compliance thresholds. Unicharm Corporation and Kao Corporation sit within the Asia-origin multinational segment, their market access contingent on CE marking timelines under EU Medical Devices Regulation.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Essity AB |
| Ontex Group |
| Hengan International Group |
| Kao Corporation |
| Johnson & Johnson |
| The Honest Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Nordic fluff pulp suppliers and German converting facilities lock in both raw material access and cost visibility across the analysis window, insulating integrated producers from freight volatility that erodes margin pools for spot-market dependent competitors.
Pricing Analysis
Cost-plus contracts with NBSK pulp indexation anchor diaper manufacturing economics across the Rhine-Ruhr corridor. Three-tier pricing structure across premium, standard, and economy levels separates dermatologically certified pharmacy formats from mass retail unisex lines and private-label economy tiers. Price differentiation hinges on REACH compliance certification tier and after-sales bundling with subscription auto-replenishment. Cost compression in economy tiers is intensifying because bio-SAP scale-up delays extend petrochemical dependency. Pharmacy channel buyers show lowest price sensitivity; Eastern EU modern trade procurement exhibits highest elasticity.
Supply Chain Analysis
Sixty-day inventory buffers at Rotterdam port terminals mask lead-time vulnerability for Nordic and North American softwood pulp flows. Geographic concentration centers on Sweden, Finland, and Canada for fluff pulp; Germany, France, and Belgium for converting and distribution. Raw material dependencies rest on sodium polyacrylate granules, thermal-bonded nonwoven rolls, and elasticized leg cuff components. Single-source vulnerability concentrates in bio-SAP pilot production where BASF and Evonik formulation expertise remains scarce. Distribution runs through pharmacy chain central warehouses, supermarket regional distribution centers, and direct-to-consumer fulfillment hubs in London and Amsterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise bridging petrochemical and bio-based absorbent science is concentrated among retiring specialists, creating a capability bottleneck that will determine competitive survival as REACH restrictions harden.
For Market Incumbents: Consolidate backward integration into Nordic fluff pulp supply through equity stakes or captive offtake agreements to defend against freight volatility and currency exposure. Expand CE marking and EMA dermatological safety certification capacity to extend regulatory moats against emerging private-label competitors lacking dedicated toxicology departments. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission programs offers market access acceleration for non-EU suppliers facing 18-24 month certification timelines. Target Poland and Romania pharmacy channel underpenetration with hypoallergenic lines positioned below incumbent premium pricing. Deploy direct-to-consumer subscription platforms with flexible sizing algorithms to bypass mass retail shelf space barriers. For Investors and Strategic Acquirers: Regional converting specialists with integrated film extrusion and mono-material pouch capabilities represent priority acquisition targets as EU Green Deal packaging mandates create first-mover advantage. Long-term viability frames around bio-SAP commercialization scale rather than legacy petrochemical asset bases. Monitor ECHA restriction roadmap implementation velocity as inflection indicator for stranded asset risk in conventional absorbent core production.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-SAP Pilot Scale-Up | REACH Annex XVII compliance insulation depends on corn-starch and bamboo-derived polymer retention parity achievement. |
| Mono-Material Packaging Transition | EU Green Deal recyclable pouch mandates favor converters with integrated film extrusion and printing capabilities. |
| Direct-to-Consumer Platform Launch | Subscription auto-replenishment captures margin pools previously held by mass retail distributors in Netherlands and United Kingdom. |
| Eastern EU Manufacturing Footprint | Poland and Romania birth-rate stability opens modern trade expansion corridors with lower labor cost bases. |
| CE Marking Capacity Expansion | MDR dermatological safety certification timelines favor integrated producers with in-house toxicology departments. |
Research Approach
Cross-validation between primary interviews with plant managers at converting facilities, procurement leads at pharmacy chains, and regulatory affairs directors anchors the qualitative findings against secondary validation from ECHA restriction roadmaps, EU customs trade data, and SEC filings of listed hygiene conglomerates. Bottom-up demand modeling triangulates against top-down market sizing.
Sensitivity analysis across bio-SAP adoption velocity scenarios and fluff pulp price index volatility bands stress-tests projection robustness. Segmentation dimensions span product architecture, age-group performance requirements, distribution channel compliance obligations, and regional regulatory cluster intensity. CAGRs derive from fitted growth curves calibrated to historical volume shipments and elasticity-adjusted price trajectories. Forecast inputs incorporate REACH implementation timelines and dual-income household expansion patterns.
Decision-makers should treat outputs as directional under base assumptions of stable birth rates and incremental REACH enforcement; material deviation in regulatory acceleration or bio-polymer breakthrough would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
Smart Diaper Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
Pet Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Baby Diapers Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Smart Connected Diaper Market