
 Middle East and Africa and Asia Pacific Baby Diaper Market | 2026-2036
Middle East and Africa and Asia Pacific Baby Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa and Asia Pacific Baby Diaper Market Foresight
Market Context
The price-performance gap between premium and commodity baby diaper tiers is broadening across the Middle East and Africa and Asia Pacific region. Procter & Gamble leverages its super-absorbent polymer R&D pipeline to command shelf space in Gulf Cooperation Council hypermarkets. Kimberly-Clark Corporation anchors its position through backward integration into fluff pulp sourcing across Southeast Asian manufacturing hubs. Hengan International competes on unit economics by dominating mid-tier distribution through China's provincial wholesale networks.
Technical Definition and Segment Structure
Middle East and Africa and Asia Pacific baby diapers are absorbent hygiene garments engineered with super-absorbent polymers, non-woven topsheets, and elasticized leg cuffs designed to capture and isolate infant waste for extended wear periods. Manufacturing employs hot-melt adhesive bonding and ultrasonic sealing to achieve breathable yet leak-resistant barrier layers. Disposable products lead volume across all measured channels, while biodegradable variants represent the fastest-growing material segment as Gulf states advance extended producer responsibility frameworks. Supermarket channels sustain margin pools in South Africa and Saudi Arabia, though online platforms in Indonesia and Vietnam capture the steepest growth trajectory among distribution channels.
Regulatory Framework and Outlook
China's NMPA and SAMR enforce absorbent material migration limits and labeling transparency that filter substandard imports from regional supply chains. India's BIS and CDSCO coordinate on skin-contact chemical thresholds and pediatric dermatological safety protocols that manufacturers must satisfy for domestic market access. The EU Green Deal's extraterritorial REACH implications shape export-oriented production standards for biodegradable segments manufactured in Turkey and Egypt. Stakeholders must monitor how Gulf standardization bodies harmonize disposable product regulations with emerging circular economy mandates.
Market Dynamics
Super-absorbent polymer supply concentration in Saudi Arabia and South Korea is compressing margin structures for mid-tier manufacturers across the Middle East and Africa and Asia Pacific region, forcing procurement reconfigurations toward captive pulp sourcing or regional joint ventures.
Growth Catalysts
- China's NMPA absorbent material migration limits:The safety standard filters substandard imports, creating shelf space for compliant domestic and regional manufacturers who invested in certified polymer sourcing.
- Urban millennial parents in metropolitan India:This demographic cluster drives premium-tier volume through quality-sensitive purchasing and subscription-based replenishment models in tier-two cities.
- Extended producer responsibility frameworks:Gulf state circular economy mandates accelerate biodegradable segment development, rewarding manufacturers with localized composting partnerships.
Market Restraints
- Fluff pulp input cost volatility:Softwood pulp price swings tied to Nordic and North American forestry cycles compress gross margins for non-integrated producers.
- Super-absorbent polymer supply concentration:Saudi petrochemical complexes and South Korean chemical groups control 70% of regional SAP output, creating procurement bottlenecks.
- India's BIS textile labeling compliance timeline:Mandatory skin-contact chemical disclosure requirements extend product registration cycles by 8-14 months for new market entrants.
Strategic Opportunities
- Nigeria's Lagos-Abuja corridor:Underpenetrated modern trade infrastructure creates first-mover advantage for brands establishing direct distribution to pharmacy chains.
- Indonesia's online platform channel:Marketplace fulfillment models bypass traditional wholesale markups, enabling price repositioning against entrenched multinational brands.
- EU Green Deal extraterritorial REACH alignment:Turkish and Egyptian export-oriented producers gain preferential access to European biodegradable segments by certifying to harmonized chemical safety standards.
Industry Challenges
- Hot-melt adhesive formulation expertise:Scarce polymer chemistry talent in Vietnam and Bangladesh delays localized barrier-layer manufacturing scale-up.
- Ultrasonic sealing equipment capex intensity:Precision bonding machinery requires 18-24 month payback periods that strain mid-tier balance sheets.
- Dual certification burden for biodegradables:Manufacturers must simultaneously satisfy Gulf standardization body requirements and EU REACH compliance, doubling testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa and Asia Pacific Baby Diaper Market |
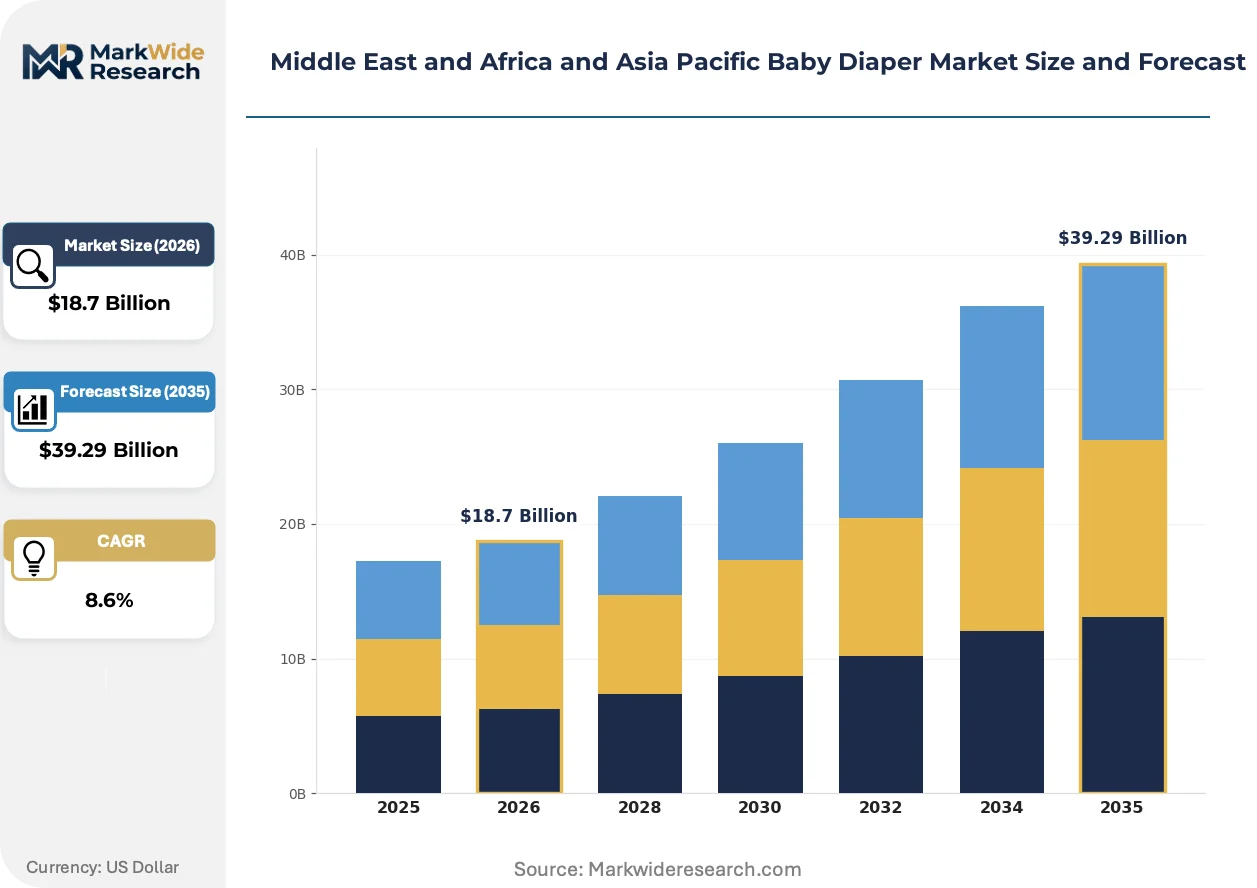
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Biodegradable, Pull-ups Material: Polymer, Cotton, Bamboo, Microfiber Distribution Channel: Online, Supermarkets, Pharmacies, Convenience Stores Age Group: Newborn, Infants, Toddlers, Older Kids |
| Companies Covered | Hengan International, Ontex Group, Procter & Gamble, Essity AB, First Quality Enterprises, Unicharm Corporation, Kao Corporation, The Honest Company, Kimberly-Clark Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa and Asia Pacific Baby Diaper Market Shifts & Advancements
Material science advances and regulatory stringency are compressing product development cycles across the Middle East and Africa and Asia Pacific baby diaper market, rewarding manufacturers who integrate compliance and performance innovation into unified R&D pipelines.
Plant-based super-absorbent polymers derived from agricultural cellulose waste are converging with conventional petroleum-derived SAP in hybrid core formulations. Premium-tier brands in Saudi Arabia and the UAE are piloting these blends to meet MOHAP biodegradability targets without sacrificing overnight absorption performance. The technology is converging with existing manufacturing lines through drop-in polymer substitution, reducing retooling barriers for mid-cap producers.
China's SAMR absorbent material labeling transparency rules now mandate full chemical constituent disclosure on primary packaging. The regulation forces reformulation of fragrance and lotion additives that previously masked under generic "skin care" claims. Domestic manufacturers with integrated polymer laboratories are responding fastest, while import-reliant brands face 6-12 month reformulation lag.
Subscription-based replenishment models are displacing traditional wholesale stocking in Indonesia's urban centers. Millennial parents in Jakarta and Surabaya now expect direct-to-home delivery synchronized to consumption algorithms, bypassing conventional supermarket diaper aisles. The shift is most visible in premium-tier segments where brand loyalty programs lock in 90-day purchase cycles.
Middle East and Africa and Asia Pacific Baby Diaper Market Segmentation
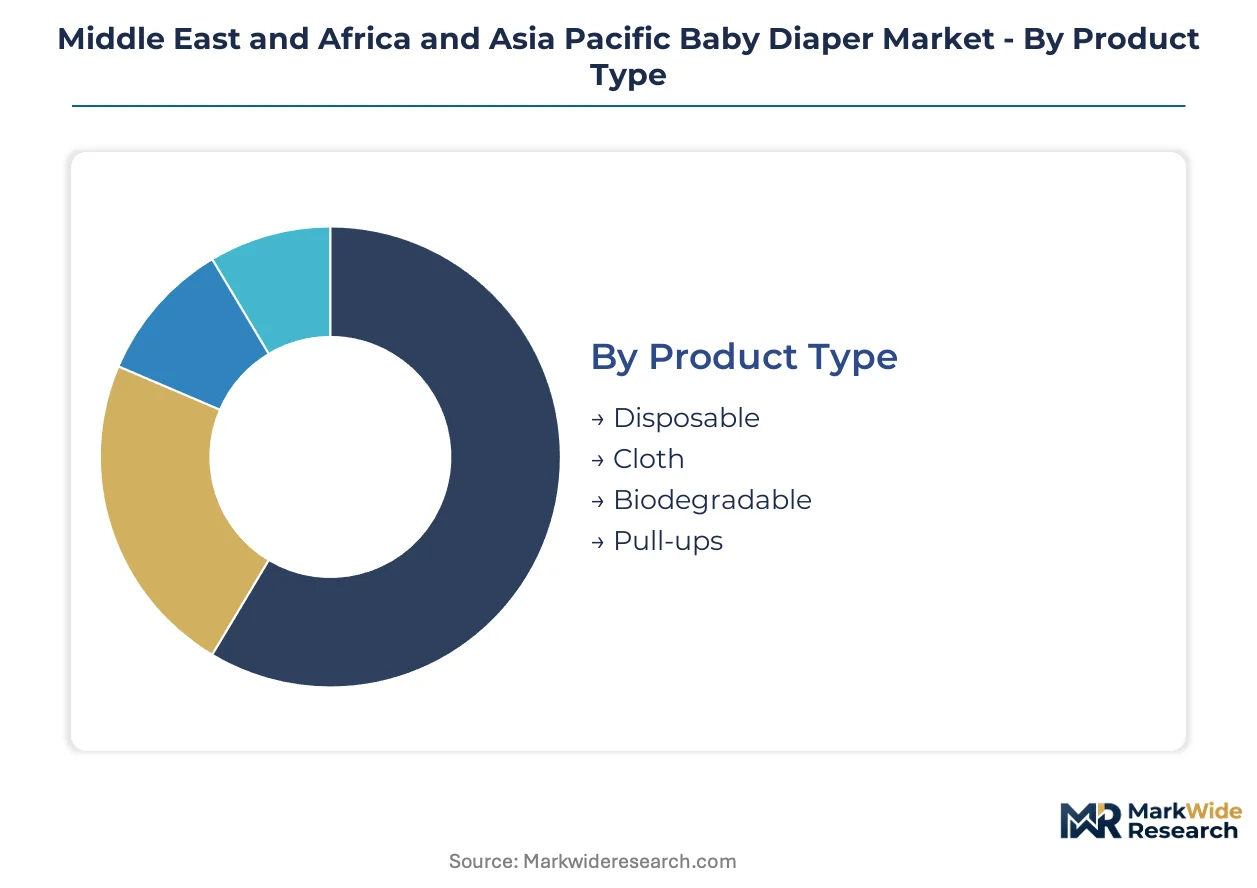
Segmentation in the Middle East and Africa and Asia Pacific baby diaper market reveals how capital deployment, regulatory compliance, and channel infrastructure determine competitive positioning. Manufacturers must align product portfolios with the distinct investment and margin profiles of each category.
Product Type:
Disposable formats demand the heaviest upfront capital for super-absorbent polymer synthesis lines and automated core-forming machinery. Cloth and biodegradable variants require lower equipment intensity but carry higher per-unit certification costs.
- Disposable:Multi-layer construction with SAP cores and breathable films dominates manufacturing footprints across Saudi petrochemical corridors and South Korean chemical parks. Demand concentrates in India's tier-two cities where modern trade penetration is deepening fastest.
- Biodegradable:Plant-based absorbent cores and compostable backsheet films require dual certification under Gulf standardization body frameworks and EU REACH protocols. Expansion is steepest in UAE and Saudi Arabia where MOHAP circular economy mandates accelerate procurement.
- Cloth:Reusable cotton-polyester blends with snap or Velcro closures serve cost-sensitive segments in Nigeria's informal retail channels.
- Pull-ups:Elasticized waistband designs for toilet-training toddlers carry premium positioning in China's urban millennial households.
Most installed capacity flows through Disposable. Expansion is steepest in Biodegradable.
Material:
Raw material selection governs supply security and margin volatility across the region's manufacturing bases. Polymer and cotton sourcing strategies diverge sharply between integrated multinationals and regional converters.
- Polymer:Petroleum-derived super-absorbent polymers from Saudi Aramco-affiliated complexes and South Korean LG Chem facilities supply 70% of regional core demand. Procurement bottlenecks in Riyadh and Dammam force mid-tier producers toward captive pulp sourcing or regional joint ventures.
- Cotton:Indian and Egyptian long-staple varieties serve premium cloth diaper segments and hybrid disposable topsheets. Demand clusters in India's BIS-compliant domestic supply chains where textile labeling rules enforce traceability.
- Bamboo:Fast-regenerating cellulose fibers from Sichuan and Yunnan provinces feed biodegradable segment growth under China's dual carbon goals.
- Microfiber:Synthetic polyester-polyamide blends enable ultra-thin core designs for premium pull-up formats in Indonesia's online channels.
Polymer commands the largest procurement spend. Bamboo is climbing the fastest on sustainability premiums.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics. Supermarket and pharmacy networks require slotting fee commitments and inventory guarantees, while online platforms demand fulfillment infrastructure investment.
- Supermarkets:Hypermarket chains in Saudi Arabia and South Africa sustain margin pools through exclusive brand placements and promotional calendar coordination. Modern trade concentration in Lagos-Abuja corridor creates first-mover access for compliant entrants.
- Online:Marketplace fulfillment models in Indonesia and Vietnam bypass traditional wholesale markups, enabling price repositioning against entrenched multinational brands. Subscription algorithms now lock in 90-day purchase cycles among Jakarta's millennial parents.
- Pharmacies:Licensed drugstore chains in Nigeria and Kenya serve quality-sensitive segments with dermatologist-endorsed premium tiers.
- Convenience Stores:Small-format urban retail in Vietnam and Philippines captures emergency replenishment demand with single-unit sachet packaging.
Supermarkets anchor volume throughput. Online is gaining share fastest on fulfillment model innovation.
Age Group:
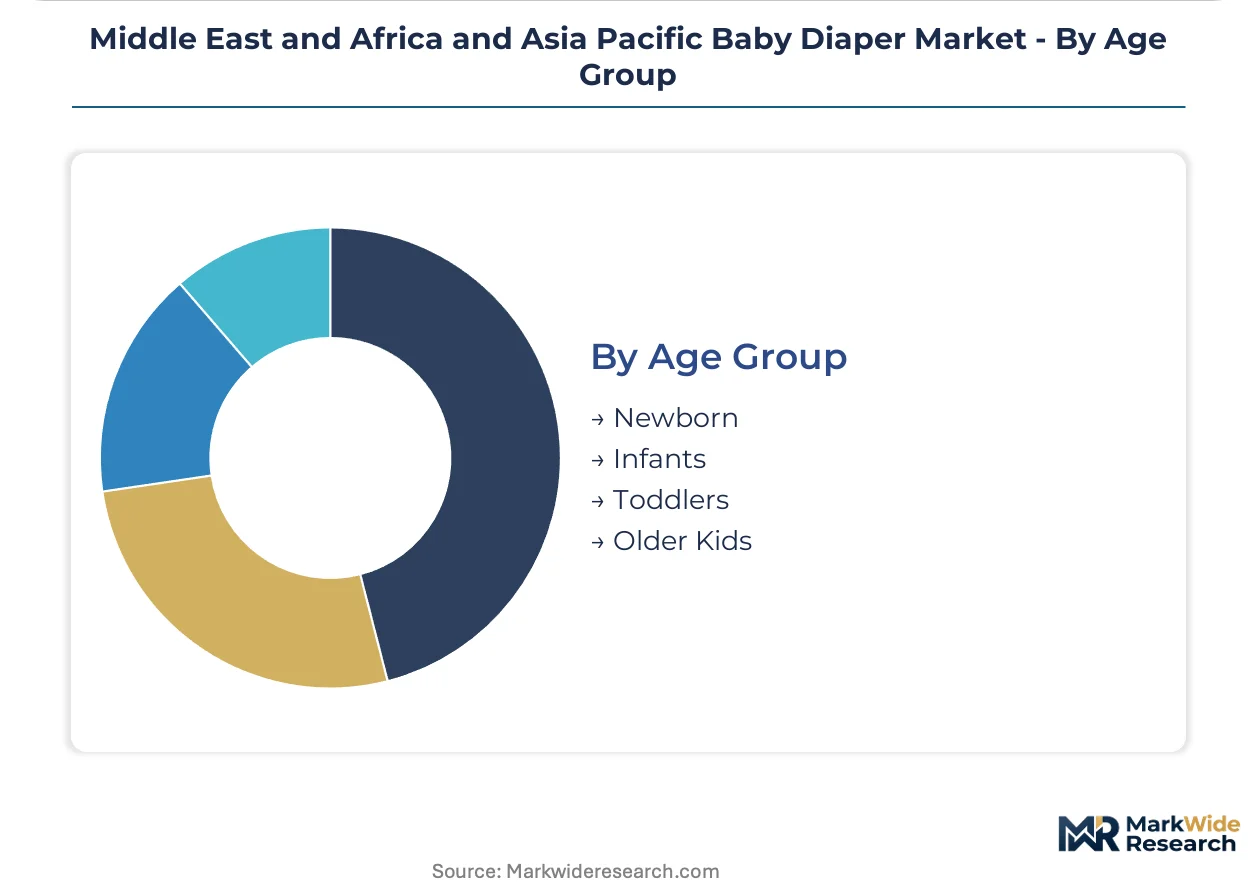
Demographic targeting shapes R&D prioritization and marketing spend allocation. Newborn and infant segments concentrate premium innovation, while toddler formats emphasize transition functionality.
- Newborn:Ultra-soft topsheets and umbilical cord cutouts address delicate skin requirements in the first 28 days. China's NMPA absorbent material migration limits filter substandard imports, creating shelf space for certified domestic manufacturers.
- Toddlers:High-capacity overnight cores and wetness indicators support extended wear during sleep training. Demand clusters in Southeast Asian urban households where dual-income parents prioritize leak protection over unit cost.
- Infants:Mid-weight cores with elasticized leg cuffs balance absorbency and mobility for crawling-stage babies.
- Older Kids:Larger waist sizing and gender-specific absorbency zones address bedwetting and special needs segments.
Newborn captures the highest per-unit margins. Toddlers show the steepest volume expansion on extended-use innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemistry talent pools in Saudi Arabia and South Korea anchor super-absorbent material supply chains across the Middle East and Africa and Asia Pacific region. Manufacturing footprints cluster near petrochemical corridors in the Gulf and textile hubs in South Asia.
Saudi Arabia
Petrochemical complexes in Riyadh and Dammam supply petroleum-derived super-absorbent polymers to regional diaper manufacturers. MOHAP circular economy mandates accelerate biodegradable segment procurement from compliant domestic producers. The Eastern Province manufacturing corridor concentrates hot-melt adhesive bonding capacity for export-oriented production.
India
Urban millennial parents in tier-two cities drive premium-tier volume through quality-sensitive purchasing patterns. BIS textile labeling rules enforce skin-contact chemical disclosure requirements that extend product registration cycles for new entrants. The Maharashtra-Gujarat industrial belt hosts fluff pulp conversion facilities serving domestic and export markets.
China
SAMR absorbent material labeling transparency rules mandate full chemical constituent disclosure on primary packaging. NMPA migration limits filter substandard imports, creating shelf space for certified domestic manufacturers. Sichuan and Yunnan provinces supply fast-regenerating bamboo cellulose fibers for biodegradable core formulations.
Indonesia
Marketplace fulfillment models in Jakarta and Surabaya bypass traditional wholesale markups through subscription-based replenishment algorithms. Millennial parents now expect direct-to-home delivery synchronized to consumption patterns. The Java-based manufacturing network scales ultrasonic sealing capacity for premium pull-up formats.
Nigeria
The Lagos-Abuja corridor presents underpenetrated modern trade infrastructure for pharmacy chain distribution. Licensed drugstore networks serve quality-sensitive segments with dermatologist-endorsed premium tiers. Local converters struggle with hot-melt adhesive formulation expertise delays.
Middle East and Africa and Asia Pacific Baby Diaper Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa and Asia Pacific baby diaper market. Integrated multinationals with captive pulp sourcing anchor volume positions in Gulf hypermarkets and Indian modern trade. Three archetypes dominate: petrochemical-backed polymer suppliers, provincial wholesale network operators, and subscription-platform direct-to-consumer brands. Competitive moves concentrate on backward integration into fluff pulp sourcing and regional joint ventures for SAP procurement security.
Among Asia-Pacific-based hygiene specialists, Hengan International and Unicharm Corporation occupy positions within the mid-tier distribution archetype, while Procter & Gamble anchors the premium-tier vector through super-absorbent polymer R&D scale. These three exemplify how geographic origin and corporate structure map to competitive positioning: the Hong Kong-listed entity represents provincial network dominance, the Japanese corporation sits within technology-forward innovation tiers, and the American multinational exemplifies integrated brand-and-supply-chain control.
| Leading Market Players |
|---|
| Hengan International |
| Ontex Group |
| Procter & Gamble |
| Essity AB |
| First Quality Enterprises |
| Unicharm Corporation |
| Kao Corporation |
| The Honest Company |
| Kimberly-Clark Corporation |
| Others |
Supply & Pricing Matrix
Sovereign-backed petrochemical producers in Saudi Arabia and South Korea anchor super-absorbent polymer supply, translating feedstock cost advantages into pricing discipline that compresses margin structures for non-integrated diaper manufacturers across the Middle East and Africa and Asia Pacific region. This ownership pattern forces mid-tier competitors toward captive pulp sourcing or regional joint ventures to defend unit economics against integrated multinational pricing power.
Pricing Analysis
The bundled-vs-unbundled service split separates premium-tier subscription models from transactional commodity purchases across distribution channels. Three-tier pricing structure across premium, standard, and economy levels reflects SAP core quality grades and BIS textile labeling compliance tiers. Cost compression in the standard tier is intensifying because fluff pulp input volatility from Nordic forestry cycles feeds through to non-integrated converters. Pharmacy channel buyers in Nigeria's Lagos-Abuja corridor exhibit highest price sensitivity, while China's urban millennial parents demonstrate lowest elasticity on dermatological safety claims.
Supply Chain Analysis
Certification/qualification gating under China's NMPA migration limits and India's BIS skin-contact disclosure rules filters substandard imports from regional supply chains. Manufacturing concentrates in Saudi Arabia's Eastern Province petrochemical corridors, South Korea's chemical parks, and China's Sichuan-Yunnan bamboo cellulose belt. Raw material dependencies rest on petroleum-derived SAP, Nordic fluff pulp, and fast-regenerating bamboo fibers. Single-source vulnerability from Saudi Aramco-affiliated complexes controlling regional polymer output creates procurement bottlenecks. Distribution runs through Gulf hypermarket chains, Indonesia's marketplace fulfillment platforms, and Nigeria's licensed pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's SAMR absorbent material labeling transparency rules and Gulf state extended producer responsibility frameworks continuously raise compliance thresholds that filter marginal competitors and consolidate share among certified manufacturers.
For Market Incumbents: Acquire captive fluff pulp conversion assets in India's Maharashtra-Gujarat industrial belt to offset Nordic pulp price volatility threatening non-integrated margin structures. Deepen backward integration into SAP procurement through joint ventures with Saudi petrochemical complexes, while accelerating MOHAP biodegradable certification to preempt Gulf circular economy mandates that will disqualify uncertified competitors from government procurement channels. For New Entrants and Emerging Players: Plant-based super-absorbent polymer hybrid formulations offer a technology-first wedge into Saudi Arabia and UAE premium tiers where MOHAP biodegradability targets create first-mover advantage for drop-in polymer substitutes. Target Indonesia's online platform channel where subscription-based replenishment algorithms bypass entrenched wholesale markups, and leverage marketplace fulfillment infrastructure to undercut multinational brand pricing with direct-to-home delivery synchronized to consumption patterns. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier provincial wholesale network operators in China lacking integrated polymer laboratories to meet SAMR reformulation timelines. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone, with certified domestic manufacturers positioned to capture shelf space vacated by import-reliant brands facing 6-12 month reformulation lags. The signal to watch is BIS product registration cycle extensions that strain new entrant balance sheets and accelerate consolidation toward compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluff Pulp Sourcing | Captive supply from India's Maharashtra-Gujarat belt insulates margins against Nordic forestry price cycles. |
| Biodegradable Certification Investment | Dual MOHAP and EU REACH compliance unlocks Gulf government procurement and European export channels. |
| Subscription Platform Partnership | Indonesia's marketplace fulfillment models bypass wholesale markups and lock in 90-day purchase cycles. |
| Regional SAP Joint Venture | Partnerships with Saudi Aramco-affiliated complexes secure polymer supply against procurement bottlenecks. |
| Provincial Wholesale Network Acquisition | China's BIS-compliant domestic distributors capture shelf space from lagging import-reliant competitors. |
Research Methodology
Coverage spans the Middle East and Africa and Asia Pacific region, with primary inputs from each major manufacturing hub and demand center. The approach combines structured interviews with brand managers at multinational hygiene companies, category buyers at Gulf hypermarket chains, procurement leads at Saudi petrochemical complexes, and supply planners at Indonesian marketplace platforms, validated against secondary sources including NMPA regulatory filings, BIS textile standards documentation, SAMR labeling directives, MOHAP circular economy frameworks, and customs trade records for SAP and fluff pulp flows. Bottom-up channel volume estimates triangulate against top-down macroeconomic consumption projections.
Granularity-level framing models product type, material composition, distribution channel, and age group dimensions at country-level resolution across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by pricing tier mix and channel margin structures. Forecast inputs incorporate NMPA migration limit implementation timelines, BIS registration cycle assumptions, and Gulf extended producer responsibility rollout schedules.
The model holds under stable regulatory enforcement intensity and uninterrupted petrochemical supply; deviation in China-Saudi diplomatic relations or Nordic pulp harvest disruptions would shift polymer availability and pricing assumptions materially. A model refresh is warranted upon material change in SAMR labeling transparency enforcement or MOHAP biodegradable procurement mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Adult Diapers Market
Baby Diapers
North America Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
United States Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
China Pant Type Adult Diaper Market