
 East Africa Baby Diaper Market | 2026-2036
East Africa Baby Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Baby Diaper Market Foresight
Modular diaper sizing is decoupling bulk purchase behavior from traditional newborn-centric assortments in East African retail. Procter & Gamble leverages its regional supply infrastructure to sustain shelf dominance across Kenyan supermarket chains. Ontex Group competes through private-label partnerships that anchor pharmacy-channel penetration in Uganda and Tanzania. Kimberly-Clark Corporation differentiates via localized absorbency engineering calibrated for humid climates.
East Africa baby diapers comprise layered absorbent hygiene articles engineered with superabsorbent polymer cores, non-woven topsheets, and elasticized leg cuffs designed to contain infant excreta across four to twelve-hour wear cycles. Disposable diapers command the dominant value share due to convenience premiums among working parents, while biodegradable materials represent the fastest-growing material segment as urban waste-management regulations tighten. Online retailers capture expanding margin pools by bypassing traditional distributor markups in secondary cities.
Kenya's Bureau of Standards enforces absorbent hygiene product safety protocols that shape import documentation and local manufacturing compliance costs. Tanzania's national standards body and Uganda's UNBS apply parallel but non-harmonized testing regimes that fragment cross-border product registration. Ethiopia's national quality infrastructure agency adds further procedural divergence for entrants targeting the Horn of Africa corridor. Stakeholders must monitor regulatory convergence negotiations under the East African Community framework to anticipate unified compliance obligations.
Market Dynamics
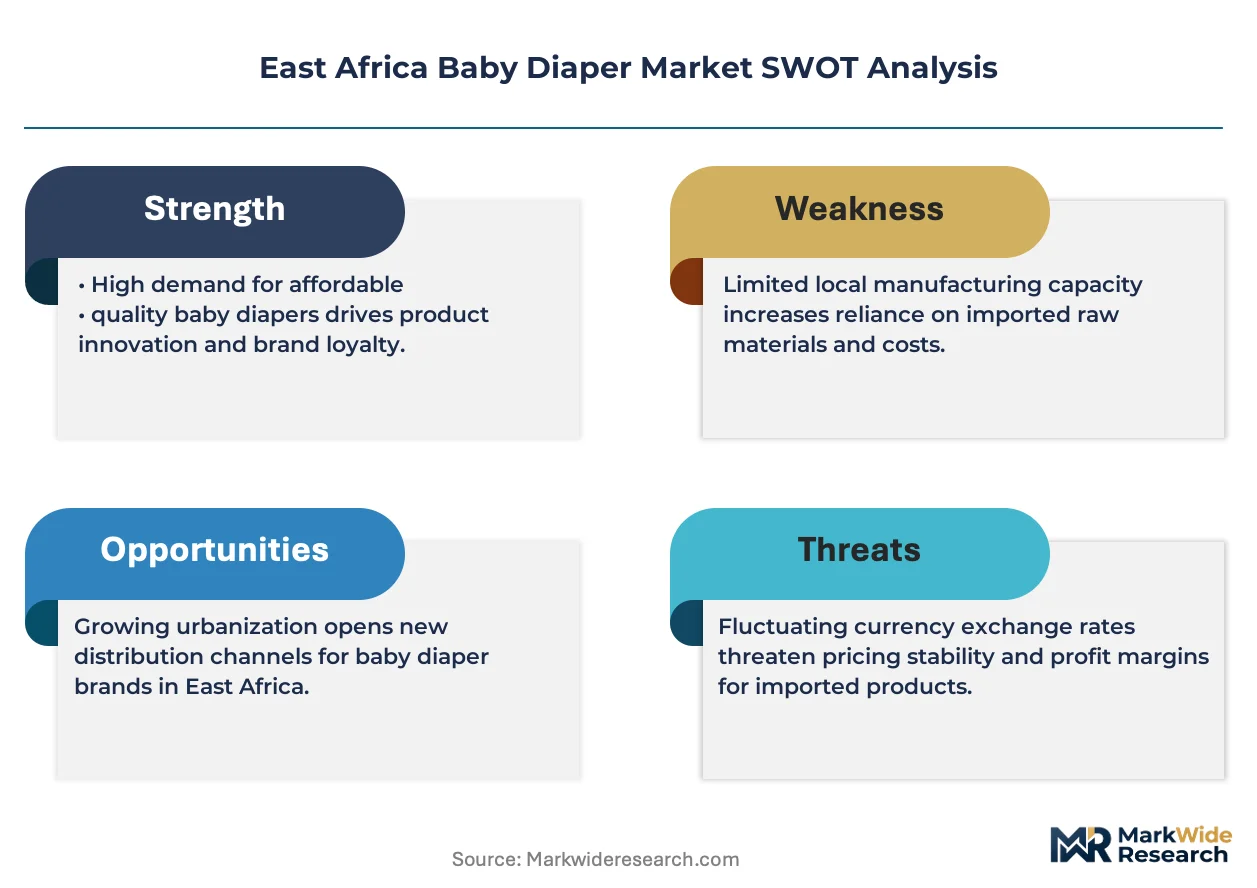
KEBS enforcement of absorbent hygiene product safety codes is compressing import timelines and elevating compliance costs for non-local manufacturers, fundamentally restructuring competitive access to Kenyan retail channels.
Growth Catalysts
- Urban Middle-Class Expansion:Nairobi, Kampala, and Dar es Salaam households are driving premium disposable diaper adoption through modern retail penetration and dual-income family structures.
- East African Community Convergence:Regulatory harmonization negotiations under the EAC framework promise unified compliance obligations that will streamline cross-border product registration.
- Superabsorbent Polymer Engineering:Advanced polymer cores calibrated for humid tropical climates are extending wear-cycle performance and reducing leakage complaints in coastal East African cities.
Market Restraints
- Input Cost Volatility:Fluctuating petroleum-derived polymer prices squeeze margins for manufacturers dependent on imported superabsorbent resin feedstocks.
- Regulatory Fragmentation:Non-harmonized testing regimes across Tanzania's national standards body, Uganda's UNBS, and Ethiopia's quality infrastructure agency multiply registration costs for regional entrants.
- Cloth Diaper Resurgence:Reusable cloth alternatives gain traction among environmentally conscious urban consumers responding to tightening municipal waste-management regulations.
Strategic Opportunities
- Secondary City E-Commerce:Online retailers bypass traditional distributor markups in secondary cities like Mombasa, Kigali, and Dodoma, capturing expanding margin pools through direct-to-consumer logistics.
- Biodegradable Material Pivot:Urban waste-management regulations in Kenyan and Tanzanian municipalities create procurement preference for compostable diaper components among institutional buyers.
- Pharmacy Channel Anchoring:Private-label partnerships with pharmacy chains in Uganda and Tanzania offer premium positioning outside supermarket price competition.
Industry Challenges
- Technical Certification Timelines:Absorbent hygiene product safety testing across multiple national standards bodies extends product launch cycles by six to twelve months.
- Supply Chain Reconfiguration:Manufacturers must establish localized warehousing to satisfy KEBS documentation requirements while managing inventory carrying costs in low-turnover secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Baby Diaper Market |
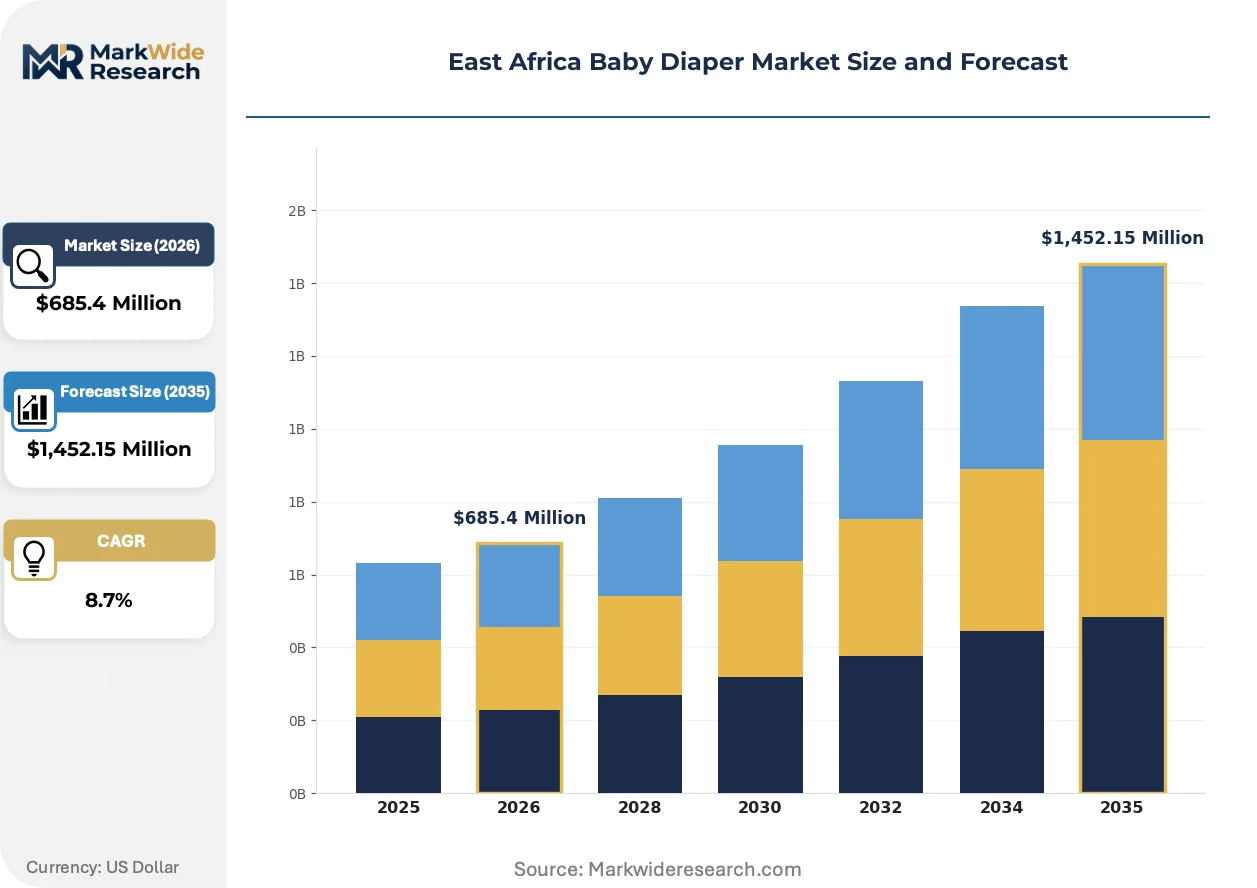
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Diapers, Cloth Diapers, Training Pants, Swim Diapers Distribution Channel: Supermarkets, Pharmacies, Online Retailers, Specialty Stores Size: Newborn, Size 1, Size 2, Size 3 Material: Non-Woven Fabrics, Polyethylene, Cotton, Biodegradable Materials |
| Companies Covered | Kao Corporation, Essity AB, Procter & Gamble, Hengan International Group, Ontex Group, Unicharm Corporation, Johnson & Johnson, Batterjee Paper Products, Kimberly-Clark Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Baby Diaper Market Shifts & Advancements
Modular sizing systems and climate-calibrated absorbency engineering are displacing traditional newborn-centric assortments, while digital distribution models compress channel margins across East African urban corridors.
Plant-based superabsorbent polymers derived from agricultural waste streams are absorbing market share from petroleum-based alternatives as Nairobi and Dar es Salaam municipalities implement organic waste diversion mandates. Premium diaper manufacturers in Kenya are adopting these materials fastest, with pharmacy-channel private-label suppliers following within eighteen to twenty-four months. This material transition is absorbing price premiums previously captured by imported European brands.
KEBS absorbent hygiene product safety protocols are mandating enhanced documentation for polymer composition and skin-contact certification, forcing importers to establish local testing partnerships or face extended customs clearance. Tanzanian and Ugandan standards bodies are observing Kenyan enforcement patterns, signaling probable regulatory alignment within the EAC framework. Manufacturers with existing KEBS compliance infrastructure gain first-mover advantage in anticipating parallel Ugandan and Tanzanian requirements.
Urban working parents in Nairobi and Kampala are consolidating diaper purchases through subscription-based e-commerce platforms that guarantee monthly delivery volumes at fixed pricing. Traditional supermarket chains respond with loyalty-program bundling, but pharmacy channels capture the highest-margin premium segments through clinician endorsement. This channel rotation is most visible in Kenyan middle-class households with consistent digital payment access.
East Africa Baby Diaper Market Segmentation
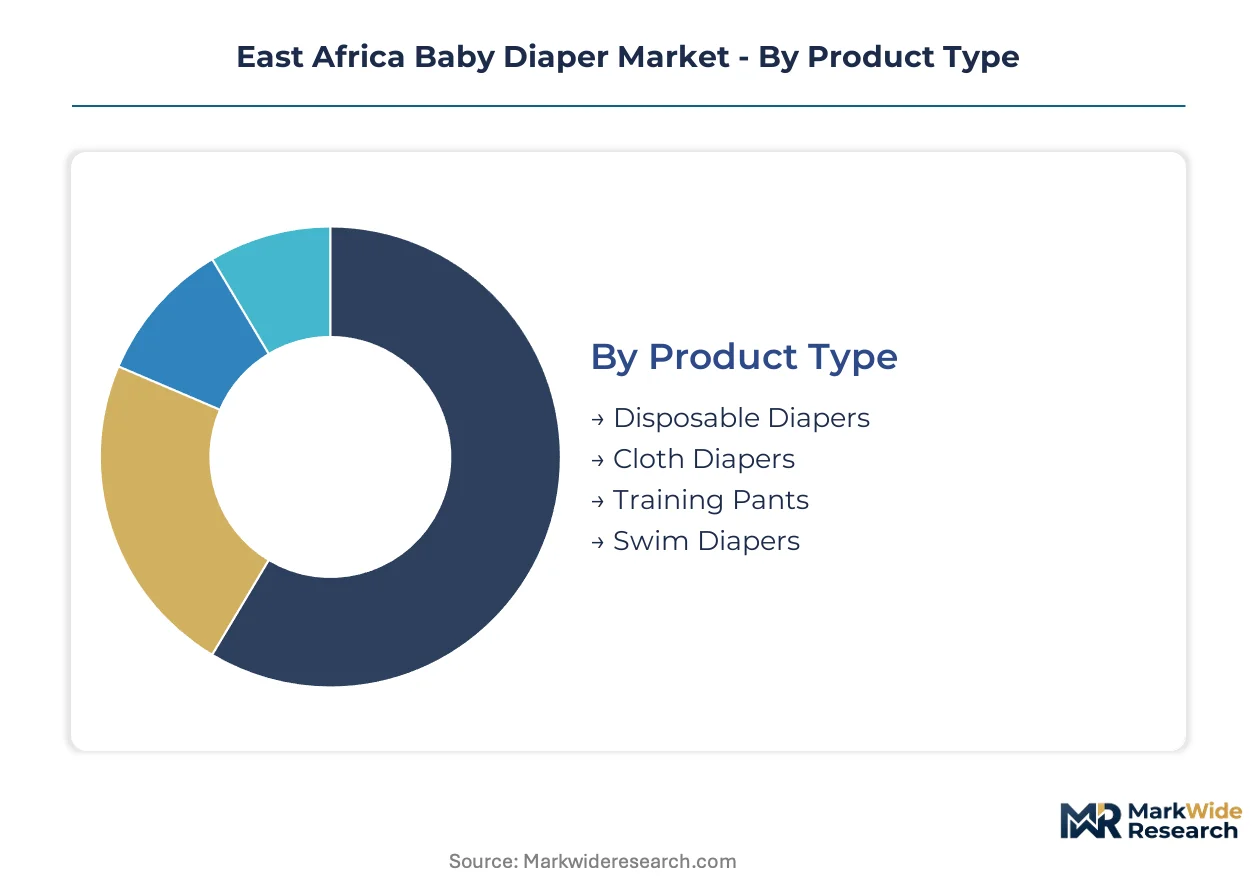
Diaper purchasing patterns across East Africa fragment sharply by urban infrastructure, income stratification, and regulatory exposure. Manufacturers must align product specifications and channel strategies with distinct buyer profiles in Nairobi, Kampala, and Dar es Salaam.
Product Type:
Working parents in dual-income Nairobi households prioritize convenience and extended wear cycles, while cost-conscious buyers in secondary cities balance unit economics against laundering labor.
- Disposable Diapers:Layered absorbent hygiene articles with superabsorbent polymer cores and elasticized leg cuffs engineered for four-to-twelve-hour containment. Demand concentrates among urban middle-class households in Nairobi and Dar es Salaam where modern retail penetration supports premium pricing and working mothers favor time-saving formats.
- Cloth Diapers:Reusable cotton or synthetic fabric systems requiring manual washing and drying cycles. Adoption is climbing fastest among environmentally conscious consumers in Kenyan municipalities with tightening organic waste diversion mandates.
- Training Pants:Pull-up style absorbent garments designed for toddler mobility and self-dressing transition.
- Swim Diapers:Non-absorbent containment garments for water environments with specialized elastic barriers.
Disposable Diapers leads volumes today; Cloth Diapers is gaining share fastest.
Distribution Channel:
Channel selection determines margin capture, certification burden, and customer access patterns across East African urban corridors.
- Supermarkets:Modern retail chains with centralized procurement and standardized shelving fees. Shelf space in Nairobi and Kampala supermarket chains is consolidating under Procter & Gamble's regional supply infrastructure dominance.
- Pharmacies:Clinician-endorsed retail environments with premium positioning and private-label partnerships. Ontex Group anchors penetration here in Uganda and Tanzania through trusted health-channel associations.
- Online Retailers:Direct-to-consumer platforms bypassing traditional distributor markups. Subscription models capture expanding margin pools in secondary cities like Mombasa and Kigali where digital payment access is deepening.
- Specialty Stores:Niche retail formats targeting organic and biodegradable product preferences.
Supermarkets leads volumes today; Online Retailers is expanding most quickly.
Size:
Modular sizing systems are decoupling bulk purchase behavior from traditional newborn-centric assortments in East African retail.
- Newborn:Preemie and zero-to-three-month specifications with umbilical cord cutouts and ultra-soft linings.
- Size 1:Four-to-eleven-pound infant capacity with gentle waistband elasticity.
- Size 2:Twelve-to-eighteen-pound specifications representing the volume anchor for established diapering households.
- Size 3:Sixteen-to-twenty-eight-pound toddler capacity with enhanced mobility engineering and extended absorbency cores calibrated for humid tropical climates.
Size 2 leads volumes today; Size 3 is climbing the fastest.
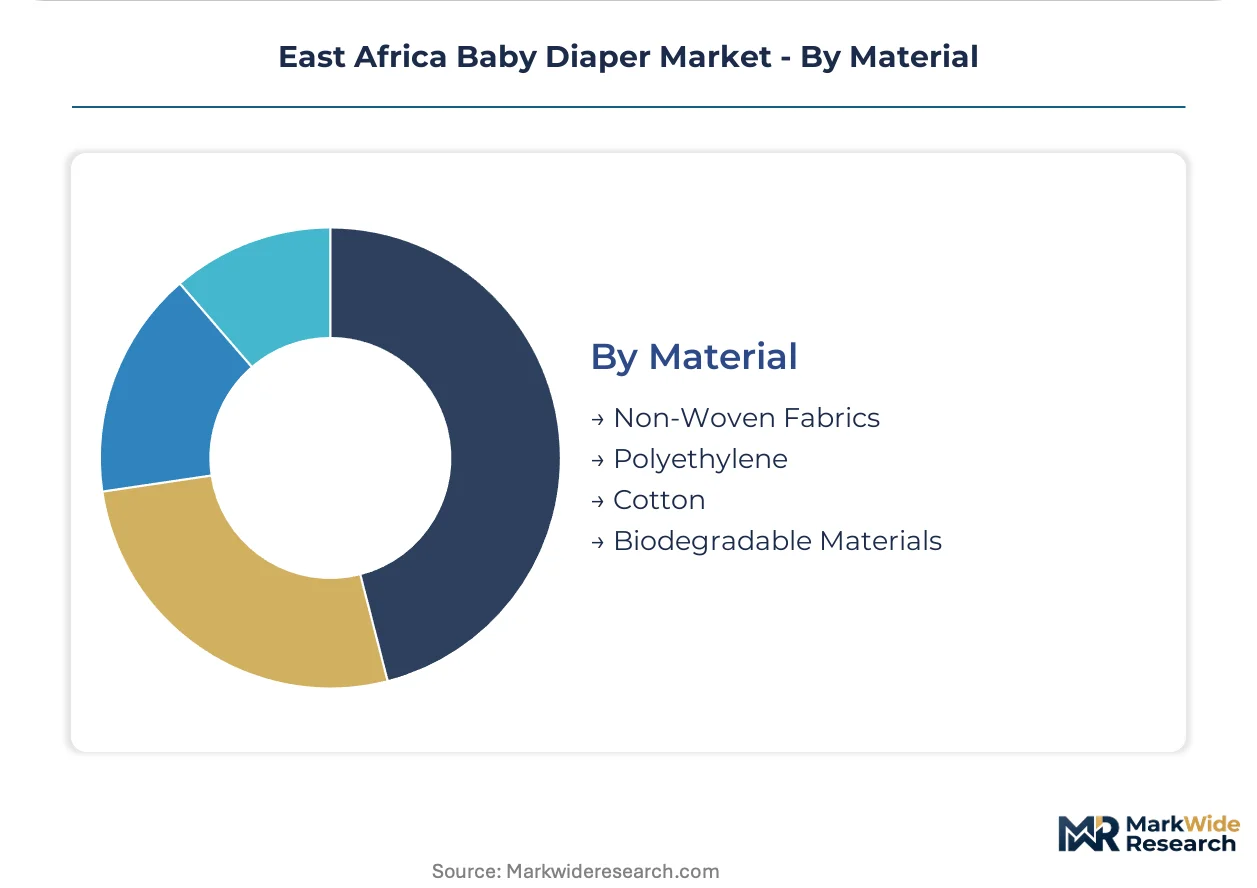
Material:
Raw material selection shapes compliance costs, waste management liability, and price positioning against petroleum price volatility.
- Non-Woven Fabrics:Spunbond-meltblown-spunbond polypropylene topsheets providing skin contact softness and liquid acquisition speed. Kenyan manufacturers are adopting these fastest for KEBS skin-contact certification compliance.
- Polyethylene:Petroleum-derived backsheet films providing moisture barrier protection. Price volatility in imported resin feedstocks is squeezing margins for manufacturers without backward integration into polymer supply.
- Cotton:Natural fiber absorbent layers with breathable properties and reduced dermatological irritation risk.
- Biodegradable Materials:Plant-based superabsorbent polymers derived from agricultural waste streams. Nairobi and Dar es Salaam municipal organic waste mandates are creating procurement preference for compostable components.
Non-Woven Fabrics leads volumes today; Biodegradable Materials shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Disposable diaper manufacturing first scaled in East Africa during the early 2000s when multinational consumer goods firms established regional distribution hubs in Nairobi. Kenya's modern retail infrastructure and stable birth rates created the foundational demand base that neighboring markets later replicated.
Kenya
Urban middle-class households in Nairobi and Mombasa drive premium disposable diaper adoption through supermarket chains and subscription e-commerce platforms. Kenya's Bureau of Standards enforces absorbent hygiene product safety codes that compress import timelines and elevate compliance documentation requirements. Manufacturing and distribution clusters concentrate in Nairobi's industrial zones where localized warehousing satisfies KEBS inspection protocols.
Tanzania
Dar es Salaam's dual-income families favor extended-wear diaper formats calibrated for humid coastal climates. Tanzania's national standards body applies parallel but non-harmonized testing regimes that fragment cross-border product registration with Kenyan protocols. Retail penetration deepens fastest in Dar es Salaam's modern trade corridors while secondary cities like Dodoma attract direct-to-consumer digital distribution.
Uganda
Kampala households balance unit economics against laundering labor, creating demand bifurcation between premium disposables and reusable cloth alternatives. Uganda's UNBS maintains independent certification requirements that multiply registration costs for regional entrants lacking existing KEBS compliance infrastructure. Pharmacy-channel private-label partnerships anchor premium positioning outside supermarket price competition in Kampala's health retail corridors.
Ethiopia
Addis Ababa's emerging middle class exhibits rising convenience premiums among working parents in formal sector employment. Ethiopia's national quality infrastructure agency adds procedural divergence for entrants targeting the Horn of Africa corridor with distinct documentation requirements. Distribution networks concentrate in Addis Ababa's commercial districts while regulatory convergence negotiations under the East African Community framework remain pending.
Rwanda
Kigali's environmentally conscious consumers respond to municipal organic waste diversion mandates with climbing adoption of biodegradable diaper components. Rwanda's national standards body observes Kenyan enforcement patterns, signaling probable regulatory alignment within regional harmonization timelines. Digital payment access in Kigali enables subscription-based e-commerce models that bypass traditional distributor markups in this compact urban market.
East Africa Baby Diaper Market Competitive Landscape
The competitive structure tilts toward multinational consumer goods conglomerates with established regional supply infrastructure. Market access concentrates around players possessing KEBS certification capabilities and localized warehousing networks. Three archetypes dominate: global hygiene giants with supermarket shelf dominance, private-label specialists anchoring pharmacy channels, and regional distributors leveraging e-commerce logistics in secondary cities. Dominant competitive moves include strategic partnerships with pharmacy chains and portfolio diversification into biodegradable material formats.
Among the established multinational tier, Procter & Gamble occupies a position exemplifying supermarket-channel consolidation through regional supply infrastructure. Ontex Group sits within the private-label specialist archetype, representing pharmacy-channel penetration strategies in Uganda and Tanzania. Kimberly-Clark Corporation anchors the climate-calibrated engineering segment, exemplifying absorbency optimization for humid tropical conditions.
| Leading Market Players |
|---|
| Kao Corporation |
| Essity AB |
| Procter & Gamble |
| Hengan International Group |
| Ontex Group |
| Unicharm Corporation |
| Johnson & Johnson |
| Batterjee Paper Products |
| Kimberly-Clark Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into superabsorbent polymer supply anchors both manufacturing resilience and margin defense for East African diaper producers navigating petroleum feedstock volatility. Kenyan manufacturers with captive resin sourcing command pricing power against import-dependent competitors facing KEBS compliance delays and currency exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments Nairobi supermarket shelves by certification grade and absorbency performance. Price differentiation hinges on KEBS skin-contact certification status and polymer core engineering calibrated for humid climates. Cost compression in the economy tier is intensifying because Ugandan and Tanzanian secondary markets absorb lower-specification imports bypassing full compliance documentation. Pharmacy-channel buyers in Kampala and Dar es Salaam exhibit lowest price sensitivity due to clinician endorsement premiums, while mass-market supermarket purchasers in Mombasa and Dodoma drive hard unit-economics negotiations.
Supply Chain Analysis
Reverse-logistics infrastructure for biodegradable diaper collection and composting remains undeveloped across East African urban corridors, constraining circular-economy pricing models. Geographic supply concentration centers on Saudi Arabia and South Korea for superabsorbent polymer feedstocks, with China dominating non-woven topsheet material flows. Raw material dependencies rest on petroleum-derived polyethylene backsheet films, imported elastic leg-cuff components, and agricultural-waste-derived plant-based polymers. Single-source vulnerability in Saudi resin supply creates exposure to Red Sea logistics disruption. Distribution runs through Nairobi-based regional warehousing clusters serving supermarket chains, with pharmacy-channel direct delivery bypassing these nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's baby diaper market functions as a regulatory compounder where KEBS enforcement of absorbent hygiene product safety codes continuously elevates compliance barriers and consolidates advantage among certified incumbents.
For Market Incumbents: Lock in pharmacy-channel exclusivity through private-label partnerships that embed clinician endorsement into brand equity. Expand backward integration into agricultural-waste polymer sourcing to capture biodegradable material premiums before Ugandan and Tanzanian standards bodies replicate Kenyan organic waste mandates. Defend against subscription-based e-commerce disintermediation by anchoring loyalty-program bundling in Nairobi's dual-income households with consistent digital payment access.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for bypassing Procter & Gamble's supermarket shelf dominance and Ontex Group's pharmacy-channel anchoring. Target secondary cities like Kigali and Dodoma where distributor markups remain elevated and digital payment penetration is deepening fastest. Pursue white-label manufacturing partnerships with East African Community-registered facilities to compress KEBS certification timelines.
For Investors and Strategic Acquirers: Roll-up economics work for regional private-label manufacturers with existing KEBS compliance infrastructure because regulatory fragmentation multiplies registration costs for unconsolidated players lacking cross-border documentation capabilities. Long-term viability hinges on exposure to biodegradable material transitions and subscription-channel revenue mix. Monitor EAC regulatory convergence negotiations for unified compliance obligation signals that would accelerate consolidation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Transition | Plant-based polymer adoption captures Nairobi municipal procurement preferences ahead of regional mandate replication. |
| Pharmacy Channel Expansion | Clinician-endorsed positioning in Kampala and Dar es Salaam extracts premium pricing outside supermarket competition. |
| Subscription E-Commerce Launch | Direct-to-consumer logistics in Mombasa and Kigali bypass traditional distributor markups and capture recurring revenue. |
| KEBS Compliance Infrastructure Investment | Localized testing partnerships compress customs clearance timelines and anticipate Ugandan and Tanzanian regulatory alignment. |
| Agricultural Waste Polymer Sourcing | Backward integration into regional agricultural residue supply hedges petroleum price volatility and satisfies organic waste mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged supply chain managers at Nairobi manufacturing clusters, category buyers at Kenyan supermarket chains, pharmacy procurement leads in Kampala and Dar es Salaam, and regulatory affairs specialists familiar with KEBS and EAC harmonization negotiations. Secondary validation drew from East African Community trade statistics, Kenya Bureau of Standards compliance bulletins, UNBS certification registries, and customs documentation patterns for absorbent hygiene product imports. Bottom-up demand modeling triangulated against top-down macroeconomic projections for urban middle-class household formation.
Segment-weighting approaches distributed volume and value estimates across product type, distribution channel, size tier, and material composition dimensions. The analytical framework applied growth rate derivation across the projection horizon based on birth-rate stability indices, modern retail penetration curves, and digital payment adoption trajectories. Modeled inputs included superabsorbent polymer price volatility assumptions and municipal waste-management regulation enforcement intensity scores for Nairobi, Dar es Salaam, and Kampala.
Polymer feedstock price shocks, EAC regulatory convergence delays, and cloth diaper substitution acceleration are the dominant revision risks to demand forecasts. Forecasts reflect assumptions about KEBS enforcement consistency and urban infrastructure investment continuity. Practitioners should monitor EAC harmonization negotiation communiques, Nairobi municipal organic waste mandate expansion, and subscription-platform customer acquisition costs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
United States Diaper Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Smart Diaper Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Baby Diapers Market
Baby Diapers
Smart Connected Diaper Market