
 Biodegradable Baby Diapers Market | 2026-2036
Biodegradable Baby Diapers Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Baby Diapers Market Outlook
Subscription-first millennial parents is collapsing the traditional supermarket-dominant purchase model for conventional diapers. GroVia leverages direct-to-consumer bundling to sustain recurring revenue from cloth-hybrid converts. The Honest Company anchors premium positioning through clean-ingredient transparency across its diaper portfolio. Seventh Generation competes on shelf presence in natural grocery channels with USDA BioPreferred-certified formulations.
Biodegradable baby diapers are absorbent hygiene products constructed with plant-derived substrates such as wood pulp and corn starch, engineered to decompose under industrial composting conditions within weeks rather than centuries. Their primary commercial purpose is to deliver leak-protection performance comparable to petroleum-based disposables while eliminating persistent plastic waste streams. Wood pulp and bamboo fiber segments lead material adoption due to established supply chains and favorable absorbency-to-weight ratios. Online retail channels capture the fastest-growing transaction volume as subscription mechanics reduce customer acquisition costs for emerging brands. Standard diapers occupy the largest revenue pool, though overnight variants command margin premiums through higher unit pricing and lower price elasticity among sleep-deprived parents.
The EU Green Deal and REACH frameworks restrict petroleum-based superabsorbent polymers in single-use products, compelling reformulation toward bio-based alternatives. FDA and EPA oversight in the United States shapes skin-contact safety standards and compostability labeling claims that determine market access for imported brands. Stakeholders must monitor composting infrastructure build-out rates and certification harmonization between national standards bodies to anticipate which geographies will absorb expanded production capacity.
Market Dynamics
Millennial and Gen-Z parents are dismantling the supermarket-dominant purchase model for infant hygiene, forcing manufacturers to rebuild distribution around subscription mechanics and direct-to-consumer bundling. This generational turnover is compressing legacy retail margins while rewarding brands that capture recurring revenue through digital-first engagement.
Growth Catalysts
- EU Green Deal enforcement:REACH framework restrictions on petroleum-based superabsorbent polymers are compelling manufacturers to reformulate with bio-based alternatives. Industrial composting infrastructure expansion in Germany, France, and the Netherlands creates viable end-of-life pathways for certified products.
- Wood pulp supply chain maturity:Established Nordic and North American fiber processing capacity delivers favorable absorbency-to-weight ratios at scale. This material substrate avoids the price volatility plaguing newer bio-polymer alternatives.
- Subscription mechanics:Direct-to-consumer bundling models reduce customer acquisition costs for emerging brands while locking in predictable demand patterns. Sleep-deprived parents exhibit low price elasticity for overnight variants delivered on auto-replenishment cycles.
Market Restraints
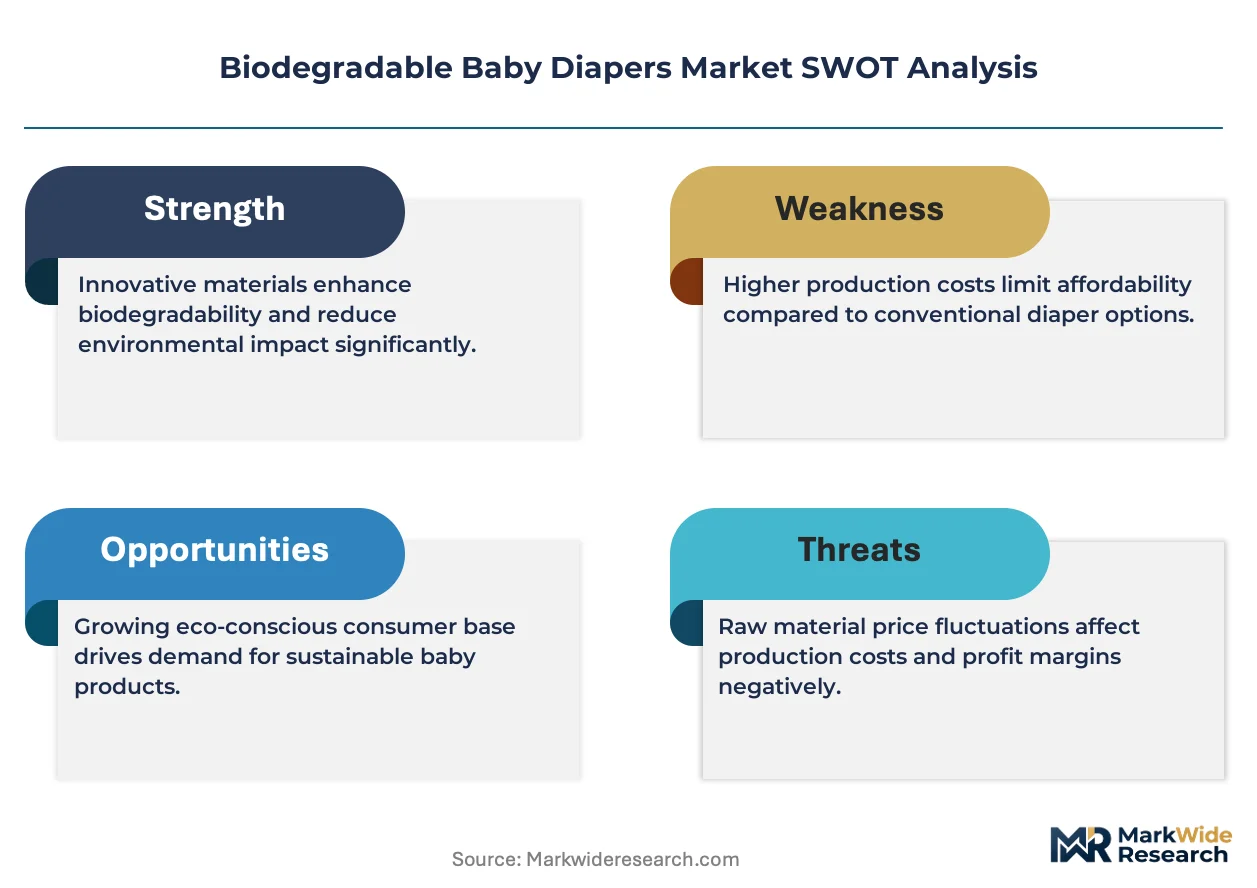
- Corn starch input cost volatility:Agricultural commodity price swings and competing food-sector demand create margin pressure for manufacturers dependent on this substrate. Drought cycles in major producing regions amplify supply uncertainty.
- Industrial composting infrastructure gaps:Municipal facilities capable of processing certified biodegradable diapers remain concentrated in Northern European markets. Home composting conditions fail to achieve the temperature and moisture profiles required for decomposition.
- Performance parity limitations:Bio-based superabsorbent polymers currently deliver lower fluid retention capacity per gram versus petroleum-derived sodium polyacrylate. Overnight and extended-wear applications remain technically challenging for pure biodegradable formulations.
Strategic Opportunities
- Underpenetrated Southern European markets:Spain and Italy lack mature municipal composting networks but show rising parent demand for plastic-free alternatives. Early entrants can shape category education before infrastructure catches up.
- USDA BioPreferred certification leverage:Federal procurement preference programs create institutional demand channels for certified products. Military base exchanges and government childcare facilities represent captive volume pools.
- Cloth-hybrid convergence:Reusable outer shell systems paired with biodegradable disposable inserts blend sustainability credentials with convenience. This architecture addresses the laundering burden that blocks full cloth diaper adoption.
Industry Challenges
- Compostability certification timeline fragmentation:Harmonization gaps between TÜV Austria OK Compost, BPI, and national standards bodies force redundant testing expenditures. Multi-market launches require sequential rather than parallel certification pathways.
- Supply chain reconfiguration friction:Transitioning from petroleum-based to bio-based input streams demands new supplier qualification protocols and quality control systems. Existing contract manufacturers lack experience with hygroscopic plant fiber handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Baby Diapers Market |
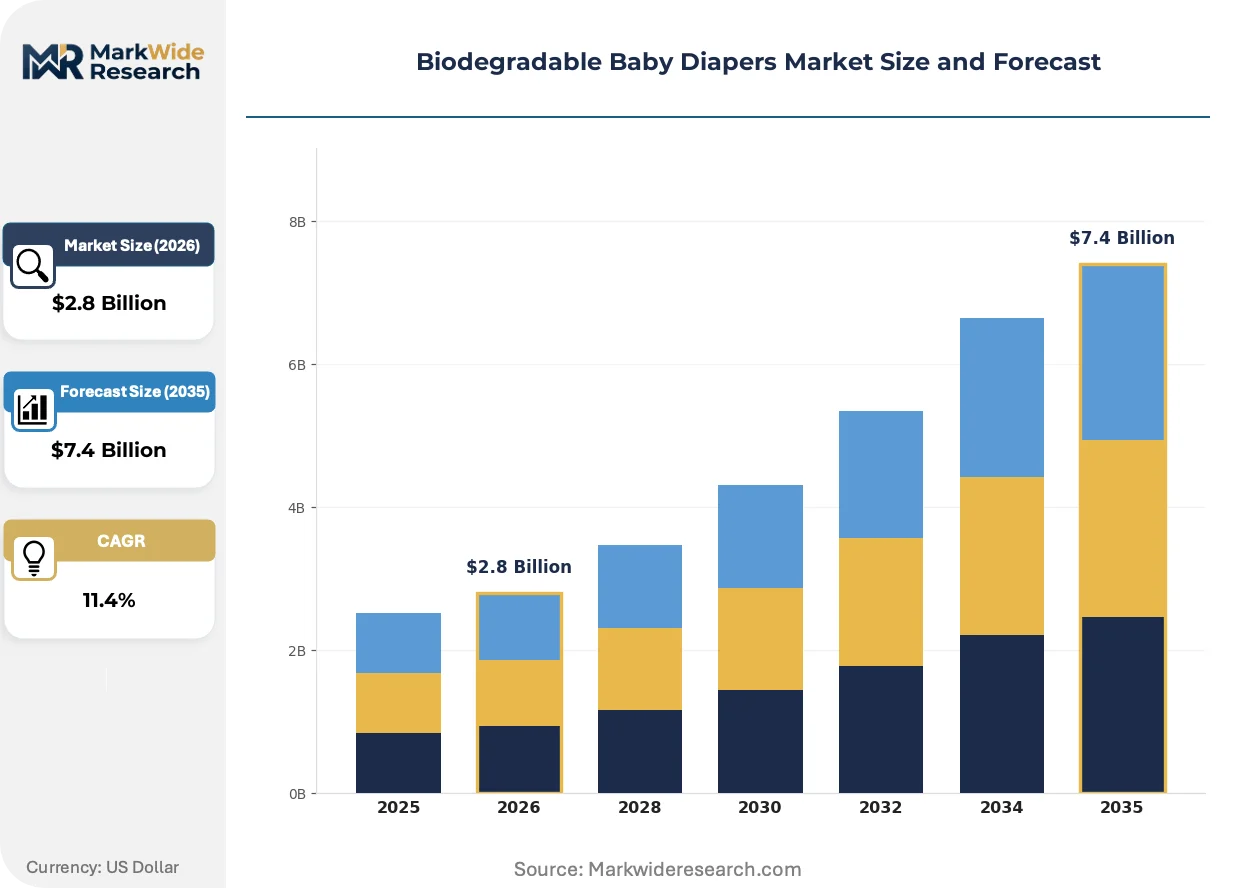
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Diapers, Training Pants, Overnight Diapers, Swim Diapers Material: Wood Pulp, Corn Starch, Bamboo Fiber, Bioplastics Packaging Type: Cartons, Bags, Pouches, Wraps Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Dyper, GroVia, The Honest Company, Andy Pandy, Nest Baby Diapers, Seventh Generation, Naty AB, Kimberly-Clark Corporation, Bambo Nature, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Baby Diapers Market Strategic Shifts
Material science breakthroughs and regulatory pressure are converging to redefine performance benchmarks for sustainable infant hygiene. Three interconnected developments are restructuring competitive advantage in this category.
Bamboo fiber processing advances are displacing wood pulp in premium product tiers. Japanese textile engineers have refined mechanical softening techniques that preserve tensile strength while achieving cotton-like hand feel. European organic retailers are accelerating SKU expansion for bamboo-dominant formulations, compressing the price premium versus conventional pulp substrates.
REACH Annex XVII restrictions on microplastic-containing hygiene products are forcing reformulation of acquisition and distribution layers. ECHA guidance documents now explicitly classify conventional plastic backsheet films as microplastic-releasing under use conditions. German and French manufacturers are racing to commercialize PLA-based breathable barriers ahead of 2027 enforcement deadlines.
Subscription-native parents are abandoning stock-up shopping patterns in favor of algorithmic replenishment. Digital-native brands capture purchase data that enables predictive sizing transitions as infants grow. This behavioral shift is most pronounced in Dutch and Danish urban markets where delivery density supports same-day fulfillment economics.
Biodegradable Baby Diapers Market Segmentation
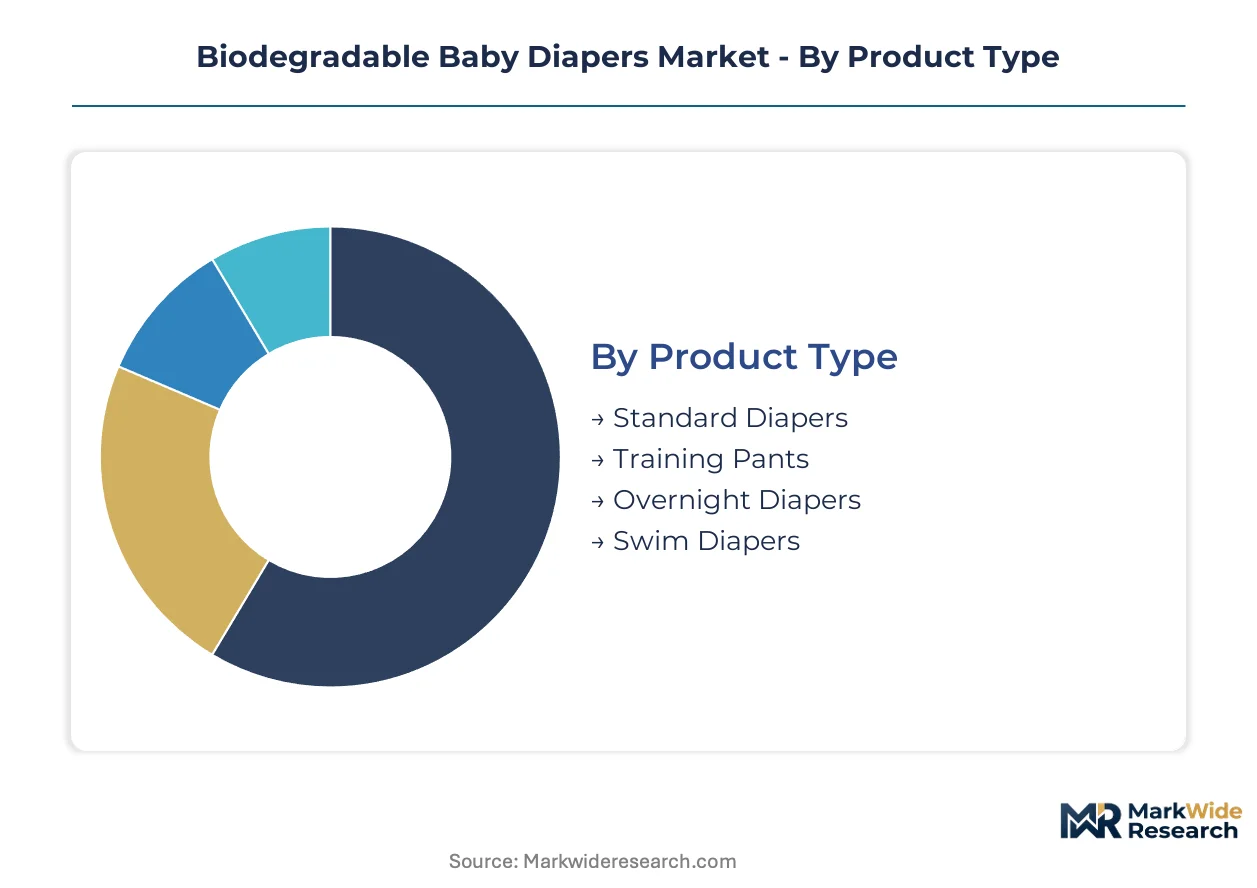
Segmentation in biodegradable baby diapers reveals how regulatory pressure and parental purchasing behavior fragment demand across technical specifications and channel preferences. Manufacturers must align material choices with composting infrastructure availability while matching packaging formats to subscription versus retail purchase patterns.
Product Type:
REACH Annex XVII restrictions on petroleum-based superabsorbent polymers force differentiated reformulation strategies across use-case scenarios, with overnight variants demanding the most technical innovation.
- Standard Diapers:Daytime-use products engineered with wood pulp acquisition layers and PLA breathable backsheets. German and French parents purchase these through municipal composting programs where TÜV Austria OK Compost certification ensures end-of-life processing.
- Training Pants:Pull-up configurations with elasticized waistbands constructed from bio-based stretch films. Dutch retailers report climbing demand for these as toddlers transition from standard diapers, though elastic recovery performance lags petroleum-based alternatives.
- Overnight Diapers:Extended-wear formulations requiring higher fluid retention capacity. Bio-based superabsorbent polymers currently deliver lower grams-of-fluid-retained-per-gram-of-material, creating technical barriers for pure biodegradable architectures.
- Swim Diapers:Hydrophobic outer layers designed for aquatic environments without swelling degradation. These occupy a niche volume position due to limited use occasions and competing reusable cloth alternatives.
Established volume favors Standard Diapers; emerging adoption favors Training Pants as elasticized bio-film technology matures.
Material:
Cost tier differentiation separates mature fiber supply chains from novel bio-polymer alternatives facing agricultural commodity volatility and processing scale constraints.
- Wood Pulp:Nordic and North American softwood kraft pulp delivers proven absorbency-to-weight ratios with established bleaching and fluffing infrastructure. FDA 21 CFR compliance for skin-contact applications is well-documented across existing suppliers.
- Bamboo Fiber:Mechanical softening advances from Japanese textile engineers now yield cotton-like hand feel without chemical processing. European organic retailers accelerate SKU expansion for this substrate as price premiums compress versus wood pulp.
- Corn Starch:Thermoplastic starch blends for acquisition and distribution layers. Competing food-sector demand and drought cycles in major producing regions create input cost volatility that pressures manufacturer margins.
- Bioplastics:PLA and PHA formulations for breathable barrier films and fastening systems. ECHA microplastic classification guidance is forcing accelerated commercialization timelines ahead of enforcement deadlines.
Supply security concentrates in Wood Pulp; steepest expansion trajectory appears in Bamboo Fiber as premium positioning justifies current cost premiums.
Packaging Type:
Customer type segmentation separates bulk subscription purchasers from trial-size retail samplers, with channel mechanics dictating structural and graphic packaging requirements.
- Cartons:Corrugated shipper formats optimized for direct-to-consumer bundling and subscription box economics. These require FSC-certified fiber content to align with parent sustainability expectations.
- Bags:Flexible polyethylene alternatives for retail shelf presence. Bio-based film structures face heat-seal strength limitations that complicate high-speed filling operations.
- Pouches:Single-unit sampling formats for health store trial programs. Unit economics challenge profitability unless paired with premium pricing tiers.
- Wraps:Minimalist paper-based formats for zero-waste retail concepts. Dutch and Danish urban markets show early adoption of these configurations.
Operational scale favors Cartons; sustainability signaling favors Wraps in urban core demographics.
Distribution Channel:
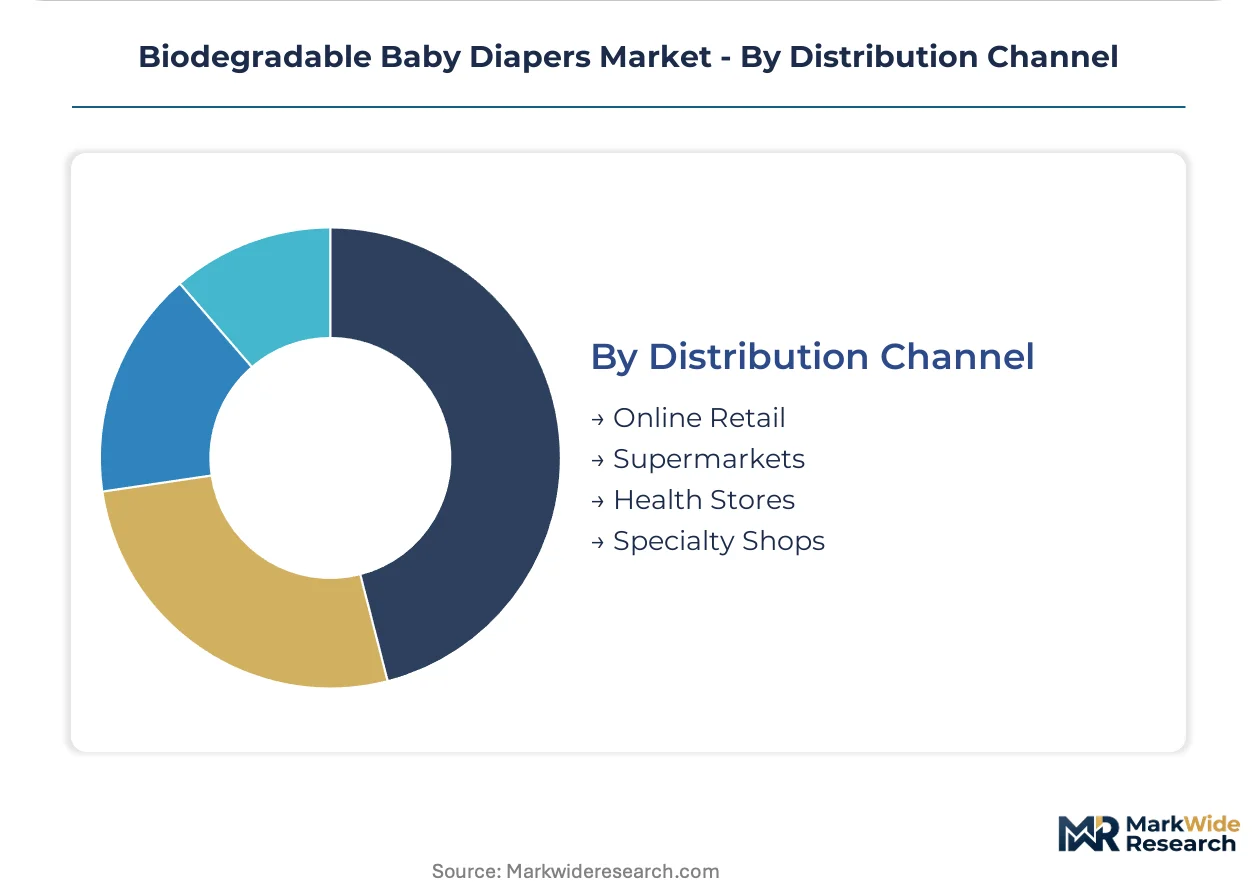
Geography determines channel viability, with composting infrastructure density correlating to health store and specialty shop penetration versus mass retail dominance.
- Online Retail:Subscription-native mechanics with algorithmic sizing transitions as infants grow. Auto-replenishment cycles capture sleep-deprived parents exhibiting low price elasticity.
- Supermarkets:Mass-market shelf presence requiring USDA BioPreferred certification for placement in natural product sets. Legacy petroleum-based diaper margins compress as bio-based alternatives gain linear footage.
- Health Stores:Curated assortment with staff education on composting requirements. These channels concentrate in Germany, France, and the Netherlands where municipal infrastructure supports end-of-life claims.
- Specialty Shops:Boutique maternity and infant-focused retailers with high-touch service models. Cloth-hybrid convergence products find initial traction through these outlets before scaling to broader distribution.
Margin structure favors Online Retail; infrastructure-dependent expansion favors Health Stores in composting-equipped municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine rail corridor and Rotterdam port complex anchor European distribution for compostable hygiene products, while Pacific Northwest hydroelectric grids power Nordic pulp processing facilities serving North American demand.
Germany
Municipal composting networks in Bavaria and Baden-Württemberg process certified diapers through TÜV Austria OK Compost pathways. The EU Green Deal REACH Annex XVII restrictions on petroleum-based superabsorbent polymers force reformulation deadlines by 2027. Berlin-Brandenburg hosts pilot facilities testing industrial-scale decomposition of PLA-based breathable barriers.
France
Parisian parent demand for plastic-free alternatives outpaces available municipal composting capacity in Île-de-France. ECHA microplastic classification guidance now explicitly targets conventional plastic backsheet films. The Lyon biotech corridor attracts PLA and PHA formulation startups racing to commercialize breathable barriers before enforcement deadlines.
Netherlands
Randstad urban density enables same-day subscription fulfillment economics for algorithmic replenishment models. Dutch health stores concentrate staff education on composting requirements where infrastructure supports end-of-life claims. Eindhoven Region polymer research clusters advance bio-based stretch film technology for training pant elasticization.
United States
USDA BioPreferred certification unlocks federal procurement channels at military base exchanges and government childcare facilities. FDA 21 CFR oversight shapes skin-contact safety standards for wood pulp acquisition layers. Pacific Northwest hydroelectric infrastructure powers Nordic pulp processing capacity serving West Coast parent demand.
United Kingdom
London health stores curate biodegradable diaper assortments despite fragmented municipal composting infrastructure across Greater London. The UK Environment Agency deliberates alignment with EU REACH frameworks post-Brexit. Manchester textile engineering clusters experiment with bamboo fiber mechanical softening techniques for premium hand feel.
Biodegradable Baby Diapers Market Competitive Environment
Listed leaders compete with private specialists across certification and channel access dimensions, creating a tiered structure where scale advantages clash with agility in regulatory navigation. The vendor base separates into three archetypes: subscription-native digital brands, legacy CPG players with bio-based line extensions, and Nordic pulp-integrated specialists. M&A activity concentrates on certification asset acquisition, while capacity expansion focuses on PLA film extrusion and bamboo fiber processing.
Within the subscription-native tier, Dyper and GroVia exemplify direct-to-consumer mechanics that collapse traditional supermarket-dominant purchase patterns. The Honest Company anchors premium positioning through clean-ingredient transparency archetypes. These three occupy positions where recurring revenue models and digital-first engagement reward first-mover advantage in algorithmic sizing transitions.
| Leading Market Players |
|---|
| Dyper |
| GroVia |
| The Honest Company |
| Andy Pandy |
| Nest Baby Diapers |
| Seventh Generation |
| Naty AB |
| Kimberly-Clark Corporation |
| Bambo Nature |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles for Nordic wood pulp feedstock concentrate supplier power in Northern Europe while compressing margin flexibility for manufacturers facing corn starch price volatility. This lead-time band ties pricing leverage directly to fiber processing capacity location, with mills in Sweden and Finland commanding premium terms against Southern European converters lacking alternative sourcing.
Pricing Analysis
Volume-discount tiering structures separate subscription-native brands from transactional retail purchasers, with auto-replenishment contracts capturing fifteen-to-twenty percent unit economics advantages over supermarket shelf pricing. Certification grade—specifically TÜV Austria OK Compost versus BPI labeling—drives price differentiation between premium and standard tiers. Cost compression in corn starch-dependent formulations is intensifying because agricultural commodity swings amplify margin pressure. Mass-market supermarket buyers exhibit highest price sensitivity, while sleep-deprived parents purchasing overnight variants through direct-to-consumer channels show lowest elasticity.
Supply Chain Analysis
Sweden and Finland anchor global supply for softwood kraft pulp fluffing capacity, while Chinese manufacturers dominate PLA film extrusion for breathable barrier layers. Raw material dependencies center on Nordic timber harvesting cycles, Brazilian sugarcane feedstock for bio-polymer alternatives, and Japanese textile engineering for bamboo fiber mechanical softening. Single-source vulnerability concentrates in PLA resin supply where European converters rely on Asian polymer production. Distribution runs through Rotterdam port complexes for European market penetration and Pacific Northwest rail corridors for North American parent demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable baby diapers sit in early-cycle recovery phase as EU Green Deal enforcement deadlines force inventory restocking ahead of 2027 reformulation mandates. This regulatory-driven cyclicality rewards positioning ahead of certification bottlenecks and infrastructure build-out completion.
For Market Incumbents: Compound subscription mechanics through algorithmic sizing transitions that lock in recurring revenue against emerging digital-native entrants. Defend shelf position in German and French health stores by accelerating TÜV Austria OK Compost certification timelines ahead of REACH Annex XVII enforcement. Prioritize backward integration into Nordic pulp processing to secure absorbency-grade fiber supply against Asian converter competition.
For New Entrants and Emerging Players: Differentiate on cloth-hybrid convergence architectures that address laundering barriers blocking full reusable adoption. Target Spanish and Italian parent demand where municipal composting infrastructure lags but plastic-free preference is accelerating. Pursue specialty shop channel entry with high-touch education models before scaling to mass retail placement.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy CPG conglomerates seeking to divest non-core sustainability line extensions lacking subscription infrastructure. Five-to-ten year viability hinges on certification asset accumulation and composting network density rather than manufacturing scale alone. Monitor ECHA guidance document releases as inflection indicators for PLA and PHA formulation startup valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-First Channel Migration | Direct-to-consumer bundling captures recurring revenue from millennial parents abandoning supermarket stock-up patterns. |
| Certification Asset Acquisition | TÜV Austria OK Compost and BPI labeling investments unlock municipal composting program participation in Germany and France. |
| Bamboo Fiber Processing Scale-Up | Japanese mechanical softening technology licensing enables premium tier positioning against wood pulp commoditization. |
| PLA Barrier Film Commercialization | ECHA microplastic classification deadlines force breathable backsheet reformulation ahead of 2027 enforcement. |
| Cloth-Hybrid Product Architecture | Reusable outer shell systems paired with biodegradable inserts address convenience barriers blocking full cloth adoption. |
Study Parameters
Desk research of EU regulatory filings, ECHA guidance documents, and municipal composting infrastructure databases preceded structured interviews with brand managers at subscription-native diaper companies, procurement leads at Nordic pulp mills, and category buyers at German health store chains. Primary fieldwork with composting facility operators and polymer research directors at Eindhoven Region clusters validated secondary trade flow analysis. Bottom-up unit economics modeling triangulated against top-down market sizing from customs records and retail audit data.
Variance-decomposition across material input costs, certification timeline delays, and channel mix shifts shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type performance tier, substrate material category, packaging format, and distribution channel mechanics. CAGRs derived from cohort-based adoption curves incorporating parental generational turnover and infrastructure build-out rates. Forecast inputs incorporated REACH Annex XVII enforcement trajectory and industrial composting facility commissioning pipelines.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation or accelerated US municipal composting investment would require recalibration. Forecasts reflect assumptions regarding bio-based superabsorbent polymer technical maturation and certification harmonization timelines between national standards bodies. Recalibration cycles align with material shifts in ECHA regulatory guidance and major Nordic pulp capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
North America Diaper Market
Baby Diapers
Dog Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
Baby Diapers Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Adult Diapers Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Smart Diaper Market