
 United States Diaper Market | 2026-2036
United States Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
United States Diaper Market Intelligence
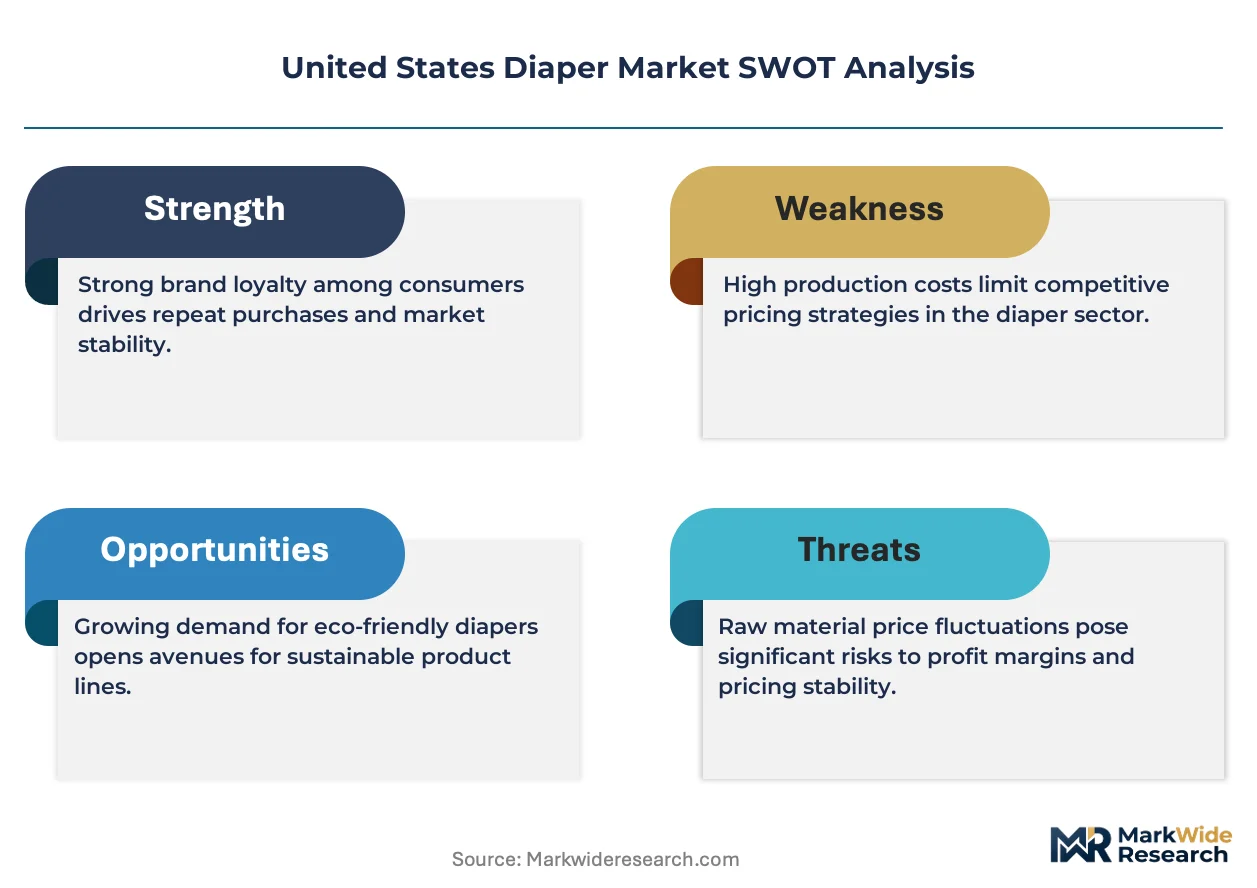
The EPA's sustainable materials management framework is rebalancing procurement criteria across institutional buyers and retail chains toward reduced synthetic content and biodegradable core materials. Procter & Gamble leverages its North American manufacturing scale to sustain volume leadership in premium disposable tiers. Kimberly-Clark anchors its position through intensive R&D in plant-based absorbent polymers. Essity competes aggressively in the adult incontinence channel with specialized hospital and long-term care contracts.
A diaper is a wearable absorbent hygiene product constructed from layered nonwoven fabrics, superabsorbent polymer cores, and elasticized containment systems designed to capture and isolate bodily waste from infants or incontinent adults. Manufacturing employs hot-melt adhesive bonding, ultrasonic sealing, and precision fiber deposition to achieve fluid acquisition rates exceeding grams per second in clinical testing. The disposable segment dominates volume but faces margin compression from raw material volatility, while bio-based alternatives command premium positioning as plant-derived superabsorbents and compostable backsheet films advance toward cost parity. Training pants represent the fastest-growing product type as delayed potty-training trends extend the addressable age window for pull-up formats.
The FDA regulates medical-grade adult incontinence products through 510(k) clearance pathways, while the EPA's sustainable materials management framework pressures manufacturers toward recycled content targets and reduced landfill burden. The Consumer Product Safety Commission enforces flammability and chemical exposure standards for infant contact materials, creating compliance thresholds that filter smaller importers. Stakeholders must monitor evolving state-level extended producer responsibility legislation and bio-based certification standards to anticipate sourcing requirements and pricing architecture shifts.
Market Dynamics
The EPA's sustainable materials management framework is restructuring procurement protocols across hospital networks and retail chains toward biodegradable superabsorbent cores and reduced synthetic backsheet content. This regulatory pressure is compressing margins for conventional petroleum-based diaper architectures while accelerating plant-derived polymer adoption curves.
Growth Catalysts
- Aging Demographics:Texas, California, and Florida exhibit concentrated elderly population density driving institutional adult incontinence procurement volumes through long-term care facility expansion.
- State-Level Extended Producer Responsibility:Proposals in multiple jurisdictions mandate post-consumer recovery targets that favor compostable core designs and closed-loop material flows.
- Hospital Network Consolidation:Integrated delivery systems in metropolitan corridors standardize absorbent hygiene purchasing through centralized GPO contracts favoring high-capacity suppliers.
Market Restraints
- Superabsorbent Polymer Feedstock Volatility:Acrylic acid derivatives tied to propylene supply chains expose manufacturers to petrochemical price swings compressing gross margins.
- Domestic Nonwoven Concentration:Meltblown and spunbond capacity clusters in the Southeast create geographic single-source risk for elasticized containment components.
- Biodegradation Rate Limitations:Industrial composting infrastructure gaps in most municipalities prevent full material recovery despite certified compostable film claims.
Strategic Opportunities
- Medicaid Home Care Waivers:State-level program expansions for aging-in-place services create reimbursement pathways for retail adult brief categories previously restricted to institutional channels.
- Plant-Based Polymer Convergence:Cellulosic superabsorbent integration with polylactic acid backsheet films enables full bio-based architecture at approaching cost parity.
- Direct-to-Consumer Subscription Models:E-commerce platforms bypass traditional retail slotting fees while capturing recurring revenue through predictive replenishment algorithms.
Industry Challenges
- Hot-Melt Adhesive Formulation Expertise:Specialized polymer chemistry knowledge for skin-safe elastic attachment remains concentrated among legacy equipment operators.
- 510(k) Clearance Timelines:FDA medical-grade adult incontinence pathways extend commercialization cycles for performance-tier products targeting clinical reimbursement codes.
- Legacy Converting Equipment Retrofit Costs:Ultrasonic sealing and precision fiber deposition upgrades demand capital outlays that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Diaper Market |
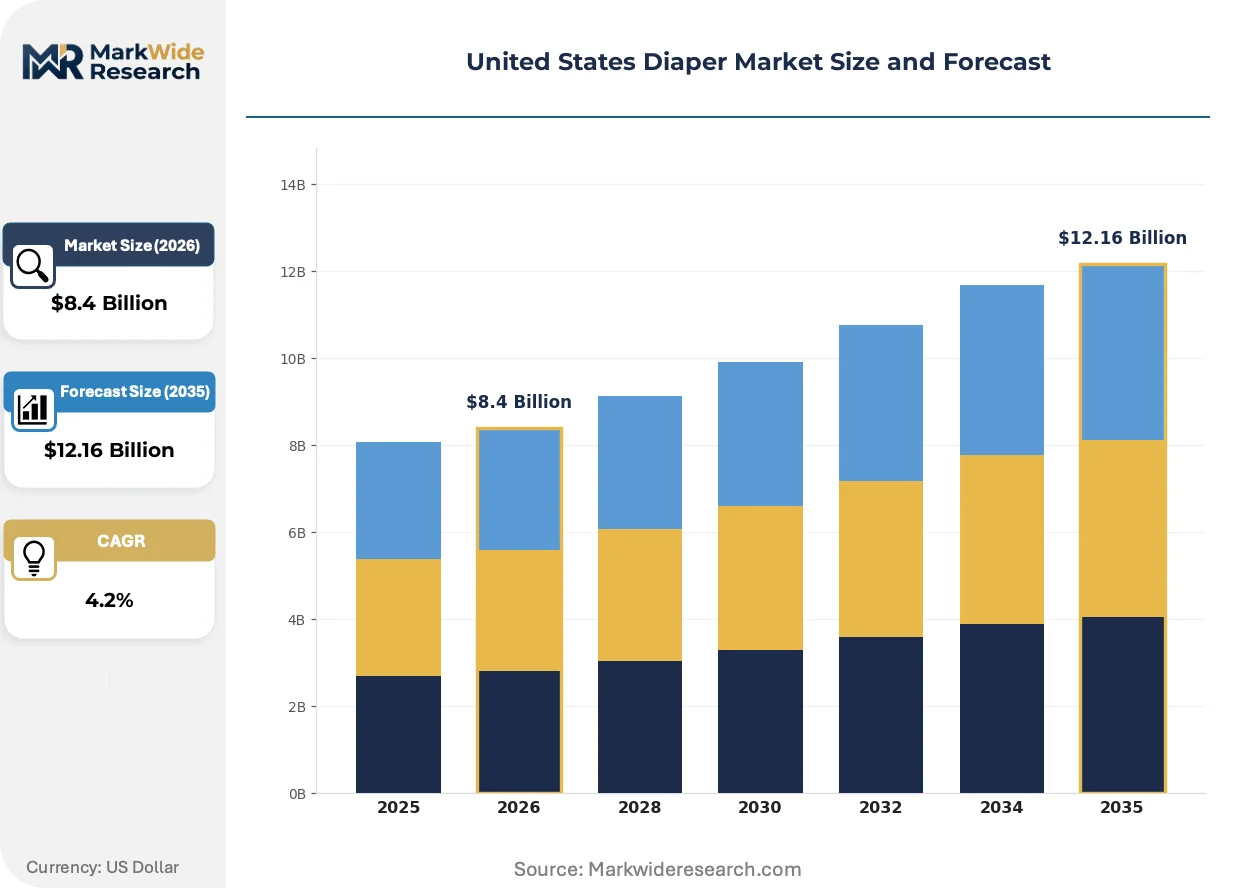
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Bio-based, Training Pants End User: Parents, Caregivers, Retailers, Hospitals Distribution Channel: Online, Supermarkets, Pharmacies, Discount Stores Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Drylock Technologies, Ontex, Procter & Gamble, Domtar, Essity, Kimberly-Clark, Svenska Cellulosa Aktiebolaget SCA, Unicharm, First Quality Enterprises, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Diaper Market Strategic Shifts & Innovations
Material substitution and channel restructuring are actively reconfiguring competitive positioning across disposable and reusable categories. Technical advancement in bio-based absorbency and regulatory pressure on synthetic content are converging to reshape manufacturing investment priorities.
Plant-derived superabsorbent polymers synthesized from modified cellulose feedstocks are overtaking petroleum-based sodium polyacrylate in premium infant and adult diaper tiers. Hospital procurement committees and eco-conscious retail buyers are adopting these materials at accelerating rates despite residual cost premiums. This substitution is compressing conventional polymer demand while enabling suppliers to capture margin through certified sustainable product lines.
The EPA's sustainable materials management framework mandates recycled content benchmarks and landfill diversion targets for federal procurement contracts. Manufacturers serving Veterans Affairs and military exchange systems must document post-consumer recycled content in packaging and reduce overall plastic mass per unit. Adult incontinence suppliers with established bio-based supply chains are securing preferred vendor status under these revised evaluation criteria.
Delayed potty-training trends among U.S. parents are extending pull-up format consumption into the 4-6 year age bracket previously served by underwear transition. Mass retailers are reallocating shelf space from taped diaper SKUs toward training pant varieties with stretch waistband architectures. This consumption-pattern shift concentrates in suburban markets with higher disposable income and extended childcare enrollment periods.
United States Diaper Market Segmentation
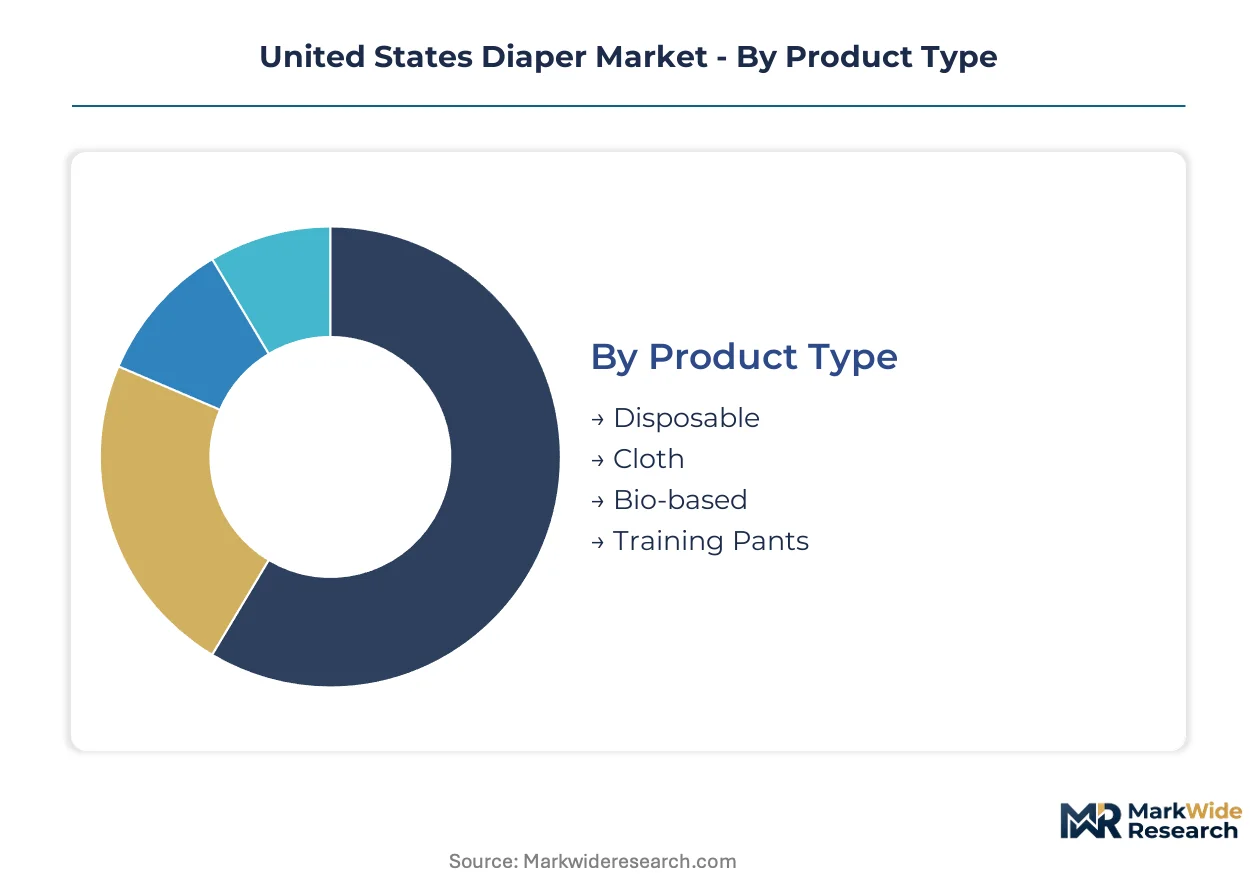
Diaper purchasing decisions in the United States split across multiple axes simultaneously. Buyers weigh absorbency performance against unit economics while channel availability and sustainability positioning filter final selection.
Product Type:
Material composition and disposal method anchor the primary purchase decision for institutional and retail buyers alike.
- Disposable:Layered nonwoven construction with sodium polyacrylate cores dominates hospital procurement and mass retail. Texas, California, and Florida account for concentrated volume through birth rate corridors and long-term care facility density.
- Training Pants:Elasticized waistband architectures with pull-up functionality extend consumption into the 4-6 year age bracket. Suburban markets with extended childcare enrollment and delayed potty-training trends drive category expansion.
- Bio-based:Plant-derived superabsorbent polymers and compostable backsheet films command shelf space in coastal metropolitan areas. EPA sustainable materials management criteria filter federal procurement toward certified biodegradable alternatives.
- Cloth:Reusable cotton and hemp fiber systems with snap or hook-and-loop closures serve eco-conscious households and diaper service subscribers. Direct-to-consumer subscription platforms bypass retail slotting fees for this segment.
Volume sits with Disposable; growth tilts toward Training Pants.
End User:
Procurement authority and reimbursement pathways determine specification requirements and contract structures.
- Hospitals:Integrated delivery systems standardize absorbent hygiene purchasing through centralized GPO contracts. FDA 510(k) clearance pathways filter supplier qualification for medical-grade adult incontinence products.
- Caregivers:Medicaid home care waiver recipients in aging-in-place programs drive retail adult brief demand previously restricted to institutional channels. State-level program expansions in Texas and Florida accelerate category access.
- Parents:Delayed potty-training trends and dual-income household schedules extend pull-up format consumption. Suburban markets with higher disposable income concentrate premium-tier purchasing.
- Retailers:Mass merchants and pharmacy chains allocate shelf space based on velocity metrics and sustainability certification status. EPA recycled content benchmarks influence private-label sourcing decisions.
Institutional procurement anchors volume; caregiver-directed purchasing climbs fastest.
Distribution Channel:
Channel selection reflects inventory carrying costs, replenishment predictability, and consumer convenience preferences.
- Supermarkets:High-velocity diaper SKUs occupy end-cap positioning with promotional slotting fees. Training pant varieties gain linear footage at the expense of taped diaper formats in suburban locations.
- Online:Direct-to-consumer subscription models deploy predictive replenishment algorithms to capture recurring revenue. E-commerce platforms bypass traditional retail margin structures for bio-based and cloth alternatives.
- Pharmacies:Adult incontinence products with medical-grade positioning stock pharmacy shelves for Medicare and Medicaid reimbursement pathways. Long-term care facility discharge planning drives post-acute purchasing.
- Discount Stores:Economy-tier disposable SKUs with reduced feature sets serve price-sensitive households. Volume-based procurement from Southeast nonwoven manufacturing clusters supports margin preservation.
Supermarket velocity leads current volume; online subscription mechanics capture steepest expansion trajectory.
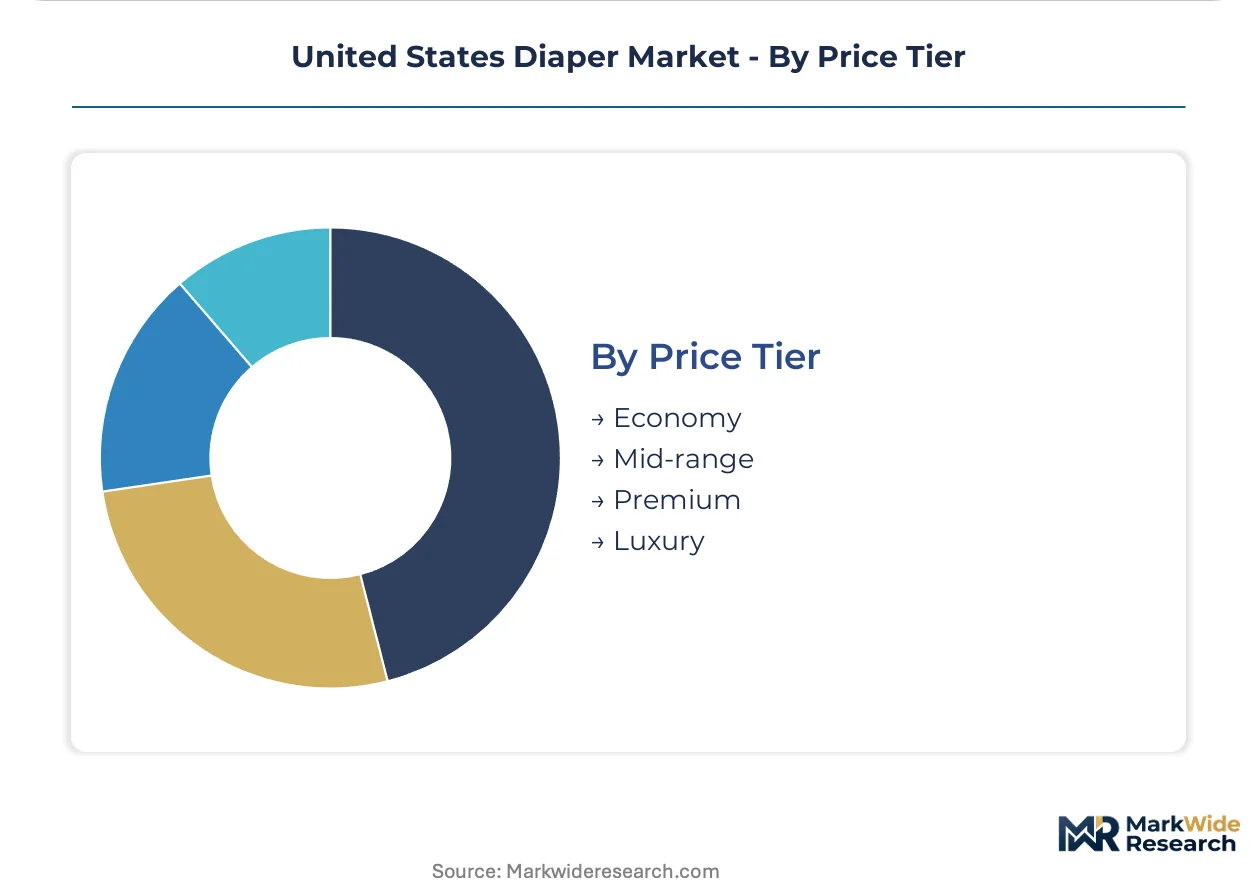
Price Tier:
Unit economics and performance specifications stratify across household budget constraints and clinical requirement severity.
- Premium:Enhanced absorbency cores with plant-based polymer integration and dermatological certification command price multiples. Coastal metropolitan buyers with sustainability preference bias concentrate here.
- Economy:Standard petroleum-based superabsorbent construction with reduced elasticization serves Medicaid-reimbursed and cash-constrained households. Discount store distribution dominates volume.
- Mid-range:Balanced feature sets with selective bio-based component integration bridge price-performance tradeoffs. Mass merchant promotional cycles drive category placement.
- Luxury:Organic cotton contact layers, designer prints, and subscription bundling target gift purchasing and status-conscious consumption. Direct-to-consumer platforms control distribution.
Economy tier holds volume concentration; Premium gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors domestic diaper manufacturing capacity through concentrated nonwoven fabric production and distribution infrastructure serving national retail networks.
Texas
Texas leads institutional volume through long-term care facility expansion along the I-35 corridor and Medicaid home care waiver program growth. State procurement guidelines favor suppliers meeting EPA sustainable materials benchmarks. Houston and San Antonio medical center networks standardize absorbent hygiene purchasing through centralized GPO contracts.
California
California drives premium-tier adoption through coastal metropolitan sustainability preferences and stringent state-level extended producer responsibility mandates. CalRecycle's packaging regulations filter retail shelf space toward certified compostable alternatives. Los Angeles and San Francisco Bay Area distribution centers channel bio-based products into West Coast markets.
Florida
Florida exhibits concentrated elderly population density accelerating adult incontinence procurement through Medicare Advantage network expansion. State aging-in-place program waivers create reimbursement pathways for retail adult brief categories. Tampa and Miami healthcare clusters anchor hospital network consolidation driving standardized purchasing.
Illinois and Ohio
The Midwest manufacturing belt maintains legacy converting equipment capacity for economy-tier disposable production serving discount retail channels. Chicago metropolitan logistics networks distribute volume into national pharmacy and supermarket chains. Cleveland and Cincinnati industrial corridors host specialized hot-melt adhesive formulation suppliers.
Southeast Cluster
Georgia and the Carolinas concentrate meltblown and spunbond nonwoven capacity creating geographic supply risk for elasticized containment components. Savannah port infrastructure handles imported superabsorbent polymer feedstocks. Charlotte and Atlanta distribution hubs coordinate replenishment for mass merchant networks across the Eastern seaboard.
United States Diaper Market Key Industry Players
Premium-margin players sit above commodity-margin players across absorbency performance and sustainability certification dimensions, with tiered pricing separating dermatologically tested plant-based tiers from standard petroleum-based construction. The vendor base organizes around three strategic archetypes: multinational consumer goods conglomerates with North American manufacturing scale, specialized hygiene companies with intensive R&D in bio-based polymers, and regional fabricators serving private-label discount retail. Dominant competitive moves include backward integration into superabsorbent polymer supply chains and strategic partnerships with composting infrastructure operators to close material recovery loops.
Within the multinational tier, Procter & Gamble and Kimberly-Clark exemplify scale-driven positioning through captive manufacturing networks and retail slotting fee leverage. Essity occupies a position bridging institutional contract specialization with bio-based innovation pipelines. Among mid-cap specialists, Ontex represents European-origin competitive entry focused on adult incontinence channel depth, while First Quality Enterprises anchors domestic private-label supply for discount retail velocity tiers.
| Leading Market Players |
|---|
| Drylock Technologies |
| Ontex |
| Procter & Gamble |
| Domtar |
| Essity |
| Kimberly-Clark |
| Svenska Cellulosa Aktiebolaget SCA |
| Unicharm |
| First Quality Enterprises |
| Others |
Cost & Logistics Intelligence
Hospital network GPO procurement anchors pricing power in the United States diaper market, compressing margins for mid-tier suppliers while rewarding scale players with multi-year contract stability. The EPA's sustainable materials management framework adds compliance cost premiums that stratify pricing across certified bio-based tiers and conventional petroleum-based construction.
Pricing Analysis
Value-based pricing tied to absorbency performance and skin-safety outcomes anchors premium-tier positioning. Three-tier pricing structure across premium, standard, and economy levels separates dermatologically certified plant-based products from basic petroleum-core disposables. Cost compression in economy tiers is intensifying because Medicaid reimbursement ceilings cap allowable spend per unit. Cash-constrained households and institutional buyers exhibit highest price sensitivity; eco-conscious coastal consumers and gift purchasers show lowest.
Supply Chain Analysis
Superabsorbent polymer feedstock rests on propylene derivative supply chains concentrated in the US Gulf Coast and imported Asian petrochemical corridors. Meltblown and spunbond nonwoven capacity clusters in Georgia and the Carolinas, creating geographic single-source vulnerability for elasticized containment components. Tariff exposure on imported acrylic acid derivatives threatens margin stability for domestic converters. Distribution runs through mass merchant DC networks in Dallas-Fort Worth and Chicago, with direct-to-consumer subscription platforms bypassing traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States diaper market sits in a materials-transition phase as plant-derived superabsorbent polymers displace petroleum-based sodium polyacrylate across premium and institutional tiers. Cellulosic feedstock integration and compostable backsheet films are redefining procurement criteria and manufacturing investment priorities.
For Market Incumbents: Extend backward integration into superabsorbent polymer supply chains to secure feedstock cost stability against propylene volatility. Lock in preferred vendor status with Veterans Affairs and military exchange systems by documenting EPA-compliant recycled content benchmarks. Capture margin compression defense through captive production of plant-based absorbent cores rather than outsourced toll manufacturing. For New Entrants and Emerging Players: The mid-range price-point gap between premium plant-based tiers and economy petroleum-core disposables offers white-space entry for hybrid construction with selective bio-based components. Medicaid home care waiver program expansion in Texas and Florida creates the most penetrable reimbursement pathway for retail adult brief categories. Direct-to-consumer subscription platforms with predictive replenishment algorithms bypass slotting fee barriers that block mass retail shelf access. For Investors and Strategic Acquirers: The window for entry favors specialized hygiene companies with intensive R&D pipelines in cellulosic superabsorbents and established composting infrastructure partnerships. Long-term viability hinges on regulatory tailwinds for extended producer responsibility mandates and federal procurement bio-based certification requirements. Watch state-level EPR legislation passage as the primary inflection signal for accelerated plant-derived polymer adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superabsorbent Polymers | Captive supply of plant-derived sodium polyacrylate alternatives insulates margin from petrochemical volatility. |
| Composting Infrastructure Partnership | Closed-loop material recovery agreements with municipal operators validate certified biodegradable product claims. |
| Direct-to-Consumer Subscription Launch | Predictive replenishment algorithms capture recurring revenue while bypassing retail slotting fee structures. |
| Medicaid Waiver Contract Expansion | State-level aging-in-place program access unlocks retail adult brief reimbursement previously restricted to institutional channels. |
| EPA Sustainable Materials Certification | Federal procurement preferred vendor status under Veterans Affairs and military exchange systems secures volume stability. |
Research Approach
Independent corroboration across primary interviews with plant managers at nonwoven manufacturing facilities, procurement leads at hospital GPOs, and category buyers at mass retail chains underwrites the qualitative findings. Secondary validation draws from EPA sustainable materials management documentation, FDA 510(k) clearance databases, and state-level extended producer responsibility legislative records. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators to anchor volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, end user archetype, distribution channel, and price tier, with additional modeling of state-level regulatory adoption patterns. CAGRs derive from regression analysis against demographic drivers, reimbursement policy shifts, and materials substitution curves. Forecast inputs incorporate superabsorbent polymer feedstock cost indices and industrial composting infrastructure deployment timelines.
Underlying measurement precision varies by segment; disposable product volume and hospital procurement flows carry tighter precision than emerging bio-based adoption rates and direct-to-consumer subscription churn. Forecasts reflect documented assumptions regarding EPA regulatory enforcement intensity and state Medicaid waiver program expansion trajectories. A small set of triggers warrants ongoing watch: propylene derivative price spikes, EPR legislation passage in additional states, and composting facility commissioning delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Disposable Hygiene Products Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Mexico Pant Type Adult Diaper Market
Baby Diapers
Europe Diaper Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Baby Diapers Market
Baby Diapers
Pet Diapers Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Latin America Diaper Market