
 Training Shoes Market | 2026-2036
Training Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Training Shoes Market Analytics
Modular sole systems with detachable cushioning inserts is pivoting how consumers evaluate training shoes. Nike leverages its Flyknit manufacturing scale to control premium supply chains. Adidas sustains R&D intensity around recycled ocean plastics for upper construction. Hoka dominates the maximal-cushioning niche through specialized geometry that differentiates its product line from conventional silhouettes.
Training shoes are athletic footwear engineered with multi-directional stability, responsive midsole compounds, and reinforced heel counters to support varied physical conditioning regimens. Their primary commercial purpose centers on reducing injury risk during dynamic movements while extending product lifespan across diverse workout modalities. Running shoes anchor the largest volume pool within product type segmentation, while cross-training shoes capture margin concentration from boutique gym operators. Synthetic fabrics lead material demand due to knit-engineering advances, though mesh variants gain share in warm-climate markets.
REACH chemical standards in Europe restrict certain phthalates in rubber outsoles, compelling reformulation across export-bound production lines. The EPA's manufacturing emissions guidelines in the United States shape domestic factory investment decisions. China's GB standards for footwear safety create compliance thresholds for brands sourcing from mainland suppliers. Stakeholders must monitor how biopolymer cost curves evolve against petroleum-based alternatives.
Market Dynamics
Modular sole systems with detachable cushioning inserts are restructuring how manufacturers design training footwear architectures and how consumers evaluate replacement economics across workout modalities.
Growth Catalysts
- REACH chemical standards:The EU Green Deal's phthalate restrictions in rubber outsoles are accelerating bio-based midsole foam adoption across European export production lines.
- Hybrid workout routines:Fitness enthusiasts pursuing combined strength and cardio regimens are demanding multi-directional stability features that single-purpose athletic footwear cannot deliver.
- Knit-engineering advances:Synthetic fabric manufacturing scale in Asia-Pacific supplier clusters is compressing unit costs for engineered mesh uppers in warm-climate markets.
Market Restraints
- Petroleum-based foam dependency:Midsole compound formulations remain tethered to volatile oil price curves that erode margin predictability for volume manufacturers.
- Concentrated supplier geography:China's GB standards compliance requirements and dual carbon goals are constraining capacity expansion timelines for mainland footwear factories.
- Technical performance ceiling:Maximal-cushioning geometries trade energy return efficiency for impact protection, limiting crossover appeal to explosive movement disciplines.
Strategic Opportunities
- Boutique gym channel expansion:Specialized cross-training shoe demand from premium fitness operators offers margin concentration unavailable through mass retail distribution.
- Recycled ocean plastics integration:Upper construction using reclaimed marine polymers aligns with ESG procurement mandates from institutional corporate wellness programs.
- Biopolymer cost curve inflection:Stakeholders monitoring bio-based alternatives against petroleum benchmarks can capture first-mover positioning as production scales mature.
Industry Challenges
- Reformulation timeline compression:EPA manufacturing emissions guidelines and state-level factory investment requirements are forcing simultaneous compliance across multiple regulatory frameworks.
- Specialized geometry replication:Competitors attempting to engineer comparable maximal-cushioning platforms face extended R&D cycles and proprietary last-shape IP barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Training Shoes Market |
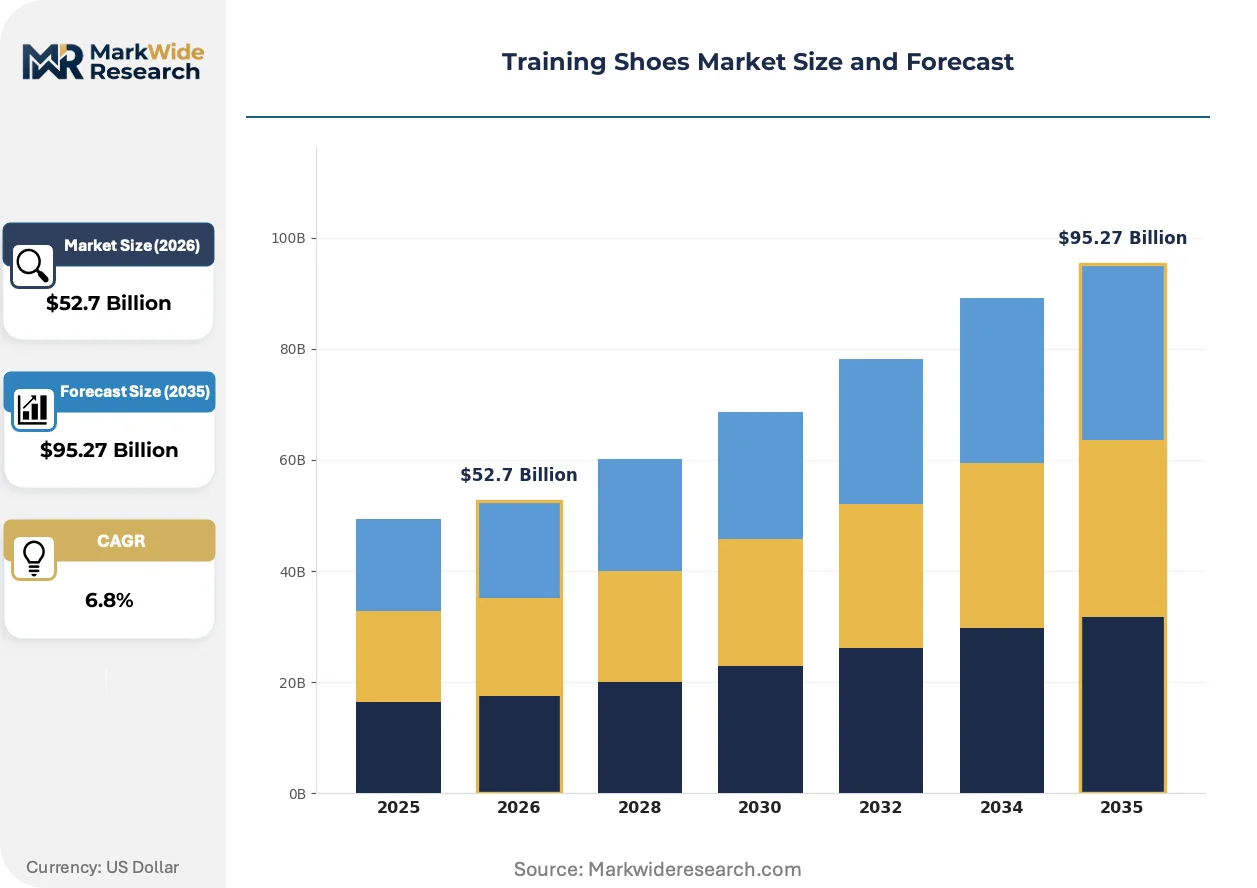
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-Training Shoes, Running Shoes, Weightlifting Shoes, Multi-Sport Shoes Material: Synthetic Fabrics, Rubber, Leather, Mesh End User: Athletes, Fitness Enthusiasts, Casual Users, Trainers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Warehouse Clubs |
| Companies Covered | Puma, Saucony, Nike, Asics, Hoka, Adidas, Brooks, New Balance, Reebok, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Training Shoes Market Evolving Landscape
Active ingredient innovation in midsole compounds and upper construction methods is compressing product development cycles while expanding performance differentiation possibilities across training disciplines.
Detachable cushioning insert architectures are modularizing how consumers approach footwear lifecycle management. Boutique gym operators and dedicated fitness enthusiasts are adopting these systems at accelerating rates to customize support profiles across varied workout schedules. This technology is modularizing the traditional unit-sale model toward component-replacement revenue streams that extend customer lifetime value metrics.
REACH chemical standards restricting specific phthalates in rubber outsole formulations are compelling wholesale material science reinvestment. European-bound production lines face mandatory reformulation deadlines that disrupt established supplier relationships and qualification protocols. Running shoe categories with high export exposure to EU markets are responding fastest, accelerating bio-based alternative certification timelines ahead of enforcement dates.
Specialized direct-to-consumer channels are displacing traditional sporting goods retail for technical training footwear purchases. Performance-focused buyers increasingly research biomechanical specifications through digital platforms before completing transactions, compressing the influence of in-store associate recommendations. China and South Korea exhibit the most pronounced channel migration, where mobile-first commerce infrastructure supports seamless specification comparison and virtual try-on validation.
Training Shoes Market Segmentation
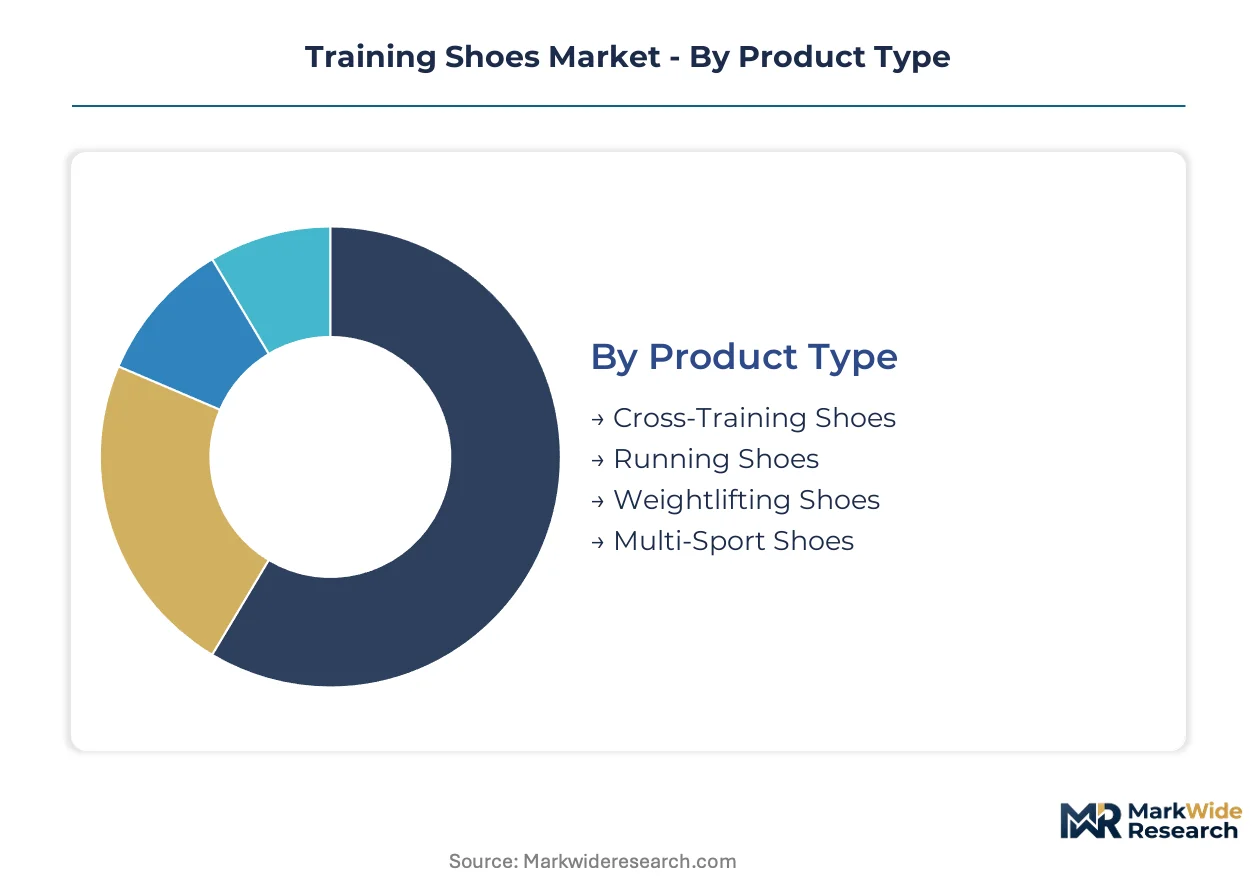
Training shoes segment across performance specifications, material engineering, and purchase contexts that reshape how manufacturers configure product portfolios. Each axis carries distinct margin profiles and technical requirements that determine competitive positioning.
Product Type:
Midsole compound density and outsole lug geometry differentiate performance envelopes across training disciplines.
- Running Shoes:Engineered with longitudinal flex grooves and heel-to-toe drop geometries optimized for repetitive forward motion. Volume concentrates in China where domestic sportswear consumption climbs alongside marathon participation rates. REACH chemical standards are accelerating bio-based midsole foam adoption across European export production lines.
- Cross-Training Shoes:Multi-directional stability platforms with reinforced heel counters support lateral movements and plyometric loading. Boutique gym operators in South Korea and the United States drive margin concentration through specialized procurement. Hybrid workout routines are expanding addressable demand beyond single-purpose athletic footwear.
- Weightlifting Shoes:Elevated heel wedges and rigid midsole plates stabilize barbell movements through fixed ankle angles.
- Multi-Sport Shoes:Compromise geometries trade discipline-specific optimization for versatility across recreational activity.
Mature deployment sits with Running Shoes. Newer deployment is concentrated in Cross-Training Shoes.
Material:
Upper construction and midsole formulation choices determine unit economics and regulatory compliance exposure.
- Synthetic Fabrics:Knit-engineering advances enable engineered mesh uppers with zone-specific stretch and lockdown properties. Manufacturing scale in Vietnam and Indonesia compresses unit costs for warm-climate market supply. EPA manufacturing emissions guidelines are reshaping domestic factory investment decisions for petroleum-derived polymer processing.
- Mesh:Open-weave constructions maximize breathability in high-humidity training environments. Demand climbs fastest in India and Southeast Asia where climate conditions prioritize ventilation over water resistance. GB standards compliance creates qualification thresholds for brands sourcing from mainland China suppliers.
- Rubber:Outsole compounds balance abrasion resistance against ground contact friction coefficients.
- Leather:Premium positioning relies on natural material aesthetics and extended durability claims.
Established volume sits with Synthetic Fabrics. Steepest expansion trajectory belongs to Mesh.
End User:
Purchase frequency and specification sophistication vary sharply across commitment levels to physical conditioning.
- Fitness Enthusiasts:Dedicated training schedules drive replacement cycles and technical feature prioritization. This segment is expanding most quickly as hybrid workout routines gain traction across North America and Western Europe. Modular sole systems with detachable cushioning inserts are restructuring replacement economics for this buyer type.
- Athletes:Competition-grade specifications require discipline-specific certifications and biomechanical customization.
- Trainers:Professional coaching contexts demand durability across multiple daily sessions and varied client needs.
- Casual Users:Aesthetic and comfort priorities dominate over performance engineering in purchase decisions.
Volume concentration rests with Casual Users. Margin expansion concentrates with Fitness Enthusiasts.
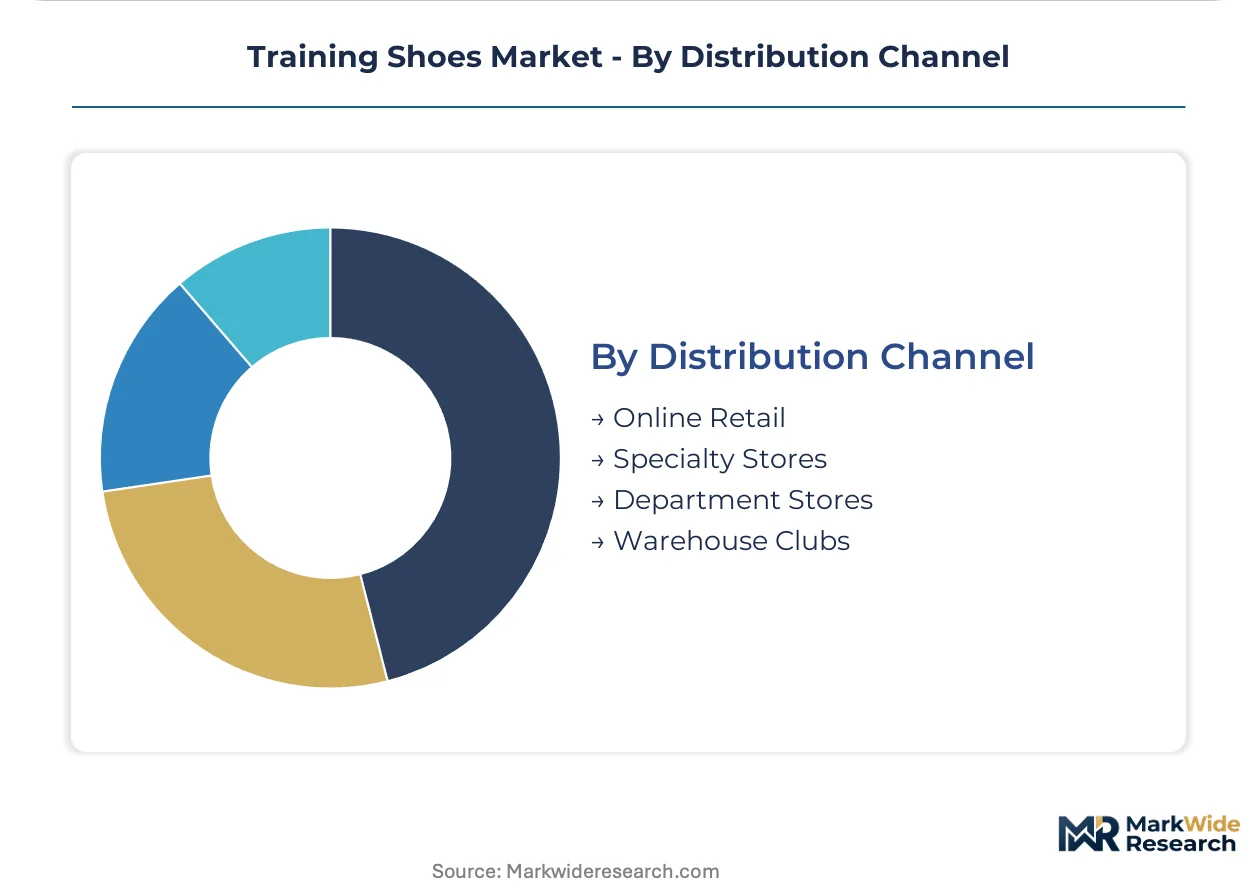
Distribution Channel:
Channel selection determines specification transparency, inventory depth, and customer acquisition cost structures.
- Online Retail:Digital platforms enable biomechanical specification comparison and virtual try-on validation before purchase completion. China and South Korea exhibit the most pronounced channel migration where mobile-first commerce infrastructure supports seamless transaction flows. Direct-to-consumer channels are displacing traditional sporting goods retail for technical training footwear.
- Specialty Stores:In-store gait analysis and fitting expertise justify premium positioning for technical product categories.
- Department Stores:Mass-market reach supports casual user segmentation with lower specification complexity.
- Warehouse Clubs:Volume pricing and limited assortment target price-sensitive replacement purchases.
Traditional strength sits with Specialty Stores. Fastest channel shift is occurring in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Asia while consumption concentrates in North America and Western Europe. China dominates export production through Fujian and Guangdong province factory networks. The United States absorbs premium volumes through direct-to-consumer channels.
United States
Marathon participation rates and boutique fitness studio expansion drive technical footwear demand. EPA manufacturing emissions guidelines reshape domestic factory investment decisions. Portland, Oregon anchors brand headquarters concentration for performance-oriented design functions.
China
Domestic sportswear consumption climbs alongside rising middle-class fitness participation. GB standards for footwear safety create compliance thresholds for mainland suppliers. Quanzhou city in Fujian province hosts dense supplier ecosystems for knit-engineered upper production.
Germany
Trail running and outdoor training cultures sustain premium product demand. REACH chemical standards restrict phthalates in rubber outsoles bound for EU markets. Bavaria-based engineering clusters specialize in biomechanical testing and last-shape development.
South Korea
Mobile-first commerce infrastructure supports seamless specification comparison and virtual try-on validation. MFDS consumer product safety frameworks govern athletic footwear import standards. Seoul Capital Area concentrates boutique gym operator procurement for cross-training categories.
India
Warm-climate training conditions prioritize mesh upper ventilation over water resistance. BIS certification requirements create qualification barriers for imported technical footwear. Tamil Nadu supplier networks expand synthetic fabric manufacturing scale for regional supply.
Training Shoes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct pricing tiers. Market structure shows moderate consolidation around heritage sportswear houses with decades of technical credibility. Three archetypes dominate: vertically integrated multinationals controlling manufacturing scale, digitally native challengers exploiting direct-to-consumer economics, and niche specialists commanding premium positioning through biomechanical differentiation. Competitive moves center on bio-based material R&D partnerships and modular sole system patent filings.
Within the heritage multinational tier, Nike and Adidas occupy positions defined by manufacturing scale and global distribution infrastructure. Hoka exemplifies the biomechanical specialist archetype through maximal-cushioning geometry differentiation. These three entities anchor competitive dynamics across premium and mass-market segments without exhaustive market coverage.
| Leading Market Players |
|---|
| Puma |
| Saucony |
| Nike |
| Asics |
| Hoka |
| Adidas |
| Brooks |
| New Balance |
| Reebok |
| Others |
Value Network & Pricing Analysis
Ethylene-vinyl acetate resin price indices cascade through midsole compound costs, compressing margin buffers for volume manufacturers while amplifying pricing power for brands with captive foam production in Vietnam and Indonesia. Petroleum-derived polymer volatility feeds directly into three-tier pricing structure across premium, standard, and economy levels, with boutique gym operators absorbing premium markups for modular sole architectures while mass retail channels face cost-down mandates.
Pricing Analysis
Margin tightening in economy-tier synthetic fabric models reflects knit-engineering scale compression in Asian supplier clusters. Pricing stratifies across premium, standard, and economy tiers based on midsole compound density certification and brand heritage positioning. Cost-down pressure on standard-tier products accelerates because of petroleum-based foam dependency eroding predictability. Casual users exhibit highest price sensitivity through warehouse club procurement, while fitness enthusiasts demonstrate lowest sensitivity when biomechanical specifications justify replacement economics.
Supply Chain Analysis
Returns flows from direct-to-consumer channels in China and South Korea are restructuring reverse logistics infrastructure, with refurbishment programs for detachable cushioning inserts creating circular revenue streams. Manufacturing concentrates in China, Vietnam, and Indonesia, with Quanzhou city anchoring knit-engineered upper production. Raw material sourcing draws from petroleum-derived EVA compounds, recycled ocean plastics, and bio-based midsole alternatives. Single-source vulnerability sits with Fujian province foam suppliers facing GB standards compliance bottlenecks. Distribution runs through mobile-first commerce platforms displacing traditional sporting goods retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mainland China's dual carbon goals are constraining footwear factory capacity expansion timelines, propping pricing power for manufacturers with qualified supplier relationships. This supply-constrained dynamic favors incumbents with established compliance infrastructure.
For Market Incumbents: Deploy modular sole system patent filings to lock in component-replacement revenue streams against digitally native challengers exploiting direct-to-consumer economics. Accelerate bio-based midsole foam certification ahead of REACH enforcement deadlines to defend margin position against reformulation-disrupted competitors. Backward integration into Vietnamese knit-engineering facilities secures supply continuity as China's GB standards tighten. For New Entrants and Emerging Players: The price-point gap between Hoka's maximal-cushioning premium positioning and economy-tier mesh models offers entry space for biomechanical specialists. Target India's warm-climate ventilation-prioritized segment where BIS certification barriers filter out heritage multinationals. Pursue boutique gym operator procurement channels in Seoul Capital Area with specialized cross-training geometries. For Investors and Strategic Acquirers: Distressed-cycle entries favor biomechanical specialist archetypes in Germany with Bavaria-based testing infrastructure and REACH-compliant material science pipelines. Five-to-ten year viability hinges on bio-based cost curve inflection against petroleum benchmarks. Monitor biopolymer production scale maturation as inflection signal for first-mover positioning capture.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Midsole Certification | REACH compliance deadlines in EU markets accelerate alternative material qualification timelines. |
| Modular Sole Patent Portfolio | Component-replacement revenue streams extend customer lifetime value beyond unit-sale economics. |
| Direct-to-Consumer Platform Launch | Mobile-first commerce infrastructure in South Korea enables specification-transparent transactions. |
| Recycled Ocean Plastics Integration | ESG procurement mandates from corporate wellness programs align upper construction with buyer priorities. |
| Boutique Gym Channel Expansion | Specialized cross-training demand from premium fitness operators captures margin concentration unavailable through mass retail. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted across footwear brand product managers, Vietnamese factory operations directors, and boutique gym procurement leads. Bottom-up triangulation against top-down macroeconomic indicators validated volume estimates. Secondary sources included EPA manufacturing emissions guidelines, ECHA REACH substance restrictions, China customs export databases, and athletic footwear trade association production surveys.
Data-stream reconciliation across shipment volumes, retail audit tracking, and brand-reported segment revenues informed the analytical framework. Segmentation dimensions modeled include product type, material composition, end-user commitment level, and distribution channel migration patterns. CAGRs were derived from regression analysis against macroeconomic fitness participation indicators and petroleum price curve assumptions. Industry-specific inputs incorporated marathon participation registration data and boutique fitness studio expansion tracking.
Inputs from Chinese supplier certification databases and EU regulatory enforcement calendars were available through the study window; gaps in real-time biopolymer production cost data introduce uncertainty bands around bio-based adoption timelines. Forecasts reflect documented assumptions regarding REACH compliance pacing and hybrid workout routine penetration. Material deviation in petroleum price volatility or dual carbon policy enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Orthopedic Footwear Market
Footwear
Snow Boots Market
Footwear
GCC Footwear Market
Footwear
Golf Footwear Market
Footwear
Women's Sneakers Market
Footwear
Sneaker Boots Market
Footwear
Cowboy Boots Market
Footwear
Women's Luxury Footwear Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Sports Footwear Market
Footwear
High Heels Footwear Market
Footwear
PVC Footwear Market
Footwear
Self-Lacing Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Athletic Footwear Market
Footwear
Water Shoes Market