
 Smart Diaper Market | 2026-2036
Smart Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Diaper Market Intelligence
The shift from infant care towards elderly care applications is hardening the market's focus on clinical-grade features and data accuracy. Established consumer goods firms like Procter & Gamble leverage extensive distribution networks to introduce smart features into existing product lines. Kimberly-Clark competes on brand loyalty and incremental innovation within its dominant infant care segment. Meanwhile, specialists such as Essity Aktiebolag and Smardii Inc. differentiate through a dedicated focus on the adult incontinence and professional healthcare channels.
A smart diaper integrates electronic components to monitor wetness, soiling, or other physiological indicators for caregivers. These systems typically use a small, reusable sensor clip or a disposable embedded strip containing capacitive sensors that transmit data to a smartphone application. While disposable smart diapers currently command the largest market volume due to convenience, demand for reusable sensor-embedded diapers is increasing in institutional settings like geriatric care centers and hospitals. The infant care application remains a high-volume category, but the patient monitoring segment offers higher margins.
Regulatory compliance presents a complex hurdle, with products navigating different frameworks across key geographies. In the United States, devices making health claims fall under FDA oversight, while in Europe, they must adhere to CE marking for electronic safety and potentially the MDR for medical applications. Japan's METI sets standards for consumer electronics integrated into such products. Stakeholder success depends on designing platforms that can adapt to divergent regional data privacy and medical device requirements.
Market Dynamics
The market's primary structural force is the pivot from infant novelty to geriatric necessity. This shift elevates requirements for clinical data accuracy, sensor reliability, and integration with professional healthcare monitoring platforms.
Growth Catalysts
- Aging Demographics:Rising longevity and a growing elderly population in developed countries, particularly Japan and Germany, create a large user base for adult incontinence monitoring.
- Sensor Miniaturization:Advances in miniaturized, low-power electronics, specifically for Bluetooth Low Energy transceivers, enable small, comfortable reusable sensor pods for diapers.
- Telehealth Expansion:Healthcare systems in the United States and Europe are incentivizing remote patient monitoring solutions to reduce hospital readmissions and manage chronic conditions at home.
Market Restraints
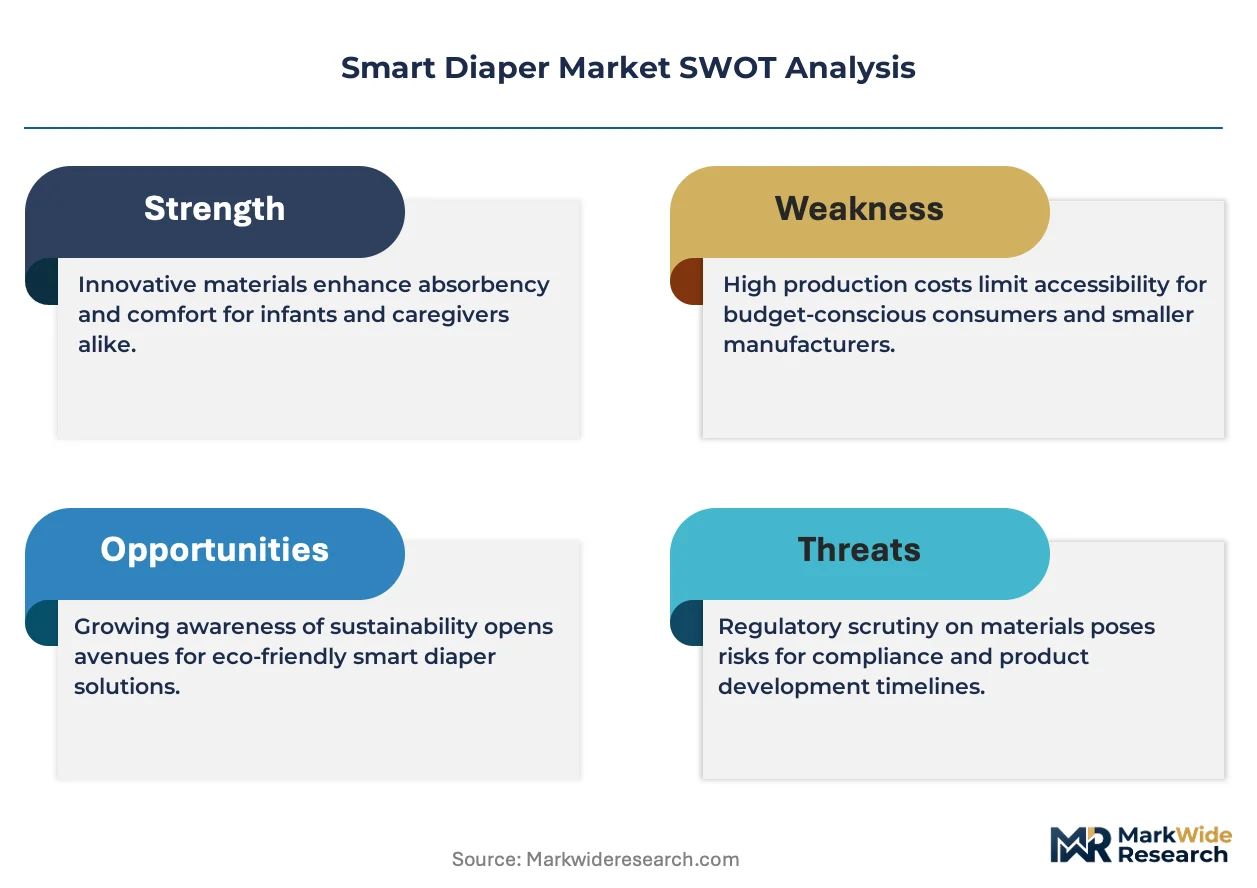
- High Unit Cost:The premium price of smart diapers over conventional alternatives remains a barrier to adoption in the cost-sensitive consumer infant care segment.
- Regulatory Divergence:Manufacturers face complex compliance pathways navigating different standards, such as FDA medical device rules in the US and the EU's MDR.
- Data Privacy Concerns:Hesitancy among consumers and institutions over the collection of sensitive personal health data, especially under regulations like GDPR, can slow market penetration.
Strategic Opportunities
- Biomarker Integration:There is white-space for developing diapers that incorporate sensors for biomarkers indicating urinary tract infections (UTIs) or dehydration.
- Emerging Markets:Untapped potential exists in markets like South Korea and Australia, which have high tech adoption rates and aging populations.
- Subscription Models:Shifting to a subscription-based service model for home care agencies and long-term care facilities can create recurring revenue streams.
Industry Challenges
- EHR System Integration:A primary hurdle is ensuring smart diaper data platforms are interoperable with fragmented Electronic Health Record (EHR) systems used by hospitals.
- Caregiver Training:Deploying these systems requires investment in training for non-technical caregivers in both home and institutional settings to ensure proper use and data interpretation.
- E-Waste Management:The disposal of single-use diapers with electronics poses an environmental challenge, attracting scrutiny from regulators and institutional buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Diaper Market |
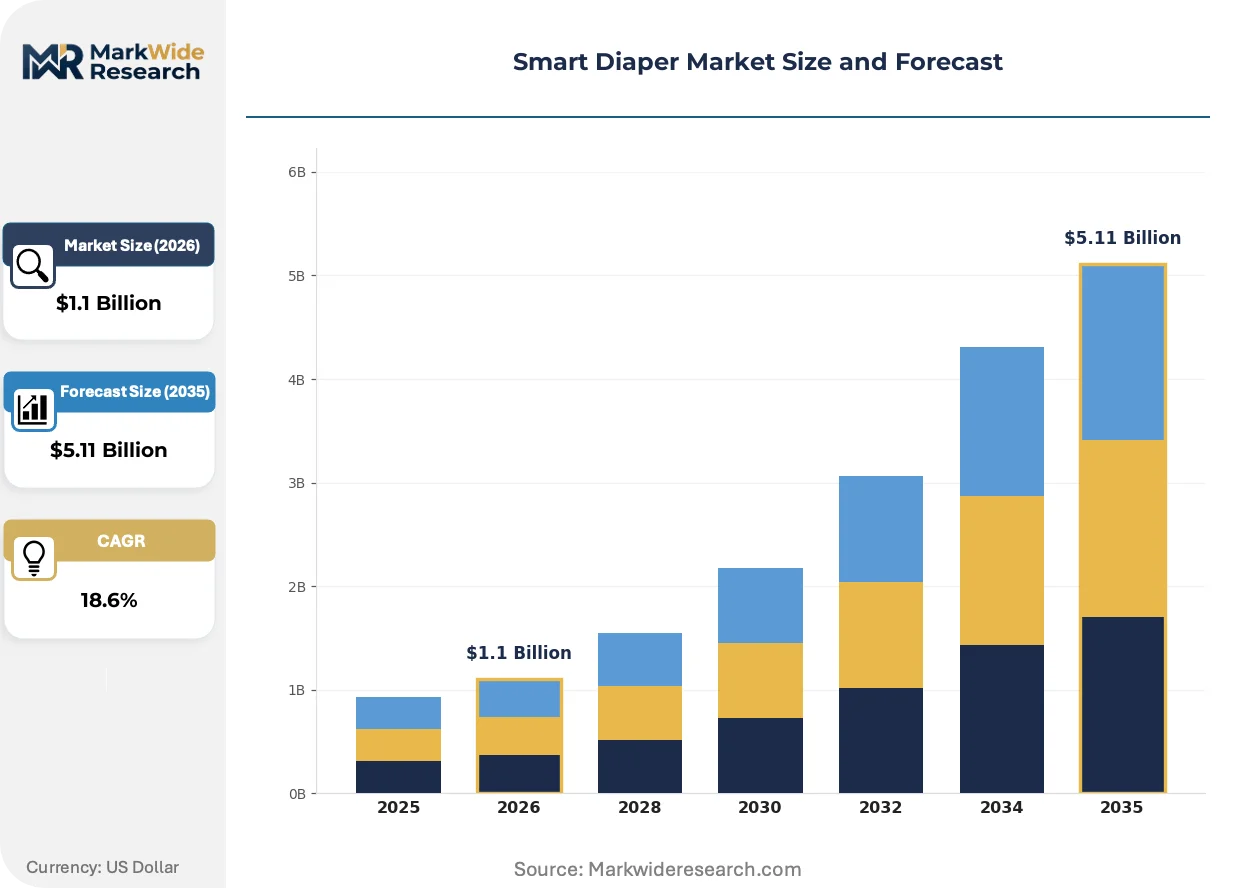
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $5.11 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Smart Diapers, Reusable Smart Diapers, Sensor-Embedded Diapers, Hybrid Smart Diapers Technology: Capacitive Sensors, Resistive Sensors, RFID Sensors, Optical Sensors, Gesture Recognition Application: Infant Care, Elderly Care, Patient Monitoring, Maternity Care, Special Needs Care End User: Home Caregivers, Hospitals, Geriatric Care Centers, Pediatric Clinics, Nursing Homes |
| Companies Covered | Essity Aktiebolag, SINOPULSAR, Procter & Gamble, Smardii Inc., Opro9, Kimberly-Clark, Ontex BV, Monit Corp., Unicharm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Diaper Market Strategic Shifts & Innovations
Product evolution is accelerating the transition from a consumer convenience item to a clinical monitoring instrument. This change is driven by technological convergence, new regulatory pressures, and shifting procurement models in professional healthcare.
Multi-parameter sensor strips combine capacitive wetness detection with temperature and pH level monitoring. Geriatric care facilities and neonatal intensive care units are primary adopters of this more advanced technology. This integration is unifying basic moisture alerts with preliminary health screening, creating a more holistic monitoring tool from a single product.
Europe’s Medical Device Regulation (MDR) establishes stricter requirements for clinical evidence and post-market surveillance. This forces manufacturers to conduct rigorous trials to validate functions like dehydration risk alerts, increasing development costs. The adult incontinence segment is most affected by this shift toward medical-grade validation, as it targets clinical settings.
Institutional buyers are moving from simple per-unit diaper purchasing toward data-as-a-service (DaaS) subscriptions. This model disrupts traditional procurement by bundling the product with a data platform, analytics, and support. The shift is most pronounced in the United States, where providers use data to document care and justify expenditures.
Smart Diaper Market Segmentation
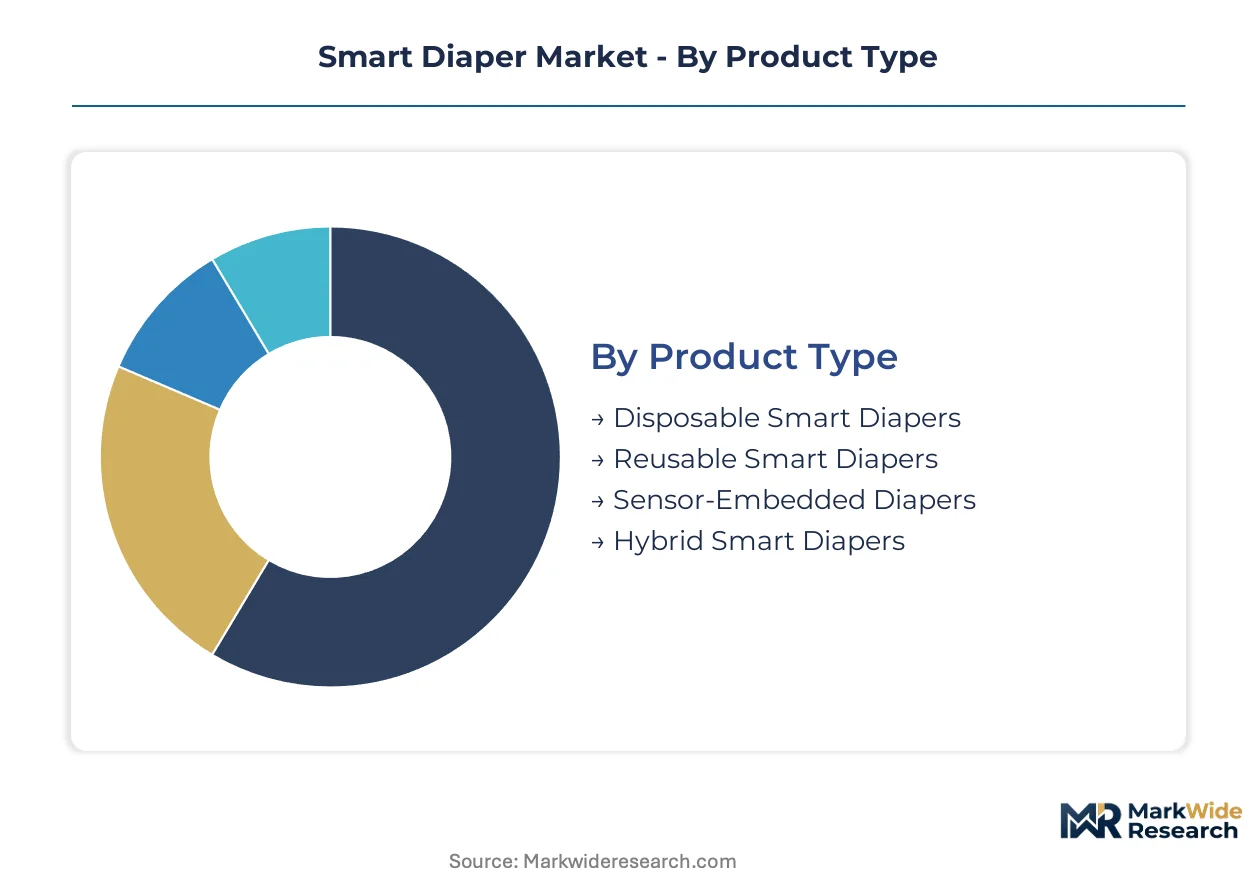
The Smart Diaper Market's segmentation reflects its dual purpose as both a consumer convenience item and a clinical monitoring instrument. Understanding these distinct segments is critical for manufacturers to tailor product development, navigate regulatory pathways, and optimize distribution strategies across varied end-user environments.
Product Type:
The product type segmentation highlights the ongoing tension between product customization for specific needs and standardization for mass market appeal. Each category offers distinct advantages for different care settings and user preferences.
- Disposable Smart Diapers:These single-use products integrate sensors directly into the absorbent material, offering convenience and hygiene. Demand concentrates in both consumer infant care and institutional elderly care settings due to ease of use and reduced cross-contamination risk.
- Reusable Smart Diapers:Featuring washable fabric components and detachable, reusable sensor pods, these products emphasize sustainability and long-term cost efficiency. Institutional settings like geriatric care centers and hospitals increasingly adopt reusable options for their economic and environmental benefits.
- Sensor-Embedded Diapers:This category includes diapers where the electronic monitoring components are permanently integrated into the diaper structure, providing a seamless user experience. Infant care applications frequently utilize this design for simplicity.
- Hybrid Smart Diapers:Hybrid models combine elements of both disposable and reusable designs, often featuring a disposable absorbent pad with a reusable outer shell or sensor system. This design offers flexibility for various care scenarios.
Most installed capacity flows through Disposable Smart Diapers. Expansion is steepest in Reusable Smart Diapers.
Technology:
The technology segmentation differentiates products based on their core sensing mechanisms, impacting data accuracy, cost, and suitability for various clinical applications. Precision and data complexity vary significantly across these sensor types.
- Capacitive Sensors:These sensors detect changes in dielectric properties caused by moisture absorption, providing reliable wetness detection. They are widely adopted in commercial smart diapers due to their cost-effectiveness and proven performance in basic moisture alerts.
- Resistive Sensors:Operating by measuring changes in electrical resistance when exposed to moisture, resistive sensors offer high sensitivity and can detect specific fluid compositions. Clinical applications requiring precise wetness levels or early detection often employ resistive sensor technology.
- RFID Sensors:Radio-frequency identification sensors allow for passive tracking of diaper usage and inventory management within large institutional settings. These sensors primarily support logistical and operational efficiencies.
- Optical Sensors:Optical sensors utilize light to detect changes in color or composition, enabling the potential for biomarker detection such as pH levels or specific chemical indicators. This technology supports advanced health screening.
- Gesture Recognition:Integrating motion sensors, this technology can detect specific movements or patterns, potentially indicating discomfort or a need for changing. It provides an additional layer of patient monitoring beyond simple wetness detection.
Capacitive sensors currently dominate the installed base. Resistive sensors demonstrate the most rapid market penetration.
Application:
The application segmentation highlights the diverse user demographics and care intensities addressed by smart diaper technology. Patient demographics and the intensity of care required drive specific product features and market demand.
- Infant Care:This segment focuses on monitoring wetness and soiling for babies, providing alerts to parents and caregivers. The high-volume consumer market for infant products continues to represent a significant revenue stream.
- Elderly Care:Addressing adult incontinence, this application provides critical monitoring for older adults in home and institutional settings. Developed economies with aging populations, such as Japan and Germany, drive substantial demand.
- Patient Monitoring:This segment encompasses the use of smart diapers for clinical data collection in hospitals and long-term care facilities. It supports remote patient monitoring programs and reduces hospital readmissions in the United States and Europe.
- Maternity Care:Smart diapers can assist in postpartum monitoring for new mothers, tracking fluid output or potential complications. This application often finds use within hospital maternity wards.
- Special Needs Care:This category serves individuals with developmental disabilities or chronic conditions requiring continuous monitoring of their toileting needs. Products here often prioritize durability and specialized alert systems.
Infant care applications command significant market volume. Elderly care applications are gaining share fastest.
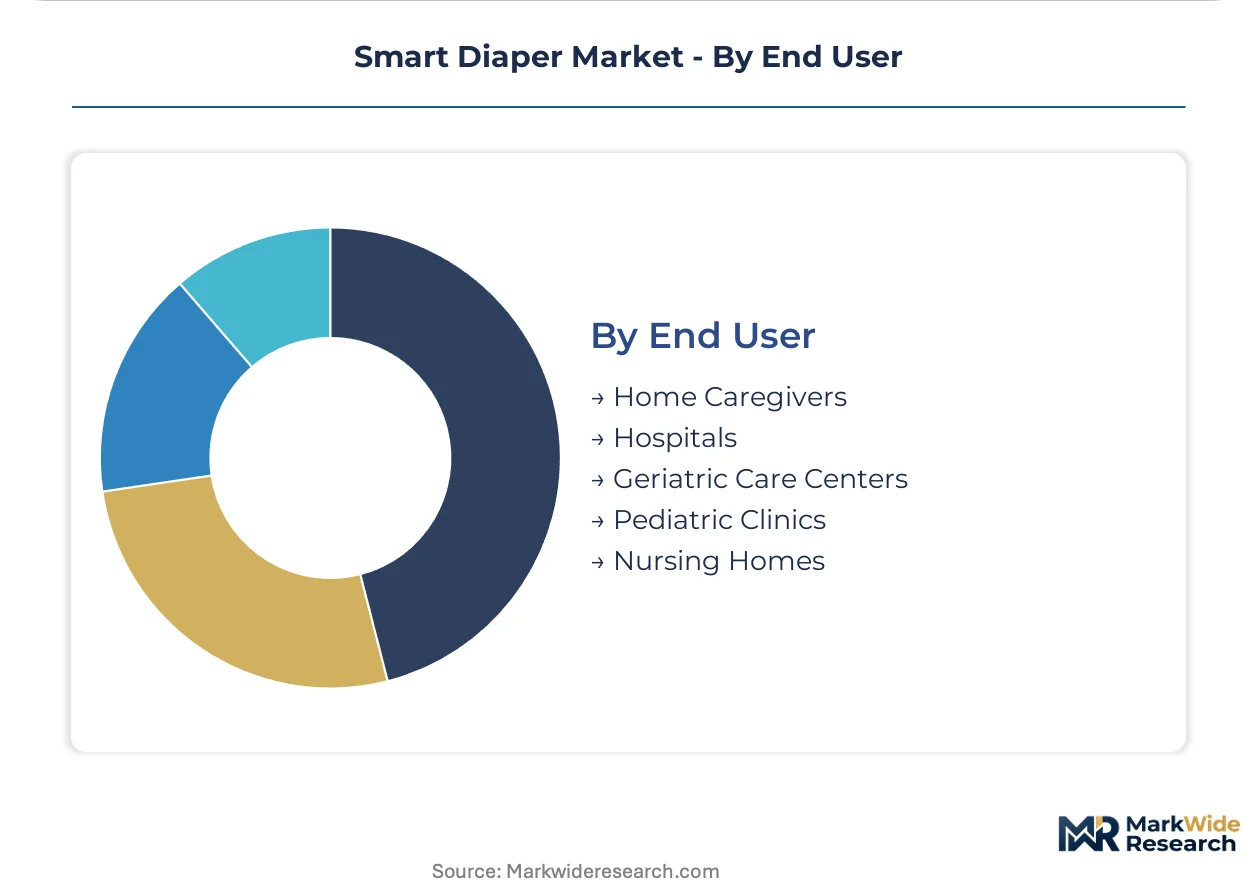
End User:
The end-user segmentation reveals the varied purchasing patterns and operational requirements across different care environments. Care delivery models and procurement strategies significantly influence product adoption in each segment.
- Home Caregivers:This group includes family members or private individuals providing care in a home setting, often for elderly relatives or infants. Their purchasing decisions prioritize ease of use, affordability, and privacy features.
- Hospitals:Hospitals utilize smart diapers for patient monitoring, particularly in geriatric and neonatal intensive care units. Integration with Electronic Health Record systems and high data accuracy are key requirements for hospital procurement.
- Geriatric Care Centers:These facilities cater to the long-term care needs of older adults, where smart diapers enhance resident comfort and staff efficiency in managing incontinence. Bulk purchasing and data-as-a-service models are common in this segment.
- Pediatric Clinics:Pediatric clinics may use smart diapers for specific diagnostic purposes or to monitor infants with particular health conditions. These clinics often require specialized, gentle sensor technologies.
- Nursing Homes:Nursing homes provide residential care for individuals requiring continuous medical attention, making them significant users of smart diapers for incontinence management and resident well-being monitoring. Operational efficiency is a primary driver.
Home caregivers represent a large, distributed user base. Hospitals are significantly increasing their procurement of smart diaper solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States healthcare system anchors significant demand for smart diapers, driven by telehealth expansion and remote patient monitoring initiatives. Japan's demographic shifts also create a substantial need for advanced elderly care solutions. These developed nations, alongside others, are defining the market's trajectory.
United States
United States healthcare providers prioritize smart diapers for remote patient monitoring and reducing hospital readmissions. FDA oversight guides product development for health claims, ensuring device efficacy and safety. Technology clusters in Silicon Valley and Boston actively integrate advanced sensors and data platforms into these solutions.
Japan
Japan's rapidly aging population creates immense demand for smart diapers in elderly care facilities and home settings. METI sets clear standards for consumer electronics integrated within these products, influencing design and functionality. Major medical technology firms in Tokyo and Osaka are developing advanced adult incontinence monitoring solutions.
Germany
Germany's robust geriatric care sector drives demand for smart diapers that offer clinical data accuracy. European Union's MDR establishes strict requirements for product validation, influencing market entry for medical-grade devices. Health tech ecosystems in Munich and Berlin are focusing on integrating smart diapers with professional healthcare monitoring platforms.
South Korea
South Korea's high technology adoption rates and aging demographics fuel demand for advanced smart diaper solutions. The country's MFDS regulates medical devices, ensuring compliance for products making health claims. R&D centers in Seoul and Daejeon are actively innovating miniaturized sensor technologies and data analytics for personal care.
United Kingdom
United Kingdom's National Health Service (NHS) initiatives promote telehealth expansion and chronic condition management, boosting smart diaper adoption. The CQC influences care standards, impacting product features for institutional settings. Digital health hubs in London and Cambridge are developing interoperable platforms for smart diaper data integration.
Smart Diaper Market Key Industry Players
Strategic partnerships dominate the current landscape, as traditional consumer goods firms collaborate with technology specialists. The smart diaper market exhibits a tiered structure, with established players and specialized health technology companies competing. Three strategic archetypes emerge: consumer goods giants, adult incontinence specialists, and sensor technology innovators. Portfolio diversification and technology licensing are also key competitive moves.
Among established consumer goods firms, Procter & Gamble represents a global leader, leveraging extensive distribution networks to integrate smart features into existing product lines for infant care. Essity Aktiebolag, a European-based company, occupies a strong position as an adult incontinence specialist, differentiating through a dedicated focus on professional healthcare channels and clinical-grade features. Smardii Inc. exemplifies a specialized health technology innovator, concentrating on dedicated smart diaper solutions and advanced sensor integration for specific clinical applications. These players anchor different segments of the market, from mass consumer to niche medical.
| Leading Market Players |
|---|
| Essity Aktiebolag |
| SINOPULSAR |
| Procter & Gamble |
| Smardii Inc. |
| Opro9 |
| Kimberly-Clark |
| Ontex BV |
| Monit Corp. |
| Unicharm Corporation |
| Others |
Cost & Logistics Intelligence
Vertical integration into sensor manufacturing anchors the supply position for smart diaper specialists, influencing their pricing power over feature-rich clinical-grade products. This integration strategy secures critical components and differentiates offerings in a competitive market.
Pricing Analysis
Input-cost pass-through from semiconductor components and super-absorbent polymers significantly impacts smart diaper pricing. The market utilizes a hybrid pricing model, combining per-unit transactional sales for disposable products with subscription-based data-as-a-service (DaaS) for institutional clients. Price differentiation stems from clinical validation under FDA oversight or CE marking, and the bundling of advanced data analytics. Pricing softness impacts the cost-sensitive consumer infant care segment due to the premium associated with smart features. Hospitals and geriatric care centers, prioritizing clinical-grade solutions, exhibit lower price sensitivity.
Supply Chain Analysis
Certification and qualification gating, particularly under the EU's Medical Device Regulation (MDR) for medical applications, significantly shapes the smart diaper supply chain. Geographic supply concentrates in China for electronic components and specialized materials from Japan and Germany. Raw material dependencies include miniaturized Bluetooth Low Energy sensors and advanced absorbent polymers. Single-source vulnerability for proprietary sensor technologies presents a structural supply chain risk. Distribution runs through established healthcare channels for clinical applications and consumer retail networks for infant care products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart diaper market functions as a regulatory compounder, with Europe’s Medical Device Regulation (MDR) driving demand for clinically validated, medical-grade solutions in adult incontinence care.
For Market Incumbents:Acquire specialized sensor technology firms to integrate advanced biomarker detection capabilities. Consolidate distribution channels in developed healthcare systems like the United States to counter emerging specialists. Invest in R&D for multi-parameter sensor strips, addressing the hardening market focus on clinical-grade features. This strategy defends against margin pressure from specialized health technology innovators.
For New Entrants and Emerging Players:Biomarker integration into sensor technology offers a technology-first wedge into the patient monitoring segment. Untapped potential exists in markets like South Korea, focusing on specific health conditions such as urinary tract infections. Partner with telehealth platforms for remote patient monitoring, leveraging digital health infrastructure for market penetration. This approach targets white-space opportunities in clinical applications.
For Investors and Strategic Acquirers:Roll-up economics work for specialized health technology innovators because regulatory divergence creates fragmented market entry points. The market's pivot from infant novelty to geriatric necessity ensures sustained demand over the next decade. Target companies with proprietary sensor intellectual property and established clinical validation pathways. Increased Electronic Health Record (EHR) system integration partnerships serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Introduce multi-parameter sensor strips for enhanced health screening in geriatric care facilities. |
| Strategic Partnership | Collaborate with Electronic Health Record (EHR) system providers for seamless data integration in hospitals. |
| Geographic Expansion | Enter high technology adoption markets with aging populations, such as South Korea. |
| Subscription Model Development | Offer data-as-a-service (DaaS) subscriptions to long-term care facilities for recurring revenue. |
| Technology Licensing | License miniaturized Bluetooth Low Energy sensor technology to established consumer goods firms. |
Research Approach
Multiple input streams — industry association reports, regulatory body publications, and company financial disclosures — were reconciled. Primary interviews with R&D directors, hospital procurement managers, geriatric care facility administrators, and regulatory affairs specialists provided qualitative insights. Secondary validation used data from FDA filings, EU MDR guidelines, and METI standards for consumer electronics. This approach ensured bottom-up and top-down triangulation for market sizing.
Historical market performance was cross-referenced against expert panel input to establish a robust analytical framework across the analysis window. The framework modeled segmentation dimensions including product type, technology, application, and end user, alongside regional regulatory compliance. Compound annual growth rates were derived from a multi-variant regression analysis. Key forecast inputs included aging population demographics and telehealth expansion rates.
The model holds under current regulatory frameworks and technological development trajectories; deviation in data privacy regulations or sensor miniaturization advancements would shift projections. Forecasts reflect assumptions regarding healthcare system incentives and consumer adoption rates. A model refresh is warranted upon material change in medical device classification rules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Europe Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Latin America Diaper Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
GCC Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
United States Diaper Market