
 Pocket Flask Market | 2026-2036
Pocket Flask Market Size, Share, and Industry Trends Forecast 2026-2036
Pocket Flask Market Analytics
Asset-light direct-to-consumer leasing is reconfiguring entry barriers for emerging flask brands. Jacob Bromwell leverages its heritage craftsmanship to sustain premium positioning in hand-hammered copper and pewter segments. BrüMate competes through insulated stainless steel technology that extends temperature retention across outdoor usage occasions. English Pewter Co. anchors its model on vertical control over Sheffield-based casting operations.
A pocket flask is a compact, curved vessel engineered to carry distilled spirits or wine in personal quantities, typically constructed from stainless steel, pewter, or food-grade polymers with leak-proof threaded or captive-cap closures; wall thickness ranges from 0.5 mm to 1.2 mm depending on material, and interior surfaces require passivation or electrolytic polishing to prevent flavor contamination. Stainless steel occupies the dominant share due to corrosion resistance and laser-weldability, while plastic variants are gaining fastest in price-sensitive camping and tailgating channels where weight reduction outweighs thermal performance. The 6 oz and 8 oz capacity bands concentrate margin pools in gift and everyday-use occasions, whereas 2 oz formats remain niche in airline and festival access segments.
The FDA regulates food-contact substances under 21 CFR 177 for polymer migration limits, while the EU REACH framework restricts nickel leaching from metal alloys in prolonged liquid contact. California Proposition 65 adds labeling burdens for chromium and lead content in decorative pewter finishes. Stakeholders must monitor evolving state-level restrictions on public alcohol container possession that could redefine permissible usage occasion marketing.
Market Dynamics
Outdoor recreation retailers are expanding shelf space allocation for portable beverage containers, while FDA migration limits for food-contact polymers are tightening material specifications across the supply base. This dual pressure from channel expansion and regulatory compression is reconfiguring competitive positioning among stainless steel, pewter, and polymer flask variants.
Growth Catalysts
- REACH nickel-leaching restrictions:The EU framework limits metal alloy migration in prolonged liquid contact, accelerating stainless steel substitution for unlined pewter in European duty-free and gift channels.
- Camping and tailgating weight priorities:Polymer variants are gaining fastest in price-sensitive outdoor channels where thermal performance matters less than packability.
- California Proposition 65 labeling:Chromium and lead disclosure requirements for decorative finishes are pushing manufacturers toward electrolytic-polished interiors and laser-welded seams.
Market Restraints
- Nickel price volatility:Austenitic stainless steel grades depend on nickel content, exposing margin structures to London Metal Exchange fluctuations.
- Sheffield casting concentration:Vertical control over pewter foundry operations limits supplier diversification for heritage-positioned brands.
- Polymer migration testing costs:21 CFR 177 compliance requires iterative extraction studies that disproportionately burden sub-$15 retail price points.
Strategic Opportunities
- Festival access segments:2 oz capacity formats remain underpenetrated in airline and event-security channels where container size restrictions apply.
- Direct-to-consumer leasing models:Asset-light subscription approaches are lowering entry barriers for emerging flask brands without retail slotting fees.
- Insulated stainless steel convergence:Vacuum-walled construction from outdoor drinkware is migrating into premium flask categories, extending temperature retention claims.
Industry Challenges
- Passivation chemistry expertise:Interior surface treatment to prevent flavor contamination requires specialized electrochemical knowledge concentrated among contract metal finishers.
- State-level possession law fragmentation:Public alcohol container regulations vary by municipality, complicating permissible usage occasion marketing and packaging claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pocket Flask Market |
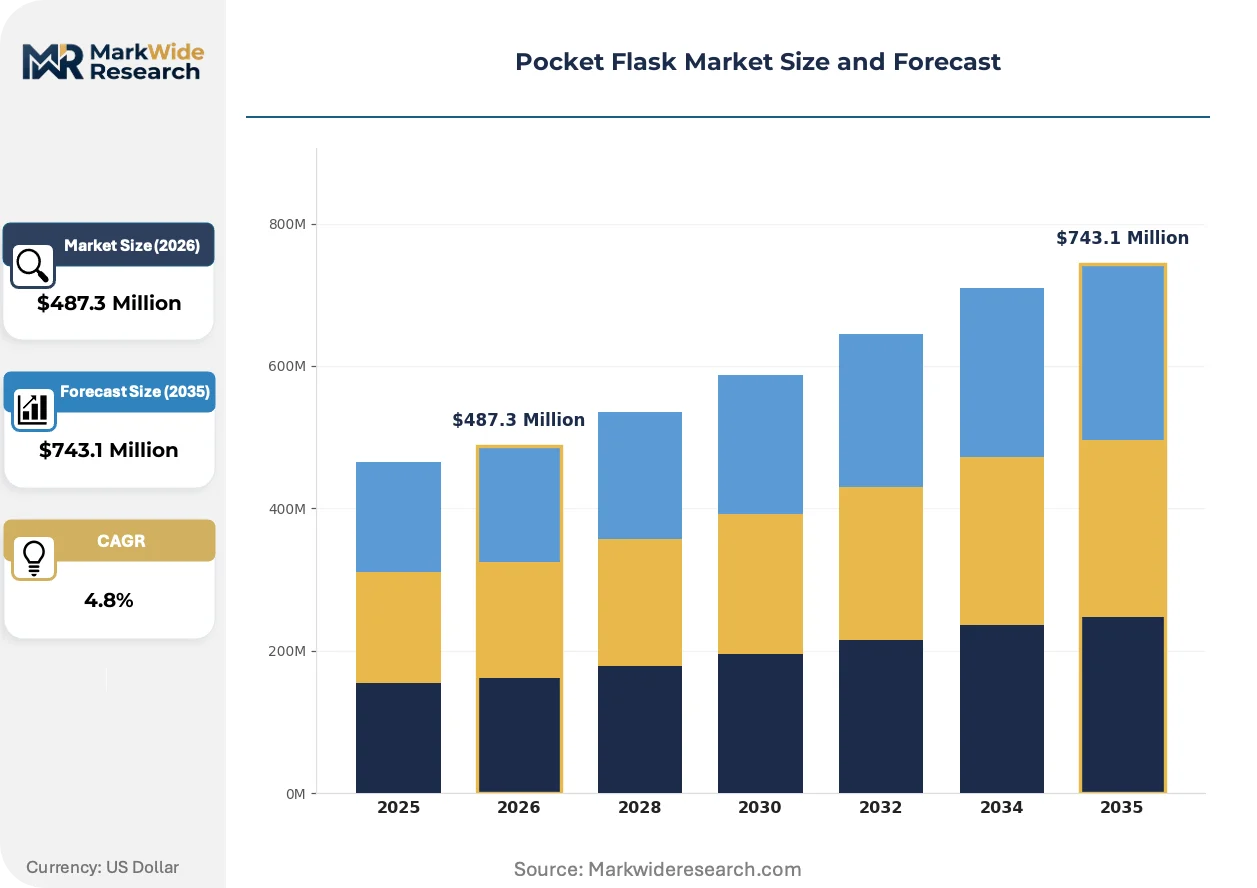
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Plastic, Glass, Aluminum Design Style: Classic, Modern, Vintage, Sports Capacity: 2 oz, 4 oz, 6 oz, 8 oz Usage Occasion: Camping, Tailgating, Everyday Use, Gifts |
| Companies Covered | Himalyan Equipment Manufacturing Co., English Pewter Co., Jacob Bromwell, Wentworth Pewter, Alfred Dunhill, Aspinal of London, Flaskaholic, BrüMate, The Whiskey Exchange, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pocket Flask Market Evolving Landscape
Material science advances and channel restructuring are compressing traditional manufacturing timelines while expanding performance expectations across price tiers. Three developments are actively reshaping how flasks are specified, sourced, and sold.
Electrochemical polishing is hybridizing with laser-welded seam construction to eliminate interior crevices where residual spirits accumulate and degrade flavor profiles. Premium outdoor retailers are specifying these combined treatments for gift-tier stainless steel lines, forcing contract manufacturers to retool from mechanical buffing to electrolytic finishing. The shift is compressing supplier margins on standard-grade products while creating tier separation at the $35-plus retail threshold.
REACH Annex XVII nickel restrictions are tightening test protocols for metal alloys in prolonged beverage contact, extending compliance documentation requirements from raw mills to finished goods importers. German and French customs authorities are rejecting shipments lacking migration certificates, forcing Asian contract manufacturers to source certified 304L and 316L grades exclusively. The regulatory friction is accelerating consolidation among European distributors with in-house metallurgical testing capabilities.
Buyers are consolidating purchase authority through specialty outdoor e-commerce platforms that unbundle after-sales service from product acquisition. Independent gear review sites and subscription curation services are displacing traditional gift-shop distribution for first-time flask purchases, particularly among millennial and Gen Z demographics. This channel rotation is most visible in United States and Canadian markets where REI, Backcountry, and direct brand sites now capture majority share of insulated stainless steel flask transactions.
Pocket Flask Market Segmentation
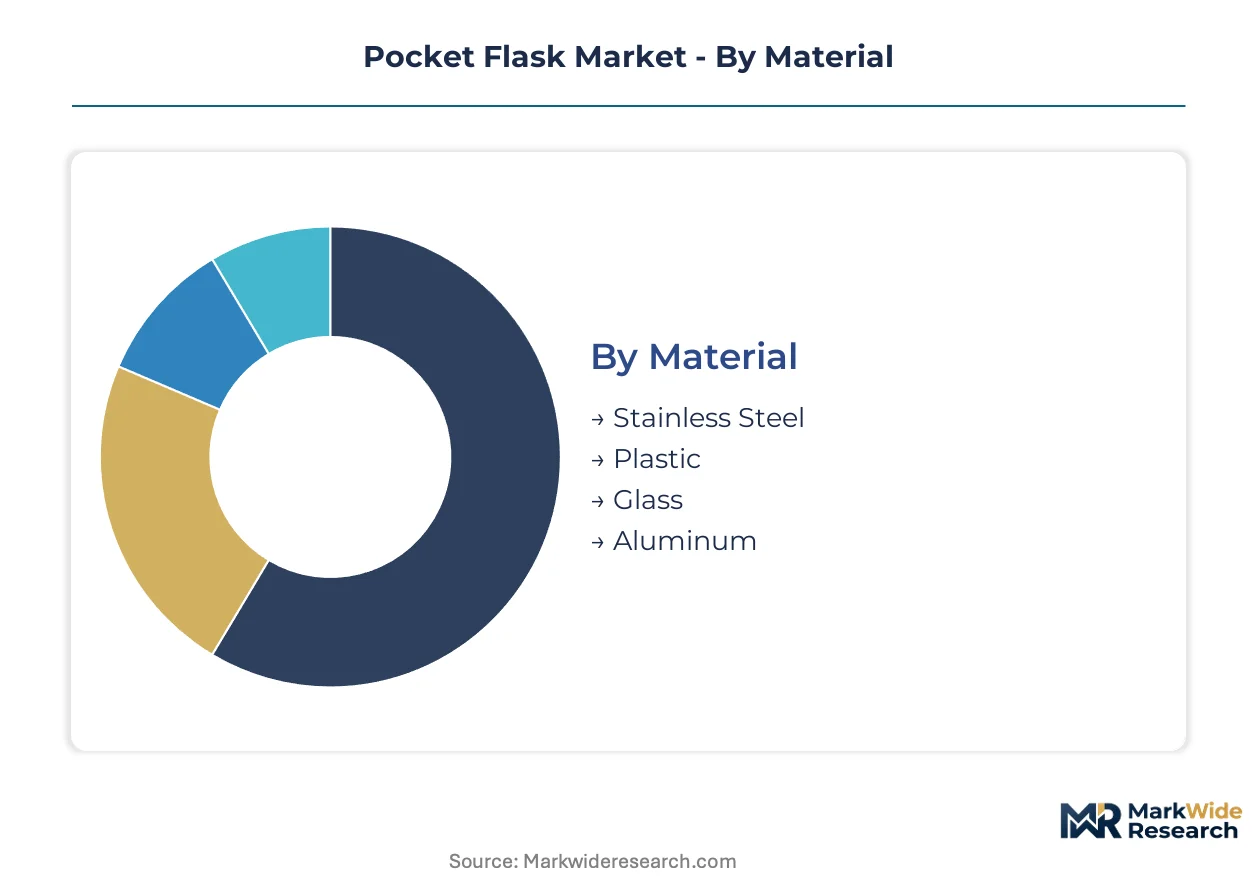
Material chemistry and capacity specifications dictate manufacturing lead times and inventory velocity across pocket flask supply chains. Design positioning and usage occasion segmentation determine channel placement and margin capture in this fragmented personal beverage container market.
Material:
Cycle times stretch longest for heritage metalworking processes while polymer injection molding turns inventory fastest.
- Stainless Steel:Austenitic grades 304L and 316L dominate through laser-weldability and passivation compatibility. Demand concentrates in Germany, Japan, and the United States where REACH nickel-leaching protocols and FDA food-contact standards enforce premium-grade sourcing. Electrochemical polishing requirements extend supplier qualification timelines to 14-18 weeks.
- Plastic:Food-grade polymers with sub-0.5 mm wall thicknesses enable sub-4-week production cycles. Camping and tailgating channels in price-sensitive North American markets absorb volume where thermal performance yields to packability priorities. 21 CFR 177 migration testing adds fixed compliance costs that compress margins below $15 retail.
- Glass:Borosilicate and soda-lime variants serve aesthetic-focused gift segments with extended curing and annealing requirements. Interior coating technologies for flavor neutrality remain underdeveloped relative to metal alternatives.
- Aluminum:Anodized 6061-T6 grades occupy mid-tier positioning with faster machining cycles than stainless but inferior corrosion resistance in prolonged spirit contact. Liner requirements add process complexity.
Stainless steel anchors the volume base while plastic gains share at the steepest rate.
Design Style:
Heritage craftsmanship commands extended production schedules while minimalist contemporary formats compress design-to-shelf timelines.
- Classic:Rounded rectangular profiles with captive-hinged caps reference early 20th-century form factors. Sheffield-based pewter casting and hand-hammered copper finishing sustain 8-12 week fulfillment cycles for heritage-positioned brands.
- Modern:Clean geometric lines with threaded polymer seals and matte PVD coatings align with outdoor retail aesthetics. Backcountry and REI shelf placement favors this styling for millennial and Gen Z demographics.
- Vintage:Art deco embossing and hammered surface textures require dedicated tooling investments. Gift-channel concentration in duty-free and specialty retail limits volume scalability.
- Sports:Team-licensed graphics and durable powder-coated finishes target tailgating occasions. Licensed IP agreements extend approval cycles and royalty structures.
Modern styling captures the majority of new product development investment while Classic formats defend margin concentration in premium gift tiers.
Capacity:
Larger formats amortize fixed tooling across greater liquid volume while micro-capacity designs serve regulatory-constrained occasions.
- 6 oz:The dominant commercial band balancing portability with sufficient volume for shared consumption. Everyday-use positioning across United States and German retail channels sustains replenishment velocity.
- 8 oz:Extended-wall construction for weekend-length outdoor excursions. Vacuum-insulated variants from outdoor drinkware suppliers are migrating into this capacity tier.
- 4 oz:Compact pocket profiles for urban commuting and discrete personal use. Lighter weight specification favors aluminum and polymer construction.
- 2 oz:Airline security-compliant and festival-access formats where container size restrictions apply. Underpenetrated relative to regulatory opportunity in event-security channels.
Six-ounce formats anchor manufacturer volume planning while two-ounce designs are expanding most quickly in regulated-access verticals.
Usage Occasion:
Planned outdoor recreation drives seasonal demand spikes while everyday carry sustains baseline manufacturing utilization.
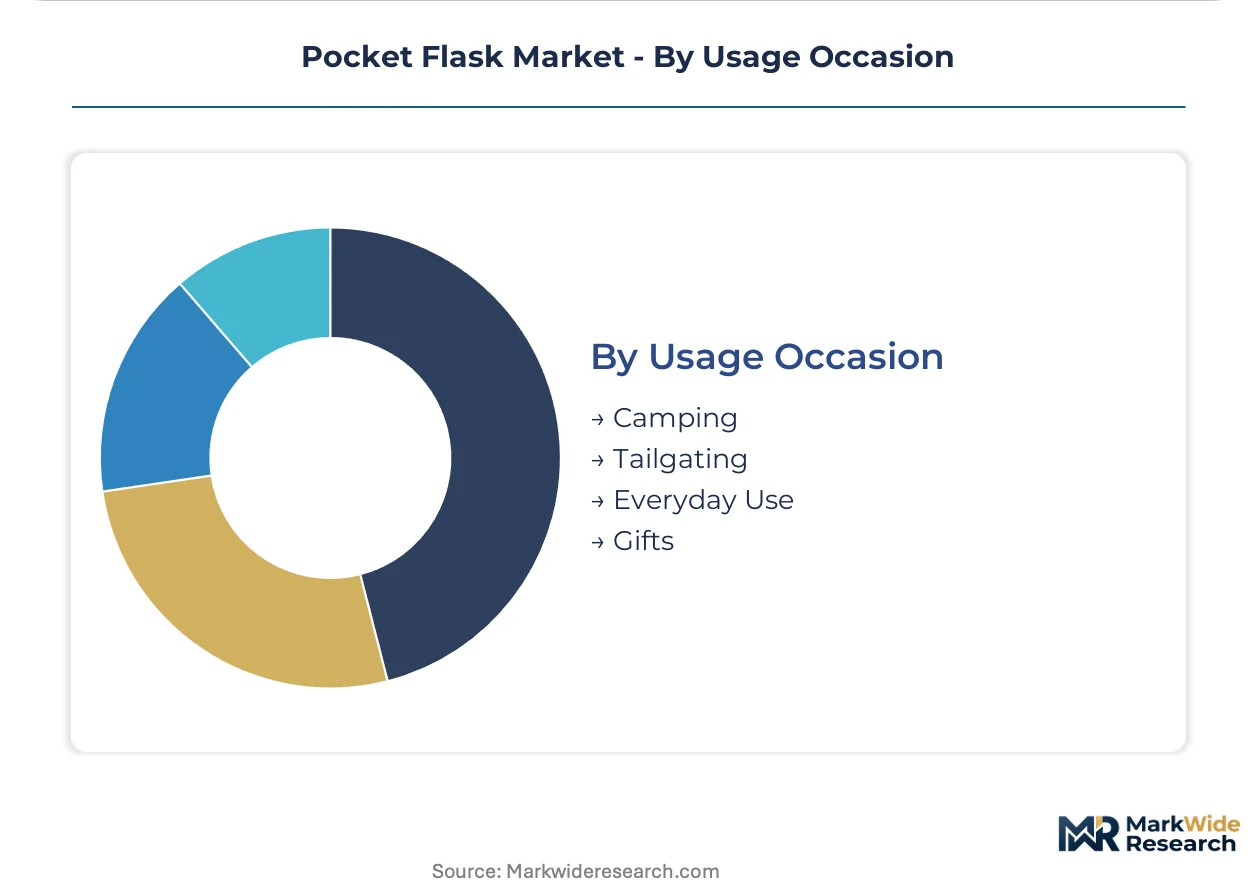
- Camping:Weight-reduction priorities favor polymer and thin-wall aluminum construction. REI and Backcountry platform consolidation is displacing traditional sporting goods distribution for first-time purchases.
- Tailgating:Durability and team-affiliation signaling dominate specification. Sports-licensed graphics and powder-coated finishes command shelf space in collegiate and professional market proximity.
- Everyday Use:Discreet pocket profiles with leak-proof sealing sustain replacement cycles. Stainless steel 6 oz and 8 oz variants concentrate in this recurring-revenue segment.
- Gifts:Presentation packaging and engraving services extend value capture. Heritage metalworking and vintage styling align with occasion-based premium pricing.
Everyday use stabilizes production scheduling while camping applications are climbing the fastest through outdoor retailer expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German stainless steel flask manufacturers capture pricing premiums through REACH-certified metallurgical documentation, while Chinese contract fabricators compete on compressed lead times for polymer variants. This asymmetry shapes regional sourcing patterns across gift and outdoor retail channels.
United States
REI and Backcountry platform consolidation concentrates insulated stainless steel demand among millennial and Gen Z demographics. FDA 21 CFR 177 migration limits for food-contact polymers tighten material specifications for camping-oriented plastic flasks. Sheffield pewter imports face California Proposition 65 labeling burdens for chromium and lead disclosure in decorative finishes.
Germany
REACH Annex XVII nickel-leaching restrictions accelerate stainless steel substitution for unlined pewter in duty-free and gift channels. German customs authorities reject shipments lacking certified 304L and 316L migration documentation. Munich and Frankfurt airport retail clusters drive premium 6 oz and 8 oz format specifications for business traveler segments.
Japan
METI-administered JIS standards enforce rigorous surface passivation requirements for interior flask finishes. Tokyo and Osaka department store gift channels sustain demand for electrochemically polished stainless steel with laser-welded seams. Domestic metalworking clusters in Tsubame-Sanjo supply heritage-positioned brands with specialized electrolytic finishing capabilities.
United Kingdom
Sheffield-based pewter casting operations anchor vertical supply control for heritage craftsmanship positioning. English Pewter Co. and Wentworth Pewter exemplify this concentration in South Yorkshire metalworking districts. Brexit customs friction extends lead times for EU-bound finished goods, compressing margin structures on sub-£25 retail price points.
China
Zhejiang and Guangdong injection molding clusters turn polymer flask inventory in sub-4-week cycles for North American camping channels. GB standards for food-contact plastics lag REACH and FDA stringency, creating compliance documentation gaps for direct EU and US export. NMPA alignment initiatives are gradually harmonizing migration testing protocols with international benchmarks.
Pocket Flask Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive metallurgical and molding capabilities. The vendor base stratifies across three functional tiers: heritage metalworking houses with foundry control, outdoor drinkware platforms with insulated stainless steel convergence, and contract manufacturers serving private-label retail programs. Competitive moves center on backward integration into certified raw material sourcing and direct-to-consumer channel unbundling that displaces traditional gift-shop distribution.
Among heritage-positioned metalworkers, English Pewter Co. and Jacob Bromwell exemplify archetypes anchored in vertical manufacturing control and craft narrative positioning. BrüMate occupies the insulated technology tier where vacuum-walled construction from outdoor drinkware migrates into premium flask categories. These three company structures illustrate how competitive positioning separates through material science investment versus brand storytelling emphasis.
| Leading Market Players |
|---|
| Himalyan Equipment Manufacturing Co. |
| English Pewter Co. |
| Jacob Bromwell |
| Wentworth Pewter |
| Alfred Dunhill |
| Aspinal of London |
| Flaskaholic |
| BrüMate |
| The Whiskey Exchange |
| Others |
Value Network & Pricing Analysis
Overcapacity in Zhejiang injection molding clusters is compressing polymer flask margins while tightening electrochemical polishing capacity in Tsubame-Sanjo sustains stainless steel premiums. This utilization asymmetry shapes supplier bargaining power across material tiers and forces buyers to accept extended lead times for certified metal grades or absorb compliance costs for rapid polymer turnaround.
Pricing Analysis
The customization-premium spread spans roughly 40-60 percentage points between configured-to-order engraving services and standard SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and surface finish complexity. Price differentiation hinges on FDA 21 CFR 177 compliance documentation and laser-welded seam construction. Pricing pressure stems from nickel price volatility on the London Metal Exchange, which squeezes austenitic stainless steel margins. Camping and tailgating channels exhibit highest price sensitivity, while gift and heritage segments absorb premiums for Sheffield pewter and hand-hammered copper finishes.
Supply Chain Analysis
Export-control regimes limiting dual-use laser-welding technology transfers constrain advanced seam construction capacity in certain Asian manufacturing zones. Supply concentrates in China for polymer injection molding, Germany for REACH-certified stainless steel finishing, and the United Kingdom for heritage pewter casting. Raw material dependencies rest on nickel ore flows from Indonesia and the Philippines, food-grade polymer resins from Saudi petrochemical complexes, and tin for pewter alloys from Peruvian and Indonesian mines. Single-source vulnerability sits with Sheffield-based foundry operations for heritage-positioned brands. Distribution runs through outdoor specialty retailers, direct-to-consumer platforms, and duty-free airport clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against insulated vacuum-walled drinkware convergence from outdoor equipment suppliers. Incumbents must navigate BrüMate-style thermal retention technology eroding traditional flask utility.
For Market Incumbents: Insulate heritage positioning through captive Sheffield foundry relationships and METI-grade passivation certification investments. Deepen backward integration into certified 304L and 316L raw material sourcing to buffer nickel price volatility. Defend gift-channel margins by bundling engraving services with electrochemically polished interiors that polymer competitors cannot replicate.
For New Entrants and Emerging Players: Festival access verticals in North America and European duty-free corridors offer underpenetrated white space for 2 oz micro-capacity formats. Target airline security-compliant segments where container size restrictions create regulatory moats. Deploy direct-to-consumer leasing models to bypass retail slotting fees and gather usage data for rapid product iteration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrochemical polishing and laser-welding equipment tiers. Long-term viability favors vertically integrated mid-cap specialists with in-house metallurgical testing capabilities rather than pure brand plays. Watch for REACH Annex XVII enforcement tightening as the signal indicating consolidation pressure on undocumentated Asian contract manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Raw Material Sourcing | REACH and FDA compliance documentation secures German and US customs clearance. |
| Direct-to-Consumer Platform Launch | REI and Backcountry consolidation makes owned channels essential for margin capture. |
| Insulated Stainless Steel Technology Migration | Vacuum-walled construction from outdoor drinkware extends temperature retention claims. |
| Electrochemical Polishing Capability Investment | Tsubame-Sanjo expertise concentration creates scarcity value in premium gift tiers. |
| Festival Access Segment Expansion | 2 oz formats exploit airline and event-security container size restrictions. |
Research Methodology
A spread of perspectives from stainless steel mill procurement managers, outdoor retailer category buyers, Sheffield foundry operators, and FDA regulatory consultants converged on the working assumptions. Primary interviews with heritage brand metalworkers and polymer injection molding engineers combined with secondary validation from customs trade databases, SEC filings of outdoor equipment suppliers, and REACH Annex XVII guidance documents. Bottom-up capacity assessments across Zhejiang, Guangdong, and Tsubame-Sanjo manufacturing clusters triangulated against top-down demand modeling from REI and Backcountry platform data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry, capacity specification, design styling, and usage occasion clustering. CAGRs derived from iterative reconciliation of channel inventory velocity data and raw material input cost trajectories. Nickel price forecasting inputs from London Metal Exchange futures curves and polymer resin cost indices from Saudi petrochemical benchmark pricing informed value projections.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on outdoor recreation and business travel recovery patterns would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and channel consolidation pace. Material shifts in FDA migration limit stringency or state-level public alcohol container possession law fragmentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Pod Vape Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Rolling Papers Market
Smoking Accessories
Herb Grinder Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
North America Smoking Pipe Market
Smoking Accessories
Japan Smoking Accessories Market
Smoking Accessories
Lighter Market
Smoking Accessories
Electric Pocket Lighter Market
Smoking Accessories
Latin America Cigarette Lighter Market
Smoking Accessories
UK Smoking Pipe Market
Smoking Accessories
North America Cigarette Lighter Market