
 United States Acetonitrile Market | 2026-2036
United States Acetonitrile Market Size, Share, and Industry Trends Forecast 2026-2036
United States Acetonitrile Market Intelligence
Multi-source procurement among pharmaceutical solvent buyers is expanding as supply security concerns reshape purchasing patterns. INEOS AG leverages its integrated acrylonitrile platform to sustain cost-competitive acetonitrile output along the Gulf Coast. Nova Molecular Technologies specializes in high-purity grades that anchor its position in analytical and pharmaceutical applications. Avantor competes through channel control, extending its distribution reach across research institutions and contract manufacturing organizations.
Acetonitrile is a polar aprotic solvent with the chemical formula CH₃CN, manufactured primarily as a byproduct of acrylonitrile production via propylene ammoxidation or through direct synthesis routes; its low viscosity and high dielectric constant make it indispensable for high-performance liquid chromatography and pharmaceutical extraction processes. Solvent applications dominate volume consumption, while pharmaceutical intermediates represent the fastest-expanding segment as peptide therapeutics and generic API manufacturing scale. Research institutions sustain steady demand for laboratory reagent grades, though this channel carries thinner margins than pharmaceutical direct sales.
EPA oversight of acrylonitrile production byproducts shapes environmental compliance costs for domestic manufacturers, while OSHA workplace exposure limits influence handling protocols across chemical manufacturing facilities. FDA standards for solvent residual limits in drug products directly determine specification requirements for pharmaceutical-grade acetonitrile. Stakeholders must monitor evolving EPA rules on per- and polyfluoroalkyl substances that could redirect solvent selection in analytical methods and pharmaceutical processes.
Market Dynamics
Acetonitrile supply security concerns are intensifying as pharmaceutical manufacturers confront the concentration of byproduct-derived production along the Gulf Coast petrochemical corridor. Domestic buyers now prioritize dual-source qualification to mitigate single-point-of-failure risks in solvent procurement.
Growth Catalysts
- Peptide therapeutic manufacturing:Contract development organizations are scaling solid-phase peptide synthesis capacity, driving solvent consumption for coupling reactions and resin washing operations.
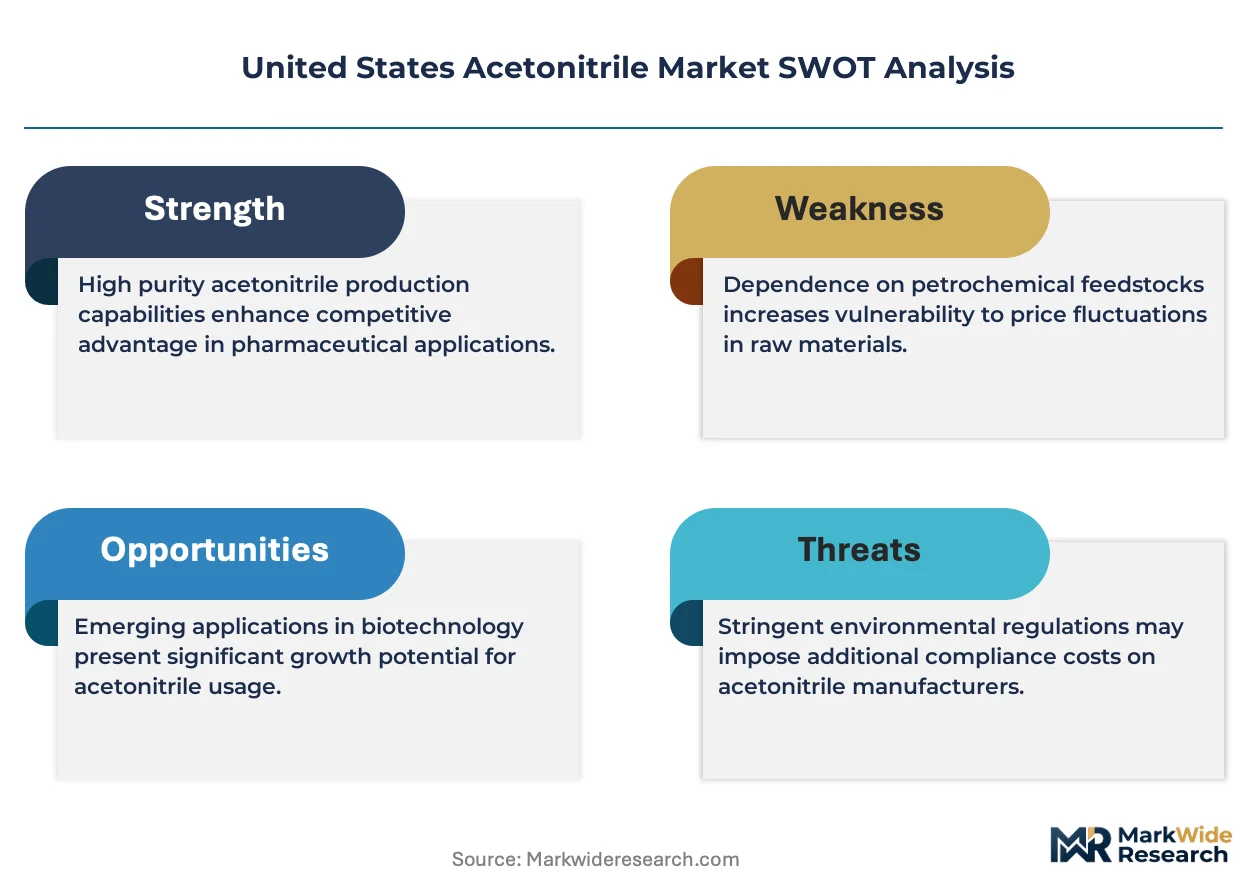
- EPA residual solvent frameworks:FDA alignment with ICH Q3C guidelines sustains demand for pharmaceutical-grade material meeting strict acetonitrile limits in final drug products.
- HPLC method proliferation:Analytical laboratories across generics manufacturers are expanding chromatography infrastructure for impurity profiling and stability testing.
Market Restraints
- Acrylonitrile feedstock volatility:Propylene price swings and ammonia cost pressure transmit directly to acetonitrile economics, compressing margins for non-integrated producers.
- Gulf Coast concentration risk:Hurricane exposure and petrochemical corridor disruption threaten 70% of domestic byproduct supply, forcing buyers to maintain strategic inventories.
- Dimethyl sulfoxide substitution:Polar aprotic alternatives are capturing select extraction applications where solvent recovery economics favor DMSO recyclability.
Strategic Opportunities
- Direct synthesis investment:Methane-ammonia oxidative coupling technology offers route diversification beyond acrylonitrile byproduct dependency for new market entrants.
- Biopharma CDMO expansion:Peptide-drug conjugate manufacturing in the Research Triangle and Boston-Cambridge corridor creates localized demand pockets for high-purity solvent.
- OSHA exposure limit revisions:Stricter workplace handling standards favor suppliers with advanced containment and closed-loop transfer systems.
Industry Challenges
- Chromatography-grade certification timelines:Lot testing for UV transmittance and gradient baseline requirements extends qualification cycles for new supplier onboarding.
- Specialized bulk logistics:Hazmat transportation capacity constraints and driver certification shortages complicate just-in-time delivery to inland pharmaceutical manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Acetonitrile Market |
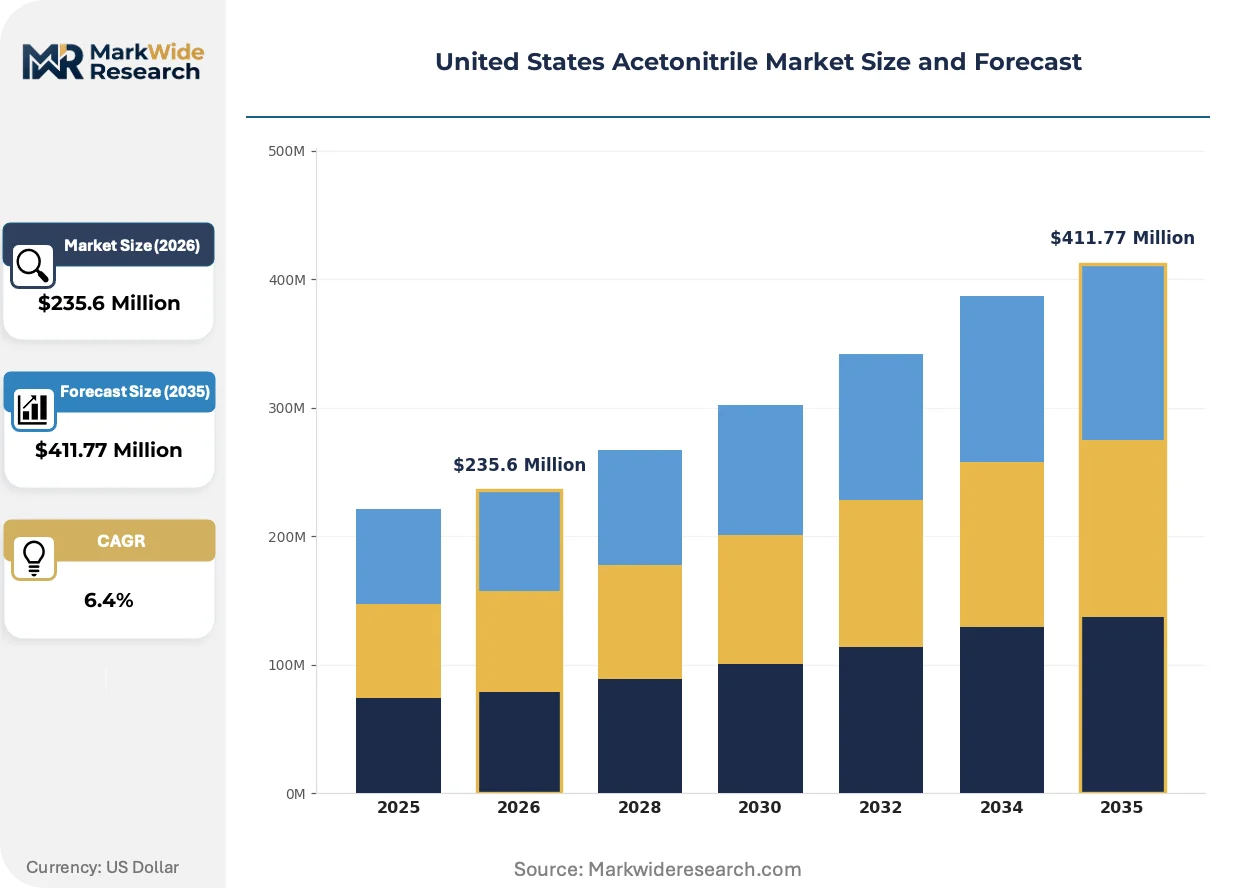
| Market Size in 2026 | $235.6 Million |
| Market Size in 2035 | $411.77 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Solvent, Laboratory Reagent, Pharmaceutical Intermediates, Extraction Agent End User: Chemical Manufacturing, Pharmaceutical Companies, Research Institutions, Academia Form: Liquid, Crystalline, Powder, Gas Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | INEOS AG, Asahi Kasei Corporation, Nova Molecular Technologies, Avantor, Honeywell International, Tedia Company, PerkinElmer, BASF, Mitsubishi Chemical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Acetonitrile Market Strategic Shifts & Innovations
Continuous processing technologies are reshaping how pharmaceutical manufacturers consume acetonitrile, with flow chemistry adoption altering batch-size economics and solvent recovery system design. These shifts are compressing traditional supply relationships while creating openings for service-integrated vendors.
Membrane-based solvent recovery systems are overtaking conventional distillation for acetonitrile reclamation in high-throughput analytical laboratories. Large contract research organizations in New Jersey and Pennsylvania are deploying nanofiltration units that cut energy consumption by half compared to thermal separation. This technology is overtaking incumbent recovery methods by enabling real-time solvent loop closure without batch downtime.
EPA enforcement of the National Emission Standards for Hazardous Air Pollutants for acrylonitrile production is tightening vent control requirements at integrated facilities. Manufacturers must install enhanced thermal oxidizers and leak detection systems, raising capital intensity for byproduct recovery operations. Pharmaceutical-grade specification tiers are widening as some suppliers invest in secondary purification while others exit the highest-purity segment.
Multi-year offtake agreements with volume flexibility clauses are displacing spot-market purchasing among top-twenty generic drug manufacturers. These arrangements transfer inventory carrying costs to distributors while locking in base-load commitments. The shift is most visible in the Midwest pharmaceutical corridor, where Indianapolis and Chicago-area manufacturers are consolidating supplier panels to three qualified vendors maximum.
United States Acetonitrile Market Segmentation
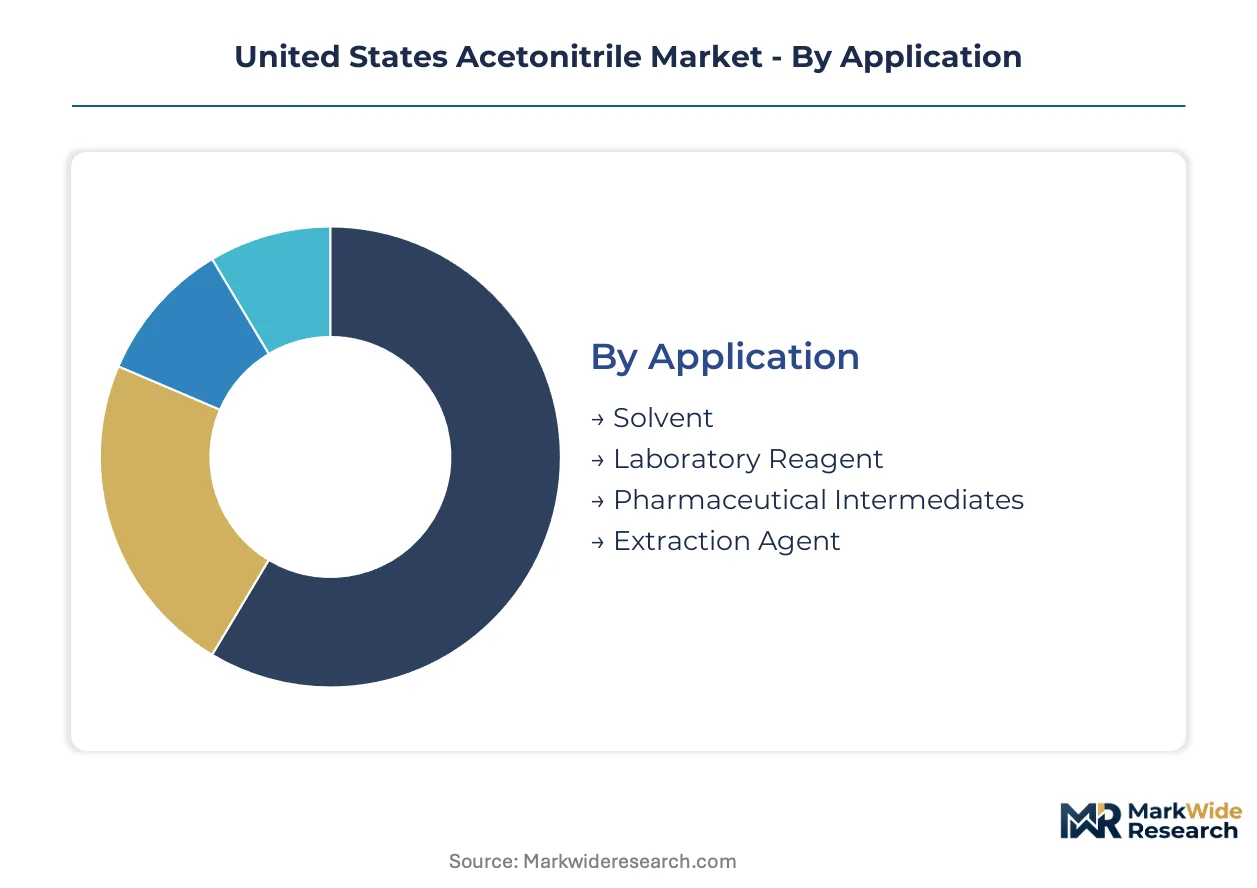
Acetonitrile consumption patterns diverge sharply across buyer types, with pharmaceutical manufacturers prioritizing lot traceability and purity certification while research institutions optimize for packaging flexibility and delivery cadence. These divergent procurement logics create distinct competitive arenas within the same chemical category.
Application:
Buyers in this category separate by performance threshold requirements and regulatory exposure intensity.
- Solvent:Polar aprotic solvent properties enable HPLC mobile phases and reaction media for peptide synthesis. Pharmaceutical contract manufacturers in the Boston-Cambridge corridor consume bulk volumes for solid-phase synthesis washing operations, with EPA residual solvent frameworks dictating specification tiers.
- Pharmaceutical Intermediates:Serves as building block for vitamin B1 synthesis and agricultural chemical precursors. Generic API manufacturers along the Gulf Coast petrochemical corridor anchor demand, though peptide therapeutic expansion is redirecting volume toward specialized CDMOs.
- Laboratory Reagent:Chromatography-grade material for analytical method development and quality control. Research institutions sustain steady offtake with thinner margin profiles than pharmaceutical direct sales.
- Extraction Agent:Deployed in botanical processing and specialty chemical purification. Select applications face substitution pressure from dimethyl sulfoxide where solvent recovery economics favor alternative recyclability.
Solvent leads volumes today; pharmaceutical intermediates is gaining share fastest.
End User:
Procurement scale and specification stringency create tiered supplier relationships across buyer types.
- Pharmaceutical Companies:Drive premium-grade demand through FDA-aligned ICH Q3C compliance requirements. Multi-year offtake agreements with volume flexibility clauses are displacing spot purchasing among top-twenty generic manufacturers.
- Chemical Manufacturing:Consumes technical grades for acrylonitrile derivative production and specialty chemical synthesis. Integrated Gulf Coast producers often source captively from acrylonitrile byproduct streams.
- Research Institutions:Require small-package distribution with rapid fulfillment. Channel control through specialized distributors sustains margin capture despite lower per-order values.
- Academia:Price-sensitive procurement with seasonal budgeting cycles. Online retail channels are capturing share through transparent pricing and consolidated shipping.
Pharmaceutical companies dominate value capture; research institutions are expanding order frequency fastest.
Form:
Physical state determines packaging, handling protocols, and transportation regulatory classification.
- Liquid:Dominant commercial form delivered in bulk tank trucks, drums, and amber glass containers. Hazmat transportation capacity constraints and driver certification shortages complicate just-in-time delivery to inland pharmaceutical sites.
- Crystalline:High-purity solid form for specialized analytical applications requiring precise weighing. Limited domestic production elevates import dependency for ultra-high specification material.
- Powder:Niche applications in solid-phase synthesis support reagents. Handling requires controlled atmosphere facilities to prevent moisture absorption.
- Gas:Minimal volume segment for calibration standards and specialized reaction atmospheres. Cylinder logistics restrict geographic service radius.
Liquid commands absolute volume dominance; crystalline forms exhibit the steepest expansion trajectory.
Distribution Channel:
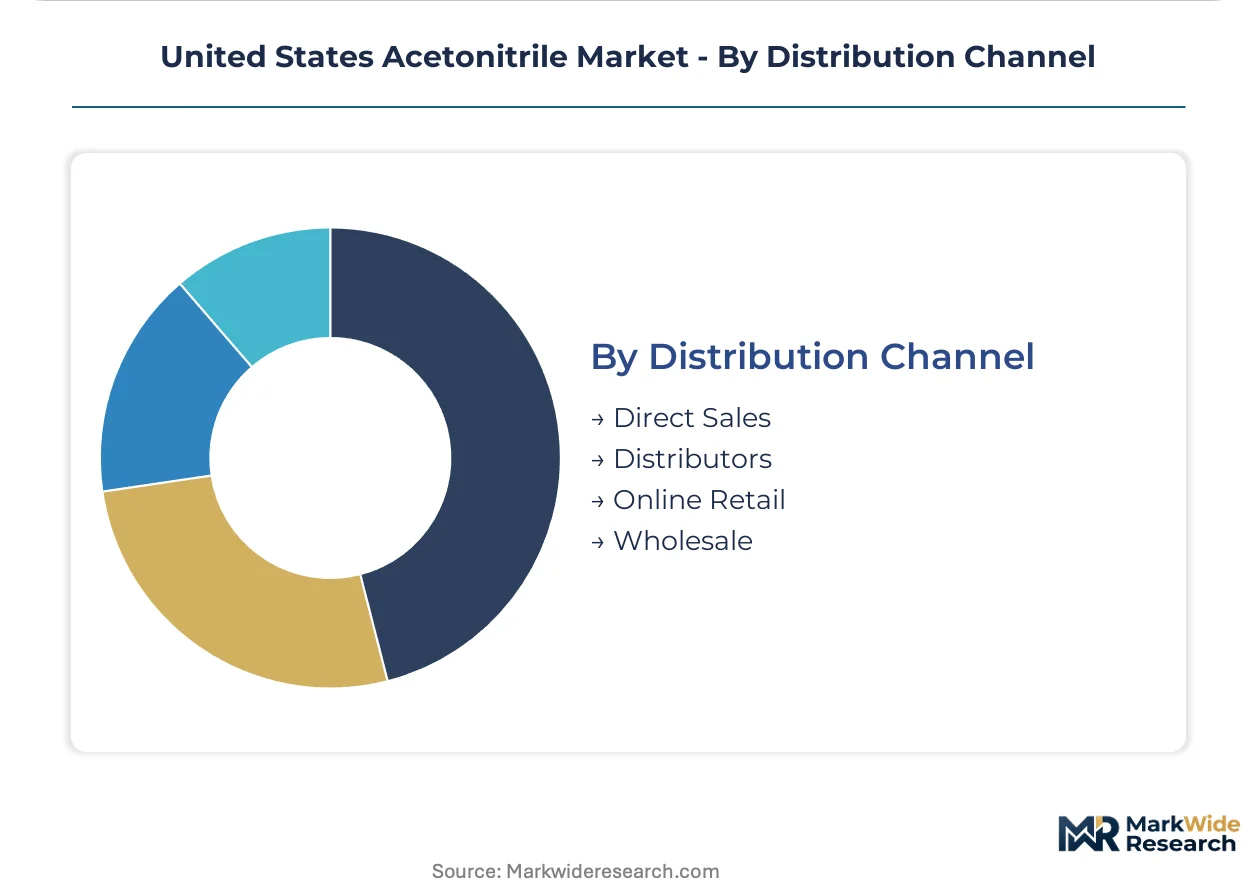
Channel selection reflects buyer scale, geographic concentration, and inventory carrying cost tolerance.
- Direct Sales:Large pharmaceutical manufacturers negotiate frame contracts with producers. These arrangements transfer inventory carrying costs to distributors while locking base-load commitments.
- Distributors:Channel control specialists extend reach across research institutions and contract manufacturing organizations. Avantor competes through this model with consolidated product portfolios.
- Wholesale:Serves chemical manufacturers with predictable bulk consumption patterns. Gulf Coast corridor concentration enables efficient tank truck logistics.
- Online Retail:Capturing academic and small-laboratory demand through transparent pricing and rapid fulfillment. Digital procurement platforms are compressing traditional distributor margins in sub-drummed quantities.
Direct sales anchor value concentration; online retail is climbing the fastest among channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors domestic acetonitrile production through integrated acrylonitrile-acetonitrile facilities clustered in Texas and Louisiana. Hurricane exposure and single-point-of-failure risks concentrate supply security concerns among pharmaceutical buyers dependent on this corridor. Regional demand fragmentation is redirecting procurement patterns toward dual-source qualification and strategic inventory positioning.
Texas Gulf Coast
Propylene ammoxidation facilities along the Houston Ship Channel generate acetonitrile as acrylonitrile byproduct for pharmaceutical solvent markets. EPA National Emission Standards for Hazardous Air Pollutants enforcement tightens vent control requirements at integrated petrochemical complexes. Beaumont-Port Arthur industrial concentration sustains captive supply chains for regional chemical manufacturers.
Louisiana Chemical Corridor
Acrylonitrile production infrastructure between Baton Rouge and Lake Charles feeds downstream acetonitrile purification operations. OSHA workplace exposure limits influence handling protocols across chemical manufacturing facilities in this high-density corridor. Specialized bulk logistics networks connect Louisiana production to Midwest pharmaceutical manufacturing sites.
Midwest Pharmaceutical Corridor
Indianapolis and Chicago-area generic drug manufacturers drive premium-grade solvent demand through FDA-aligned ICH Q3C compliance requirements. Multi-year offtake agreements with volume flexibility clauses are displacing spot-market purchasing among top-twenty generic producers. Hazmat transportation capacity constraints complicate just-in-time delivery from Gulf Coast supply origins.
Boston-Cambridge Biotech Cluster
Peptide-drug conjugate manufacturing expansion creates localized demand pockets for high-purity acetonitrile in solid-phase synthesis operations. Contract development organizations scaling chromatography infrastructure for impurity profiling sustain analytical-grade consumption. Regional CDMO growth is compressing traditional supply relationships while creating openings for service-integrated vendors.
Research Triangle
North Carolina-based contract manufacturing organizations anchor emerging demand for pharmaceutical-grade solvent in peptide therapeutic production. Membrane-based solvent recovery system deployment cuts energy consumption for regional analytical laboratories. Durham-Chapel Hill institutional concentration sustains steady offtake for laboratory reagent grades with thinner margin profiles.
United States Acetonitrile Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct synthesis route diversification beyond acrylonitrile byproduct dependency. Market structure consolidates around integrated petrochemical conglomerates with captive feedstock access and specialized high-purity refiners serving pharmaceutical specifications. Two strategic archetypes dominate: Gulf Coast-integrated volume producers and regional high-purity specialists. Competitive moves center on secondary purification capacity investments and multi-year offtake agreement structuring with volume flexibility clauses.
Within the integrated petrochemical tier, INEOS AG represents archetypal Gulf Coast concentration through its acrylonitrile platform operations. Nova Molecular Technologies exemplifies the high-purity specialist archetype, occupying a position in analytical and pharmaceutical applications. Avantor anchors distribution channel control, extending reach across research institutions and contract manufacturing organizations.
| Leading Market Players |
|---|
| INEOS AG |
| Asahi Kasei Corporation |
| Nova Molecular Technologies |
| Avantor |
| Honeywell International |
| Tedia Company |
| PerkinElmer |
| BASF |
| Mitsubishi Chemical Corporation |
| Others |
Cost & Logistics Intelligence
Multi-year offtake agreements with volume flexibility clauses are displacing spot-market purchasing among top-twenty generic drug manufacturers, forcing suppliers to restructure pricing models around committed base-load volumes rather than transactional premiums. This procurement shift compresses margin capture for non-integrated producers while rewarding Gulf Coast-integrated players with captive feedstock access.
Pricing Analysis
Propylene and ammonia cost pass-through dominates acetonitrile pricing mechanics, with integrated producers absorbing volatility more effectively than merchant market participants. Three-tier pricing structure across pharmaceutical-grade, analytical-grade, and technical-grade levels reflects certification burden and purity testing intensity. Cost compression in technical grades is intensifying because DMSO substitution erodes volume in select extraction applications. Research institutions and academic buyers exhibit highest price sensitivity, while peptide therapeutic CDMOs prioritize lot traceability over per-liter cost.
Supply Chain Analysis
Regional distribution centers in Houston, Chicago, and Philadelphia anchor hub-and-spoke patterns for pharmaceutical-grade material, with hazmat-certified warehousing capacity constraining service radii. Production concentrates in Texas and Louisiana along the Gulf Coast petrochemical corridor, with secondary purification capacity clustered in New Jersey and Pennsylvania. Feedstock draws from propylene ammoxidation byproduct streams and direct synthesis pilot operations. Single-source vulnerability threatens pharmaceutical buyers dependent on hurricane-exposed Gulf Coast infrastructure. Distribution runs through specialized chemical distributors with channel control over research institutions and contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Peptide-drug conjugate manufacturing expansion redirects volume toward pharmaceutical-grade specifications with stringent FDA-aligned ICH Q3C compliance requirements.
For Market Incumbents: Anticipate direct synthesis route diversification by new entrants seeking to bypass acrylonitrile byproduct dependency. Defensive consolidation should center on secondary purification capacity investments in the Midwest pharmaceutical corridor and multi-year offtake agreement structuring with volume flexibility clauses. Channel control over Boston-Cambridge and Research Triangle CDMOs represents the priority defensive lever against high-purity specialists. For New Entrants and Emerging Players: EPA National Emission Standards for Hazardous Air Pollutants enforcement in the United States opens a window for direct synthesis technologies with lower vent control capital intensity. White-space targets include localized supply to peptide therapeutic CDMOs in the Research Triangle and membrane-based solvent recovery system integration for large contract research organizations. The most penetrable segment is analytical-grade laboratory reagent supply to research institutions through online retail channels with rapid fulfillment capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with high-purity specialists possessing pharmaceutical-grade certification and regional proximity to biotech clusters. Long-term viability favors players with backward integration into feedstock or forward integration into solvent recovery services. The acquisition target archetype is regional high-purity refiners with established FDA compliance records. The signal to watch as inflection indicator is OSHA workplace exposure limit revision timing and enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Purification Capacity Expansion | Pharmaceutical-grade certification investments capture peptide therapeutic CDMO demand in Boston-Cambridge. |
| Direct Synthesis Technology Development | Methane-ammonia oxidative coupling reduces acrylonitrile byproduct dependency for new market entrants. |
| Membrane-Based Solvent Recovery Deployment | Nanofiltration units cut energy consumption for New Jersey and Pennsylvania contract research organizations. |
| Multi-Year Offtake Agreement Structuring | Volume flexibility clauses lock base-load commitments from Indianapolis and Chicago-area generic manufacturers. |
| Hazmat Distribution Network Consolidation | Specialized bulk logistics overcome driver certification shortages for inland pharmaceutical site delivery. |
Research Approach
Coverage spans the Gulf Coast petrochemical corridor, Midwest pharmaceutical manufacturing belt, and Northeast biotech clusters, with primary inputs from each region combined with secondary validation. Interviews with plant managers at integrated acrylonitrile facilities, procurement leads at peptide therapeutic CDMOs, distribution channel partners, and technical R&D directors at high-purity refiners informed demand-side and supply-side perspectives. Secondary sources include EPA enforcement records, FDA drug approval databases with solvent residual specifications, customs and trade data, and SEC filings from petrochemical conglomerates. Bottom-up volume modeling and top-down value reconciliation triangulate market size estimates.
Granularity-level framing applied grade-tier segmentation across pharmaceutical, analytical, and technical specifications, with end-use industry splits between pharmaceutical manufacturing, chemical synthesis, and research applications. Packaging format distinctions separated bulk tank truck, drum, and small-package channels. Regional production hub modeling captured Texas Gulf Coast, Louisiana Chemical Corridor, and Northeast purification capacity contributions. CAGRs derive from segment-level volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporate peptide therapeutic pipeline expansion rates and HPLC method proliferation in generic drug quality control laboratories.
Revisions become necessary when EPA per- and polyfluoroalkyl substance rules redirect solvent selection, OSHA exposure limit revisions alter handling economics, or hurricane disruption exceeds historical frequency assumptions. Forecasts reflect documented assumptions around propylene feedstock availability and pharmaceutical manufacturing reshoring intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Oxygenated Solvents Market
Solvents
North America Acetonitrile Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
Butyl Glycol Market
Solvents
Asia-Pacific Ethane Market
Solvents
Global Solvent Dyes Market
Solvents
Phenol Derivatives Market
Solvents
Pharmaceutical Solvent Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market
Solvents
North America Toluene Market
Solvents
Global Glycidol Market
Solvents
Organic Solvents Market
Solvents
Chlorobenzene Market
Solvents
Ortho-Xylene Market
Solvents
Global Droppers Market
Solvents
Toluene Derivatives Market