
 North America Toluene Market | 2026-2036
North America Toluene Market Size, Share, and Industry Trends Forecast 2026-2036
North America Toluene Market Intelligence
Automotive OEMs and their tier-one coating suppliers is rotating toward higher-purity toluene grades for electrocoat and basecoat systems. Exxon Mobil Corporation leverages its integrated Gulf Coast refining complex to supply specification-grade solvent streams directly to automotive paint lines. BASF SE anchors its North American position through backward integration into benzene derivatives, while LyondellBasell Industries Holdings B.V. competes on scale across the Houston Ship Channel corridor.
Toluene is an aromatic hydrocarbon with molecular formula C₇H₈, typically produced via catalytic reforming of naphtha or as a byproduct of ethylene cracking, with commercial grades ranging from nitration-grade purity to mixed xylene streams. Its primary industrial purpose centers on serving as a precursor for benzene and xylene production, plus direct use as a solvent in coatings and adhesives formulations. Chemical intermediate applications dominate volume off-take, while solvent-grade product commands margin premiums in electronics cleaning and specialty coatings. The automotive end-user segment shows the fastest structural expansion, driven by refinished vehicle volumes and OEM assembly plant throughput across Mexico and the southeastern United States.
EPA National Emission Standards for Hazardous Air Pollutants and OSHA Permissible Exposure Limits constrain solvent handling practices, pushing manufacturers toward closed-loop recovery systems and lower-VOC formulations. The Toxic Substances Control Act and state-level air quality regulations in California and Texas further shape product specifications and facility siting decisions. Stakeholders must monitor evolving EPA risk evaluations for commercial-grade toluene and calibrate capital allocation between solvent recovery infrastructure and alternative feedstock investments.
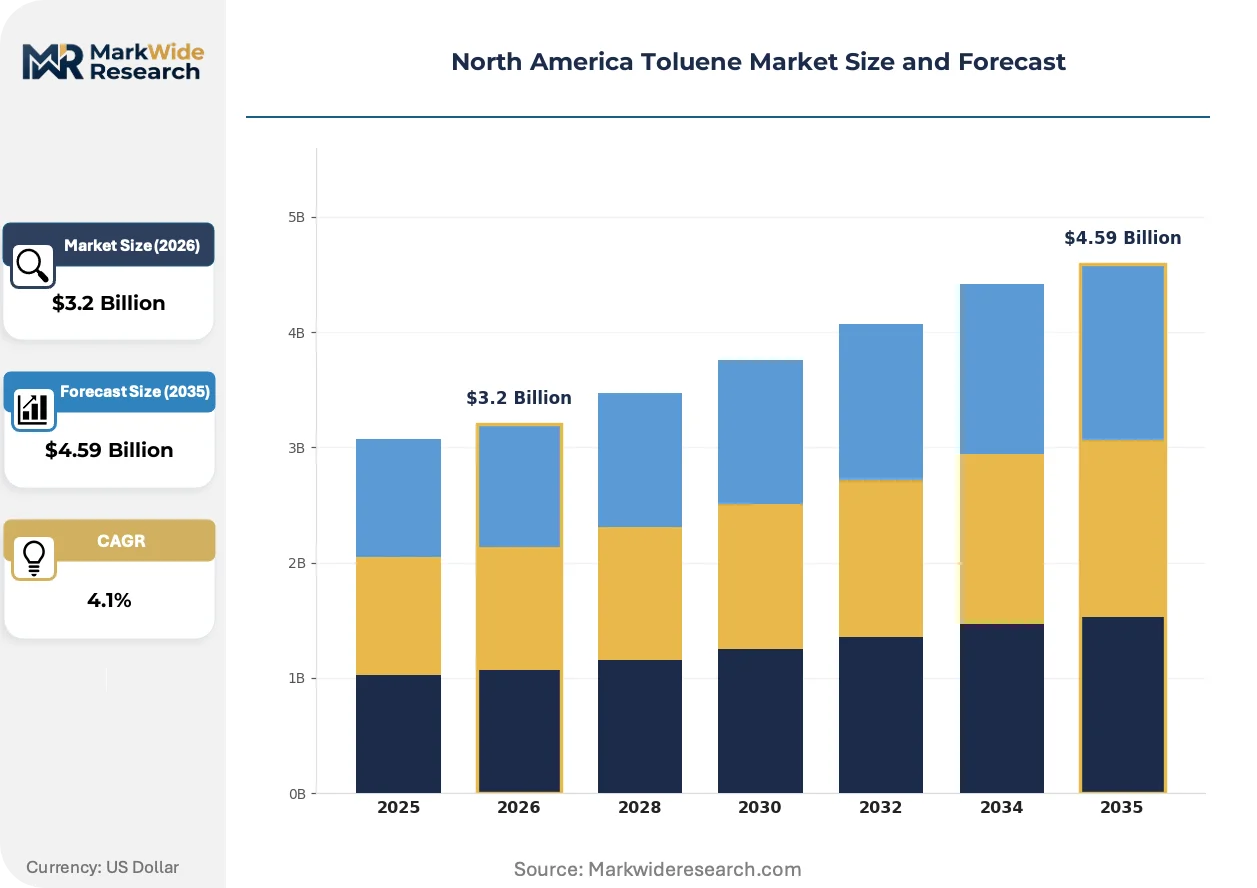
Market Dynamics
Waterborne coating formulations are displacing solvent-based systems across automotive OEM lines, compressing specification-grade toluene demand while simultaneously elevating purity requirements for remaining solvent applications.
Growth Catalysts
- EPA VOC Compliance Deadlines:Automotive refinish shops in Texas and California face phased emission limits, forcing inventory turnover toward compliant solvent grades that retain toluene in reduced-concentration blends.
- Mexico Automotive Assembly Expansion:OEM plant construction in Guanajuato and Nuevo León is generating derivative demand for basecoat solvents through tier-one supplier co-location.
- Pygas Extraction Economics:Steam cracker operators are maximizing aromatics recovery from heavy feedstocks, expanding merchant toluene availability along the US Gulf Coast.
Market Restraints
- Naphtha Feedstock Volatility:Catalytic reformer economics swing with natural gas liquids pricing, compressing margin visibility for integrated producers.
- Gulf Coast Supply Concentration:Over half of North American capacity clusters within hurricane exposure zones, creating force majeure vulnerability without geographic diversification.
- Waterborne Substitution:Electrocoat primer systems now operate at below-five-percent solvent content, permanently reducing volume absorption per vehicle produced.
Strategic Opportunities
- Electronics-Grade Purification:Semiconductor fabs in Arizona and Oregon require sub-ten-ppb impurity specifications, commanding triple-digit price premiums over nitration-grade material.
- IRA Clean Hydrogen Hub Development:Carbon capture retrofits at Texas refineries may qualify for production tax credits, lowering effective aromatics production costs.
- Canadian Oil Sands Diluent Demand:Pipeline operators specify toluene-rich diluent blends for bitumen transport, creating non-chemical absorption outside traditional solvent markets.
Industry Challenges
- Process Safety Expertise Shortage:Refinery operators struggle to recruit experienced catalytic reforming engineers familiar with continuous catalyst regeneration systems.
- Closed-Loop Recovery Capital Requirements:Automotive paint shops must install solvent distillation units to meet OSHA Permissible Exposure Limits, stretching SME balance sheets.
- Cross-State Shipment Documentation:California Air Resources Board tracking requirements create administrative friction for Gulf Coast suppliers serving West Coast coating formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Toluene Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.59 Billion |
| CAGR (2026 – 2036) | 4.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Fuel Additive, Chemical Intermediate, Coatings End User: Manufacturing, Automotive, Electronics, Construction Application: Paints, Adhesives, Inks, Plastics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Chevron Phillips Chemical Company LLC, Chevron Corporation, Exxon Mobil Corporation, SABIC, Mitsubishi Chemical Group Corporation, Shell PLC, LyondellBasell Industries Holdings B.V., China Petroleum & Chemical Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Toluene Market Strategic Shifts & Innovations
Reformer catalyst technology and regulatory emission frameworks are jointly reshaping how toluene purity grades align with end-use specifications across transportation and electronics sectors.
Membrane separation technology for aromatics recovery is bifurcating the merchant market between cryogenic extraction units and hybrid distillation-membrane systems. Petrochemical operators in Louisiana and Texas are piloting polymeric membranes for xylene-toluene split fractions, reducing energy intensity by fifteen to twenty percent versus conventional extractive distillation. This technology is bifurcating supplier tiers into integrated refiners with captive membrane capacity and merchant traders dependent on tolling arrangements.
EPA National Emission Standards for Hazardous Air Pollutants maximum achievable control technology reviews are compelling coating facilities to install carbon adsorption or thermal oxidizer systems for exhaust streams. The regulatory burden falls disproportionately on independent job shops lacking corporate environmental staffs, accelerating consolidation toward multi-site operators with centralized compliance functions. California's South Coast Air Quality Management District is enforcing stricter localized limits than federal baselines, fragmenting formulation standards within the same national market.
Automotive OEMs are consolidating solvent procurement through single-source framework agreements with integrated refiners, displacing the historical spot-market purchasing pattern among tier-one suppliers. This concentration transfers inventory risk upstream while locking in volume commitments that constrain supplier flexibility to serve spot electronics-grade buyers. The shift is most visible in southeastern US assembly corridors where Toyota, BMW, and Mercedes-Benz operate paint shops under unified chemical management contracts.
North America Toluene Market Segmentation
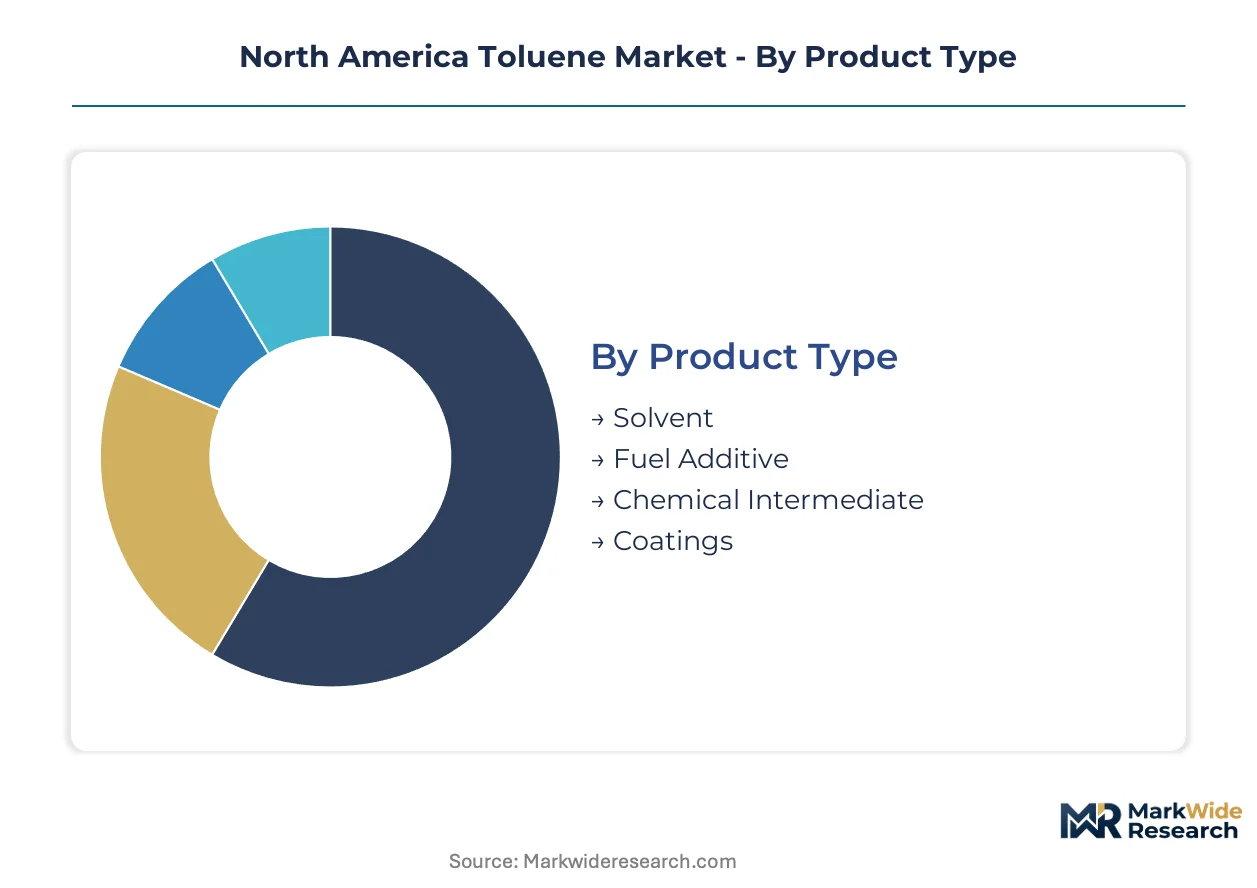
Toluene value pools fragment across four distinct axes in North America. Product type determines margin capture through purity gradients, while end-user concentration in automotive and electronics channels shapes volume allocation priorities.
Product Type:
Solvent and chemical intermediate grades command the widest margin spreads, with specification purity driving price tier separation.
- Solvent:Nitration-grade and electronic-grade purities serve distinct demand tiers. Electronics cleaning applications in Arizona and Oregon fabs require sub-ten-ppb impurity thresholds, extracting triple-digit premiums over standard solvent grades. Automotive refinish shops in Texas and California absorb specification-grade volumes under EPA VOC compliance deadlines.
- Chemical Intermediate:Catalytic reformer output flows disproportionately into benzene and xylene derivative production. Gulf Coast integrated refineries capture margin through captive aromatics recovery, while merchant traders face compressed spreads during naphtha feedstock volatility cycles.
- Fuel Additive:Canadian oil sands diluent blending specifications create non-chemical demand outside traditional solvent markets. Pipeline operators specify toluene-rich formulations for bitumen transport viscosity reduction.
- Coatings:Waterborne formulation displacement is compressing volume absorption per vehicle, though remaining solvent demand concentrates in higher-purity electrocoat and basecoat systems.
Solvent holds installed capacity. Chemical Intermediate is rotating up the share rankings.
End User:
Volume concentration clusters in automotive assembly corridors, with electronics and construction channels exhibiting divergent purity requirements.
- Automotive:OEM paint shops in Guanajuato and Nuevo León generate derivative solvent demand through tier-one supplier co-location. Southeastern US assembly plants operated by Toyota, BMW, and Mercedes-Benz consolidate procurement through single-source framework agreements with integrated refiners.
- Electronics:Semiconductor fabrication facilities impose the most stringent impurity specifications in the market. Arizona fabs require dedicated supply chains with contamination controls that exclude standard merchant grades.
- Manufacturing:General industrial solvent applications span adhesives, cleaning compounds, and process chemicals across mid-continent distribution networks.
- Construction:Adhesives and sealants formulations absorb lower-purity mixed aromatic streams with less specification intensity than automotive or electronics channels.
Automotive anchors volume throughput. Electronics is expanding most quickly on a value-per-ton basis.
Application:
Paint system formulations dominate volume off-take, though adhesive and ink applications retain solvent-grade requirements resistant to waterborne substitution.
- Paints:Automotive OEM basecoat and electrocoat systems drive specification-grade demand. Waterborne primer formulations now operate below five percent solvent content, permanently reducing per-vehicle absorption rates.
- Adhesives:Structural bonding applications in aerospace and industrial assembly retain solvent-based formulation requirements. California Air Resources Board tracking requirements create administrative friction for Gulf Coast suppliers serving West Coast adhesive formulators.
- Inks:Publication gravure and flexographic printing maintain solvent carrier demand despite digital displacement in commercial print segments.
- Plastics:Polystyrene and polyurethane precursor applications flow through chemical intermediate channels rather than direct solvent sales.
Paints holds the largest installed consumption base. Adhesives is climbing the fastest in specification-grade premium capture.
Distribution Channel:
Procurement consolidation is shifting volume risk upstream, fragmenting channel economics between integrated supply agreements and spot merchant trade.
- Direct Sales:Integrated refiners like Exxon Mobil supply specification-grade streams directly to automotive paint lines under multi-year framework contracts. This concentration transfers inventory risk from tier-one suppliers to upstream producers.
- Distributors:Merchant traders dependent on tolling arrangements face margin compression as membrane separation technology bifurcates supplier tiers. Independent job shops lacking corporate environmental staffs accelerate consolidation toward multi-site operators.
- Online Sales:Specialty chemical platforms serve small-volume electronics-grade buyers excluded from direct refiner relationships. Documentation requirements for California Air Resources Board compliance limit platform scalability.
- Retail:Consumer-grade solvent products for DIY and light industrial applications operate at lowest purity thresholds with minimal regulatory documentation burden.
Direct Sales holds contracted volume commitments. Distributors is gaining share fastest in merchant spot trade flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over half of North American toluene capacity clusters along the US Gulf Coast petrochemical corridor, creating geographic concentration that amplifies hurricane exposure risk while minimizing logistics costs to derivative benzene and xylene processors.
United States
Integrated refineries in Texas and Louisiana supply specification-grade solvent streams directly to automotive paint lines under multi-year framework agreements. EPA National Emission Standards for Hazardous Air Pollutants maximum achievable control technology reviews compel coating facilities to install carbon adsorption systems. The Houston Ship Channel corridor anchors merchant toluene availability, with steam cracker operators maximizing aromatics recovery from heavy feedstocks.
Canada
Pipeline operators specify toluene-rich diluent blends for bitumen transport viscosity reduction, creating non-chemical absorption outside traditional solvent markets. Health Canada and provincial environmental regulators enforce workplace exposure limits that align with OSHA Permissible Exposure Limits benchmarks. Alberta oil sands production corridors drive diluent demand, with rail and pipeline logistics connecting to US Gulf Coast aromatics suppliers.
Mexico
OEM plant construction in Guanajuato and Nuevo León generates derivative solvent demand through tier-one supplier co-location to assembly operations. Mexican environmental authorities implement phased emission standards that mirror California Air Resources Board tracking requirements for cross-border shipments. The Bajío Region automotive corridor concentrates paint shop operations for Toyota, BMW, and Mercedes-Benz assembly plants.
North America Toluene Market Key Industry Players
Concentration sits with integrated petrochemical majors possessing captive refinery aromatics recovery capacity. The supplier base tiers into Gulf Coast integrated refiners with membrane separation technology, merchant traders dependent on tolling arrangements, and specialty electronics-grade purifiers serving semiconductor fabs. Dominant competitive moves include backward integration into benzene derivative production and strategic framework contracting with automotive OEMs to lock in volume commitments.
Within the integrated refiner tier, Exxon Mobil Corporation and LyondellBasell Industries Holdings B.V. occupy positions defined by Gulf Coast infrastructure scale, while BASF SE exemplifies the backward-integrated aromatics derivative model. Chevron Phillips Chemical Company LLC represents the joint-venture structure common to major petrochemical partnerships. These entities anchor supply relationships through direct sales channels that transfer inventory risk from tier-one coating suppliers to upstream producers.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company LLC |
| Chevron Corporation |
| Exxon Mobil Corporation |
| SABIC |
| Mitsubishi Chemical Group Corporation |
| Shell PLC |
| LyondellBasell Industries Holdings B.V. |
| China Petroleum & Chemical Corporation |
| BASF SE |
| Others |
Cost & Logistics Intelligence
EPA National Emission Standards for Hazardous Air Pollutants compliance gates both supplier qualification and price differentiation, forcing coating formulators to absorb specification-grade premiums or exit regulated channels entirely. This regulatory filter concentrates purchasing power among integrated refiners capable of certifying solvent streams to sub-ten-ppb thresholds for electronics and automotive applications.
Pricing Analysis
EPA VOC compliance deadlines dictate the pricing tier structure across the North American toluene market, separating nitration-grade solvent from specification-grade electrocoat and electronics-cleaning purities. Price differentiation rests on certification level and volume scale, with semiconductor fabs in Arizona commanding triple-digit premiums over standard merchant grades. Cost compression in refinery-grade material is intensifying because pygas extraction economics expand merchant availability. Automotive OEMs consolidating through single-source framework agreements show lowest price sensitivity, while independent refinish shops in Texas and California face highest exposure to compliant-grade premiums.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive paint shop procurement, though semiconductor fabs maintain strategic stockpiles against contamination-risk supply interruptions. Supply concentrates in the United States Gulf Coast corridor, with integrated refineries in Texas and Louisiana anchoring merchant availability. Raw material dependencies include naphtha feedstocks, natural gas liquids, and heavy pygas streams from ethylene crackers. Single-source vulnerability runs through hurricane-exposed production clusters without geographic diversification. Distribution feeds from direct refinery sales to automotive OEMs, with merchant traders dependent on tolling arrangements for membrane separation capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American toluene market operates as a regulatory-entrenchment defensive moat, where EPA certification requirements and OSHA exposure limits create switching costs that lock automotive OEMs into qualified supplier relationships. Incumbents benefit from captive aromatics recovery infrastructure that new entrants cannot replicate without decade-scale capital deployment.
For Market Incumbents: Compound backward integration into benzene derivatives to capture margin upstream, while locking southeastern US automotive corridors through multi-year framework agreements that transfer inventory risk from tier-one suppliers. Waterborne substitution in electrocoat systems threatens volume absorption per vehicle, demanding investment in electronics-grade purification capacity to offset automotive compression. For New Entrants and Emerging Players: Anchor in Canadian oil sands diluent blending specifications, where pipeline operators require toluene-rich formulations outside traditional solvent competition. The most penetrable white-space sits in merchant electronics-grade supply to Arizona and Oregon semiconductor fabs excluded from direct refiner relationships. A specialty tolling model leveraging third-party membrane separation capacity offers the clearest go-to-market angle without integrated refinery investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronics-grade purification infrastructure, favoring long-term positions in assets with regulatory-locked demand from semiconductor fabrication. Target acquisition archetypes include merchant traders with tolling access to membrane separation technology and established California Air Resources Board documentation capabilities. The signal to watch is EPA risk evaluation timelines for commercial-grade toluene, which would trigger capital reallocation between solvent recovery and alternative feedstock investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzene Derivatives | BASF SE captures margin through captive aromatics recovery at Gulf Coast complexes. |
| Electronics-Grade Purification Capacity Expansion | Sub-ten-ppb specifications command triple-digit premiums over nitration-grade material. |
| Long-term Framework Agreements with Automotive OEMs | Toyota, BMW, and Mercedes-Benz paint shops consolidate procurement through unified chemical management. |
| Membrane Separation Technology Deployment | Polymeric membrane pilots in Louisiana and Texas reduce energy intensity versus extractive distillation. |
| Carbon Capture Retrofit at Refinery Complexes | IRA Clean Hydrogen Hub tax credits lower effective aromatics production costs in Texas. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, American Chemistry Council reports, and EPA regulatory dockets. Interviews with catalytic reforming engineers, automotive coating procurement leads, and semiconductor fab chemical managers inform operational constraints. Customs and trade data on aromatics flows, combined with refinery capacity disclosures, enable bottom-up volume triangulation against top-down market sizing.
Segmentation dimensions modeled include purity grade tier, end-use industry concentration, and regional production hub configuration across the analysis window. CAGRs derive from trend extrapolation of automotive assembly throughput, electronics fabrication capacity additions, and waterborne formulation displacement rates. Forecast inputs incorporate naphtha feedstock volatility cycles and pygas extraction economics from heavy feedstock cracking.
Decision-makers should treat outputs as directional under assumptions of sustained EPA VOC compliance enforcement and stable Gulf Coast refining infrastructure; material deviation would warrant model refresh. Revision becomes warranted when hurricane damage to Houston Ship Channel facilities or EPA risk evaluation outcomes cross thresholds that restructure supplier qualification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Tetraethyl Benzene Market
Solvents
Propylene Glycol Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Triacetin Market
Solvents
Dibutyl Ether Market
Solvents
Global Droppers Market
Solvents
2-Butanone Market
Solvents
Retardant Solvent Market
Solvents
Wax Dispersion Market
Solvents
Global Glycol Market
Solvents
Diethyl Ether Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Crotonaldehyde Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Dihydromyrcene Market
Solvents
GCC Acetonitrile Market