
 Global Glycidol Market | 2026-2036
Global Glycidol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glycidol Market Intelligence
Buyer concentration among polyurethane foam manufacturers is recalibrating procurement patterns across the glycidol value chain. BASF SE leverages its integrated epoxy intermediates platform to sustain captive supply advantages in European markets. Hangzhou Dayangchem anchors Asia-Pacific volume through specialized glycidol derivatives production. FUJIFILM Wako Pure Chemical Corporation differentiates via analytical-grade purity standards that command premium positioning in pharmaceutical and diagnostic applications.
Glycidol is an epoxide compound with the molecular formula C₃H₆O₂, typically manufactured through epichlorohydrin dehydrochlorination or glycerol dehydration routes, and functions primarily as a reactive intermediate for polymer modification and surfactant synthesis. The analytical grade segment leads value contribution due to stringent purity specifications demanded by pharmaceutical and life-science end users, while technical grade competes on volume in industrial polyurethane and adhesive applications. Pharmaceutical-grade glycidol occupies the fastest-expanding margin pool as CDSCO and FDA scrutiny of epoxide impurities in drug formulations intensifies.
REACH registration requirements and EPA TSCA Section 5 new chemical notifications govern glycidol commercialization in Europe and the United States, with both frameworks tightening mutagenicity assessment protocols that directly impact product registration timelines and import eligibility. China's SAMR implements GB standards for epoxide content in food-contact materials, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor regulatory harmonization efforts between OECD member states and emerging chemical regulatory bodies to anticipate certificate-of-analysis requirements that will determine market access eligibility.
Market Dynamics
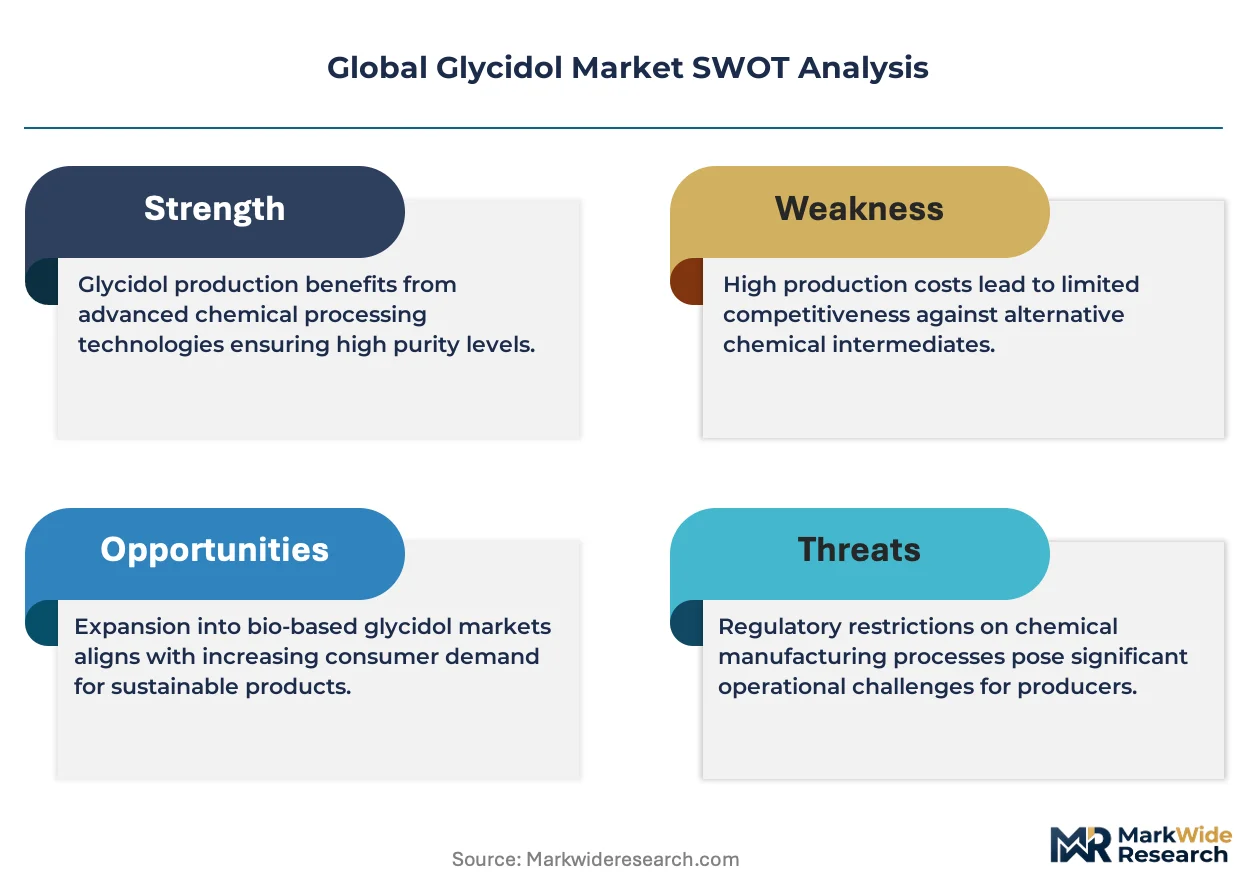
REACH registration deadlines and EPA TSCA Section 5 mutagenicity protocols are compressing product registration timelines while simultaneously elevating purity thresholds, forcing suppliers to recalibrate manufacturing footprints and certificate-of-analysis documentation ahead of import eligibility windows.
Growth Catalysts
- Construction sector epoxy insulation demand:Polyurethane foam manufacturers in China and Germany are scaling glycidol procurement for rigid foam applications in energy-efficient building envelopes.
- CDSCO pharmaceutical impurity scrutiny:India's tightening epoxide monitoring in active pharmaceutical ingredient synthesis is pulling analytical-grade glycidol into quality control workflows.
- Glycerol dehydration process refinement:Catalytic route improvements are lowering energy intensity for bio-based glycidol production, expanding feedstock flexibility beyond petrochemical epichlorohydrin.
Market Restraints
- Epichlorohydrin feedstock volatility:Chlor-alkali capacity constraints and propylene cost swings transmit directly to glycidol production economics.
- East Asian supply concentration:China and South Korea host over 70% of merchant glycidol capacity, creating single-source vulnerability for European and North American formulators.
- Propylene oxide substitution pressure:Alternative epoxides with lower mutagenicity classifications are displacing glycidol in select surfactant and polymer modification applications.
Strategic Opportunities
- Brazilian agrochemical formulation expansion:ANVISA registration pathways for epoxide intermediates remain underpenetrated relative to glyphosate and 2,4-D derivative demand growth.
- EU Green Deal bio-based feedstock mandates:Glycerol-derived glycidol qualifies for renewable content credits in REACH-registered polymer applications.
- Direct-to-formulator digital procurement platforms:Specialty chemical distributors are launching API-integrated ordering systems that bypass traditional multi-tier distribution for mid-volume buyers.
Industry Challenges
- Analytical-grade certification timelines:ISO 17025-accredited testing for pharmaceutical-grade glycidol batches extends 6-12 weeks, compressing just-in-time delivery windows for CDMO customers.
- Legacy batch reactor retrofitting:Continuous flow epoxidation technology requires capital-intensive equipment replacement at established European and Japanese manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glycidol Market |
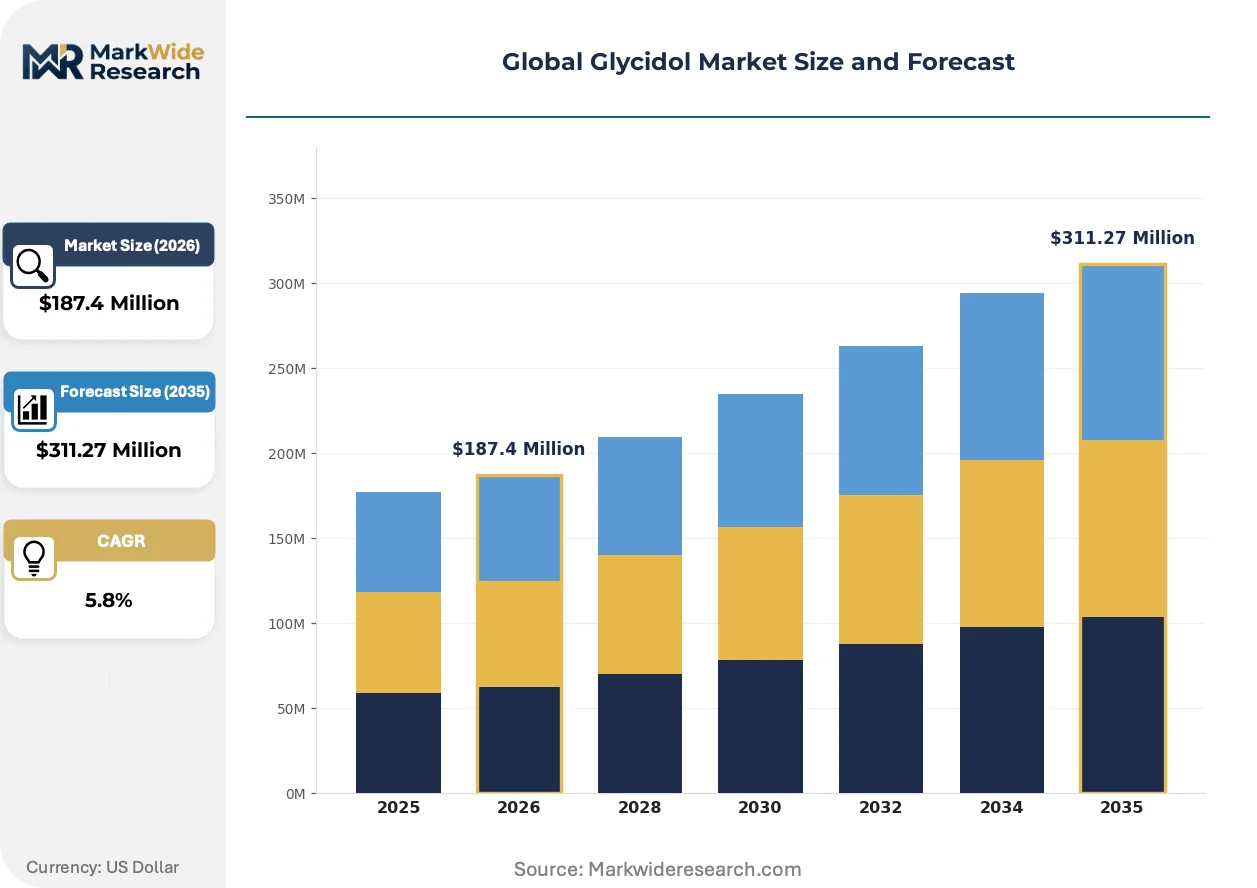
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Grade, Technical Grade, Pharmaceutical Grade, Food Grade, Cosmetic Grade Application: Polyurethane Foams, Lubricant Additives, Surfactants, Adhesives, Polymer Production End User Industry: Chemical Manufacturers, Personal Care Producers, Pharmaceutical Manufacturers, Paint & Coating Producers, Agrochemical Companies Form: Liquid, Solution, Powder, Emulsion |
| Companies Covered | Meryer Chemical Technology, Nacalai Tesque Inc., FUJIFILM Wako Pure Chemical Corporation, Hangzhou Dayangchem, LGC Group, HBCChem Inc., Kanto Chemical Co. Inc., BASF SE, Acros Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glycidol Market Strategic Shifts & Innovations
Continuous processing technology and bio-based feedstock integration are displacing conventional batch manufacturing, while regulatory harmonization efforts between OECD member states are reshaping certificate-of-analysis requirements for cross-border glycidol trade.
Continuous flow epoxidation systems are converging with real-time spectroscopic monitoring to enable pharmaceutical-grade glycidol production with reduced batch-to-batch variability. European and Japanese manufacturers are piloting these installations to meet EMA and PMDA impurity specification tightening. The technology is converging with automated quality assurance platforms that compress release timelines from weeks to days for analytical-grade shipments.
EPA TSCA Section 5 new chemical notification protocols are expanding mutagenicity data requirements for glycidol imports into the United States. The agency's revised epoxide assessment framework now demands in vivo genotoxicity studies that extend registration timelines by 12-18 months. Pharmaceutical and diagnostic end-use segments are responding by consolidating supplier relationships with vendors holding pre-existing EPA consent orders.
Buyer concentration among polyurethane foam manufacturers is compressing procurement cycles and elevating volume-commitment expectations from glycidol suppliers. Long-term offtake agreements with minimum annual quantity thresholds are displacing spot market purchases for technical-grade material. This pattern is most visible in China and Germany, where construction sector epoxy insulation demand is consolidating around vertically integrated resin formulators.
Global Glycidol Market Segmentation
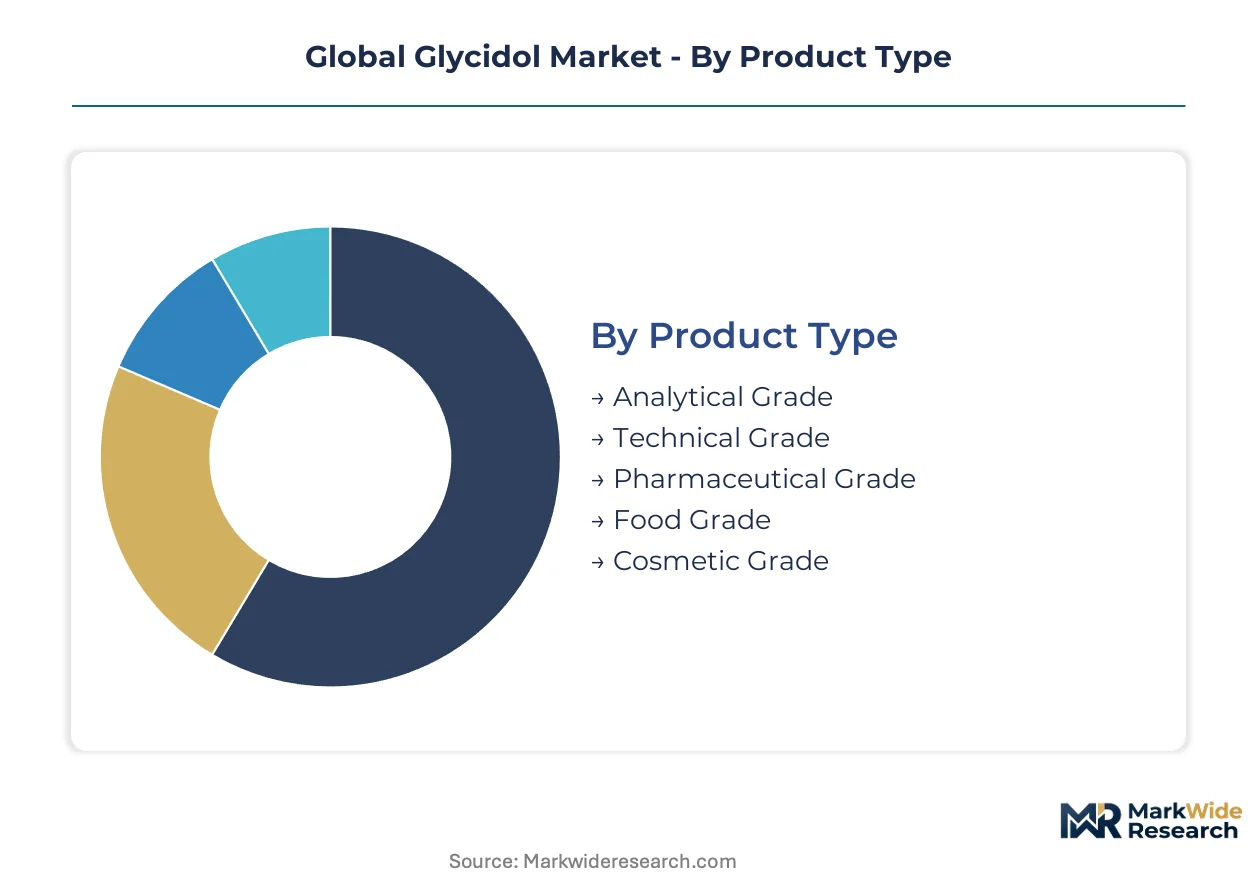
Glycidol's market structure reflects divergent purity requirements across end-use applications, with certification grades determining access to pharmaceutical and food-contact value chains. Segmentation by product type, application, end user, and physical form reveals how regulatory thresholds and performance specifications fragment procurement patterns across industrial and specialty chemical buyers.
Product Type:
Standalone analytical and pharmaceutical grades command premium positioning through certified impurity profiles, while technical and industrial grades embed into bulk polymer systems where purity tolerances relax.
- Analytical Grade:Purity specifications exceeding 99.5% with comprehensive certificate-of-analysis documentation for chromatography and spectroscopy applications. CDSCO and FDA impurity scrutiny in pharmaceutical quality control workflows concentrates demand among contract research organizations in India and the United States. EMA and PMDA tightening of epoxide monitoring protocols is extending batch release timelines for this segment.
- Technical Grade:Standardized epoxide content for industrial polyurethane foam and adhesive manufacturing without pharmaceutical-grade certification overhead. Construction sector procurement in Germany and China dominates volume absorption, with BASF SE and regional Chinese formulators driving long-term offtake agreements.
- Pharmaceutical Grade:Manufactured under ICH Q3D elemental impurity guidelines with dedicated manufacturing line segregation. Regulatory filings in the United States require pre-existing EPA consent orders.
- Food Grade:GB standards compliance for food-contact material applications in China, with migration testing for epoxy-based can coatings.
- Cosmetic Grade:Restricted use profiles under EU Cosmetics Regulation with residual epichlorohydrin limits below 1 ppm.
Technical Grade leads volumes today; Pharmaceutical Grade is gaining share fastest.
Application:
Cost tier differentiation separates commodity polyurethane foam applications from high-margin lubricant additive formulations requiring customized molecular architecture.
- Polyurethane Foams:Rigid foam insulation for energy-efficient building envelopes represents the dominant volume sink. German and Chinese construction codes are mandating higher thermal performance standards that expand epoxy-based polyol demand.
- Lubricant Additives:Extreme-pressure and anti-wear functionality in synthetic base stocks commands formulation premiums. Japanese and South Korean automotive OEM specifications drive specialized glycidol derivative procurement.
- Surfactants:Non-ionic emulsifier synthesis for industrial cleaning and personal care applications competes with propylene oxide-based alternatives.
- Adhesives:Structural bonding applications in aerospace and electronics assembly require controlled viscosity grades.
- Polymer Production:Epoxy resin backbone modification for coatings and composites manufacturing.
Polyurethane Foams anchors current demand; Lubricant Additives shows the steepest expansion trajectory.
End User Industry:
Customer type fragmentation concentrates high-volume procurement among chemical manufacturers while personal care and pharmaceutical buyers fragment across specialized distributors.
- Chemical Manufacturers:Integrated epoxy resin and surfactant producers represent the consolidated demand base. Chinese state-owned enterprises and German specialty chemical groups dominate procurement scale.
- Pharmaceutical Manufacturers:Active pharmaceutical ingredient synthesis and impurity reference standard procurement require ISO 17025-accredited supplier relationships.
- Personal Care Producers:Cosmetic-grade glycidol derivatives for hair conditioning and skin care formulations.
- Paint & Coating Producers:Industrial protective coatings and automotive refinish applications.
- Agrochemical Companies:Epoxide intermediate demand for glyphosate and 2,4-D derivative synthesis in Brazilian and Indian markets.
Chemical Manufacturers dominate volume absorption; Pharmaceutical Manufacturers are climbing the fastest.
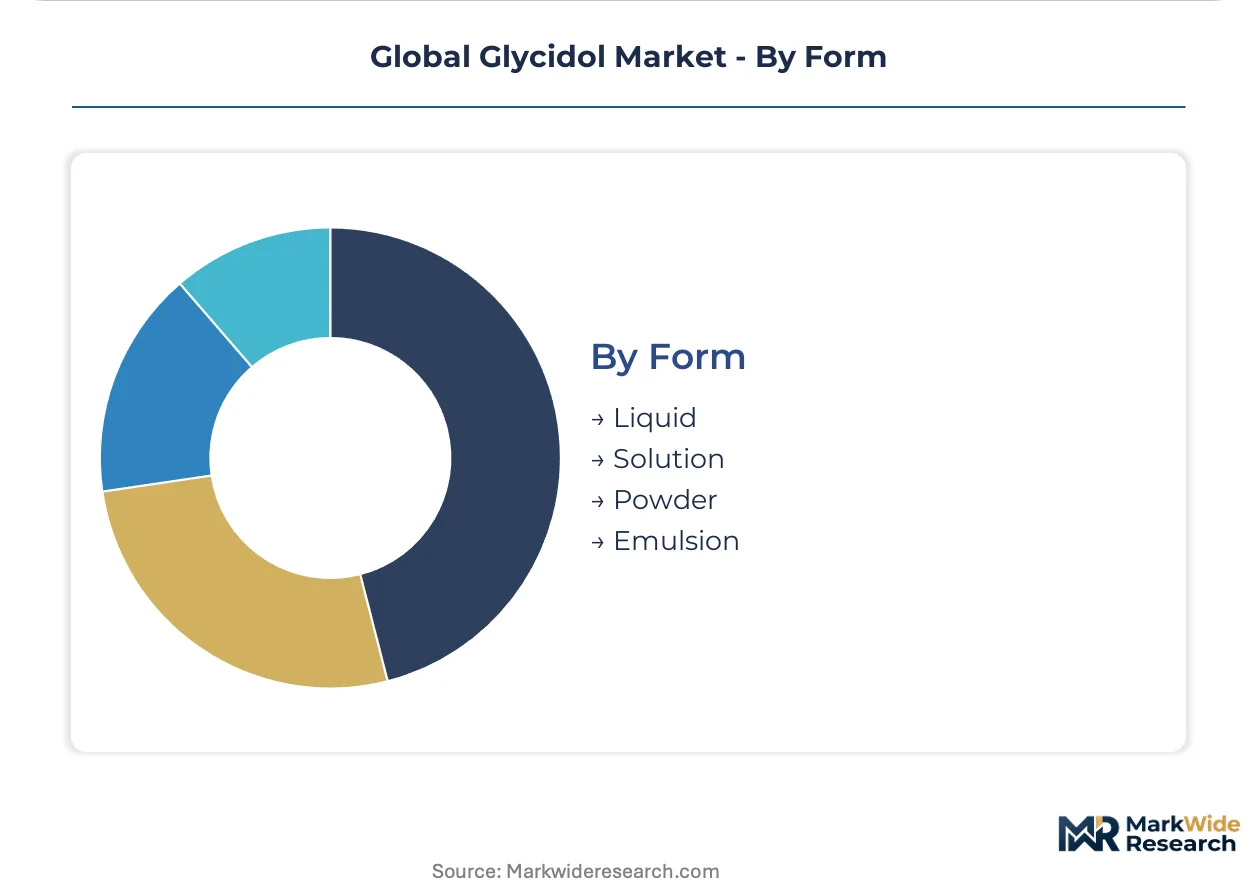
Form:
Supply concentration in liquid bulk formats reflects transportation economics, while powder and emulsion variants address formulation flexibility requirements in dispersed systems.
- Liquid:Standard bulk delivery format for industrial-scale polyurethane and adhesive manufacturing. Tanker truck and ISO tank container logistics dominate intra-Asia and trans-Atlantic trade.
- Solution:Pre-diluted formats for laboratory and small-batch pharmaceutical synthesis workflows.
- Powder:Solid-state handling advantages for powder coating and dry blend adhesive applications.
- Emulsion:Water-dispersed systems for textile finishing and paper coating processes requiring controlled release profiles.
Liquid leads volumes today; Solution is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and polymer scientists concentrate in Germany's Rhine-Ruhr corridor, China's Yangtze River Delta, and the US Gulf Coast petrochemical belt, anchoring glycidol production expertise and downstream formulation capabilities across three continents.
China
Epoxy resin manufacturers in Jiangsu and Zhejiang provinces drive glycidol consumption for rigid polyurethane foam insulation in energy-efficient construction. SAMR enforces GB standards for epoxide content in food-contact materials, creating compliance checkpoints for domestic and imported material. The Ningbo-Zhoushan petrochemical cluster hosts integrated glycidol derivative production serving agrochemical and surfactant formulators.
Germany
Construction sector demand for high-performance building envelope materials pulls glycidol into polyol systems manufactured in North Rhine-Westphalia. REACH registration requirements and ECHA mutagenicity protocols compress product registration timelines while elevating purity thresholds. The Leverkusen-Dormagen chemical corridor maintains captive glycidol supply chains within vertically integrated epoxy intermediates platforms.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts procure analytical-grade glycidol for impurity reference standards and active pharmaceutical ingredient synthesis. EPA TSCA Section 5 new chemical notifications demand in vivo genotoxicity studies that extend registration timelines by 12-18 months. The Texas-Louisiana Gulf Coast petrochemical complex processes epichlorohydrin feedstock for technical-grade glycidol serving regional adhesive and coating formulators.
Japan
Automotive OEM specifications from Toyota and Honda drive specialized glycidol derivative procurement for synthetic lubricant additives manufactured in Aichi and Osaka prefectures. PMDA tightening of epoxide monitoring protocols extends batch release timelines for pharmaceutical-grade material. The Kawasaki-Kashima industrial zone maintains continuous flow epoxidation pilot installations for reduced batch-to-batch variability.
India
Contract research organizations in Hyderabad and Bangalore absorb analytical-grade glycidol for chromatography applications and pharmaceutical quality control workflows. CDSCO scrutiny of epoxide impurities in active pharmaceutical ingredient synthesis intensifies supplier certification requirements. The Gujarat chemical belt imports technical-grade material for polyurethane foam manufacturers serving construction and automotive sectors.
Global Glycidol Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where captive supply advantages separate integrated chemical groups from merchant producers. The vendor base fragments across three strategic archetypes: multinational diversified chemicals with backward integration into epichlorohydrin, regional specialists in glycidol derivatives, and analytical-grade purists serving pharmaceutical and diagnostic segments. Capacity expansion and strategic partnerships dominate competitive moves, with long-term offtake agreements displacing spot market purchases for technical-grade material.
Among diversified chemical conglomerates, BASF SE anchors European supply through integrated epoxy intermediates platforms. Japanese analytical-grade specialists including FUJIFILM Wako Pure Chemical Corporation and Kanto Chemical Co. Inc. occupy premium positioning in pharmaceutical and diagnostic applications. Chinese regional producers exemplified by Hangzhou Dayangchem anchor Asia-Pacific volume through specialized derivatives production. These three archetypes represent the competitive spectrum from scale-driven commodity supply to purity-certified specialty positioning.
| Leading Market Players |
|---|
| Meryer Chemical Technology |
| Nacalai Tesque Inc. |
| FUJIFILM Wako Pure Chemical Corporation |
| Hangzhou Dayangchem |
| LGC Group |
| HBCChem Inc. |
| Kanto Chemical Co. Inc. |
| BASF SE |
| Acros Organics |
| Others |
Cost & Logistics Intelligence
Epichlorohydrin feedstock costs transmit directly through glycidol production economics, with chlor-alkali capacity constraints and propylene volatility creating tiered pricing separation between technical-grade bulk supply and analytical-grade certified batches. REACH registration overhead and EPA TSCA Section 5 mutagenicity study requirements embed compliance premiums into pharmaceutical-grade quotations, while construction sector procurement in Germany and China compresses technical-grade margins through volume-commitment contracting.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical-grade glycidol from unbundled technical-grade spot transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: analytical-grade commands 40-60% premiums over technical material due to ISO 17025-accredited testing and dedicated manufacturing line segregation. Cost compression in technical-grade supply is intensifying because Chinese state-owned enterprises are consolidating procurement around long-term offtake agreements with minimum annual quantity thresholds. Polyurethane foam manufacturers in Germany exhibit highest price sensitivity due to epoxy insulation margin pressure, while pharmaceutical CDMOs in New Jersey and Massachusetts absorb premium pricing for pre-existing EPA consent order security.
Supply Chain Analysis
Direct-to-formulator digital procurement platforms are displacing traditional multi-tier distribution for mid-volume buyers in specialty chemical segments. Merchant glycidol capacity concentrates in China, South Korea, and Japan, with over 70% of global supply originating from East Asian petrochemical clusters. Manufacturing draws from epichlorohydrin, glycerol, and catalytic hydrogenation inputs, with glycerol dehydration routes expanding bio-based feedstock flexibility. Single-source vulnerability for European and North American formulators intensifies as China and South Korea dominate merchant production. Distribution runs through tanker truck and ISO tank container logistics for liquid bulk, with specialized cold-chain handling for pharmaceutical-grade shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glycidol functions as a regulatory compounder where EPA TSCA Section 5 mutagenicity protocol expansion and EMA impurity specification tightening simultaneously elevate purity thresholds and compress registration timelines. CDSCO epoxide monitoring intensification in India represents the most visible demand catalyst across pharmaceutical quality control workflows.
For Market Incumbents: Lock in captive epichlorohydrin supply through backward integration or long-term feedstock agreements to defend against chlor-alkali capacity volatility. BASF SE's integrated epoxy intermediates platform in the Leverkusen-Dormagen corridor exemplifies this defensive posture. Prioritize continuous flow epoxidation technology investment to reduce batch-to-batch variability for EMA and PMDA compliance, while consolidating analytical-grade customer relationships through pre-emptive EPA consent order maintenance.
For New Entrants and Emerging Players: Launch via direct-to-formulator digital procurement platforms targeting mid-volume polyurethane foam manufacturers in Brazil and India where ANVISA and CDSCO registration pathways remain underpenetrated relative to agrochemical derivative demand growth. Brazilian glyphosate and 2,4-D formulation expansion offers the most penetrable white-space, with glycerol-derived glycidol qualifying for EU Green Deal renewable content credits as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where analytical-grade certification capabilities fragment across regional specialists lacking EPA consent order coverage or EMA pre-registration. The 5-10 year viability window favors targets with installed continuous flow epoxidation capacity and existing pharmaceutical-grade customer relationships. Acquisition target archetype: Japanese or European pure-play specialists with ISO 17025-accredited testing infrastructure and PMDA/EMA regulatory filings. Monitor EPA TSCA Section 5 registration timeline extensions as the critical inflection signal for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Epoxidation Installation | PMDA and EMA impurity specification tightening rewards reduced batch-to-batch variability in pharmaceutical-grade production. |
| Backward Integration into Epichlorohydrin | Chlor-alkali capacity constraints in European and Asian markets favor captive feedstock security for margin defense. |
| Long-term Supply Agreement with CDMOs | Pre-emptive EPA consent order relationships lock in analytical-grade demand from New Jersey and Massachusetts pharmaceutical clusters. |
| Glycerol Dehydration Process Scale-up | EU Green Deal renewable content credits in REACH-registered applications differentiate bio-derived glycidol positioning. |
| Joint Venture in Brazilian Agrochemical Formulation | ANVISA epoxide intermediate registration pathways remain underpenetrated relative to glyphosate derivative demand expansion. |
Research Approach
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each market's chemical manufacturing and pharmaceutical formulation clusters. The research combines interviews with plant managers at epoxy resin manufacturers, procurement leads at polyurethane foam formulators, distribution channel partners in specialty chemicals, and technical R&D directors at glycidol derivative producers, validated against secondary sources including customs and trade data, Cefic and ACC industry reports, SEC 10-K filings from diversified chemical conglomerates, and EPA TSCA Section 5 consent order databases. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic drivers across the analysis window.
Rate-of-change decomposition separates volume growth into construction sector epoxy insulation demand, pharmaceutical impurity reference standard expansion, and agrochemical formulation derivative uptake. Segmentation dimensions include grade tier (analytical, technical, pharmaceutical, food, cosmetic), end-use industry (chemical manufacturing, pharmaceutical, personal care, coatings, agrochemical), and regional production hub concentration. CAGRs derive from regression analysis of historical capacity utilization, feedstock cost trajectories, and regulatory registration timeline impacts, with glycerol dehydration technology diffusion and continuous flow epoxidation adoption curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA TSCA Section 5 mutagenicity study requirement expansion or chlor-alkali capacity disruption scenarios. Projections reflect assumptions regarding REACH-EMA-PMDA regulatory harmonization progress and Chinese SAMR GB standards enforcement intensity for food-contact material applications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Japan Acetonitrile Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Solvent Recovery Systems Market
Solvents
Ionic Liquids Market
Solvents
Isoamylene Market
Solvents
Sugar Dissolvers Market
Solvents
Ethyl Acetate Market
Solvents
Hydrophobic Solvents Market
Solvents
Global Solvents Market
Solvents
Hydrofluoroether Market
Solvents
United States Acetonitrile Market
Solvents
Benzyl Alcohol Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
Solvent Cement Market
Solvents
Fluorinated Solvents Market