
 North America Acetonitrile Market | 2026-2036
North America Acetonitrile Market Size, Share, and Industry Trends Forecast 2026-2036
North America Acetonitrile Market Intelligence
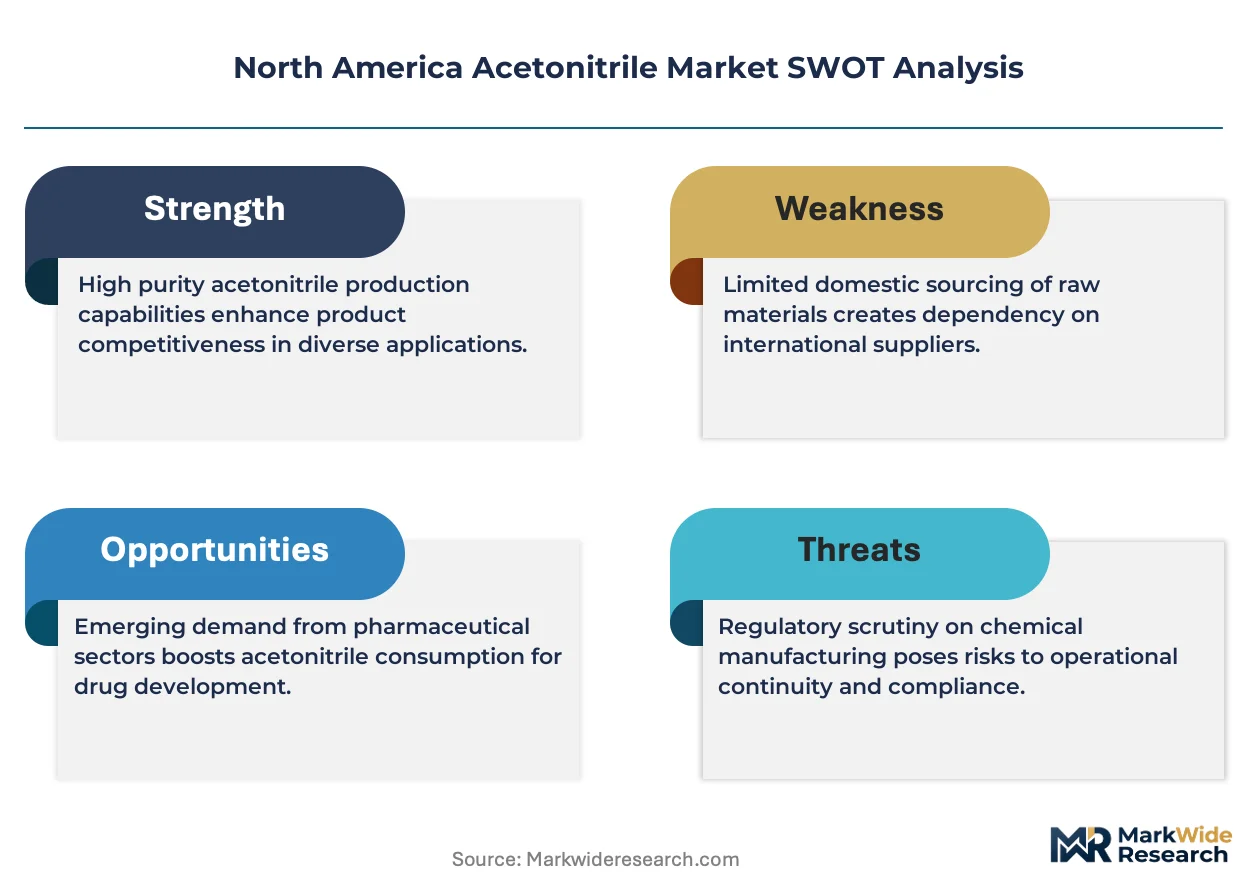
Acetonitrile derived from acrylonitrile byproduct streams is shifting toward bio-based and synthetic alternative feedstocks as propylene price volatility reshapes product economics. Nova Molecular Technologies specializes in high-purity solvent recovery systems that reduce virgin material dependence. Honeywell International Inc leverages its integrated chemical manufacturing footprint to sustain cost-advantaged supply positions. INEOS AG anchors regional capacity through its Gulf Coast petrochemical infrastructure.
Acetonitrile is a colorless, polar aprotic solvent with a molecular formula of C₂H₃N, a boiling point of 81.6°C, and a dielectric constant of 37.5, manufactured primarily as a byproduct of acrylonitrile production via propylene ammoxidation or through direct synthesis routes for high-purity grades. Its primary industrial purpose centers on pharmaceutical and analytical applications requiring minimal residual water content and ultraviolet transparency. Pharmaceutical Grade dominates value capture due to stringent USP and ACS certification requirements, while Laboratory Grade competes on volume through academic procurement channels. Chromatography application demand leads growth velocity as biopharmaceutical quality control protocols expand.
EPA oversight of acrylonitrile emissions and OSHA permissible exposure limits shape workplace handling standards and capital expenditure thresholds for production facilities. FDA pharmaceutical manufacturing guidelines and USP monograph specifications determine product qualification pathways for solvent suppliers serving drug makers. Stakeholders must monitor feedstock diversification timelines and purity certification evolution to align capacity investments with shifting end-user specifications.
Market Dynamics
Propylene feedstock volatility is compressing acrylonitrile-derived acetonitrile margins while forcing solvent buyers toward certified bio-based alternatives and recovery-loop supply arrangements.
Growth Catalysts
- HPLC-grade pharmaceutical demand:Biopharmaceutical quality control labs in the United States and Canada are expanding chromatography solvent volumes. USP certification requirements lock in premium-grade procurement.
- EPA acrylonitrile emission controls:Stricter byproduct handling standards are accelerating investment in closed-loop recovery systems at Gulf Coast production sites.
- Academic research infrastructure:National Institutes of Health funding expansion for analytical chemistry programs sustains laboratory-grade volume commitments across public university systems.
Market Restraints
- Propylene price volatility:Steam cracker feedstock economics swing acetonitrile production costs unpredictably, squeezing contract pricing stability for derivative solvent buyers.
- Gulf Coast supply concentration:Over 70% of North American capacity clusters along Texas-Louisiana petrochemical corridors, exposing buyers to hurricane disruption and logistics bottlenecks.
- Dimethyl sulfoxide substitution:Polar aprotic alternatives with lower toxicity profiles are displacing acetonitrile in select pharmaceutical synthesis steps.
Strategic Opportunities
- Mexico pharmaceutical manufacturing expansion:Nearshoring of drug production to Baja California and Querétaro creates new high-purity solvent demand outside traditional US procurement channels.
- IRA clean chemistry incentives:US tax credits for sustainable manufacturing processes subsidize bio-based acetonitrile pilot production from agricultural waste streams.
- Direct-to-lab distribution platforms:E-procurement channels serving academic and contract research organizations are compressing distributor markups and expanding supplier reach.
Industry Challenges
- USP monograph compliance timelines:Certification updates for residual solvent testing methods delay new supplier qualification by 12-18 months.
- Specialized logistics infrastructure:Temperature-controlled bulk transport and hazmat handling requirements constrain last-mile delivery flexibility for mid-volume buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Acetonitrile Market |
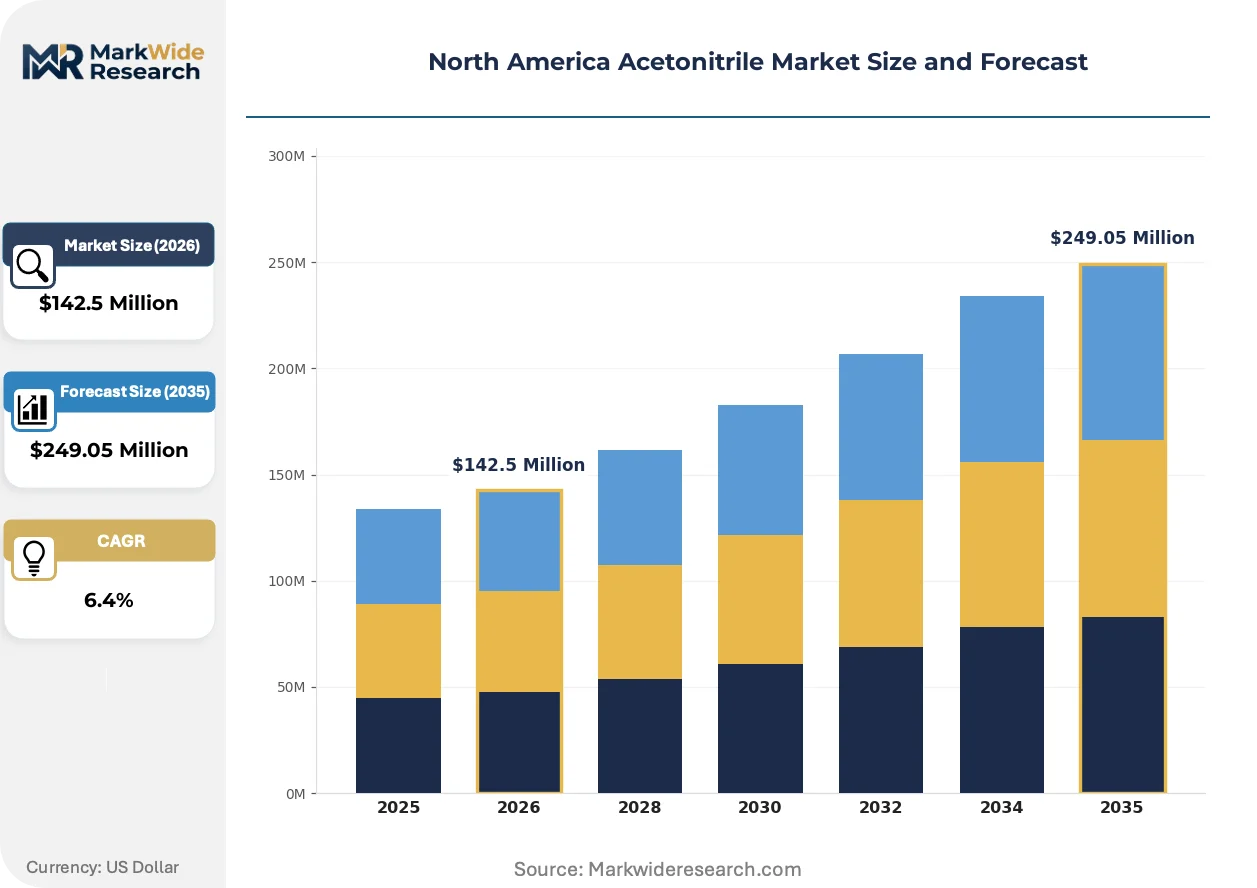
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Laboratory Grade, Analytical Grade Application: Solvent, Reagent, Extraction, Chromatography End User: Chemical Industry, Pharmaceutical Companies, Laboratories, Academic Institutions Distribution Channel: Direct Sales, Online Sales, Retail Distribution, Wholesalers |
| Companies Covered | Nova Molecular Technologies, Tedia Company Inc., BASF SE, Honeywell International Inc, INEOS AG, Dow Inc., Avantor Performance Materials LLC, Asahi Kasei Corporation, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Acetonitrile Market Strategic Shifts & Innovations
Continuous processing technologies and feedstock diversification are disrupting batch-based acetonitrile production economics while reshaping buyer-supplier contracting structures across the region.
Membrane-based solvent purification is automating the removal of trace water and UV-absorbing contaminants from recovered acetonitrile streams. Pharmaceutical manufacturers with captive recovery operations are adopting these systems fastest, cutting virgin solvent dependence by half. This automation is compressing the cost gap between recycled and virgin HPLC-grade material.
OSHA permissible exposure limit reviews for acetonitrile vapor are tightening workplace monitoring requirements. Manufacturing facilities must install upgraded ventilation and detection systems, raising operational compliance costs. Small-batch analytical labs in California and Massachusetts are responding by consolidating solvent handling into centralized prep areas.
Long-term offtake agreements are replacing spot purchasing for chromatography-grade solvent. Biopharmaceutical quality control departments are locking in multi-year supply contracts with purity guarantees. This shift is most pronounced among CDMOs clustered in Research Triangle Park and the Boston-Cambridge corridor.
North America Acetonitrile Market Segmentation
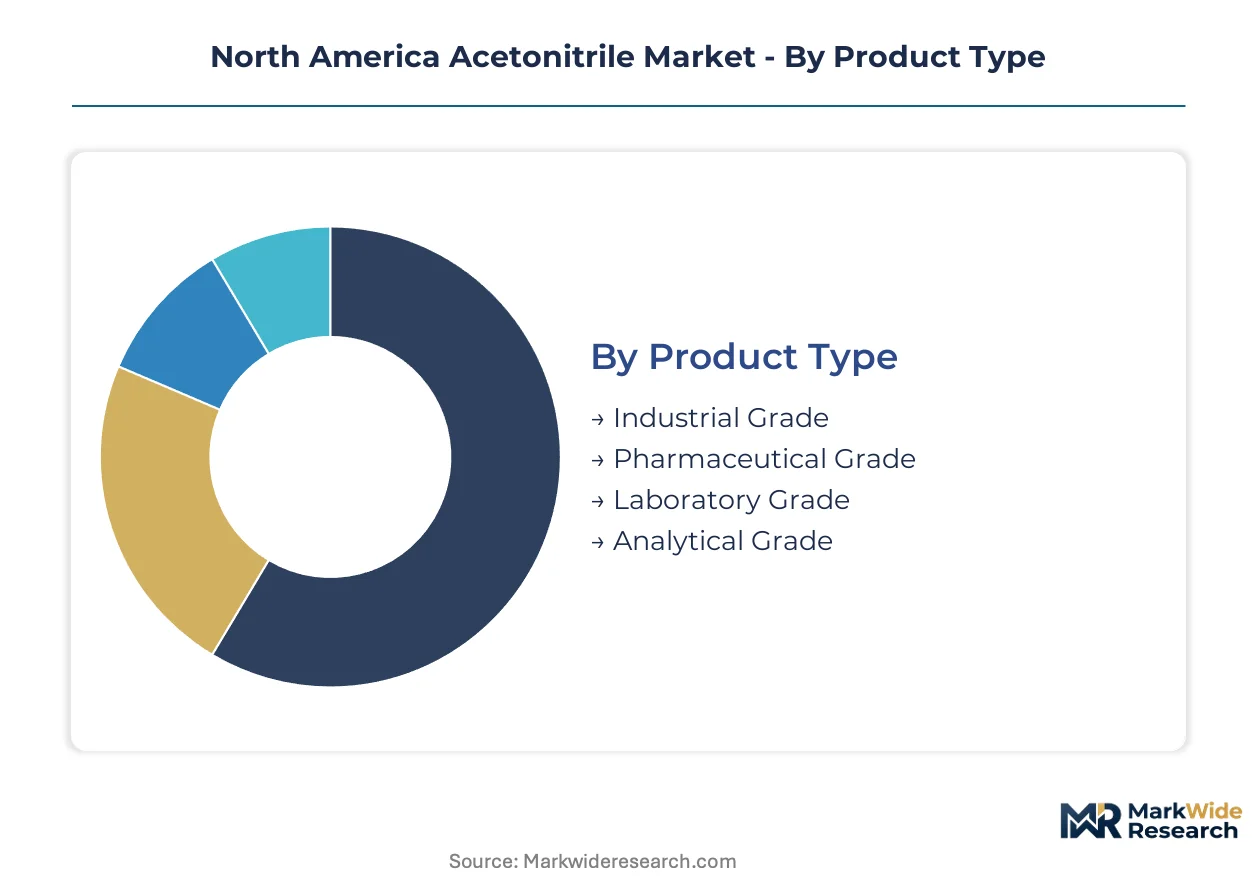
Acetonitrile procurement decisions pivot on purity certification thresholds, application-specific performance requirements, and volume scale economics. Buyers across pharmaceutical manufacturing, analytical laboratories, and chemical synthesis operations segment their supplier selection by matching grade specifications to end-use tolerances.
Product Type:
Purity specifications and certification requirements drive buyer willingness to pay across grade tiers, with USP and ACS monographs creating rigid qualification barriers.
- Pharmaceutical Grade:Meets USP monograph specifications for residual solvent limits and ultraviolet transparency below 200nm. Drug manufacturers in the Boston-Cambridge corridor and Research Triangle Park lock in multi-year supply contracts with certified suppliers to secure qualification continuity.
- Laboratory Grade:Satisfies ACS reagent standards for general analytical procedures without HPLC-specific certification. Academic procurement channels across public university systems in the United States sustain volume commitments through centralized purchasing consortia.
- Industrial Grade:Standard purity for chemical synthesis and extraction operations where trace contaminant tolerance is higher.
- Analytical Grade:Intermediate purity tier for routine quality control testing outside pharmaceutical GMP environments.
Pharmaceutical Grade leads on scale; Laboratory Grade leads on momentum as NIH funding expansion broadens academic research infrastructure.
Application:
Functional performance requirements in separation science and reaction chemistry determine solvent specification intensity and replacement cost thresholds.
- Chromatography:HPLC and UHPLC systems demand minimal residual water content, low UV cutoff, and batch-to-batch consistency for reproducible retention times. Biopharmaceutical quality control labs are expanding solvent volumes fastest as peptide and oligonucleotide therapeutic pipelines mature.
- Solvent:Polar aprotic dissolution medium for pharmaceutical intermediates, agrochemical active ingredients, and specialty chemical synthesis. Contract development and manufacturing organizations in the Gulf Coast corridor consume bulk volumes for reaction media.
- Reagent:Precipitation and derivatization chemistry in analytical sample preparation workflows.
- Extraction:Selective phase separation for pharmaceutical purification and natural product isolation.
Chromatography commands the steepest expansion trajectory; Solvent maintains the largest absolute volume position.
End User:
Regulatory exposure and quality system maturity shape procurement sophistication and supplier audit intensity.
- Pharmaceutical Companies:FDA-regulated manufacturing operations require validated supply chains with documented change control and contamination prevention protocols. CDMOs nearshoring to Baja California and Querétaro are creating new high-purity demand outside traditional US procurement channels.
- Laboratories:Independent testing facilities and quality control departments prioritize lot traceability and certificate of analysis accessibility. California and Massachusetts analytical labs are consolidating solvent handling into centralized prep areas in response to OSHA exposure limit reviews.
- Chemical Industry:Commodity solvent buyers with lower specification tolerance and price-sensitive procurement.
- Academic Institutions:Grant-funded research programs with episodic volume spikes and consortia-negotiated pricing.
Pharmaceutical Companies anchor value capture; Laboratories are gaining share fastest as diagnostic and contract testing markets expand.
Distribution Channel:
Order frequency, volume scale, and technical service requirements determine channel selection and margin structure.
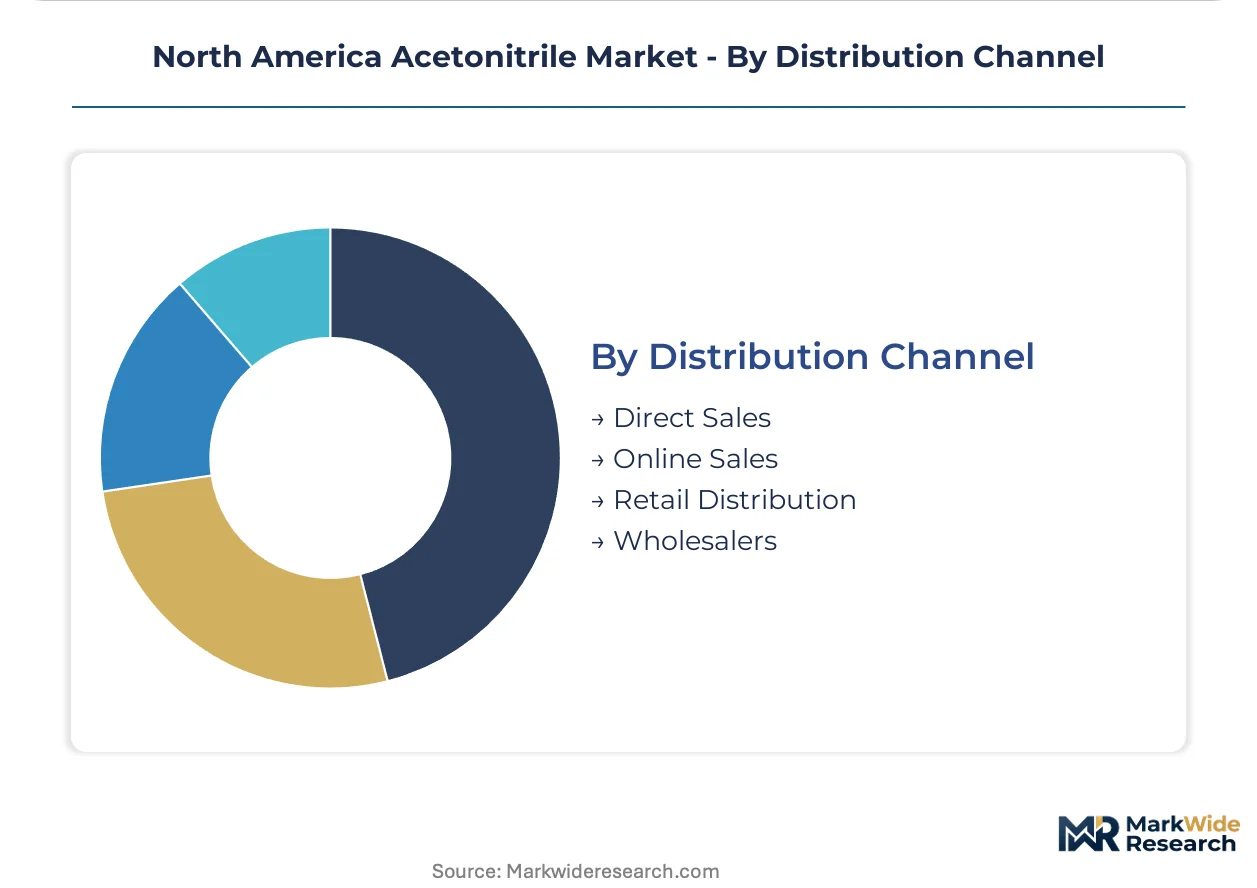
- Direct Sales:Bulk tanker and drum deliveries from manufacturers to large-volume pharmaceutical and chemical producers. Gulf Coast petrochemical corridor buyers leverage proximity to INEOS and integrated producer infrastructure for cost-advantaged supply.
- Online Sales:E-procurement platforms serving academic and contract research organizations are compressing distributor markups and expanding supplier reach beyond traditional territory assignments.
- Wholesalers:Regional distributors with temperature-controlled warehousing and hazmat handling capabilities for mid-volume buyers.
- Retail Distribution:Small-package sales through scientific supply catalogs for bench-scale research operations.
Direct Sales dominates volume throughput; Online Sales is climbing the fastest as digital procurement penetrates institutional buying workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors North American acetonitrile supply, with over 70 percent of regional capacity concentrated along Texas-Louisiana infrastructure. Pharmaceutical manufacturing clusters in the Northeast and Midwest drive HPLC-grade demand, while Mexico's nearshoring expansion creates new procurement channels outside traditional US supply chains.
United States
Biopharmaceutical quality control labs in the Boston-Cambridge corridor and Research Triangle Park are expanding chromatography solvent volumes as peptide therapeutic pipelines mature. EPA acrylonitrile emission controls under the Clean Air Act are accelerating investment in closed-loop recovery systems at Gulf Coast production sites. The Texas-Louisiana petrochemical corridor concentrates over 70 percent of domestic capacity, exposing buyers to hurricane disruption risks and logistics bottlenecks.
Canada
Health Canada-regulated pharmaceutical manufacturing operations in Ontario and Quebec require validated supply chains with documented change control protocols. The country's national pharmaceutical regulator maintains alignment with FDA guidelines for residual solvent testing methods, streamlining cross-border supplier qualification. Academic research infrastructure across public university systems sustains laboratory-grade volume commitments through centralized purchasing consortia.
Mexico
Nearshoring of drug production to Baja California and Querétaro is creating new high-purity solvent demand outside traditional US procurement channels. COFEPRIS pharmaceutical manufacturing oversight is tightening documentation requirements for imported raw materials, extending supplier qualification timelines. The Bajío Region pharmaceutical cluster is attracting contract development and manufacturing organizations seeking proximity to North American markets with lower operational costs.
North America Acetonitrile Market Key Industry Players
Global majors compete with regional champions across integrated production and specialty recovery capabilities. The vendor base clusters around three tiers: petrochemical conglomerates with captive acrylonitrile feedstock, high-purity solvent specialists with recovery-loop expertise, and diversified chemical distributors serving fragmented academic and laboratory markets. Strategic archetypes include integrated propylene-to-solvent producers, solvent recovery technology specialists, and regional distribution platforms. Capacity expansion along the Gulf Coast and bio-based feedstock pilot investments represent dominant competitive moves.
Among integrated chemical manufacturers, Honeywell International Inc and INEOS AG exemplify scale-driven positions anchored to Gulf Coast infrastructure. Nova Molecular Technologies occupies a specialist tier focused on high-purity solvent recovery systems that reduce virgin material dependence. These three companies collectively illustrate the competitive spectrum from petrochemical integration to circular economy technology.
| Leading Market Players |
|---|
| Nova Molecular Technologies |
| Tedia Company Inc. |
| BASF SE |
| Honeywell International Inc |
| INEOS AG |
| Dow Inc. |
| Avantor Performance Materials LLC |
| Asahi Kasei Corporation |
| Mitsubishi Chemical Corporation |
| Others |
Cost & Logistics Intelligence
EPA acrylonitrile emission controls under the Clean Air Act gate qualified supply access and premium-tier pricing power for HPLC-grade acetonitrile. Solvent buyers face compressed procurement flexibility as certified producers absorb compliance capital costs into long-term offtake premiums.
Pricing Analysis
Propylene feedstock volatility passes through directly to acetonitrile contract pricing, compressing margins for derivative solvent buyers. Three-tier pricing structure across pharmaceutical, laboratory, and industrial grades reflects USP certification intensity and volume scale. Pricing pressure stems from bio-based alternative pilot programs subsidized under IRA clean chemistry incentives. Academic procurement consortia exhibit highest price sensitivity; biopharmaceutical CDMOs lock in premium-tier contracts with purity guarantees.
Supply Chain Analysis
Direct-to-pharma channels handle hyperscale buyer demand through Gulf Coast tanker deliveries, while e-procurement platforms serve fragmented academic markets. Supply concentrates in the United States Texas-Louisiana corridor, with secondary sourcing from Canadian petrochemical infrastructure and emerging Mexican nearshoring clusters. Feedstock dependence rests on propylene ammoxidation streams, acrylonitrile byproduct recovery, and pilot-scale bio-based agricultural waste conversion. Single-source vulnerability from hurricane exposure along the Gulf Coast threatens regional logistics continuity. Distribution runs through integrated producer networks, regional wholesalers with hazmat capabilities, and digital platforms compressing distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America acetonitrile market represents a late-cycle quality story as biopharmaceutical quality control protocols shift procurement toward USP-certified HPLC-grade specifications with documented change control.
For Market Incumbents: Anchor Gulf Coast capacity positions through backward integration into propylene feedstock logistics and captive acrylonitrile supply. Invest in membrane-based solvent recovery automation to defend margin compression from virgin material substitution. Secure multi-year offtake agreements with Boston-Cambridge and Research Triangle Park CDMOs before USP monograph compliance timelines extend qualification windows. For New Entrants and Emerging Players: Enter via Mexico's Baja California and Querétaro pharmaceutical manufacturing expansion, where COFEPRIS import documentation requirements have slowed incumbent qualification. Target laboratory-grade consortia procurement at underfunded public university systems as the most penetrable volume tier. Lead with direct-to-lab digital distribution to bypass established wholesaler relationships. For Investors and Strategic Acquirers: Roll-up economics work for solvent recovery technology specialists because pharmaceutical manufacturers are cutting virgin material dependence by half through captive circular systems. Five-to-ten-year viability hinges on bio-based feedstock commercialization timelines and EPA emission control stringency. Watch IRA clean chemistry incentive renewal debates as the signal for bio-based acetonitrile production inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive feedstock access insulates Honeywell and INEOS from steam cracker economics volatility. |
| Membrane-Based Recovery System Deployment | Nova Molecular Technologies automation cuts virgin solvent dependence for pharmaceutical captive operations. |
| Mexico Nearshoring Capacity Positioning | Baja California and Querétaro drug production expansion creates new high-purity solvent demand outside US procurement channels. |
| Bio-Based Feedstock Pilot Investment | IRA tax credits subsidize agricultural waste stream conversion alternatives to acrylonitrile byproduct dependence. |
| Direct-to-Lab E-Procurement Platform Launch | Digital channels compress distributor markups and expand supplier reach beyond traditional territory assignments. |
Research Approach
Coverage spans the United States Gulf Coast, Northeast pharmaceutical corridors, Canada Ontario-Quebec manufacturing clusters, and Mexico Bajío Region, with primary inputs from each. The analysis combines structured interviews with plant managers at integrated petrochemical producers, procurement leads at biopharmaceutical CDMOs, distribution channel partners with hazmat warehousing capabilities, and technical R&D directors at solvent recovery specialists. Secondary validation draws from EPA Clean Air Act filings, FDA pharmaceutical manufacturing guidance documents, SEC 10-K chemical segment disclosures, and American Chemistry Council trade data. Bottom-up volume modeling and top-down value triangulation cross-check segment outputs.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models grade tier specifications, end-use application intensity, packaging format economics, and regional production hub proximity. CAGRs derive from segment-level demand elasticity analysis and feedstock cost pass-through coefficients. Key forecast inputs include NIH funding expansion trajectories for academic research infrastructure and biopharmaceutical peptide therapeutic pipeline maturation rates.
Inputs from EPA regulatory dockets and pharmaceutical procurement databases were available through the study window; gaps in real-time propylene contract pricing introduce uncertainty bands around margin compression assumptions. Forecasts reflect documented base-case assumptions regarding IRA incentive continuity and USP monograph revision timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Diethanolamide Market
Solvents
Electronic Cleaning Solvents Market
Solvents
N-Pentyl Chloride Market
Solvents
Mesitylene Market
Solvents
Solvent Green 7 Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Monochlorobenzene Market
Solvents
Global Glycidol Market
Solvents
Benzene Market
Solvents
North America Toluene Market
Solvents
Chlorobenzene Market
Solvents
Benzylamine Market
Solvents
Global Solvent Evaporation Market
Solvents
C2 Chlorinated Solvents Market
Solvents
Ionic Liquids Market