
 Chlorobenzene Market | 2026-2036
Chlorobenzene Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorobenzene Market Analysis
The agrochemical sector is pivoting toward chlorobenzene-derived intermediates as crop protection chemistry intensifies. Sinopec leverages its integrated petrochemical complexes to anchor regional supply chains for chlorobenzene derivatives. Kureha Corporation specializes in high-purity grades for specialty chemical applications. Jiangsu Yangnong Chemicals Group Co., Ltd. competes on agrochemical downstream integration, sustaining captive demand for chlorobenzene feedstock.
Chlorobenzene is a halogenated aromatic hydrocarbon produced via benzene chlorination using ferric chloride catalysis, yielding mono- and poly-chlorinated variants with boiling points ranging from 132°C to 180°C depending on substitution degree. The compound serves primarily as a chemical intermediate and industrial solvent in pesticide synthesis, dye production, and rubber processing operations. Pure Grade chlorobenzene commands premium positioning in pharmaceutical and electronics applications where residual impurity thresholds sit below 0.1%. Technical Grade dominates volume flows into agrochemical and rubber processing channels where cost efficiency outweighs purity requirements. Laboratory Grade occupies a narrow but high-margin niche serving analytical standards and research institutions.
EPA regulations under the Toxic Substances Control Act constrain chlorobenzene emissions and waste handling protocols in U.S. chemical processing facilities. REACH registration requirements and ECHA classification protocols govern chlorobenzene import volumes and substitution pressures across European manufacturing bases. China's MEE enforces wastewater discharge standards for chlorinated benzene compounds that shape production economics in Shandong and Jiangsu chemical clusters. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate plant location and product grade strategies.
Market Dynamics
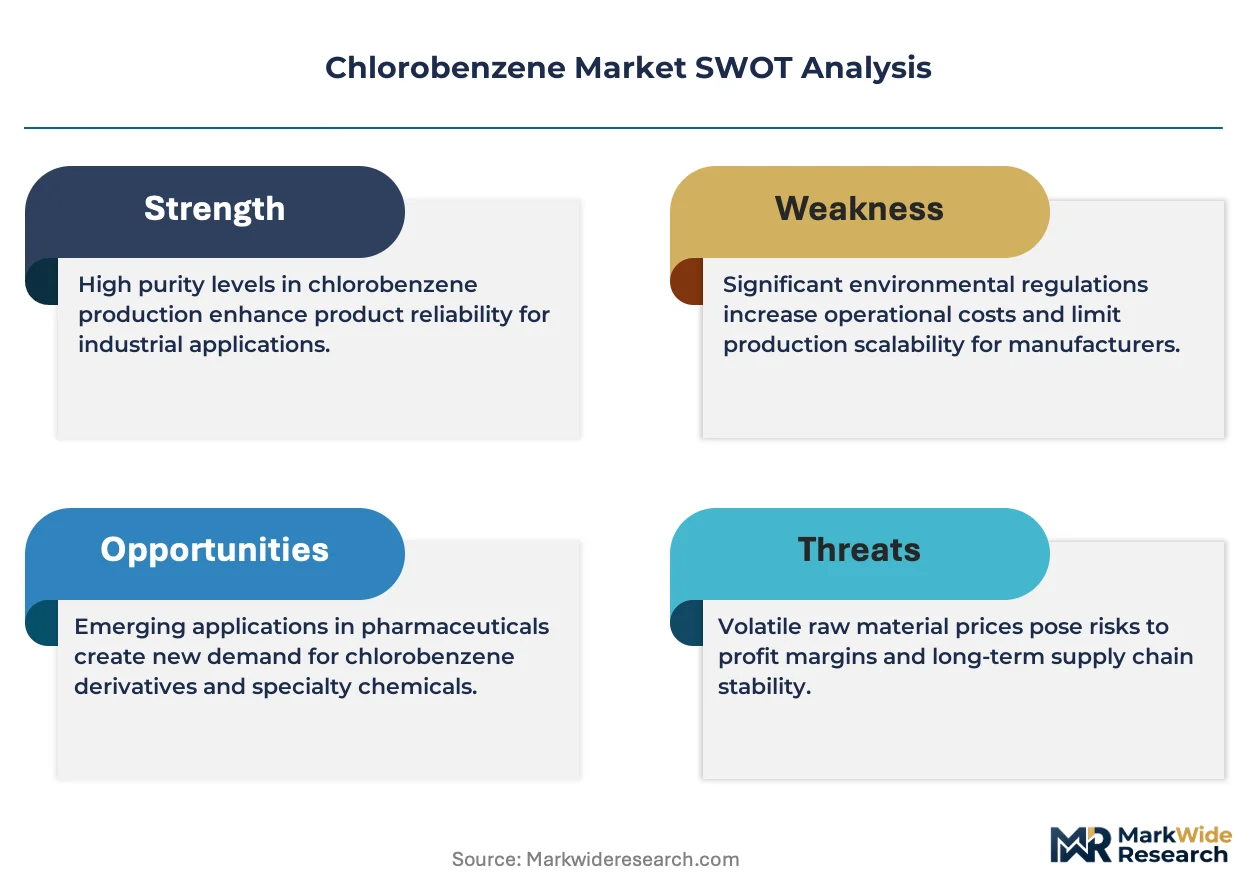
REACH registration pressures and the EU Green Deal are compressing chlorinated aromatic production margins in Europe, redirecting investment toward integrated complexes in China and the US Gulf Coast where emissions compliance costs remain structurally lower.
Growth Catalysts
- Agrochemical downstream integration:Pesticide manufacturers are securing captive chlorobenzene supply chains to insulate against feedstock volatility. This integration locks in volume commitments from specialty chemical producers.
- REACH substitution timelines:The EU's phased restrictions on legacy chlorinated solvents are pushing formulators toward chlorobenzene alternatives with more favorable toxicological profiles, expanding addressable demand in coatings and adhesives.
- Electronics-grade purification:Semiconductor etching and display manufacturing require sub-0.1% impurity thresholds. High-purity chlorobenzene distillation capabilities are attracting premium positioning in East Asian electronics clusters.
Market Restraints
- Benzene feedstock volatility:Crude oil price swings transmit directly to chlorobenzene production economics, compressing margins for non-integrated producers lacking upstream aromatics access.
- Shandong-Jiangsu supply concentration:Over 60% of global chlorobenzene capacity sits within 500 kilometers in eastern China, creating geographic risk exposure to regional environmental enforcement actions or logistics disruptions.
- Green solvent substitution:Bio-based alternatives and aqueous formulations are displacing chlorobenzene in textile dyeing and metal degreasing applications where performance parity has improved.
Strategic Opportunities
- Indian agrochemical manufacturing:The PLI scheme and dedicated chemical parks in Gujarat and Andhra Pradesh offer tariff advantages for chlorobenzene-derived pesticide intermediates serving domestic and export markets.
- Carbon border adjustment mechanisms:The EU CBAM creates competitive openings for producers with verified low-carbon chlorination processes, rewarding investments in ferric chloride catalyst recycling and energy recovery systems.
- Pharmaceutical CDMO integration:Contract development and manufacturing organizations are consolidating API synthesis steps, creating demand for multi-ton chlorobenzene quantities in continuous flow reactor installations.
Industry Challenges
- Halogenation process engineering expertise:The specialized knowledge required for safe chlorine handling and HCl byproduct recovery is concentrated among aging workforces in legacy chemical manufacturing regions.
- MEE wastewater compliance timelines:China's Ministry of Ecology and Environment is accelerating discharge standard revisions, forcing producers to retrofit biological treatment and activated carbon systems on compressed schedules.
- Legacy asset retrofit complexity:Batch chlorination infrastructure predating 2010 environmental standards requires substantial capital reconfiguration to meet current emissions monitoring and containment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorobenzene Market |
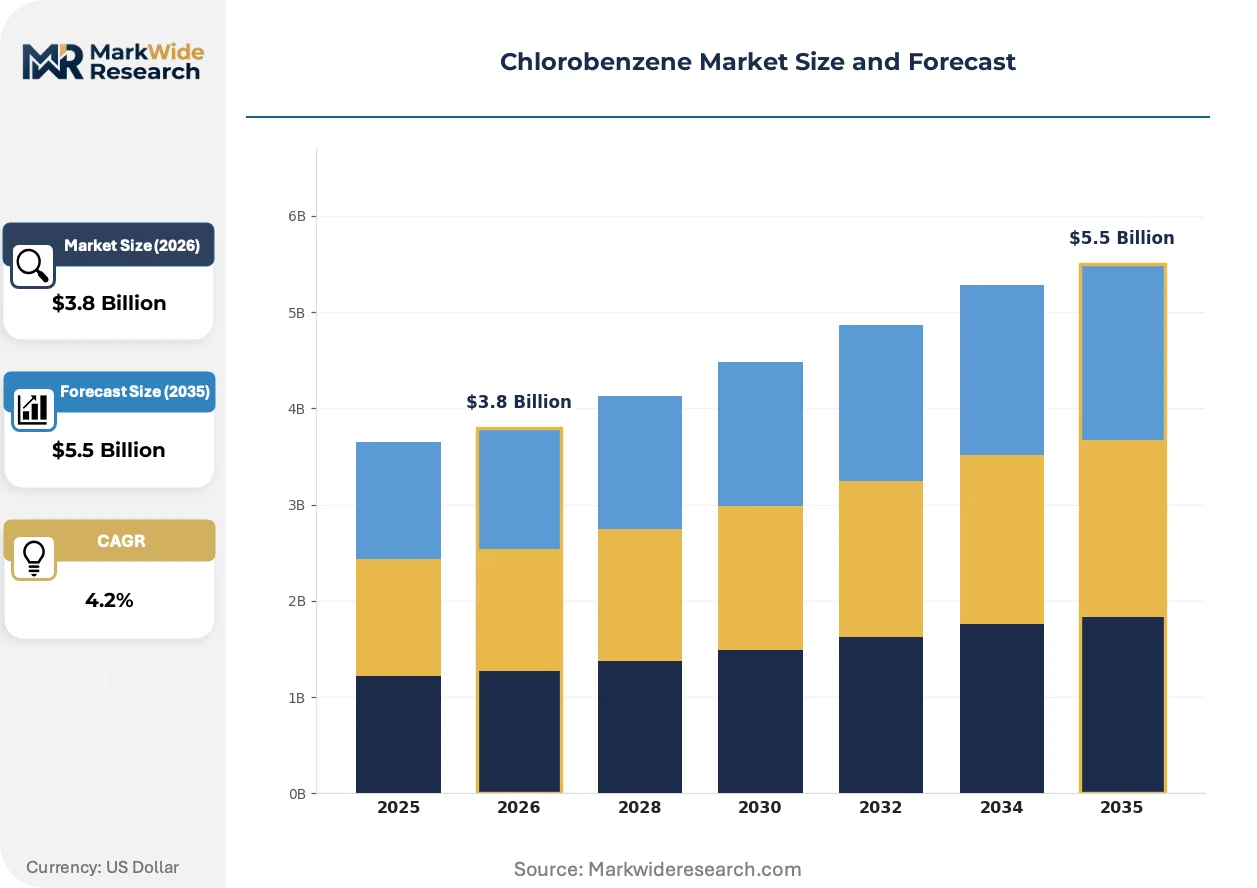
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Pure Grade, Industrial Grade, Laboratory Grade Application: Solvent, Intermediate for Pesticides, Dye Manufacturing, Rubber Processing End Use Industry: Agrochemical Manufacturers, Textile Manufacturers, Paint & Coatings, Chemical Processing Units Packaging Type: Drums, Tankers, Metal Cans, Fiber Drums |
| Companies Covered | Sinopec, Kureha Corporation, Anhui Bayi Chemical Industry, Merck KGaA, Lanxess, Chemada Fine Chemicals, Jiangsu Yangnong Chemicals Group Co., Ltd., Honeywell International Inc, China Petrochemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorobenzene Market Emerging Trajectories
Continuous flow reactor technology is displacing batch chlorination across chlorobenzene production, cutting solvent losses and enabling real-time process analytics that were economically unfeasible in conventional stirred-tank configurations.
Membrane-based chlorine recovery systems are electrifying separation economics in integrated chlorobenzene complexes. Specialty chemical producers in the US Gulf Coast are deploying these units to reduce chlorine purchasing volumes by 15-25%. The technology compresses operating costs while tightening emissions profiles ahead of EPA Toxic Substances Control Act enforcement windows.
REACH authorization requirements for chlorinated aromatics are forcing downstream users to document substitution plans or secure time-limited exemptions. Agrochemical formulators in Germany and the Netherlands are consolidating suppliers to reduce compliance documentation burdens. This regulatory friction is accelerating captive integration strategies among volume consumers.
Specification-driven procurement contracts are replacing spot-market purchasing for electronics-grade chlorobenzene. Display panel manufacturers in South Korea and Taiwan are locking in multi-year supply agreements with embedded purity guarantees and audit rights. This shift transfers inventory risk upstream while compressing the viable supplier base to integrated producers with analytical certification capabilities.
Chlorobenzene Market Segmentation
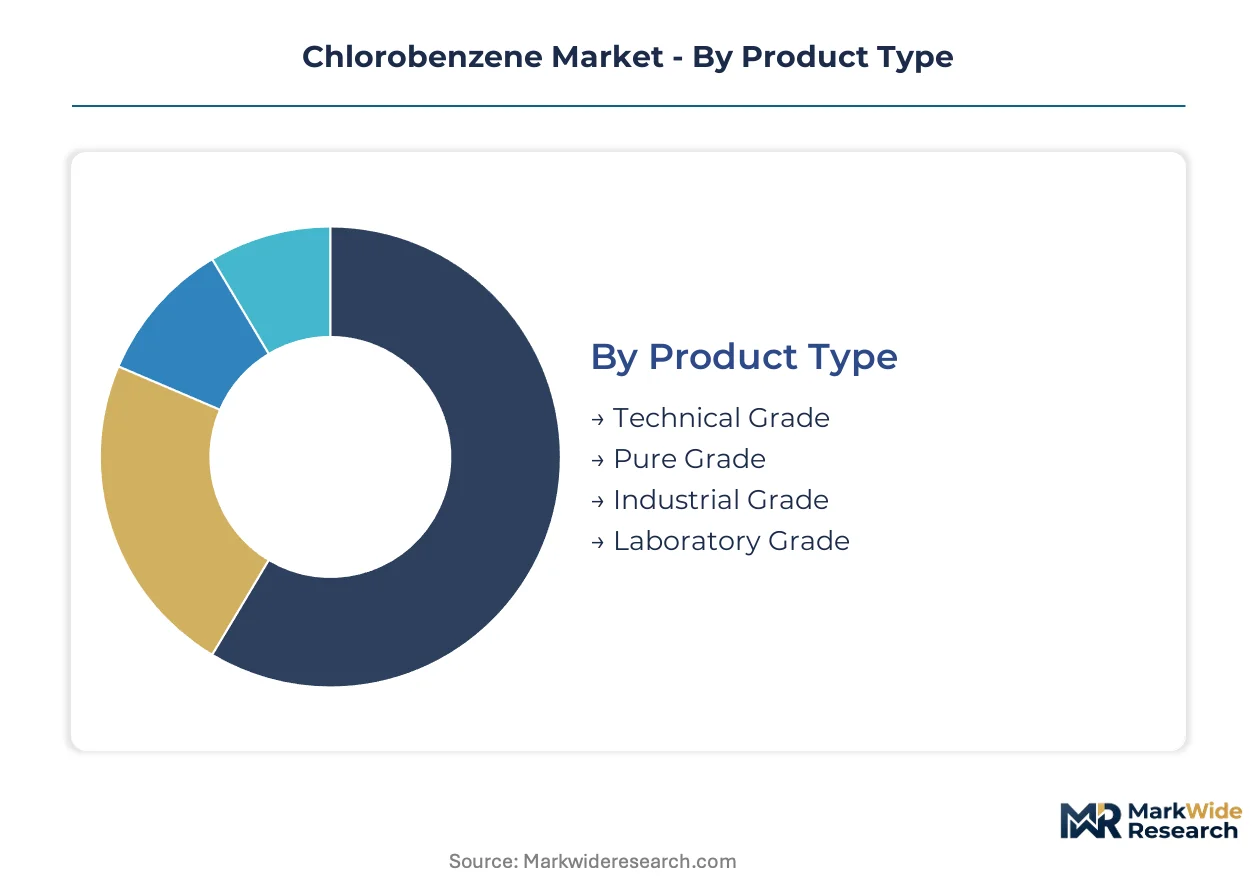
Chlorobenzene procurement patterns diverge sharply across purity thresholds and container formats. Specification requirements from semiconductor etching operations, agrochemical synthesis, and rubber compounding create distinct commercial channels with incompatible sourcing protocols.
Product Type:
Volume flows concentrate in cost-optimized grades while premium tiers capture margin concentration in specialized applications.
- Technical Grade:Residual impurity tolerance above 0.5% suits bulk agrochemical and rubber processing applications where cost efficiency dominates procurement criteria. Sinopec and Jiangsu Yangnong Chemicals Group anchor supply contracts for captive pesticide intermediate production across Shandong chemical clusters.
- Pure Grade:Sub-0.1% impurity specification enables pharmaceutical API synthesis and electronics-grade solvent applications. Kureha Corporation maintains distillation capabilities that satisfy semiconductor manufacturers in South Korea and Taiwan requiring embedded purity guarantees and audit rights.
- Industrial Grade:Mid-range purity positioning serves general chemical processing and metal degreasing operations with moderate specification tolerance.
- Laboratory Grade:Analytical standard certification supports research institutions and quality control laboratories with batch-level traceability requirements.
Today's leader: Technical Grade. Tomorrow's challenger: Pure Grade.
Application:
End-use concentration in crop protection chemistry is reshaping demand composition across regional manufacturing bases.
- Solvent:Carrier function in coatings and adhesives formulations faces displacement pressure from aqueous and bio-based alternatives where performance parity has improved.
- Intermediate for Pesticides:Chlorobenzene serves as feedstock for chloronitrobenzene and other agrochemical precursors. Indian PLI scheme beneficiaries in Gujarat and Andhra Pradesh are securing captive supply chains for export-oriented pesticide manufacturing.
- Dye Manufacturing:Pigment intermediate synthesis concentrates in China due to integrated textile chemical supply chains in Zhejiang and Jiangsu provinces.
- Rubber Processing:Vulcanization accelerator production consumes technical grade volumes with specification tolerance for sulfur cross-linking chemistry.
Intermediate for Pesticides commands current volume leadership. Dye Manufacturing offers the steepest expansion trajectory as textile chemical clusters deepen backward integration.
End Use Industry:
Customer type determines contract structure, with agrochemical integrators favoring multi-year commitments against spot-market textile purchasing.
- Agrochemical Manufacturers:Captive chlorobenzene integration insulates against benzene feedstock volatility. REACH substitution timelines in Europe are compressing supplier bases as formulators consolidate documentation burdens.
- Textile Manufacturers:Dye intermediate procurement concentrates in Shandong-Jiangsu corridor with MEE wastewater compliance driving supplier selection.
- Paint & Coatings:Solvent applications face EPA Toxic Substances Control Act emissions constraints and green formulation substitution in North American markets.
- Chemical Processing Units:General intermediate demand spans batch and continuous reactor configurations with divergent purity requirements.
Agrochemical Manufacturers anchor contract volumes. Chemical Processing Units present the most fragmented procurement profile.
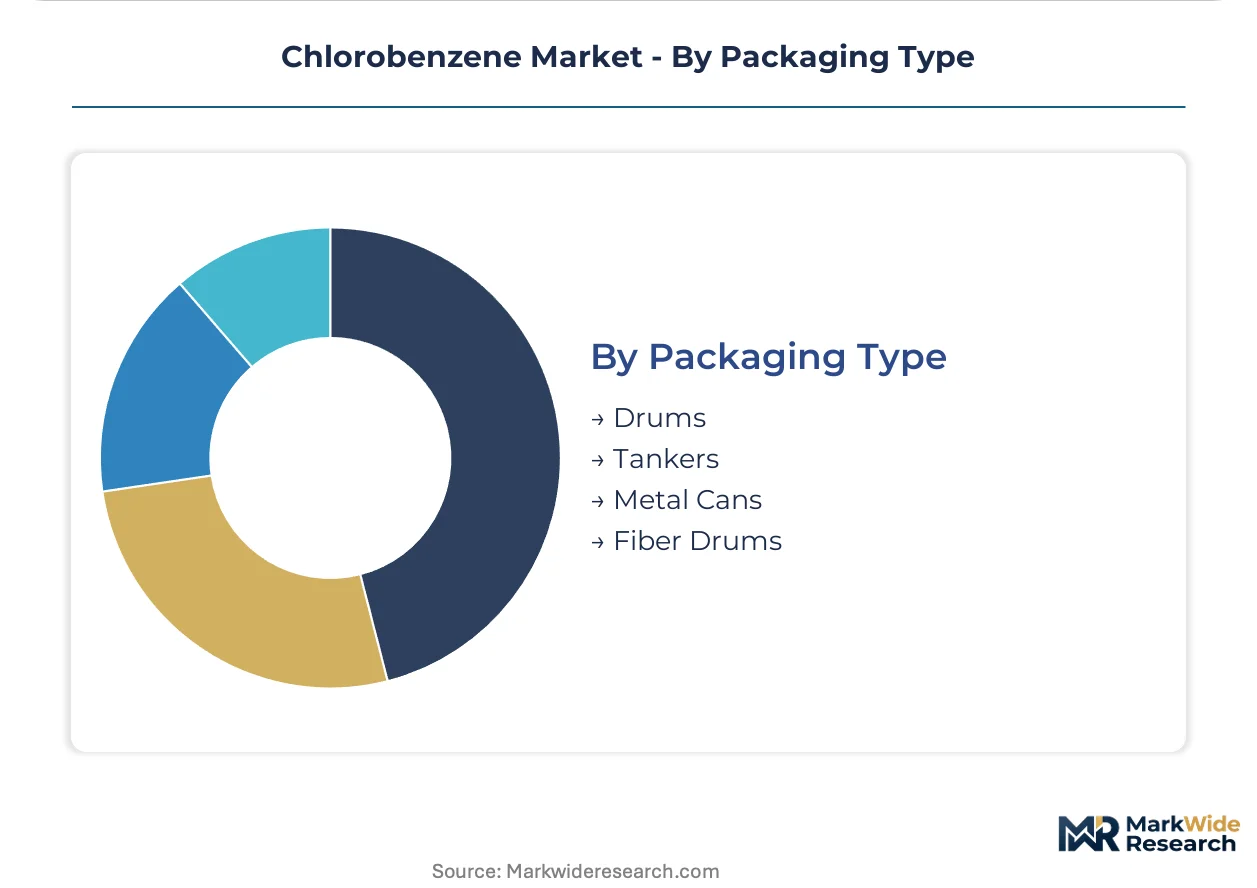
Packaging Type:
Logistics configuration tracks shipment scale and hazard classification across integrated versus merchant supply chains.
- Drums:Standard 200-liter steel containers serve mid-volume chemical processors with inventory turnover requirements below tanker minimums.
- Tankers:Bulk liquid transport enables continuous flow reactor feedstock delivery for integrated chlorobenzene derivatives complexes.
- Metal Cans:Small-format packaging supports laboratory grade distribution with contamination prevention specifications.
- Fiber Drums:Lightweight alternative for solid chlorobenzene derivatives and intermediate formulations with reduced corrosion risk.
Tankers dominate tonnage flows. Metal Cans capture the highest unit margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting chlorobenzene investment toward jurisdictions where emissions compliance costs remain structurally lower. REACH authorization timelines and EU Green Deal carbon pricing are compressing European production margins. Capital is migrating to integrated petrochemical complexes in China and the US Gulf Coast where environmental enforcement carries lower cost penalties.
China
Agrochemical intermediate demand and dye manufacturing concentration anchor chlorobenzene consumption. MEE wastewater discharge standards are accelerating treatment system retrofits across Shandong and Jiangsu chemical clusters. The Yangtze River Delta hosts integrated chlorobenzene derivatives complexes serving captive pesticide and rubber processing supply chains.
United States
Electronics-grade purification requirements and semiconductor etching applications drive high-purity demand. EPA Toxic Substances Control Act emissions protocols constrain batch chlorination operations while favoring continuous flow reactor investments. The US Gulf Coast petrochemical corridor attracts membrane-based chlorine recovery system deployments that reduce operating costs ahead of enforcement windows.
Germany
REACH substitution pressures and ECHA classification protocols are forcing downstream agrochemical formulators to consolidate supplier bases. The EU CBAM creates competitive pressure on carbon-intensive chlorination imports. Industrial chemical processing in North Rhine-Westphalia faces margin compression as documentation burdens intensify for chlorinated aromatic users.
India
PLI scheme beneficiaries in Gujarat and Andhra Pradesh are securing captive chlorobenzene supply chains for export-oriented pesticide manufacturing. The country's national chemical regulator is aligning discharge standards with evolving MEE benchmarks. Dedicated chemical parks in western and southern states offer tariff advantages for chlorobenzene-derived intermediate production.
Japan
Specialty chemical applications and pharmaceutical CDMO integration sustain demand for high-purity grades. METI industrial chemical standards govern chlorinated aromatic handling protocols in legacy manufacturing regions. Kansai and Chubu industrial corridors maintain distillation capabilities for sub-0.1% impurity threshold requirements in electronics and pharmaceutical synthesis.
Chlorobenzene Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical groups commanding volume flows and purity-focused distillers capturing premium tiers. Market structure concentrates around three archetypes: state-affiliated energy majors with upstream aromatics access, specialty chemical distillers with analytical certification capabilities, and regional chemical processors serving captive agrochemical demand. Dominant competitive moves include backward integration into benzene feedstock and geographic relocation toward lower-compliance-cost jurisdictions.
Among Asia-Pacific integrated producers, Sinopec and Jiangsu Yangnong Chemicals Group Co., Ltd. exemplify the state-linked petrochemical archetype with captive demand insulation. Kureha Corporation occupies a position representing the high-purity distillation specialist tier serving electronics and pharmaceutical channels with embedded purity guarantees. These three anchors illustrate how geographic origin and corporate structure map to divergent competitive positioning across technical and pure grade segments.
| Leading Market Players |
|---|
| Sinopec |
| Kureha Corporation |
| Anhui Bayi Chemical Industry |
| Merck KGaA |
| Lanxess |
| Chemada Fine Chemicals |
| Jiangsu Yangnong Chemicals Group Co., Ltd. |
| Honeywell International Inc |
| China Petrochemical Corporation |
| Others |
Supply Flow & Price Mechanics
Pure-to-technical grade divergence splits chlorobenzene procurement into two non-interoperable channels, with sub-0.1% impurity specifications commanding embedded purity guarantees and audit rights while residual tolerance above 0.5% flows through spot-indexed bulk contracts. This bifurcation concentrates pricing power with Kureha Corporation and Sinopec respectively, as certification capabilities and captive benzene access become mutually exclusive competitive moats that reshape downstream supply chain configurations.
Pricing Analysis
Distributor margin capture runs through specification-driven procurement contracts replacing spot-market purchasing for electronics-grade material. Three-tier pricing structure across premium, standard, and economy levels reflects purity certification, volume scale, and geographic delivery cost differentiation. Cost compression in technical grade is intensifying because benzene feedstock volatility transmits directly to non-integrated producers. Agrochemical manufacturers show highest price sensitivity due to cost efficiency procurement criteria, while semiconductor etching operations demonstrate least sensitivity given sub-0.1% impurity thresholds.
Supply Chain Analysis
Dual-sourcing requirements from display panel manufacturers in South Korea and Taiwan mandate multi-supplier qualification, compressing the viable supplier base to integrated producers with analytical certification capabilities. Geographic supply concentration centers on China, the United States, and Japan. Raw material dependencies draw from benzene aromatics, ferric chloride catalyst, and chlorine feedstock. Single-source vulnerability persists as over 60% of global capacity sits within 500 kilometers in eastern China. Distribution runs through tanker bulk liquid transport for integrated complexes and drum containers for mid-volume chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chlorobenzene constitutes a late-cycle quality story as semiconductor etching and pharmaceutical CDMO integration pivot procurement toward sub-0.1% impurity specifications that reward distillation capabilities over commodity scale.
For Market Incumbents: Lock in multi-year supply agreements with embedded purity guarantees before REACH substitution timelines compress supplier bases further. Secure backward integration into benzene feedstock to insulate against crude oil price volatility that compresses margins for non-integrated producers. Prioritize continuous flow reactor investments ahead of EPA Toxic Substances Control Act enforcement windows that disadvantage batch chlorination operations. For New Entrants and Emerging Players: Specialty chemical distillers with analytical certification capabilities represent an underserved buyer archetype as electronics-grade purification requirements outstrip existing high-purity capacity. Target Indian agrochemical manufacturing under PLI scheme beneficiaries in Gujarat and Andhra Pradesh seeking captive chlorobenzene supply chains for export-oriented pesticide production. Pursue joint venture structures with established benzene producers to circumvent capital barriers in ferric chloride catalysis infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where MEE wastewater compliance timelines force sub-scale producers to retrofit biological treatment systems on compressed schedules, creating distressed asset opportunities. Five-to-ten year viability favors integrated petrochemical groups with upstream aromatics access and regional positioning in lower-compliance-cost jurisdictions. Watch for carbon border adjustment mechanism implementation as inflection indicator that rewards verified low-carbon chlorination processes with competitive tariff positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive benzene access insulates Sinopec and Jiangsu Yangnong against feedstock volatility that erodes merchant producer margins. |
| Continuous Flow Reactor Deployment | Membrane-based chlorine recovery systems cut operating costs 15-25% ahead of EPA enforcement windows in US Gulf Coast complexes. |
| High-Purity Distillation Capacity | Sub-0.1% impurity certification satisfies South Korean and Taiwanese semiconductor manufacturers requiring embedded audit rights. |
| Geographic Relocation | Investment migration toward Shandong-Jiangsu chemical clusters exploits structurally lower emissions compliance costs versus European production. |
| Long-term Supply Agreement | Multi-year contracts with agrochemical integrators lock in volume commitments against benzene price swings and substitution pressures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers, procurement leads at downstream agrochemical OEMs, distribution channel partners, and technical R&D directors with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE discharge standard documentation. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Segment-weighting approaches applied grade tier, end-use industry, packaging format, and regional production hub dimensions throughout the projection horizon. CAGRs derived from regression against benzene price elasticity, agrochemical downstream integration rates, and electronics-grade purity demand trajectories. Forecast inputs incorporated REACH substitution timeline progression and MEE wastewater standard revision schedules.
Underlying measurement precision varies by segment; pure grade and electronics applications carry tighter precision than technical grade commodity flows. Forecasts reflect assumptions around benzene feedstock stability, chlorine supply continuity, and regulatory enforcement intensity. Deviation in MEE discharge standard acceleration or EU CBAM carbon pricing implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
N-Hexane Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Benzylamine Market
Solvents
2-Butanone Market
Solvents
Ketone-Based Solvents Market
Solvents
Butane Market
Solvents
Wax Dispersion Market
Solvents
Diethanolamine (DEA) Market
Solvents
Triacetin Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Chloromethane Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
Diethanolamide Market
Solvents
C2 Chlorinated Solvents Market
Solvents
Potassium Formate Market
Solvents
2 - Ethyl Anthraquinone Market