
 Middle East Gaming Market | 2026-2036
Middle East Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Gaming Market Outlook
Casual mobile players is collapsing into hardcore and esports-oriented consumers across the Middle East. Krafton leverages its battle royale expertise to anchor competitive gaming communities in Gulf markets. Tencent Holdings Ltd. sustains platform dominance through WeGame international expansion and minority stakes in regional publishers. Tamatem Games specializes in culturally localized mobile titles, occupying a distinct position between global franchises and Arabic-language content gaps.
Middle East Gaming encompasses interactive electronic entertainment software and hardware distributed across mobile, PC, console, and virtual reality platforms, requiring low-latency server infrastructure and Arabic localization pipelines to serve dispersed populations across arid geographies with uneven broadband penetration. Mobile Games command the largest participant base given smartphone ubiquity and prepaid data affordability, while VR Games represent the fastest-growing category as Saudi-funded immersive entertainment venues proliferate. Free-to-Play monetization captures mass market volume through advertising and cosmetic microtransactions, though In-App Purchases increasingly drive revenue per user as Gulf consumers demonstrate higher willingness to pay for progression acceleration and exclusive digital goods.
Saudi Arabia's General Authority for Media Regulation and the UAE's National Electronic Security Authority enforce content classification and data residency requirements that shape product localization timelines and server deployment decisions for foreign publishers. Egypt's Supreme Council for Media Regulation adds another compliance layer for North African market access, particularly regarding religious and political content screening. Stakeholders must monitor evolving national gaming investment funds and sovereign wealth vehicle priorities that determine which development studios receive preferential licensing and infrastructure support across the Gulf Cooperation Council corridor.
Market Dynamics
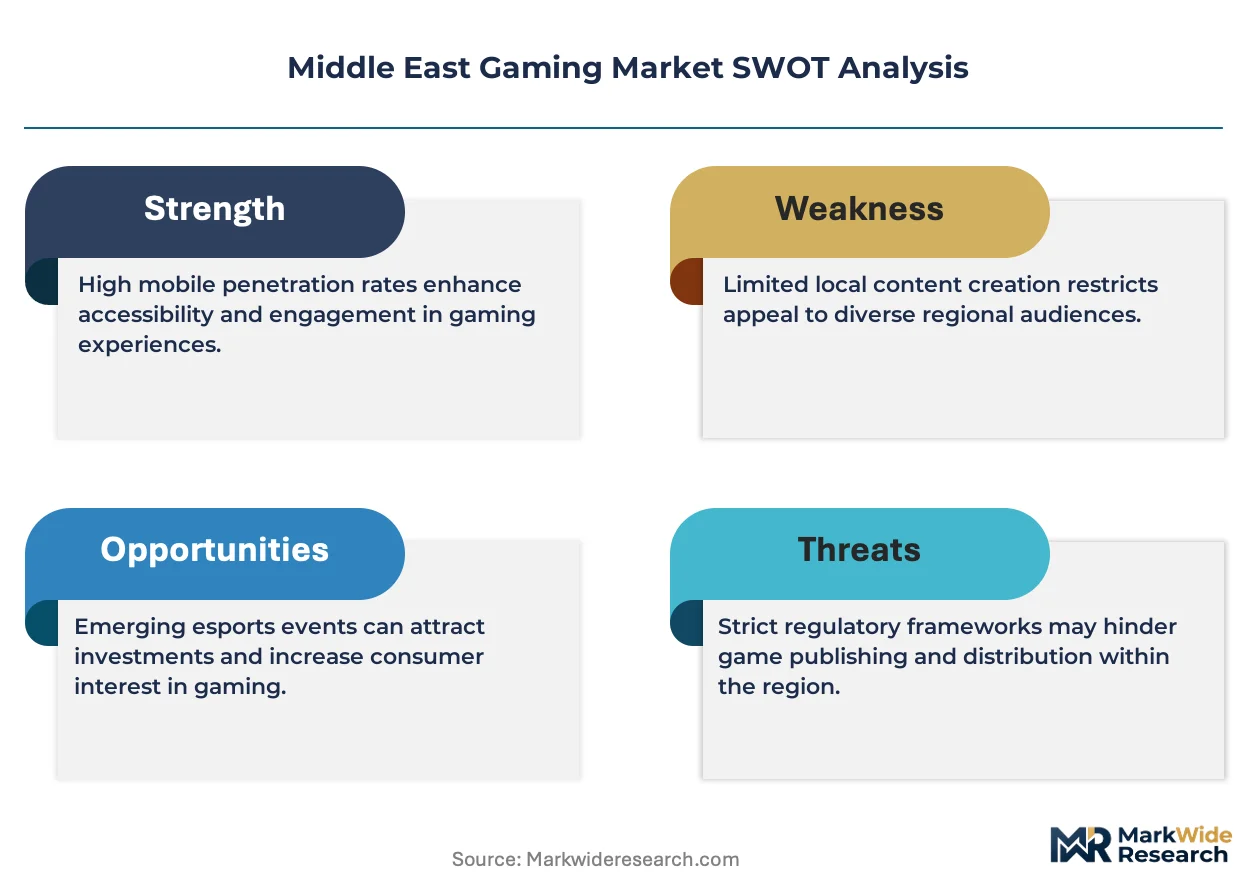
Sovereign wealth deployment into esports infrastructure and domestic game development studios is compressing the traditional publisher-developer hierarchy across Gulf Cooperation Council markets. This capital injection from national investment vehicles is forcing foreign publishers to localize faster and partner deeper than in other emerging regions.
Growth Catalysts
- Vision 2030 Esports Infrastructure:Saudi Arabia's sovereign-backed stadium construction and tournament hosting capacity is creating captive demand for competitive gaming content and professional league structures.
- Prepaid Data Affordability:Mobile network operators across the Gulf have compressed entry costs for mass-market smartphone users, expanding the addressable base beyond credit-card-holding consumers.
- NESA Cybersecurity Standards:The UAE's data residency and classification framework is accelerating compliant server deployment, reducing latency for real-time multiplayer experiences in Dubai and Abu Dhabi clusters.
Market Restraints
- Content Localization Timelines:Saudi Arabia's General Authority for Media Regulation and Egypt's Supreme Council for Media Regulation impose sequential approval processes that extend product launch windows by quarters.
- Arid Geography Broadband Gaps:Uneven fiber penetration across dispersed desert populations forces reliance on 4G/5G infrastructure with higher per-gigabyte delivery costs than fiber-dependent markets.
- Religious and Political Screening:Multi-layer content review for religious sensitivity and political neutrality creates compliance friction absent in secular entertainment markets.
Strategic Opportunities
- Immersive Entertainment Venues:Saudi-funded VR arcades and mixed-reality experience centers are creating location-based demand distinct from home hardware cycles.
- Arabic-Language Content Gaps:Narrative-driven genres remain underlocalized relative to action and sports titles, creating white space for culturally native storytelling.
- Domestic Studio Incubation:National gaming investment funds are offering preferential licensing and infrastructure support to studios establishing regional headquarters in Riyadh or Dubai.
Industry Challenges
- Game Development Talent Scarcity:Technical art, engine programming, and live operations expertise remain concentrated in established hubs, requiring expatriate recruitment or remote team structures.
- Live Service Operational Complexity:Persistent content pipelines for games-as-a-service models demand 24/7 community management across time zones with limited regional workforce depth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Gaming Market |
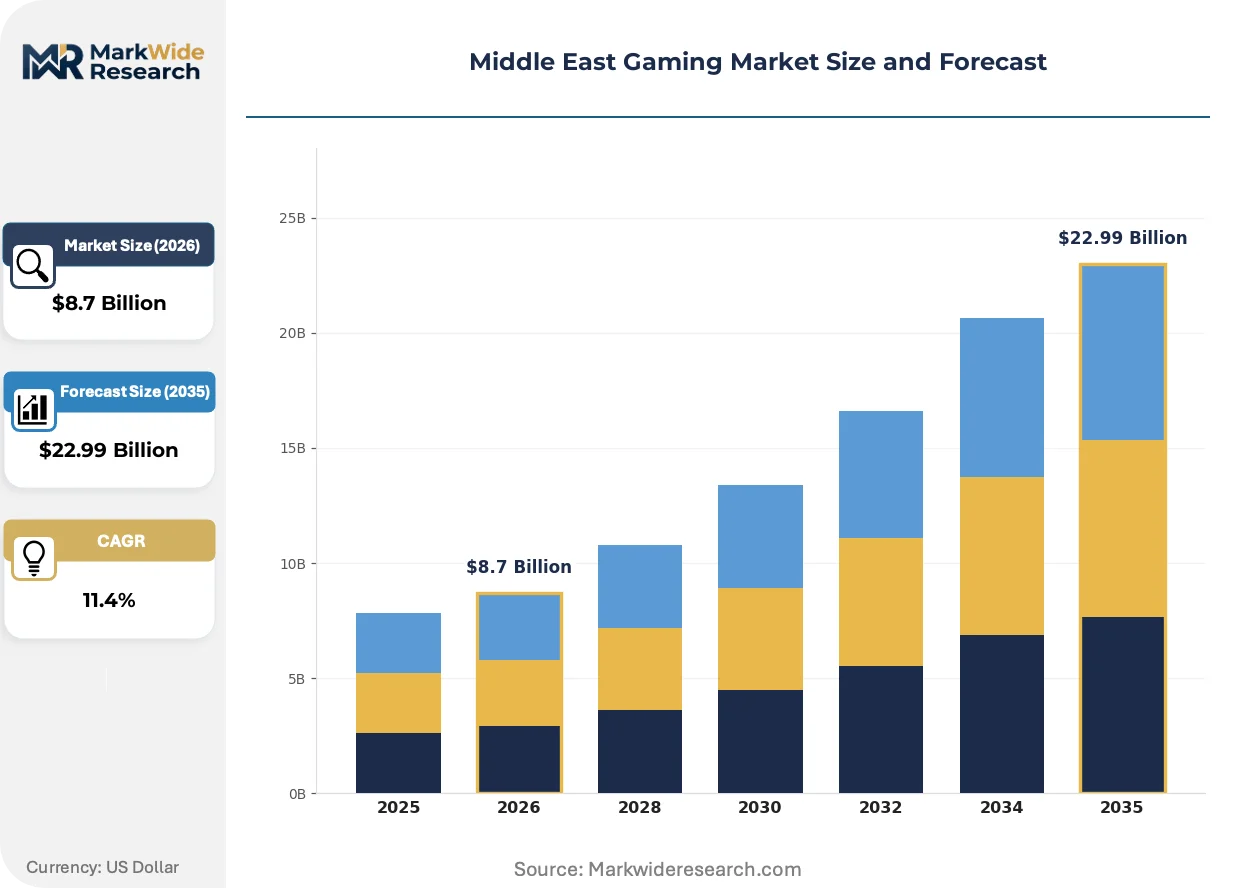
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Mobile Games, PC Games, Console Games, VR Games Monetization Model: Free-to-Play, Subscription, Pay-to-Play, In-App Purchases Player Demographics: Casual Gamers, Professional Gamers, Kids, Adults Distribution Channel: Online Platforms, Retail Stores, Digital Downloads, Subscription Services |
| Companies Covered | Krafton, Perfect World Co. Ltd., Tencent Holdings Ltd., 37 Interactive Entertainment, Garena, NetEase Inc., Shanghai miHoYo Network Technology Co. Ltd., Games24x7, Tamatem Games, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Gaming Market Strategic Shifts
Cloud gaming infrastructure is compressing hardware ownership cycles across Middle East markets, enabling high-fidelity experiences on entry-level devices. This shift is redrawing competitive boundaries between platform operators and traditional console manufacturers.
Cloud-native game streaming is fragmenting the historical console-PC-mobile hierarchy by decoupling rendering performance from local hardware investment. Young adult professionals in Riyadh and Dubai are adopting subscription-based access faster than ownership models, compressing upgrade cycles from years to months. This technology is fragmenting publisher revenue concentration by enabling smaller studios to reach premium-quality audiences without distribution gatekeepers.
Saudi Arabia's General Authority for Media Regulation is tightening age classification and content descriptor requirements for all distributed titles. Foreign publishers must now submit expanded documentation on violence, gambling mechanics, and social interaction features before commercial release. Esports tournament organizers and mobile free-to-play operators face the steepest compliance burden as real-time content moderation becomes a licensing condition.
Consumption patterns are rotating from casual mobile sessions toward dedicated competitive play blocks as Gulf consumers professionalize their gaming engagement. Evening and weekend tournament participation is displacing fragmented commute-time play among the young professional demographic. This behavioral shift is most visible in Saudi Arabia where Vision 2030 marketing has normalized gaming as a spectator and participant activity rather than a stigmatized pastime.
Middle East Gaming Market Segmentation
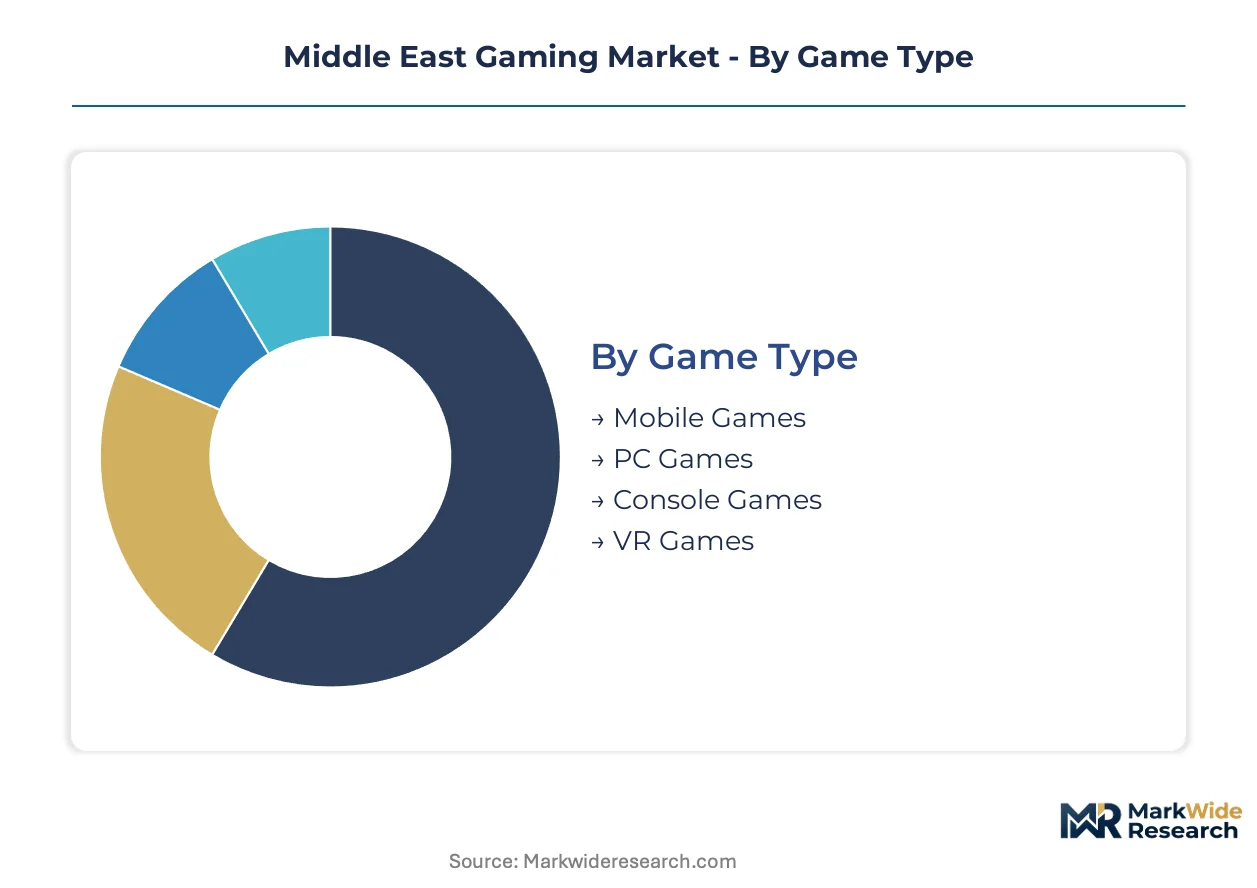
Segmentation in the Middle East Gaming Market reveals how infrastructure constraints and regulatory fragmentation create distinct commercial corridors. Each category maps to specific deployment challenges—from prepaid data economics shaping platform choices to content approval timelines dictating go-to-market sequencing.
Game Type:
Saudi Arabia and UAE infrastructure investments favor domestically hosted segments, while export-led categories depend on international server networks and face higher latency penalties.
- Mobile Games:Touch-optimized titles running on iOS and Android architectures dominate session volume through prepaid data affordability. Demand concentrates in Saudi Arabia's mass-market smartphone base where Vision 2030 marketing has normalized daily mobile engagement.
- VR Games:Immersive experiences requiring head-mounted displays and spatial tracking sensors are expanding most quickly through Saudi-funded location-based entertainment venues. Momentum sits with Riyadh and Dubai mixed-reality arcades where hardware costs are externalized from consumer purchase decisions.
- PC Games:Keyboard-and-mouse titles with mod support and competitive precision requirements serve esports professionals and dedicated hobbyists.
- Console Games:PlayStation and Xbox platform exclusives with physical media options appeal to collectors and premium households in Gulf urban centers.
Mobile Games holds the largest share; momentum sits with VR Games.
Monetization Model:
Cost tier stratification separates mass-market access models from premium commitment structures, with compliance burdens varying sharply across revenue mechanics.
- Free-to-Play:Zero-entry-cost titles monetizing through advertising impressions and optional cosmetic purchases capture volume across prepaid data users. Egypt's price-sensitive smartphone base and Saudi Arabia's young professional segment both gravitate toward this low-friction entry point.
- In-App Purchases:Microtransactions for progression acceleration and exclusive digital goods are climbing the fastest as Gulf consumers demonstrate higher willingness-to-pay than comparable emerging markets. UAE and Saudi Arabia banking integration enables seamless one-tap purchasing.
- Subscription:Recurring monthly fees for catalog access require credit card penetration that remains uneven outside Gulf Cooperation Council urban centers.
- Pay-to-Play:Upfront purchase requirements for complete content access persist among narrative-driven genres and premium console releases.
Free-to-Play dominates volume contribution; In-App Purchases delivers steepest expansion trajectory.
Player Demographics:
Application maturity separates established casual engagement from emerging professional infrastructure, with talent pipeline investments reshaping category boundaries.
- Casual Gamers:Fragmented-session players seeking low-commitment entertainment during commutes or breaks represent the established base. Saudi Arabia's stigma reduction campaigns and UAE marketing have normalized this behavior across age cohorts.
- Professional Gamers:Tournament-competing, streaming, or coaching individuals with structured training regimens are gaining share fastest through sovereign-funded esports infrastructure. Riyadh's stadium construction and league franchising create direct employment pathways.
- Kids:Age-gated users requiring parental consent mechanisms and content filtering drive compliance complexity for publishers targeting family segments.
- Adults:Time-constrained players with disposable income represent the premium monetization target for progression-acceleration features.
Casual Gamers retains volume leadership; Professional Gamers shows strongest momentum.
Distribution Channel:
Supply concentration in platform operator hands creates margin pressure for publishers, with digital infrastructure quality determining regional competitiveness.
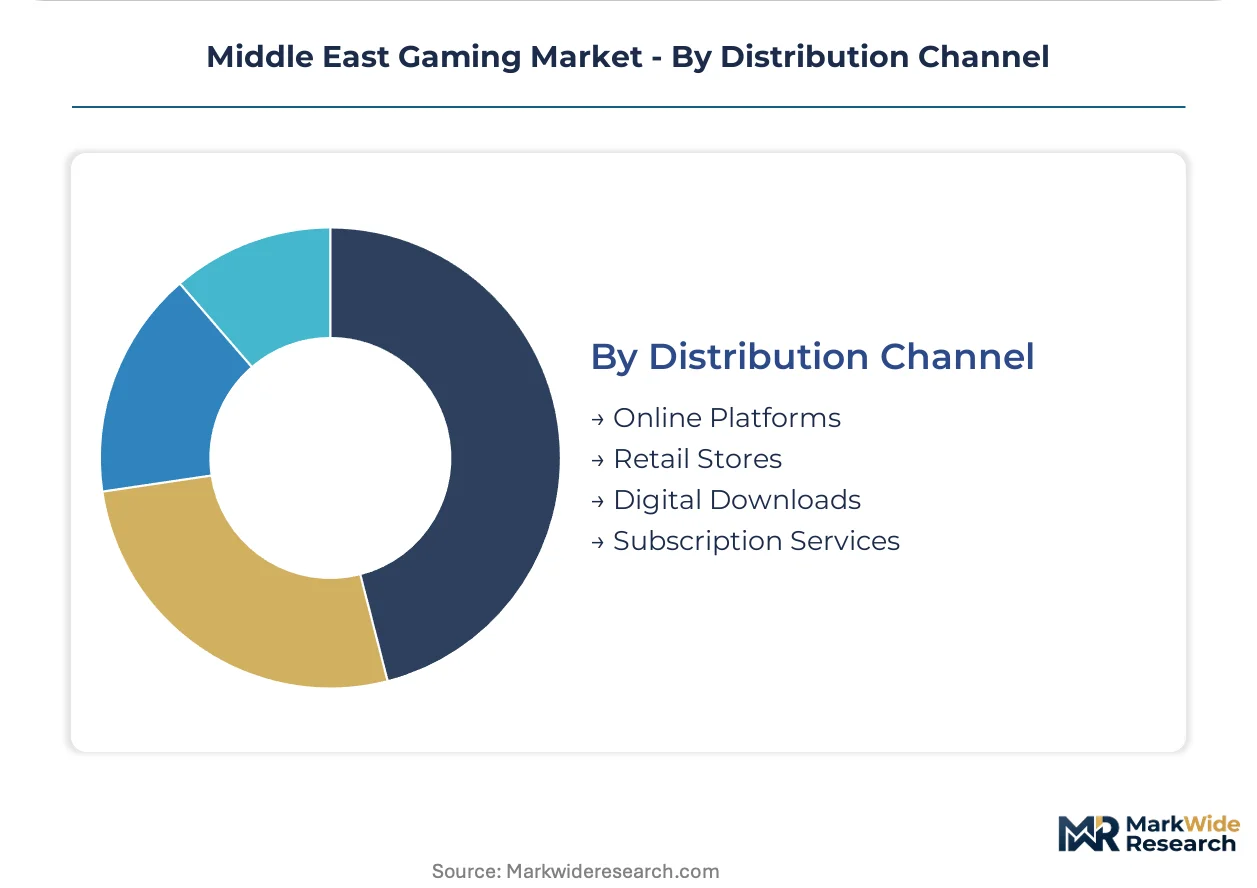
- Digital Downloads:Direct-to-device delivery via App Store, Google Play, Steam, and console marketplaces bypasses physical logistics entirely. UAE and Saudi Arabia fiber and 5G penetration support this channel's dominance in Gulf urban corridors.
- Subscription Services:Xbox Game Pass, PlayStation Plus, and emerging regional platforms offer catalog access with rotating content libraries. Saudi Arabia's domestic investment funds are incubating local equivalents to capture this recurring revenue stream.
- Online Platforms:Browser-based and cloud-streaming access methods reduce hardware requirements but depend on consistent low-latency connectivity unevenly available across desert geographies.
- Retail Stores:Physical boxed software and hardware bundles persist in mall-centric Gulf shopping cultures and collector communities.
Digital Downloads commands current share; Subscription Services exhibits fastest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's 5G backbone and fiber trunk lines connecting Riyadh to Gulf Cooperation Council neighbors anchor the region's low-latency gaming infrastructure. Cross-border data corridors through UAE exchange points reduce multiplayer latency for titles hosted in Dubai clusters.
Saudi Arabia
Vision 2030 sovereign wealth deployment into esports stadiums and domestic studio incubation is compressing foreign publisher entry timelines. The General Authority for Media Regulation enforces sequential content classification extending product launch windows. NEOM and Riyadh host the densest concentration of immersive entertainment venues and professional league infrastructure.
United Arab Emirates
Dubai's young professional demographic demonstrates the Gulf's highest willingness-to-pay for progression-accelerating microtransactions. NESA cybersecurity standards mandate data residency and real-time content moderation as licensing conditions. Abu Dhabi and Dubai clusters concentrate compliant server deployment and tournament organizer headquarters.
Egypt
Prepaid data affordability across Cairo and Alexandria expands the mass-market smartphone base beyond credit-card penetration limits. The Supreme Council for Media Regulation imposes additional religious and political content screening layers for North African market access. Giza and New Cairo host emerging mobile game development studios serving Arabic-language content gaps.
Qatar
State-backed digital infrastructure investments position Doha as a secondary tournament hosting hub complementing Saudi capacity. National media regulators align classification requirements with Gulf Cooperation Council standards to accelerate cross-border title approvals. Lusail and Education City clusters concentrate esports training facilities and regional publisher satellite offices.
Kuwait
High disposable income concentrations among young professionals drive premium console and PC hardware adoption rates exceeding regional averages. The national communications authority enforces content filtering requirements that extend localization timelines for foreign publishers. Kuwait City hosts the primary concentration of gaming retail and digital distribution platform marketing operations.
Middle East Gaming Market Competitive Environment
Listed Asian technology conglomerates compete with private regional specialists across platform access and content localization dimensions. Market structure tilts toward consolidated platform operators with minority portfolio stakes in domestic publishers, forcing independent studios toward deeper cultural adaptation partnerships. Three archetypes dominate: battle royale specialists leveraging competitive gaming expertise, platform conglomerates sustaining ecosystem control through distribution infrastructure, and culturally native publishers occupying Arabic-language narrative gaps. Dominant competitive moves include strategic partnerships with sovereign wealth-funded domestic studios and accelerated server deployment to satisfy data residency requirements.
Within the culturally native publisher tier, Tamatem Games occupies a distinct position between global franchises and Arabic content localization demands. Among Asian-listed conglomerates, Tencent Holdings Ltd. and NetEase Inc. exemplify platform operators sustaining market presence through international distribution expansion and minority regional stakes. Krafton represents the battle royale specialist archetype, anchoring competitive community formation through genre expertise transferred from established Asian markets.
| Leading Market Players |
|---|
| Krafton |
| Perfect World Co. Ltd. |
| Tencent Holdings Ltd. |
| 37 Interactive Entertainment |
| Garena |
| NetEase Inc. |
| Shanghai miHoYo Network Technology Co. Ltd. |
| Games24x7 |
| Tamatem Games |
| Others |
Value Chain & Pricing Dynamics
Take-or-pay server capacity agreements between Gulf telecom operators and cloud gaming platforms lock in both low-latency infrastructure access and predictable per-gigabyte pricing for publishers targeting Saudi Arabia and UAE clusters. These multi-year arrangements insulate foreign operators from spot-market bandwidth volatility while committing them to minimum revenue thresholds regardless of subscriber uptake.
Pricing Analysis
Volume-discount tiering structures separate mass-market free-to-play publishers from premium live-service operators based on concurrent user commitments. Three-tier pricing structure across premium, standard, and economy levels reflects compliance burden differentiation, with NESA-certified data residency commanding surcharge premiums. Cost compression in the standard tier is intensifying because prepaid data economics force advertising-revenue dependence. Casual mobile players in Egypt demonstrate highest price sensitivity, while young professionals in Dubai show lowest sensitivity to progression-accelerating microtransaction pricing.
Supply Chain Analysis
South Korea and China anchor graphics processing unit and game engine middleware supply for Middle East publishers localizing high-fidelity titles. Taiwan feeds from advanced semiconductor foundries producing mobile chipsets powering Saudi Arabia's smartphone-dominant user base. Single-source vulnerability in Unity and Unreal Engine licensing creates concentration risk for domestic studios building on these platforms. Distribution runs through platform operator gatekeepers—Apple's App Store, Google Play, and regional cloud streaming services—extracting revenue share percentages that shape publisher margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud gaming infrastructure is compressing hardware ownership cycles and fragmenting platform economics, as subscription-based access models decouple rendering performance from local device investment and redraw competitive boundaries between ecosystem operators.
For Market Incumbents: Fortify data residency compliance capabilities ahead of NESA and General Authority for Media Regulation enforcement expansion, locking in first-mover server deployment advantages in Riyadh and Dubai clusters. Deepen backward integration into Arabic localization pipelines to reduce reliance on third-party cultural adaptation vendors facing approval timeline compression. Sovereign wealth-funded domestic studios represent the primary competitive threat requiring partnership or preemption.
For New Entrants and Emerging Players: Anchor in narrative-driven genres underserved by current battle royale and sports title saturation, particularly story-rich mobile RPGs addressing Arabic-language content gaps. Saudi Arabia's immersive entertainment venue buildout offers the most penetrable geography for location-based VR experiences externalizing hardware costs from consumers. Pursue co-development partnerships with Tamatem Games or equivalent culturally native publishers to accelerate regulatory approval velocity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among live-service operators with persistent content pipelines and established Gulf consumer payment integration. Long-term viability hinges on regulatory relationship depth and sovereign wealth co-investment alignment rather than short-term download metrics. Studios with demonstrated General Authority for Media Regulation pre-approval track records signal defensible competitive positioning through the projection horizon.
| Strategic Initiative | Industry Significance |
|---|---|
| Data Residency Certification | NESA-compliant server deployment in Dubai clusters reduces multiplayer latency penalties for UAE consumers. |
| Arabic Localization Pipeline | In-house cultural adaptation teams compress General Authority for Media Regulation approval timelines by quarters. |
| Sovereign Wealth Partnership | Joint ventures with Saudi gaming investment funds unlock preferential licensing and stadium infrastructure access. |
| Cloud Platform Integration | Native integration with WeGame and regional streaming services expands addressable base beyond hardware owners. |
| Esports League Franchising | Professional tournament structure participation captures Vision 2030 marketing expenditure and spectator monetization. |
Study Parameters
A standing panel of game development executives, regulatory affairs leads at regional publishers, esports tournament organizers, and cloud infrastructure procurement officers provided ongoing calibration across primary fieldwork. Secondary validation drew from General Authority for Media Regulation filing disclosures, NESA compliance documentation, SEC filings of listed Asian technology conglomerates, and hyperscaler capex announcements for Middle East data center buildouts. Bottom-up sizing of studio revenue and top-down triangulation against sovereign wealth investment disclosures anchored value estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled monetization model, platform type, player demographic, and compliance tier segmentation dimensions. CAGRs were derived from fitted growth curves incorporating prepaid data affordability trajectories, fiber penetration buildout schedules, and content approval velocity assumptions. Forecast inputs included Vision 2030 infrastructure commitment schedules and young professional disposable income projections.
Underlying assumptions cover regulatory enforcement continuity and sovereign wealth funding persistence, with deviation risk concentrated in content classification timeline extensions or geopolitical compression of cross-border data corridor availability. Recalibration cycles align with material shifts in NESA standard revisions, General Authority for Media Regulation directive updates, and sovereign wealth vehicle priority reallocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Stock Video Market
Digital Media
VFX Market
Digital Media
North America Photographic Services Market
Digital Media
Sound Effects Services Market
Digital Media
Entertainment Market
Digital Media
In Flight Entertainment Market
Digital Media
Mexico Webtoons Market
Digital Media
United States Online Gambling Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Digital Video Advertising Market
Digital Media
Global ACGN Market
Digital Media
Online Movie Market
Digital Media
Global Digital Painting Market
Digital Media
3D Anaglyph Glasses Market
Digital Media
Digital Content Locker Market
Digital Media
Digital Content Creator Market