
 Anime Merchandising Market | 2026-2036
Anime Merchandising Market Size, Share, and Industry Trends Forecast 2026-2036
Anime Merchandising Market Analytics
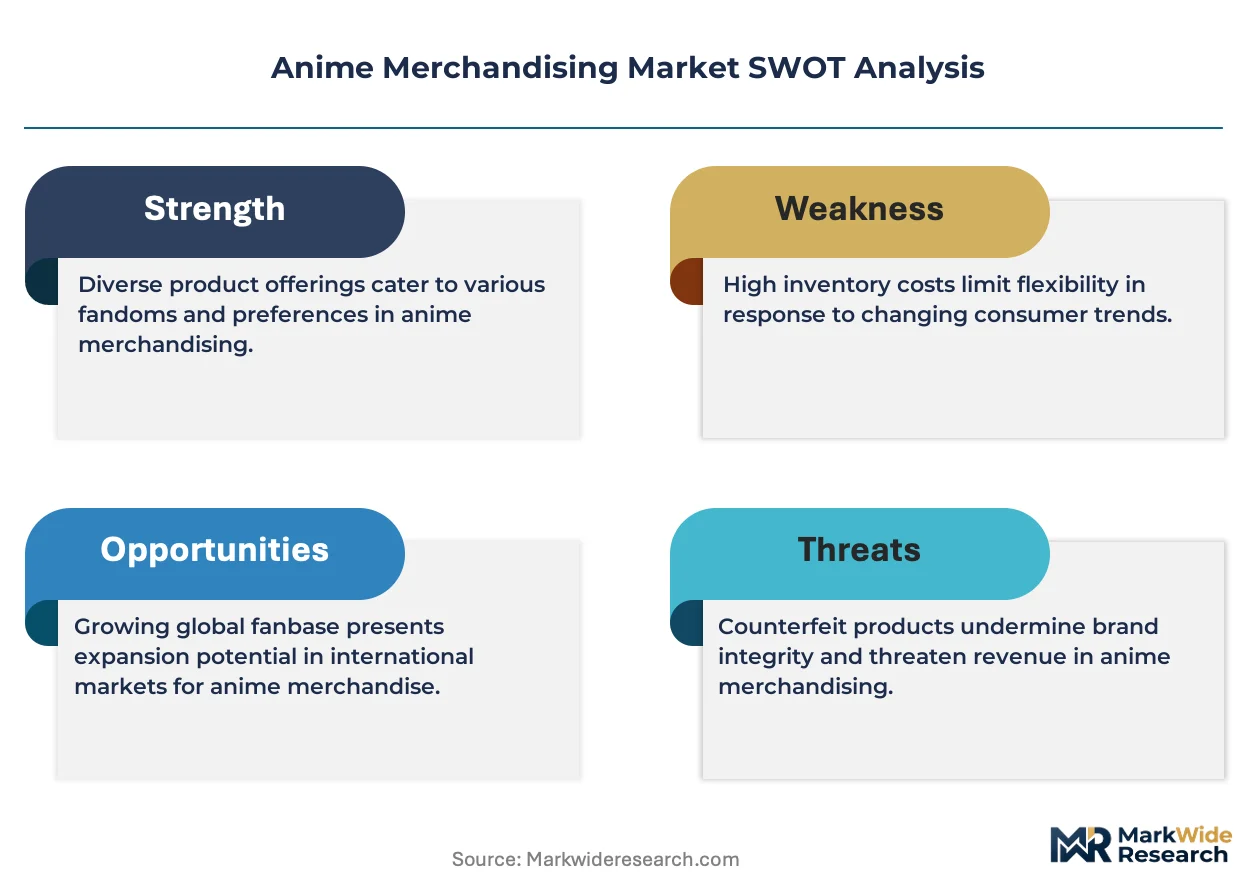
Biodegradable packaging substrates are restructuring cost structures across figure and collectible lines. Bandai Namco Holdings leverages captive manufacturing in Japan to sustain margin control on premium resin kits. Good Smile Company anchors its competitive edge through direct-to-fan digital pre-order channels. Kotobukiya specializes in limited-edition sculptor collaborations that differentiate its catalog from mass-market alternatives.
Anime merchandising encompasses the commercial production and distribution of licensed physical goods derived from Japanese animation intellectual property, spanning PVC-cast figures, screen-printed apparel, acrylic standees, and die-cast accessories manufactured through injection molding, rotocasting, and sublimation processes. The primary commercial purpose centers on monetizing fan engagement through tangible ownership of character-linked artifacts that extend narrative immersion beyond screen-based consumption. Figures and collectibles command the dominant margin pool due to collector-grade finishing and scarcity-driven pricing, while online retail channels capture the fastest-growing transaction volume through platform-native community features. Apparel and accessories remain structurally mature segments where volume scales through fast-fashion partnerships rather than artisan production.
Japans METI oversees content export promotion frameworks, while the US CBP enforces customs valuation and copyright border enforcement on imported goods; Chinas NMPA and SAMR jointly regulate cross-border e-commerce licensing and product safety labeling for anime-derived merchandise entering domestic markets. These regulatory layers shape demand by determining release velocity, import cost structures, and platform eligibility for foreign sellers. Stakeholders must monitor evolving content review timelines and tariff classifications as primary determinants of regional market access and inventory planning cycles.
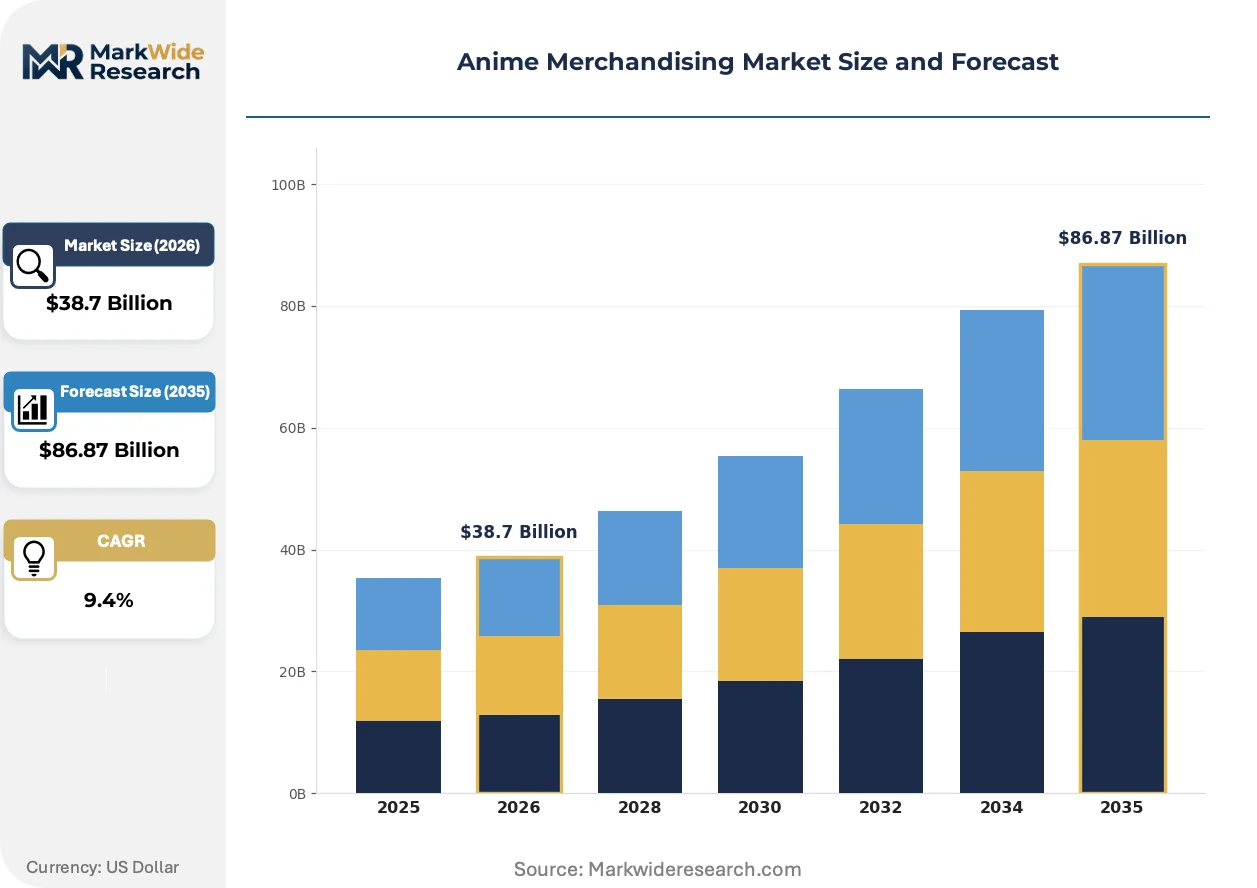
Market Dynamics
China's NMPA content review timelines have become the dominant pacing mechanism for global anime merchandise release schedules, compressing product launch windows and forcing manufacturers to pre-position inventory months ahead of domestic approval signals.
Growth Catalysts
- Direct-to-fan pre-order platforms:Digital-first sales channels bypass traditional wholesale markups and capture full margin on limited-production resin kits.
- Japan's METI export promotion frameworks:Government-backed content licensing accelerators reduce bureaucratic friction for Japanese IP holders entering Southeast Asian markets.
- Biodegradable packaging substrates:EU Green Deal-aligned material transitions open preferential shelf placement in European retail channels.
Market Restraints
- Petroleum-derived resin price volatility:PVC and ABS pellet costs fluctuate with crude oil benchmarks, squeezing margin on mass-market figure lines.
- Guangdong Province mold-making concentration:Over 70 percent of global PVC figure tooling originates from a single Chinese manufacturing cluster, creating single-point-of-failure risk.
- China SAMR cross-border e-commerce licensing:Extended product safety labeling reviews delay market entry by 4-8 months for imported collectibles.
Strategic Opportunities
- Indonesia and Vietnam fan convention circuits:Emerging buyer pools in Jakarta and Ho Chi Minh City lack established domestic distribution, creating first-mover whitespace.
- AI-assisted sculpting workflows:Machine learning tools accelerate prototype iteration, collapsing traditional 18-month figure development cycles.
- EU CSRD supply chain disclosure mandates:Early compliance with carbon footprint reporting requirements secures preferred supplier status with European retail anchors.
Industry Challenges
- Master sculptor talent scarcity:Hand-finishing expertise for premium collectible-grade prototypes concentrates among aging practitioners in Tokyo and Osaka.
- Multi-territory licensing synchronization:Coordinating simultaneous release windows across Japan, China, North America, and Europe requires complex rights-holder negotiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anime Merchandising Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Figures, Apparel, Collectibles, Accessories Distribution Channel: Online Retail, Physical Stores, Events, Wholesale Customer Type: Fans, Collectors, Retailers, Casual Buyers Price Tier: Premium, Mid-Range, Budget, Limited Edition |
| Companies Covered | Aniplex, Animate, Bandai Namco Holdings, Max Factory, Toei Animation, Good Smile Company, Kotobukiya, TMS Entertainment, Studio Ghibli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anime Merchandising Market Evolving Landscape
Digital fabrication and sustainable materials are converging to compress production timelines while redefining collector expectations around provenance and environmental accountability.
Photopolymer resin 3D printing is rewriting how limited-run garage kits reach collectors. Independent sculptors in Tokyo's Akihabara district now bypass traditional mold-making entirely, printing master prototypes directly for rotocasting production. This workflow collapses minimum viable order quantities from thousands to hundreds, enabling viable business models for niche character licenses.
EU REACH chemical safety registrations are forcing reformulation of traditional PVC plasticizers. Manufacturers serving European markets must substitute orthophthalate-based softeners with bio-based alternatives, adding 12-18 months to material qualification timelines. Premium figure lines targeting German and French collectors absorb these costs through pricing stratification.
Collector purchasing has migrated from impulse retail to community-validated pre-commitment models. Fan-operated Discord servers and WeChat groups now aggregate demand signals months before official announcements, shifting power toward organized buyer cohorts. This pattern is most pronounced in Shanghai and Seoul, where group-buy coordinators negotiate directly with Japanese distributors for allocation priority.
Anime Merchandising Market Segmentation
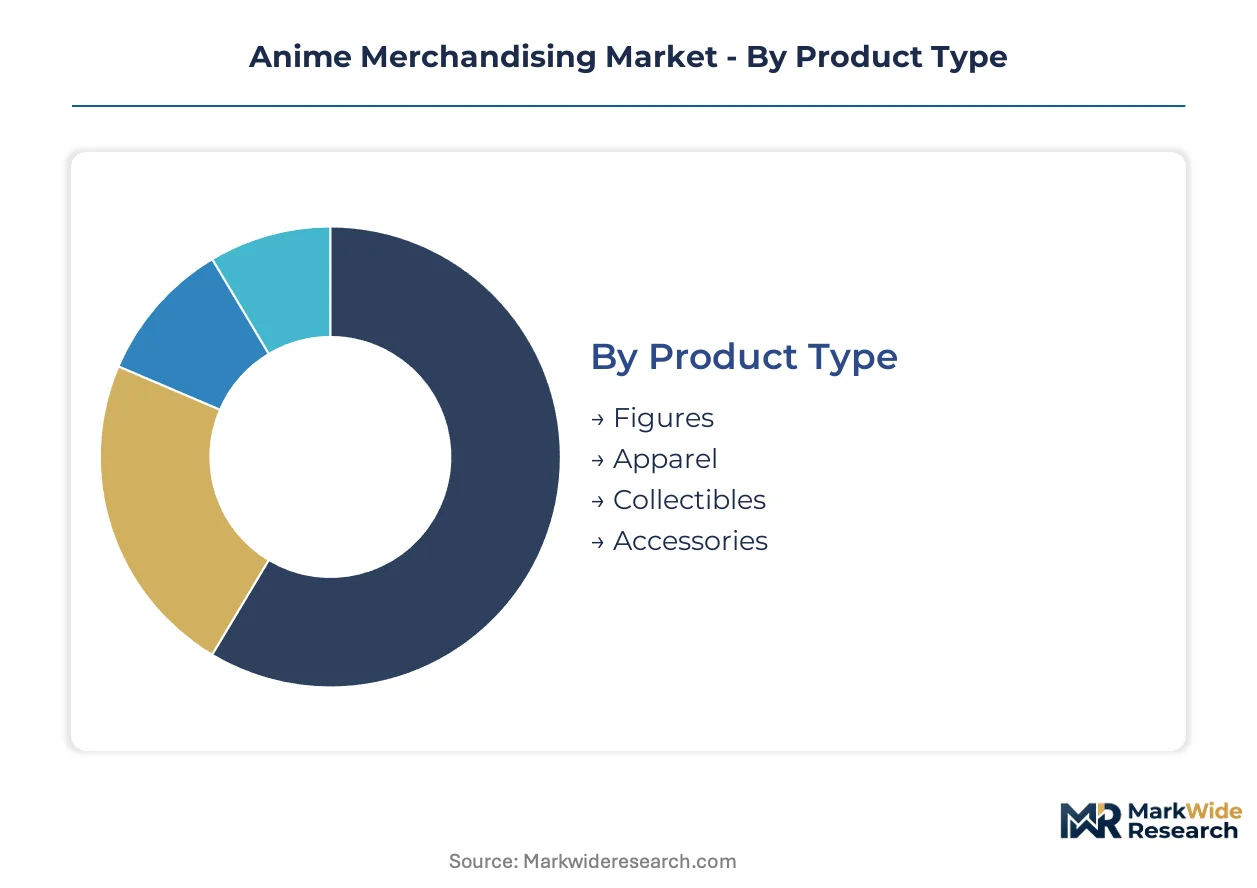
Segmentation in anime merchandising determines margin capture and inventory risk. Product complexity varies dramatically across categories, from hand-finished resin prototypes to screen-printed cotton basics. Distribution channel selection dictates release velocity and community engagement depth.
Product Type:
Integration depth separates standalone display pieces from wearable or utilitarian goods that embed into daily routines.
- Figures:PVC-cast and resin-sculpted three-dimensional character representations requiring injection molding or rotocasting production. Demand concentrates among Japanese otaku collectors and Shanghai-based high-net-worth buyers, driven by scarcity-driven pre-order allocation systems and master sculptor reputation premiums.
- Apparel:Screen-printed or sublimated cotton and polyester garments featuring character artwork and franchise branding. Fast-fashion partnerships in Seoul and Jakarta drive volume scaling, though margin compression from licensed royalty structures limits profitability compared to collectible tiers.
- Collectibles:Trading cards, acrylic standees, and die-cast accessories manufactured through precision stamping and laser cutting. Japanese convenience store exclusive releases and Chinese blind-box mechanics sustain impulse purchase frequency among casual franchise followers.
- Accessories:Bags, jewelry, and phone cases integrating character motifs into functional everyday objects. Korean beauty crossover collaborations and Southeast Asian convention circuits represent emerging demand concentrations for this segment.
Figures lead volumes today; collectibles are gaining share fastest through mobile game tie-in mechanics and gacha-based distribution models.
Distribution Channel:
Cost tier alignment determines which channels absorb wholesale markups versus capturing full manufacturer margin.
- Online Retail:Platform-native storefronts and direct-to-fan pre-order systems operating through domestic e-commerce aggregators and brand-owned websites. Bandai Namco and Good Smile Company anchor competitive positioning through proprietary digital channels that bypass traditional distributor networks.
- Physical Stores:Dedicated anime specialty retailers, hobby shop chains, and department store concessions with high-touch merchandising. Tokyo's Akihabara district and Osaka's Nipponbashi remain global pilgrimage destinations where tactile inspection drives premium conversion rates.
- Events:Convention-exclusive releases, pop-up installations, and fan exhibition limited drops creating artificial scarcity through temporal and geographic restriction. Comiket in Tokyo and Anime Expo in Los Angeles generate concentrated revenue spikes tied to seasonal product calendars.
- Wholesale:Traditional distributor networks supplying mass-market retail anchors and international import specialists. China's SAMR cross-border licensing delays and US CBP customs valuation enforcement create margin erosion through extended inventory holding periods.
Online retail leads volumes today; events are climbing the fastest as convention circuits expand across Southeast Asia.
Customer Type:
Application intensity varies from narrative immersion seekers to commercial intermediaries extracting resale value.
- Fans:Franchise-committed purchasers driven by character attachment and community participation. Japanese and South Korean fan club membership systems provide early access allocation priority and exclusive variant offerings.
- Collectors:Investment-oriented buyers prioritizing condition grading, provenance documentation, and secondary market liquidity. Hong Kong and Singapore auction houses now hold dedicated anime collectible sessions reflecting asset-class recognition.
- Retailers:Commercial intermediaries sourcing inventory for downstream resale through physical or digital storefronts. Guangdong Province-based trading companies dominate cross-border procurement for Southeast Asian market penetration.
- Casual Buyers:Impulse purchasers with low franchise attachment responding to visual design or gift-giving occasions. Convenience store distribution in Taiwan and Thailand captures this transient demand through low-commitment price points.
Fans lead volumes today; collectors are expanding most quickly as grading services and fractional ownership platforms mature.
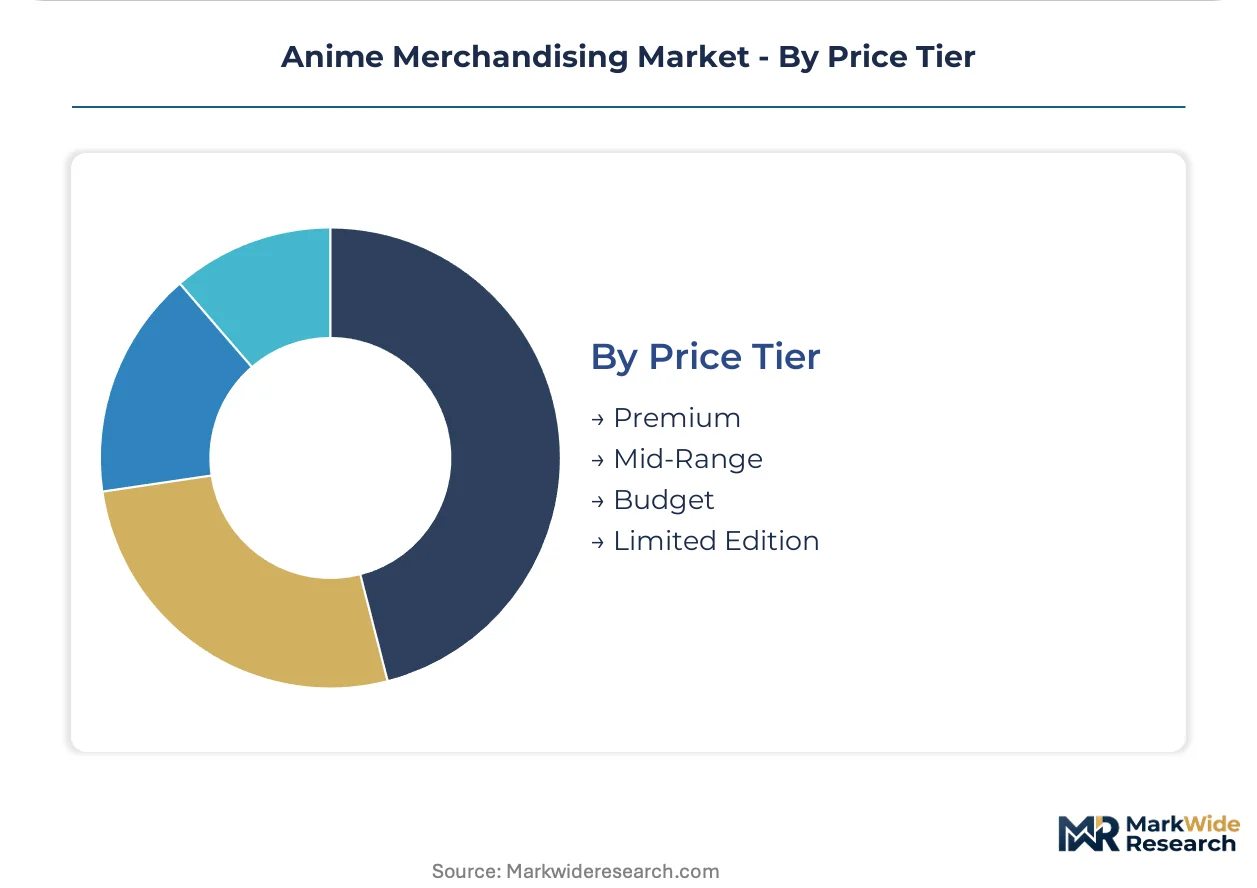
Price Tier:
Supply concentration determines which tiers absorb material cost volatility versus passing through to captive demand.
- Premium:Hand-finished resin kits and limited sculptor collaborations priced at multiples of mass-market alternatives. Aging master sculptor talent scarcity in Tokyo and Osaka constrains production scalability regardless of demand signals.
- Mid-Range:Factory-produced PVC figures with standardized paint applications and moderate edition sizes. Petroleum-derived resin price volatility directly squeezes margin on this tier, forcing manufacturers toward volume commitments with Guangdong mold-makers.
- Budget:High-volume injection-molded goods with simplified articulation and basic packaging. Fast-fashion partnerships and mass-market retail placement in Indonesia and Vietnam drive scale economics through minimized unit costs.
- Limited Edition:Numerically restricted releases with certificates of authenticity and event-exclusive distribution windows. AI-assisted sculpting workflows are collapsing traditional 18-month development cycles, enabling more frequent limited drops without prototype bottlenecks.
Premium leads volumes today; limited edition is gaining share fastest through digital fabrication and compressed production timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Akihabara district anchors global anime merchandising production and collector pilgrimage traffic. Japan's METI export promotion frameworks accelerate IP licensing velocity into Southeast Asian markets. China's NMPA content review timelines now dictate synchronized release windows across multiple territories.
Japan
Japanese otaku collectors drive premium figure demand through scarcity-driven pre-order allocation systems. METI oversees content export promotion frameworks that reduce bureaucratic friction for IP holders entering Southeast Asia. Master sculptor talent concentrates in Tokyo and Osaka, constraining hand-finished resin kit scalability regardless of demand signals.
China
Shanghai-based high-net-worth buyers command allocation priority for limited-edition sculptor collaborations through group-buy coordinators. The NMPA and SAMR jointly regulate cross-border e-commerce licensing and product safety labeling, extending import timelines by 4-8 months. Guangdong Province mold-making clusters produce over 70 percent of global PVC figure tooling, creating single-point-of-failure concentration risk.
United States
Anime Expo in Los Angeles generates concentrated revenue spikes tied to seasonal product calendars and convention-exclusive drops. The US CBP enforces customs valuation and copyright border enforcement on imported goods, shaping inventory planning cycles. California and Texas host the largest fan convention circuits outside Asia, anchoring North American demand aggregation.
South Korea
Seoul-based fan club membership systems provide early access allocation priority and exclusive variant offerings for domestic collectors. The MFDS regulates product safety standards for imported collectibles entering Korean markets. Korean beauty crossover collaborations represent emerging demand concentrations for accessories and wearable merchandise segments.
Indonesia
Jakarta's expanding fan convention circuits concentrate emerging buyer pools lacking established domestic distribution infrastructure. The country's national trade ministry oversees cross-border e-commerce licensing for imported anime-derived merchandise. Local trading companies dominate procurement from Guangdong manufacturers for Southeast Asian market penetration.
Anime Merchandising Market Competitive Landscape
Direct-to-fan digital pre-order platforms dominate the current landscape as manufacturers bypass traditional wholesale markups. The vendor base concentrates among integrated IP holders with captive manufacturing and specialized sculpting houses with master artisan networks. Three archetypes define competitive positioning: conglomerate entertainment groups with vertical manufacturing control, boutique sculptor-driven studios with limited-edition specialization, and platform-native distributors with community-validated demand aggregation. Portfolio diversification into biodegradable packaging substrates and AI-assisted sculpting workflows represent the dominant competitive moves reshaping margin structures.
Among Japan-based integrated entertainment groups, Bandai Namco Holdings exemplifies conglomerate-scale vertical manufacturing control with captive production facilities sustaining margin discipline on premium resin kits. Good Smile Company and Kotobukiya occupy distinct positions within the sculptor-driven tier, with the former anchoring competitive positioning through proprietary direct-to-fan digital channels and the latter specializing in limited-edition collaborations that differentiate catalog depth from mass-market alternatives.
| Leading Market Players |
|---|
| Aniplex |
| Animate |
| Bandai Namco Holdings |
| Max Factory |
| Toei Animation |
| Good Smile Company |
| Kotobukiya |
| TMS Entertainment |
| Studio Ghibli |
| Others |
Value Network & Pricing Analysis
Premium resin kit scarcity versus mass-market PVC commoditization creates a dual-track pricing architecture where hand-finished collector pieces command sculptor reputation premiums while petroleum-derived input volatility erodes standardized figure margins. This bifurcation maps directly onto supply chain configurations: captive Japanese manufacturing sustains pricing power for limited editions, while Guangdong mold-making concentration exposes mid-tier producers to cost pass-through pressures.
Pricing Analysis
Petroleum-derived resin cost pass-through dominates margin structures across factory-produced PVC tiers, with orthophthalate plasticizer substitution under EU REACH adding qualification premiums to European-bound shipments. Three-tier pricing structure across premium, standard, and economy levels separates master-sculptor limited editions from rotocast mid-range volumes and injection-molded budget lines. Pricing pressure stems from crude oil benchmark volatility squeezing mid-tier manufacturers locked into volume commitments with Guangdong mold-makers. Casual buyers in Southeast Asian convenience store channels exhibit highest price sensitivity, while Hong Kong and Singapore auction house collectors absorb premium tier increases without volume elasticity.
Supply Chain Analysis
Master sculptor talent scarcity in Tokyo and Osaka constrains hand-finishing capacity for premium collectible-grade prototypes, while Guangdong Province mold-making clusters generate over 70 percent of global PVC figure tooling. Raw material dependencies center on petroleum-derived PVC and ABS pellets, photopolymer resins for 3D-printed prototyping, and bio-based plasticizer alternatives for EU REACH compliance. Single-source vulnerability concentrates in Guangdong's tooling ecosystem, where geographic clustering creates disruption risk from regional logistics chokepoints or regulatory enforcement. Distribution runs through direct-to-fan digital pre-order platforms for premium tiers, traditional wholesale networks for mass-market retail, and convention-exclusive drops for limited editions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anime merchandising offers margin expansion through biodegradable packaging substrate transitions that unlock preferential European shelf placement and AI-assisted sculpting workflows that compress prototype development costs. Premium tier demand inelasticity supports pricing power capture.
For Market Incumbents: Anchor competitive positioning through backward integration into captive resin kit manufacturing and proprietary digital pre-order channels that bypass wholesale markups. METI export promotion frameworks accelerate Southeast Asian licensing velocity, while master sculptor talent scarcity in Tokyo threatens long-term premium tier scalability. Defend against emerging platform-native distributors by deepening direct-to-fan community engagement through Discord and WeChat group-buy coordination. For New Entrants and Emerging Players: EU Green Deal-aligned material transitions in European markets open a window for biodegradable packaging substrate specialists to secure preferred supplier status with retail anchors. Indonesia and Vietnam fan convention circuits represent whitespace with concentrated emerging buyer pools lacking established domestic distribution infrastructure. Enter through AI-assisted sculpting workflows that collapse traditional 18-month development cycles, enabling viable limited-run garage kit economics at minimum viable order quantities below traditional mold-making thresholds. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented sculptor-driven studios lack digital pre-order platform infrastructure and face margin compression from petroleum-derived resin volatility. Long-term viability favors integrated IP holders with captive manufacturing and proprietary community-validated demand aggregation. Target acquisition archetype: boutique studios with master artisan networks but underdeveloped direct-to-fan channels. Watch for inflection signals in China NMPA content review timeline compression or Guangdong mold-making cluster disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Transition | EU Green Deal compliance secures preferential shelf placement with German and French retail anchors. |
| AI-Assisted Sculpting Workflow Adoption | Machine learning tools collapse prototype iteration timelines from 18 months to viable limited-run economics. |
| Direct-to-Fan Platform Expansion | Proprietary digital pre-order channels bypass traditional wholesale markups and capture full manufacturer margin. |
| Southeast Asian Convention Circuit Entry | Jakarta and Ho Chi Minh City events concentrate emerging buyer pools lacking established domestic distribution. |
| Master Sculptor Talent Pipeline Development | Hand-finishing expertise concentration in aging Tokyo and Osaka practitioners threatens premium tier scalability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with Japanese figure manufacturers, Chinese cross-border e-commerce licensing specialists, Southeast Asian convention organizers, and European retail category buyers with secondary validation. Secondary sources included METI export promotion documentation, China NMPA content review procedural filings, EU REACH chemical safety registration databases, and customs valuation enforcement records from US CBP. Bottom-up demand aggregation across product tiers and top-down market sizing triangulated volume and value estimates.
Historical reference periods anchored projection modeling across the analysis window, with segmentation dimensions spanning product type complexity tiers, distribution channel cost structures, customer archetype application intensity, and regional regulatory framework clusters. CAGRs derived from regression analysis of pre-order allocation velocity, convention circuit expansion patterns, and cross-border e-commerce licensing timeline trajectories. Industry-specific inputs included petroleum-derived resin price benchmarks, master sculptor production capacity constraints, and digital fabrication adoption curves.
Revisions become necessary when China NMPA content review timelines extend beyond baseline assumptions, Guangdong mold-making clusters experience disruption, or EU REACH chemical safety registrations force unplanned material reformulation. Forecasts reflect documented assumptions regarding pre-order platform penetration rates and biodegradable packaging substrate cost curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Entertainment in the Home Market
Digital Media
Secondary Ticket Market
Digital Media
Digital Content Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Drone Wedding Photography Market
Digital Media
North America Webtoons Market
Digital Media
Global Digital Painting Market
Digital Media
Video Wall Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Digital Media Switchers Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Anime Streaming Tool Market
Digital Media
United Kingdom Webtoons Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Da Vinci Systems Market
Digital Media
3D Animation Market