
 Middle East Media and Entertainment Market | 2026-2036
Middle East Media and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Media and Entertainment Market Outlook
Content licensing clearance under SAMR's GB standards for imported media is rotating access for international distributors seeking entry. MBC Group leverages its vertically integrated production studios across Riyadh and Dubai to control Arabic-language drama pipelines. beIN Media Group anchors sports broadcasting rights across North Africa and the Gulf. Abu Dhabi Media competes through documentary and cultural programming aligned with federal cultural mandates.
Middle East media and entertainment encompasses audio-visual content creation, aggregation, and distribution across theatrical, broadcast, and digital channels, utilizing compression codecs, content delivery networks, and rights management encryption to deliver entertainment and information products to consumer and commercial audiences. Streaming services dominate growth as fiber broadband penetration and 5G rollout expand addressable audiences, while cable television sustains premium positioning through live sports exclusivity and bundled telecom packages. Theatrical releases are recovering as cinema infrastructure investment accelerates under national diversification plans, particularly in Saudi Arabia where screen counts multiply.
Saudi Arabia's General Authority for Audiovisual Media (GAMA) regulates content classification and licensing, while the UAE's National Media Council enforces decency standards and foreign ownership caps that shape joint-venture structures. Egypt's Supreme Council for Media Regulation imposes local content quotas affecting distribution economics. Stakeholders must monitor how shifting censorship boundaries interact with platform subscription fatigue and advertising budget migration to short-form video.
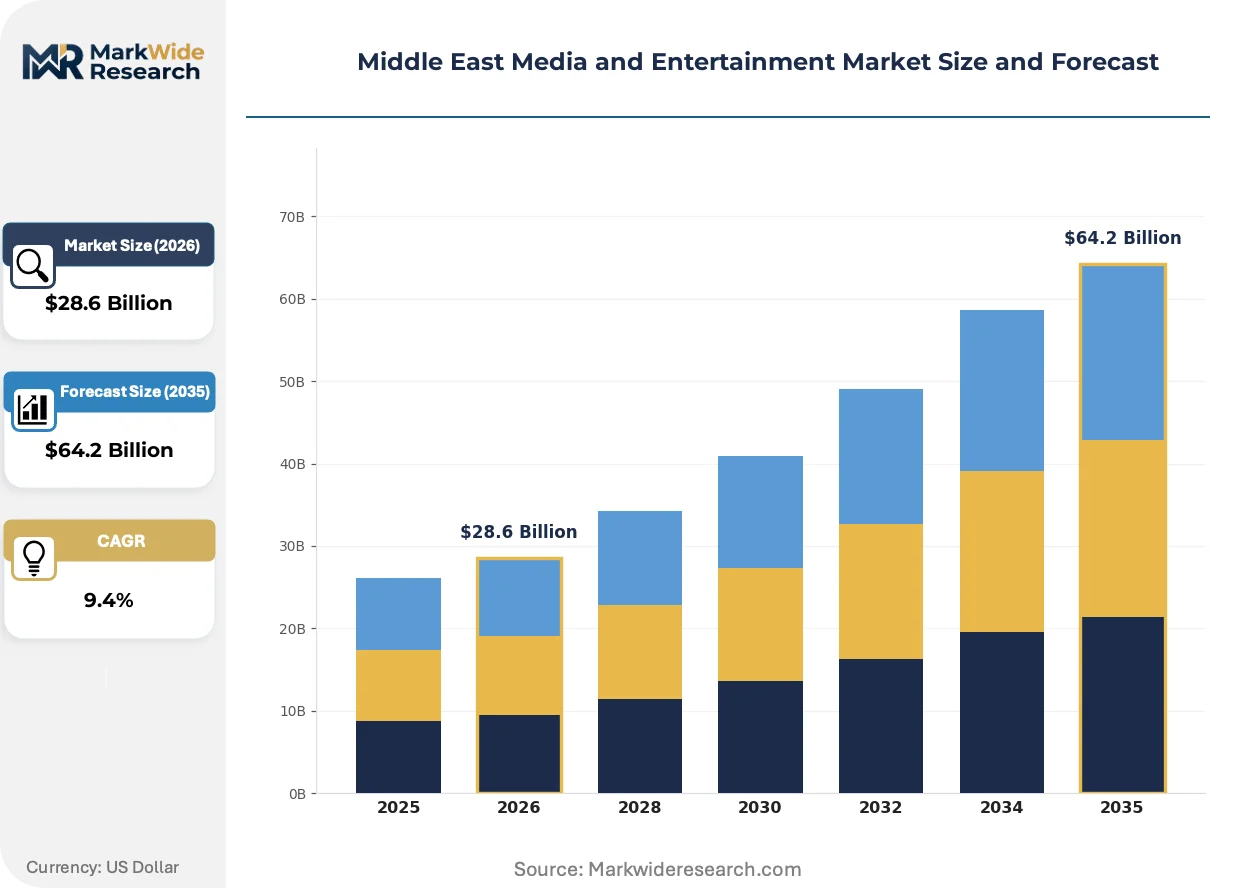
Market Dynamics
Saudi Vision 2030's cultural opening is compressing production timelines for Arabic-language content while 5G infrastructure expansion across Gulf Cooperation Council states redefines addressable audience reach for streaming distributors.
Growth Catalysts
- Fiber broadband rollout:Saudi Arabia's National Transformation Program targets universal high-speed coverage, expanding streaming platform subscriber bases in secondary cities beyond Riyadh and Jeddah.
- GAMA licensing reform:Saudi Arabia's General Authority for Audiovisual Media streamlined content classification procedures, reducing clearance delays for international distributors seeking theatrical and digital release windows.
- Co-production treaties:Bilateral filming agreements between UAE, Saudi Arabia, and Egypt enable location arbitrage and talent pooling across Cairo, Dubai, and Riyadh production hubs.
Market Restraints
- Regulatory fragmentation:Egypt's Supreme Council for Media Regulation imposes local content quotas distinct from UAE decency standards, forcing multi-territory distributors to maintain parallel compliance workflows.
- Cinema infrastructure concentration:Saudi Arabia's screen count expansion concentrates in Riyadh and Jeddah, leaving smaller Gulf markets theatrically underserved relative to per-capita purchasing power.
- Content localization costs:Arabic dialect variation between Levantine, Gulf, and Egyptian markets necessitates separate dubbing and subtitling pipelines, inflating distribution economics for non-Arabic origin content.
Strategic Opportunities
- Kuwait and Bahrain penetration:These Gulf Cooperation Council states exhibit high disposable income and underdeveloped local production capacity, creating first-mover advantages for regional streaming platforms.
- Esports and gaming content:Saudi Arabia's Savvy Games Group investments are catalyzing demand for competitive gaming broadcasts and interactive entertainment formats adjacent to traditional media.
- Virtual production adoption:LED volume stages at Dubai Studio City and Neom's media cluster enable location-agnostic shooting, reducing dependency on physical sets and weather-dependent scheduling.
Industry Challenges
- Arabic-script technical talent:Shortage of VFX supervisors, colorists, and post-production specialists fluent in regional content requirements constrains output scaling for premium drama series.
- Cross-border rights clearance:Pan-Arab music licensing and talent appearance agreements require negotiation with multiple collective management organizations, complicating regional distribution windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Media and Entertainment Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Films, TV Shows, Music, Video Games Delivery Platform: Streaming Services, Cable Television, Radio, Theatrical Releases Consumer Segment: Families, Young Adults, Retirees, Professionals Revenue Model: Subscription, Ad-Supported, Pay-Per-View, Licensing |
| Companies Covered | MBC Group, Orbit Showtime Network, beIN Media Group, Abu Dhabi Media, Arab Media Group, Zawya Ltd, Intigral Inc, Eye Media LLC, Qudurat Media, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Media and Entertainment Market Strategic Shifts
Cloud-native production workflows and AI-assisted localization are compressing content supply chains while regulatory frameworks across Gulf states diverge on foreign ownership and content classification standards.
Virtual production using real-time rendering engines is decomposing traditional location shooting requirements for Arabic-language drama. Saudi producers at Neom and Dubai Studio City operators are adopting LED volumes for desert and urban backdrops. This technology is collapsing shooting schedules from months to weeks while enabling simultaneous multi-territory release coordination.
Saudi Arabia's General Authority for Audiovisual Media introduced content rating categories aligned with international standards yet distinct from UAE's National Media Council classification tiers. International distributors now maintain parallel compliance documentation for theatrical releases crossing the Saudi-UAE border. Premium drama imports face the most complex navigation between these frameworks.
Young adult audiences across Riyadh, Dubai, and Cairo are fragmenting attention toward creator-driven short-form vertical video, compressing subscription streaming engagement metrics. Platform operators are responding with mobile-optimized original formats and talent incubator programs targeting Gulf-based influencers. This behavioral pivot is most pronounced among 18-29 demographic segments in Saudi Arabia and UAE urban centers.
Middle East Media and Entertainment Market Segmentation
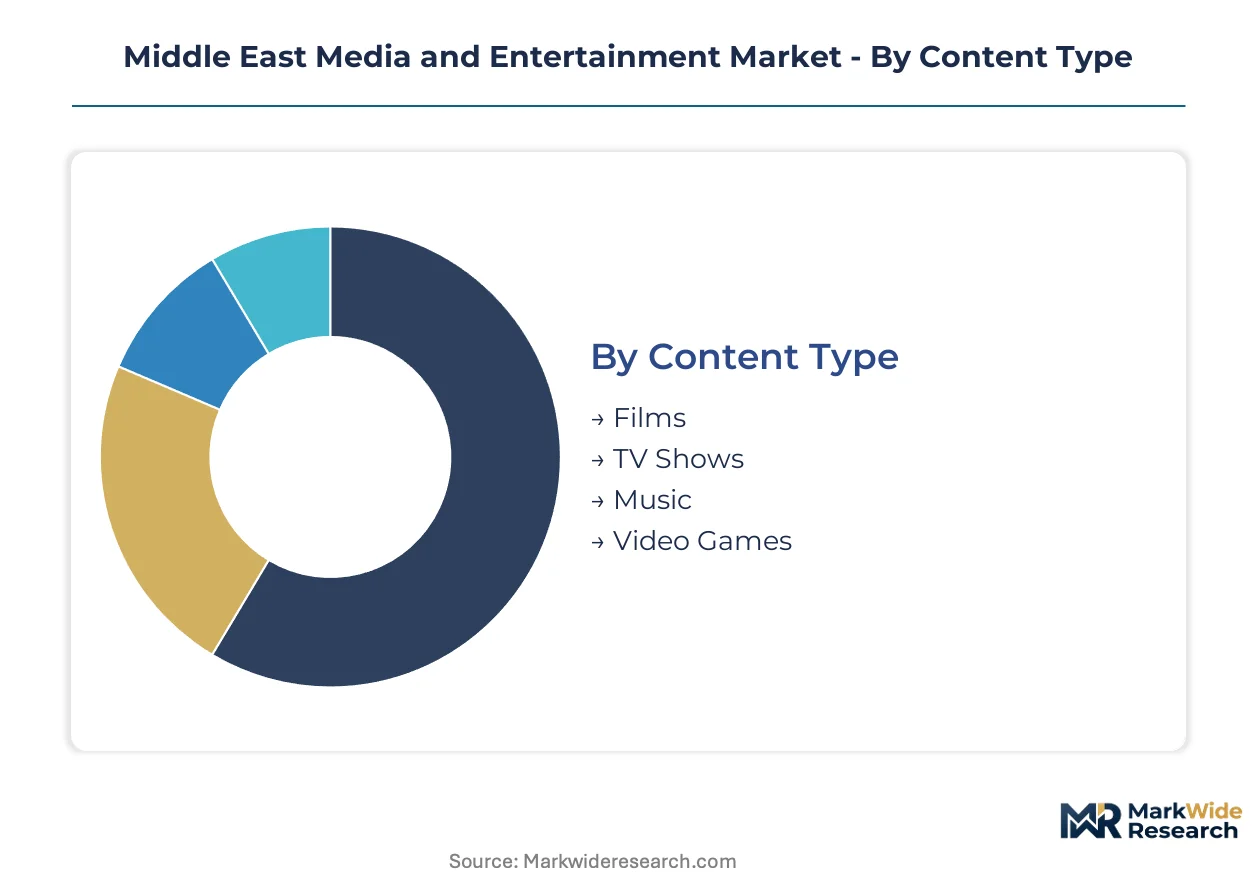
Channel fragmentation across the Middle East requires distributors to map content types against delivery infrastructure and payment willingness. Segmentation reveals where Saudi Vision 2030 investment concentrates versus where legacy broadcast still dominates.
Content Type:
Distribution channels favor different content formats based on production cost recovery timelines and censorship clearance complexity.
- Films:Theatrical releases command premium pricing in Saudi Arabia's expanding cinema infrastructure, with GAMA classification determining windowing between theatrical and streaming. Dubai and Riyadh production hubs are prioritizing Arabic-language features for simultaneous Gulf-wide release.
- TV Shows:Drama series drive subscription streaming adoption across MBC Group and Shahid platforms, with Ramadan scheduling creating concentrated production cycles. Egyptian studios supply Levantine-format content while Saudi producers develop Gulf-dialect originals.
- Music:Pan-Arab licensing agreements with regional collective management organizations shape distribution economics for streaming platforms.
- Video Games:Savvy Games Group investments are localizing competitive gaming content for Saudi and UAE esports broadcasts.
TV Shows dominate installed base. Films is where expansion concentrates.
Delivery Platform:
Cost tier segmentation separates premium subscription offerings from mass-market ad-supported alternatives.
- Streaming Services:Fiber broadband penetration in Saudi secondary cities and UAE urban corridors expands addressable audiences for Shahid, StarzPlay, and Netflix MENA. 5G rollout enables mobile-first consumption among young adult demographics.
- Cable Television:beIN Media Group's sports exclusivity sustains bundled telecom packages across Qatar and UAE, with live football rights locking in premium subscriber retention.
- Radio:Commuter audiences in Cairo and Jeddah maintain listenership for news and music formats.
- Theatrical Releases:Saudi screen count multiplication concentrates in Riyadh and Jeddah, leaving Kuwait and Bahrain theatrically underserved relative to disposable income levels.
Cable Television dominates installed base. Streaming Services is gaining share fastest.
Consumer Segment:
Application-based segmentation aligns content investment with household spending authority and platform access patterns.
- Families:Multi-user subscription plans and Ramadan co-viewing events concentrate demand for G-rated Arabic drama and religious programming.
- Young Adults:Creator-driven short-form vertical video fragments attention away from long-form streaming in Riyadh and Dubai urban centers, forcing platform operators toward mobile-optimized originals.
- Retirees:Traditional broadcast news and cultural programming retains loyalty through Abu Dhabi Media documentary output.
- Professionals:Commute-time podcast consumption and premium sports subscriptions align with disposable income concentration in Gulf Cooperation Council financial sectors.
Families dominates installed base. Young Adults is where expansion concentrates.
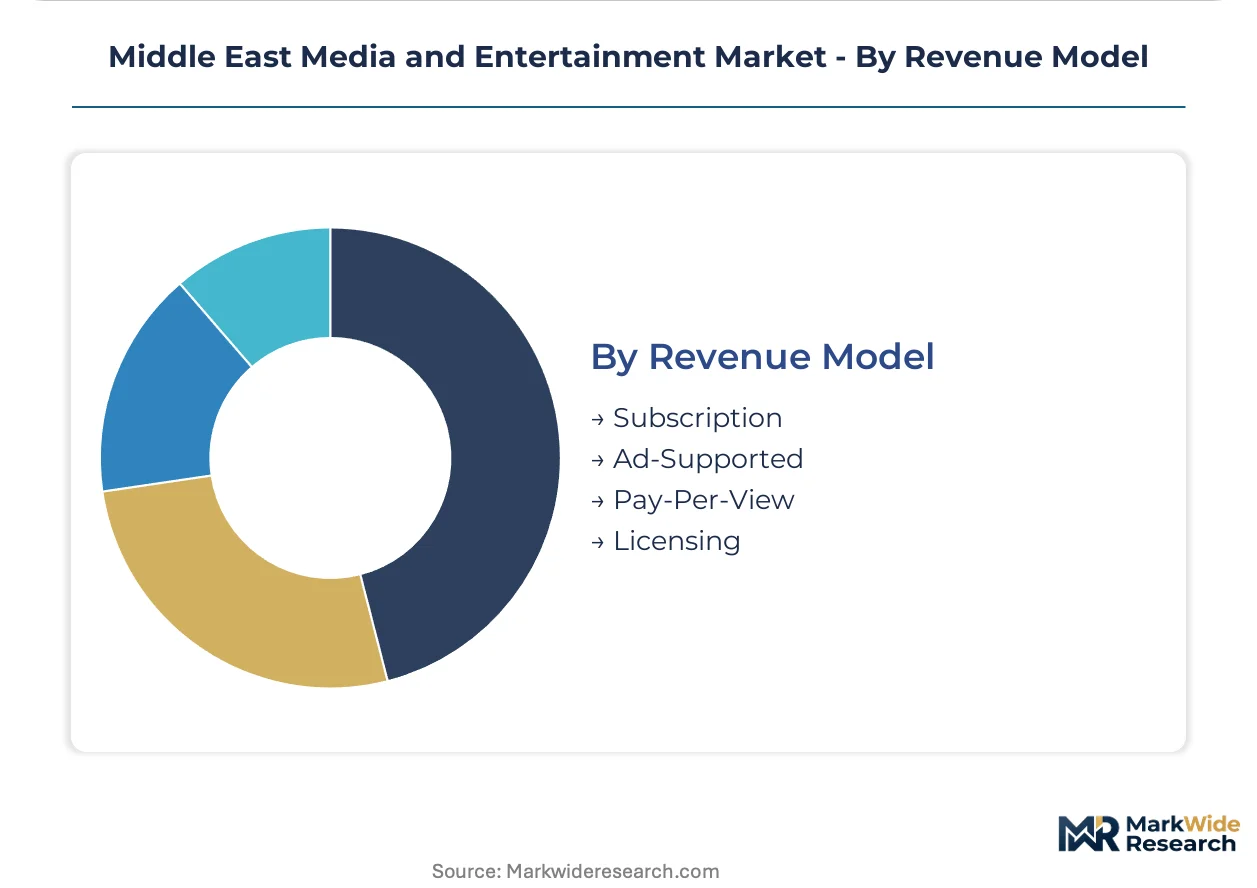
Revenue Model:
Margin structure varies sharply between predictable subscription recurring revenue and volatile advertising exposure.
- Subscription:Annual plans reduce churn for MBC Group and Netflix MENA, though Saudi and UAE consumers exhibit growing price sensitivity as platform proliferation accelerates.
- Ad-Supported:YouTube and TikTok capture brand budgets migrating from traditional broadcast, with Gulf-based influencer talent incubators targeting 18-29 demographic segments.
- Pay-Per-View:Live sports events and day-and-date film releases generate concentrated revenue spikes.
- Licensing:Content clearance under divergent Saudi and UAE regulatory frameworks complicates multi-territory syndication economics for international distributors.
Subscription dominates installed base. Ad-Supported is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC Interconnector grid and Saudi Arabia's fiber backbone expansion underwrite the region's streaming infrastructure capacity, enabling platform operators to reach secondary cities beyond traditional broadcast footprints.
Saudi Arabia
Riyadh and Jeddah anchor theatrical demand as screen counts multiply under Vision 2030, while GAMA's streamlined content classification reduces clearance delays for international distributors. The General Authority for Audiovisual Media now permits co-production treaties that enable location arbitrage with Egyptian and UAE studios. Neom's media cluster is deploying LED volume stages for virtual production.
United Arab Emirates
Dubai Studio City and Abu Dhabi's twofour54 free zones concentrate post-production talent and tax-incentivized filming for regional drama series. The National Media Council enforces foreign ownership caps that shape joint-venture structures for streaming platforms entering the market. Sharjah's documentary funding aligns with federal cultural mandates competing for prestige content.
Egypt
Cairo's long-established studios supply Levantine-format Arabic drama to Gulf broadcasters, though the Supreme Council for Media Regulation imposes local content quotas affecting syndication economics. The country's dubbing infrastructure serves Egyptian Arabic localization for pan-Arab distribution. Alexandria maintains secondary production capacity for lower-budget serials.
Qatar
beIN Media Group's Doha headquarters anchors sports broadcasting rights across North Africa and the Gulf, with live football exclusivity sustaining premium subscriber retention. The country's sovereign wealth backing enables aggressive rights acquisition against regional competitors. Lusail's media infrastructure supports 4K production for international event coverage.
Kuwait
High disposable income and underdeveloped local production capacity create first-mover advantages for Saudi and UAE streaming platforms expanding northward. The country's small domestic market limits theatrical infrastructure investment relative to per-capita purchasing power. Kuwait City concentrates demand for premium Arabic drama and live sports subscriptions.
Middle East Media and Entertainment Market Competitive Environment
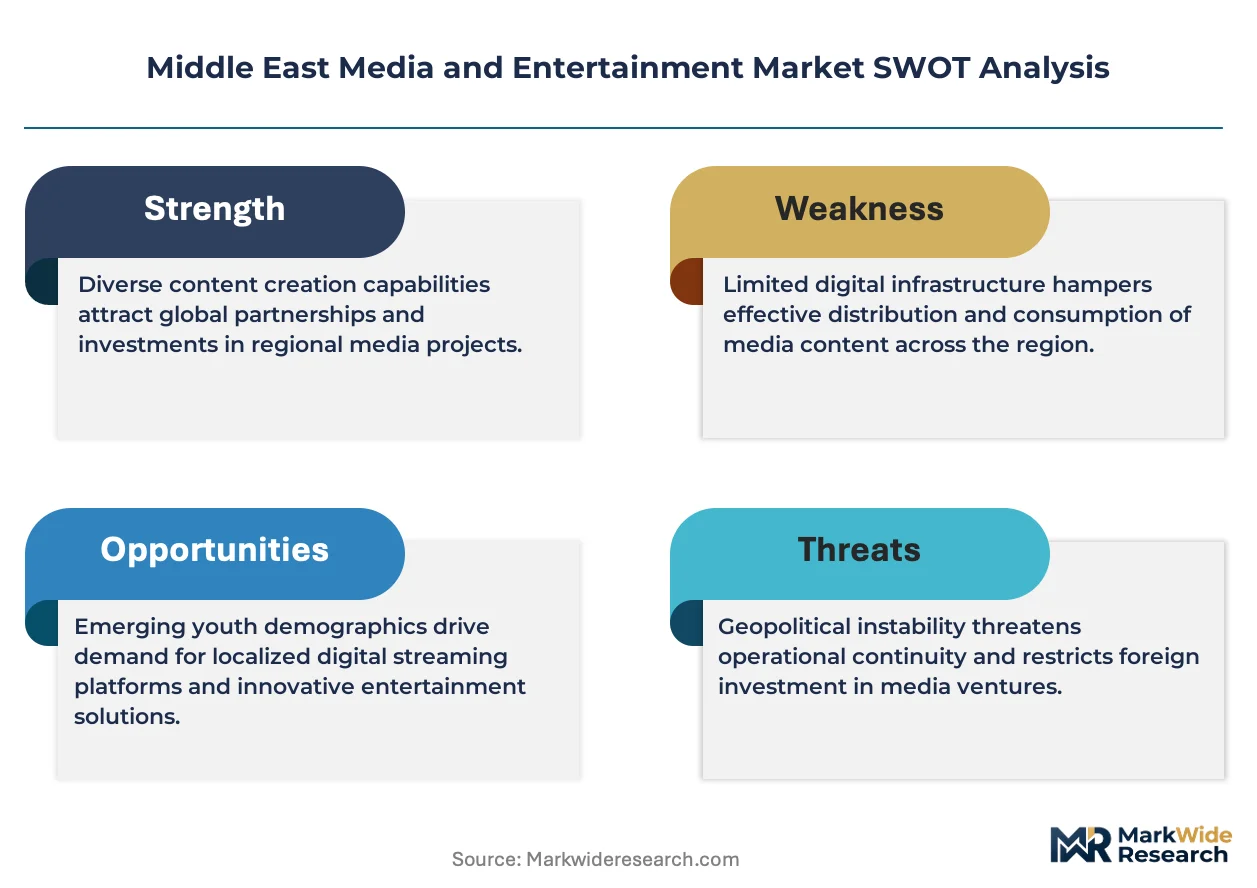
Listed leaders compete with private specialists across content verticals and regulatory jurisdictions, with publicly traded MBC Group and beIN Media Group facing privately held Abu Dhabi Media and Orbit Showtime Network. The market structures around three archetypes: vertically integrated production-distribution conglomerates controlling Arabic-language drama pipelines, sports-rights aggregators locking in live event exclusivity, and platform-agnostic content licensors navigating multi-territory clearance. Competitive moves concentrate on co-production treaty exploitation for location arbitrage and fiber-enabled streaming expansion into secondary GCC cities.
Within the vertically integrated tier, MBC Group and beIN Media Group exemplify divergent content strategies—MBC leveraging Riyadh and Dubai production studios for Arabic drama control, beIN anchoring sports rights across North Africa. Abu Dhabi Media occupies a position aligned with federal cultural mandates, competing through documentary prestige rather than volume drama output. These three entities represent how regulatory geography shapes competitive positioning: Saudi licensing reform favors MBC's theatrical windowing, Qatari sovereign backing sustains beIN's rights acquisition, and UAE federal mandates direct Abu Dhabi Media's programming mix.
| Leading Market Players |
|---|
| MBC Group |
| Orbit Showtime Network |
| beIN Media Group |
| Abu Dhabi Media |
| Arab Media Group |
| Zawya Ltd |
| Intigral Inc |
| Eye Media LLC |
| Qudurat Media |
| Others |
Value Chain & Pricing Dynamics
LED volume stages replacing physical location shoots are compressing production timelines while redistributing cost structures across Riyadh, Dubai, and Cairo hubs. This substitution simultaneously collapses weather-dependent scheduling risks and concentrates pricing power with virtual production facility operators possessing scarce technical talent pools.
Pricing Analysis
Content format tiering creates the primary spread, separating premium Arabic-language originals from licensed international catalog and ad-supported user-generated inventory. Subscription streaming services deploy annual-plan discounts to reduce churn, while theatrical windowing commands peak pricing in Saudi Arabia's expanding cinema infrastructure. Pricing pressure stems from platform proliferation accelerating consumer subscription fatigue across Gulf Cooperation Council states. Young adult segments in Riyadh and Dubai exhibit highest price sensitivity, driving ad-supported tier adoption, whereas family multi-user plans demonstrate lowest elasticity due to Ramadan co-viewing habits.
Supply Chain Analysis
Just-in-time content commissioning now dominates streaming platform procurement, replacing the strategic stockpiling of finished drama libraries that characterized legacy broadcast economics. Production supply concentrates in Saudi Arabia, the United Arab Emirates, and Egypt, with Cairo's dubbing infrastructure feeding Egyptian Arabic localization pipelines. Raw material dependencies include LED volume hardware, real-time rendering software licenses, and pan-Arab music rights clearing through multiple collective management organizations. Single-source vulnerability runs through concentrated VFX supervisor talent pools fluent in regional content requirements. Distribution runs through fiber-enabled streaming platforms, cable sports bundles, and theatrical exhibitors concentrated in Riyadh and Jeddah.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Content licensing and platform subscription revenue layers are expanding faster than theatrical hardware infrastructure, creating service-attach economics that favor recurring-revenue operators over capital-intensive screen builders.
For Market Incumbents: Compound control over Arabic-language drama pipelines through co-production treaty exploitation across Saudi-Egyptian-UAE filming agreements. Defend against creator-driven short-form fragmentation by incubating mobile-optimized original formats targeting Gulf-based influencers. Prioritize backward integration into LED volume stage operations at Neom and Dubai Studio City to capture virtual production margins.
For New Entrants and Emerging Players: Differentiate on Kuwait and Bahrain penetration where high disposable income meets underdeveloped local production capacity. Target underserved theatrical markets in secondary Gulf Cooperation Council cities lacking screen infrastructure relative to purchasing power. Pursue esports and gaming content localization partnerships with Saudi Arabia's Savvy Games Group as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a regulatory-opening phase that favors vertically integrated production-distribution conglomerates over pure-play licensors. Long-term viability across the next decade hinges on controlling both content creation and platform distribution endpoints. Watch GAMA licensing reform momentum as the signal for international distributor entry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Production Adoption | LED volume deployment at Neom and Dubai Studio City collapses shooting schedules from months to weeks. |
| Co-Production Treaty Exploitation | Bilateral filming agreements enable location arbitrage and talent pooling across Cairo, Dubai, and Riyadh hubs. |
| Streaming Platform Expansion | Fiber broadband penetration in Saudi secondary cities extends addressable audiences beyond traditional broadcast footprints. |
| Esports Content Localization | Savvy Games Group investments catalyze demand for competitive gaming broadcasts adjacent to traditional media. |
| Mobile-Original Format Development | Young adult attention fragmentation toward vertical video forces platform operators toward influencer incubator programs. |
Study Parameters
Initial hypotheses were tested against primary input from streaming platform executives, theatrical distribution leads, content licensing specialists, and post-production facility operators and refined through secondary validation. Primary fieldwork drew from regulatory affairs directors at GAMA and the National Media Council, alongside procurement managers at MBC Group and beIN Media Group. Secondary sources included GAMA classification filings, UAE National Media Council ownership documentation, Saudi cinema infrastructure investment disclosures, and pan-Arab music licensing registry data. Bottom-up platform subscriber modeling and top-down Gulf Cooperation Council media spending estimates were triangulated against production capacity surveys.
Variance decomposition across the projection horizon isolates regulatory reform impact, infrastructure buildout timing, and generational consumption shift effects. The analytical framework segments by content type, delivery platform, consumer demographic, and revenue model, with dialect-specific localization requirements modeled as a cross-cutting dimension. CAGRs were derived from installed-base growth rates and average revenue per user trajectories. Forecast inputs incorporate 5G rollout schedules, fiber backbone expansion milestones, and co-production treaty implementation progress.
Forecasts assume regulatory continuity in Saudi Arabia's GAMA classification reform and UAE foreign ownership frameworks; material policy shifts would require re-modeling subscriber and theatrical windowing economics. Content censorship boundary changes, platform subscription fatigue acceleration, and short-form video monetization breakthroughs represent specific revision risks. Practitioners should keep alternative scenarios live as young adult consumption patterns and sovereign wealth media investment priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Online Gambling Market
Digital Media
Europe Online Video Platform Market
Digital Media
Webtoons Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Manga Market
Digital Media
Animation Services Market
Digital Media
Pro AV Market
Digital Media
Digital Media Production Software Market
Digital Media
Digital Content Creator Market
Digital Media
Social TV Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Digital Distribution Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Video Production Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
US Animation, Vfx and Post Production Market