
 Digital Rights Management in Media and Entertainment Market | 2026-2036
Digital Rights Management in Media and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Rights Management in Media and Entertainment Market Intelligence
Subscription-based license management is recalibrating what content owners purchase, shifting perpetual ownership toward recurring entitlement verification. Microsoft Corporation leverages its Azure Media Services infrastructure to anchor enterprise-grade protection for broadcasters. Apple Inc. differentiates through its FairPlay Streaming ecosystem, which controls hardware-software integration across iPhone, iPad, and Apple TV endpoints. Google LLC competes via Widevine modular security levels, sustaining Android-dominated mobile and connected TV distribution.
Digital Rights Management in Media and Entertainment encompasses cryptographic access control, authentication protocols, encryption algorithms, and license management systems that enforce usage rules on digital content. The technology operates through client-server architectures where encrypted media files decrypt only after rights validation against policy servers, primarily serving to prevent unauthorized copying, redistribution, and playback of copyrighted audiovisual works. Encryption and access control solutions capture the largest addressable base as studios mandate studio-grade protection for theatrical window releases. Cloud-based deployment expands fastest as over-the-top platforms abandon capital-intensive on-premises license server farms in favor of elastic, API-delivered entitlement services.
The EU Digital Services Act and GDPR impose transparency and data minimization requirements on platforms deploying DRM user-tracking, while the United States Copyright Office and WIPO Internet Treaties establish the legal foundation for anti-circumvention enforcement. China's MIIT and NMPA enforce domestic cryptographic standards that foreign DRM vendors must navigate for market access. Stakeholders must monitor fragmentation between regional content protection mandates and emerging AI-generated media attribution requirements that will reshape authentication architectures.
Market Dynamics
Streaming platforms now mandate hardware-agnostic protection that travels across devices, forcing DRM architectures to abandon siloed console-specific encryption in favor of unified entitlement layers that authenticate users regardless of playback endpoint.
Growth Catalysts
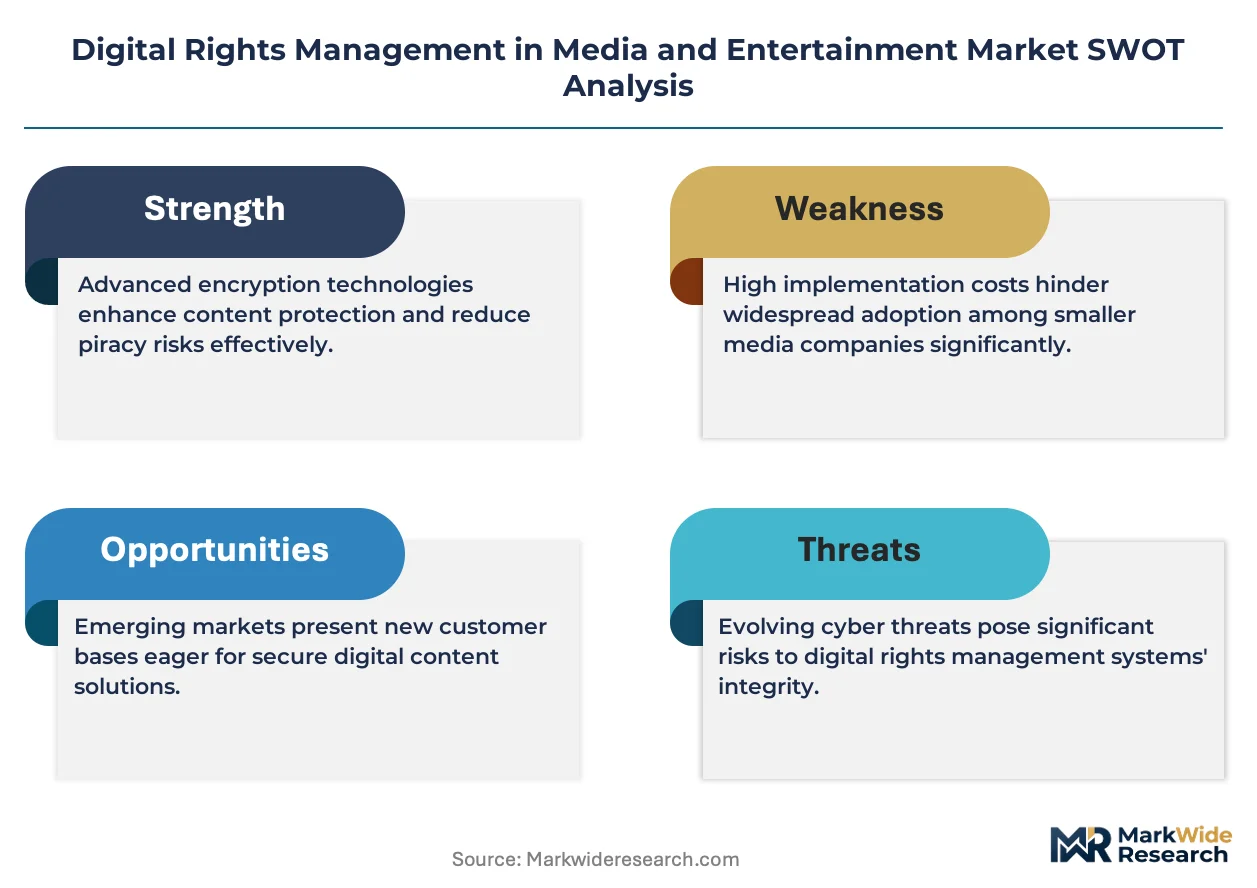
- EU Digital Services Act transparency mandates:Platforms operating across member states must deploy auditable rights-tracking infrastructure, expanding enterprise DRM procurement for compliance documentation.
- 4K HDR theatrical window releases:Studios require studio-grade encryption for premium content, driving upgrades from standard-definition protection systems.
- Cross-device entitlement synchronization:Consumers expect seamless license portability between smartphones, tablets, and connected televisions, accelerating cloud-based license server adoption.
Market Restraints
- Cloud infrastructure cost volatility:Elastic license server scaling introduces unpredictable egress and compute expenses that compress margins for mid-sized streaming operators.
- Domestic cryptographic standard fragmentation:China's MIIT and NMPA enforce proprietary encryption protocols that foreign vendors must license, creating technical barriers to market entry.
- Open-source circumvention tools:Widely distributed decryption utilities erode protection efficacy, forcing continuous algorithm refresh cycles that strain R&D budgets.
Strategic Opportunities
- AI-generated media attribution:Synthetic video and audio creation demands provenance-tracking DRM extensions that verify content authenticity through cryptographic watermarking.
- India's OTT platform expansion:Regional streaming services in Mumbai and Bangalore seek affordable cloud-native protection as subscriber bases scale past ten million users.
- Blockchain-anchored license tokens:Decentralized entitlement registries enable peer-to-peer secondary content markets while preserving royalty distribution integrity.
Industry Challenges
- Post-quantum cryptography migration:Existing RSA and elliptic-curve encryption face obsolescence threats, requiring algorithm replacement across installed device bases without service interruption.
- Legacy set-top box integration:Cable operators maintain millions of aging hardware units with fixed decryption capabilities, complicating unified protection rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Rights Management in Media and Entertainment Market |
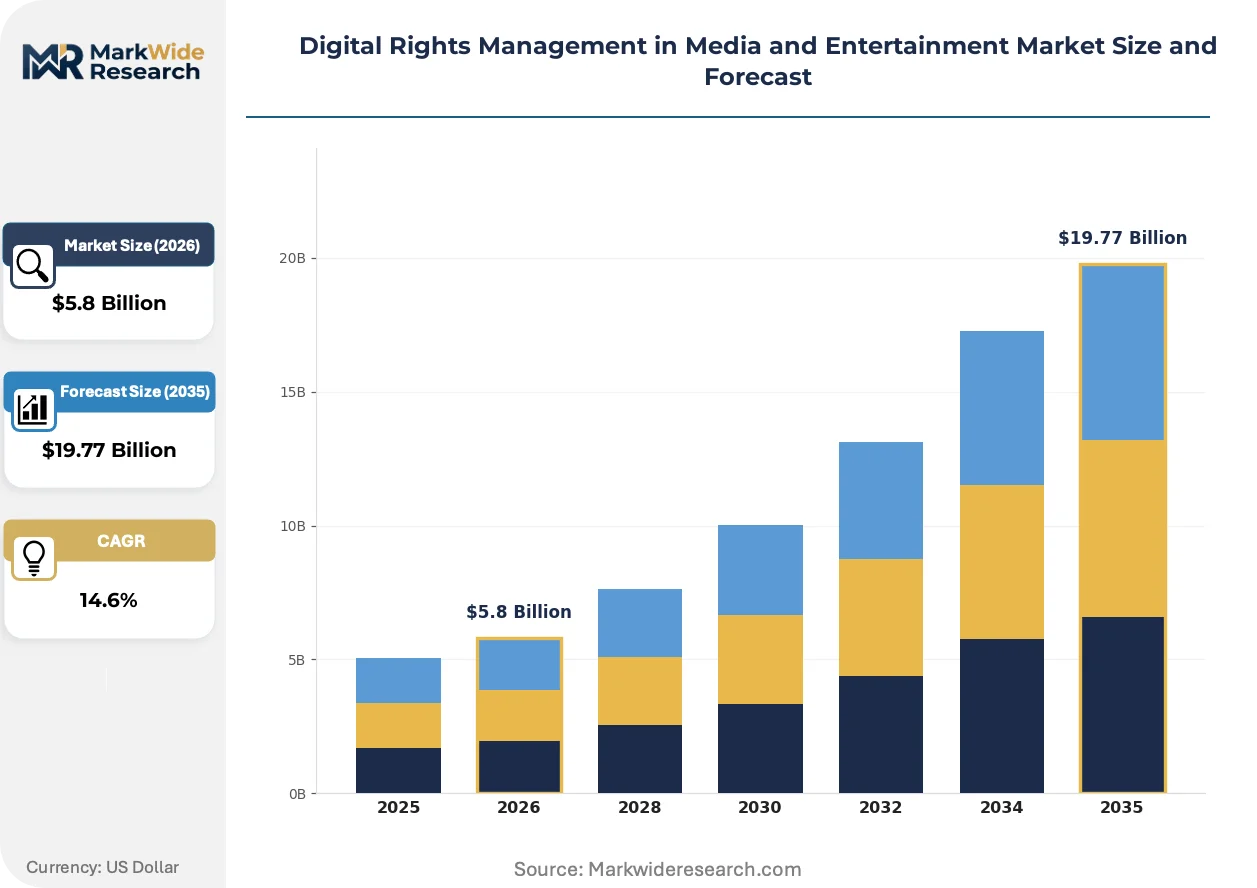
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Access Control, Authentication, Encryption, License Management Application: Digital Distribution, Streaming Services, Content Creation, Media Preservation End User: Film Studios, Music Labels, Broadcasting Companies, Game Developers Deployment: On-Premises, Cloud-Based, Hybrid, Third-Party Providers |
| Companies Covered | Google LLC, Microsoft Corporation, Apple Inc., Irdeto BV, Adobe Systems Incorporated, Intertrust Technologies Corporation, Bitmovin Inc., Verimatrix Inc., Kudelski Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Rights Management in Media and Entertainment Market Strategic Shifts & Innovations
Authentication architectures are fragmenting across hardware-software boundaries as studios demand protection that persists through screen capture, device mirroring, and output port interception.
Widevine modular security levels are modularizing how Android ecosystem stakeholders tier protection strength. Low-tier implementations secure standard-definition mobile streams with software-only decryption. Premium-tier deployments mandate hardware-backed trusted execution environments for 4K content. This stratification compresses licensing costs for budget operators while preserving theatrical-grade protection for flagship releases.
GDPR data minimization requirements are reshaping user-tracking protocols within DRM systems. The European regulation limits persistent identifier retention, forcing platforms to adopt ephemeral session tokens. French CNIL enforcement actions against over-collection practices have prompted streaming services to strip biometric viewing pattern analysis from authentication flows.
Subscription fatigue is compressing household willingness to maintain multiple streaming memberships. Consumers now rotate between platforms monthly rather than maintaining perpetual subscriptions. This churn pattern concentrates in the United States where average households subscribe to four services simultaneously, down from previous peaks, forcing platforms to prioritize frictionless re-activation over complex multi-step authentication sequences.
Digital Rights Management in Media and Entertainment Market Segmentation
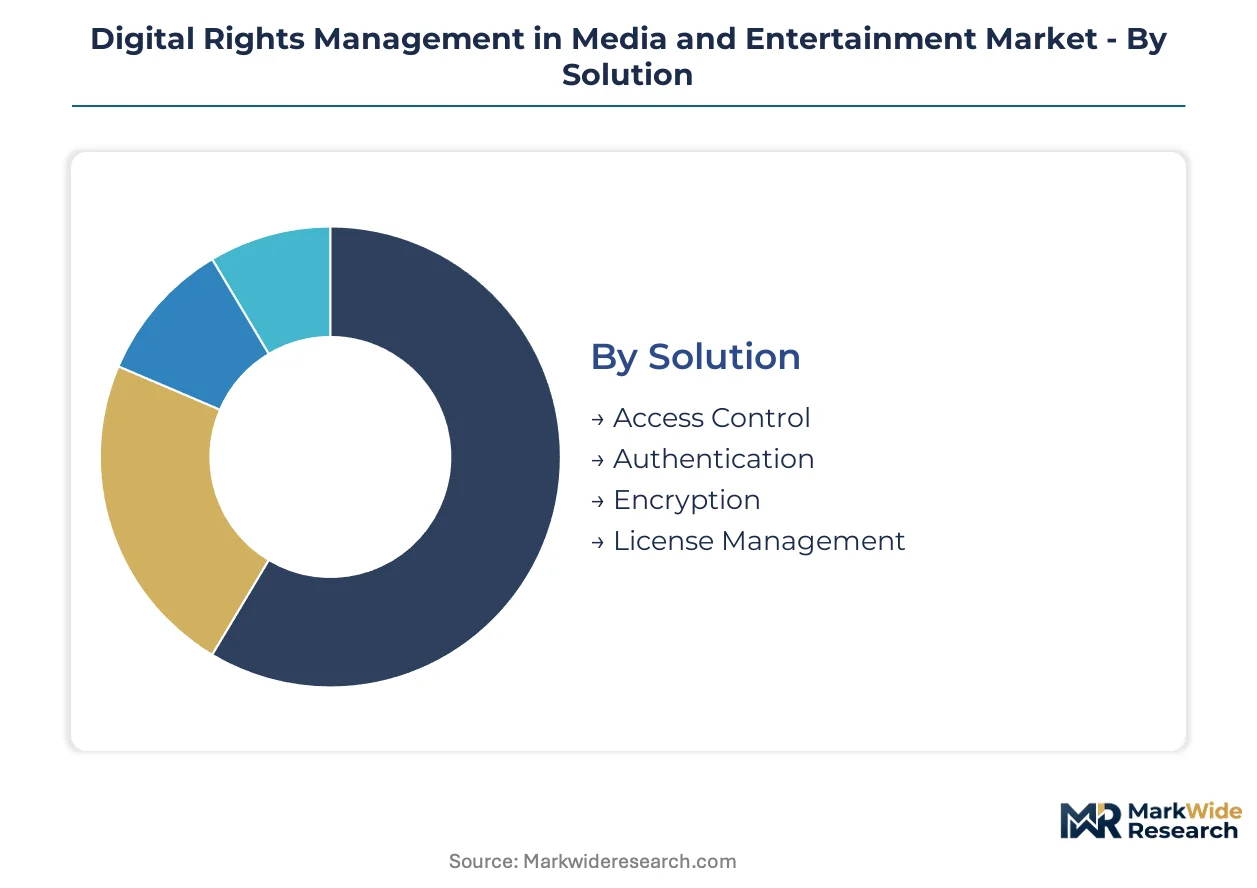
Segmentation reveals how DRM architectures fragment across technical specifications, operational contexts, and buyer economics. Studios select protection tiers based on content value, distribution velocity, and compliance exposure rather than adopting uniform solutions.
Solution:
Technical specifications determine protection efficacy against circumvention vectors and performance overhead on playback devices.
- Encryption:AES-128 and AES-256 algorithms secure content at rest and in transit. Hollywood studios mandate hardware-backed decryption for 4K theatrical releases, driving demand for chipset-integrated trusted execution environments in the United States.
- License Management:Entitlement servers authenticate playback rights through policy enforcement points. Cloud-native deployments dominate as over-the-top platforms abandon capital-intensive on-premises infrastructure in favor of elastic API services.
- Access Control:Role-based and attribute-based mechanisms restrict content availability by geography, device type, or subscription tier. Geofencing requirements intensify under the EU Digital Services Act's territorial licensing mandates.
- Authentication:Multi-factor and device-fingerprinting protocols verify user identity before decryption key release. Biometric integration faces regulatory headwinds from French CNIL enforcement against persistent identifier retention.
Encryption leads on scale; license management leads on momentum.
Application:
Deployment context shapes protection architecture trade-offs between security rigor and user experience friction.
- Streaming Services:Real-time license delivery across millions of concurrent sessions demands sub-100-millisecond authentication latency. Netflix, Disney+, and Spotify drive standardization through their collective procurement influence.
- Digital Distribution:Download-to-own models require persistent license binding to device hardware identifiers. Transactional video-on-demand platforms prioritize forensic watermarking for leak tracing over encryption strength.
- Content Creation:Pre-release rough cuts and dailies circulate through production workflows with time-limited access tokens. Major studios in Los Angeles and London deploy studio-specific DRM for post-production collaboration.
- Media Preservation:Archival formats prioritize format longevity over active protection, migrating legacy content from obsolete encryption schemes to current standards without quality degradation.
Streaming services anchor current revenue; digital distribution is expanding most quickly as transactional models resurge.
End User:
Buyer scale and content value concentration determine willingness to invest in premium protection tiers versus commodity solutions.
- Film Studios:Theatrical window releases command studio-grade encryption with hardware security module integration. Major Hollywood distributors co-develop protection standards with Silicon Valley technology partners.
- Music Labels:Audio streaming dominates revenue, requiring scalable license management for subscriber access across mobile and connected devices. Universal Music Group and Sony Music Entertainment influence Widevine and FairPlay roadmap priorities.
- Broadcasting Companies:Linear and hybrid streaming models require conditional access system integration with legacy set-top box infrastructure. European public broadcasters face GDPR constraints on viewer analytics collection.
- Game Developers:Anti-tampering and online authentication protect multiplayer economies and downloadable content. Cloud gaming services introduce new attack surfaces requiring server-side rendering protection.
Film studios set technical benchmarks; music labels provide volume scale.
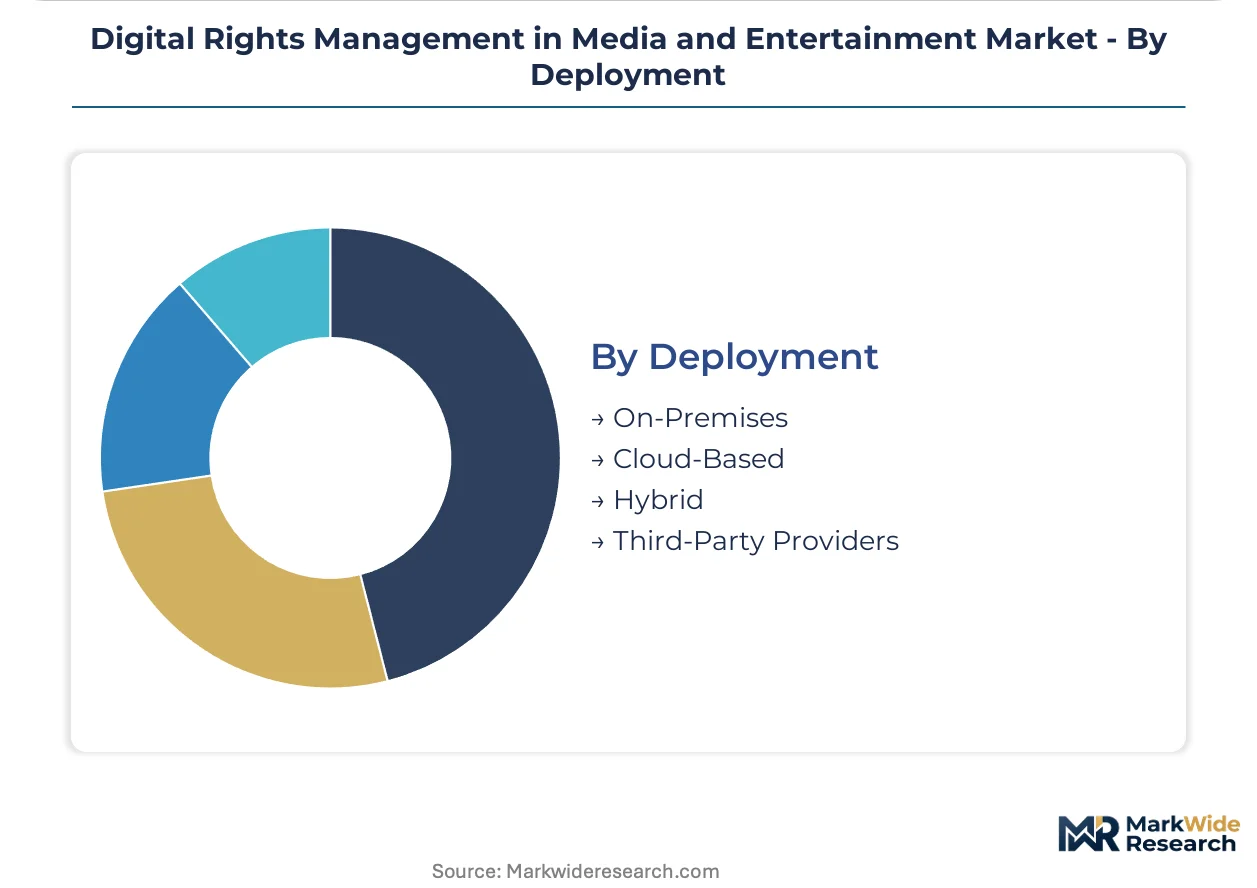
Deployment:
Infrastructure ownership models reflect capital availability, operational expertise, and regulatory data residency requirements.
- Cloud-Based:Elastic scaling matches license server capacity to subscriber concurrency without overprovisioning. Amazon Web Services, Microsoft Azure, and Google Cloud Platform compete for streaming platform workloads.
- Hybrid:Sensitive policy decisions execute on-premises while burst capacity leverages public cloud. European broadcasters adopt this architecture to satisfy GDPR data localization expectations.
- On-Premises:Dedicated hardware satisfies national security concerns and legacy integration requirements. China's MIIT mandates domestic cryptographic modules for platforms operating under NMPA jurisdiction.
- Third-Party Providers:Specialized DRM vendors deliver managed services reducing in-house cryptographic expertise requirements. Mid-sized streaming operators in India and Southeast Asia favor this model for rapid market entry.
Cloud-based deployment dominates new capacity; hybrid architectures gain share fastest among established operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates more studio-grade DRM procurement than Germany, yet both markets face divergent regulatory pressures that reshape platform compliance architectures. France and the United Kingdom enforce stricter data minimization mandates than their Asia-Pacific counterparts. China's domestic cryptographic standards create technical barriers absent in India's emerging OTT expansion.
United States
Hollywood studios and Silicon Valley technology firms co-develop next-generation protection standards through consortium-driven roadmaps. The United States Copyright Office administers anti-circumvention enforcement under the Digital Millennium Copyright Act. Los Angeles-based post-production facilities deploy studio-specific DRM for theatrical window releases requiring hardware-backed decryption.
Germany
European public broadcasters integrate conditional access systems with legacy set-top box infrastructure while migrating toward cloud-native architectures. The GDPR limits persistent identifier retention in viewer analytics collection. Munich and Berlin host major broadcasting technology clusters where hybrid deployment models satisfy data localization expectations.
France
Streaming platforms face intensified geofencing requirements under territorial licensing mandates within the EU Digital Services Act framework. The CNIL enforces actions against over-collection practices in biometric viewing pattern analysis. Paris-based media technology vendors specialize in ephemeral session token implementations for authentication flows.
China
Domestic OTT platforms must navigate MIIT and NMPA enforcement of proprietary encryption protocols for market access. The country's national cryptographic standards mandate domestic security modules for platforms operating under audiovisual regulator jurisdiction. Beijing and Shanghai clusters concentrate development of hardware-integrated trusted execution environments for 4K content protection.
India
Regional streaming services in Mumbai and Bangalore seek affordable cloud-native protection as subscriber bases scale past ten million users. The country's telecommunications regulator oversees content delivery network standards affecting DRM latency requirements. Hyderabad and Chennai emerge as hubs for third-party managed DRM services targeting mid-sized operators.
Digital Rights Management in Media and Entertainment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with technology giants anchoring enterprise-grade deployments while niche vendors serve regional operators. The vendor base concentrates around three strategic tiers: cloud infrastructure owners, specialized security vendors, and broadcast technology integrators. Dominant competitive moves include technology licensing partnerships and vertical integration into hardware-software stacks. Geographic expansion through local certification compliance represents a secondary vector for market entry.
Among technology infrastructure owners, Google LLC, Microsoft Corporation, and Apple Inc. occupy positions that exemplify divergent ecosystem strategies. Google LLC anchors Android-dominated mobile and connected TV distribution through modular security tiering. Microsoft Corporation leverages Azure Media Services infrastructure for broadcaster-facing enterprise deployments. Apple Inc. controls hardware-software integration across endpoint devices through its proprietary streaming ecosystem. These three entities represent distinct archetypes: open-platform modularization, cloud-native enterprise services, and closed-loop device integration.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Apple Inc. |
| Irdeto BV |
| Adobe Systems Incorporated |
| Intertrust Technologies Corporation |
| Bitmovin Inc. |
| Verimatrix Inc. |
| Kudelski Group |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialists in enterprise DRM licensing have consolidated fragmented security vendors across Silicon Valley and European broadcasting hubs, tightening pricing discipline through centralized procurement negotiations while cloud infrastructure owners compete on elastic capacity economics.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for cloud-native license management services. Three-tier pricing structure across premium, standard, and economy levels segments by security rigor: hardware-backed encryption commands premium positioning, software-only protection serves budget operators, and hybrid deployments occupy the mid-market. Pricing pressure stems from open-source circumvention tools forcing continuous R&D refresh cycles. Mid-sized streaming operators in emerging markets exhibit highest price sensitivity, while Hollywood studios prioritize protection efficacy over cost.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China anchor hardware security module provisioning to encryption chipset fabricators. The supply chain draws from Taiwan for semiconductor manufacturing, South Korea for memory components, and domestic Chinese foundries for MIIT-compliant cryptographic modules. Single-source vulnerability concentrates in trusted execution environment licensing from ARM Holdings. Distribution runs through hyperscaler marketplaces and specialized broadcast technology integrators serving tiered operator segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Digital Services Act functions as a regulatory compounder, mandating auditable rights-tracking infrastructure that expands enterprise DRM procurement regardless of underlying content consumption trends.
For Market Incumbents: Cement dominance through backward integration into hardware security module design partnerships with Taiwan and South Korean foundries. Deepen cloud-native API standardization to lock in streaming platform switching costs. Counter emerging blockchain-anchored license token challengers by embedding provenance-tracking into existing entitlement architectures.
For New Entrants and Emerging Players: Cloud-native managed services targeting India's ten-million-plus subscriber OTT platforms offer the most penetrable entry vector. Bypass capital-intensive infrastructure buildouts by leveraging third-party provider certifications. Pursue forensic watermarking specialization for transactional video-on-demand leak tracing, where studio procurement remains fragmented.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-deployment specialists with GDPR-compliant European broadcasting credentials. Long-term viability hinges on post-quantum cryptography migration readiness across installed device bases. Monitor CNIL enforcement patterns against biometric identifier retention as the inflection signal for authentication protocol replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Migration | RSA and elliptic-curve replacement across device bases prevents future decryption vulnerability exposure. |
| AI-Generated Media Attribution Integration | Cryptographic watermarking extensions verify synthetic video authenticity for studio compliance. |
| Blockchain-Anchored License Token Development | Decentralized entitlement registries enable peer-to-peer secondary markets with royalty integrity. |
| GDPR-Compliant Ephemeral Session Architecture | CNIL-aligned authentication flows strip persistent identifiers from biometric viewing analytics. |
| India Cloud-Native Managed Service Expansion | Affordable protection tiers capture Mumbai and Bangalore OTT subscriber scale beyond ten million users. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with streaming platform CTOs, broadcast technology procurement leads, DRM vendor product strategists, and post-production facility technical directors. Secondary validation draws from SEC filings of hyperscaler infrastructure providers, EU Digital Services Act implementation guidance, WIPO Internet Treaties documentation, and China's MIIT cryptographic standard disclosures. Bottom-up entitlement server deployment counts triangulate against top-down studio content protection spend estimates.
Granularity-level modeling disaggregates across solution type, application context, end-user scale, and deployment architecture throughout the forecast period. CAGRs derive from license server capacity scaling trajectories correlated with streaming subscriber growth curves and theatrical window release volumes. Industry-specific inputs include hardware security module shipment data and cloud API call volume disclosures from major platform operators.
Regulatory enforcement variance, open-source circumvention tool proliferation, and post-quantum cryptography standardization delays are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Adult Animation Market
Digital Media
South Korea Webtoons Market
Digital Media
Webcomics Market
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
Video Production Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Digital Content Market
Digital Media
Wedding Photography Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
Entertainment Transcription Market
Digital Media
Middle East Gaming Market
Digital Media
Sports Graphics Market
Digital Media
Global Streaming Media Device Market
Digital Media
VFX Market
Digital Media
US Webtoons Market
Digital Media
4K Content Market