
 Europe Animation, VFX and Post Production Market | 2026-2036
Europe Animation, VFX and Post Production Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Animation, VFX and Post Production Market Insights
Multi-source production partnerships between film studios and independent VFX houses is broadening across Europe. Framestore leverages its London and Munich facilities to anchor high-end feature work for streaming clients. DNEG competes on volume capacity across multiple European sites. Scanline VFX specializes in proprietary fluid simulation technology that differentiates its disaster-sequence portfolio.
Europe Animation, VFX and Post Production encompasses the creation, manipulation, and finishing of moving image content through digital compositing, render farm processing, and color grading pipelines operating at 4K to 8K resolution standards, serving theatrical release, broadcast streaming, and interactive entertainment distribution. 3D Animation and VFX Services occupy the largest margin pools as streaming platforms escalate per-episode visual effects budgets. Motion Capture technology is gaining structural share as real-time engine integration reduces post-production iteration cycles for gaming companies and virtual production stages.
The EU Audiovisual Media Services Directive and national tax credit schemes in France, the United Kingdom, and Germany shape where productions locate and how studios qualify for rebates. EMA and national regulators like the British Film Institute and Centre national du cinéma enforce content investment obligations that redirect platform spending toward European creative industries. Stakeholders must monitor how the EU AI Act's transparency requirements for generative tools will reshape asset creation workflows and staff composition across facility networks.
Market Dynamics
Streaming platforms are compressing post-production timelines while escalating per-shot VFX complexity, forcing facility networks to restructure talent deployment and render farm capacity across European production hubs.
Growth Catalysts
- EU Audiovisual Media Services Directive:Mandatory European content quotas redirect platform commissioning budgets toward local animation and VFX houses, expanding contract pipelines for qualifying productions.
- Real-time engine integration:Unreal Engine and Unity pipelines are collapsing previs-to-final-render workflows, cutting iteration cycles for virtual production stages and gaming crossovers.
- France:The Centre national du cinéma's tax rebate scheme attracts large-scale international features, concentrating high-compositing-capacity investments in Paris and regional facility clusters.
Market Restraints
- Render farm energy costs:Electricity price volatility in Germany and the United Kingdom squeezes facility operating margins, particularly for 8K finishing and AI-assisted upscaling workloads.
- Specialized talent scarcity:Senior compositors and pipeline technical directors concentrate in London and Paris, leaving secondary European markets understaffed for complex sequence delivery.
- EU AI Act transparency mandates:Disclosure requirements for generative training data and synthetic asset provenance add compliance overhead to tool deployment and client delivery protocols.
Strategic Opportunities
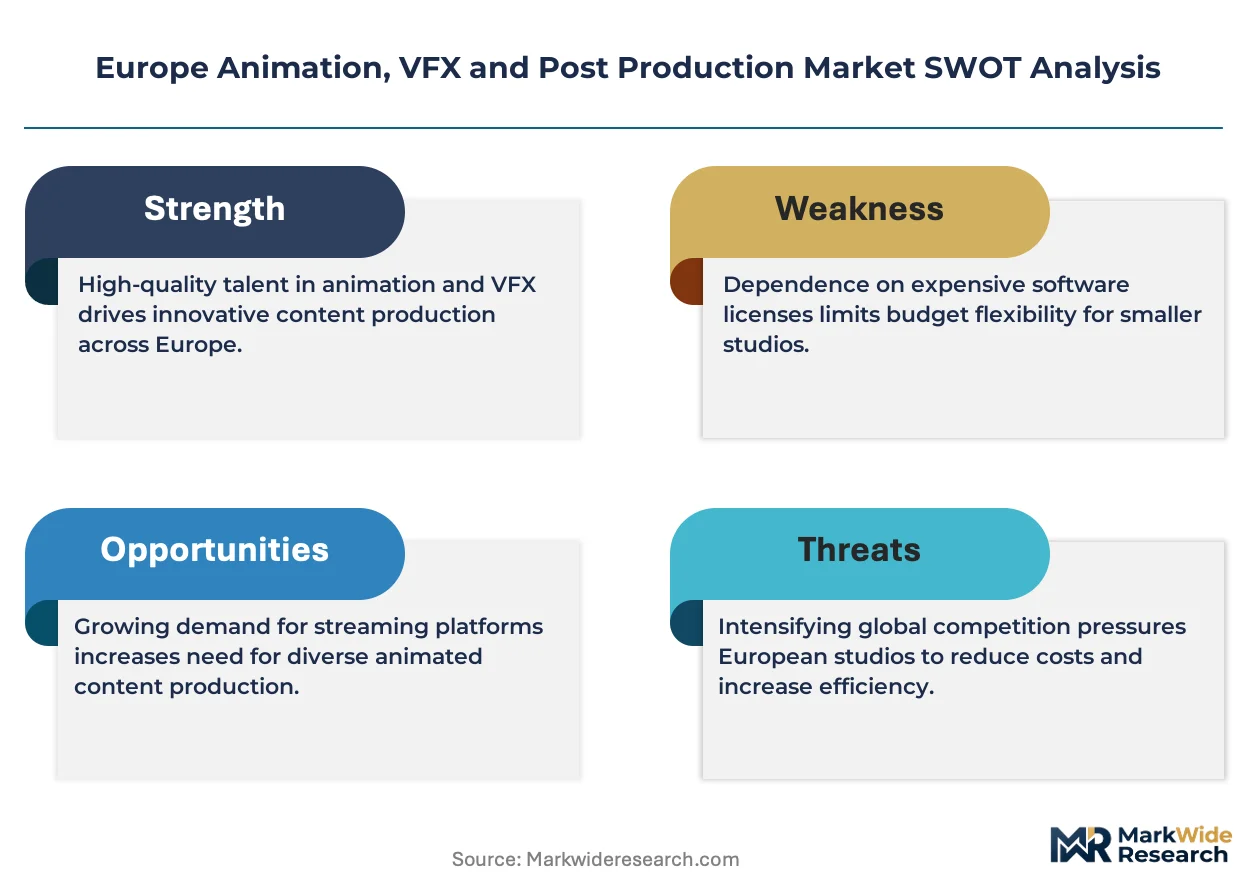
- Eastern European capacity expansion:Poland and Czech Republic offer lower facility operating costs with growing English-language talent pools, positioning for overflow work from Western European hubs.
- German gaming-engine convergence:Automotive and industrial visualization studios in Munich and Stuttgart are repurposing real-time pipelines for entertainment VFX, creating hybrid service offerings.
- Virtual production stage buildouts:LED volume infrastructure investments in Spain and Italy attract location-agnostic streaming productions seeking Mediterranean-set content without travel logistics.
Industry Challenges
- Pipeline standardization gaps:Proprietary software ecosystems at major facilities create friction when productions split sequences across multiple European vendors.
- Skills transfer bottlenecks:Traditional 2D animation expertise in Southern Europe requires reskilling for real-time 3D and virtual production toolsets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Animation, VFX and Post Production Market |
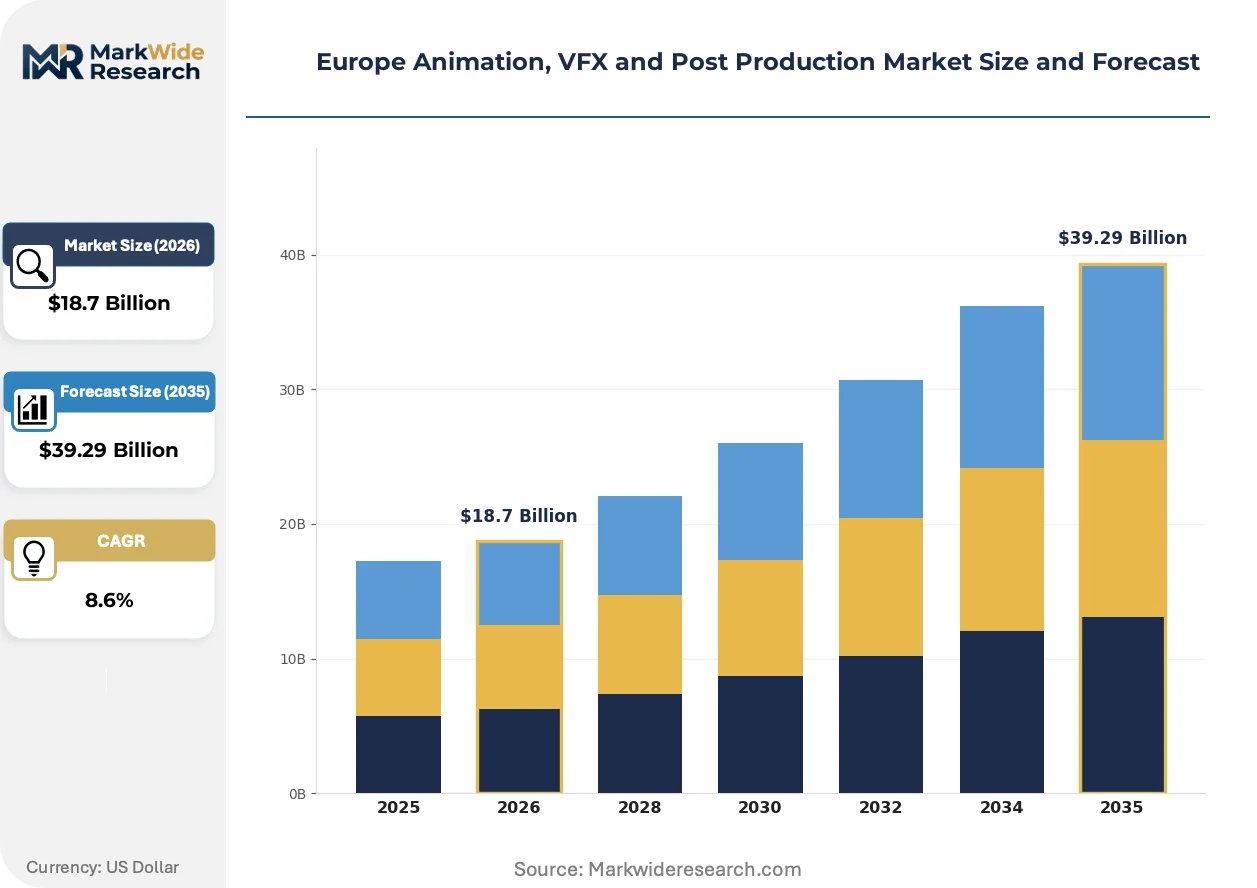
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 2D Animation, 3D Animation, VFX Services, Post Production End User: Film Studios, Advertising Agencies, Gaming Companies, Television Networks Distribution Channel: Direct Sales, Online Platforms, Partnerships, Broadcasting Technology: Computer Graphics, Motion Capture, Augmented Reality, Visual Effects Software |
| Companies Covered | Framestore, Scanline VFX, Cinesite, RISE FX GmbH, Outpost VFX, DNEG, MPC Film, Aardman Animations, Maxon Computer GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Animation, VFX and Post Production Market Trends and Innovations
Artificial intelligence is penetrating asset creation and finishing workflows, compressing manual labor requirements while raising quality thresholds for final delivery across European facility networks.
Neural rendering and AI-assisted rotoscoping are absorbing tasks previously executed by junior compositing artists, with streaming platforms and gaming publishers adopting these tools at accelerated procurement cycles. Facility operators are restructuring entry-level staffing models and reinvesting training budgets toward AI supervision and prompt engineering competencies.
The EU AI Act's transparency requirements for generative content are reshaping contractual liability frameworks between studios and platform clients. Productions must now document synthetic asset provenance and training data sources, with the United Kingdom and France implementing national guidance ahead of full harmonization. VFX houses are embedding metadata capture into pipeline architectures to preempt delivery rejections.
Platform buyers are consolidating vendor relationships around multi-project retainer structures rather than per-picture bidding. Netflix and Amazon Studios are prioritizing European facilities with guaranteed capacity blocks and dedicated supervisory teams, displacing spot-market commissioning in London and Berlin. This concentration rewards scaled operators with balance-sheet capacity to reserve talent and infrastructure.
Europe Animation, VFX and Post Production Market Segmentation
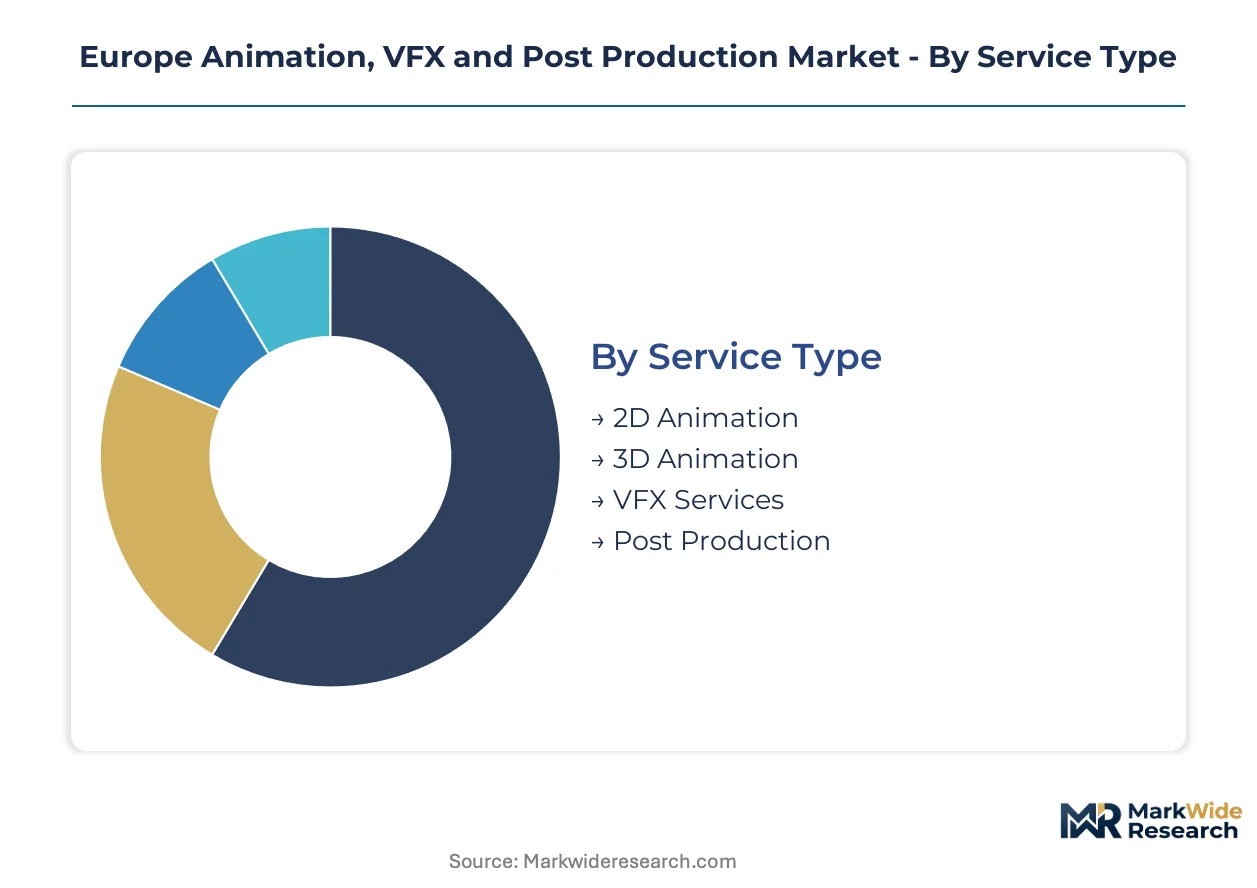
Segmentation in the Europe Animation, VFX and Post Production Market reveals distinct capital requirements, margin profiles, and client concentration patterns. Facilities structure their infrastructure investments around service tiers and technology stacks that align with streaming platform procurement patterns.
Service Type:
3D Animation and VFX Services demand the heaviest upfront infrastructure commitments, with render farm capacity and real-time engine integration driving facility-level investment decisions across Paris, London, and Munich.
- 3D Animation:Real-time engine pipelines using Unreal Engine and Unity compress previs-to-final workflows. Streaming platforms in the United Kingdom and France are escalating per-episode budgets for photorealistic character work and environmental sequences.
- VFX Services:High-compositing-capacity operations serving disaster sequences and crowd simulations require specialized fluid dynamics and particle systems. The Centre national du cinéma's tax rebate scheme concentrates large-scale international features in Paris facility clusters.
- 2D Animation:Traditional frame-by-frame techniques persist in Southern European studios, though reskilling toward hybrid 2D-3D pipelines is accelerating.
- Post Production:Color grading and finishing at 4K to 8K resolution standards serve theatrical and streaming distribution, with LED volume integration reshaping deliverable specifications.
3D Animation absorbs the bulk of installed capacity; VFX Services is expanding most quickly.
End User:
Client procurement patterns diverge sharply between project-based spot purchasing and multi-year retainer structures, with streaming platforms consolidating vendor relationships around guaranteed capacity blocks.
- Film Studios:Large-scale theatrical releases drive peak demand for 8K finishing and complex sequence delivery, with tax credit arbitrage between the United Kingdom, France, and Germany influencing production location decisions.
- Gaming Companies:Real-time engine convergence and motion capture integration for cinematic cutscenes are collapsing traditional post-production timelines, particularly among Munich and Stuttgart visualization studios.
- Television Networks:Broadcast streaming hybrids maintain steady volume for episodic finishing, though per-episode VFX complexity remains below streaming-native productions.
- Advertising Agencies:Rapid-turnaround commercial work prioritizes motion graphics and compositing speed over photorealistic complexity.
Film Studios command the largest project values; Gaming Companies are climbing the fastest as engine technology bridges entertainment and interactive pipelines.
Distribution Channel:
Channel selection reflects client scale and repeat engagement patterns, with platform consolidation favoring direct relationships over intermediary procurement.
- Direct Sales:Multi-project retainer agreements with Netflix and Amazon Studios lock in dedicated supervisory teams and reserved render capacity, displacing spot-market commissioning in London and Berlin.
- Partnerships:Co-production frameworks between film studios and independent VFX houses split sequences across European facility networks, though pipeline standardization gaps create operational friction.
- Online Platforms:Self-service marketplaces for stock assets and template-based motion graphics serve smaller advertising and corporate clients.
- Broadcasting:Traditional television network procurement maintains legacy post-house relationships for news and sports graphics packages.
Direct Sales captures the dominant share of high-value contracts; Partnerships are gaining share fastest as productions distribute risk across vendor networks.
Technology:
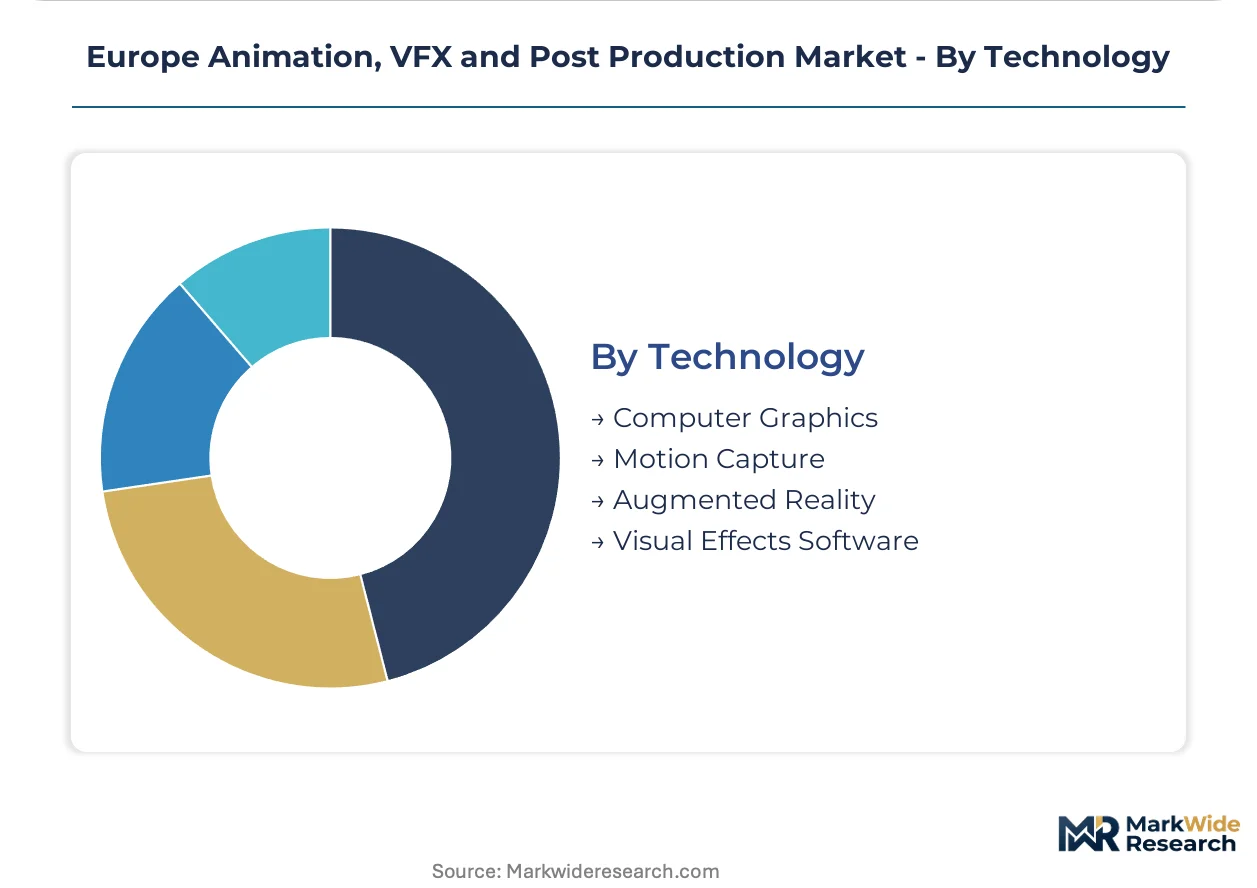
Technology stack selection determines labor composition, with AI-assisted tools restructuring entry-level staffing models toward supervision and prompt engineering competencies.
- Computer Graphics:Proprietary render engines and shader development differentiate facility capabilities for photorealistic environmental work, with 8K output standards driving hardware refresh cycles.
- Motion Capture:Real-time performance translation for virtual production stages and gaming cinematics is gaining structural share as LED volume infrastructure spreads to Spain and Italy.
- Visual Effects Software:Neural rendering and AI-assisted rotoscoping absorb tasks previously executed by junior compositing artists, with EU AI Act transparency mandates embedding metadata capture into pipeline architectures.
- Augmented Reality:Interactive overlay work for live broadcast and experiential marketing remains niche relative to core entertainment pipelines.
Computer Graphics anchors the majority of facility R&D spend; Motion Capture is gaining share fastest as virtual production stage buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London and Paris anchor European VFX capacity through established talent pools and tax incentive schemes that attract streaming platform commissioning budgets.
United Kingdom
Framestore and DNEG operate flagship facilities in London serving Netflix and Amazon Studios retainer contracts. The British Film Institute administers the Film Tax Relief scheme that rebates qualifying production expenditure. Soho and Shepherd's Bush concentrate high-end compositing stages where LED volume infrastructure is displacing traditional green-screen workflows.
France
Paris facility clusters absorb large-scale international features seeking the Centre national du cinéma's tax rebate. Macron's government expanded the TRIP scheme to 40% for international productions. Île-de-France hosts specialized fluid simulation and crowd system operations that differentiate French houses from volume competitors.
Germany
Munich and Stuttgart visualization studios repurpose automotive real-time pipelines for entertainment VFX convergence. The Federal Film Fund and regional subsidies from FilmFernsehFonds Bayern attract gaming-engine hybrid productions. Bavaria's technical universities feed pipeline technical director talent directly into local facility networks.
Spain
Barcelona and Madrid LED volume buildouts capture Mediterranean-set streaming productions avoiding travel logistics. Spain's international tax credit and Pinewood Studios Canarias infrastructure attract overflow work from Paris and London. Catalan facilities specialize in virtual production stage operation for period drama location substitution.
Poland
Warsaw and Krakow emerging VFX houses compete on lower facility operating costs with growing English-language talent pools. The Polish Film Institute's cash rebate scheme positions the country for Western European overflow sequences. Wrocław technical schools are reskilling traditional animators for real-time 3D toolsets.
Europe Animation, VFX and Post Production Market Competitive Landscape
Global majors compete with regional champions across talent retention and render farm scale, producing a tiered structure where London and Paris facilities anchor premium work while Eastern European houses absorb volume overflow. Three archetypes dominate: integrated streaming retainer operators, specialized technology houses with proprietary simulation tools, and regional cost-competitive overflow processors. M&A activity concentrates facility networks under multi-site brands, while strategic partnerships split high-shot-count sequences across geographic clusters to optimize tax credit arbitrage.
Within the integrated streaming tier, Framestore and DNEG exemplify multi-facility operators with dedicated supervisory teams reserved for platform retainer structures. Scanline VFX occupies a specialized position through proprietary fluid simulation technology that differentiates disaster sequence portfolios. Among German precision-engineering influenced houses, RISE FX GmbH and Maxon Computer GmbH represent the technical toolset and software infrastructure archetype that supplies pipeline technology across European facility networks.
| Leading Market Players |
|---|
| Framestore |
| Scanline VFX |
| Cinesite |
| RISE FX GmbH |
| Outpost VFX |
| DNEG |
| MPC Film |
| Aardman Animations |
| Maxon Computer GmbH |
| Others |
Pricing and Supply Chain Analysis
Render farm electricity futures in Germany and the United Kingdom cascade through facility operating budgets into three distinct pricing tiers for streaming platform clients, with energy-intensive 8K finishing and AI-assisted workloads commanding premium rates while overflow capacity in Eastern Europe undercuts Western hubs.
Pricing Analysis
Service bundling separates turnkey virtual production packages—with dedicated LED volume stages and real-time engine supervision—from unbundled per-shot compositing work where clients supply their own editorial infrastructure. Project-based pricing dominates theatrical features and streaming miniseries, with retainers locking guaranteed capacity blocks for platform anchor clients. Price differentiation hinges on render farm scale and proprietary technology ownership, with fluid simulation specialists extracting premiums for disaster sequences. Cost compression in mid-tier episodic work is intensifying because streaming platforms are consolidating vendor relationships around fewer preferred suppliers. Independent advertising agencies and smaller broadcast networks exhibit the highest price sensitivity, while Netflix and Amazon Studios prioritize reliability over rate competition.
Supply Chain Analysis
Freight costs for specialized motion capture hardware and LED volume components from East Asian manufacturing centers add landed cost premiums to Spanish and Italian facility buildouts. Supply concentration rests on the United Kingdom, France, and Germany for senior compositing talent and pipeline technical directors, while Poland and the Czech Republic feed growing English-language capacity. Raw material dependencies include GPU clusters from NVIDIA and AMD, proprietary render engine licenses, and motion capture suit arrays. Single-source vulnerability around cloud render farm provisioning creates exposure when platform demand spikes collide with infrastructure capacity constraints. Distribution runs through direct retainer agreements with streaming platforms, bypassing traditional production service intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's transparency mandates for generative content create a compliance moat that favors established facilities with embedded metadata capture architectures, raising barriers for undercapitalized entrants lacking pipeline provenance systems.
For Market Incumbents: Anticipate platform consolidation by reserving dedicated supervisory teams and render capacity blocks under multi-project retainer structures before competitors lock preferred supplier status. Defend margin position through backward integration into proprietary AI-assisted rotoscoping tools that reduce junior compositor headcount. Monitor Eastern European facility expansion as a volume threat to mid-tier episodic work.
For New Entrants and Emerging Players: Capture overflow sequences from Paris and London facility clusters by positioning in Warsaw or Krakow with English-speaking talent pools and Polish Film Institute rebate eligibility. Target virtual production stage operation in Spain and Italy where Mediterranean-set streaming productions seek location substitution without travel logistics. Lead with LED volume technical expertise as a differentiated entry proposition.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized technology houses with proprietary simulation tools in Munich and Stuttgart, where automotive visualization pipelines converge with entertainment VFX. Long-term viability hinges on real-time engine integration capabilities and platform retainer contract visibility. Watch for inflection when streaming platforms accelerate guaranteed capacity block commitments beyond current London and Berlin concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Volume Infrastructure Buildout | Spain's Pinewood Studios Canarias captures Mediterranean-set productions seeking location substitution. |
| Proprietary AI Tool Development | Neural rendering integration reduces junior compositor dependency while raising EU AI Act compliance barriers. |
| Multi-Project Retainer Structuring | Netflix and Amazon Studios prioritize European facilities with guaranteed capacity and dedicated teams. |
| Eastern European Capacity Expansion | Poland and Czech Republic position for Western European overflow with lower operating costs. |
| Real-Time Engine Pipeline Convergence | Munich automotive visualization studios repurpose pipelines for gaming-engine entertainment VFX hybrids. |
Research Methodology
Document review covered facility financial disclosures, EU regulatory filings, and streaming platform procurement patterns, complemented by interviews with VFX facility executives, pipeline technical directors, platform commissioning editors, and tax incentive scheme administrators. Secondary validation drew from British Film Institute expenditure reports, Centre national du cinéma rebate statistics, and hyperscaler content spend disclosures. Bottom-up project pipeline enumeration and top-down platform budget allocation analysis were triangulated against facility capacity utilization estimates.
Segment-level value outputs were generated across service type, end user, distribution channel, and technology stack dimensions over the projection horizon. CAGRs were derived from facility investment cycles, platform commissioning trajectory modeling, and tax incentive scheme evolution assumptions. Render farm energy cost volatility and AI-assisted workflow penetration rates served as key forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to streaming platform budget reallocation, EU AI Act enforcement intensity, and render farm electricity price trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Media and Entertainment Market
Digital Media
Indonesia Digital Media Market
Digital Media
Online Gambling Market
Digital Media
Media Coding Service Market
Digital Media
Middle East Gaming Market
Digital Media
United Kingdom Webtoons Market
Digital Media
Professional Dubbing Services Market
Digital Media
ACGN Subculture Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Digital Effects Services Market
Digital Media
Social TV Market
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
United States Sports Betting Market
Digital Media
Digital Video Content Market
Digital Media
Saudi Arabia Webtoons Market