
 Music Streaming Market | 2026-2036
Music Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
Music Streaming Market Intelligence
Young adult subscribers is collapsing the historical dominance of family-plan buyers as the primary revenue archetype in music streaming. Spotify sustains its product specialization through algorithmic playlist infrastructure that anchors listener retention across diverse geographies. Tencent Music dominates Greater China through social entertainment features that extend beyond pure audio playback into karaoke and live streaming. Amazon Music competes by bundling its service with Prime membership, leveraging e-commerce channel control to reduce customer acquisition costs.
Music streaming denotes the digital transmission of audio content via internet protocol to end-user devices, typically employing adaptive bitrate protocols between 96 kbps and 320 kbps to balance fidelity against variable network conditions, with primary commercial purpose being on-demand access to licensed catalogs without permanent ownership. Subscription streaming generates the dominant share of industry revenue while ad-supported streaming captures emerging-market expansion where payment infrastructure remains underdeveloped. Smart speakers represent the fastest-growing device category as voice-activated discovery reshapes household listening patterns, though smartphones retain the largest installed base.
The US Copyright Office and EU directives on digital single market copyright shape royalty structures and platform licensing obligations, while India's Copyright Act amendments under Ministry of Electronics and Information Technology oversight impose local content storage mandates that alter data architecture decisions. Brazil's ANCINE content quota regulations and South Korea's KCC broadcasting standards further fragment compliance requirements across operational jurisdictions. Stakeholders must monitor evolving mechanical royalty rate proceedings and emerging market localization mandates to calibrate content investment and infrastructure deployment strategies.
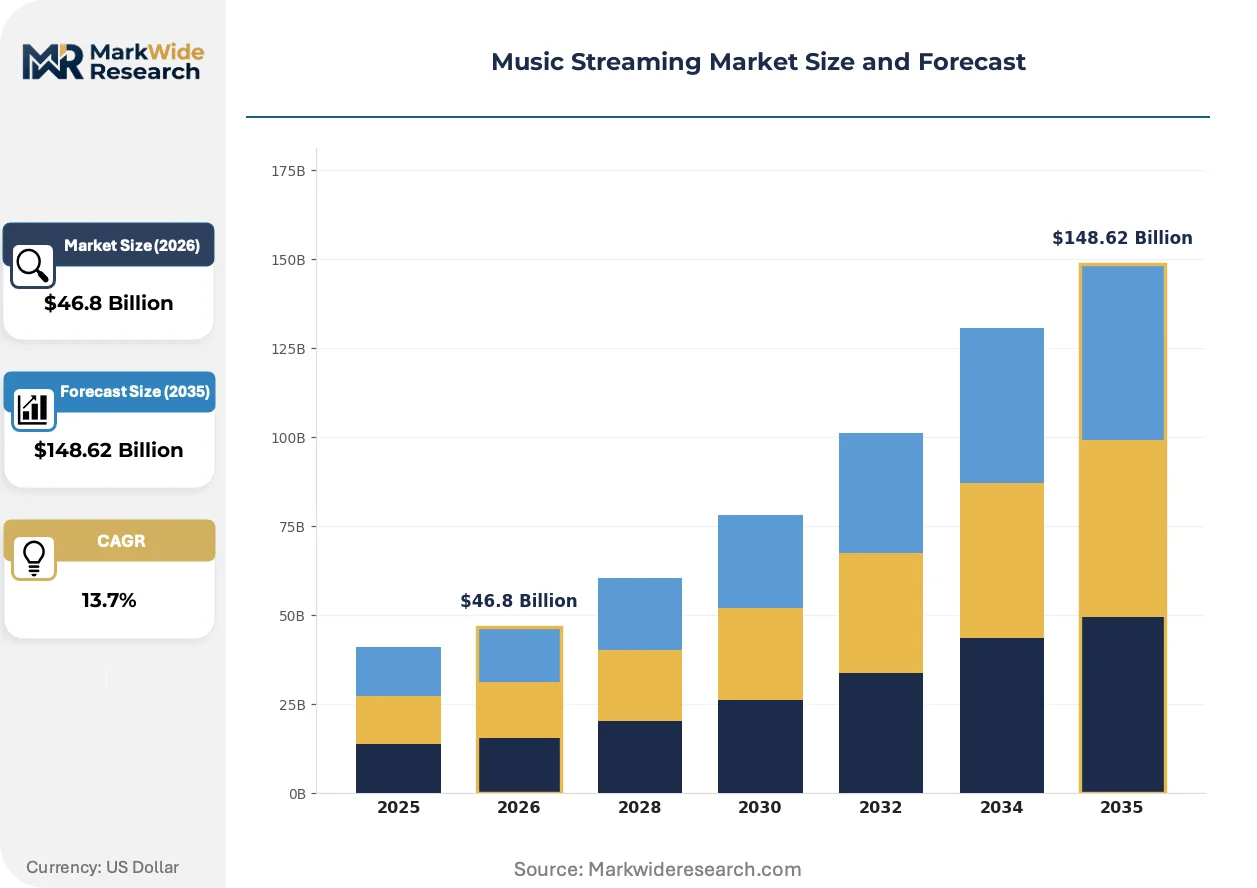
Market Dynamics
Algorithmic personalization infrastructure is compressing subscriber churn rates while fragmenting royalty pools across territorial licensing regimes, forcing platform operators to rebuild content recommendation engines around local repertoire mandates.
Growth Catalysts
- EU Digital Single Market Copyright Directive:Article 17 obligations are accelerating publisher negotiations and clearing backlog licensing disputes across member states.
- Smart speaker voice activation:Household penetration of voice-controlled audio discovery is expanding total addressable listening hours beyond smartphone-bound consumption.
- Brazil's payment infrastructure modernization:Pix instant payment rails are reducing subscription friction in Latin America's largest addressable market.
Market Restraints
- Mechanical royalty rate volatility:US Copyright Royalty Board proceedings create structural uncertainty in cost-of-goods calculations for on-demand streaming.
- Data localization mandates:India's Ministry of Electronics and Information Technology content storage requirements are fragmenting cloud architecture economics.
- Terrestrial radio substitution:Free ad-supported broadcast audio retains durable listener hours in vehicle and workplace environments.
Strategic Opportunities
- Nigeria's mobile-first subscriber base:Underpenetrated formal payment enrollment creates first-mover advantage for telco-bundled streaming partnerships.
- Social entertainment convergence:Karaoke and live streaming feature integration is expanding average revenue per user beyond pure audio subscription.
- South Korea's KCC broadcasting standards:Regulatory clarity on content categorization is enabling platform localization with reduced compliance ambiguity.
Industry Challenges
- ML engineer scarcity:Recommendation algorithm talent competition with ad-tech and fintech sectors is inflating compensation costs.
- Legacy label contract renegotiation:Historical most-favored-nation clauses complicate territory-specific pricing flexibility.
- Cross-border copyright clearance:Mechanical and performance rights fragmentation across PROs delays catalog launches in new markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Music Streaming Market |
| Market Size in 2026 | $46.8 Billion |
| Market Size in 2035 | $148.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Free Streaming, Subscription Streaming, Ad-Supported Streaming, Hybrid Streaming Device Type: Smartphones, Smart Speakers, Personal Computers, Tablets, Connected TVs Music Genre: Pop, Rock, Jazz, Classical, Hip Hop, Electronic User Demographic: Teens, Young Adults, Middle Aged, Seniors |
| Companies Covered | Spotify, Tencent Music, Apple Music, Amazon Music, YouTube Music, NetEase, Yandex Music, Deezer, Tidal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Music Streaming Market Strategic Shifts & Innovations
Audio delivery infrastructure is compressing latency thresholds while expanding immersive format adoption, reshaping how platforms differentiate through technical performance rather than catalog breadth alone.
Spatial audio processing is miniaturizing. Binaural rendering engines now operate on standard smartphone chipsets without dedicated hardware acceleration. Mid-tier device manufacturers in South Korea and China are adopting the format as a default output standard. This capability compression is collapsing the premium tier's historical exclusivity on immersive listening experiences.
EU directives on digital single market copyright are mandating transparency in algorithmic recommendation systems. Platforms must now disclose ranking parameters and provide alternative non-personalized playlist options. Independent artist collectives in Germany and France are leveraging these disclosure requirements to negotiate fairer playlist placement protocols.
Subscription bundling is displacing standalone service signups. Telecommunications operators in Brazil and Nigeria are packaging streaming access with mobile data allowances, capturing subscribers before standalone platform registration. This channel shift is concentrating customer acquisition economics around carrier relationship management rather than direct-to-consumer marketing spend.
Music Streaming Market Segmentation
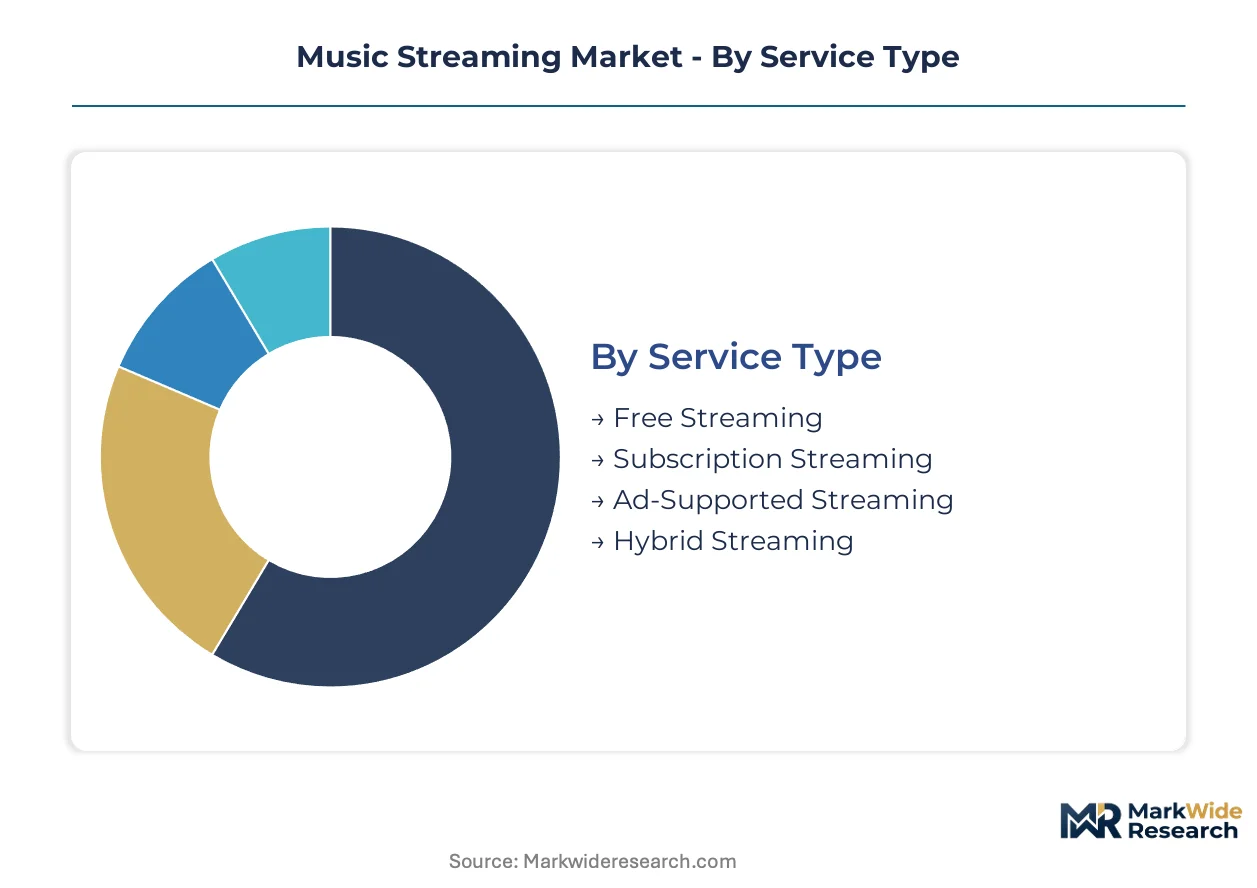
Segmentation in music streaming reveals how platform economics bifurcate between high-ARPU subscription households and ad-supported mass-market penetration. Each dimension exposes distinct channel strategies, from telco bundling in emerging markets to voice-activated discovery in mature economies.
Service Type:
Free streaming flows through ad-tech exchanges and carrier partnerships. Subscription streaming routes through direct-to-consumer billing and Prime-style retail bundles. Hybrid models split acquisition and retention across both channels.
- Free Streaming:Ad-funded access with limited skips and lower bitrate tiers, concentrating demand in Nigeria and India where Pix and UPI payment rails remain underpenetrated among informal workers.
- Subscription Streaming:Premium tier delivering lossless audio and offline downloads, anchoring revenue concentration in US and South Korean households with established credit infrastructure and smart speaker penetration.
- Ad-Supported Streaming:Freemium gateway funded by programmatic audio advertising, scaling fastest in Brazil where ANCINE content quotas drive local catalog investment that attracts brand spend.
- Hybrid Streaming:Blended model combining subscription base with supplemental ad inventory, gaining traction among price-sensitive young adult cohorts in European markets facing inflation pressure.
By volume, ad-supported streaming leads. By growth pace, hybrid models are climbing the fastest.
Device Type:
Cost tiers separate flagship smartphone subscribers from entry-level device users. Smart speaker households command premium pricing. Tablet and connected TV segments chase margin through family-plan multi-seat licensing.
- Smartphones:Dominant access point employing adaptive bitrate protocols between 96-320 kbps, with demand concentrating in Brazil and Nigeria where mobile-first consumption patterns have eliminated desktop intermediation entirely.
- Smart Speakers:Voice-activated discovery hardware expanding total addressable listening hours beyond screen-bound interaction, steepest expansion trajectory in US and South Korean households with embedded Alexa and Naver Clova ecosystems.
- Personal Computers:Legacy access point for high-fidelity desktop listening and playlist curation, retaining niche concentration among professional audio editors and classical music archivists in Germany and France.
- Tablets:Secondary mobile screen for kitchen and bedroom ambient listening, scaling through family-plan multi-seat allowances in middle-income households across Italy and Spain.
- Connected TVs:Visual-first music video and concert streaming endpoint, capturing living-room co-viewing sessions in UK and Japanese markets with strong YouTube Music integration.
Smartphones dominate installed base. Smart speakers are gaining share fastest in revenue per active hour.
Music Genre:
Application context drives genre segmentation. Pop and electronic soundtrack commuting and exercise. Classical and jazz anchor focus-work and aging demographic retention. Hip hop and rock fragment across regional identity markets.
- Pop:Globally standardized catalog with shortest path to playlist placement, concentrating streaming hours among teens and young adults across all measured geographies.
- Rock:Catalog-heavy genre with durable back-catalog monetization through heritage artist estates, strongest retention power among middle-aged subscribers in UK and US.
- Jazz:Niche genre with high engagement duration per session, scaling through algorithmic discovery features in French and Japanese markets with established live venue ecosystems.
- Classical:Metadata-intensive genre requiring composer-orchestra-soloist indexing, concentrated demand among seniors and high-income professionals in German and Austrian markets.
- Hip Hop:Youth-culture dominant genre with regional variant proliferation, fastest catalog growth in South Korea and Nigeria where local language rap subgenres drive platform differentiation.
- Electronic:DJ-culture and dance-floor oriented genre with strong festival tie-in monetization, expanding most quickly in Brazilian and Dutch markets with embedded event promoter partnerships.
Pop leads in total stream count. Electronic and hip hop are expanding most quickly in emerging market penetration.
User Demographic:
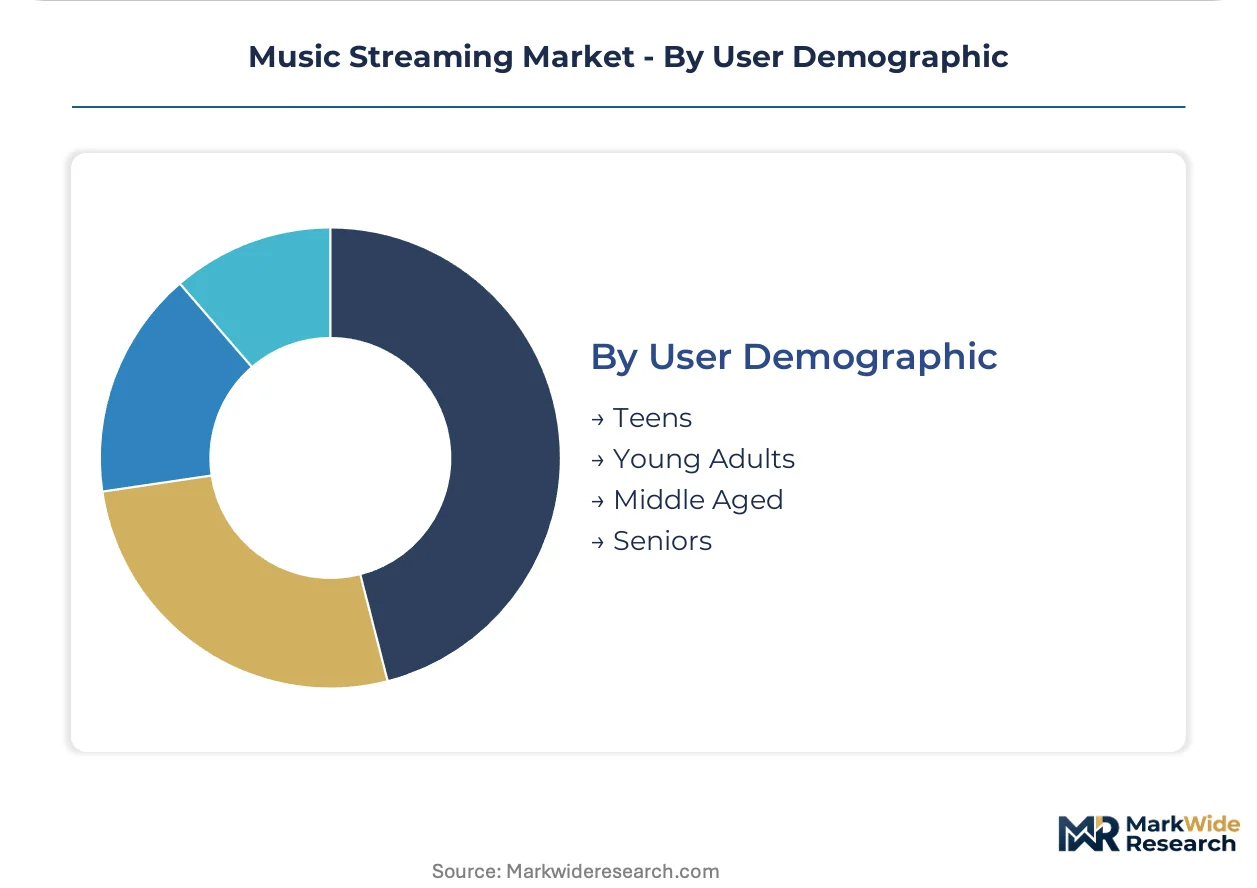
Customer type segmentation aligns pricing power with life-stage disposable income. Young adults collapse historical family-plan dominance. Senior cohorts represent undermonetized retention opportunity.
- Teens:Ad-supported and family-plan dependent segment with low direct payment conversion, concentrating in US and South Korean households where parental subscription sponsorship is culturally normative.
- Young Adults:Mobile-first solo subscribers with highest churn risk and platform-switching propensity, steepest expansion trajectory in Nigeria and Brazil where telco-bundled partnerships capture pre-formal-banking cohorts.
- Middle Aged:Stable subscription tenure with lower price sensitivity and higher family-plan anchoring, revenue concentration in German and Japanese markets with established credit-card autopay infrastructure.
- Seniors:Underpenetrated cohort with device-friction barriers and catalog nostalgia preferences, emerging target for simplified voice-interface onboarding in UK and Australian markets with aging population demographics.
Young adults lead in new subscriber acquisition velocity. Seniors represent the most underpenetrated expansion reservoir.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform licensing infrastructure concentrates in jurisdictions with mature copyright frameworks and high smartphone penetration. The United States, Germany, Brazil, South Korea, and Nigeria each present distinct regulatory and demand configurations that shape operator economics.
United States
Credit-card autopay infrastructure and smart speaker household penetration drive subscription revenue concentration. The US Copyright Royalty Board proceedings on mechanical royalty rates create structural uncertainty in platform cost calculations. Los Angeles and Nashville anchor music publishing and recording industry clusters where label negotiations determine catalog availability.
Germany
EU Digital Single Market Copyright Directive Article 17 obligations accelerate publisher licensing negotiations across member states. The Federal Cartel Office scrutinizes platform market power in streaming distribution. Berlin hosts independent artist collectives leveraging algorithmic transparency mandates to negotiate playlist placement protocols.
Brazil
Pix instant payment rails reduce subscription friction among informal workers previously excluded from formal banking. ANCINE content quota regulations mandate local repertoire investment that attracts domestic brand advertising spend. São Paulo concentrates music industry infrastructure and telco partnership negotiations for bundled streaming distribution.
South Korea
KCC broadcasting standards provide regulatory clarity on content categorization that reduces compliance ambiguity for platform localization. Naver Clova smart speaker ecosystems expand voice-activated discovery beyond smartphone interaction. Seoul anchors K-pop production clusters where local language rap subgenres drive platform differentiation strategies.
Nigeria
Mobile-first consumption patterns have eliminated desktop intermediation entirely among young adult subscribers. Underpenetrated formal payment enrollment creates first-mover advantage for telco-bundled streaming partnerships. Lagos concentrates Afrobeats production infrastructure where local promoter partnerships drive festival tie-in monetization.
Music Streaming Market Key Industry Players
Concentration sits with algorithmic personalization specialists and ecosystem-integrated platforms that leverage bundling economics. The vendor structure fragments across pure-play audio streaming services, technology conglomerates with media distribution arms, and regional social entertainment platforms. Three archetypes dominate: Western subscription-first operators, Asia-Pacific social entertainment integrators, and e-commerce bundled services. Competitive moves center on carrier partnership exclusivity and voice interface integration.
Within the Western subscription tier, Spotify and Apple Music exemplify algorithmic-first and hardware-integrated positioning respectively. Tencent Music anchors the Asia-Pacific social entertainment archetype where karaoke and live streaming extend beyond pure audio playback. Amazon Music occupies the ecosystem-bundled position, leveraging Prime membership economics to reduce customer acquisition costs.
| Leading Market Players |
|---|
| Spotify |
| Tencent Music |
| Apple Music |
| Amazon Music |
| YouTube Music |
| NetEase |
| Yandex Music |
| Deezer |
| Tidal |
| Others |
Cost & Logistics Intelligence
Per-stream royalty contracts lock in supply access to major label catalogs while anchoring cost visibility across the analysis window. These agreements tether platform margins to mechanical rate proceedings in the United States and publisher negotiations in Germany, creating pricing rigidity that resists rapid tier adjustment.
Pricing Analysis
The US Copyright Royalty Board dictates the pricing tier structure through mechanical royalty rate proceedings that compress margin flexibility at the standard subscription level. Three-tier pricing structure across premium, standard, and economy levels segments buyers by audio fidelity demand and offline download requirements. Cost compression in the ad-supported tier is intensifying because programmatic CPM softness in Brazil and Nigeria reduces effective revenue per stream. Family-plan subscribers in South Korea and the United States exhibit lowest price sensitivity, while young adult solo subscribers in emerging markets demonstrate highest churn elasticity.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for smart speaker hardware destined for US and European households. Content delivery infrastructure concentrates in the United States, Ireland, and Singapore where hyperscaler data centers anchor streaming latency performance. Raw material dependencies span lithium-ion battery cells for portable speakers, rare earth elements for voice-recognition chipsets, and optical fiber for backbone transmission. Single-source vulnerability sits with concentrated cloud compute providers. Distribution runs through telecommunications carrier partnerships in Brazil and Nigeria, direct-to-consumer app stores in mature markets, and retail bundling via e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where playlist algorithm network effects create switching costs that cement subscriber retention. Regulatory entrenchment through copyright licensing frameworks further deepens incumbent protection.
For Market Incumbents: Consolidate algorithmic personalization capabilities through targeted ML engineering hires in Berlin and Seoul, countering talent competition from ad-tech and fintech sectors. Deepen carrier exclusivity arrangements in Nigeria and Brazil before telco-bundled distribution channels mature. Secure mechanical royalty rate certainty through early engagement with US Copyright Royalty Board proceedings.
For New Entrants and Emerging Players: CE marking fast-track for smart speaker hardware enables rapid European market entry ahead of established voice ecosystem lock-in. White-space concentration sits with senior demographic onboarding in the United Kingdom and Australia, where simplified voice interfaces remain underdeveloped. Target social entertainment feature integration—karaoke and live streaming—to differentiate from pure-play audio incumbents in Greater China and Southeast Asia.
For Investors and Strategic Acquirers: Capital is best deployed toward platform operators with demonstrated telco bundling scale in underpenetrated formal payment markets. Long-term viability rests on algorithmic retention infrastructure and regional licensing completeness rather than catalog breadth alone. Watch mechanical royalty rate determination outcomes as inflection signals for margin structure recalibration across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Personalization Investment | Spotify's playlist infrastructure demonstrates retention power across diverse geographies. |
| Telco Bundling Partnership | Carrier exclusivity in Brazil and Nigeria captures subscribers before standalone registration. |
| Social Entertainment Integration | Tencent Music's karaoke features extend ARPU beyond pure audio subscription tiers. |
| Voice Interface Development | Naver Clova and Alexa ecosystems reshape household discovery patterns in South Korea and the US. |
| Regional Licensing Compliance |
Research Approach
The analysis maps subscription streaming, ad-supported streaming, and social entertainment platforms, each validated through streaming platform executives, record label licensing directors, telecommunications carrier partnership managers, and independent artist collective representatives. Primary interview findings triangulate against secondary sources including US Copyright Office filings, EU Digital Single Market directive documentation, ANCINE regulatory releases, and KCC broadcasting standards. Bottom-up subscriber projections reconcile with top-down market sizing across service type, device category, and geographic clusters.
Consistency checks validate volume and value outputs against external benchmarks including carrier-reported bundled subscriber additions and platform-disclosed premium subscriber counts. Segmentation dimensions span service tier, device type, music genre, and user demographic cohorts across the projection horizon. CAGRs derive from subscriber growth trajectories, ARPU evolution by market maturity, and ad-load monetization scaling in emerging economies. Forecast inputs incorporate Pix payment rail penetration rates in Brazil, smart speaker household adoption curves, and mechanical royalty rate proceeding outcomes.
Underlying assumptions cover stable copyright licensing frameworks, continued mobile-first consumption pattern entrenchment, and payment infrastructure modernization in target emerging markets, with deviation risk concentrated in regulatory rate determinations, data localization mandate expansion, and terrestrial radio substitution resilience. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Mexico Commercial Printing Market
Media and Entertainment
Cloud TV Market
Media and Entertainment
Asia-Pacific Animation Market
Media and Entertainment
In-Flight Advertising Market
Media and Entertainment
Online Casino Market
Media and Entertainment
Virtual Sports Market
Media and Entertainment
Subscription Video on Demand (Svod) Market
Media and Entertainment
Music Publishing Market
Media and Entertainment
Digital TV Market
Media and Entertainment
Programmatic Advertising Market
Media and Entertainment
Video Production Market
Media and Entertainment
Global Exhibition Market
Media and Entertainment
Sports Streaming Platform Market
Media and Entertainment
Sports Graphics Market
Media and Entertainment
APAC Media and Entertainment Market
Media and Entertainment
Video Wall Market