
 Digital Entertainment in the Home Market | 2026-2036
Digital Entertainment in the Home Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Entertainment in the Home Market Insights
Over-the-top streaming distribution is reconfiguring how content reaches living rooms worldwide. Amazon.com, Inc. leverages its Prime ecosystem to anchor subscription retention across device categories. Samsung Electronics dominates smart TV hardware through vertical control over display panels and proprietary operating systems. Sony Corporation specializes in premium game console entertainment that extends into streaming service bundling.
Digital entertainment in the home encompasses connected hardware and software systems delivering audiovisual content through internet protocol television, adaptive bitrate streaming, and cloud gaming infrastructure. These systems rely on HEVC and AV1 compression standards, 4K HDR display protocols, and sub-50ms latency thresholds to enable real-time interactive experiences. Smart TVs and streaming devices lead installed base expansion while game consoles capture the highest per-user revenue pools. Free ad-supported tiers are displacing monthly subscriptions among price-sensitive young adults, though annual subscriptions retain stronger lifetime value from family demographics.
FCC broadband labeling rules and EU GDPR cross-border data frameworks shape how platforms collect viewing data and price services across jurisdictions. The EU AI Act introduces content recommendation transparency requirements that affect algorithmic personalization engines. Stakeholders must monitor how interoperability mandates from regulators redefine platform control over proprietary content ecosystems.
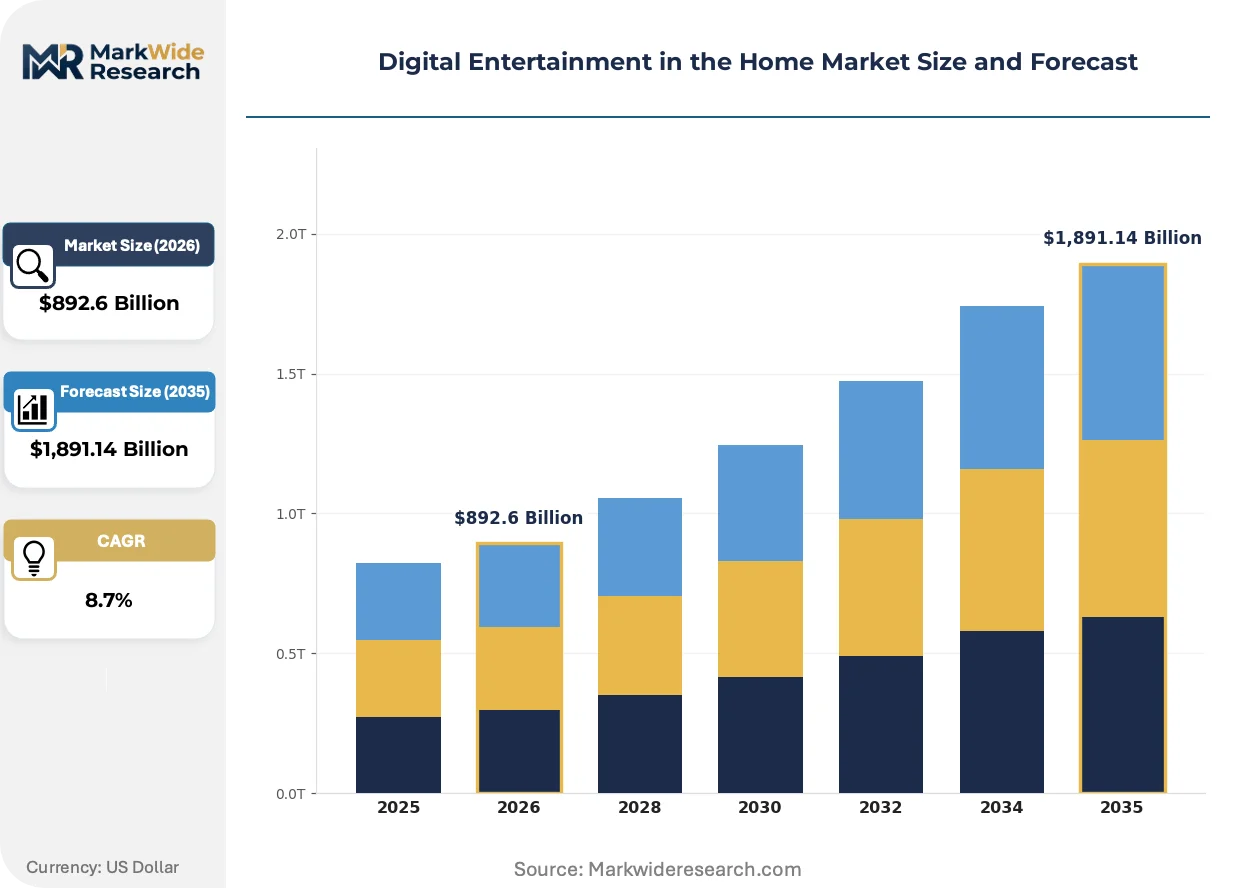
Market Dynamics
Adaptive bitrate streaming protocols are collapsing latency thresholds for interactive content delivery, forcing hardware manufacturers to redesign encoding pipelines around sub-50 millisecond performance benchmarks that enable cloud gaming and real-time social viewing experiences.
Growth Catalysts
- HEVC and AV1 compression standards:These codecs reduce bandwidth requirements by fifty percent versus legacy H.264, enabling 4K HDR streaming over mid-tier broadband connections in suburban United States households.
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract smart TV and streaming device assembly, lowering hardware costs for price-sensitive consumers entering the connected entertainment ecosystem.
- Cloud gaming infrastructure:Edge server deployments by telecommunications operators eliminate console hardware dependencies, expanding addressable audiences to smartphone-casting users in Southeast Asian markets.
Market Restraints
- Display panel supply concentration:Korean and Chinese manufacturers control over ninety percent of OLED and advanced LCD substrate production, creating input cost volatility for smart TV assemblers during semiconductor cycle downturns.
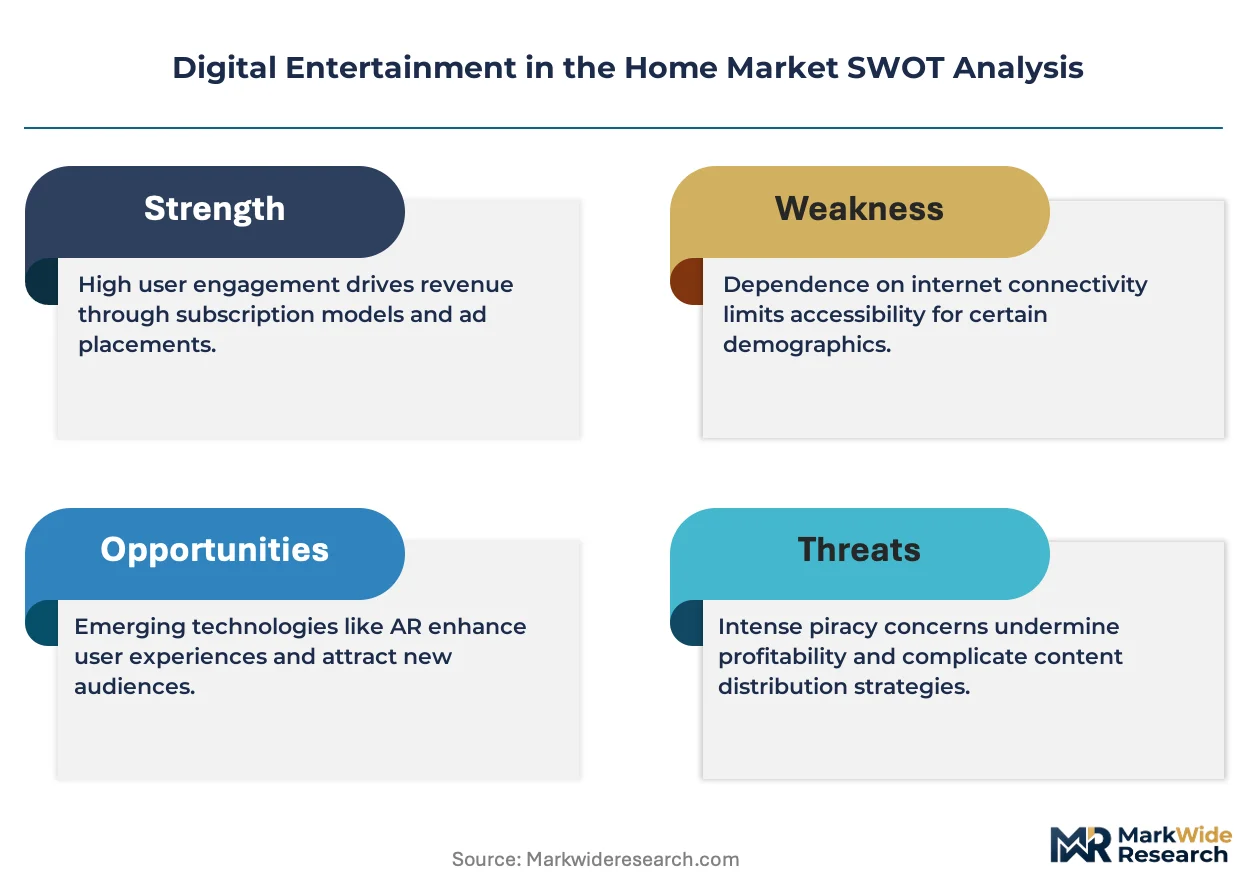
- EU AI Act recommendation transparency:Algorithmic explainability mandates increase engineering overhead for personalization engines, slowing deployment of next-generation content discovery features across European markets.
- Free ad-supported television substitution:FAST platforms capture younger demographics unwilling to commit to monthly subscriptions, compressing average revenue per user for premium streaming services.
Strategic Opportunities
- Brazil's underserved broadband households:Fixed wireless access rollouts by regional telecommunications providers create first-mover advantages for low-bandwidth-optimized streaming bundles in Latin America's largest market.
- Immersive audio-visual convergence:Spatial audio processing combined with light-field display technologies enable premium home cinema experiences that differentiate high-ASP product tiers from commodity streaming hardware.
- South Korea's K-content export infrastructure:Government-backed production subsidies and international distribution agreements amplify demand for Korea-originated streaming catalogs across Southeast Asian subscriber bases.
Industry Challenges
- Legacy HDMI interoperability:Fragmented certification across HDMI 2.1 feature subsets creates consumer confusion and elevated return rates for streaming devices connecting to older television hardware.
- Cross-border content licensing complexity:Territorial rights windows vary by jurisdiction, forcing platform operators to maintain redundant content libraries and geo-fencing infrastructure that inflate operational overhead.
- Silicon design talent scarcity:System-on-chip architectures for media processing require specialized video codec engineering expertise concentrated among a limited pool of semiconductor design houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Entertainment in the Home Market |
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $1,891.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart TVs, Streaming Devices, Blu-ray Players, Game Consoles Content Type: Movies, Series, Live Sports, Music Subscription Model: Monthly Subscription, Pay-Per-View, Free Ad-Supported, Annual Subscription User Demographics: Families, Young Adults, Seniors, Students |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, Panasonic Corporation, TCL Technology Group Corporation, Hisense, Amazon.com, Inc., Google LLC, Roku, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Entertainment in the Home Market Trends and Innovations
Cloud-native content delivery architectures are dissolving traditional boundaries between gaming, streaming, and social media consumption. Three concurrent developments are restructuring how entertainment platforms architect their technology stacks and monetization models.
Edge computing nodes positioned within last-mile networks are collapsing the distance between content origin and consumer display. Telecommunications operators in Japan and South Korea deploy micro-data centers inside central office facilities, enabling interactive streaming experiences previously restricted to locally-rendered game consoles. This infrastructure compression eliminates the hardware tax that previously gated premium entertainment access.
The EU AI Act's transparency requirements for algorithmic recommendation systems are mandating explainable personalization interfaces. Streaming platforms must now disclose ranking factors and provide user-controlled filtering options, increasing frontend development complexity while reducing engagement optimization flexibility. German and French regulators are already enforcing audit schedules that quarterly review recommendation engine fairness metrics.
Subscription fatigue among millennial and Generation Z households is fragmenting entertainment budgets across multiple micro-services rather than consolidating around single-platform mega-bundles. Young adults in urban United States markets rotate monthly between three to four specialized services, canceling and resubscribing based on content release calendars rather than maintaining continuous memberships. This behavioral churn forces platforms to front-load marketing spend around tentpole releases rather than amortizing acquisition costs across annual billing cycles.
Digital Entertainment in the Home Market Segmentation
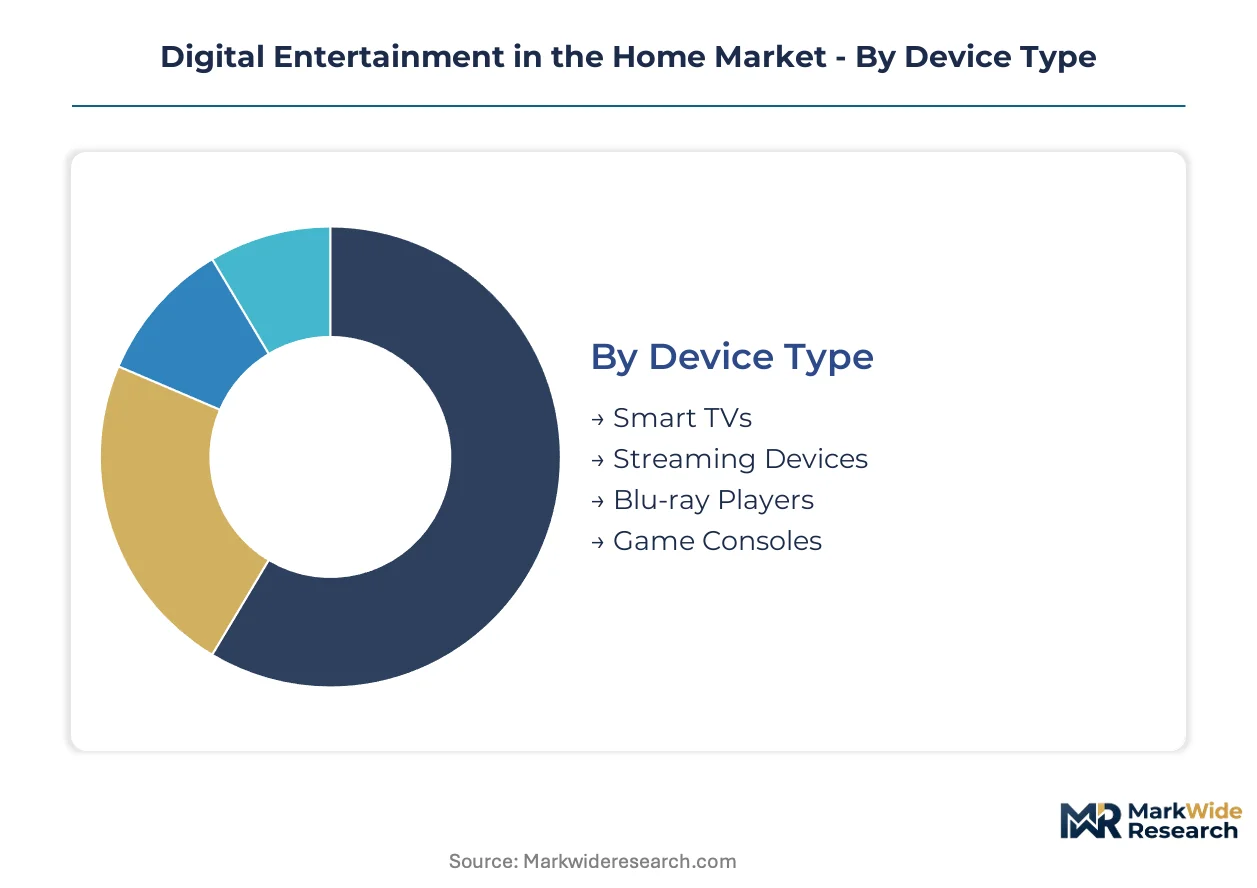
Device capabilities and content consumption patterns diverge sharply across household configurations in digital home entertainment. Subscription model preferences split along generational fault lines, forcing platforms to engineer flexible billing architectures. Understanding these segment boundaries clarifies where engineering investments and licensing expenditures generate differentiated returns.
Device Type:
The use-case spectrum spans passive lean-back viewing to interactive gaming sessions demanding sub-50 millisecond latency.
- Smart TVs:Integrated operating systems from Samsung Electronics and LG Electronics enable direct streaming without external hardware. Korean and Chinese display panel manufacturers supply over ninety percent of advanced LCD and OLED substrates, concentrating cost volatility in Seoul and Shenzhen production clusters.
- Streaming Devices:Compact HDMI dongles and set-top boxes from Roku and Amazon Fire TV extend connectivity to legacy television hardware. Demand concentrates in suburban United States households upgrading older displays without full television replacement cycles.
- Blu-ray Players:Physical media playback hardware retains niche adoption among audiovisual enthusiasts seeking uncompressed bitrates for home cinema installations.
- Game Consoles:Sony PlayStation and Microsoft Xbox systems anchor premium entertainment with highest per-user revenue pools through software and service bundling.
Established volume favors Smart TVs; emerging adoption favors Streaming Devices.
Content Type:
Cost tier stratification separates premium live rights from commoditized on-demand libraries.
- Movies:Theatrical window compression accelerates streaming availability, collapsing traditional release chronologies. Studio direct-to-consumer strategies concentrate investment in franchise properties with built-in audience recognition.
- Series:Binge-release formats dominate subscriber acquisition campaigns, though weekly episodic drops retain engagement longevity for flagship productions. Korean drama exports through South Korea's K-content infrastructure expand fastest across Southeast Asian markets.
- Live Sports:Exclusive broadcasting rights command premium subscription tiers with annual contractual commitments rather than monthly flexibility.
- Music:Audio streaming integrates into video platform bundles as secondary value-add rather than standalone revenue driver.
Revenue concentration sits with Live Sports; subscriber growth velocity favors Series.
Subscription Model:
Customer type determines payment tolerance and churn propensity across billing frequencies.
- Monthly Subscription:Standard recurring revenue foundation enabling service rotation behavior among urban millennials. Young adults in United States markets cycle through three to four specialized services based on content release calendars.
- Pay-Per-View:Event-based pricing for live sports and premium theatrical releases captures non-subscriber spending. Families demonstrate highest conversion rates for tentpole sporting events requiring single-purchase access.
- Free Ad-Supported:FAST platforms displace paid commitments among price-sensitive demographics, compressing average revenue per user for premium tiers.
- Annual Subscription:Upfront payment locks reduce churn and improve lifetime value calculations for family demographic segments.
Margin protection relies on Annual Subscription; audience expansion depends on Free Ad-Supported.
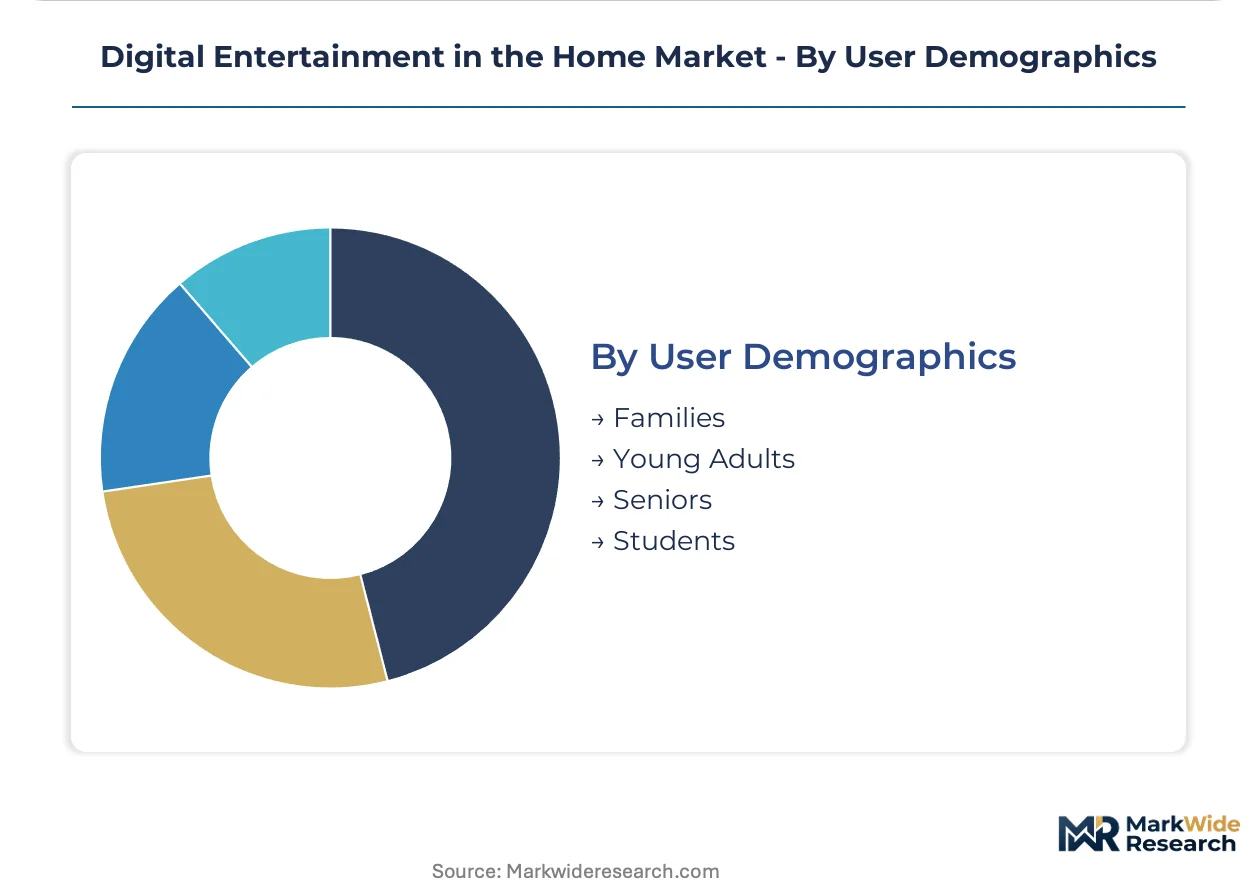
User Demographics:
Application context varies from multi-user household coordination to individual mobile casting.
- Families:Parental control requirements and content rating filters drive smart TV operating system selection. Bundled children's programming and educational content libraries influence platform stickiness.
- Young Adults:Smartphone-first consumption with casting dependencies shapes hardware preferences toward streaming device compatibility.
- Seniors:Simplified interface designs and voice control integration reduce navigation friction for less technologically experienced users.
- Students:Budget constraints and shared credential usage patterns concentrate demand in lowest-price subscription tiers or password-sharing arrangements.
Platform investment prioritizes Families; acquisition cost efficiency targets Young Adults.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in South Korean and Japanese hardware exports while content licensing arbitrage favors United States-based streaming platforms operating across multiple territories.
United States
FCC broadband infrastructure investments expand addressable households for 4K HDR streaming services. The Commission's broadband labeling rules mandate transparent speed disclosures that reshape how platforms price service tiers. Silicon Valley and Seattle technology clusters anchor cloud gaming infrastructure development and adaptive bitrate streaming protocol engineering.
China
Smart TV penetration and 5G home networks reshape consumption patterns across tier-one cities. MIIT standards for home networking equipment accelerate interoperability between domestic display manufacturers and telecommunications operators. Shenzhen and Beijing production clusters concentrate advanced LCD substrate manufacturing and streaming device assembly operations.
South Korea
Government-backed K-content export subsidies amplify demand for Korea-originated streaming catalogs across Southeast Asian markets. The country's national broadcasting regulator coordinates with MFDS on content rating harmonization for cross-border distribution. Seoul metropolitan area houses Samsung Electronics and LG Electronics headquarters commanding vertical control over display panel supply chains.
Germany
EU AI Act recommendation transparency requirements increase engineering overhead for personalization engines deployed across European subscriber bases. The national media regulator enforces quarterly audit schedules reviewing algorithmic fairness metrics for streaming platforms. Munich and Berlin technology hubs concentrate audio-visual processing semiconductor design talent.
Brazil
Fixed wireless access rollouts by regional telecommunications providers create first-mover advantages for low-bandwidth-optimized streaming bundles. ANATEL spectrum allocations for 5G fixed wireless enable competitive alternatives to fiber infrastructure in underserved metropolitan peripheries. São Paulo state anchors Latin American streaming platform operations and Portuguese-language content production facilities.
Digital Entertainment in the Home Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling critical inputs. The vendor base stratifies between consolidated display panel manufacturing and fragmented streaming device assembly. Three archetypes dominate: ecosystem platform operators bundling hardware and content, display technology specialists capturing upstream margin pools, and connectivity enablers bridging legacy hardware to IP-based delivery. Competitive moves concentrate on exclusive content licensing arrangements and proprietary operating system development.
Among Asia-Pacific hardware manufacturers, Samsung Electronics, LG Electronics, and Sony Corporation exemplify the integrated platform archetype combining display manufacturing with proprietary content ecosystems. Amazon.com, Inc. represents the ecosystem bundling approach anchoring subscription retention across device categories. These companies occupy positions spanning the value chain from semiconductor design through consumer-facing service aggregation.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Panasonic Corporation |
| TCL Technology Group Corporation |
| Hisense |
| Amazon.com, Inc. |
| Google LLC |
| Roku, Inc. |
| Others |
Pricing and Supply Chain Analysis
Korean and Chinese display panel manufacturers control over ninety percent of OLED and advanced LCD substrate production, anchoring margin capture upstream while downstream streaming hardware assemblers compete on thin assembly economics. This concentration transfers pricing power to Seoul and Shenzhen production clusters, forcing device brands to differentiate through software integration and content bundling rather than component cost advantage.
Pricing Analysis
Configured-to-order smart TV pricing commands substantial premiums over standard SKUs, with panel size tiering and operating system customization driving spreads. Three-tier pricing structure across premium, standard, and economy levels segments households by willingness to pay for display technology and content ecosystem depth. Price differentiation hinges on HDR certification tier and voice control integration sophistication. Cost compression in entry-level streaming devices is intensifying because India's PLI scheme attracts aggressive hardware assembly investment. Young adults exhibit highest price sensitivity, rotating between promotional subscription tiers, while families locked into annual commitments show lowest elasticity.
Supply Chain Analysis
Hon Hai Precision Industry, TPV Technology, and MTC Electronics hold dominant contract manufacturing capacity for streaming devices and smart TV assembly. Display panel sourcing concentrates in South Korea, China, and Taiwan, with advanced OLED substrates captive to Samsung Display and LG Display operations. Raw material dependencies include indium tin oxide for transparent electrodes, rare earth phosphors for quantum dot enhancement, and high-purity silicon for system-on-chip fabrication. Single-source vulnerability around Korean OLED substrate supply creates disruption exposure during semiconductor cycle downturns. Distribution runs through electronics retail chains, direct-to-consumer platform storefronts, and telecommunications operator bundling programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where proprietary content ecosystems and device-software integration create switching costs that cement subscriber retention across hardware refresh cycles.
For Market Incumbents: Entrench platform stickiness through exclusive content licensing arrangements that extend beyond theatrical windows, while deepening backward integration into display panel supply through captive production or long-term offtake agreements with Korean substrate manufacturers. FAST platform substitution and cloud gaming infrastructure commoditization represent primary threats to premium subscription tiers. Vertical integration into edge server deployment with telecommunications operators offers defensive control over latency-sensitive interactive experiences. For New Entrants and Emerging Players: Brazil's underserved broadband households present the most penetrable geographic white space, where fixed wireless access rollouts by regional telecommunications providers create first-mover opportunities for low-bandwidth-optimized streaming bundles. Immersive audio-visual convergence through spatial audio and light-field display technologies offers premium tier differentiation against commodity hardware incumbents. Partnership-led go-to-market approaches with regional telecommunications operators minimize customer acquisition costs in infrastructure-constrained markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed streaming platform operators carrying substantial content library amortization burdens and subscriber acquisition cost loads. Long-term viability across a five-to-ten year horizon favors platforms with demonstrated annual subscription retention in family demographic segments and proprietary hardware distribution channels. Acquisition targets should demonstrate exclusive sports rights positioning or K-content export infrastructure leverage. Monitor quarterly churn rates among annual subscription cohorts as inflection indicator for platform health deterioration.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Licensing | Secures multi-year sports broadcasting rights from FIFA and regional leagues to anchor premium tier subscriptions. |
| Edge Server Deployment | Partnerships with NTT Docomo and SK Telecom collapse latency for cloud gaming services in Japanese and Korean markets. |
| Proprietary Operating System Development | Samsung Tizen and LG webOS integration locks smart TV users into platform-specific content discovery algorithms. |
| Backward Integration into Display Panels | Captive OLED substrate production insulates Samsung Electronics from Korean supply concentration volatility. |
| FAST Platform Launch | Free ad-supported tiers from Roku and Amazon capture price-sensitive young adults unwilling to commit to monthly subscriptions. |
Research Methodology
The analysis maps streaming services, smart TV hardware, gaming consoles, and content delivery infrastructure, each validated through platform engineering executives, content licensing directors, telecommunications operator strategy heads, and display panel procurement managers. Primary fieldwork combined structured interviews with secondary validation against FCC broadband deployment filings, MIIT equipment standards publications, EU AI Act regulatory texts, and SEC 10-K disclosures from listed platform operators. Bottom-up installed base modeling triangulated against top-down household penetration projections from national statistical agencies.
Assumptions held fixed include regulatory enforcement timelines for EU AI Act transparency mandates and FCC broadband labeling compliance schedules, while variable conditions encompassed cloud gaming infrastructure deployment pace and FAST platform substitution rates. Segmentation modeling spanned device type, content format, subscription model, and household demographic configuration across the projection horizon. CAGRs derived from logistic diffusion curves fitted to smart TV replacement cycles and streaming service adoption saturation patterns. Forecast inputs incorporated 5G fixed wireless access rollout trajectories and K-content export subsidy program extensions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed streaming entrants or display panel supply consolidation would shift outcomes beyond modeled ranges. Model boundaries exclude adjacent markets including theatrical exhibition, physical media retail, and out-of-home digital signage. Quarterly review of subscriber acquisition cost trends, smart TV panel pricing indices, and telecommunications operator capex disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
North America Photographic Services Market
Digital Media
Video Wall Market
Digital Media
Wedding Photography Market
Digital Media
Europe Online Video Platform Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Digital Effects Services Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Animation Services Market
Digital Media
Digital Video Content Market
Digital Media
Video Production Market
Digital Media
Global Stock Video Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Media Gateway Market
Digital Media
Video Content Management Market
Digital Media
US Automatic Content Recognition Market
Digital Media
United Kingdom Webtoons Market