
 Digital Effects Services Market | 2026-2036
Digital Effects Services Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Effects Services Market Insights
Cloud-based managed services for rendering and compositing pipelines is expanding the addressable market for mid-tier studios that previously lacked capital for on-premises infrastructure. Industrial Light & Magic leverages its proprietary StageCraft virtual production technology to anchor premium episodic work. Weta Digital specializes in creature animation and digital humans, sustaining its position through deep R&D investment in simulation algorithms. Framestore competes across advertising and feature film segments, extending its geographic footprint through satellite offices in Montreal and Mumbai.
Digital effects services encompass the creation, manipulation, and integration of computer-generated imagery, live-action footage, and synthetic elements at resolutions up to 8K with color spaces supporting HDR delivery. These services enable filmmakers, advertisers, and game developers to realize visual narratives that physical production cannot execute safely or economically. VFX and 3D animation command the largest revenue pools, though real-time rendering technology is displacing traditional offline workflows in previsualization and virtual production environments. Cloud-based and hybrid delivery models are capturing share fastest, as studios prioritize elastic compute capacity over fixed capital expenditure in render farm infrastructure.
The Federal Communications Commission shapes content distribution standards in the United States, while the UK's Office of Communications enforces accessibility and technical quality mandates for broadcast VFX. India's Ministry of Information and Broadcasting oversees content certification that affects post-production service demand. The European Union's AI Act introduces transparency requirements for generative tools increasingly deployed in digital effects pipelines. Stakeholders must evaluate which regulatory jurisdictions their rendering infrastructure touches, as data localization rules and content ratings regimes multiply compliance obligations across multi-territory productions.
Market Dynamics
Real-time rendering engines are compressing traditional VFX production cycles from months to weeks, forcing legacy facilities to retool compositing pipelines or surrender episodic work to virtual-production-enabled competitors.
Growth Catalysts
- EU AI Act transparency mandates:Studios deploying generative fill tools for background replacement must document training data provenance, creating audit-ready service demand from compliance-conscious streamers.
- 8K HDR delivery specifications:Streaming platforms now require mastered content in Rec. 2020 color space with 4000-nit peak luminance, expanding retouching and grading service contracts.
- India's post-production clusters:Mumbai and Chennai facilities leverage time-zone arbitrage to capture overnight compositing work from Los Angeles-based productions.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in CUDA-optimized render hardware exposes studios to allocation delays and 40-60% spot-price volatility during semiconductor shortages.
- Technical debt in proprietary pipelines:Legacy studios maintain decades of custom shader code incompatible with USD-based asset exchange, fragmenting talent pools and inflating integration costs.
- FCC captioning mandates:Burned-in VFX elements complicate compliance with enhanced accessibility rules for streaming content, requiring redundant deliverable versions.
Strategic Opportunities
- Virtual production volume buildout:Underpenetrated markets in São Paulo and Dubai lack LED stage infrastructure, opening first-mover positions for hardware-software bundled service offerings.
- Game engine convergence:Unreal Engine and Unity pipelines now power final-pixel cinematography, enabling VFX houses to capture previs-through-final work previously split across vendors.
- India's PLI scheme for animation:Production-linked incentives for visual effects studios reduce effective labor costs by 20-25% for qualifying export projects.
Industry Challenges
- Simulation specialist scarcity:Fluid dynamics and finite-element cloth solvers require physics PhDs; training pipelines produce fewer than 200 qualified graduates annually across all markets.
- Cross-platform color management:Delivering consistent imagery across theatrical DCI-P3, streaming Rec. 2020, and mobile sRGB displays demands redundant grading passes that erode margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Effects Services Market |
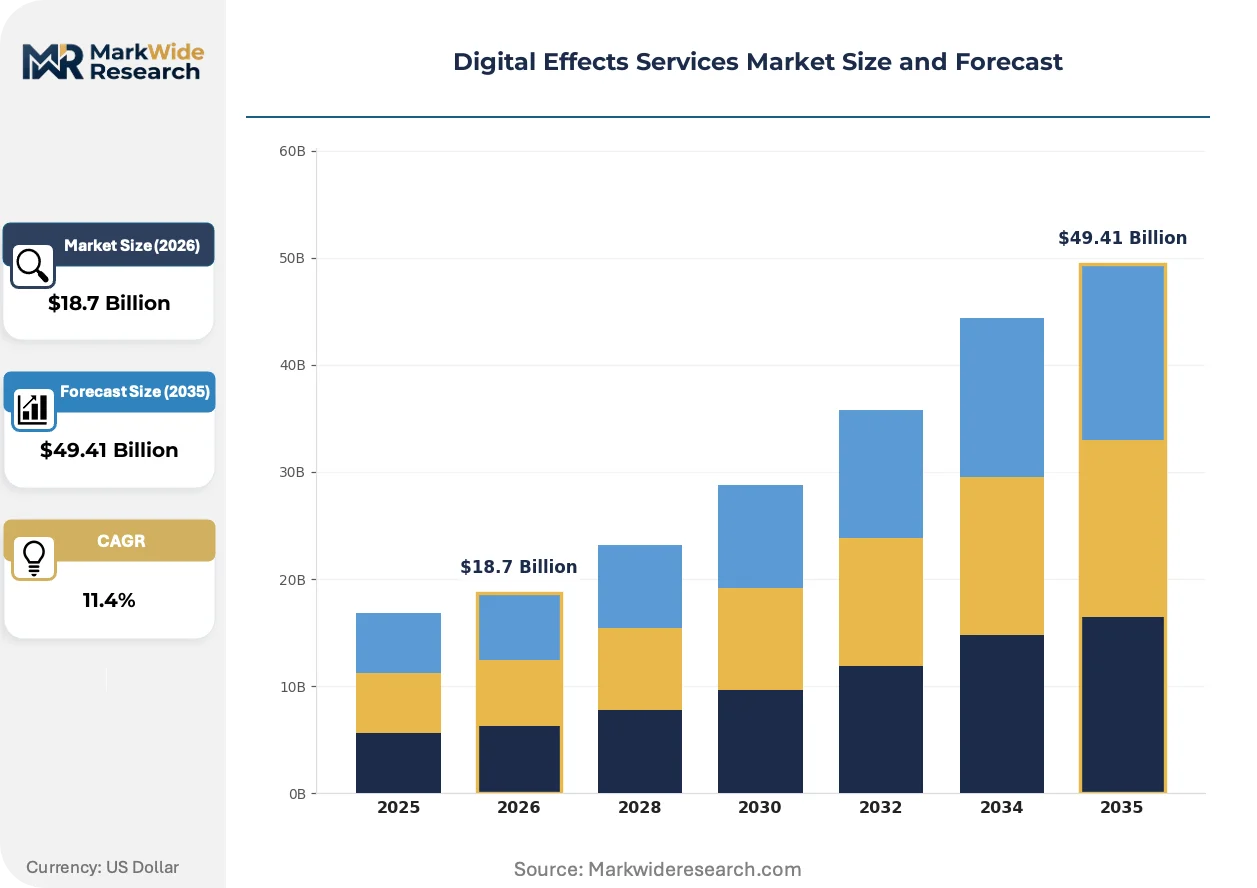
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: VFX, Motion Graphics, 3D Animation, Compositing End User: Film Production, Television Broadcasting, Advertising Agencies, Video Game Development Delivery Model: On-premises, Cloud-based, Hybrid, Managed Services Technology: Real-time Rendering, Augmented Reality, Virtual Reality, CGI |
| Companies Covered | Industrial Light & Magic, Weta Digital, Framestore, DNEG, Moving Picture Company, Digital Domain, Rodeo FX, Animal Logic, Scanline VFX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Effects Services Market Trends and Innovations
Neural rendering techniques are collapsing the boundary between real-time and offline quality thresholds, enabling new service categories that did not exist three years ago.
Gaussian splatting is rewriting asset creation economics for photorealistic environments. Indie game developers and commercial directors now capture location data with consumer LiDAR hardware, bypassing traditional photogrammetry service contracts. The structural consequence compresses location-scouting budgets and displaces mid-tier environment-build vendors.
The EU AI Act's transparency requirements for generative tools are reshaping pipeline architecture. Studios must maintain immutable logs for every AI-assisted texture or matte painting, adding compliance infrastructure costs that favor larger facilities with dedicated legal-technical staff. European co-productions are responding by centralizing VFX supervision in London and Berlin to ensure audit continuity.
Streamers now unbundle finishing services from primary VFX contracts, forcing houses to compete à la carte for color grading, mastering, and localization. This procurement fragmentation favors boutique specialists in Paris and Toronto while pressuring full-service facilities to defend retainer relationships through exclusive talent lockups. The shift is most visible in episodic drama, where seasonal volume justifies dedicated finishing suites.
Digital Effects Services Market Segmentation
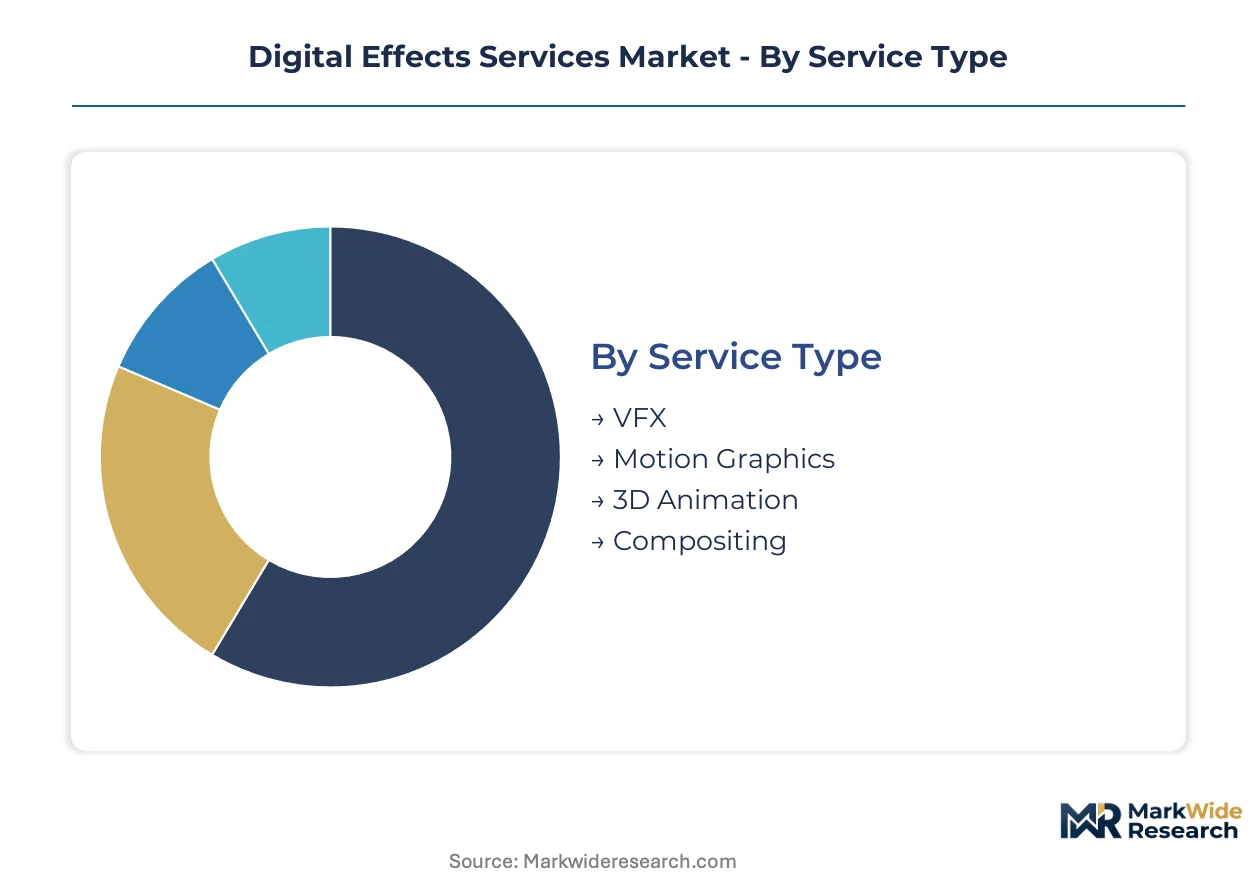
Service differentiation in digital effects reflects divergent capital intensity and client risk tolerance. Studios select delivery models and technology stacks based on project scale, security requirements, and timeline compression needs. Segmentation reveals where margin concentrates versus where volume expands.
Service Type:
Customization intensity spans from templated motion graphics to bespoke creature simulation, with standardization possible only at the lower end of visual complexity.
- VFX:Encompasses particle systems, fluid dynamics, and digital environment creation at resolutions up to 8K HDR. Demand clusters in Los Angeles and London for tentpole franchise work, where streaming platforms now mandate delivery in Rec. 2020 color space.
- 3D Animation:Character rigging, procedural animation, and performance capture pipelines require specialized Maya and Houdini expertise. India's Mumbai and Chennai facilities capture volume through time-zone arbitrage on overnight compositing cycles.
- Motion Graphics:Lower-complexity title sequences and UI overlays for broadcast and advertising.
- Compositing:Integration of live-action plates with CG elements, increasingly automated through AI-assisted rotoscoping tools.
Most installed capacity flows through VFX. Expansion is steepest in 3D Animation.
End User:
Client procurement maturity varies from cost-plus studio relationships to fixed-bid competitive tenders, with advertising agencies demanding the fastest turnaround cycles.
- Film Production:Theatrical releases and streaming features requiring photorealistic digital humans and destruction simulation. Major facilities in London and Wellington anchor this tier through proprietary StageCraft and creature R&D pipelines.
- Television Broadcasting:Episodic drama and unscripted content with compressed post schedules. Virtual production volumes now displace traditional green-screen workflows for premium series.
- Advertising Agencies:30-second spots with rapid iteration demands and brand-mandated color accuracy across DCI-P3 and sRGB deliverables.
- Video Game Development:Cinematics and in-engine assets converging with real-time rendering pipelines from Unreal Engine and Unity.
Film Production retains the highest contract values. Television Broadcasting is gaining share fastest as streaming volume multiplies.
Delivery Model:
Capital deployment preferences split between ownership-heavy on-premises farms and elastic cloud consumption, with hybrid configurations emerging as the compromise architecture.
- Cloud-based:Render farm capacity procured through AWS, Azure, or Google Cloud Platform with per-hour GPU pricing. Mid-tier studios in Toronto and Montreal adopt this to bypass seven-figure infrastructure investments.
- Hybrid:Sensitive asset processing on-premises with burst rendering to cloud. European co-productions favor this for GDPR compliance on facial capture data.
- On-premises:Owned render hardware with NVIDIA CUDA optimization, still preferred by facilities handling unreleased franchise IP.
- Managed Services:End-to-end pipeline operation outsourced to specialists who maintain software licenses and hardware refresh cycles.
On-premises retains the largest sunk investment base. Cloud-based is climbing the fastest as spot-price volatility stabilizes.
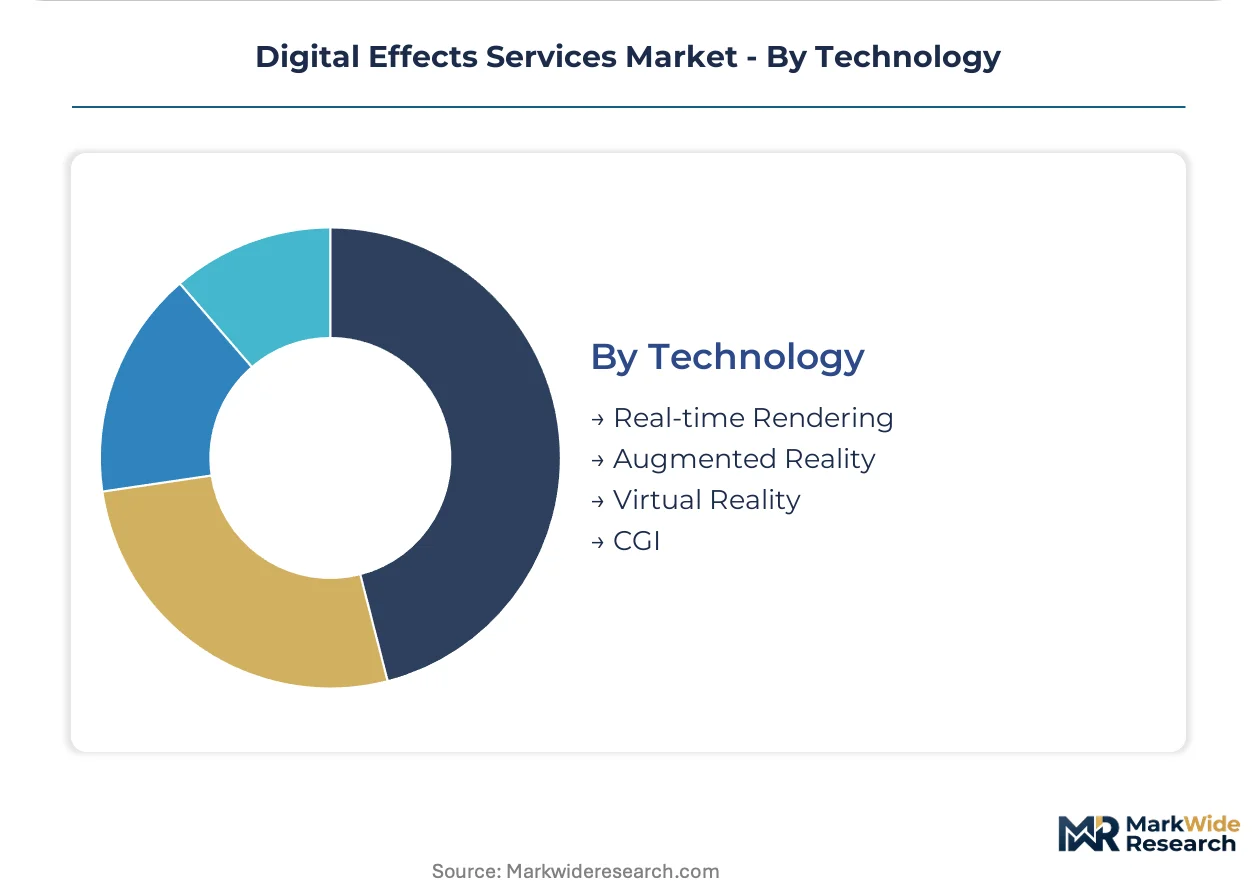
Technology:
Technical maturity ranges from established CGI pipelines to nascent neural rendering methods that collapse traditional production timelines.
- Real-time Rendering:Unreal Engine and Unity powering final-pixel cinematography without offline compositing. LED volume stages in Los Angeles and London now deploy this for in-camera VFX.
- CGI:Traditional offline ray-tracing with RenderMan and Arnold, still required for photorealistic fur and subsurface skin scattering.
- Augmented Reality:Real-time overlay graphics for broadcast sports and live events, demanding sub-frame latency.
- Virtual Reality:Stereoscopic 360-degree content for location-based entertainment and training simulations.
CGI maintains the deepest talent bench. Real-time Rendering is expanding most quickly as game engine quality thresholds rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's post-production sector captures overnight compositing cycles from Los Angeles through time-zone arbitrage, while the United Kingdom anchors premium episodic work through proprietary virtual production technology. Regulatory frameworks and infrastructure investments across five countries shape where digital effects capacity concentrates and expands.
United States
Streaming platforms mandate Rec. 2020 color space delivery with 4000-nit peak luminance for HDR content. The Federal Communications Commission enforces enhanced accessibility rules that complicate VFX workflows with burned-in elements. Los Angeles LED volume stages deploy real-time rendering for in-camera effects on tentpole franchise productions.
United Kingdom
The Office of Communications enforces technical quality mandates for broadcast VFX that drive compliance investment. London facilities anchor European co-production supervision to ensure audit continuity under EU AI Act transparency requirements. Soho post-production houses compete for unbundled finishing services across color grading and localization.
India
The Ministry of Information and Broadcasting oversees content certification affecting post-production demand timing. Production-linked incentives for animation and VFX studios reduce effective labor costs for qualifying export projects. Mumbai and Chennai clusters process overnight compositing cycles for North American episodic releases.
Canada
Provincial tax credits and federal production incentives attract foreign VFX investment to Montreal and Toronto. The country's national broadcast regulator enforces domestic content quotas that sustain local animation capacity. Vancouver and Montreal facilities adopt cloud-based rendering to bypass seven-figure infrastructure investments.
Germany
The EU AI Act's training data provenance requirements reshape pipeline architecture for generative tool deployment. Berlin facilities centralize VFX supervision for European co-productions seeking audit-ready compliance documentation. Munich and Hamburg studios specialize in automotive visualization and industrial simulation adjacent to manufacturing clients.
Digital Effects Services Market Competitive Landscape
Top-tier vendors anchor premium episodic and feature film work, while mid-tier facilities compete on cloud-enabled elasticity and geographic tax incentives. The vendor base stratifies across proprietary technology holders, volume-based service providers, and boutique finishing specialists. Three archetypes dominate: virtual-production-integrated houses, creature simulation specialists, and advertising-focused compositing shops. Competitive moves concentrate on talent lockups through exclusive contracts and geographic expansion via satellite offices.
Among established premium-tier operators, Industrial Light & Magic and Weta Digital occupy positions defined by proprietary R&D investment and deep specialization. Industrial Light & Magic exemplifies the virtual-production-integrated archetype through its StageCraft technology deployment. Weta Digital represents the creature and digital human specialization tier sustained by physics simulation expertise. Framestore sits within the multi-segment competitor category spanning advertising and feature film delivery.
| Leading Market Players |
|---|
| Industrial Light & Magic |
| Weta Digital |
| Framestore |
| DNEG |
| Moving Picture Company |
| Digital Domain |
| Rodeo FX |
| Animal Logic |
| Scanline VFX |
| Others |
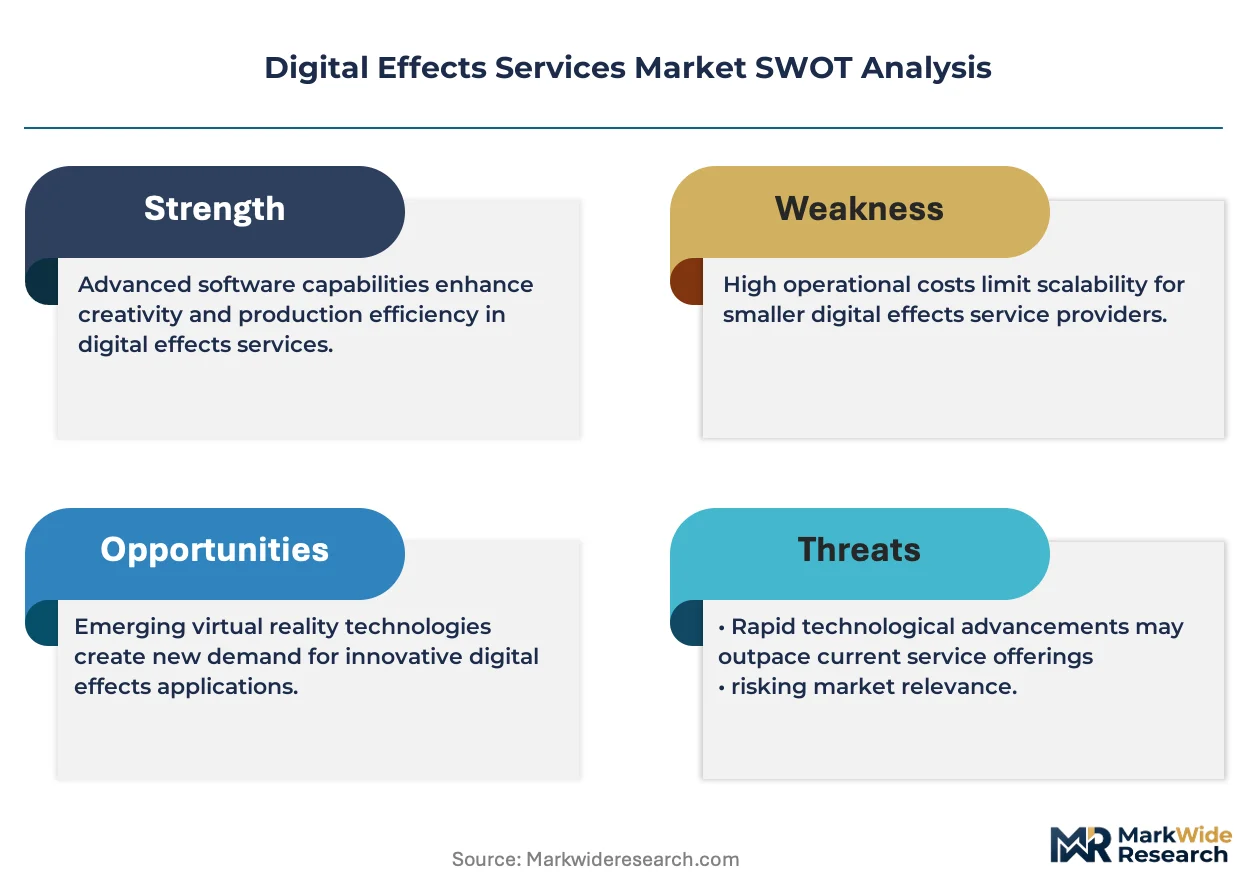
Pricing and Supply Chain Analysis
GPU compute cycles constitute the dominant input cost, flowing from NVIDIA's CUDA-optimized silicon through cloud spot markets and on-premises render farms into project-based service tiers that stratify by resolution and turnaround pressure.
Pricing Analysis
Capacity additions in India's Mumbai and Chennai clusters are reshaping price floors for overnight compositing cycles, compressing margin on standard-definition episodic work. Project-based contracts dominate, with price differentiation anchored in resolution tier and color-space complexity. Pricing pressure stems from streamers unbundling finishing services, forcing à la carte competition. Advertising agencies exhibit highest price sensitivity due to rapid iteration demands, while franchise tentpole productions absorb premium rates for proprietary StageCraft deployment.
Supply Chain Analysis
Direct-to-studio channels handle hyperscale streamer demand, with boutique finishing houses serving unbundled procurement. Supply concentrates in the United States, the United Kingdom, and India, with hardware dependencies on NVIDIA GPUs, LED volume infrastructure, and proprietary simulation software. Single-source vulnerability runs through CUDA-optimized render hardware exposed to semiconductor allocation delays. Distribution runs through long-term retainer relationships for premium tier work, spot contracting for episodic overflow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in virtual production integration and AI-assisted pipeline automation, with cloud-based delivery models reducing fixed capital drag.
For Market Incumbents: Acquire specialized simulation talent pools to defend against scarcity in fluid dynamics and finite-element cloth solvers. Consolidate proprietary USD-based asset pipelines to reduce technical debt fragmentation. Threats emerge from game engine convergence displacing traditional offline workflows; vertical integration into LED volume hardware-software bundles offers defensive positioning. For New Entrants and Emerging Players: Launch via cloud-native managed services to bypass seven-figure render farm investments. Target São Paulo and Dubai virtual production volumes, where LED stage infrastructure remains underpenetrated. White-space exists in compliance-ready generative tool documentation for EU AI Act transparency mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where technical debt in legacy shader code fragments integration economics. Long-term viability favors facilities with dedicated legal-technical staff for audit-ready pipeline architecture. Acquisition target archetype: mid-tier studios with elastic cloud contracts and established streamer relationships. Signal to watch: streamer procurement unbundling accelerating toward dedicated finishing specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Production Volume Buildout | First-mover positions in São Paulo and Dubai capture unmet LED stage demand. |
| Cloud-Native Pipeline Migration | Elastic GPU procurement from AWS and Azure reduces fixed infrastructure exposure. |
| Compliance Infrastructure Investment | Immutable logging systems satisfy EU AI Act training data provenance requirements. |
| Simulation Specialist Acquisition | Physics PhD talent pools anchor creature animation and digital human capabilities. |
| Finishing Service Specialization | Boutique color grading and mastering suites capture unbundled streamer procurement. |
Research Methodology
Coverage spans the United States, United Kingdom, India, Canada, and Germany, with primary inputs from each market cluster. Primary interviews combined VFX pipeline supervisors, streaming platform procurement officers, post-production facility executives, and regulatory compliance leads with secondary validation from FCC filing databases, EU AI Act implementation guidance, Indian PLI scheme documentation, and customs records for GPU import flows. Bottom-up project pipeline tracking and top-down streaming content expenditure analysis provided triangulation.
Rate-of-change decomposition separated volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled included service type, end user procurement maturity, delivery model capital intensity, and technology stack migration patterns. CAGRs derived from elasticity-adjusted demand curves incorporating streamer content commissioning schedules and real-time rendering adoption thresholds. Industry-specific inputs captured LED volume stage deployment timelines and generative tool regulatory compliance cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated game engine quality convergence. Forecasts reflect assumptions about streamer content volume sustainability and regulatory enforcement consistency across jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
North America Webtoons Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Manga Market
Digital Media
Online Art Market
Digital Media
Stock Music Software Market
Digital Media
Anime Streaming Tool Market
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
Mexico Webtoons Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Europe Online Gambling Market
Digital Media
Music Rights Management Market
Digital Media
Global Animation Market
Digital Media
Middle East Gaming Market
Digital Media
Animation Services Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Naruto Around Market