
 France Steam Rooms Market | 2026-2036
France Steam Rooms Market Size, Share, and Industry Trends Forecast 2026-2036
France Steam Rooms Market Foresight
Capital-intensity divergence between full-system manufacturers and component suppliers is bifurcating competitive dynamics in France. KLAFS Group leverages in-house sauna and steam engineering to sustain premium positioning across European wellness projects. Harvia anchors its French presence through controlled distribution of Finnish-built generator technology. Marmox France SAS differentiates via waterproofing substrates that integrate with steam room builds.
France steam rooms are enclosed thermal environments operating at 40–50°C with near-saturation humidity, powered by electric or gas steam generators that vaporize water through pressurized heating elements for therapeutic and relaxation purposes. Modular steam generators are gaining share in retrofit projects where spatial constraints limit traditional equipment placement. Electric steam generators lead new construction pipelines across hospitality chains, while wall-mounted units capture demand in private residences where mechanical room space is minimal.
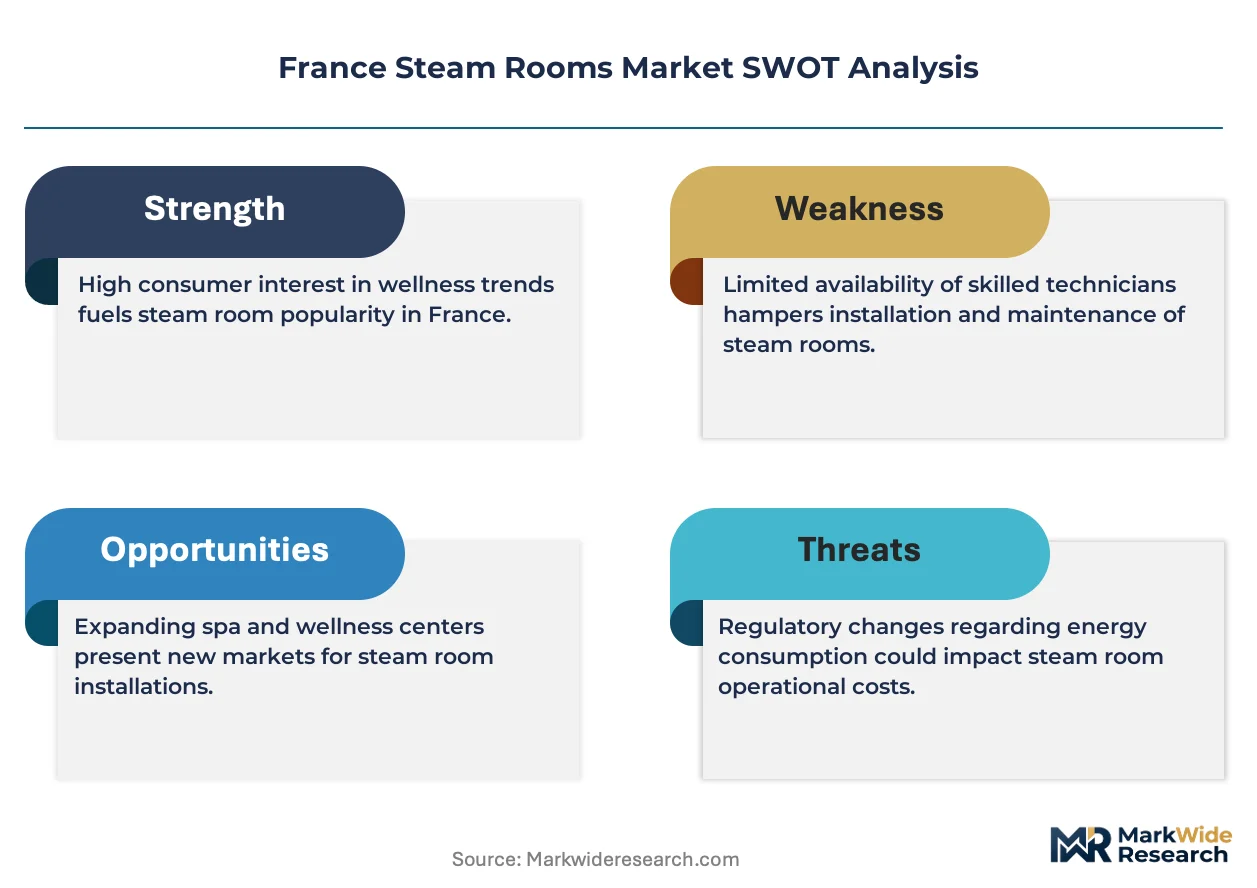
ANSM monitors material safety for surfaces in prolonged humid contact, while the French Ministry of Ecological Transition enforces RT 2020 efficiency thresholds on heating equipment in commercial buildings. CE marking under the EU Construction Products Regulation governs structural waterproofing and electrical safety for installed systems. Stakeholders must track evolving efficiency mandates and certification requirements as renovation rates accelerate across France's aging hospitality stock.
Market Dynamics
The RT 2020 thermal regulation is compressing equipment replacement cycles across France's commercial building stock, forcing hospitality operators to retire legacy steam generators ahead of schedule. This regulatory pressure is bifurcating the supplier base between certified system integrators and uncertified maintenance contractors.
Growth Catalysts
- RT 2020 efficiency mandates:The French Ministry of Ecological Transition requires commercial buildings to meet strict thermal performance thresholds, accelerating generator upgrades in hotels and wellness centers.
- Provence wellness resort cluster:High-end thermal spa developments across Aix-en-Provence and the Luberon are specifying custom steam room installations as anchor amenities.
- Modular retrofit technology:Compact wall-mounted steam generators enable equipment installation in mechanical rooms with severe spatial constraints.
Market Restraints
- Copper and stainless steel input volatility:Generator housing and heating element materials face commodity price swings that compress fabrication margins for domestic equipment assemblers.
- Generator supply concentration:Core pressurized heating element technology remains concentrated among a narrow base of specialized European component manufacturers.
- Natural gas connection limitations:Historic Parisian building stock lacks the infrastructure for gas-fired steam generation, restricting fuel choice in Île-de-France retrofits.
Strategic Opportunities
- Corsica and overseas territories:These French regions show underpenetrated hospitality development with limited local steam room installation capacity.
- Residential wellness integration:High-net-worth homeowners in Neuilly-sur-Seine and Lyon are specifying private steam rooms as standard features in new construction.
- CE marking harmonization:The EU Construction Products Regulation creates pathway for French-certified systems to access adjacent Belgian and Luxembourg markets without redundant testing.
Industry Challenges
- Certified steam technician shortage:ANSM-mandated surface safety protocols require specialized installation training that outpaces vocational program output.
- Legacy electrical infrastructure incompatibility:Aging Parisian commercial buildings require costly panel upgrades to support modern three-phase steam generator loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Steam Rooms Market |
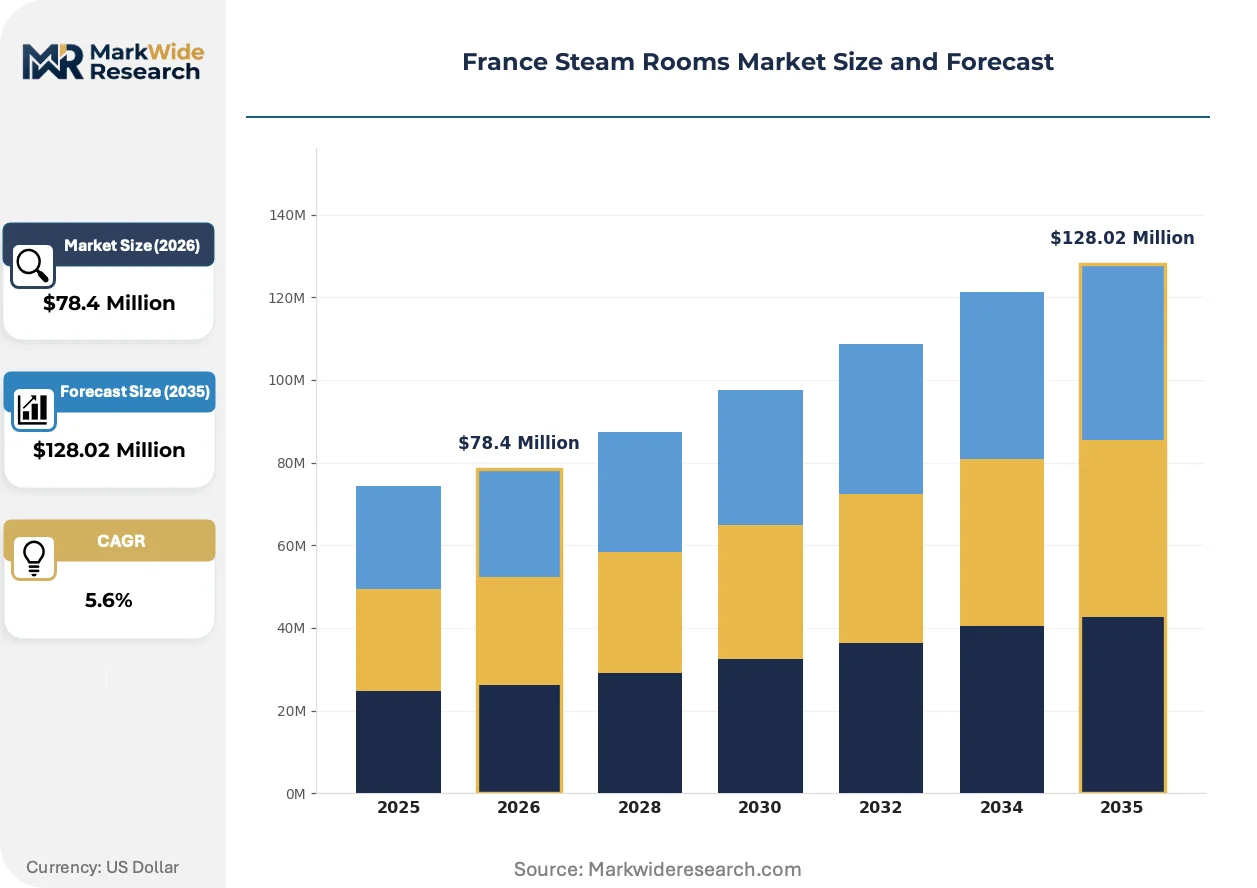
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $128.02 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric Steam Generator, Gas Steam Generator, Modular Steam Generator, Wall Mounted Steam Generator Application: Luxury Spas, Fitness Centers, Wellness Resorts, Boutique Hotels End User: Hospitality Chains, Health Clubs, Private Residences, Rehabilitation Centers Installation: New Construction, Retrofit Projects, Commercial Buildings, Residential Properties |
| Companies Covered | Kohler, Marmox France SAS, KLAFS Group, Harvia, Bien-Etre & Confort, Preti, Duravit, Iber Spa, Thermae, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Steam Rooms Market Shifts & Advancements
Steam generation technology is fragmenting across multiple performance tiers as regulatory pressure and end-use diversification pull specifications in opposing directions. Equipment manufacturers are responding with specialized product architectures rather than universal platforms.
Smart humidity control systems with IoT-enabled sensors are bifurcating the premium equipment segment from basic generator-only sales. Luxury wellness chains in Cannes and Saint-Tropez are specifying these integrated systems to enable remote monitoring and predictive maintenance scheduling. The technology is bifurcating vendor revenue models toward recurring software and service contracts alongside hardware margins.
ANSM surface material safety protocols are tightening testing requirements for surfaces in prolonged humid contact, particularly for antimicrobial and anti-slip coatings. French steam room fabricators must now submit extended leaching and durability test data before commercial deployment. Hospitality operators in Paris are prioritizing pre-certified material packages to accelerate project timelines and reduce regulatory risk.
Wellness procurement teams are consolidating vendor relationships to reduce coordination complexity across multi-site portfolios. Major hotel groups in Île-de-France are awarding single-source contracts covering design, equipment, and maintenance rather than fragmenting responsibility. This concentration is most visible among international hospitality chains with standardized amenity specifications across their French properties.
France Steam Rooms Market Segmentation
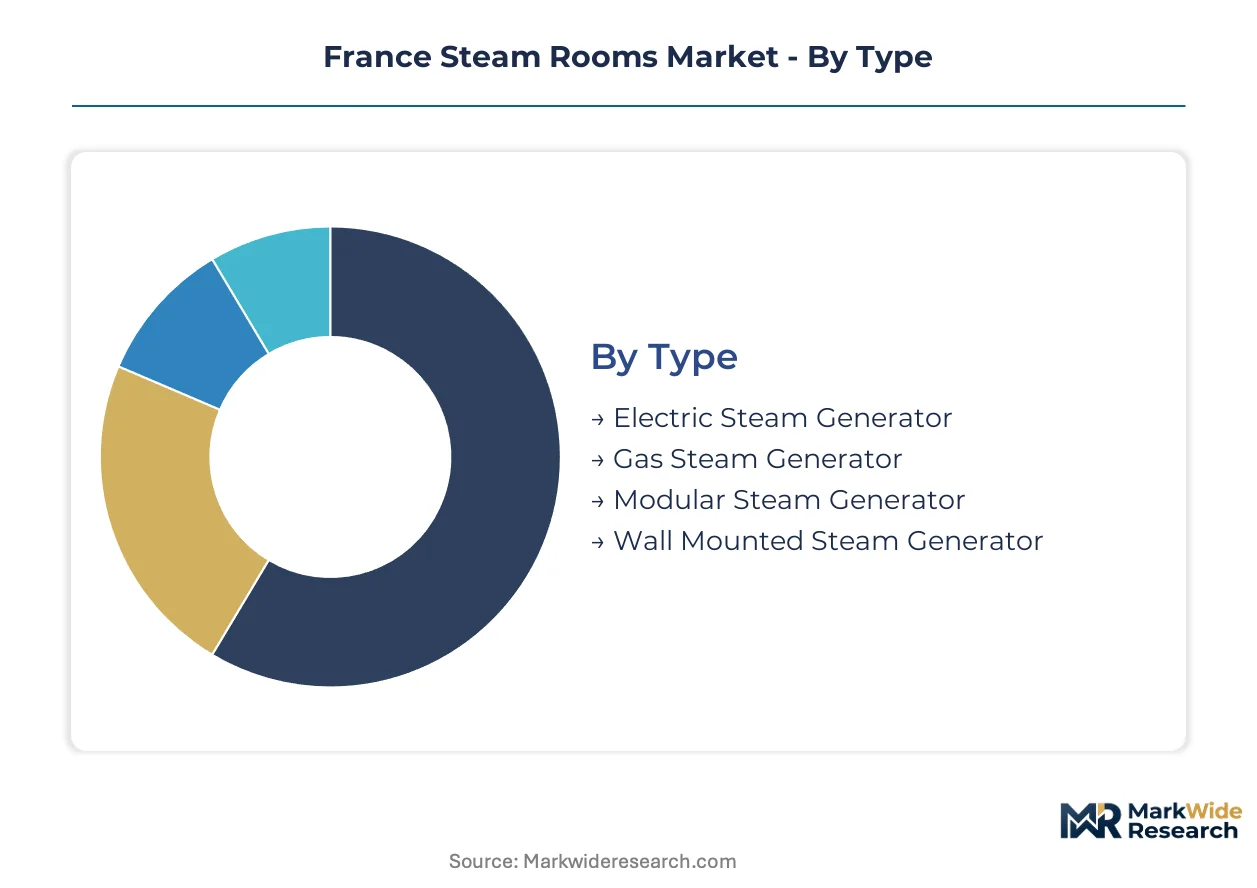
Steam room equipment specifications diverge sharply across French end-uses, with thermal performance mandates and spatial constraints fragmenting procurement requirements. Understanding these segment boundaries clarifies where technology substitution threatens incumbent suppliers and where protected demand pools sustain premium positioning.
Type:
Gas-fired alternatives pose the most acute substitution threat to electric steam generators as energy cost differentials widen across French commercial operators.
- Electric Steam Generator:Pressurized heating elements vaporize water through resistive electrical load, delivering precise temperature control required by ANSM surface safety protocols. Parisian hospitality chains in the Île-de-France region specify these units exclusively due to natural gas infrastructure gaps in historic building stock.
- Modular Steam Generator:Compact, field-configurable units with segmented heating chambers enable phased capacity deployment in renovation timelines constrained by RT 2020 compliance deadlines. Provence wellness resorts favor these systems for their ability to match generator output to seasonal occupancy fluctuations without full equipment replacement.
- Gas Steam Generator:Combustion-based steam production offers lower operational costs where pipeline infrastructure exists, primarily in new construction zones outside central Paris.
- Wall Mounted Steam Generator:Vertical form factor eliminates floor space requirements in mechanical rooms with severe spatial constraints.
Electric steam generators retain volume leadership; modular steam generators hold the steepest expansion curve.
Application:
Cost tier stratification separates specification budgets, with wellness resorts commanding capital allocations that boutique properties cannot approach.
- Wellness Resorts:Destination thermal spa developments across Aix-en-Provence and the Luberon anchor amenity portfolios with custom-engineered steam environments. These installations integrate smart humidity control systems and ANSM-certified surface materials as non-negotiable specifications.
- Luxury Spas:High-end urban facilities in Cannes and Saint-Tropez specify IoT-enabled predictive maintenance architectures alongside core steam generation equipment. Procurement teams consolidate single-source vendor relationships to reduce coordination complexity across multi-site portfolios.
- Fitness Centers:Mid-market health clubs prioritize equipment reliability and rapid service response over integrated technology stacks.
- Boutique Hotels:Smaller properties favor standardized, pre-certified material packages to accelerate project timelines and reduce regulatory risk.
Wellness resorts dominate capital deployment; luxury spas are expanding most quickly through technology integration.
End User:
Customer type determines installation complexity, with hospitality chains imposing standardization requirements that fragment the supplier base.
- Hospitality Chains:International hotel groups with standardized amenity specifications across French properties award single-source contracts covering design, equipment, and maintenance. These operators face compressed equipment replacement cycles driven by RT 2020 thermal regulation mandates.
- Private Residences:High-net-worth homeowners in Neuilly-sur-Seine and Lyon specify private steam rooms as standard features in new construction, favoring wall-mounted units where mechanical room space is minimal.
- Health Clubs:Commercial fitness operators prioritize throughput capacity and durability under high-frequency use patterns.
- Rehabilitation Centers:Medical wellness facilities require ANSM-mandated surface safety protocols and specialized installation training that outpaces vocational program output.
Hospitality chains retain volume leadership; private residences hold the steepest expansion curve.
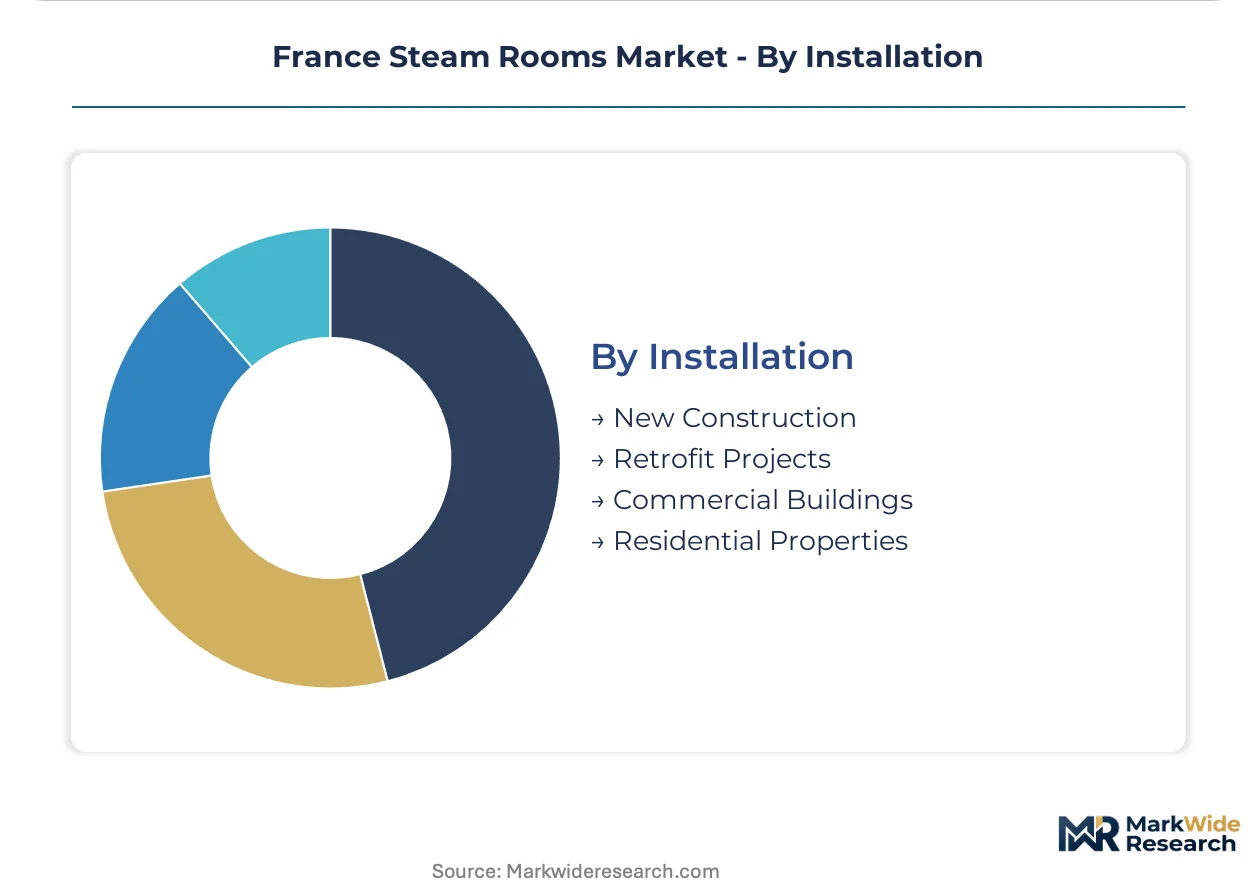
Installation:
Supply concentration in certified system integrators versus uncertified maintenance contractors bifurcates execution quality across project types.
- Retrofit Projects:Spatial constraints in France's aging hospitality stock drive demand for compact wall-mounted generators and modular configurations that fit existing mechanical rooms. Legacy electrical infrastructure incompatibility in aging Parisian commercial buildings requires costly panel upgrades to support modern three-phase steam generator loads.
- New Construction:Greenfield developments integrate steam generation from architectural planning stages, enabling optimal equipment sizing and placement. Electric generators lead these pipelines across hospitality chains building to RT 2020 standards.
- Commercial Buildings:Multi-tenant properties face complex coordination between building management systems and tenant-specific steam requirements.
- Residential Properties:Single-family installations benefit from simplified permitting and faster project timelines.
Retrofit projects retain volume leadership; new construction holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France hospitality chains show the least price elasticity, absorbing premium equipment costs to meet RT 2020 mandates, while Corsica and overseas territories exhibit acute sensitivity to installation logistics and freight-inflated pricing.
Île-de-France
Parisian luxury hotel groups drive specification intensity for wall-mounted electric generators where historic building stock lacks gas infrastructure. ANSM surface safety protocols compress project timelines as operators prioritize pre-certified material packages. Neuilly-sur-Seine and central Paris districts anchor private residential demand for compact mechanical room solutions.
Provence-Alpes-Côte d'Azur
Aix-en-Provence wellness resorts command capital allocations for custom-engineered steam environments with integrated smart humidity controls. The French Ministry of Ecological Transition enforces RT 2020 efficiency thresholds on new thermal spa developments. Cannes and Saint-Tropez luxury spa clusters specify IoT-enabled predictive maintenance architectures as standard amenities.
Auvergne-Rhône-Alpes
Lyon's high-net-worth residential segment favors modular steam generators in new construction where mechanical room space is minimal. CE marking under the EU Construction Products Regulation governs waterproofing and electrical safety for cross-border equipment sourcing. The Lyon metropolitan area shows accelerating boutique hotel retrofit activity constrained by legacy electrical infrastructure.
Corsica
Island hospitality development faces acute underpenetration with limited local installation capacity and elevated freight costs for generator equipment. The French overseas territories regulatory framework extends mainland building codes with additional maritime logistics compliance requirements. Ajaccio and Bastia coastal zones show emerging thermal spa project pipelines dependent on mainland contractor mobilization.
Hauts-de-France
Lille metropolitan wellness centers prioritize equipment reliability and rapid service response over integrated technology stacks. Regional vocational training programs struggle to output certified steam technicians at pace with ANSM-mandated installation requirements. The Lille-Roubaix-Tourcoing urban cluster exhibits mid-market fitness center expansion with standardized generator specifications.
France Steam Rooms Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-system manufacturers commanding premium positioning through in-house engineering capabilities while component suppliers compete on fabrication efficiency. The supplier base bifurcates between certified system integrators meeting RT 2020 compliance requirements and uncertified maintenance contractors serving price-sensitive retrofit segments. Two dominant strategic archetypes emerge: vertically integrated wellness project specialists and regional distribution anchors for foreign generator technology. Competitive moves concentrate on single-source contract consolidation by hospitality chains and geographic expansion into underpenetrated overseas territories.
Among German-integrated wellness specialists, KLAFS Group represents the full-system engineering archetype with captive sauna and steam capabilities across European projects. Finnish-built generator technology reaches French markets through Harvia's controlled distribution presence. Marmox France SAS occupies a distinct position as a domestic waterproofing substrate specialist integrating with steam room construction workflows. These three anchors exemplify how geographic origin and structural specialization map to tiered competitive positioning in a regulatory-compressed replacement cycle.
| Leading Market Players |
|---|
| Kohler |
| Marmox France SAS |
| KLAFS Group |
| Harvia |
| Bien-Etre & Confort |
| Preti |
| Duravit |
| Iber Spa |
| Thermae |
| Others |
Supply & Pricing Matrix
Project-based contracting with multi-year maintenance riders locks in both generator supply access and predictable lifetime cost visibility for French hospitality operators navigating RT 2020 compliance deadlines. This structure transfers commodity price volatility risk from end-users to equipment integrators while embedding certified installation capacity.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value capture for steam generator suppliers. Pricing stratifies across premium certified systems, standard RT 2020-compliant equipment, and economy retrofit packages. Price differentiation hinges on ANSM certification tier and bundled remote monitoring capabilities. Cost compression in the economy tier is intensifying because copper and stainless steel input volatility squeezes domestic fabricator margins. Boutique hotels exhibit acute price sensitivity, while Île-de-France luxury chains absorb premium equipment costs to meet regulatory mandates.
Supply Chain Analysis
Finland and Germany anchor pressurized heating element and control system manufacturing for French-bound steam generators. Core components draw from Italian waterproofing substrate specialists and Spanish ceramic surface fabricators. Single-source vulnerability concentrates in specialized European heating element technology. Distribution runs through certified system integrators in Île-de-France and Provence, with direct-to-contractor channels serving Corsica and overseas territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's steam room market represents early-cycle expansion as RT 2020 thermal regulations force premature replacement of legacy equipment across commercial building stock. Residential wellness integration in Neuilly-sur-Seine and Lyon accelerates penetration beyond traditional hospitality channels.
For Market Incumbents: Fortify certified technician training pipelines to outpace ANSM-mandated installation requirements that constrain project velocity. Deepen backward integration into waterproofing substrates to defend margin position against commodity input volatility in copper and stainless steel heating elements. For New Entrants and Emerging Players: Differentiate on modular retrofit technology tailored to spatial constraints in Parisian historic building stock. Target Corsica and French overseas territories where underpenetrated hospitality development meets limited local installation capacity. Lead with CE-marked equipment packages that accelerate cross-border access to Belgian and Luxembourg markets. For Investors and Strategic Acquirers: The market sits at a regulatory-compressed replacement cycle phase that favors vertically integrated wellness project specialists over pure-play component distributors. Long-term viability rests on capturing recurring software and service revenue from IoT-enabled predictive maintenance architectures. Watch certified steam technician output rates as the inflection signal for execution capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Technician Training Program | ANSM-mandated installation protocols outpace vocational program output, constraining project completion. |
| Modular Retrofit Product Line | RT 2020 deadlines compress renovation timelines where spatial constraints limit traditional equipment placement. |
| Smart Humidity Control Integration | Cannes and Saint-Tropez luxury chains specify IoT-enabled systems for remote monitoring capabilities. |
| Waterproofing Substrate Backward Integration | Marmox France SAS demonstrates defensible positioning via captive supply of steam room construction materials. |
| Corsica Distribution Partnership | Island hospitality development faces acute underpenetration with elevated freight costs for generator equipment. |
Research Methodology
Desk research of EU Construction Products Regulation filings, French Ministry of Ecological Transition regulatory notices, and hospitality development permits preceded structured interviews with wellness resort procurement directors, certified steam system integrators, ANSM compliance officers, and building renovation contractors. Secondary validation drew from CE marking databases, RT 2020 implementation reports, and regional vocational training program outputs. Bottom-up equipment shipment estimates triangulated against top-down hospitality construction value data.
Variance decomposition across type, application, end user, and installation dimensions shaped the analytical framework throughout the forecast period. Segmentation modeling captured electric versus gas generator substitution dynamics, modular versus conventional configuration adoption curves, and retrofit versus new construction project flows. CAGRs derived from equipment replacement cycle compression under RT 2020 mandates and residential wellness penetration rates in high-net-worth districts.
Material uncertainties — copper and stainless steel commodity price swings, certified technician training program expansion rates, and natural gas infrastructure extension in historic Parisian districts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and hospitality capital expenditure recovery trajectories. Recalibration cycles align with material shifts in RT 2020 amendment schedules and ANSM surface material safety protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Hearth Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Mattress Topper Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Louvre Windows Market
Homecare and Decor
Fragrant Drawer Liners Market