
 Garden Sheds Market | 2026-2036
Garden Sheds Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Sheds Market Analysis
Modular flat-pack configurations with pre-cut panels is recalibrating how landscape contractors evaluate total installed cost against traditional on-site builds. Keter leverages resin co-extrusion expertise to dominate weather-resistant consumer segments across European retail channels. Arrow Sheds anchors its position through galvanized steel roll-forming scale that sustains cost leadership in big-box distribution. Palram competes via polycarbonate and PVC hybrid engineering that differentiates its portfolio in light-transmitting greenhouse-adjacent structures.
Garden sheds are freestanding, single-story enclosures engineered from metal, timber, resin, or composite panels, typically spanning 4 to 20 square meters, designed for tool storage, equipment housing, and workspace extension in residential and light commercial settings. Wooden sheds retain premium positioning among heritage-conscious buyers despite ongoing pressure-treatment compliance costs, while resin sheds represent the fastest-expanding material class due to rot immunity and minimal assembly skill requirements. Metal sheds occupy the volume-intensive agricultural and rental-property maintenance segments where durability-to-price ratios govern procurement decisions. Gable and barn-style roof configurations capture disproportionate margin pools in North American retail due to aesthetic familiarity and snow-load engineering certification.
EPA-treated wood standards, REACH chemical restrictions in Europe, and ISO 9001 manufacturing certifications collectively shape material eligibility and cross-border market access for shed producers. USDA biobased labeling programs influence federal procurement preferences for timber-sourced structures in the United States. Stakeholders must monitor evolving embodied-carbon disclosure requirements from the EU Green Deal and CSRD frameworks that will soon differentiate compliant suppliers from stranded inventory holders.
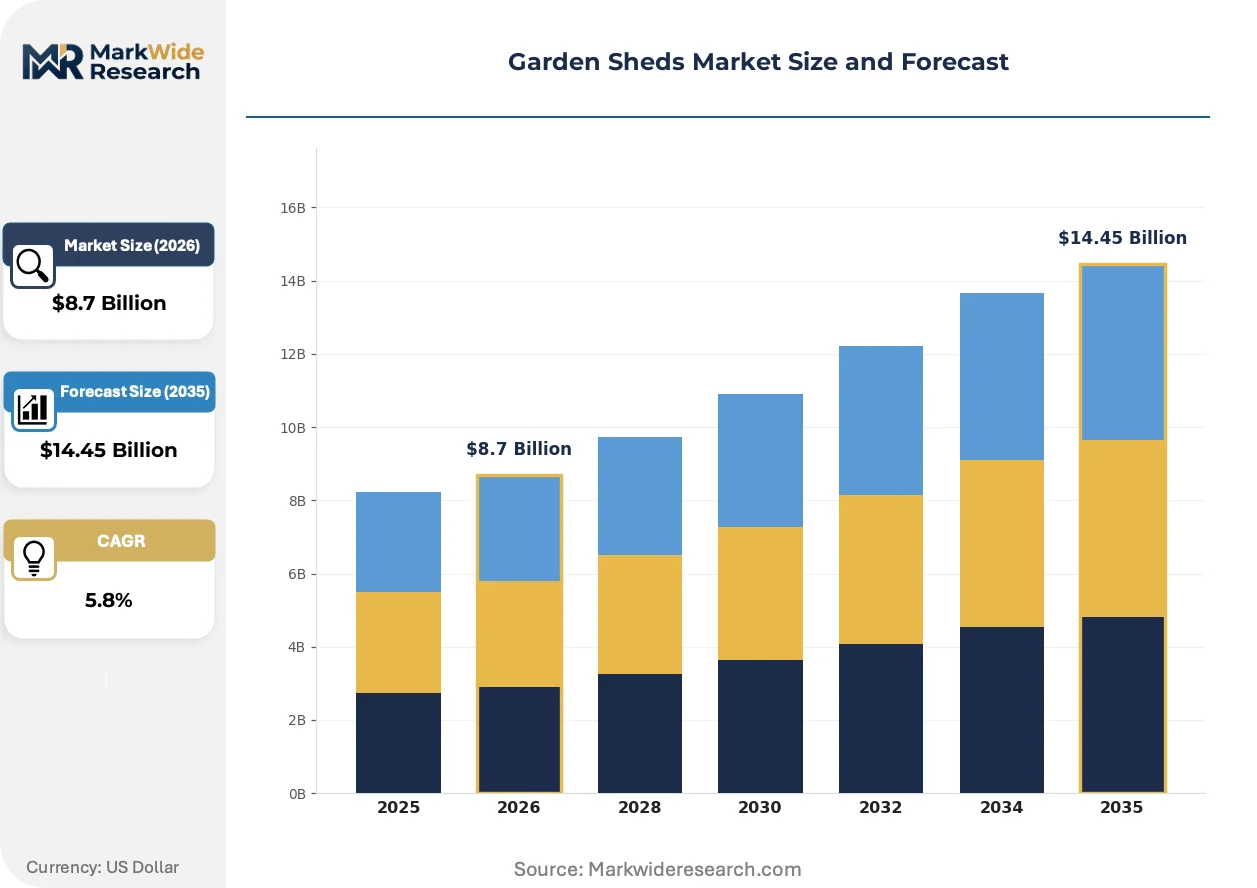
Market Dynamics
Modular flat-pack assembly systems are compressing installed cost premiums against traditional on-site construction, forcing distributors to recalibrate inventory models toward pre-cut panel SKUs.
Growth Catalysts
- Suburban outdoor living investment:Residential homeowners in Australia are prioritizing backyard renovation budgets toward storage infrastructure as remote work extends domestic space requirements.
- REACH chemical compliance:European resin formulations meeting ECHA restrictions on phthalate plasticizers are unlocking cross-border retail placement previously blocked by hazardous substance barriers.
- Rot-immune material substitution:Polymer composite panels are displacing pressure-treated lumber in coastal humidity zones where EPA wood treatment standards accelerate corrosion failure.
Market Restraints
- Galvanized steel input volatility:Zinc price swings tied to Chinese smelter output constraints are compressing margin predictability for roll-formed metal shed producers.
- Pressure-treatment compliance costs:EPA lumber standards are elevating landed costs for timber imports, stranding inventory at ports awaiting certification documentation.
- Polycarbonate UV degradation:Light-transmitting greenhouse-adjacent structures face warranty exposure in high-altitude installations where solar intensity accelerates polymer brittleness.
Strategic Opportunities
- Federal biobased procurement preference:USDA labeling programs are creating tiered access for domestic timber suppliers into institutional maintenance contracts.
- EU embodied-carbon disclosure mandates:CSRD frameworks will differentiate compliant shed manufacturers from stranded inventory holders unable to verify supply chain emissions.
- Rental property maintenance automation:Property management platforms are integrating bulk shed procurement into standardized unit-turnover workflows.
Industry Challenges
- Flat-pack assembly skill scarcity:Landscape contractors face margin erosion from callback rates on improperly seated panel joints requiring rework.
- ISO 9001 certification timeline compression:Cross-border market access delays from audit backlogs are freezing new product launches for six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Sheds Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Sheds, Wooden Sheds, Plastic Sheds, Resin Sheds Size: Small, Medium, Large, Extra Large Construction Style: Gable, Barn, Lean-To, Flat Roof End User: Residential, Commercial, Agricultural, Landscape Contractors |
| Companies Covered | Rubbermaid, DuraMax, Arrow Sheds, Timberline Barns, Esh's Utility Buildings, Lifetime, Palram, SOJAG, Keter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Sheds Market Emerging Trajectories
Material science advances and regulatory disclosure mandates are simultaneously elevating performance thresholds and transparency requirements across shed procurement channels.
Resin co-extrusion with integrated UV stabilizers is converging with consumer demand for zero-maintenance ownership. Heritage-conscious buyers in North American retail are accepting premium positioning for synthetic alternatives that replicate timber grain without pressure-treatment compliance burdens. This convergence is compressing traditional lumber's addressable market in coastal and high-humidity installations.
EPA-treated wood standards are reshaping import documentation requirements for timber-sourced structures. Cross-border shipments now face extended customs holds awaiting certification verification against formaldehyde emission thresholds. Agricultural and rental-property segments are accelerating metal and resin substitution to bypass documentation friction entirely.
Direct-to-contractor digital platforms are fragmenting traditional big-box distribution for volume maintenance accounts. Facility managers in United States commercial landscaping are bypassing retail markup through aggregated procurement portals. Australia exhibits the most advanced channel shift, where suburban homeowner associations coordinate group purchasing through localized platform interfaces.
Garden Sheds Market Segmentation
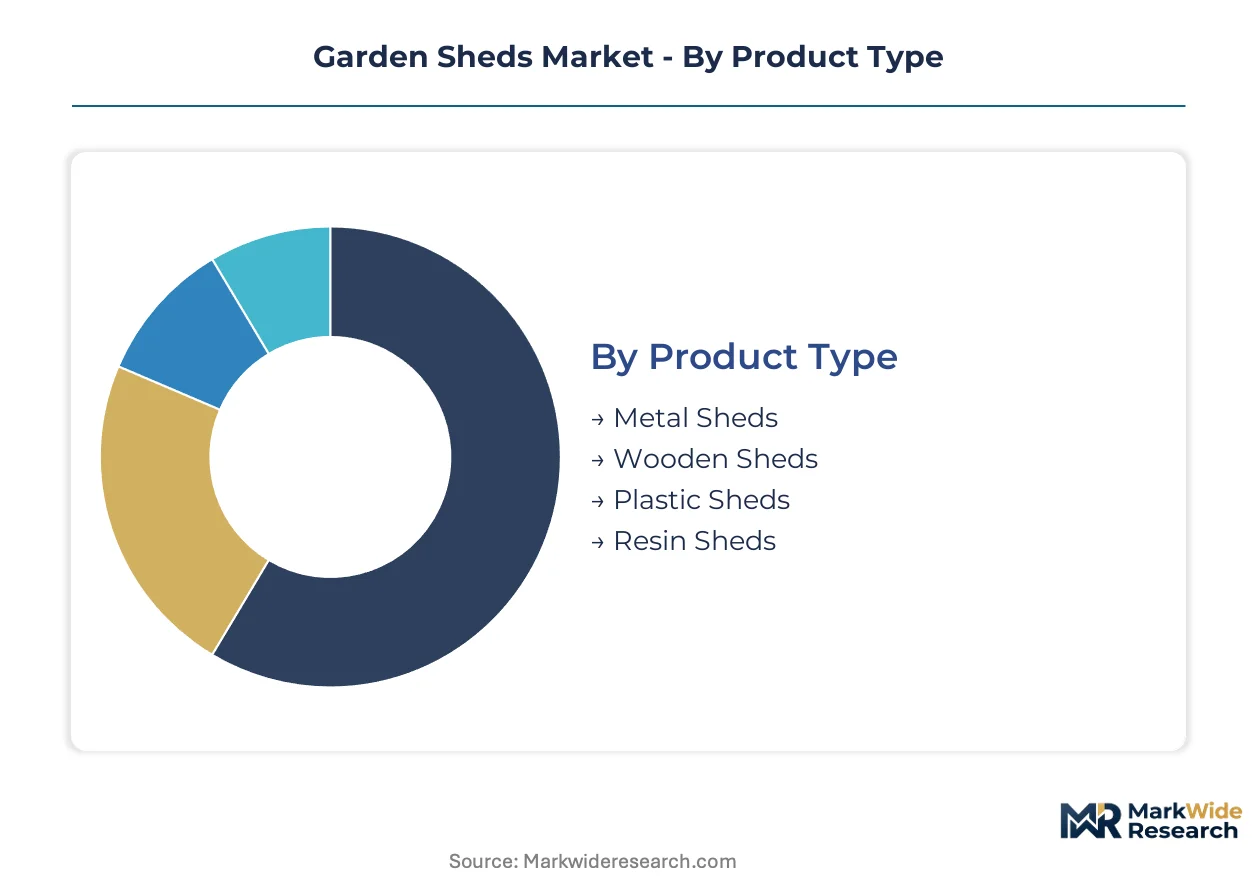
Material specifications and dimensional thresholds determine procurement workflows across garden shed categories. Construction style preferences cluster regionally around snow-load engineering and aesthetic heritage requirements. End-user segmentation reveals divergent durability-to-price sensitivities between homeowner associations and institutional maintenance buyers.
Product Type:
Material composition defines weathering performance, assembly complexity, and regulatory compliance burden for each specification tier.
- Metal Sheds:Roll-formed galvanized steel panels deliver superior strength-to-weight ratios for high-wind zones. Agricultural buyers in the United States favor these structures for equipment storage where durability-to-price ratios govern procurement decisions. Zinc price volatility from Chinese smelter constraints compresses margin predictability for producers.
- Wooden Sheds:Pressure-treated lumber retains premium positioning among heritage-conscious buyers despite compliance costs. Suburban Australian homeowners prioritize timber aesthetics for backyard renovation investments. EPA-treated wood standards elevate landed costs and documentation friction for cross-border shipments.
- Plastic Sheds:Polyethylene formulations offer entry-level price positioning with minimal maintenance requirements.
- Resin Sheds:Co-extruded polymer composites with integrated UV stabilizers deliver rot immunity and zero-maintenance ownership.
Metal sheds lead on scale; resin sheds lead on momentum.
Size:
Dimensional thresholds segment total installed cost and foundation requirements for distinct use-case intensities.
- Small:Compact footprints under 4 square meters serve balcony and terrace storage in dense urban cores.
- Medium:Standard suburban lot configurations balance tool capacity with setback compliance.
- Large:Workshop-adjacent structures accommodate ride-on equipment and workspace extension. Residential remote-work trends in Australia expand demand for these configurations as domestic space requirements extend outdoors.
- Extra Large:Commercial-grade footprints exceed 15 square meters for fleet equipment housing. Landscape contractors in the United States specify these units for maintenance yard consolidation, though flat-pack assembly skill scarcity elevates callback rates.
Medium dimensions dominate volume; extra large commands margin expansion.
Construction Style:
Roof geometry determines snow-load certification, interior volume efficiency, and aesthetic familiarity in regional retail channels.
- Gable:Symmetrical pitched roofs with central ridge lines optimize headroom and drainage. North American retail channels capture disproportionate margin pools from this configuration due to engineering certification familiarity and visual tradition.
- Barn:Gambrel roof profiles maximize storage volume in the loft zone. Heritage-conscious buyers accept premium positioning for this silhouette despite higher material intensity.
- Lean-To:Single-slope designs attach to existing structures for constrained sites.
- Flat Roof:Minimal profile configurations suit modernist architectural contexts and height-restricted zones.
Gable roofs anchor retail placement; barn styles concentrate margin capture.
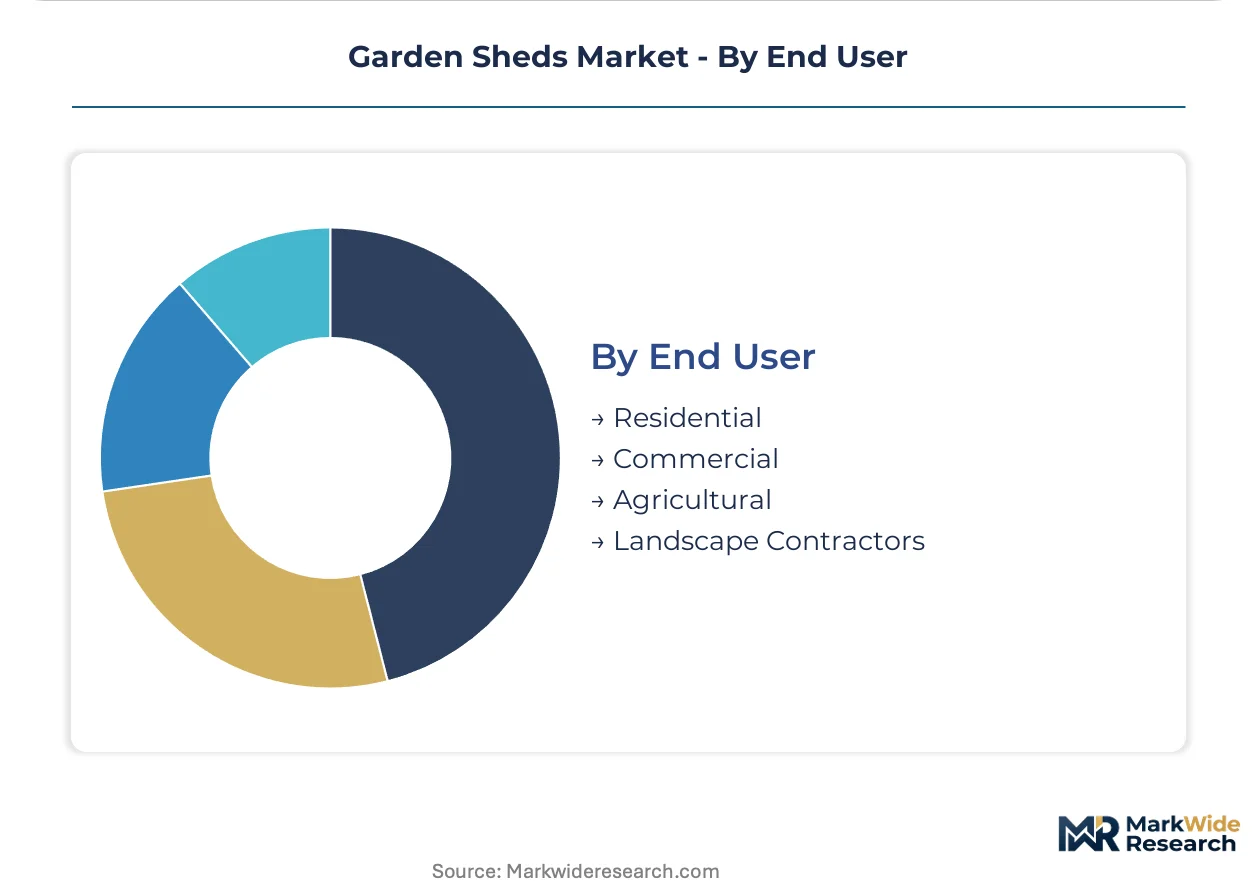
End User:
Procurement authority and volume scale differentiate specification requirements across buyer categories.
- Residential:Individual homeowners prioritize aesthetic integration and assembly simplicity. Australian suburban buyers are expanding storage investments as outdoor living spaces gain priority in renovation budgets.
- Commercial:Facility managers and property management platforms integrate bulk procurement into standardized workflows. Direct-to-contractor digital platforms fragment traditional big-box distribution for volume accounts.
- Agricultural:Equipment-intensive operations specify metal configurations for corrosion resistance and span capability.
- Landscape Contractors:Maintenance fleet operators require rapid deployment and modular expandability. Flat-pack assembly systems compress installed cost premiums but elevate callback exposure from improperly seated panel joints.
Residential channels drive volume breadth; commercial buyers accelerate platform procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The garden sheds industry traces its modern mass-market origins to post-war suburban expansion in the United States, where standardized metal panel fabrication and mail-order distribution first achieved scale. This American foundation established the template for global backyard storage infrastructure.
United States
Backyard renovation spending continues climbing across suburban markets, with facility managers in commercial landscaping bypassing retail markup through aggregated procurement portals. EPA-treated wood standards are elevating landed costs for timber imports, stranding inventory at ports awaiting certification documentation. The Southeast manufacturing corridor, particularly around Georgia and the Carolinas, hosts roll-formed metal fabrication clusters serving big-box distribution channels.
Germany
Heritage-conscious buyers in Bavaria and Baden-Württemberg accept premium positioning for timber aesthetics despite REACH chemical restrictions on phthalate plasticizers. ECHA compliance requirements are unlocking cross-border retail placement previously blocked by hazardous substance barriers. The North Rhine-Westphalia industrial basin concentrates resin co-extrusion capacity supplying weather-resistant consumer segments across European retail channels.
Australia
Residential homeowners in New South Wales and Victoria are expanding storage investments as remote work extends domestic space requirements into outdoor living areas. The country's national building code regulator enforces cyclone-rated structural standards that differentiate compliant suppliers in coastal humidity zones. Melbourne's southeastern manufacturing belt hosts modular flat-pack assembly operations compressing installed cost premiums against traditional on-site builds.
United Kingdom
Heritage-conscious buyers in the Home Counties and Cotswolds prioritize timber grain aesthetics for garden integration despite pressure-treatment compliance burdens. The UK's national environmental regulator enforces embodied-carbon disclosure frameworks aligned with EU CSRD mandates that will soon differentiate compliant shed manufacturers. The Midlands manufacturing corridor hosts galvanized steel roll-forming operations sustaining cost leadership in national distribution.
Japan
Compact suburban lot configurations in the Kanto region around Tokyo drive demand for small-footprint storage solutions under 4 square meters. METI energy efficiency guidelines influence material specifications for ancillary residential structures. The Osaka-Kobe industrial zone in Kansai hosts polycarbonate and PVC hybrid engineering operations differentiating portfolios in light-transmitting greenhouse-adjacent structures.
Garden Sheds Market Vendor Landscape
The competitive structure tilts toward material-specialist archetypes rather than integrated conglomerates. Roll-formed metal fabricators, resin co-extrusion specialists, and timber heritage brands occupy distinct tiered positions with limited cross-material overlap. Two strategic archetypes dominate: weather-resistant polymer engineers leveraging rot immunity for coastal markets, and galvanized steel scale players optimizing durability-to-price ratios for agricultural procurement. M&A activity concentrates on regional distribution network acquisition, while portfolio diversification drives resin specialists into polycarbonate hybrid structures.
Among North American heritage-timber and metal-scale fabricators, Timberline Barns, Arrow Sheds, and Rubbermaid occupy positions representing the traditional material dichotomy. Timberline Barns exemplifies the premium-timber archetype targeting heritage-conscious buyers despite compliance cost headwinds. Arrow Sheds anchors the galvanized steel volume tier where roll-forming scale sustains cost leadership in institutional procurement channels. Rubbermaid sits within the resin-transition segment, its brand recognition in consumer storage translating into shed market positioning.
| Leading Market Players |
|---|
| Rubbermaid |
| DuraMax |
| Arrow Sheds |
| Timberline Barns |
| Esh's Utility Buildings |
| Lifetime |
| Palram |
| SOJAG |
| Keter |
| Others |
Supply Flow & Price Mechanics
EU embodied-carbon disclosure mandates from the CSRD framework gate qualified supply and premium-tier pricing access for garden shed manufacturers unable to verify supply chain emissions, compressing margins for non-compliant timber importers while elevating certified resin and metal producers into higher price bands.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage-timber heritage brands from roll-formed metal volume players and entry-level polyethylene imports. Price differentiation hinges on EPA-treated wood certification tier and galvanized steel gauge thickness. Cost compression in the metal tier is intensifying because zinc price volatility from Chinese smelter constraints feeds directly into roll-formed panel landed costs. Agricultural buyers in the United States exhibit highest price sensitivity; heritage-conscious suburban Australian homeowners show lowest.
Supply Chain Analysis
Resin co-extrusion feedstock rests on petrochemical complexes in Germany, Belgium, and the Netherlands supplying UV-stabilized polymer formulations across European retail channels. Raw material dependencies include high-density polyethylene resin, zinc-coated steel coil, and pressure-treated lumber certified to EPA formaldehyde emission thresholds. Single-source vulnerability concentrates in Chinese zinc smelter output governing galvanized steel pricing. Distribution runs through big-box retail chains in North America and direct-to-contractor digital platforms in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The garden sheds market functions as a stable compounder where suburban outdoor living investment drives steady replacement and expansion cycles across residential renovation budgets.
For Market Incumbents: Anchor roll-forming scale in the Southeast United States manufacturing corridor to sustain cost leadership against resin substitution threats. Defend channel position by deepening backward integration into zinc-coated steel coil supply. Prioritize ISO 9001 certification maintenance to prevent cross-border market access delays from audit backlogs freezing product launches.
For New Entrants and Emerging Players: Capture white-space in Australian cyclone-rated structural segments where national building code enforcement differentiates compliant suppliers. Target commercial landscaping procurement platforms in the United States bypassing retail markup. Deploy modular flat-pack assembly systems with pre-cut panel SKUs to compress installed cost premiums against traditional on-site builds.
For Investors and Strategic Acquirers: Valuations sit cheapest among resin co-extrusion specialists lacking polycarbonate hybrid diversification. Long-term viability favors manufacturers with verified embodied-carbon disclosure capabilities spanning the projection horizon. Target acquisition archetype: regional distribution network owners in fragmented European retail channels. Watch EPA-treated wood documentation friction as inflection indicator accelerating metal and resin substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Resin Co-Extrusion Capacity Expansion | North Rhine-Westphalia industrial basin investments unlock weather-resistant consumer segments across ECHA-compliant European retail channels. |
| Backward Integration into Zinc-Coated Steel Coil | Captive supply of galvanized feedstock insulates roll-formed metal producers from Chinese smelter output volatility. |
| Direct-to-Contractor Digital Platform Launch | Melbourne-based platform interfaces enable Australian homeowner associations to coordinate group purchasing outside traditional retail markup. |
| EU Embodied-Carbon Disclosure Certification | CSRD framework compliance differentiates shed manufacturers from stranded inventory holders unable to verify supply chain emissions. |
| Cyclone-Rated Structural Standard Adoption | Australia's national building code regulator enforcement creates tiered market access for coastal humidity zone compliant suppliers. |
Methodological Framework
Coverage spans the United States, Germany, Australia, the United Kingdom, and Japan, with primary inputs from each market combining interviews with landscape contractors, big-box retail category managers, resin co-extrusion plant engineers, and timber import compliance officers. Secondary validation draws from EPA certification databases, ECHA REACH substance restrictions, USDA biobased labeling program records, and customs trade documentation. Bottom-up demand modeling triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window. Segmentation dimensions include material composition, dimensional thresholds, construction style geometry, and end-user procurement authority. CAGRs derive from installed base replacement cycles, renovation spending elasticity, and regulatory compliance cost pass-through assumptions. Industry-specific inputs incorporate suburban backyard renovation budget allocations and remote-work-driven outdoor living space extensions.
Zinc price volatility, EPA documentation backlog duration, and ECHA chemical restriction scope expansion are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions around regulatory enforcement intensity and material substitution elasticity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Door Handles Market