
 Asia-Pacific Wall Covering Market | 2026-2036
Asia-Pacific Wall Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wall Covering Market Outlook
Hospitality developers is reorganizing procurement priorities across the Asia-Pacific Wall Covering Market, shifting volume toward experience-driven interiors that command premium rates. Sangetsu Corporation leverages its Japanese manufacturing base to sustain consistent supply of vinyl-backed textiles across ASEAN hotel chains. Shinhan Wallcoverings anchors South Korean demand through specialized digital printing capabilities for custom commercial installations. Asian Paints competes aggressively in India's fragmented retail channel, extending distribution into tier-two cities through localized dealer networks.
Wall coverings encompass decorative and protective surface materials applied to interior vertical substrates, including paper-based laminates, polyvinyl chloride films, woven textile backings, and engineered wood veneers that typically range from 0.3 to 2.0 millimeters in thickness and serve to modify acoustics, moisture resistance, and aesthetic character of built environments. Papers and vinyl categories dominate current volume, with vinyl capturing margin pools in commercial hospitality due to scrubbability and fire-retardant certifications, while fabrics and wood segments attract premium residential specification in Japan and Australia where tactile authenticity commands price premiums. The installation type dimension reveals professional application as the structural default across commercial end users, though DIY channels expand in Australia's mature housing stock where consumer confidence in self-application has risen.
China's SAMR enforces GB standards limiting formaldehyde emissions in interior decorative materials, directly shaping vinyl formulation chemistry and adhesive selection for manufacturers supplying the mainland. Japan's METI maintains JIS standards for flame resistance in public buildings, creating compliance thresholds that filter lower-specification imports from regional competitors. India's BIS certification requirements for imported wall covering materials add testing costs that advantage domestic producers like Asian Paints. Stakeholders must monitor divergence between national emission standards and installation labor qualifications as these dual regulatory vectors increasingly determine market access and project win rates across the region.
Market Dynamics
Hospitality developers across Southeast Asia are consolidating specification power, forcing material suppliers to align vinyl-backed textile production with accelerated hotel renovation cycles and stricter GB emission thresholds from China's SAMR.
Growth Catalysts
- Urban residential renovation:India's premium housing corridors in Mumbai and Bangalore compress replacement cycles, driving specification upgrades toward moisture-resistant laminates.
- GB 18580 emission limits:China's SAMR enforcement of formaldehyde thresholds filters low-grade imports, advantaging compliant domestic vinyl formulators.
- Digital printing:Custom commercial installations in South Korea leverage specialized inkjet systems for short-run hospitality murals, reducing minimum order quantities.
Market Restraints
- Petrochemical input volatility:Polyvinyl chloride resin prices fluctuate with ethylene feedstock costs, compressing margin pools for vinyl-dominant portfolios.
- Import testing burdens:India's BIS certification requirements add 8-12 week clearance timelines, disadvantaging ASEAN suppliers against Asian Paints' domestic production.
- Natural fiber substitution:Engineered wood veneers and woven textiles face displacement from lower-cost fiberglass-reinforced papers in budget commercial segments.
Strategic Opportunities
- Tier-two Indian distribution:Asian Paints' dealer network expansion into secondary cities captures underpenetrated renovation demand outside Mumbai and Bangalore.
- Fire-retardant certification convergence:Japan's METI JIS standards and Australia's NCC requirements create cross-certification efficiencies for scrubbable vinyl suppliers.
- DIY channel maturation:Australia's established housing stock supports self-application growth through retail partnerships with hardware chains.
Industry Challenges
- Skilled installer scarcity:Seamless textile application requires certified technicians, creating bottlenecks in Vietnam's hospitality construction pipeline.
- Multi-standard compliance:Divergent VOC limits between China's GB standards, Japan's JIS frameworks, and India's BIS requirements fragment formulation R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wall Covering Market |
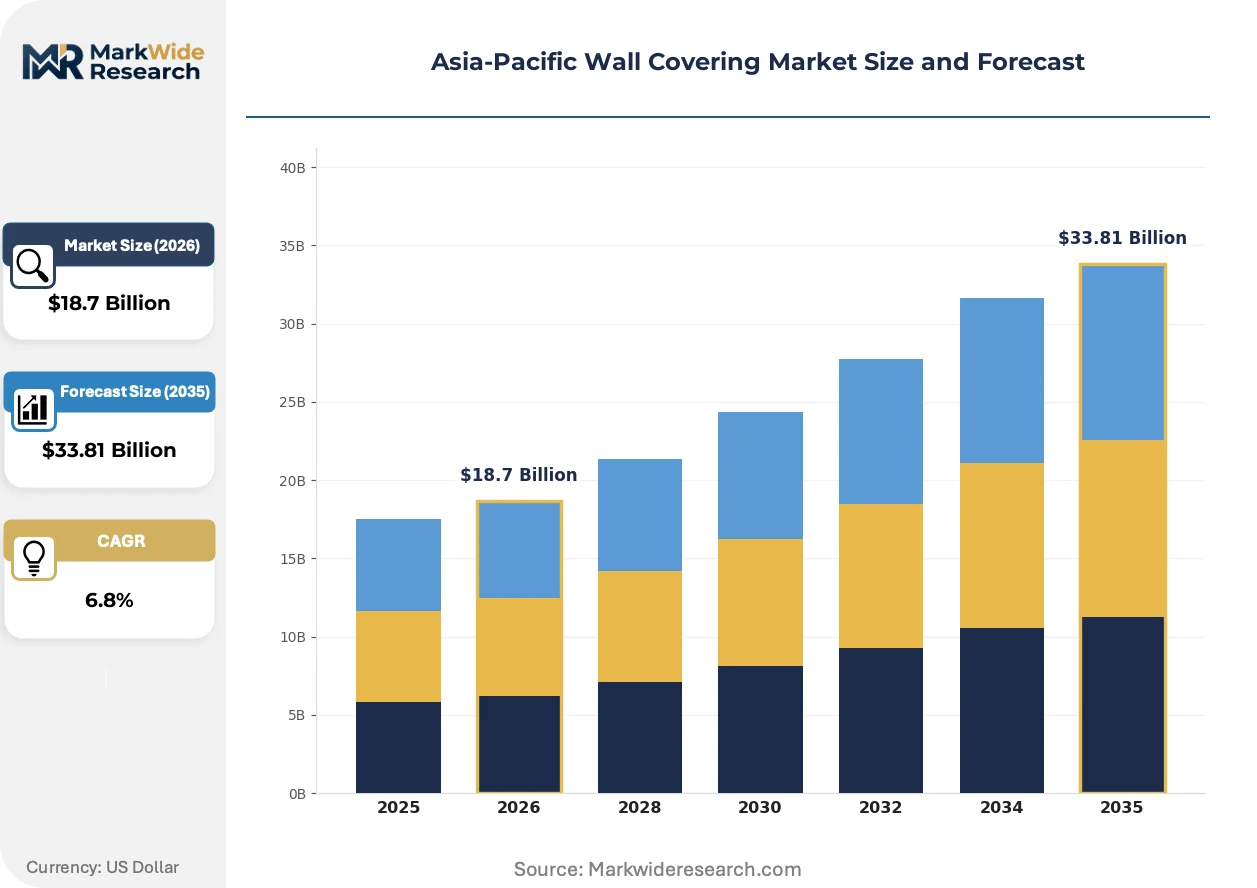
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Papers, Vinyl, Fabrics, Wood End User: Residential, Commercial, Hospitality, Retail Installation Type: DIY, Professional, Custom, Standard Design Style: Modern, Traditional, Eclectic, Minimalist |
| Companies Covered | LAMEX Wall, Elegant Haus International, JC Maison, Shinhan Wallcoverings, A.S. Création Tapeten AG, Asian Paints, York Wallcoverings, Graham & Brown, Sangetsu Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wall Covering Market Strategic Shifts
Surface engineering is compressing material thickness thresholds while expanding functional performance, as acoustic dampening and antimicrobial properties migrate from premium tiers toward mid-market specification.
Digital inkjet deposition systems are miniaturizing pattern replication costs for custom hospitality murals. Boutique hotel chains in Thailand and Indonesia adopt short-run digital wallcoverings at 500-2000 square meter batches. This technology is miniaturizing the economic minimum for bespoke interior specification, compressing lead times from twelve weeks to ten days.
China's SAMR GB 18580-2017 standard tightens formaldehyde emission caps for interior decorative materials to 0.124 milligrams per cubic meter. Vinyl manufacturers reformulate adhesive chemistries toward water-based acrylic systems. Japanese imports face accelerated testing protocols at mainland ports, advantaging domestic producers with established compliance documentation.
Specification authority is concentrating within hospitality procurement departments, displacing architect-driven material selection. Major hotel operators in Singapore and Bangkok centralize surface material decisions at regional headquarters. This consolidation compresses supplier qualification lists to three-to-five approved vendors per product category.
Asia-Pacific Wall Covering Market Segmentation
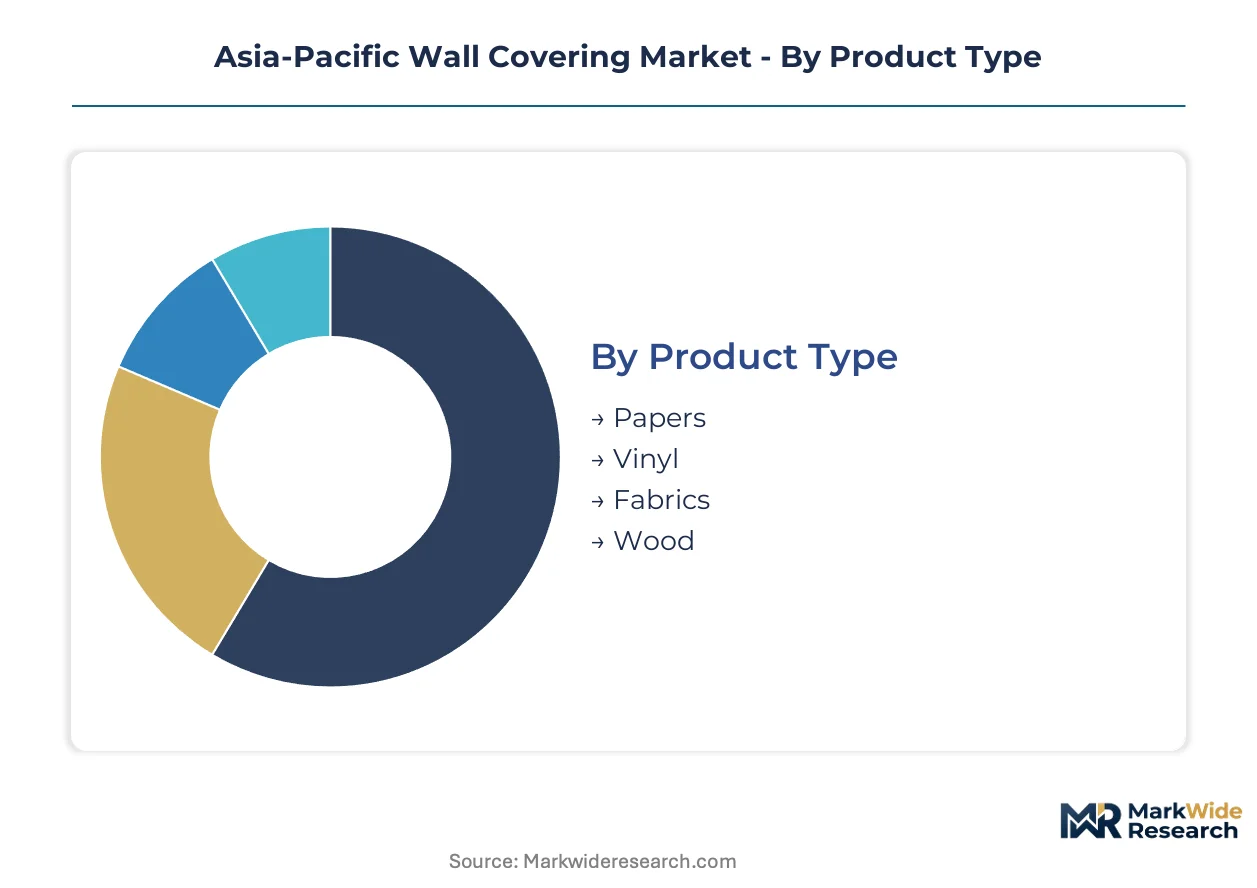
Segmentation in the Asia-Pacific Wall Covering Market reveals how material chemistry, application environment, and installation economics partition margin pools. Procurement teams in Singapore and Bangkok now segment suppliers by compliance documentation rather than price alone.
Product Type:
Substitution pressure from fiberglass-reinforced papers and low-cost laminates is compressing margin pools for natural fiber segments, forcing vinyl formulators to defend through certification differentiation.
- Papers:Cellulose-based wall coverings with printed or embossed surface treatments, typically 0.3-0.8 millimeters thick. Demand concentrates in India's budget residential renovations in tier-two cities where Asian Paints' dealer networks distribute low-unit-cost rolls, though moisture susceptibility limits bathroom and kitchen specification.
- Vinyl:Polyvinyl chloride films laminated to paper or fabric backings, engineered for scrubbability and flame-retardant compliance. Hospitality procurement across Southeast Asia concentrates specification here due to GB 18580 emission thresholds and METI JIS fire standards, with vinyl capturing commercial margin pools through certification bundling.
- Fabrics:Woven textile backings including silk, linen, and synthetic blends applied with adhesive systems. Japan's premium residential corridors in Tokyo and Osaka sustain demand where tactile authenticity commands price premiums over synthetic alternatives.
- Wood:Engineered veneers and thin-profile timber laminates, 0.6-2.0 millimeters thick, requiring specialized moisture barriers. Australia's architect-driven commercial segment specifies these for acoustic dampening in boardrooms and hospitality lobbies.
Vinyl retains volume leadership; fabrics hold the steepest expansion curve among premium tiers.
End User:
Cost tier stratification separates specification authority, with hospitality and retail consolidating procurement at regional headquarters while residential remains fragmented across dealer networks.
- Residential:Individual homeowners and rental property managers selecting through retail channels or contractor relationships. Mumbai and Bangalore's premium housing corridors compress replacement cycles, driving moisture-resistant laminate upgrades in bathroom and kitchen applications.
- Commercial:Office landlords and corporate facilities managers prioritizing durability and maintenance economics. Australia's mature commercial stock supports professional installation contracts with 5-7 year replacement horizons.
- Hospitality:Hotel operators and resort developers specifying experience-driven interiors. Major chains in Thailand and Indonesia centralize decisions at Singapore regional headquarters, compressing approved vendor lists to three-to-five suppliers per material category.
- Retail:Branded store networks and shopping mall operators requiring high-traffic durability. South Korea's digital printing capabilities enable short-run custom murals for flagship locations, reducing minimum order quantities.
Commercial captures the widest installation base; hospitality delivers the steepest margin expansion.
Installation Type:
Volume concentration in professional channels reflects commercial end-user dominance, though DIY maturation in developed housing markets is redistributing labor economics.
- DIY:Consumer self-application through retail purchase of pre-pasted or peel-and-stick products. Australia's established housing stock and hardware chain partnerships sustain this channel, with consumer confidence in self-application rising.
- Professional:Certified technician application required for commercial warranties and fire-code compliance. Vietnam's hospitality construction pipeline faces bottlenecks here, as seamless textile application demands trained installers.
- Custom:Bespoke design execution including digital-printed murals and hand-finished specialty treatments. Boutique hotel chains in Indonesia adopt 500-2000 square meter short runs with ten-day lead times.
- Standard:Catalog-pattern installation with minimal specification deviation, dominating volume residential and budget commercial segments. India's fragmented retail channel relies on this category for inventory efficiency.
Professional installation commands volume leadership; custom application climbs fastest on digital printing adoption.
Design Style:
Geography of taste preferences fragments manufacturing runs, with Japanese and Australian markets diverging from Southeast Asian pattern preferences.
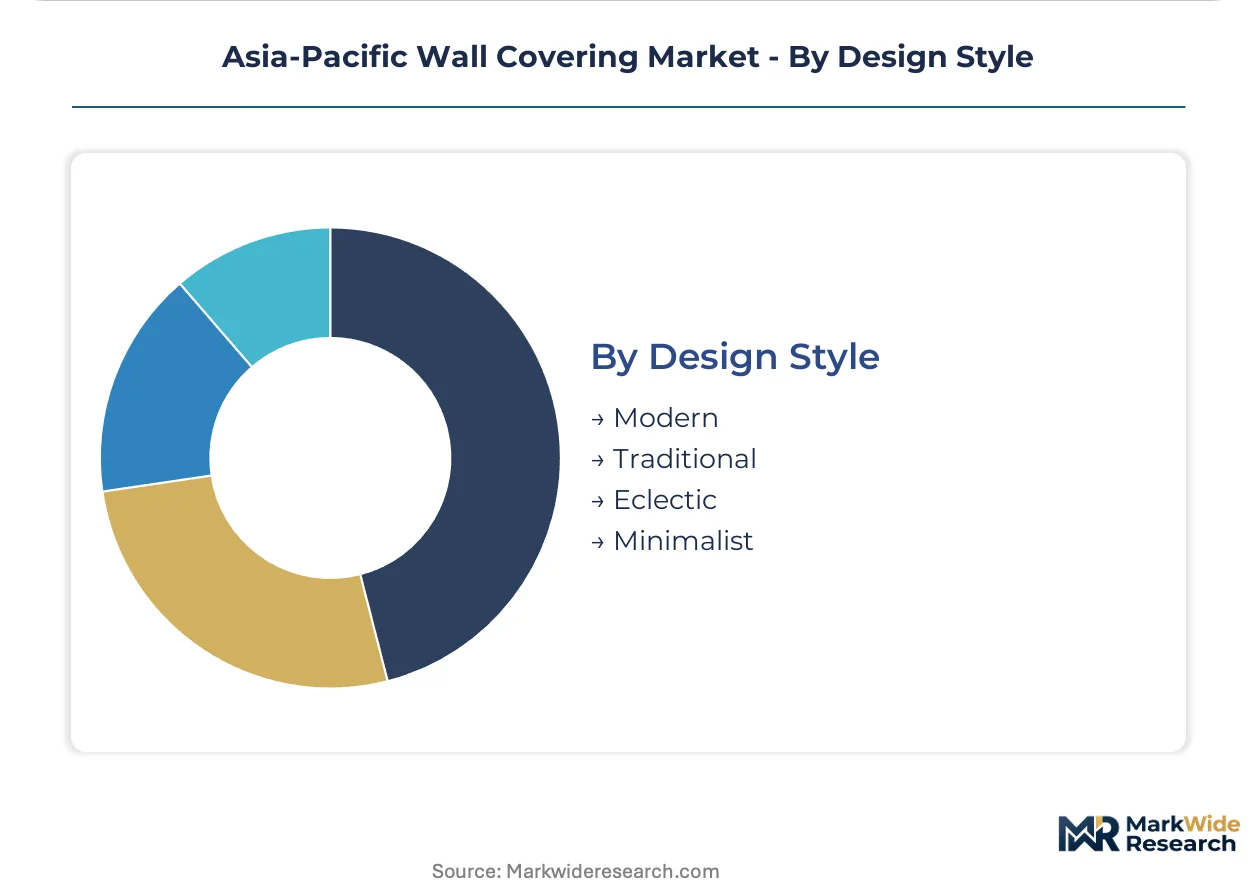
- Modern:Clean lines, geometric patterns, and solid-color fields with minimal ornamentation. South Korea's commercial interiors and Australia's corporate spaces sustain specification here.
- Traditional:Ornate patterns, historical motifs, and rich color palettes referencing regional craft traditions. India's heritage hospitality properties in Rajasthan and Kerala maintain demand.
- Eclectic:Mixed-period references and bold pattern layering for statement interiors. Bangkok and Jakarta's boutique hotel segment experiments here, though shorter trend cycles challenge inventory planning.
- Minimalist:Near-monochrome palettes with texture-as-pattern and negative space emphasis. Japan's residential specification in Tokyo's compact apartments favors this approach for spatial expansion.
Modern styling retains volume leadership; minimalist design gains fastest in premium urban residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's distribution dominance for vinyl-backed wall coverings across ASEAN hotel chains, while Singapore's Changi cargo hub enables just-in-time specification for Southeast Asian hospitality developers.
China
GB 18580-2017 emission thresholds from SAMR filter low-grade vinyl imports, advantaging domestic formulators with established compliance documentation. The Yangtze River Delta manufacturing corridor supplies scrubbable hospitality-grade materials to regional hotel operators. Shanghai's design districts concentrate specification authority for premium commercial interiors.
Japan
METI's JIS fire-resistance standards for public buildings create compliance thresholds that sustain premium positioning for domestic textile-backed products. Tokyo's compact residential stock drives minimalist specification where tactile authenticity commands price premiums. Osaka's commercial construction pipeline maintains demand for certified installer networks.
India
BIS certification requirements add clearance timelines that advantage Asian Paints' domestic production against ASEAN imports. Mumbai's premium housing corridors compress replacement cycles toward moisture-resistant laminates. Bangalore's tech-sector residential clusters accelerate specification upgrades in bathroom and kitchen applications.
South Korea
Specialized digital printing capabilities enable short-run custom murals for hospitality and retail flagship locations. Seoul's commercial interior design houses leverage inkjet systems to reduce minimum order quantities. Busan's manufacturing base supports regional export of printed vinyl to Southeast Asian boutique hotel chains.
Australia
NCC fire-code requirements converge with Japan's METI standards, creating cross-certification efficiencies for scrubbable vinyl suppliers. Sydney and Melbourne's mature housing stock supports DIY channel maturation through hardware chain partnerships. Perth's commercial construction maintains professional installation demand for acoustic-dampening wood veneers.
Asia-Pacific Wall Covering Market Competitive Environment
Concentration sits with diversified surface-material conglomerates and specialized digital printing houses across distinct national markets. The vendor base spans Japanese manufacturing conglomerates with captive vinyl compounding, South Korean inkjet specialists, and Indian paint-and-coatings giants extending into decorative surfaces. Two strategic archetypes dominate: compliance-integrated formulators leveraging GB and JIS certification bundling, and digitally agile short-run producers capturing boutique hospitality specification. Competitive moves center on backward integration into adhesive chemistry and geographic expansion through tier-two distribution partnerships.
Among Japan-based manufacturers, Sangetsu Corporation exemplifies the compliance-integrated archetype through its sustained supply positioning across ASEAN hotel chains. Shinhan Wallcoverings anchors the South Korean digital specialization vector for custom commercial installations. Asian Paints occupies a scale-driven position within India's fragmented retail channel, extending surface-material distribution through localized dealer networks into secondary cities.
| Leading Market Players |
|---|
| LAMEX Wall |
| Elegant Haus International |
| JC Maison |
| Shinhan Wallcoverings |
| A.S. Création Tapeten AG |
| Asian Paints |
| York Wallcoverings |
| Graham & Brown |
| Sangetsu Corporation |
| Others |
Value Chain & Pricing Dynamics
Fiberglass-reinforced paper substitution for woven textile backings simultaneously compresses margin pools in Southeast Asian budget commercial segments and redistributes supply geography toward China's Yangtze River Delta manufacturing corridor, where vinyl formulators exploit captive resin compounding to defend pricing power against ASEAN hospitality procurement consolidation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified hospitality-grade vinyl with GB 18580 and METI JIS bundling from moisture-resistant residential laminates and basic cellulose papers. Price differentiation hinges on compliance documentation depth and volume scale, with Singapore-based hotel operators extracting steepest discounts through centralized regional procurement. Cost compression in economy tiers intensifies because Indian BIS certification adds 8-12 week clearance timelines that advantage domestic producers. Budget commercial segments exhibit highest price sensitivity; boutique hospitality chains in Thailand and Indonesia demonstrate lowest sensitivity due to experience-driven interior mandates.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Singapore trade lane elevate inbound logistics costs for Japanese textile-backed imports serving ASEAN hotel chains. Manufacturing concentrates in China, South Korea, and Japan, with the Yangtze River Delta, Busan, and Osaka anchoring respective vinyl compounding, digital printing, and premium fabric finishing. Raw material dependencies center on polyvinyl chloride resin, ethylene feedstock, and water-based acrylic adhesive systems. Single-source vulnerability sits with China's ethylene supply concentration. Distribution runs through Singapore's Changi cargo hub for just-in-time hospitality specification across Bangkok and Jakarta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installer scarcity across Vietnam's hospitality construction pipeline and India's fragmented retail channel creates persistent capability gaps that advantage stakeholders with captive technician training infrastructure.
For Market Incumbents: Compound certification bundling advantages by deepening backward integration into water-based acrylic adhesive chemistry, defending against emerging digital printing houses in South Korea that threaten custom hospitality specification. Add capacity in India's tier-two cities to preempt Asian Paints' distribution expansion. METI JIS and Australia's NCC cross-certification investment remains the critical lever for margin defense. For New Entrants and Emerging Players: Post-installation service underperformance by established vinyl suppliers creates entry space for certified technician networks targeting Vietnam's hospitality pipeline bottlenecks. Penetrate Indonesia's boutique hotel segment through short-run digital partnerships with Seoul-based inkjet specialists. Lead with ten-day lead time guarantees for 500-2000 square meter custom mural batches. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed South Korean digital printing specialists possessing specialized inkjet systems for hospitality murals. Five-to-ten year viability hinges on convergence between GB 18580 emission thresholds and Japan's METI standards compressing compliant vendor lists. Monitor BIS certification timeline extensions as inflection signal for Indian domestic production premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | Water-based acrylic formulation control secures GB 18580 compliance for China hospitality supply. |
| Cross-Certification Investment | METI JIS and Australia's NCC alignment reduces testing duplication for ASEAN hotel chains. |
| Tier-Two Distribution Expansion | Asian Paints' dealer network model captures underpenetrated Indian renovation demand outside Mumbai. |
| Digital Printing Partnership | Seoul inkjet capabilities enable 500-2000 square meter short runs for Indonesia boutique hotels. |
| Certified Installer Network Buildout | Vietnam technician training infrastructure alleviates seamless textile application bottlenecks. |
Study Parameters
Initial hypotheses were tested against primary input from hospitality procurement directors, vinyl formulation chemists, certified installation contractors, and tier-two retail dealers, then refined through customs trade records, BIS certification databases, METI JIS compliance filings, and ASEAN hotel development pipeline tracking. Bottom-up volume builds from individual project specifications triangulated against top-down manufacturing capacity assessments across China's Yangtze River Delta, South Korea's Busan corridor, and Japan's Osaka industrial zone.
Variance decomposition across material type, end-user segment, installation channel, and national regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling, with inputs including ethylene feedstock price trajectories, GB standard enforcement intensity, and hospitality renovation cycle compression in Mumbai and Bangalore.
Underlying assumptions cover sustained SAMR emission enforcement, stable ASEAN hotel development financing, and India's BIS clearance timelines, with deviation risk concentrated in petrochemical input volatility and skilled installer availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Bookends Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Home Decor Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Interior Design Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
India Decorative Laminates Market