
 South Africa Metal Packaging Market | 2026-2036
South Africa Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Metal Packaging Market Analytics
Market Context with Strategic Players
Tool-and-die engineering capacity in the Gauteng industrial belt is bifurcating the competitive landscape between capital-heavy incumbents and emerging regional specialists. Nampak Limited leverages its integrated tinplate and aluminum can operations across Rosslyn and Durban to sustain volume leadership in beverage packaging. Ardagh Metal Packaging S.A. anchors its position through specialized two-piece aluminum can lines serving SABMiller and Coca-Cola bottling networks. Crown Holdings Inc. competes aggressively on lightweighting technology, differentiating its product portfolio for premium craft beer segments.
Technical Definition and Structural Segments
South Africa metal packaging encompasses rigid containers, closures, and semi-rigid forms fabricated from aluminum, steel, tinplate, or metal composites, typically ranging from 0.15mm to 0.45mm in wall thickness depending on structural requirements and internal pressure loads. These structures provide barrier protection against oxygen, light, and moisture for shelf-stable goods, with surface coatings and internal linings engineered to prevent metal-ion migration and preserve product integrity. Cans dominate volume throughput across the Food & Beverage end-user channel, where aluminum two-piece beverage containers command the fastest expansion due to recycling economics and downgauging advances. Steel food cans retain mature, stable demand in ambient shelf-stable categories, while tinplate aerosol tubes in Personal Care applications concentrate margin pools through specialized valve and coating specifications.
Regulatory Frame and Forward-Looking Close
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility frameworks that obligate metal packaging producers to fund and manage post-consumer collection and recycling infrastructure. The South African Bureau of Standards mandates SANS 10213 compliance for food-contact metal containers, while National Regulator for Compulsory Specifications certification governs aerosol and pressurized packaging safety standards. These regulatory layers elevate capital requirements for new entrants and reshape procurement criteria toward verified recycled content and circular design. Stakeholders must monitor evolving carbon border adjustment mechanisms in key export destinations and align capex planning with domestic recycling capacity buildouts.
Market Dynamics
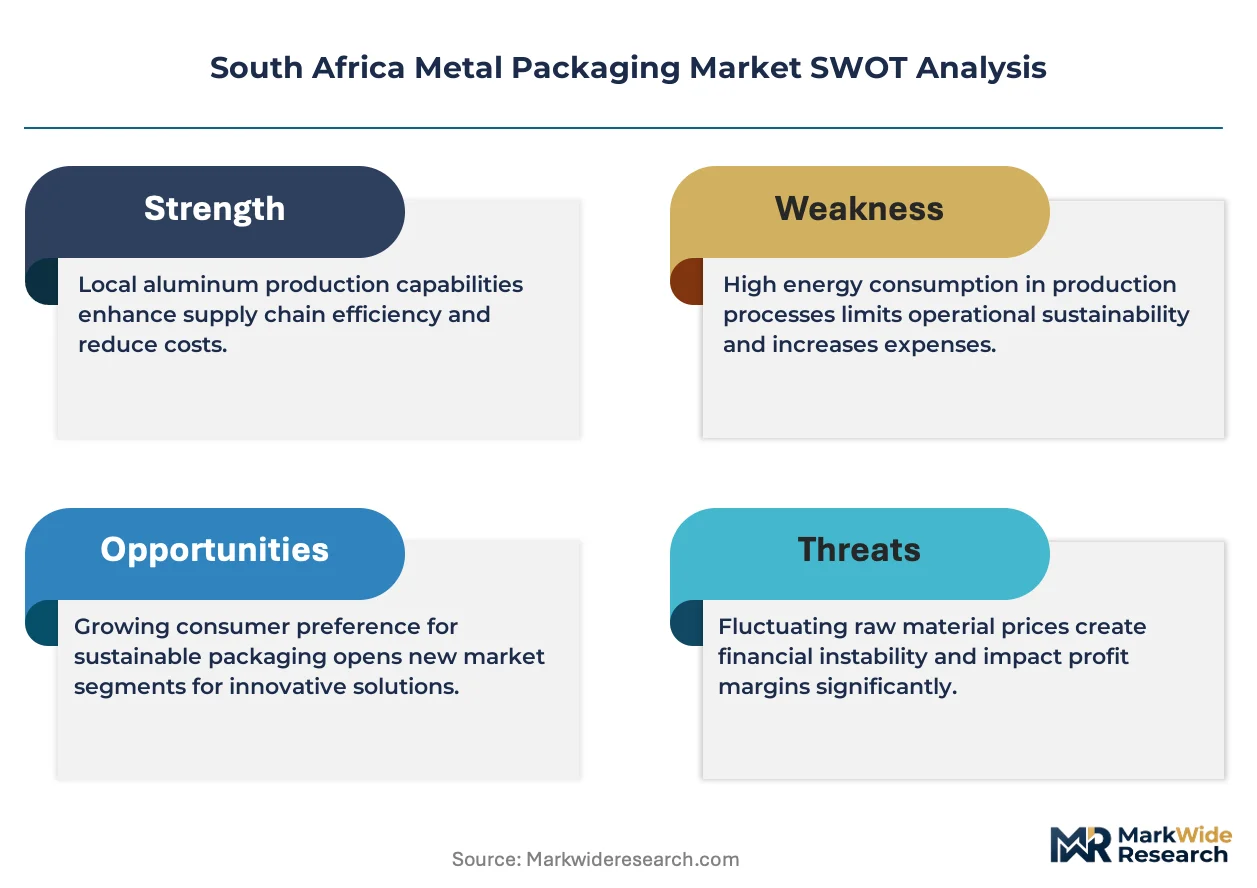
South Africa's extended producer responsibility regulations are compressing converter margins while forcing capital redeployment toward closed-loop recycling infrastructure and verified recycled content verification systems.
Growth Catalysts
- EPR Compliance Deadlines:The Department of Forestry, Fisheries and the Environment mandates producer-funded collection networks, accelerating investment in automated sorting and alloy separation capabilities.
- Craft Beverage Expansion:Gauteng and KwaZulu-Natal microbreweries are converting from glass to aluminum two-piece cans for distribution efficiency and shelf differentiation.
- Downgauging Technology:Advanced draw-and-wall-ironing equipment enables 0.15mm wall thickness in beverage containers, reducing aluminum unit consumption per can.
Market Restraints
- Tinplate Import Dependency:Domestic cold-rolling capacity constraints force reliance on Chinese and European tinplate suppliers, exposing converters to freight cost volatility and currency fluctuation.
- Steel Can Substitution:Retort pouch formats in ambient pet food and ready meals are displacing cylindrical steel containers in volume-sensitive logistics chains.
- Tool-and-Die Bottleneck:Gauteng's limited precision engineering capacity creates 14-18 month lead times for new can-end forming equipment.
Strategic Opportunities
- Western Cape Wine Canning:Premium wine producers in Stellenbosch and Paarl are piloting aluminum bottles and slim cans for outdoor consumption occasions and export logistics.
- Aerosol Pharma Expansion:Metered-dose inhaler demand from South Africa's respiratory therapeutic market is creating specification-grade tinplate tube opportunities.
- Recycling Infrastructure Gaps:Informal collector networks in township economies represent untapped feedstock aggregation points for formal smelter offtake agreements.
Industry Challenges
- Lacquer Chemist Scarcity:South Africa's technical training pipeline produces insufficient coating formulation specialists for epoxy-phenolic and organosol internal lining development.
- SANS 10213 Certification Timelines:Food-contact safety testing at accredited laboratories extends new product qualification cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Metal Packaging Market |
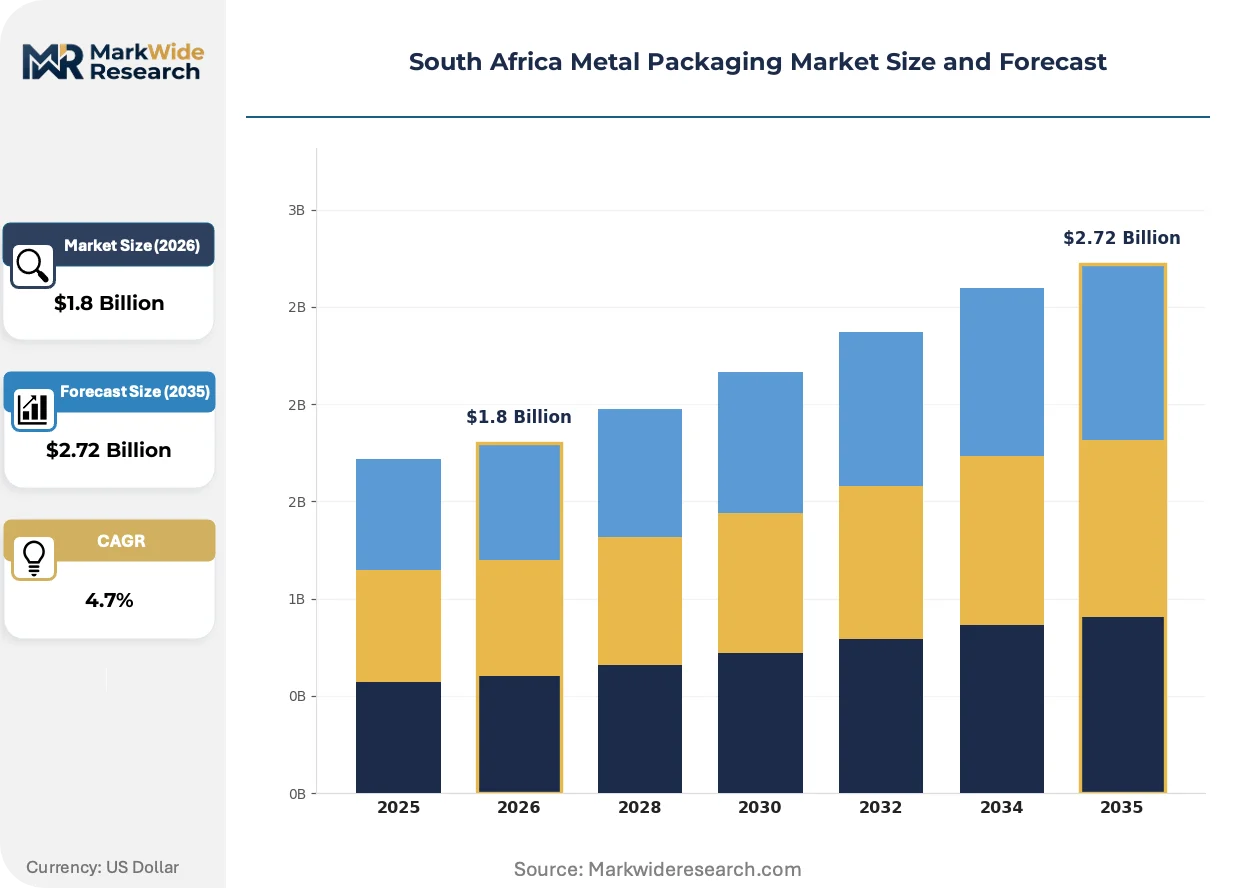
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Bottles, Tubes, Closures Material: Aluminum, Steel, Tinplate, Metal Composites End User: Food & Beverage, Personal Care, Pharmaceuticals, Industrial Application: Packing, Storage, Dispensing, Transportation |
| Companies Covered | Nampak Limited, Ardagh Metal Packaging S.A., Crown Holdings Inc., Ball Corporation, CAN-PACK S.A., Metpac SA, Metal Box South Africa, Nampak Bevcan Limited, Envirocan Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Metal Packaging Market Evolving Landscape
Active innovation across South Africa's metal packaging sector concentrates on lightweighting automation, regulatory compliance infrastructure, and downstream recycling integration rather than fundamental material substitution.
Digital printing technology is miniaturizing. Direct-to-can inkjet systems from European suppliers enable 24-hour design-to-production turnaround for promotional beverage runs. SABMiller's bottling network is adopting this capability for seasonal limited editions. The technology is compressing minimum order quantities from 500,000 units toward 50,000, enabling brand fragmentation.
Regulatory enforcement is intensifying. The Department of Forestry, Fisheries and the Environment's 2024 EPR implementation rules obligate metal packaging producers to achieve 70% post-consumer collection rates by 2028. This mandate is forcing converters to pre-fund municipal separation infrastructure and integrate informal waste picker networks into formal supply chains. Beverage can manufacturers face the steepest compliance cost escalation.
Buyer consolidation is restructuring procurement. Mass retail chains in Johannesburg-Pretoria and Durban are centralizing packaging specifications across private-label food and beverage lines. This concentration is displacing fragmented converter relationships with national framework agreements tied to recycled content verification and carbon footprint disclosure. The shift is most visible in canned vegetable and legume sourcing.
South Africa Metal Packaging Market Segmentation
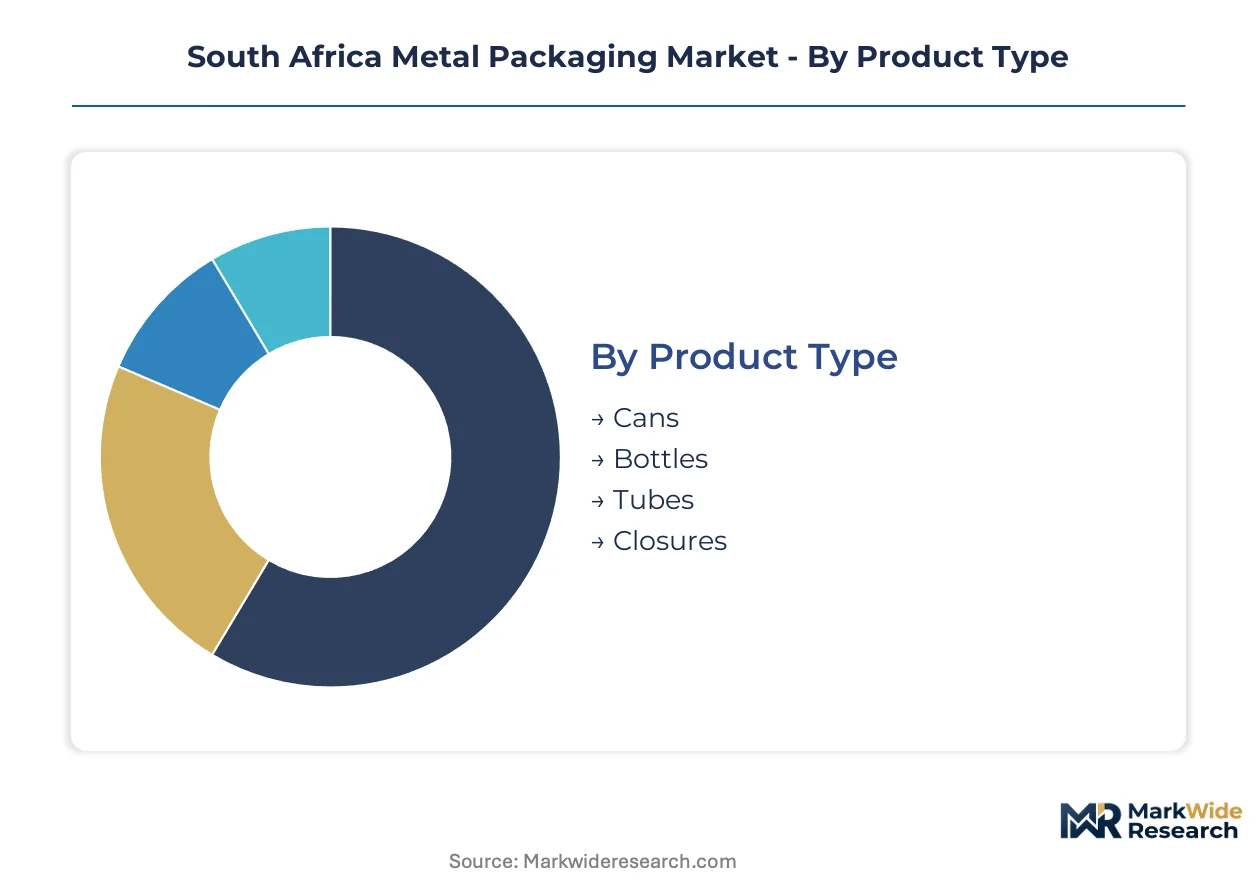
Metal packaging demand across South Africa fragments along material performance requirements and end-use regulatory intensity. Each segment carries distinct tooling investments and recycling obligation profiles under extended producer responsibility frameworks.
Product Type:
Domestic consumption concentrates in beverage and food cans around Johannesburg-Pretoria and Durban corridors, while tube and closure exports serve SADC pharmaceutical and personal care manufacturers.
- Cans:Two-piece aluminum beverage containers and three-piece steel food cans dominate volume throughput. Beverage can demand from SABMiller and Coca-Cola bottling networks concentrates in Gauteng, with craft brewery adoption accelerating in KwaZulu-Natal. Draw-and-wall-ironing equipment enables sub-0.20mm wall specifications.
- Bottles:Aluminum wine bottles and shaped beverage containers serve premium positioning for Stellenbosch and Paarl producers targeting export logistics efficiency. Pilot lines are scaling for outdoor consumption occasions.
- Tubes:Tinplate aerosol and collapsible tubes concentrate in Personal Care applications. Metered-dose inhaler specifications from South Africa's respiratory therapeutic market drive specialized valve and coating requirements.
- Closures:Crown corks, screw caps, and dispensing closures complete container systems. Food-contact safety testing under SANS 10213 extends qualification timelines for new closure-liner combinations.
Cans command the established base. The steepest expansion runs through bottles.
Material:
Cost tier stratification separates high-volume aluminum beverage applications from specification-grade tinplate pharmaceutical tubes.
- Aluminum:Two-piece beverage cans leverage infinite recyclability and downgauging economics. Domestic smelter offtake agreements with informal collector networks are securing post-consumer feedstock under EPR mandates.
- Steel:Tin-coated and chrome-coated steel retains stable demand in ambient shelf-stable food categories. Cold-rolling capacity constraints force import dependency from Chinese and European suppliers.
- Tinplate:Low-carbon steel substrate with tin coating provides corrosion resistance for aerosol and food applications. Sourcing volatility exposes converters to freight cost fluctuations and currency risk.
- Metal Composites:Laminated and polymer-lined metal forms address barrier requirements for aggressive contents. Limited domestic formulation capacity constrains local production scale.
Aluminum anchors volume leadership. Tinplate captures the steepest margin expansion.
End User:
Application maturity varies from fragmented craft beverage procurement to consolidated mass retail framework agreements.
- Food & Beverage:Canned vegetables, legumes, and beverages concentrate procurement through Johannesburg-Pretoria and Durban retail chains. Private-label centralization is displacing fragmented converter relationships with national agreements tied to recycled content verification.
- Personal Care:Aerosol deodorants and hair care products drive tinplate tube demand. Specialized valve and coating specifications concentrate margin pools through technical differentiation.
- Pharmaceuticals:Metered-dose inhaler tubes and primary packaging for respiratory therapeutics require specification-grade tinplate. CDSCO-aligned compliance elevates qualification barriers for new entrants.
- Industrial:Chemical and lubricant containers face substitution pressure from polymer alternatives. Volume-sensitive logistics chains are shifting toward composite formats.
Food & Beverage commands the established base. Pharmaceuticals present the steepest specification-grade expansion.
Application:
Functional requirements separate high-barrier preservation formats from logistics-optimized transportation systems.
- Packing:Primary containment functions dominate aluminum beverage can and steel food can deployment. Internal epoxy-phenolic and organosol linings prevent metal-ion migration.
- Storage:Ambient shelf-stable categories rely on steel container hermetic sealing. Retort pouch substitution is displacing cylindrical formats in pet food and ready meals.
- Dispensing:Aerosol valves and pump mechanisms integrate with tinplate tube bodies. Personal Care and Pharmaceutical end-users drive precision engineering requirements.
- Transportation:Lightweight aluminum formats optimize export logistics for wine and craft beverage producers. Durban port logistics zones concentrate outbound shipment consolidation.
Packing commands the established base. Transportation applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Forestry, Fisheries and the Environment anchors regulatory enforcement across South Africa's metal packaging corridors, with provincial industrial clusters adapting EPR mandates to local collection infrastructure capacity.
Gauteng
SABMiller and Coca-Cola bottling networks drive aluminum two-piece can demand through Johannesburg-Pretoria manufacturing clusters. The provincial environmental affairs department enforces municipal separation infrastructure funding under national EPR rules. Rosslyn industrial belt hosts integrated tinplate and aluminum operations with captive tool-and-die engineering capacity.
KwaZulu-Natal
Craft brewery conversion from glass to aluminum accelerates around Durban port logistics zones for export efficiency. Extended producer responsibility regulations obligate producer-funded collection networks in eThekwini municipality. Pinetown-New Germany industrial corridor concentrates can-end forming equipment and downstream coating operations.
Western Cape
Stellenbosch and Paarl wine producers pilot aluminum bottles and slim cans for outdoor consumption occasions. Provincial environmental compliance deadlines for 70% post-consumer collection rates by 2028 pressure Cape Town metro separation infrastructure. Somerset West packaging converters test direct-to-can digital printing for promotional limited editions.
Eastern Cape
Port Elizabeth automotive supplier networks generate secondary demand for industrial lubricant containers and metal shipping formats. Provincial waste management regulations lag national EPR implementation timelines, creating compliance gap risks. Coega industrial development zone attracts tinplate tube manufacturers targeting SADC pharmaceutical export markets.
South Africa Metal Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-heavy incumbents controlling beverage can volume throughput while regional specialists capture specification-grade pharmaceutical and personal care segments. The competitive landscape bifurcates around tool-and-die engineering capacity in the Gauteng industrial belt. Strategic archetypes include integrated converters with captive smelter relationships, precision coating specialists serving aerosol applications, and digital printing adopters compressing promotional run minimums. Dominant competitive moves center on backward integration into recycling infrastructure and technology licensing for downgauging equipment.
Among South Africa-based converters, Nampak Limited and Nampak Bevcan Limited exemplify integrated leadership through combined tinplate and aluminum operations across multiple provincial corridors. Ardagh Metal Packaging S.A. and Crown Holdings Inc. represent multinational-tier positioning through specialized two-piece aluminum lines and lightweighting technology portfolios. CAN-PACK S.A. and Envirocan Limited occupy mid-tier specialist positions focused on regional beverage network servicing and environmental compliance infrastructure.
| Leading Market Players |
|---|
| Nampak Limited |
| Ardagh Metal Packaging S.A. |
| Crown Holdings Inc. |
| Ball Corporation |
| CAN-PACK S.A. |
| Metpac SA |
| Metal Box South Africa |
| Nampak Bevcan Limited |
| Envirocan Limited |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between beverage can manufacturers and aluminum smelters lock in feedstock access while anchoring price visibility across volatile LME cycles. These contracts insulate converters from spot market swings but embed minimum volume commitments that strain working capital during demand softening.
Pricing Analysis
Price spreads between Johannesburg-Pretoria and Durban corridors reflect inland freight premiums and port proximity advantages. Three-tier pricing structure across premium specification-grade, standard beverage can, and economy food can levels stratifies around certification burden and alloy purity. Cost compression in standard beverage tiers intensifies because EPR compliance fees are flowing through to converter invoices. Mass retail chains exhibit highest price sensitivity through centralized procurement, while pharmaceutical aerosol buyers prioritize specification compliance over unit economics.
Supply Chain Analysis
Durban port congestion on Asia-South Africa trade lanes elevates container demurrage costs for tinplate coil imports. Domestic cold-rolling capacity constraints draw primary steel substrate from Chinese and European mills, with alloy coatings sourced from specialized Southeast Asian processors. Single-source vulnerability concentrates in precision tool-and-die engineering where Gauteng's limited capacity creates equipment procurement bottlenecks. Distribution runs through Johannesburg-Pretoria manufacturing clusters for inland beverage networks and Durban port zones for export-bound wine and pharmaceutical formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across craft beverage procurement and informal recycling networks creates niche entry points for specialized converters. Private-label centralization at mass retail chains simultaneously compresses margins for undifferentiated volume players.
For Market Incumbents: Secure backward integration into informal collector networks to lock in post-consumer aluminum feedstock ahead of EPR collection rate deadlines. Invest in captive tool-and-die engineering capacity to bypass Gauteng equipment lead time bottlenecks. Retort pouch substitution in ambient food categories threatens cylindrical steel can volumes, requiring coating technology diversification into barrier film lamination.
For New Entrants and Emerging Players: Anchor in Western Cape wine canning pilots where premium positioning tolerates higher unit costs and specification-grade requirements exclude volume incumbents. Target metered-dose inhaler tube manufacturing for South Africa's respiratory therapeutic market, where CDSCO-aligned compliance barriers filter out commodity competitors. Lead with direct-to-can digital printing capability to capture promotional run fragmentation from SABMiller's seasonal limited edition programs.
For Investors and Strategic Acquirers: Precision coating specialists with aerosol valve integration capabilities represent the most defensible acquisition profile in this market. Long-term viability hinges on circular infrastructure ownership rather than conversion equipment scale. Watch informal collector network formalization rates as the inflection signal for feedstock security premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Captures post-consumer aluminum feedstock ahead of EPR collection mandates from the Department of Forestry, Fisheries and the Environment. |
| Direct-to-Can Digital Printing Deployment | Compresses minimum order quantities from mass retail scale toward craft brewery promotional runs in Gauteng and KwaZulu-Natal. |
| Precision Coating Capacity Expansion | Addresses lacquer chemist scarcity for epoxy-phenolic internal lining development in pharmaceutical aerosol applications. |
| Western Cape Wine Canning Pilot Scale-Up | Targets aluminum bottle adoption by Stellenbosch and Paarl producers for outdoor consumption occasion expansion. |
| Tool-and-Die Engineering Captive Investment | Bypasses 14-18 month equipment lead times constraining new can-end forming capacity in the Rosslyn industrial belt. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with beverage procurement managers at SABMiller and Coca-Cola bottling networks, coating formulation specialists at tinplate tube manufacturers, and informal waste picker cooperative organizers. Secondary validation drew from South African Bureau of Standards SANS 10213 certification records, Department of Forestry, Fisheries and the Environment EPR implementation filings, and aluminum trade flow data through Durban port authorities. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Across the analysis window, forecasts employed segmented modeling across material type, end-use channel, and provincial production corridor dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory phase-in intensity and recycling infrastructure buildout pacing. Industry-specific inputs included craft brewery conversion rates from glass to aluminum and metered-dose inhaler prescription growth in South Africa's respiratory therapeutic market.
Material uncertainties — tinplate import tariff volatility, informal collector network formalization delays, and carbon border adjustment mechanism adoption in key export destinations — sit outside the modeled envelope. Forecasts reflect documented assumptions about EPR compliance cost pass-through and smelter offtake agreement renewal rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Metal Pails Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Metal Drums Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Tin Cans Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
Brass Foils Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
PTP Aluminum Foil Market