
 Indonesia Metal Packaging Market | 2026-2036
Indonesia Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Metal Packaging Market Foresight
Processed food demand among Indonesian urban consumers is realigning metal packaging procurement toward higher-volume, shelf-stable formats. Crown Holdings dominates beverage can supply through its regional manufacturing footprint. PT Pelangi Indah Canindo Tbk specializes in decorative tinplate containers for premium gift segments. Rheem Indonesia leverages its technical heritage to sustain industrial drum and pail production for chemical applications.
Indonesia metal packaging encompasses rigid and semi-rigid containers fabricated from aluminum, steel, and tinplate substrates through drawing, ironing, welding, or seaming processes, engineered to provide barrier protection against moisture, oxygen, and light for perishable and sensitive contents. Cans capture the largest volume share within product type categories, driven by carbonated soft drink and processed seafood filling lines. Aluminum material demand is accelerating fastest as lightweighting imperatives reduce freight costs across Indonesia's archipelagic distribution network. Food and beverages application segments anchor the majority of tinplate procurement, while pharmaceutical-grade specifications command premium positioning.
BIS-equivalent Indonesian national standards and the Ministry of Industry's food-contact material regulations shape substrate purity and coating compliance obligations for domestic producers. The Ministry of Health's pharmaceutical packaging guidelines further segment market access through sterilization-grade certification requirements. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate recycling mandates that will determine capital allocation toward circular production systems.
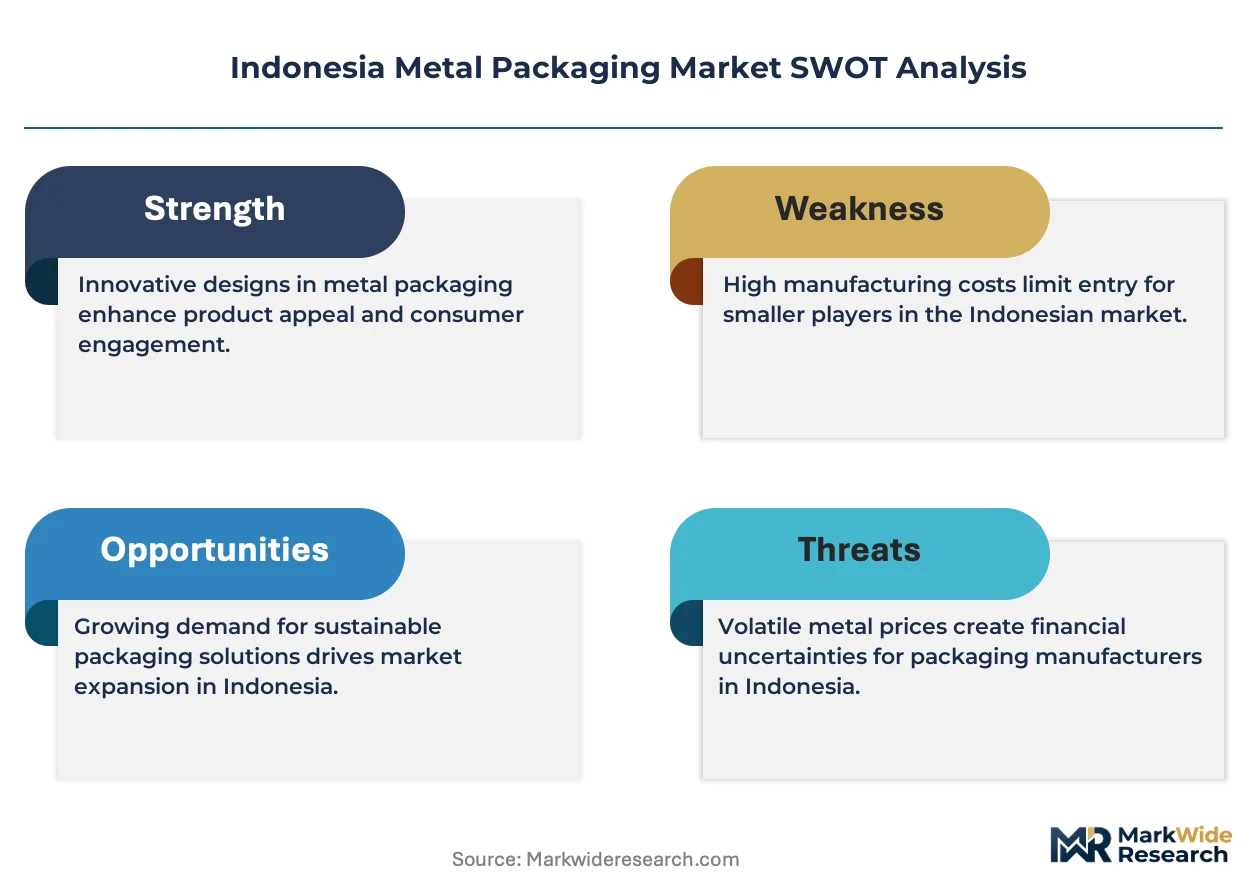
Market Dynamics
Indonesia's archipelagic distribution network is compressing logistics tolerances, forcing lightweight aluminum substitution and regionalized production footprints to offset freight cost penalties across island supply chains.
Growth Catalysts
- Urban Processed Food Consumption:Jakarta and Surabaya manufacturing clusters are expanding filling-line capacity for shelf-stable seafood and ready-meal formats, pulling tinplate procurement toward higher-volume runs.
- BIS-Equivalent Standards Alignment:The Ministry of Industry's food-contact material regulations are accelerating substrate purity investments among domestic producers seeking export-equivalent certification.
- Aluminum Lightweighting:Drawing and ironing process improvements are reducing can wall thickness, cutting per-unit shipping weight for beverage distributors serving outer-island markets.
Market Restraints
- Tinplate Input Cost Volatility:Cold-rolled steel substrate prices fluctuate with regional scrap metal flows, compressing margin predictability for decorative container specialists.
- Java-Centric Supply Concentration:Over 70 percent of domestic metal packaging fabrication capacity sits within a 200-kilometer radius of Jakarta, exposing national distribution to single-point disruption risks.
- Plastic Pouch Substitution:Flexible laminate formats for condiments and cooking oils are capturing share in price-sensitive rural channels where barrier performance requirements are less stringent.
Strategic Opportunities
- Sumatra and Sulawesi Underpenetration:Secondary cities outside Java present greenfield demand for regional canning facilities serving local palm oil and spice processing clusters.
- Extended Producer Responsibility Tailwinds:Pending Ministry of Environment recycling mandates will favor producers with integrated aluminum collection and re-melt capabilities.
- Digital Printing Convergence:UV-cured inkjet systems combined with variable-data seaming are enabling short-run premium customization for seasonal gift tin segments.
Industry Challenges
- Coating Chemist Talent Scarcity:Formulation expertise for BPA-NI epoxy alternatives remains concentrated among a handful of technical specialists, slowing compliance transitions.
- Pharmaceutical Sterilization Certification Timelines:Ministry of Health validation protocols for aseptic canning lines extend qualification periods by 8-14 months versus food-grade equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Metal Packaging Market |
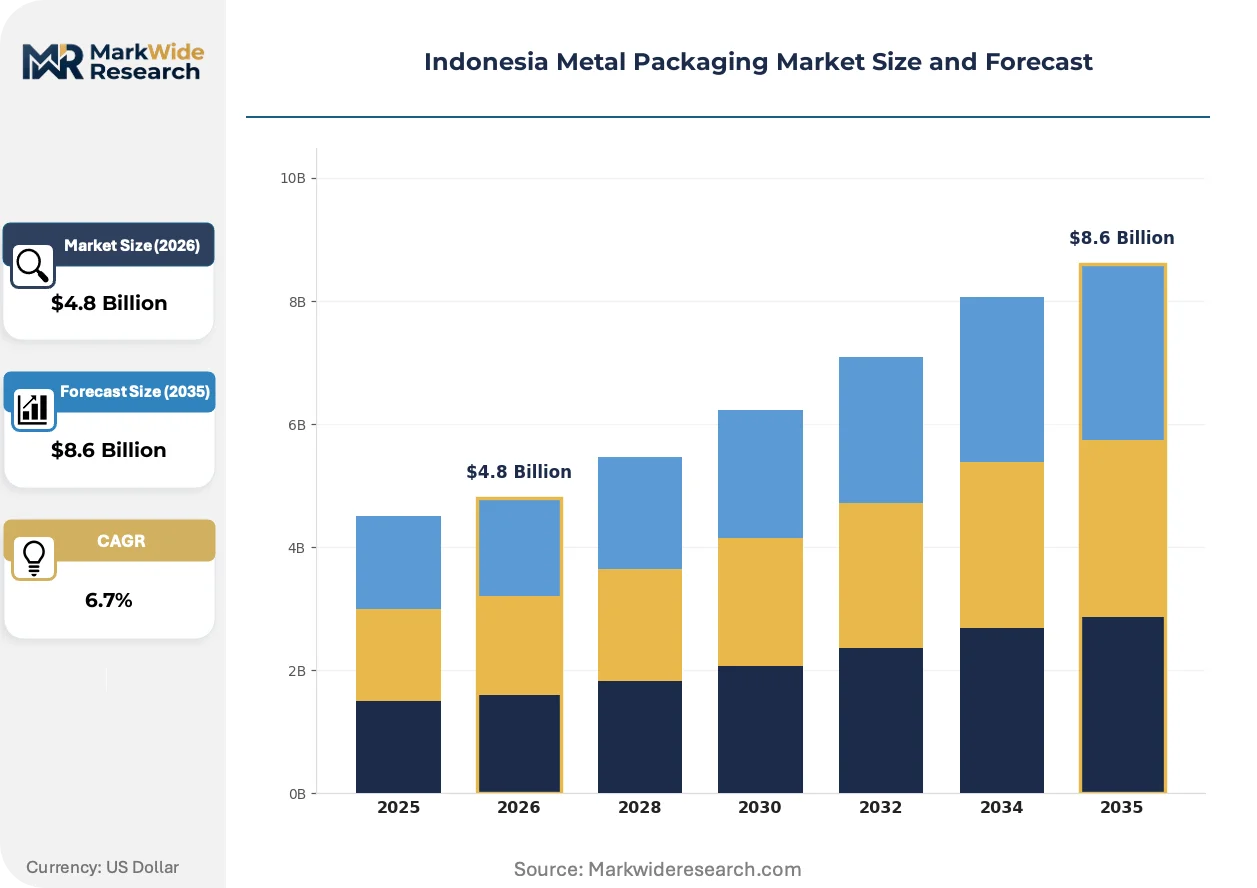
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Foils, Closures, Containers Material: Aluminum, Steel, Tinplate, Others Application: Food & Beverages, Personal Care, Pharmaceuticals, Chemicals End User: Manufacturers, Distributors, Retailers, Exporters |
| Companies Covered | Sonoco Products Company, Rheem Indonesia, PT Pelangi Indah Canindo Tbk, PT Cometa Can Corporation, PT Indonesia Raya Makmur, Crown Holdings, PT Indonesia Multi Colour Printing, P.T. New Red & White, PT United Can Company Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Metal Packaging Market Shifts & Advancements
Material science advances and regulatory precision are converging to redefine barrier performance standards and production economics across Indonesian metal packaging operations.
Polymer-ceramic hybrid coatings are unifying oxygen scavenging and corrosion resistance in single-layer application, eliminating multi-pass coating lines. Beverage can producers in the Tangerang corridor are adopting these systems at pilot scale. This unifying technology is compressing capital requirements for new entrant canmakers by 30-40 percent versus conventional epoxy-phenolic infrastructure.
Indonesia's BIS-equivalent national standards for food-contact materials are tightening migration limit testing protocols for heavy metals and primary aromatic amines. Domestic tinplate importers must now submit batch-level coating composition certificates to the Ministry of Industry's technical directorate. Small-scale decorative tin producers lacking in-house laboratory capabilities are outsourcing compliance testing to third-party Jakarta laboratories, extending procurement cycles.
Direct-to-manufacturer procurement is consolidating purchasing authority among multinational beverage and processed food anchors, displacing traditional distributor intermediaries. Brand owners in the carbonated soft drink and canned seafood verticals are negotiating multi-year aluminum supply agreements with mill-direct pricing clauses. This pattern is most pronounced in the Bekasi and Sidoarjo industrial zones where filling-line consolidation has concentrated buyer power among five anchor accounts.
Indonesia Metal Packaging Market Segmentation
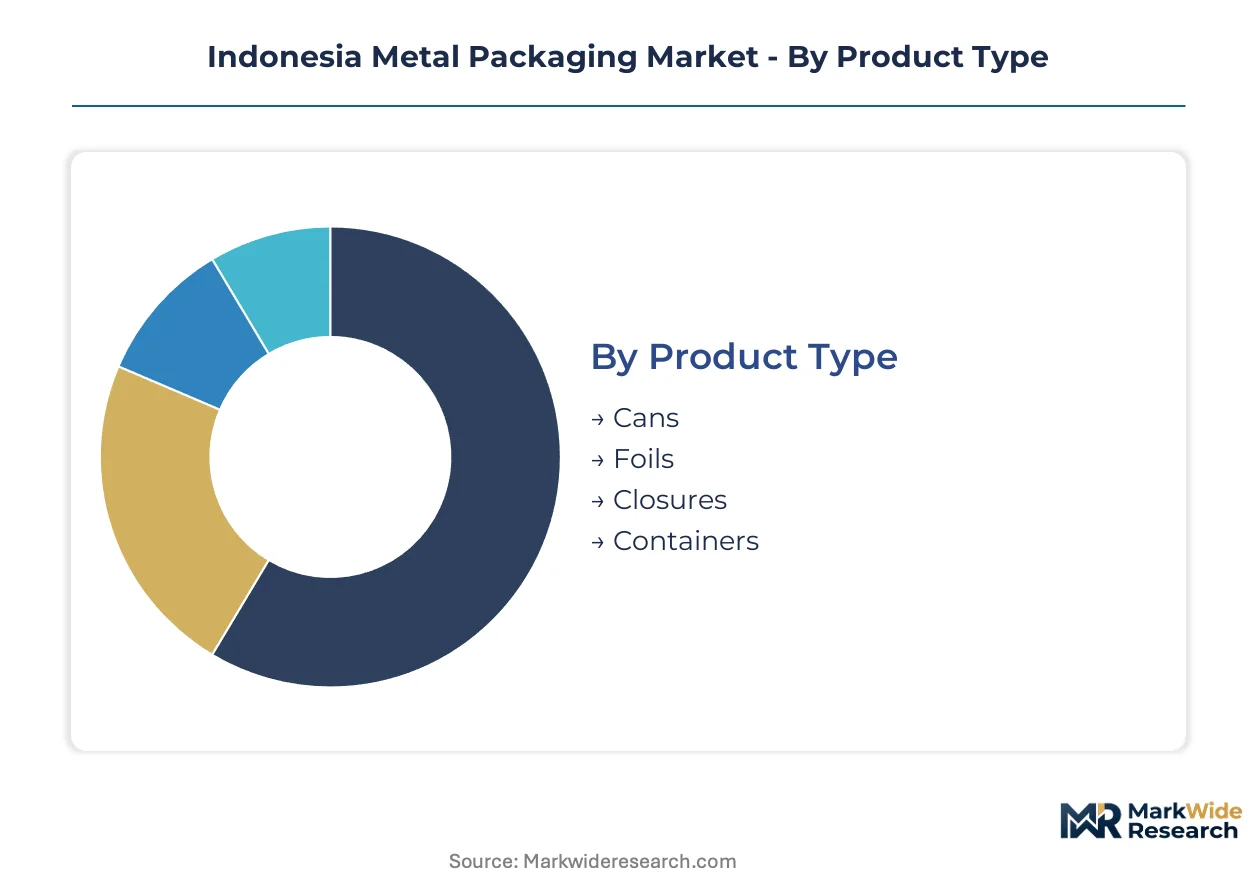
Metal packaging procurement in Indonesia diverges sharply by substrate physics and end-use sterility requirements. Each segmentation axis carries distinct capital obligations, regulatory exposure, and logistics constraints that shape supplier positioning.
Product Type:
Drawing and ironing lines for two-piece beverage cans demand the heaviest upfront capital outlays, while foil rolling mills and closure stamping presses operate at lower fixed-cost thresholds.
- Cans:Two-piece aluminum beverage cans and three-piece food cans dominate volume through drawing, ironing, and seaming processes. Bekasi and Sidoarjo filling-line clusters pull procurement toward higher-volume runs for carbonated soft drinks and processed seafood. Ministry of Industry food-contact certification requirements are compressing supplier qualification timelines.
- Foils:Thin-gauge aluminum foil for flexible laminate integration and household wrap applications. Tangerang corridor converters are expanding cold-rolling capacity to serve instant noodle and confectionery barrier layers. Lightweighting imperatives across Indonesia's archipelagic distribution network accelerate substitution for rigid alternatives.
- Closures:Crown caps, screw caps, and lug caps fabricated from tinplate or aluminum strip. Pharmaceutical-grade liner specifications command premium positioning against commodity beverage applications.
- Containers:Industrial drums, pails, and decorative tins spanning chemical handling to premium gift segments. Rheem Indonesia sustains technical leadership in welded steel drum production for Surabaya petrochemical clusters.
Cans absorb the bulk of installed capacity; foils are expanding most quickly.
Material:
Substrate selection in Indonesia tracks freight economics and regulatory migration limits more than input cost alone, with aluminum commanding logistics premiums and tinplate retaining food-safety certification advantages.
- Aluminum:Cold-rolled sheet and coil for beverage cans, foils, and lightweight closures. Drawing and ironing process improvements are reducing wall thickness to cut per-unit shipping weight for outer-island distributors serving Sulawesi and Papua markets.
- Steel:Cold-rolled substrate for industrial drums, pails, and structural containers. Chemical sector demand in Surabaya manufacturing clusters sustains volume through corrosion-resistant coating specifications.
- Tinplate:Electrolytically tin-coated steel for food cans, closures, and decorative tins. BIS-equivalent national standards are tightening batch-level coating composition certification requirements for domestic importers.
- Others:Chromium-coated steel and polymer-laminated substrates for niche pharmaceutical and high-acid food applications. Limited domestic production capacity forces reliance on regional mill imports.
Aluminum claims the steepest expansion trajectory as lightweighting penetrates beverage distribution; tinplate retains defensive positioning in shelf-stable food certification.
Application:
Application segmentation maps directly to sterilization-grade requirements and barrier performance specifications, with pharmaceutical and chemical verticals imposing capital-intensive qualification protocols that food and beverage lines avoid.
- Food & Beverages:Carbonated soft drinks, processed seafood, ready-meals, and cooking oils in cans, foils, and closures. Jakarta and Surabaya manufacturing clusters anchor procurement concentration for shelf-stable formats.
- Personal Care:Aerosol cans, tinplate gift boxes, and aluminum tubes for cosmetics and fragrances. Digital printing convergence is enabling short-run seasonal customization for premium gift segments.
- Pharmaceuticals:Sterilization-grade cans, aluminum blister foils, and child-resistant closures. Ministry of Health validation protocols extend aseptic canning line qualification periods substantially versus food-grade equivalents.
- Chemicals:Industrial drums, pails, and tight-head containers for lubricants, agrochemicals, and specialty solvents. Surabaya petrochemical corridor demand sustains welded steel drum production.
Food and beverages command the majority of substrate procurement; pharmaceuticals impose the most stringent certification barriers to entry.
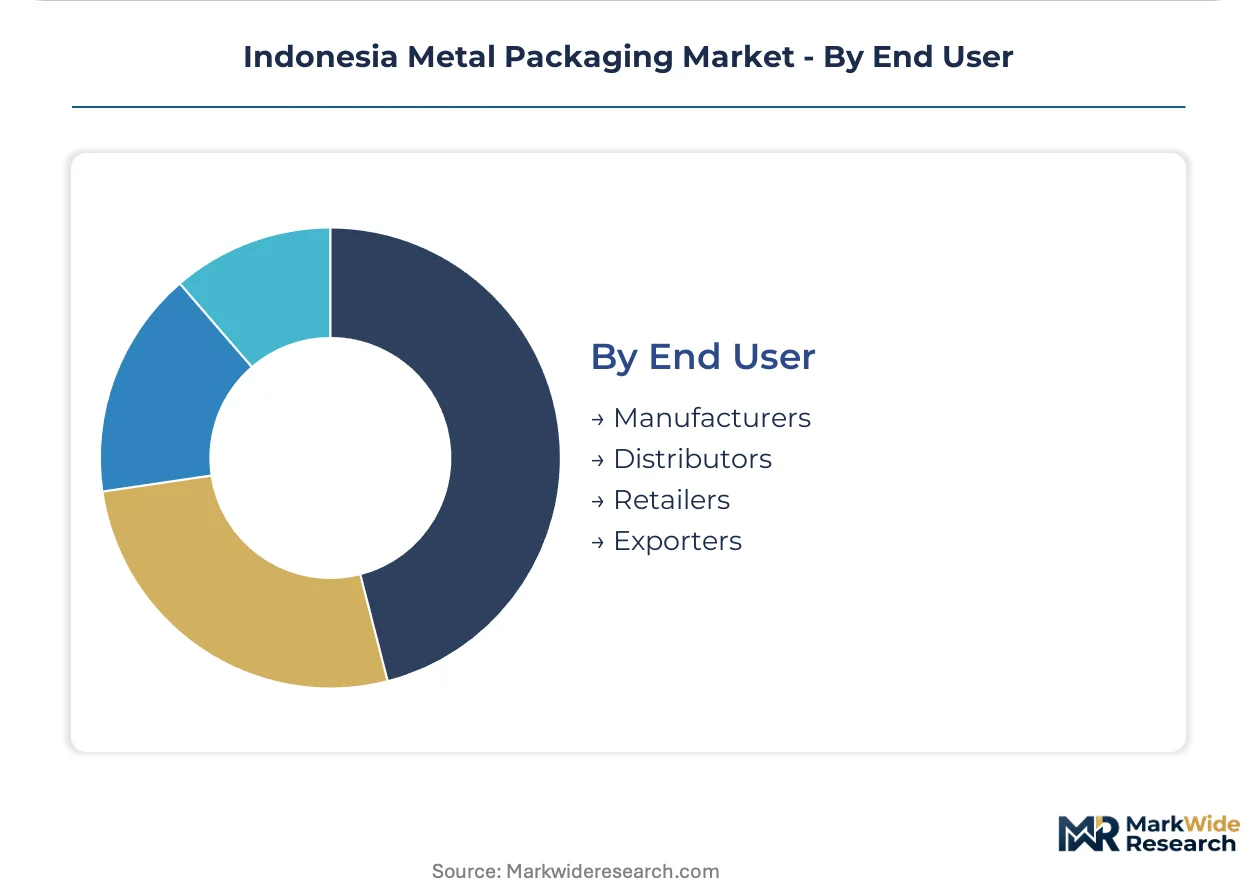
End User:
End-user segmentation reveals consolidating buyer power among multinational anchors, with direct-to-manufacturer procurement displacing traditional distributor intermediaries across Java's industrial corridor.
- Manufacturers:Beverage bottlers, food processors, chemical formulators, and pharmaceutical packagers operating filling lines. Five anchor accounts in Bekasi and Sidoarjo zones now negotiate multi-year aluminum supply agreements with mill-direct pricing clauses.
- Distributors:Regional wholesalers serving outer-island markets and secondary cities. Logistics cost penalties across Indonesia's archipelagic distribution network are compressing their margin structures.
- Retailers:Modern trade chains and traditional market vendors procuring private-label metal packaging. Price-sensitive rural channels are witnessing plastic pouch substitution for condiments and cooking oils.
- Exporters:Processed seafood and palm oil derivative packagers seeking BIS-equivalent certification for destination market compliance. Batch-level coating composition certificates are now mandatory for Ministry of Industry technical directorate submission.
Manufacturers concentrate purchasing authority through direct procurement; exporters face the most complex multi-jurisdiction certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bekasi's integrated industrial zones concentrate beverage can fabrication through tax-incentive structures that offset capital-intensive drawing and ironing line investments. These special economic zones anchor procurement gravity for multinational filling-line operators serving Jakarta's urban consumer base.
Java
Carbonated soft drink and processed seafood demand pulls tinplate and aluminum procurement toward Bekasi and Sidoarjo manufacturing clusters. Ministry of Industry food-contact material regulations compress supplier qualification timelines for domestic producers. Five anchor accounts in these zones now negotiate multi-year aluminum supply agreements with mill-direct pricing clauses.
Sumatra
Palm oil processing and spice grinding clusters in Medan and Palembang generate underpenetrated demand for regional canning facilities. The Ministry of Environment's pending extended producer responsibility frameworks will favor producers with integrated collection infrastructure. Local processors currently rely on Java-sourced containers, incurring archipelagic freight cost penalties.
Sulawesi
Canned tuna and coconut derivative packagers in Makassar drive specialty food can demand. BIS-equivalent national standards for food-contact materials require batch-level coating composition certificates for tinplate importers. Secondary city manufacturing presents greenfield opportunities for aluminum lightweighting investments serving outer-island distribution networks.
Kalimantan
Petrochemical and mining chemical handling sustains industrial drum demand around Balikpapan and Samarinda. Surabaya-based welded steel drum producers currently serve these applications through inter-island shipping. Regional fabrication capacity would eliminate logistics tolerances across the Java Sea distribution corridor.
Papua
Remote consumer markets and extractive industry supply chains create niche demand for corrosion-resistant containers. Aluminum lightweighting imperatives reduce per-unit shipping weight for distributors serving these outermost islands. Limited local fabrication forces reliance on Surabaya and Makassar supply origins.
Indonesia Metal Packaging Market Competitive Landscape
Top-tier vendors anchor beverage can supply through regional manufacturing footprints, while mid-tier fabricators concentrate in decorative tinplate and industrial drum specializations. The vendor base stratifies across three archetypes: multinational beverage can specialists with integrated aluminum supply chains, domestic tinplate converters serving gift and processed food segments, and technical industrial container producers with welded steel heritage. Capacity expansion and direct-to-manufacturer procurement consolidation represent the dominant competitive vectors reshaping supplier relationships.
Among multinational specialists, Crown Holdings exemplifies scale-driven beverage can positioning through regional manufacturing presence. PT Pelangi Indah Canindo Tbk and Rheem Indonesia occupy distinct specialization tiers—Pelangi Indah representing decorative tinplate conversion for premium gift applications, Rheem anchoring technical industrial drum production for chemical sector demand. These three entities illustrate the market's structural segmentation across consumer beverage, premium decorative, and industrial handling verticals.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Rheem Indonesia |
| PT Pelangi Indah Canindo Tbk |
| PT Cometa Can Corporation |
| PT Indonesia Raya Makmur |
| Crown Holdings |
| PT Indonesia Multi Colour Printing |
| P.T. New Red & White |
| PT United Can Company Ltd |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap tinplate converters anchor Indonesia's decorative container segment, their generational ownership patterns preserving pricing discipline through long-term customer relationships even as raw material volatility compresses margins. These entrenched ownership structures concentrate supply authority in Java's industrial corridor while resisting price transparency that multinational beverage anchors now demand through direct procurement channels.
Pricing Analysis
Short lead-time premiums command substantial markups over contract-scheduled deliveries as Bekasi filling-line clusters rush seasonal promotional runs. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade sterilization certification from commodity beverage applications and rural-market economy tins. Cost compression in standard-grade food cans is intensifying because cold-rolled steel substrate volatility forces domestic producers to absorb margin erosion rather than pass through price adjustments. Rural retailers exhibit highest price sensitivity, driving substitution toward flexible plastic pouches for condiments and cooking oils.
Supply Chain Analysis
Cold-rolled steel substrate supply rests on Chinese, Japanese, and South Korean mill exports to Indonesian tinplate coaters and canmakers. Aluminum coil for beverage can drawing and ironing lines draws from Australian bauxite refinement and regional ASEAN smelter capacity. Single-source vulnerability concentrates in specialty coating chemistries for BPA-NI epoxy alternatives, where formulation expertise clusters among a handful of technical specialists. Distribution runs through Java-centric fabrication hubs serving outer-island markets via inter-island shipping networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer-ceramic hybrid coatings are displacing conventional multi-pass epoxy-phenolic systems, compressing capital barriers for new entrants while forcing legacy producers to retool or cede share to technology-advantaged competitors.
For Market Incumbents: Deepen backward integration into aluminum collection and re-melt capabilities ahead of pending Ministry of Environment extended producer responsibility mandates. Crown Holdings and established beverage can specialists should lock in multi-year coil supply agreements with Australian and ASEAN smelters before greenfield competitors secure tolling arrangements. Retain coating chemist talent through technical apprenticeship pipelines as BPA-NI formulation expertise scarcity threatens compliance timelines. For New Entrants and Emerging Players: The gap between premium pharmaceutical-grade sterilization certification and economy rural-market tins creates entry space for mid-tier regional canning facilities in Sumatra and Sulawesi. Target palm oil processing clusters in Medan and spice grinding operations in Palembang with aluminum lightweighting investments that offset archipelagic freight penalties. Pursue toll manufacturing arrangements with established Java-based coaters to bypass capital-intensive coating line investments while building local customer relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic tinplate converters with decorative gift segment specialization and established Ministry of Industry certification relationships in secondary Javanese cities. Long-term viability hinges on circular production system readiness across the analysis window. Watch for Ministry of Environment recycling mandate implementation timelines as the critical inflection signal determining which assets capture extended producer responsibility tailwinds versus stranded legacy infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Collection | Captures extended producer responsibility premiums ahead of Ministry of Environment mandates. |
| Regional Canning Facility Expansion | Serves Sumatra palm oil clusters while eliminating Java Sea freight cost penalties. |
| Polymer-Ceramic Coating Technology Adoption | Compresses capital requirements by 30-40 percent versus conventional epoxy infrastructure. |
| Direct-to-Manufacturer Procurement Consolidation | Displaces distributor intermediaries as five anchor accounts negotiate mill-direct pricing. |
| Pharmaceutical Sterilization Certification Investment | Extends qualification timelines but commands premium positioning against commodity tiers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating chemists, canmaking plant managers, and beverage procurement directors. Ministry of Industry technical directorate submissions, Ministry of Health pharmaceutical packaging guidelines, and BIS-equivalent national standards documentation provided regulatory boundary conditions. Bottom-up capacity assessments across Bekasi, Sidoarjo, and Tangerang manufacturing clusters triangulated against top-down demand estimates from carbonated soft drink and processed seafood filling-line operators.
Granularity-level modeling tracked substrate physics, sterilization-grade requirements, and logistics constraints across product type, material, application, and end-user dimensions. CAGRs were derived through trend extrapolation of urban processed food consumption patterns and aluminum lightweighting penetration rates across the analysis window. Drawing and ironing process improvements, archipelagic distribution network compression, and BIS-equivalent certification alignment served as core forecast inputs.
Inputs from Ministry of Industry batch-level coating composition certificates were available through the study window; gaps in real-time cold-rolled steel spot pricing introduce uncertainty bands around margin forecasts. Forecasts reflect assumptions regarding extended producer responsibility implementation timelines and aluminum coil import tariff stability. Regulatory acceleration, substrate technology breakthroughs, and outer-island infrastructure investments warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
Packaging Metallization Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
India Metal Cans Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Latin America Metal Packaging Market