
 Europe Intravenous Solutions Market | 2026-2036
Europe Intravenous Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Intravenous Solutions Market Intelligence
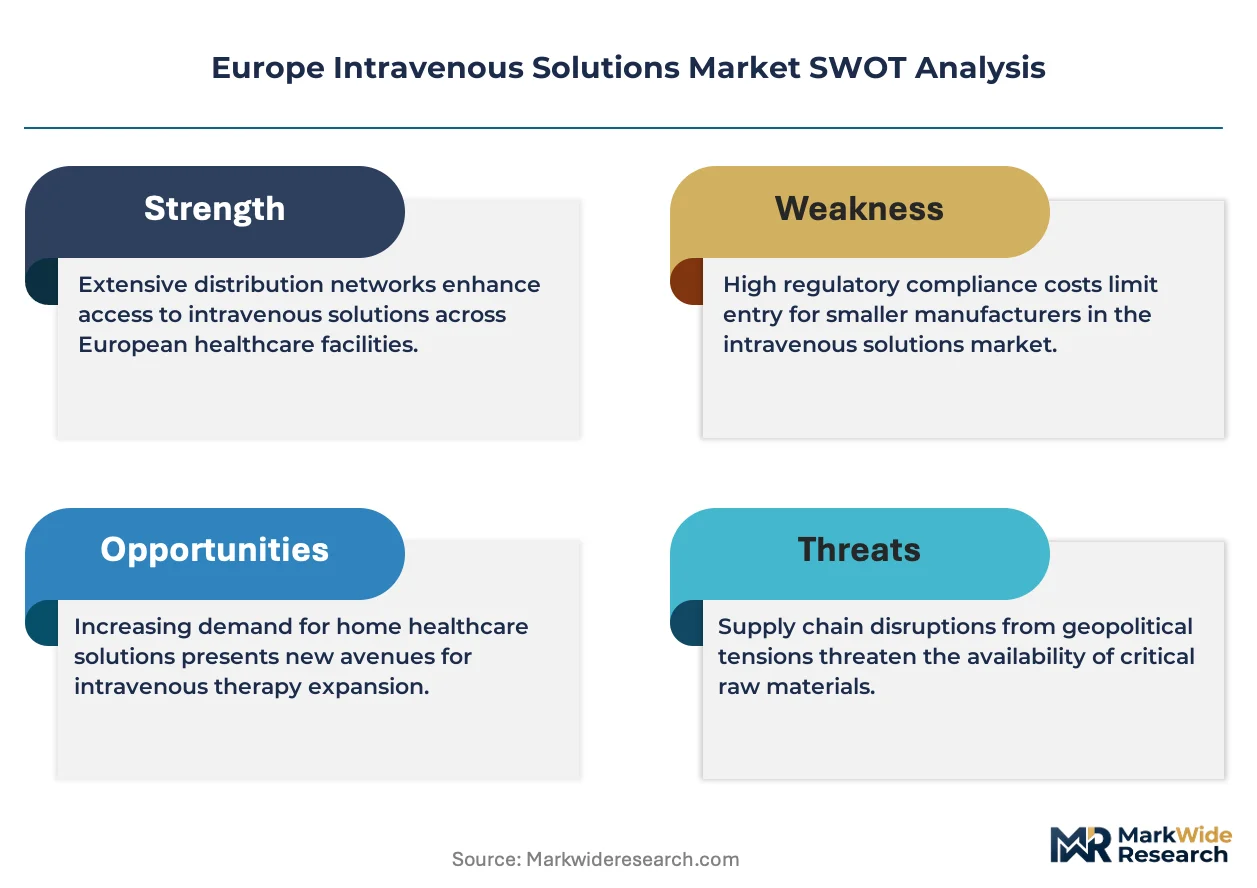
European pharmaceutical-grade saline and dextrose manufacturing capacity is hardening around sterilizable flexible film technologies. Fresenius Kabi AG dominates central European production with captive supply of active pharmaceutical ingredients. Baxter International Inc. leverages its pan-European distribution network to sustain just-in-time hospital contracts. B. Braun Melsungen AG specializes in closed-system transfer devices that reduce contamination risk during compounding.
Europe intravenous solutions are sterile, pyrogen-free aqueous formulations administered directly into the venous circulation, typically containing electrolytes, carbohydrates, or amino acids in concentrations calibrated to plasma osmolality. These solutions serve as volume resuscitation vehicles, medication diluents, and parenteral nutrition carriers in acute and chronic care settings. Electrolyte solutions occupy the largest revenue share due to universal deployment in surgical and emergency protocols, while nutritional solutions represent the fastest-expanding category as home parenteral nutrition programs multiply across national health systems. Prefilled syringes command premium positioning through reduced preparation error rates and pharmacy labor savings.
The European Medicines Agency (EMA) oversees centralized marketing authorization for novel intravenous formulations, while the EU Medical Device Regulation (MDR) imposes strengthened biocompatibility and traceability mandates on infusion sets and containers. REACH compliance constrains plasticizer selection in polyvinyl chloride bags, pushing converters toward ethylene-vinyl acetate and polypropylene alternatives. Stakeholders must monitor national tender consolidation movements and prepare for sequential MDR transition deadlines that will reshape competitive access across member states.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing sterilization and packaging compliance timelines, forcing converters to abandon polyvinyl chloride in favor of ethylene-vinyl acetate and polypropylene alternatives. Hospital procurement consolidation across Germany, France, and the United Kingdom is simultaneously reshaping contract structures toward multi-year, just-in-time supply agreements.
Growth Catalysts
- Home parenteral nutrition expansion:National health systems in Germany and the United Kingdom are reimbursing ambulatory infusion programs, shifting clinical volume from inpatient to home settings.
- REACH plasticizer constraints:The regulation is accelerating material substitution toward flexible film technologies that meet biocompatibility mandates without legacy plasticizers.
- Surgical volume recovery:Elective procedure backlogs across France and Italy are resuscitating demand for electrolyte resuscitation fluids and medication diluents.
Market Restraints
- Active pharmaceutical ingredient concentration:European saline and dextrose precursor supply clusters in Germany and the Netherlands, creating single-source vulnerability for compounders.
- MDR transition cost burden:The regulation imposes extended clinical evaluation and notified body recertification expenses that disproportionately burden mid-scale converters.
- Glass-to-plastic substitution limits:High-parenteral-nutrition formulations requiring oxygen barrier properties resist migration from borosilicate containers, constraining cost reduction.
Strategic Opportunities
- Central and Eastern European hospital modernization:Poland and Romania are expanding per capita infusion capacity with EU cohesion fund backing, opening tender opportunities for flexible film suppliers.
- Closed-system transfer device integration:Convergence of needle-free connectors with pre-filled syringe formats is automating compounding workflows in oncology and intensive care units.
- EMA centralized authorization pathways:The framework offers streamlined market access for novel formulations addressing rare disease parenteral nutrition gaps.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic processing technicians and quality assurance specialists command premium wages in Germany and Switzerland, constraining capacity expansion.
- Legacy ERP-to-UDI integration:Hospital pharmacies and manufacturers face friction harmonizing traceability systems with the EU Medical Device Regulation's unique device identifier mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Intravenous Solutions Market |
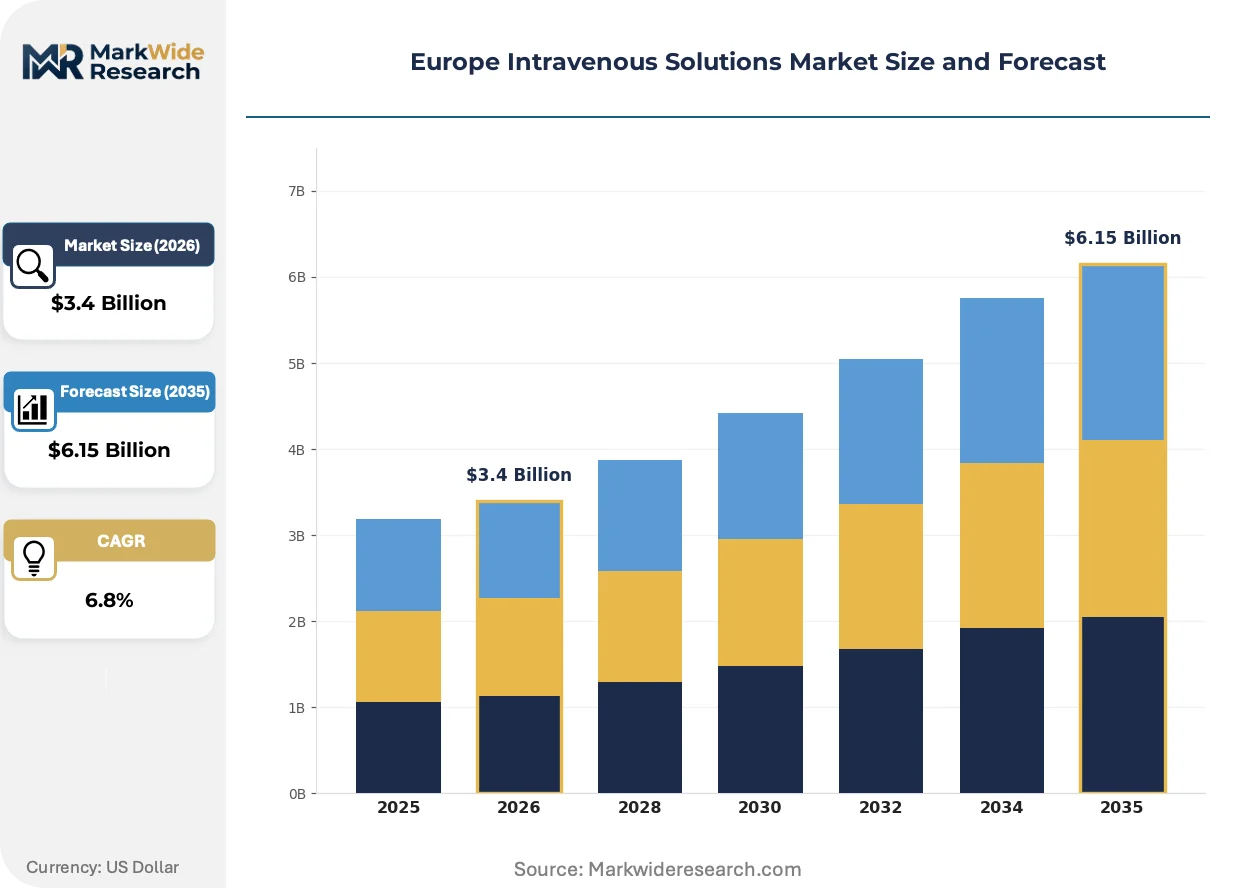
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Solutions, Nutritional Solutions, Antibiotic Solutions, Blood Products Delivery Mode: Continuous Infusion, Intermittent Infusion, Rapid Infusion, Controlled Infusion End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Packaging Type: Bags, Bottles, Vials, Prefilled Syringes |
| Companies Covered | Grifols S.A., Terumo Corporation, Baxter International Inc., Amanta Healthcare Ltd, Otsuka Pharmaceutical Co. Ltd, B. Braun Melsungen AG, ICU Medical Inc., Vifor Pharma Group, Fresenius Kabi AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Intravenous Solutions Market Strategic Shifts & Innovations
Automation is penetrating sterile compounding and packaging workflows, reducing human touchpoints in critical contamination control zones. Material science advances and regulatory data integrity mandates are simultaneously reshaping how solutions are formulated, filled, and traced across the hospital-to-home continuum.
Robotic compounding systems are automating batch preparation in hospital pharmacies and centralized admixture facilities. German and French health systems are deploying these platforms in oncology and pediatric units where dosing precision and sterility assurance outweigh capital expenditure. The technology is automating error-prone manual steps, compressing pharmacy labor costs while tightening compliance with good manufacturing practice standards.
REACH enforcement is hardening scrutiny of di(2-ethylhexyl) phthalate in polyvinyl chloride infusion containers. The European Chemicals Agency's authorization sunset dates are forcing converters to validate ethylene-vinyl acetate and polypropylene alternatives ahead of stock depletion. Nutritional solutions requiring extended shelf stability face the steepest reformulation timelines, with manufacturers accelerating extractables and leachables testing protocols.
Hospital procurement consortia are consolidating tender authority across regional health economies. The United Kingdom's NHS Supply Chain and France's Resah are aggregating demand for standard electrolyte and dextrose solutions, displacing individual hospital negotiations. This concentration is most visible in Germany, where university hospital alliances now command volume discounts that compress margins for non-integrated suppliers.
Europe Intravenous Solutions Market Segmentation
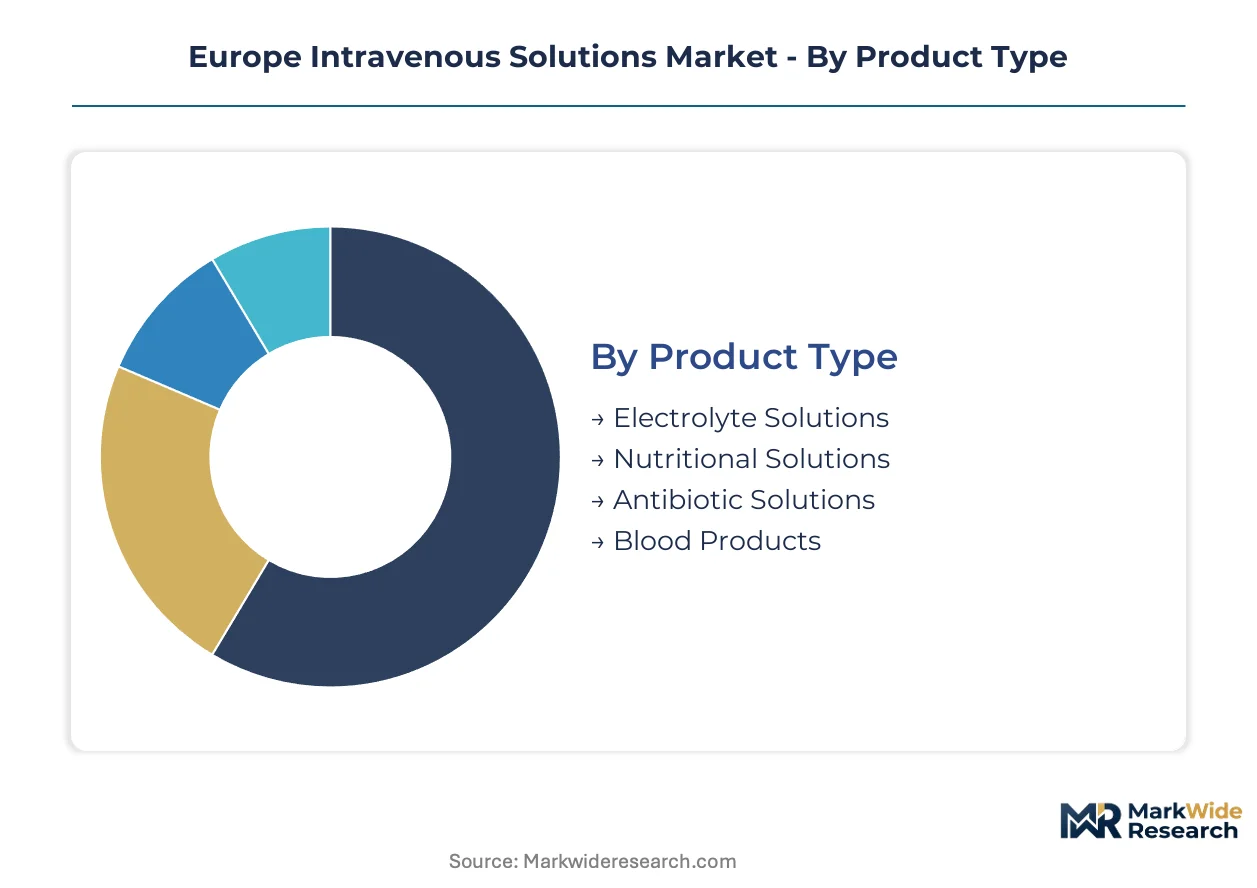
Segmentation in the Europe intravenous solutions market reveals how supply chain configuration, clinical workflow requirements, and regulatory compliance demands fragment commercial opportunity. Manufacturers must align production assets with specific delivery modes and packaging formats to secure tender access across national health systems.
Product Type:
Manufacturing capacity for active pharmaceutical ingredients clusters around saline and dextrose precursors in Germany and the Netherlands, concentrating supply risk for compounders dependent on electrolyte and nutritional feedstocks.
- Electrolyte Solutions:Sterile aqueous formulations containing sodium chloride, potassium, or balanced crystalloid mixtures calibrated to plasma osmolality. Demand concentrates in German and French university hospital surgical suites where emergency resuscitation protocols mandate immediate availability. REACH plasticizer constraints are accelerating migration from PVC containers toward ethylene-vinyl acetate alternatives.
- Nutritional Solutions:Parenteral nutrition formulations combining amino acids, lipids, and glucose in multi-chamber bags requiring oxygen barrier properties. Home care programs in the United Kingdom and Germany are expanding ambulatory reimbursement, shifting clinical volume from inpatient wards to domestic settings. These formulations resist full plastic substitution due to stability requirements.
- Antibiotic Solutions:Pre-mixed or diluent-compatible sterile preparations for antimicrobial delivery.
- Blood Products:Volume expanders and plasma-derived solutions governed by specialized cold-chain and traceability mandates.
Today's leader: Electrolyte Solutions. Tomorrow's challenger: Nutritional Solutions.
Delivery Mode:
Cost tier differentiation separates capital-intensive smart pump integration from gravity-fed alternatives, with procurement consortia negotiating distinct contract structures for each workflow category.
- Continuous Infusion:Steady-rate delivery systems deployed in intensive care and anesthesia maintenance requiring precision volumetric pumps. German hospital alliances are standardizing on interoperable pump platforms that reduce medication error rates through dose error reduction software.
- Intermittent Infusion:Scheduled bolus administration common in antibiotic and electrolyte replacement protocols. Outpatient clinics in France leverage these workflows to compress chair time and pharmacy labor costs.
- Rapid Infusion:High-flow delivery for emergency resuscitation and trauma protocols.
- Controlled Infusion:Variable-rate systems for patient-controlled analgesia and titrated sedation.
Continuous Infusion commands premium pricing through pump ecosystem lock-in. Intermittent Infusion offers the steepest expansion trajectory as ambulatory volumes climb.
End User:
Application requirements diverge sharply between acute care settings demanding immediate availability and home settings prioritizing portability and patient self-administration competence.
- Hospitals:High-volume consumers of standard electrolyte and dextrose solutions with just-in-time inventory mandates. NHS Supply Chain and France's Resah are consolidating tender authority, displacing individual hospital negotiations with multi-year framework agreements.
- Home Care:The fastest-expanding category as national health systems in Germany and the United Kingdom reimburse ambulatory parenteral nutrition programs. Patients require training-compatible delivery systems and 24-hour nursing support hotlines.
- Outpatient Clinics:Day-case infusion centers for chemotherapy and hydration therapy.
- Rehabilitation Centers:Extended-care facilities managing gradual transition from parenteral to enteral nutrition.
Hospitals retain volume dominance. Home Care is gaining share fastest as reimbursement frameworks mature.
Packaging Type:
Material science advances and MDR biocompatibility mandates are reshaping container selection, with converters validating alternatives ahead of REACH authorization sunset dates.
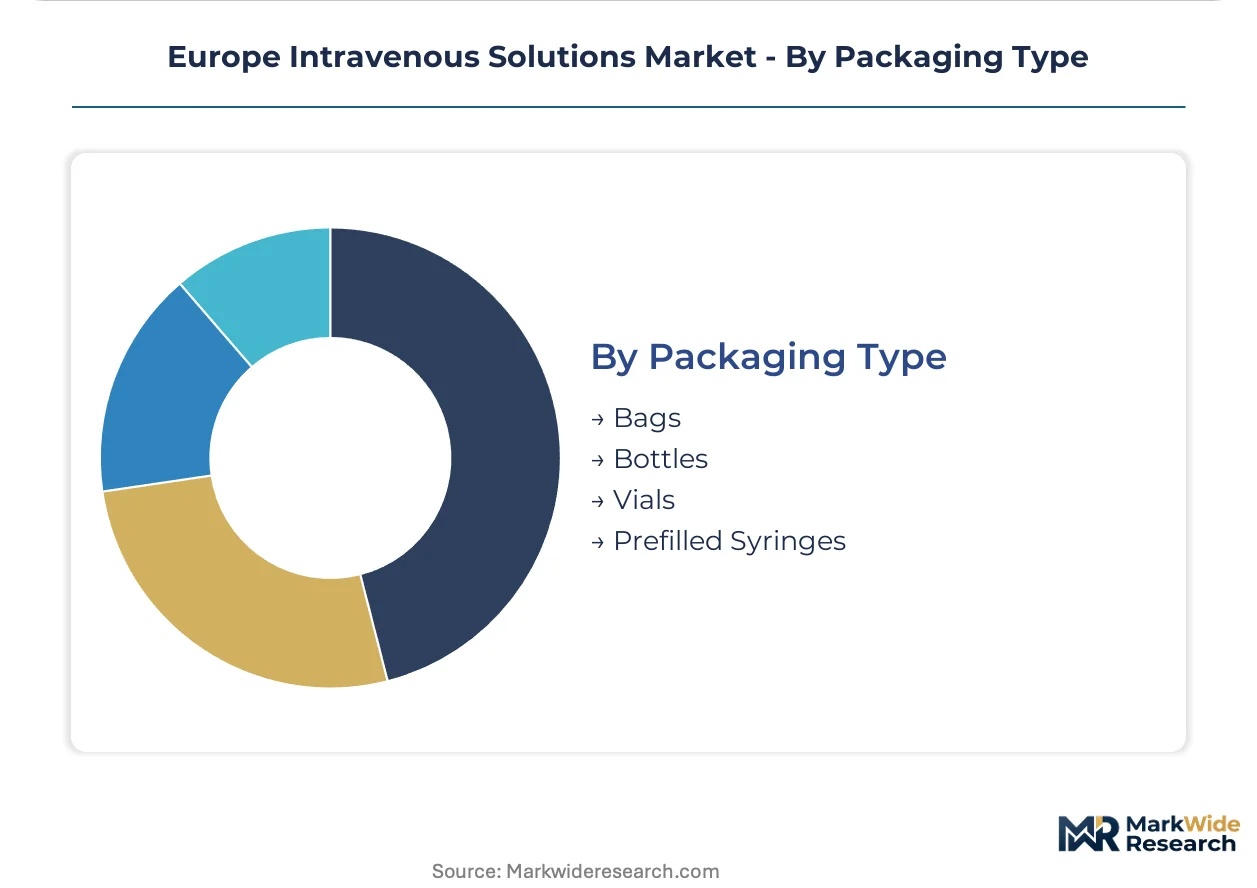
- Bags:Flexible film containers dominating electrolyte and nutritional solution volume. ECHA scrutiny of di(2-ethylhexyl) phthalate is forcing accelerated validation of polypropylene and ethylene-vinyl acetate alternatives.
- Prefilled Syringes:Single-unit presentations commanding premium positioning through reduced compounding error rates and pharmacy labor savings. Oncology units in German university hospitals are deploying these formats for high-risk cytotoxic preparations.
- Bottles:Rigid containers for bulk electrolyte solutions in surgical settings.
- Vials:Small-volume presentations for medication reconstitution and dilution.
Bags hold manufacturing scale advantage. Prefilled Syringes represent the fastest-climbing margin tier as safety premiums justify higher unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United Kingdom diverge sharply in procurement architecture despite comparable patient volumes, with NHS Supply Chain centralizing tender authority while German university hospital alliances retain fragmented negotiation leverage.
Germany
Fresenius Kabi AG anchors captive saline and dextrose precursor production in Hesse and Baden-Württemberg, insulating compounders from API supply shocks. The EU MDR imposes extended clinical evaluation timelines on mid-scale converters, disproportionately burdening regional manufacturers. Bavaria's university hospital alliances now command volume discounts that compress margins for non-integrated suppliers.
United Kingdom
NHS Supply Chain aggregation of electrolyte and dextrose demand displaces individual hospital negotiations with multi-year framework agreements. Home parenteral nutrition reimbursement expansion shifts clinical volume from inpatient wards to domestic settings, requiring 24-hour nursing support infrastructure. London and Southeast England concentrate day-case infusion center capacity for chemotherapy and hydration therapy.
France
Resah procurement consolidation reshapes contract structures toward just-in-time supply agreements for standard crystalloid solutions. ECHA REACH enforcement accelerates di(2-ethylhexyl) phthalate sunset timelines, forcing converters toward ethylene-vinyl acetate validation. The Île-de-France region hosts robotic compounding deployment in oncology units where dosing precision outweighs capital expenditure.
Italy
Elective surgical backlog resuscitation drives electrolyte resuscitation fluid demand across Lombardy and Emilia-Romagna hospital systems. ANSM national pharmaceutical regulator alignment with EMA centralized pathways streamlines novel formulation access. Northern Italian converters face MDR transition cost burdens that favor scaled producers with notified body recertification resources.
Poland
EU cohesion fund backing expands per capita infusion capacity in Warsaw and Kraków hospital modernization programs. Central and Eastern European tender opportunities open for flexible film suppliers as procurement standards converge with Western European MDR compliance. Regional health economies prioritize gravity-fed delivery systems over capital-intensive smart pump integration.
Europe Intravenous Solutions Market Key Industry Players
German producers anchor one tier through captive API supply and pan-European distribution networks; Swiss and Japanese specialists hold differentiated positions in closed-system transfer devices and precision delivery technologies. Market structure concentrates around three to five integrated compounders with backward integration into precursor manufacturing, while mid-scale converters face margin compression from procurement consolidation. Two strategic archetypes dominate: vertically integrated pharmaceutical conglomerates with sterile manufacturing scale, and niche specialists in high-barrier nutritional formulations. Competitive moves center on M&A for capacity consolidation and strategic partnerships for MDR compliance cost-sharing.
Within the integrated pharmaceutical tier, Fresenius Kabi AG and Baxter International Inc. exemplify scale-driven archetypes with European production footprints and hospital contract density. B. Braun Melsungen AG occupies a specialist position in contamination-risk reduction technologies. These three entities represent the competitive core around which procurement consolidation and regulatory compliance burdens reshape vendor viability.
| Leading Market Players |
|---|
| Grifols S.A. |
| Terumo Corporation |
| Baxter International Inc. |
| Amanta Healthcare Ltd |
| Otsuka Pharmaceutical Co. Ltd |
| B. Braun Melsungen AG |
| ICU Medical Inc. |
| Vifor Pharma Group |
| Fresenius Kabi AG |
| Others |
Cost & Logistics Intelligence
Aseptic processing technicians in Germany and Switzerland command premium wages that compress margins for mid-scale converters, widening pricing-tier spreads between integrated pharmaceutical conglomerates and regional compounders dependent on outsourced sterilization services.
Pricing Analysis
Capacity additions in Central and Eastern Europe are reshaping price floors for standard electrolyte solutions as Polish and Romanian hospital modernization programs absorb volume previously sourced from Western European converters. Three-tier pricing structure across premium, standard, and economy levels separates closed-system transfer devices with MDR certification from gravity-fed alternatives and bulk procurement tenders. Cost compression in standard crystalloid bags is intensifying because NHS Supply Chain and France's Resah aggregate demand into multi-year framework agreements. Outpatient clinics exhibit highest price sensitivity due to reimbursement caps, while intensive care units prioritize pump interoperability over unit cost.
Supply Chain Analysis
Domestic-content mandates in EU cohesion fund disbursements are reshaping sourcing patterns for hospital modernization tenders in Poland and Romania, favoring converters with regional manufacturing footprints over distant suppliers. Active pharmaceutical ingredient production clusters in Germany and the Netherlands, with flexible film conversion capacity concentrating in Italy and Spain. Saline precursor supply, dextrose feedstock, and ethylene-vinyl acetate resin constitute critical input dependencies. Single-source vulnerability for compounders without captive precursor supply represents the dominant structural risk. Distribution runs through pan-European logistics networks anchored by just-in-time hospital contracts and GPO aggregation platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe intravenous solutions market functions as a regulatory compounder where EU MDR transition deadlines and REACH authorization sunsets are compressing vendor viability windows and consolidating procurement authority around compliant suppliers.
For Market Incumbents: Anchor sterile manufacturing scale through backward integration into precursor chemistry, securing captive saline and dextrose supply against API concentration risk in Germany and the Netherlands. Accelerate ethylene-vinyl acetate validation ahead of ECHA di(2-ethylhexyl) phthalate sunset dates to defend tender access against mid-scale converters facing recertification cost burdens.
For New Entrants and Emerging Players: The price-point gap between premium closed-system transfer devices and economy gravity-fed bags offers entry space for hybrid-format suppliers targeting Central and Eastern European hospital modernization. Poland and Romania present the most penetrable geographies given EU cohesion fund expansion of per capita infusion capacity. A go-to-market angle emphasizing MDR compliance cost-sharing partnerships with regional distributors bypasses direct notified body recertification investments.
For Investors and Strategic Acquirers: Pharmaceutical conglomerates with hospital contract density are the most active acquirer in this space, seeking sterile manufacturing capacity to fill geographic gaps. Over a five-to-ten-year horizon, viability hinges on MDR compliance completion rates across mid-scale converter portfolios. The acquisition target archetype comprises regional compounders with validated flexible film technologies and established GPO relationships. Watch EMA centralized authorization pathway utilization for novel parenteral nutrition formulations as inflection indicator for nutritional solution margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Completion | Notified body recertification secures continued market access across German and French tenders. |
| Flexible Film Validation | Ethylene-vinyl acetate substitution ahead of REACH deadlines protects electrolyte solution margins. |
| Home Parenteral Nutrition Infrastructure | 24-hour nursing support networks capture ambulatory reimbursement expansion in the United Kingdom. |
| Robotic Compounding Deployment | Automation in German oncology units reduces pharmacy labor costs and dosing error liability. |
| Central and Eastern European Tender Participation | Polish and Romanian hospital modernization opens volume opportunities for compliant suppliers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, GPO contracts specialists, aseptic processing technicians, and EMA regulatory affairs leads with secondary validation against EMA centralized authorization databases, EU MDR transition timelines, hospital procurement consortium tender disclosures, and REACH authorization sunset schedules. Bottom-up volume modeling across product type, delivery mode, end user, and packaging format segments triangulated against top-down pharmaceutical manufacturing capacity assessments.
Historical reference periods anchored the projection horizon through trend extrapolation calibrated to surgical volume recovery patterns, home parenteral nutrition reimbursement expansion trajectories, and material substitution timelines driven by ECHA enforcement. Segmentation dimensions modeled included electrolyte versus nutritional versus antibiotic solution categories, continuous versus intermittent infusion workflows, hospital versus home care settings, and flexible film versus glass container packaging formats. CAGRs derived from compound growth logic applied to procedure volume forecasts and pricing elasticity assumptions, with REACH compliance cost pass-through rates and MDR recertification expense burdens incorporated as industry-specific forecast inputs.
Caveats apply where EMA regulatory delays, REACH authorization timeline extensions, or hospital procurement consortium restructuring could materially shift the outlook, particularly if MDR transition deadlines compress competitive access faster than modeled. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Smear Mask Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
United States Intravenous Solutions Market