
 South Korea Home Appliances Market | 2026-2036
South Korea Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Home Appliances Market Analytics
The South Korean home appliances sector is recalibrating around a widening gap between AI-integrated premium suites and price-driven commodity replacements. Samsung Electronics leverages its semiconductor supply chain to dominate smart refrigerator platforms with proprietary AI food management. LG Electronics anchors the washing machine segment through direct-drive motor technology and in-house compressor manufacturing. Coway Co., Ltd. specializes in water and air purification appliances, occupying a defensible niche against diversified conglomerates.
South Korea home appliances encompass electrically powered domestic equipment designed for food preservation, garment care, climate control, and meal preparation, typically operating at 220V/60Hz with energy efficiency ratings graded from Grade 1 to Grade 5 under national standards. Refrigerators and air conditioners command the largest installed base, though IoT-enabled technology segments are expanding fastest as broadband penetration and apartment automation converge. The residential end user category retains volume leadership, while commercial and hotel segments concentrate margin pools through bulk procurement of energy-efficient systems.
MFDS oversees product safety certification for electrical appliances, while MEET enforces escalating energy efficiency standards that manufacturers must meet for domestic market access. KTL and KTC testing laboratories verify compliance with KC mark requirements, creating a regulated barrier that favors established players with dedicated certification teams. Stakeholders must monitor how tightening carbon regulations and smart grid integration requirements reshape R&D allocation between connected appliance ecosystems and core efficiency gains.
Market Dynamics
MFDS safety certification and MEET carbon mandates are compressing market access for component importers while Seoul's high-rise residential automation pulls premium smart kitchen suites into standard specifications.
Growth Catalysts
- Apartment automation mandates:Seoul metropolitan corridor developers now specify IoT-ready appliances as baseline in new high-rise contracts, accelerating replacement cycles in residential complexes.
- MEET efficiency thresholds:Escalating carbon-reduction mandates for imported compressors and motors are forcing manufacturers to upgrade domestic supply chains, creating captive demand for local component producers.
- Busan commercial refurbishment:Manufacturing belt hotels and food-service operators are shortening equipment replacement cycles to meet corporate ESG targets, concentrating bulk procurement of energy-efficient refrigeration systems.
Market Restraints
- Compressor import dependency:Premium inverter compressor supply concentrates among Japanese and German specialists, exposing Korean assemblers to currency volatility and allocation constraints during peak demand windows.
- KC mark certification timeline:KTL and KTC laboratory testing queues extend lead times for new product launches, favoring incumbents with dedicated certification teams and freezing smaller competitors from seasonal windows.
- Apartment size constraints:Seoul's micro-unit housing stock limits physical dimensions for refrigerator and washing machine installations, capping average selling prices and compressing margin on full-size premium models.
Strategic Opportunities
- Jeju Island hospitality expansion:Boutique hotel construction and casino resort refurbishment are creating concentrated demand for commercial-grade climate control and food preservation systems outside the Seoul-Busan axis.
- Water purification service models:Subscription-based filter replacement and IoT-enabled quality monitoring are penetrating rental apartment segments previously served by low-margin retail purchases.
- Smart grid integration incentives:KEPCO demand-response programs reward connected appliance adoption with rate reductions, opening utility-partnered distribution channels for air conditioner and water heater manufacturers.
Industry Challenges
- Embedded systems engineering scarcity:Domestic talent pools for appliance firmware and edge-AI development lag hardware manufacturing scale, forcing reliance on semiconductor division poaching or offshore contracting.
- Legacy apartment electrical infrastructure:Pre-2000s high-rise buildings lack circuit capacity for simultaneous operation of multiple high-wattage smart appliances, requiring costly retrofit coordination with property management associations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Home Appliances Market |
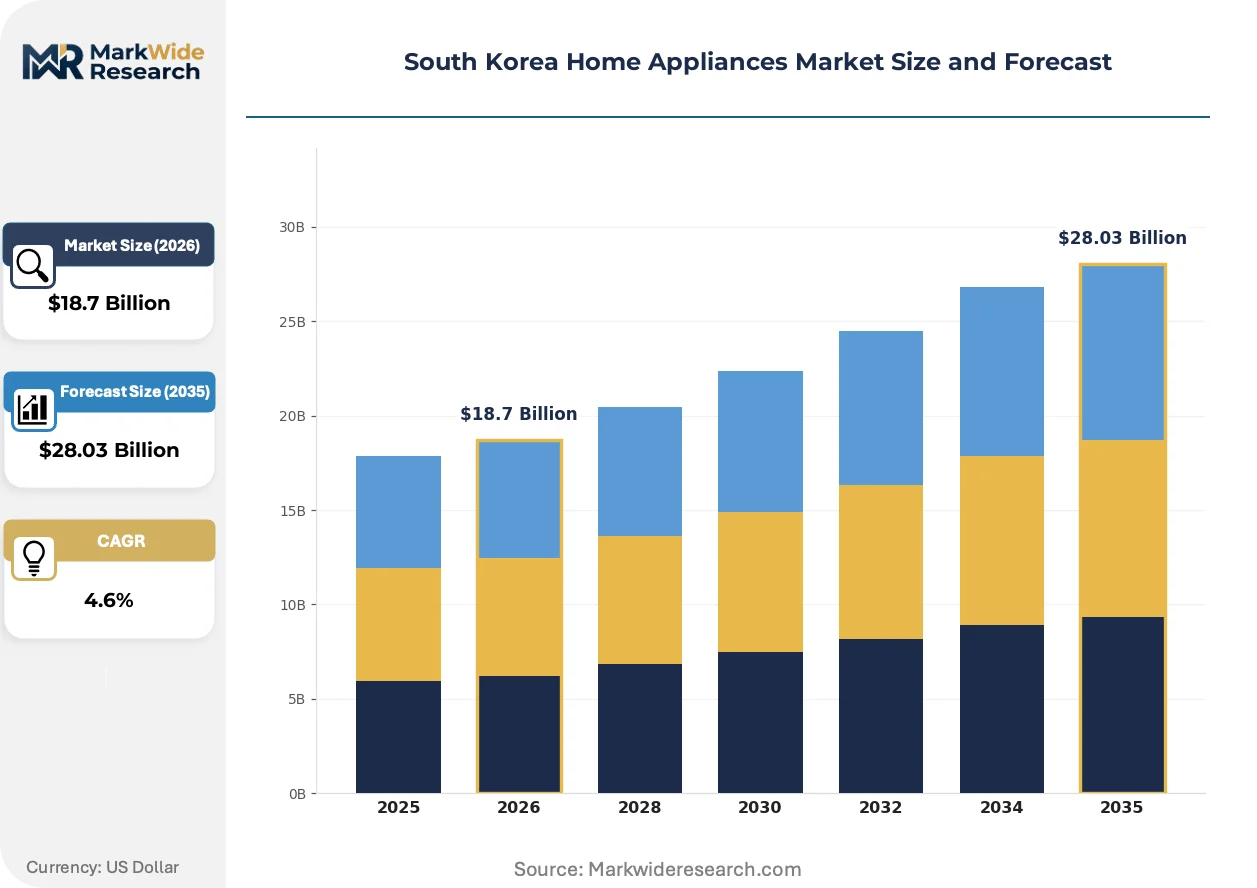
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Air Conditioners, Microwaves Technology: Smart, Energy-Efficient, Traditional, IoT-Enabled End User: Residential, Commercial, Hotels, Institutions Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Coway Co., Ltd., Whirlpool Corporation, Samsung Electronics, Haier Electronics Group Co Ltd, Panasonic Corporation, LG Electronics, SK Magic, BSH Hausgeräte GmbH, Winia Electronics (Daewoo), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Home Appliances Market Evolving Landscape
AI-enabled food management and predictive maintenance capabilities are migrating from flagship products to mid-tier lines, compressing the premium-commodity gap while regulatory pressure on embodied carbon reshapes component sourcing.
Edge-AI inference chips embedded in refrigerator door panels are absorbing routine inventory tracking and meal-planning functions previously handled by smartphone applications. Young professional households in Gangnam and Seongsu-dong districts are adopting these systems at replacement-cycle velocity. This absorption is compressing standalone smart home hub value propositions and forcing platform consolidation around appliance-native control architectures.
MEET's 2024-2030 carbon intensity benchmarks for imported steel and aluminum components are tightening material provenance documentation requirements. Manufacturers must now certify supply chain emissions for compressor housings and heat exchanger coils to maintain domestic market access. Air conditioner assemblers with captive metal fabrication or Korean-sourced sheet steel are responding fastest, while import-dependent competitors face margin compression or product line rationalization.
After-sales service unbundling is fragmenting traditional dealer-margin structures. Independent technicians certified through KTL's appliance repair program are capturing maintenance revenue directly from apartment management associations, bypassing manufacturer-authorized service networks. This pattern concentrates in Busan's dense commercial districts and Seoul's older high-rise clusters where bulk service contracts dominate procurement logic.
South Korea Home Appliances Market Segmentation
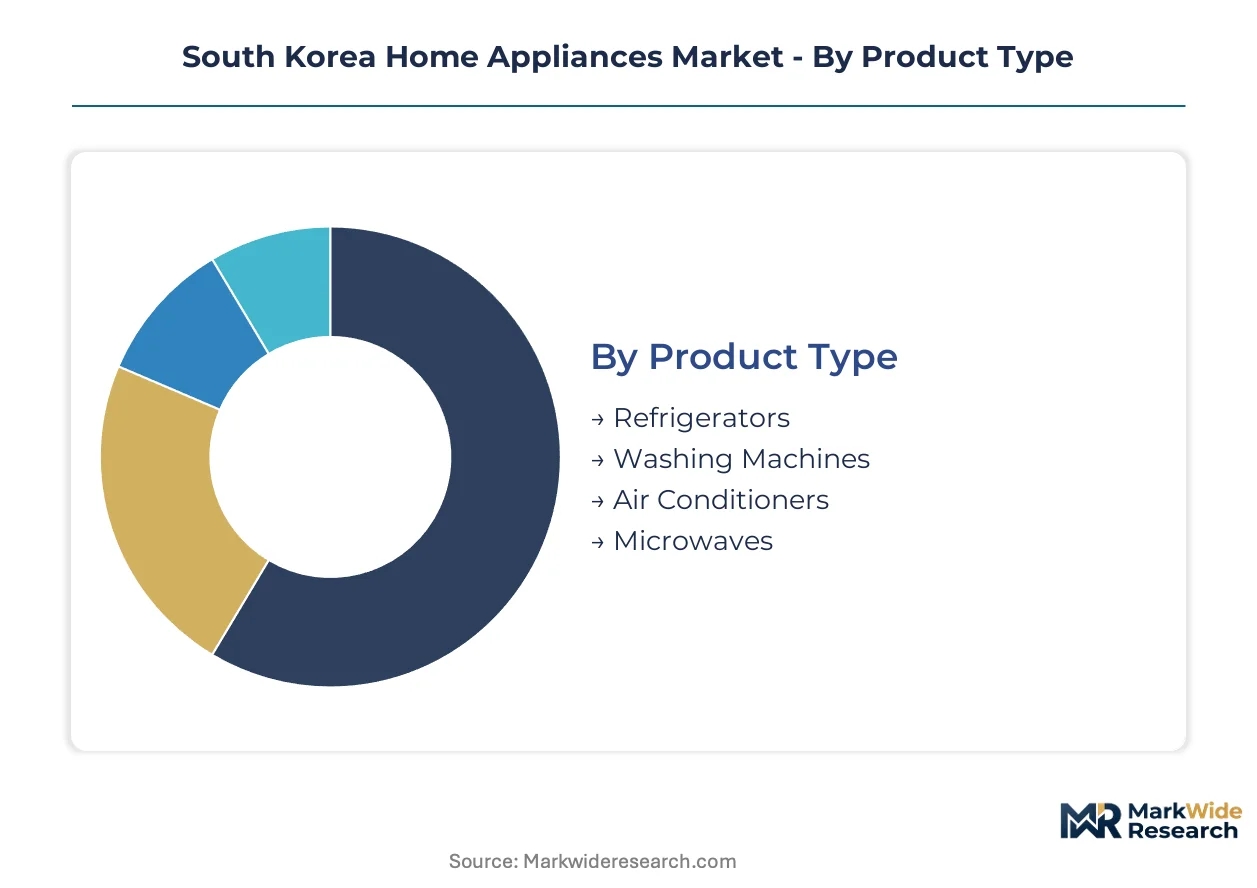
Segmentation in the South Korean home appliances market reveals how replacement cycles, regulatory thresholds, and channel economics fragment demand across technical tiers and end-use contexts. Understanding these divides clarifies where manufacturers must align product specifications with MFDS certification requirements and MEET efficiency mandates.
Product Type:
Upgrade cycles vary sharply by product category, with Seoul's high-rise residential automation pulling certain segments into accelerated replacement timelines while others lag on durability-driven purchasing.
- Refrigerators:Double-door and French-door configurations with AI food management systems dominate new apartment specifications in Gangnam and Seongsu-dong districts, where IoT integration has become a baseline developer requirement rather than premium upsell.
- Washing Machines:Direct-drive motor technology and steam sanitization functions concentrate demand among young professional households in Seoul's metropolitan corridor, though physical dimensions in micro-unit housing constrain capacity specifications and average selling prices.
- Air Conditioners:Inverter compressor systems with smart grid compatibility are penetrating fastest through KEPCO demand-response incentive programs.
- Microwaves:Combination oven-microwave units with sensor cooking retain stable replacement demand in Busan's commercial food-service refurbishment cycles.
Volume placements concentrate in Refrigerators; the faster expansion belongs to Air Conditioners.
Technology:
Cost tiers separate technology adoption patterns, with premium smart systems commanding developer-specified contracts while traditional units persist in price-sensitive replacement channels.
- Smart:Edge-AI inference chips embedded in appliance control panels enable predictive maintenance and energy optimization, absorbing functions previously handled by standalone home automation hubs.
- Energy-Efficient:Grade 1 and Grade 2 MEET-certified models dominate institutional procurement in Busan's manufacturing belt, where corporate ESG targets mandate equipment upgrades.
- Traditional:Basic mechanical controls without connectivity persist in rental apartment segments and legacy high-rise buildings with limited electrical infrastructure capacity.
- IoT-Enabled:Broadband-connected appliances with smartphone integration are climbing fastest in Jeju Island hospitality construction outside the Seoul-Busan axis.
Traditional units retain the largest installed base; IoT-Enabled systems are climbing the fastest.
End User:
Application context determines margin structure, with bulk commercial contracts concentrating procurement leverage while residential fragmentation preserves pricing power for differentiated features.
- Residential:Individual household purchases across Seoul's metropolitan corridor and Busan's dense districts drive replacement-cycle velocity, with apartment size constraints capping premium model penetration.
- Commercial:Food-service operators and retail chains in Busan's manufacturing belt are shortening equipment replacement cycles to meet corporate carbon-reduction targets, concentrating demand for energy-efficient refrigeration.
- Hotels:Boutique properties and casino resorts on Jeju Island are creating concentrated demand for commercial-grade climate control systems with integrated air purification.
- Institutions:Schools and healthcare facilities prioritize MEET Grade 1 certification and extended warranty terms over connected features.
Residential channels absorb the highest unit volumes; Hotels are gaining share fastest.
Distribution Channel:
Customer type and procurement scale fragment channel economics, with direct sales capturing institutional bulk contracts while online retail penetrates replacement-driven residential purchases.
- Online Retail:E-commerce platforms with installation coordination services are capturing replacement-cycle purchases from time-constrained professionals in Seoul's high-density districts.
- Offline Retail:Manufacturer-branded experience centers and electronics megastores retain importance for high-consideration smart appliance purchases requiring demonstration.
- Direct Sales:Bulk procurement contracts with property developers and hotel operators bypass retail margin structures entirely.
- Wholesalers:Regional distributors serve independent technicians and apartment management associations in Busan's commercial districts with unbundled after-sales service models.
Offline Retail maintains the deepest penetration; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area concentrates over half of national appliance demand through dense high-rise residential automation and developer-specified smart kitchen contracts.
Seoul Capital Area
Developer mandates for IoT-ready appliances in Gangnam and Seongsu-dong high-rises accelerate replacement cycles among young professional households. MFDS safety certification and MEET efficiency thresholds filter import-dependent competitors from premium segments. Samsung Electronics and LG Electronics anchor manufacturing and R&D clusters in Suwon and Pyeongtaek, supplying AI-integrated refrigerator platforms to metropolitan developers.
Busan-Ulsan
Commercial food-service operators and hotel chains shorten equipment replacement cycles to meet corporate ESG targets, concentrating bulk procurement of energy-efficient refrigeration. KEPCO demand-response programs incentivize smart grid-compatible air conditioner installations in manufacturing belt facilities. Independent technician networks in Busan's dense commercial districts capture after-sales service revenue through unbundled maintenance contracts.
Daegu-Gyeongbuk
Textile and electronics manufacturing heritage supports component supply chains for direct-drive motors and compressor assemblies. MEET carbon-reduction mandates on imported steel housings push assemblers toward Korean-sourced sheet metal. Daegu's industrial parks host mid-tier appliance fabricators serving price-sensitive replacement channels in legacy apartment complexes.
Daejeon-Sejong
Government administrative relocation to Sejong City generates institutional procurement for MEET Grade 1-certified climate control systems in public buildings. KTL and KTC testing laboratory proximity accelerates KC mark certification timelines for domestic manufacturers. Daejeon's research institutes collaborate with appliance makers on smart grid integration and edge-AI firmware development.
Gwangju-Honam
Agricultural processing and food manufacturing bases sustain commercial refrigeration demand outside the Seoul-Busan axis. Smaller apartment stock and older high-rise electrical infrastructure limit premium smart appliance penetration, preserving traditional mechanical-control segments. Regional distributors serve independent technicians with unbundled service models bypassing manufacturer-authorized networks.
South Korea Home Appliances Market Competitive Landscape
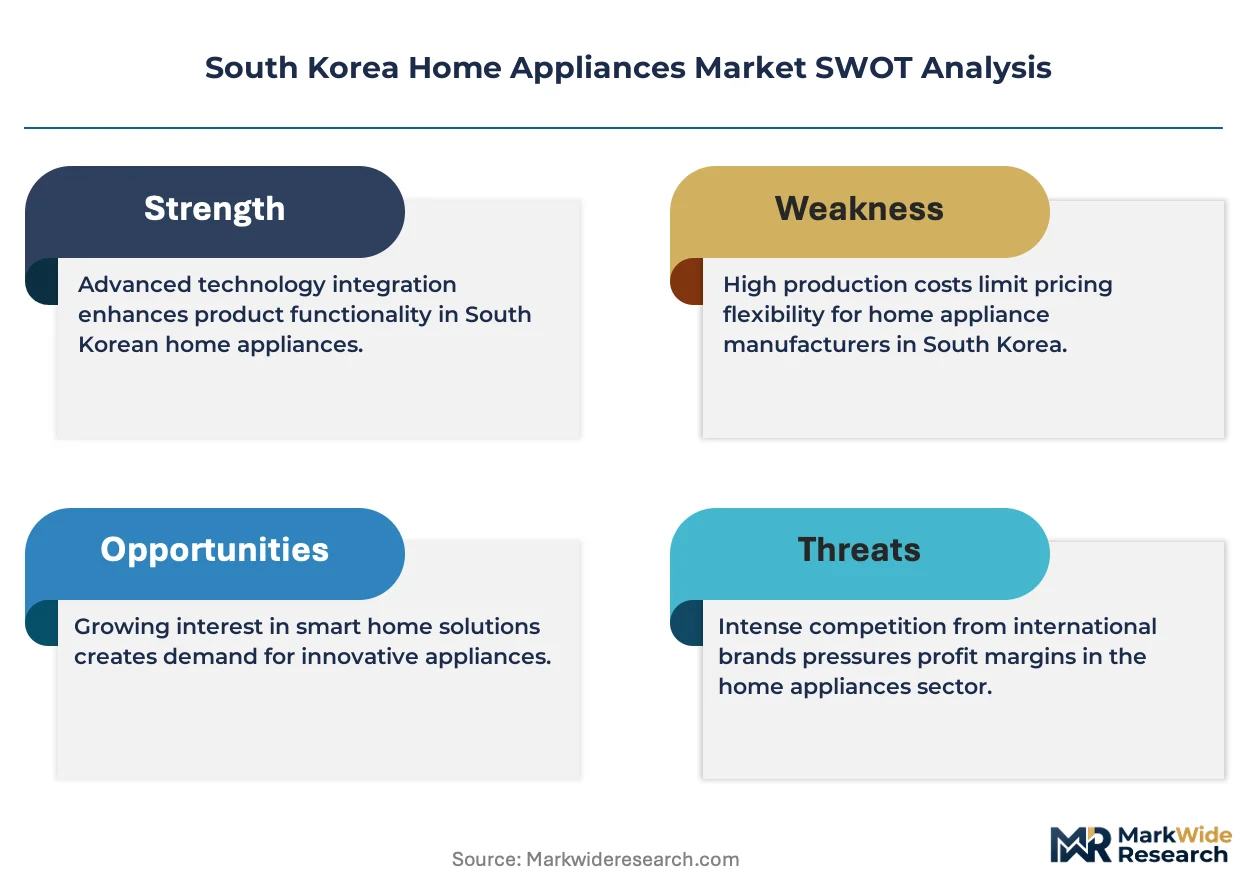
Premium-margin players sit above commodity-margin players across technology integration and certification capability dimensions. The market structure consolidates around diversified conglomerates with captive semiconductor and compressor supply chains, mid-tier specialists in purification niches, and import-dependent assemblers facing margin compression from MEET material documentation requirements. Three archetypes dominate: integrated technology conglomerates controlling core components, single-category specialists defending defensible niches, and regional distributors capturing service revenue through unbundled maintenance networks. Competitive moves concentrate on backward integration into compressor manufacturing and strategic partnerships with property developers for bulk procurement contracts.
Among Korea-based diversified manufacturers, Samsung Electronics and LG Electronics exemplify integrated conglomerates leveraging semiconductor and motor technology divisions to dominate smart appliance platforms. Coway Co., Ltd. occupies a specialist position in water and air purification, defending margin through subscription-based filter replacement models rather than competing across full appliance suites. These three anchors illustrate how market position depends on supply chain control depth rather than portfolio breadth alone.
| Leading Market Players |
|---|
| Coway Co., Ltd. |
| Whirlpool Corporation |
| Samsung Electronics |
| Haier Electronics Group Co Ltd |
| Panasonic Corporation |
| LG Electronics |
| SK Magic |
| BSH Hausgeräte GmbH |
| Winia Electronics (Daewoo) |
| Others |
Value Network & Pricing Analysis
MEET's carbon-reduction mandates for imported steel and aluminum components gate both qualified supply and premium-tier pricing access, forcing manufacturers to document embodied emissions or forfeit developer-specified contracts in Seoul's high-rise residential corridor.
Pricing Analysis
Value-based pricing anchored to energy efficiency outcomes dominates institutional procurement, with Grade 1 MEET certification commanding measurable premiums over Grade 3-4 alternatives in Busan's commercial refurbishment cycles. Price differentiation rests on certification tier and after-sales service bundling, with unbundled maintenance contracts compressing margins in legacy apartment segments. Cost compression in mid-tier mechanical-control units is intensifying because import-dependent assemblers face margin pressure from material documentation requirements. Rental apartment management associations exhibit highest price sensitivity; boutique hotel operators on Jeju Island show lowest sensitivity due to ESG-mandated procurement timelines.
Supply Chain Analysis
Freight cost volatility from Japanese and German compressor specialists exposes Korean assemblers to currency-driven input price swings during peak seasonal demand windows. Supply concentrates in South Korea for direct-drive motors and sheet steel fabrication, Japan and Germany for premium inverter compressors, and China for electronic control modules. Raw material dependencies span rare earth elements for high-efficiency motor magnets, aluminum for heat exchanger coils, and specialized steel grades for compressor housings. Single-source vulnerability in Japanese inverter compressor allocation creates structural risk during semiconductor foundry allocation conflicts. Distribution runs through manufacturer-branded experience centers for high-consideration purchases and direct sales channels for developer bulk contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive compressor manufacturing and in-house semiconductor fabrication determine who secures developer-specified premium contracts versus who faces commodity-margin compression.
For Market Incumbents: Hedge against import dependency by accelerating backward integration into domestic compressor production or securing long-term allocation agreements with Japanese specialists before MEET documentation requirements tighten further. Defend margin position through exclusive smart grid integration partnerships with KEPCO that freeze out competitors lacking firmware development scale.
For New Entrants and Emerging Players: Edge-AI inference chips for predictive maintenance offer the most penetrable wedge into mid-tier refrigerator and washing machine lines where Samsung and LG have not yet migrated flagship capabilities. Target Gwangju-Honam's agricultural processing base with commercial refrigeration systems that bypass Seoul's electrical infrastructure constraints. Pursue subscription-based water purification service models that bypass retail margin structures entirely.
For Investors and Strategic Acquirers: KEPCO demand-response program enrollment spikes are the leading indicator that smart grid-compatible inventory will command acquisition premiums over traditional mechanical-control portfolios. Long-term viability favors specialists with captive metal fabrication or Korean-sourced sheet steel that insulate margins from MEET carbon documentation requirements. Watch for independent technician certification volume through KTL's repair program as signal of unbundled service model maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of inverter compressors insulates margins from Japanese allocation constraints and MEET documentation costs. |
| Smart Grid Integration Partnership | KEPCO demand-response program enrollment opens utility-partnered distribution channels with rate reduction incentives. |
| Subscription Service Model Launch | Filter replacement and IoT monitoring subscriptions penetrate rental segments previously served by low-margin retail. |
| Regional Certification Team Expansion | Dedicated KTL and KTC liaison capabilities compress lead times for KC mark approval versus competitor queues. |
| Jeju Island Hospitality Focus | Boutique hotel and casino resort construction outside Seoul-Busan axis concentrates commercial-grade climate control demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with appliance R&D directors, property developer procurement managers, KTL certification specialists, and KEPCO demand-response program officers with bottom-up and top-down triangulation. Secondary sources included MFDS safety certification databases, MEET efficiency standard documentation, KC mark registration records, and import customs declarations for compressor and motor components.
Granularity-level modeling segmented volume and value outputs by product type, technology tier, end-user category, and distribution channel across the projection horizon, with CAGRs derived from replacement cycle velocity analysis and regulatory threshold timing. Industry-specific forecast inputs captured apartment automation mandate penetration rates in Seoul's metropolitan corridor and Busan commercial refurbishment cycle shortening patterns.
Several conditions sit outside the modeled scope, including abrupt tariff shifts on Japanese compressor imports, KEPCO incentive program suspension, and MFDS safety standard revisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
European Built-In Refrigerator Market
Home Appliances
Electrical Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
Oman Major Home Appliances Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
India Refrigerator Market
Home Appliances
Canada Home Appliances Market