
 Household Refrigerators and Freezers Market | 2026-2036
Household Refrigerators and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Household Refrigerators and Freezers Market Intelligence
Demand from urban households seeking smart, integrated appliances is rotating away from suburban families prioritizing bulk storage capacity. Whirlpool Corporation leverages its extensive distribution network to serve these diverse consumer segments across multiple price points. Samsung Electronics differentiates with its smart cooling technologies and connected features integrated into its premium lines. Meanwhile, Haier Group competes on manufacturing scale and rapid product development, particularly in Asian markets.
Household refrigerators and freezers are enclosed appliances utilizing a vapor-compression refrigeration cycle to transfer heat from the interior to the external environment. These systems depend on a refrigerant, compressor, condenser coils, and an evaporator to maintain temperatures below ambient for food preservation. The French Door product type commands a premium, while adoption of inverter technology is accelerating due to its energy-saving benefits. Online retailers are rapidly gaining share as a key distribution channel, altering the path to market for many brands.
Energy efficiency standards, such as the EPA's Energy Star program in the United States and EU energy labelling regulations, mandate continuous performance improvements. Concurrently, the EU's F-Gas Regulation and similar rules in other jurisdictions restrict the use of high global warming potential refrigerants, influencing component design. Manufacturers must decide whether to invest in advanced smart features for premium segments or focus on cost-effective, compliant models for mass-market adoption.
Market Dynamics
The household refrigerator and freezer market is shaped by the dual pressures of stringent energy efficiency regulations and the mandated phase-out of high global warming potential refrigerants, forcing a concurrent redesign of both core cooling systems and insulation materials.
Growth Catalysts
- Inverter Technology:The widespread integration of inverter compressors provides significant energy savings and quieter operation, creating a compelling upgrade incentive for consumers in mature markets seeking lower utility bills and improved home acoustics.
- Urbanization in Asia:Rapid household formation and rising disposable incomes in high-density urban centers across India and China are fueling first-time purchases and demand for compact, feature-rich models suited for smaller living spaces.
- Energy Labeling Mandates:Regulatory frameworks, including the EU's energy labelling and the EPA's Energy Star program in the United States, continuously tighten standards, which accelerates the replacement cycle for older, less efficient appliances.
Market Restraints
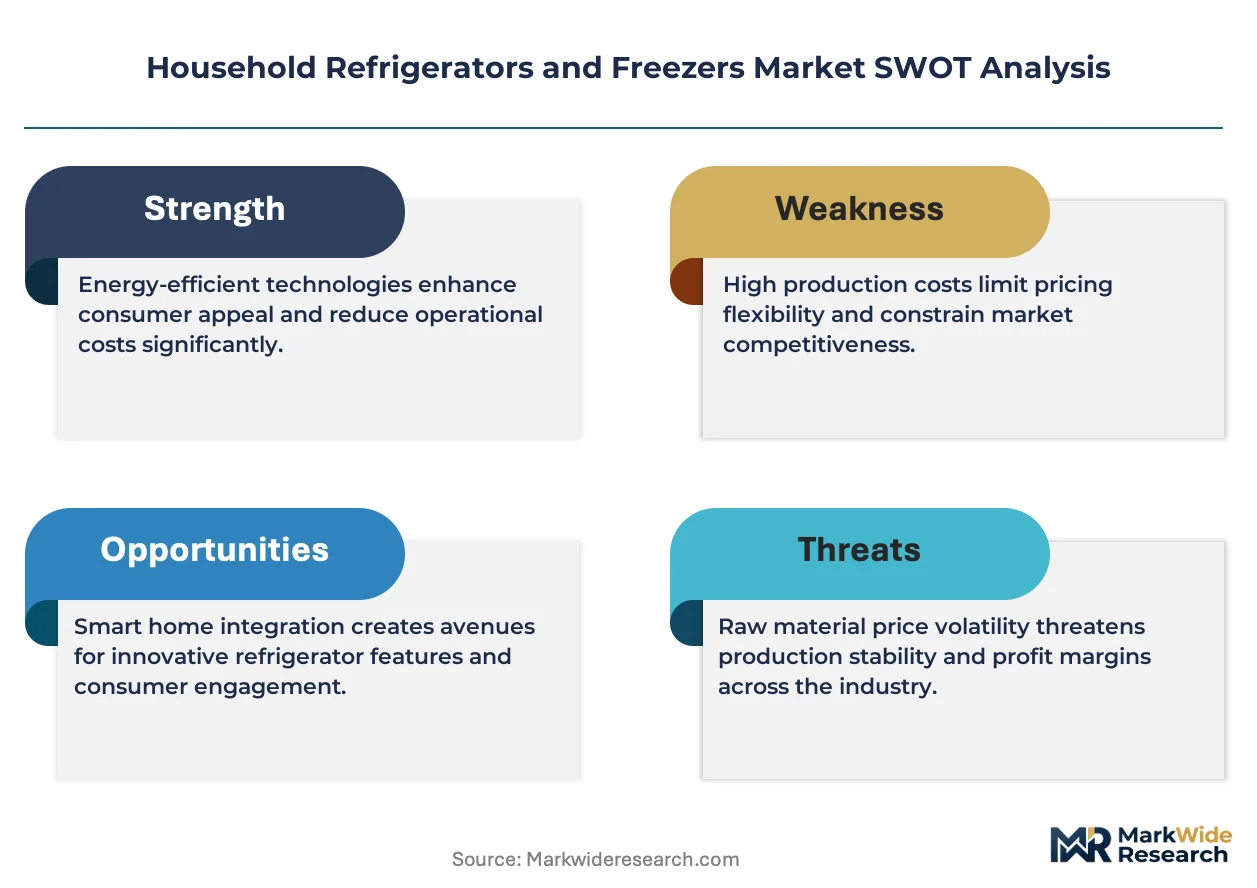
- Raw Material Volatility:Price fluctuations in key commodities, particularly steel for casings, copper for coils and wiring, and petrochemicals for insulation foam, directly impact production costs and compress manufacturer margins.
- Refrigerant Transition Complexity:Shifting to low-GWP refrigerants like R-600a or R-290 requires significant engineering to manage flammability risks and maintain cooling performance, adding cost and design complexity to new models.
- Logistics and Channel Costs:The high cost of transporting bulky, heavy appliances and managing last-mile delivery, especially in congested urban areas, adds a significant layer of expense that is ultimately passed on to consumers.
Strategic Opportunities
- Secondary City Expansion:Targeting emerging middle-class consumers in secondary and tertiary cities across Southeast Asia and Africa, where grid electrification is improving, opens a new frontier for volume growth beyond saturated primary markets.
- AI-Powered Food Management:Integrating AI-driven camera systems that track inventory, suggest recipes, and monitor food freshness can create a new subscription-based service layer and lock consumers into a specific smart home ecosystem.
- Direct-to-Consumer Channels:Developing robust online direct-to-consumer (DTC) sales platforms allows brands to bypass traditional retail, control the customer experience, and capture data on consumer preferences to inform future product development.
Industry Challenges
- Multi-Jurisdictional Compliance:Navigating the patchwork of differing energy, safety, and refrigerant regulations, such as the EU F-Gas rules and various GB standards in China, creates significant testing and certification burdens for global manufacturers.
- Smart Feature IP Licensing:The integration of smart home connectivity and advanced user interfaces often requires complex and costly intellectual property licensing agreements with technology platform holders, increasing bill-of-materials cost.
- Production Line Re-tooling:The shift to alternative refrigerants and more efficient compressor designs necessitates substantial capital investment in re-tooling manufacturing facilities, posing a barrier to smaller or less capitalized players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Refrigerators and Freezers Market |
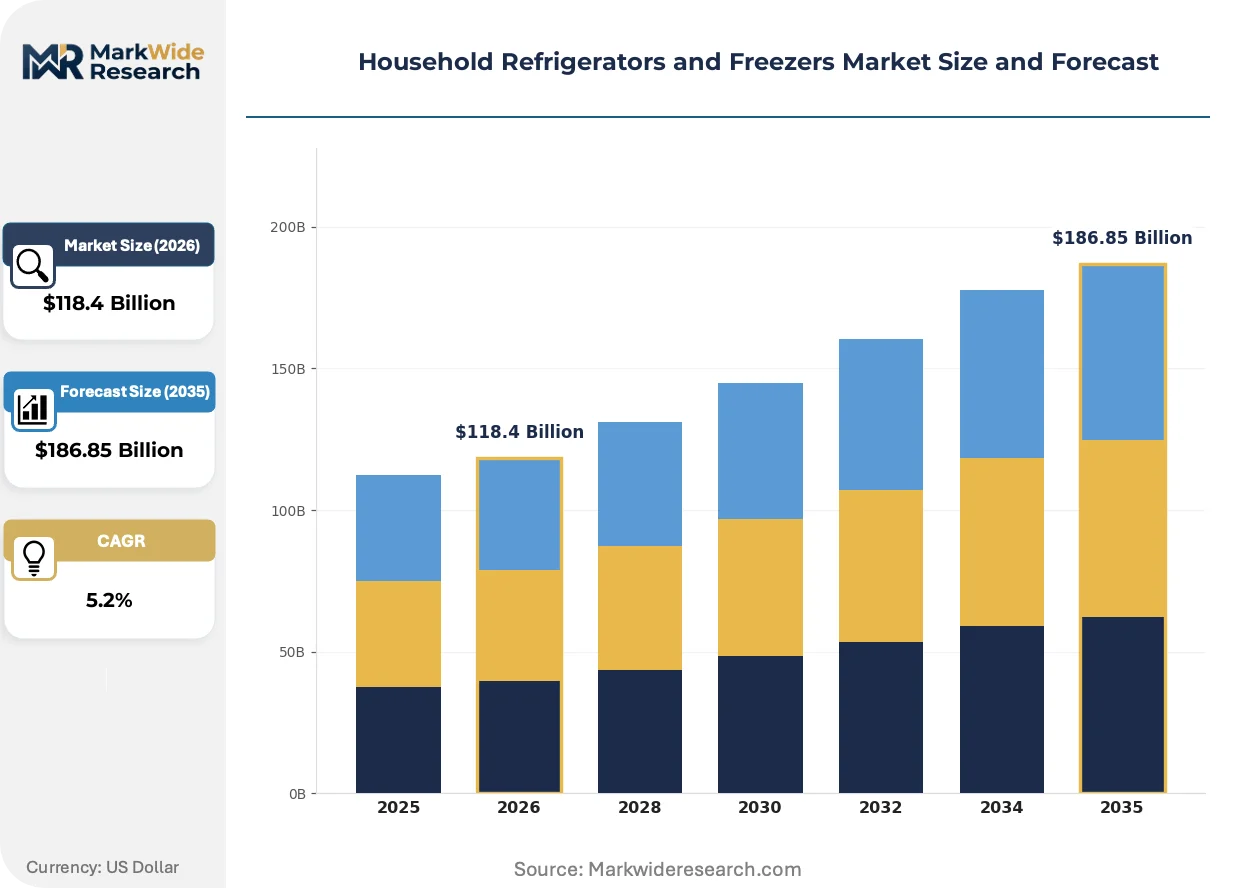
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $186.85 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Door, Double Door, Side-by-Side, French Door, Compact Technology: Inverter, Direct Cool, Frost Free, Smart Cooling, Turbo Cooling End User: Urban Households, Suburban Families, Rental Apartments, Vacation Homes, Dormitories Distribution Channel: Electronic Stores, Online Retailers, Appliance Wholesalers, Specialty Dealers, Direct Sales |
| Companies Covered | Electrolux, Bosch, Whirlpool Corporation, Maytag, GE Appliances, Samsung Electronics, Haier Group, KitchenAid, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Refrigerators and Freezers Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of sustainability mandates with smart technology. This creates a distinct bifurcation between cost-effective, eco-efficient appliances for the mass market and premium, connected units that serve as central hubs for the smart kitchen.
Smart diagnostic technology utilizes embedded sensors and Wi-Fi connectivity to actively monitor component performance and predict potential failures in compressors or fans. Premium and mid-range consumer segments are adopting these features for the promise of proactive service alerts and reduced appliance downtime. This capability is fragmenting the traditional after-sales service market, pushing it from a reactive, break-fix model toward predictive, subscription-based maintenance relationships.
China's national "dual carbon" objectives and associated GB standards for appliance energy consumption are setting a rapid pace for innovation. This regulatory push is forcing manufacturers to invest heavily in R&D for next-generation vacuum insulation panels and variable-speed compressors. The mass-market segment is most affected, as brands compete aggressively to achieve the highest energy efficiency ratings to attract cost-conscious consumers.
A definitive behavioral change is the consumer pivot toward purchasing major home appliances via online channels, including large e-commerce marketplaces and brand-direct websites. This trend disrupts the historical dominance of brick-and-mortar big-box retailers and specialized local appliance stores. The shift is most advanced in North American and European metropolitan areas, where online price transparency and delivery convenience are primary purchasing factors.
Household Refrigerators and Freezers Market Segmentation
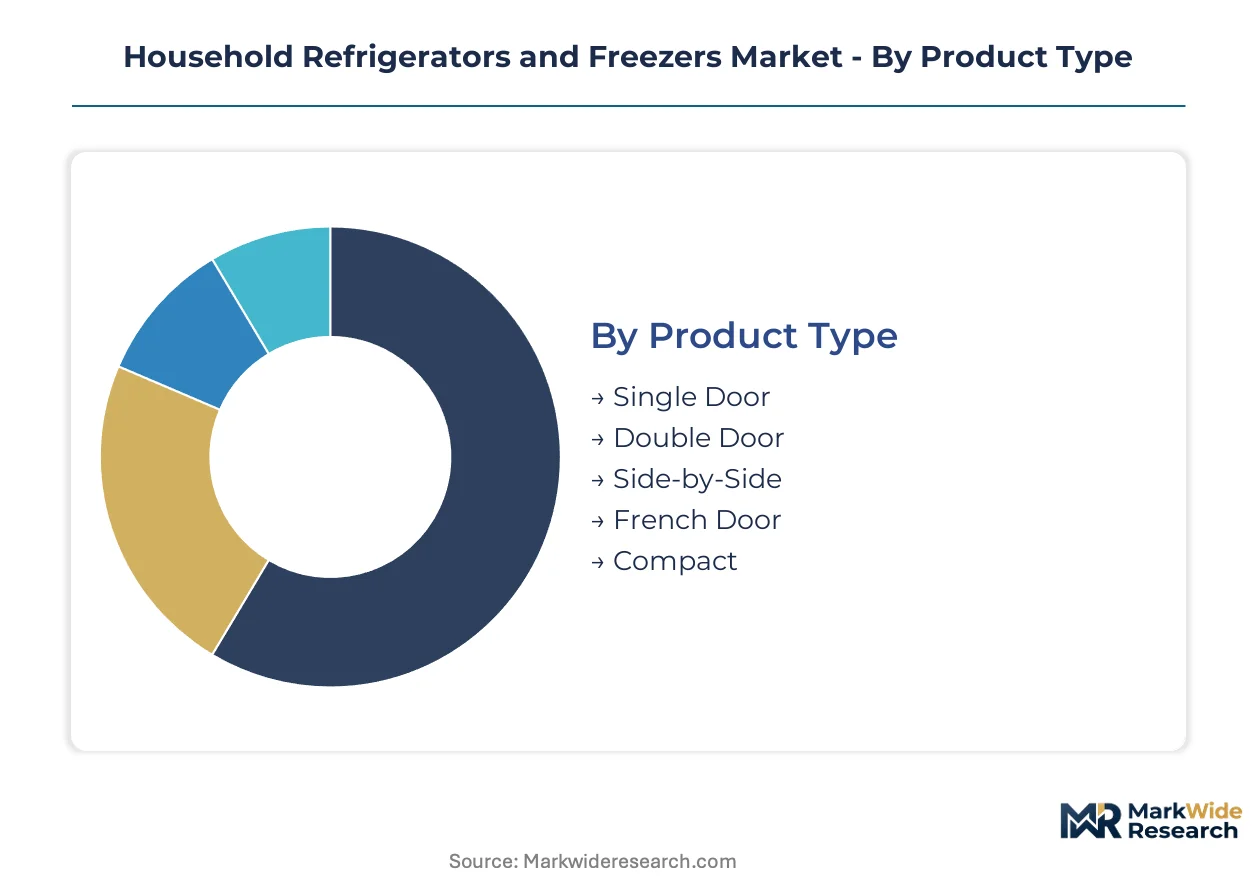
The Household Refrigerators and Freezers market exhibits diverse segmentation, reflecting varied consumer needs, technological advancements, and distribution strategies. Understanding these segments helps manufacturers tailor product development and market penetration efforts effectively across different economic strata and geographical regions.
Product Type:
Margin pools within this category typically sit with premium, feature-rich product types that offer advanced aesthetics and functionality to discerning consumers.
- French Door:These units feature two side-by-side refrigerator doors above a freezer drawer, offering wide storage and ergonomic access. Demand concentrates in urban households across Europe and North America seeking premium aesthetics and flexible storage solutions.
- Side-by-Side:Side-by-side models feature two full-height doors, one for the refrigerator and one for the freezer, maximizing internal capacity. Suburban families in the United States and Canada prioritize these for bulk food storage and convenient organization.
- Single Door:Single door refrigerators offer basic cooling functionality within a compact footprint, serving budget-conscious consumers and small living spaces.
- Double Door:Double door models typically feature a top-mounted freezer and bottom refrigerator, providing a balance of capacity and cost-effectiveness for mid-tier households.
- Compact:Compact units cater to niche applications like dormitories, small offices, or secondary refrigeration needs, emphasizing portability and minimal space requirements.
The dominant share belongs to Double Door, while French Door is closing the gap fastest.
Technology:
Cost tiers primarily differentiate the technology landscape, influencing accessibility and performance for various consumer segments.
- Inverter:Inverter technology employs a variable-speed compressor that adjusts cooling power based on demand, reducing energy consumption and noise levels. Consumers in India and China increasingly seek these units for long-term utility savings and quieter home environments.
- Smart Cooling:Smart cooling systems integrate sensors, algorithms, and often AI to optimize temperature, humidity, and airflow, extending food freshness. Premium urban households in South Korea and Germany adopt these for integrated home ecosystems and proactive food management.
- Direct Cool:Direct cool systems rely on natural convection for cooling, offering simplicity and lower cost, primarily serving entry-level markets.
- Frost Free:Frost free technology prevents ice buildup through automatic defrost cycles, improving convenience and maintaining consistent cooling performance.
- Turbo Cooling:Turbo cooling functions rapidly lower temperatures for quick chilling of newly added items, appealing to users seeking immediate cooling effects.
Inverter technology remains the most impactful for energy efficiency, with Smart Cooling solutions expanding most quickly among premium buyers.
End User:
Application needs dictate feature sets and capacity requirements across different end-user groups, influencing product design.
- Urban Households:These households typically occupy smaller living spaces and prioritize compact, feature-rich appliances that integrate seamlessly into modern interiors. Demand is particularly strong in high-density cities like Mumbai and Shanghai for smart, connected units.
- Suburban Families:Suburban families require larger capacity refrigerators and freezers for bulk purchasing and extended food storage, often prioritizing durability and organizational features. North American and European suburban areas drive demand for multi-door and side-by-side models.
- Rental Apartments:Rental apartments require durable, cost-effective appliances with standard features, often supplied by landlords or property management companies.
- Vacation Homes:Vacation homes demand reliable, energy-efficient units that can operate effectively during periods of infrequent use, often with smart monitoring capabilities.
- Dormitories:Dormitories necessitate compact, basic, and highly durable refrigerators designed for personal use in limited shared living environments.
Urban Households and Suburban Families represent the largest consumer bases, driving demand for distinct product categories.
Distribution Channel:
Customer type significantly influences the preferred distribution channel, impacting brand reach and sales strategy across diverse markets.
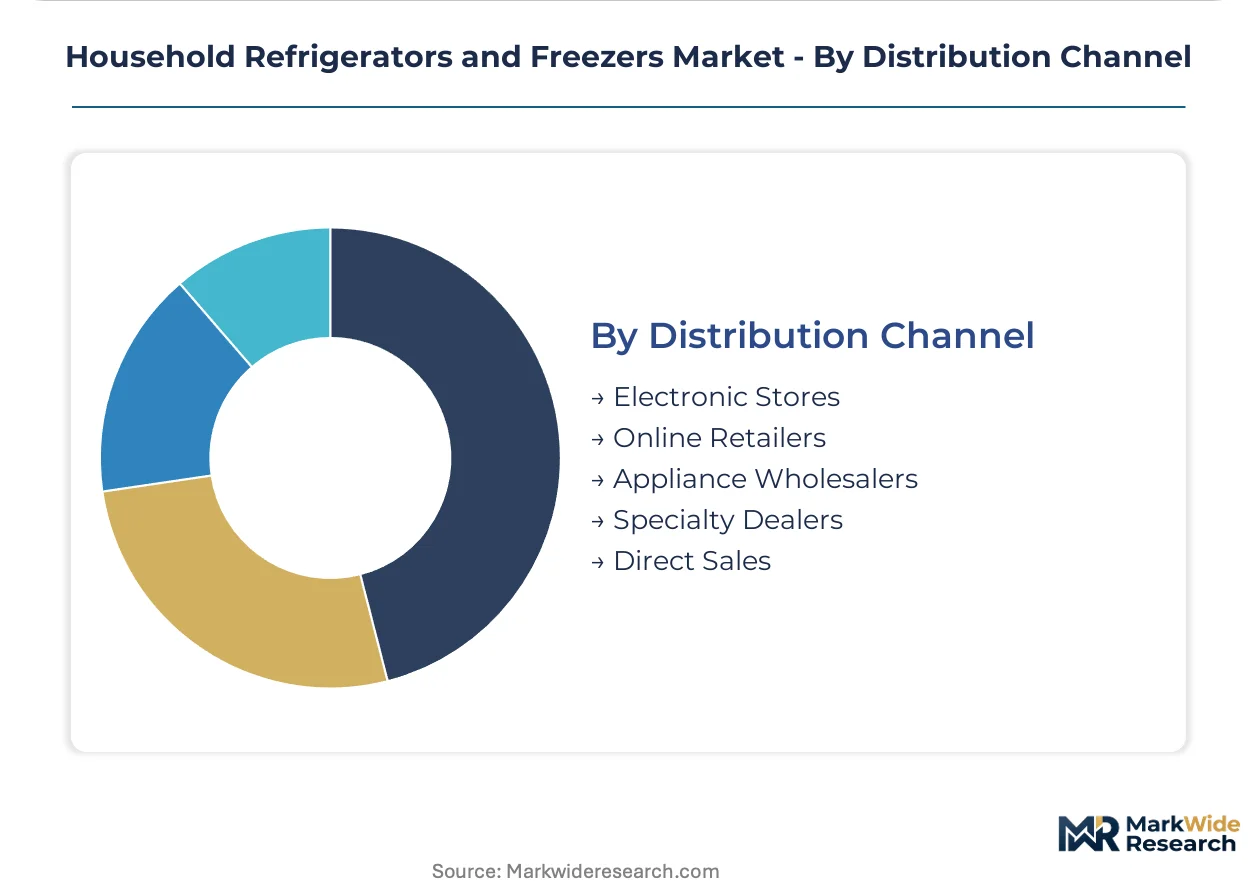
- Online Retailers:These platforms offer extensive product catalogs, price comparison tools, and home delivery services, appealing to digitally native consumers seeking convenience. North American and European metropolitan areas show a strong preference for this channel due to transparency.
- Electronic Stores:Brick-and-mortar electronic stores provide a physical touchpoint for consumers to inspect products, receive expert advice, and make immediate purchases. Consumers in Germany and Japan often prefer this channel for major appliance purchases.
- Appliance Wholesalers:Appliance wholesalers serve bulk buyers such as property developers, hotels, or retailers, focusing on volume discounts and efficient supply chain logistics.
- Specialty Dealers:Specialty dealers offer curated selections, personalized service, and often installation support for premium or niche appliance brands, targeting discerning buyers.
- Direct Sales:Direct sales channels allow manufacturers to control the entire customer journey, offering exclusive products and services directly to consumers, often online.
Online Retailers are rapidly gaining market share, while Electronic Stores continue to serve a substantial customer base, offering tangible product interaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive grid interconnectivity across major population centers underwrites robust demand for household refrigerators and freezers. Modern distribution networks facilitate product movement to diverse consumer segments. This infrastructure supports both premium and mass-market appliance adoption.
United States
Suburban families in the United States prioritize large-capacity side-by-side models for bulk food storage. The EPA's Energy Star program drives continuous performance improvements, accelerating replacement cycles. Manufacturing facilities in Kentucky and Ohio concentrate on producing energy-efficient, multi-door refrigerators for the North American market.
China
Rapid urbanization in China fuels first-time purchases and demand for compact, feature-rich models. China's "dual carbon" objectives and GB standards drive heavy investment in next-generation vacuum insulation panels. Appliance manufacturing hubs in Guangdong and Zhejiang provinces lead product development for Asian consumers.
India
Rising disposable incomes in India's urban centers drive demand for inverter technology units, offering long-term utility savings. The Bureau of Energy Efficiency (BEE) star rating system promotes energy-efficient appliances. Production facilities in Maharashtra and Tamil Nadu scale manufacturing to meet the expanding domestic consumer base.
Germany
Premium urban households in Germany increasingly adopt smart cooling systems for integrated home ecosystems. EU energy labelling regulations mandate continuous performance improvements, pushing manufacturers towards higher efficiency. Engineering and design centers in Bavaria and Baden-Württemberg focus on developing advanced features for discerning European buyers.
South Korea
Urban households in South Korea seek smart, connected units as central hubs for the modern kitchen. The Korea Energy Management Corporation (KEMCO) sets stringent energy efficiency standards, fostering rapid technological advancements. Major electronics manufacturers in Seoul and Gyeonggi province drive innovation in AI-powered food management ecosystems.
Household Refrigerators and Freezers Market Key Industry Players
Concentration sits with established global conglomerates leveraging extensive distribution networks and strong brand recognition. The market exhibits a tiered structure, from premium innovators focusing on smart features to mass-market volume producers emphasizing cost-effectiveness. Strategic archetypes include technology leaders, scale-driven manufacturers, and regional specialists. Companies pursue competitive moves like portfolio diversification into adjacent home appliance categories and geographic expansion into high-growth urban centers.
Within the global conglomerate archetype, Whirlpool Corporation, an American multinational, represents a player with an extensive distribution network across diverse consumer segments. Samsung Electronics, a South Korean firm, exemplifies a technology leader, anchoring its position with advanced smart cooling solutions and integrated connected features. Haier Group, a Chinese multinational with a significant global footprint, occupies a position as a scale-driven manufacturer, particularly strong in Asian markets through rapid product development and cost-effective models.
| Leading Market Players |
|---|
| Electrolux |
| Bosch |
| Whirlpool Corporation |
| Maytag |
| GE Appliances |
| Samsung Electronics |
| Haier Group |
| KitchenAid |
| LG Electronics |
Cost & Logistics Intelligence
The transition to low global warming potential refrigerants simultaneously reshapes component supply geography and pricing economics, driving investment in specialized manufacturing capabilities. This shift impacts design complexity and material sourcing across the value chain for household appliances.
Pricing Analysis
Pricing stratifies across premium, standard, and economy tiers, reflecting variations in smart features and manufacturing scale. Advanced smart features, coupled with brand premium, serve as key differentiation drivers for higher price points. Pricing pressure stems from raw material volatility, particularly for steel and copper, compressing manufacturer margins. Mass-market consumers exhibit the highest price sensitivity, often prioritizing energy efficiency ratings, while premium urban households show less concern for initial cost.
Supply Chain Analysis
Strategic stockpiling of critical components balances just-in-time manufacturing for bulky appliances, mitigating raw material volatility risks. Geographic supply concentrates in China and India, which serve as major manufacturing hubs for global and domestic markets. The supply chain relies on steel, copper, and specialized refrigerants, making it susceptible to commodity price volatility. Multi-channel distribution, blending online retailers with physical electronic stores, dominates the downstream structure, influencing last-mile delivery costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase, primarily driven by accelerated replacement cycles for older, less efficient units due to tightening energy regulations.
For Market Incumbents: Shield core market share by consolidating extensive distribution networks and implementing a dual product strategy, catering to both premium smart segments and cost-effective mass markets. Invest heavily in R&D for next-generation energy efficiency solutions to counter increasing regulatory compliance burdens. Leverage existing brand recognition to cross-sell into adjacent smart home ecosystems.
For New Entrants and Emerging Players: Lead with innovative, AI-powered food management systems to establish a new subscription-based service layer within premium urban households. Target secondary and tertiary cities across Southeast Asia and Africa for volume growth, where grid electrification is improving. Develop robust direct-to-consumer channels to control the customer experience and gather valuable preference data.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional specialists possessing strong local supply chains and established manufacturing footprints in high-growth Asian markets. Long-term viability rests on identifying companies capable of navigating multi-jurisdictional compliance and scaling production of energy-efficient models. The acceleration of online retail share serves as a key signal to watch for market inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Direct-to-Consumer Channels | Captures customer data directly from urban households for product development. |
| Invest in Low-GWP Refrigerant R&D | Ensures compliance with EU F-Gas Regulation and similar global rules. |
| Develop AI-Powered Food Management | Creates new subscription revenue streams for premium urban households. |
| Scale Manufacturing in Asia | Addresses rising demand from India and China's expanding consumer base. |
| Acquire Regional Appliance Specialists | Strengthens distribution networks to serve diverse consumer segments. |
Research Approach
A spread of perspectives from manufacturing executives, retail channel managers, regulatory affairs specialists, and consumer insights leads converged on the working assumptions. This involved combining primary interviews with industry stakeholders and secondary validation from government energy efficiency reports, appliance industry trade publications, corporate financial disclosures, and e-commerce sales data. Bottom-up and top-down triangulation ensured data consistency.
The forecast framework modeled segmentation dimensions including product type, technology, end user, distribution channel, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and projected market dynamics across the analysis window. Key industry-specific forecast inputs included inverter technology adoption rates and urban household formation trends.
The analysis sits within stated boundaries; outcomes outside unforeseen supply chain disruptions or sudden shifts in global economic conditions would require recalibration. Forecasts reflect assumptions regarding regulatory stability and consumer purchasing patterns. Revision becomes warranted when significant market structure changes cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Electrical Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Australia Washing Machine Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
Small Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Major Home Appliances Market
Home Appliances
Germany Major Home Appliance Market