

Residential Air-to-Air Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Air-to-Air Heat Pump Market Insights
A-rated efficiency tiers is unwinding legacy non-inverter stock across temperate climate zones. Daikin Industries leverages captive compressor production to sustain margin control across European channels. Mitsubishi Electric anchors premium cold-climate performance through proprietary flash-injection circuits. Panasonic Holdings competes on price-aggressive inverter platforms in Southeast Asian growth corridors.
Residential air-to-air heat pumps are vapor-compression HVAC systems that transfer thermal energy between indoor and outdoor air streams, typically operating with refrigerants at evaporation temperatures between minus fifteen and plus fifteen degrees Celsius to deliver space heating and cooling. The primary commercial purpose is to displace onsite fossil fuel combustion with grid-delivered efficiency in single and multi-family dwellings. Split heat pumps occupy the dominant volume position while inverter technology captures disproportionate margin pools through part-load efficiency premiums. Smart thermostat enabled systems are the fastest-growing technology segment as utility demand-response programs expand enrollment.
The US EPA SNAP program and EU F-Gas Regulation are tightening refrigerant global warming potential thresholds, forcing manufacturers toward R-32 and R-290 transitions that reshape product architecture and certification costs. Japan's METI Top Runner program sustains efficiency escalation that exports competitive pressure into North American and European markets. Stakeholders must monitor refrigerant transition timelines against heat pump manufacturing capacity expansion to avoid stranded inventory or supply bottlenecks.
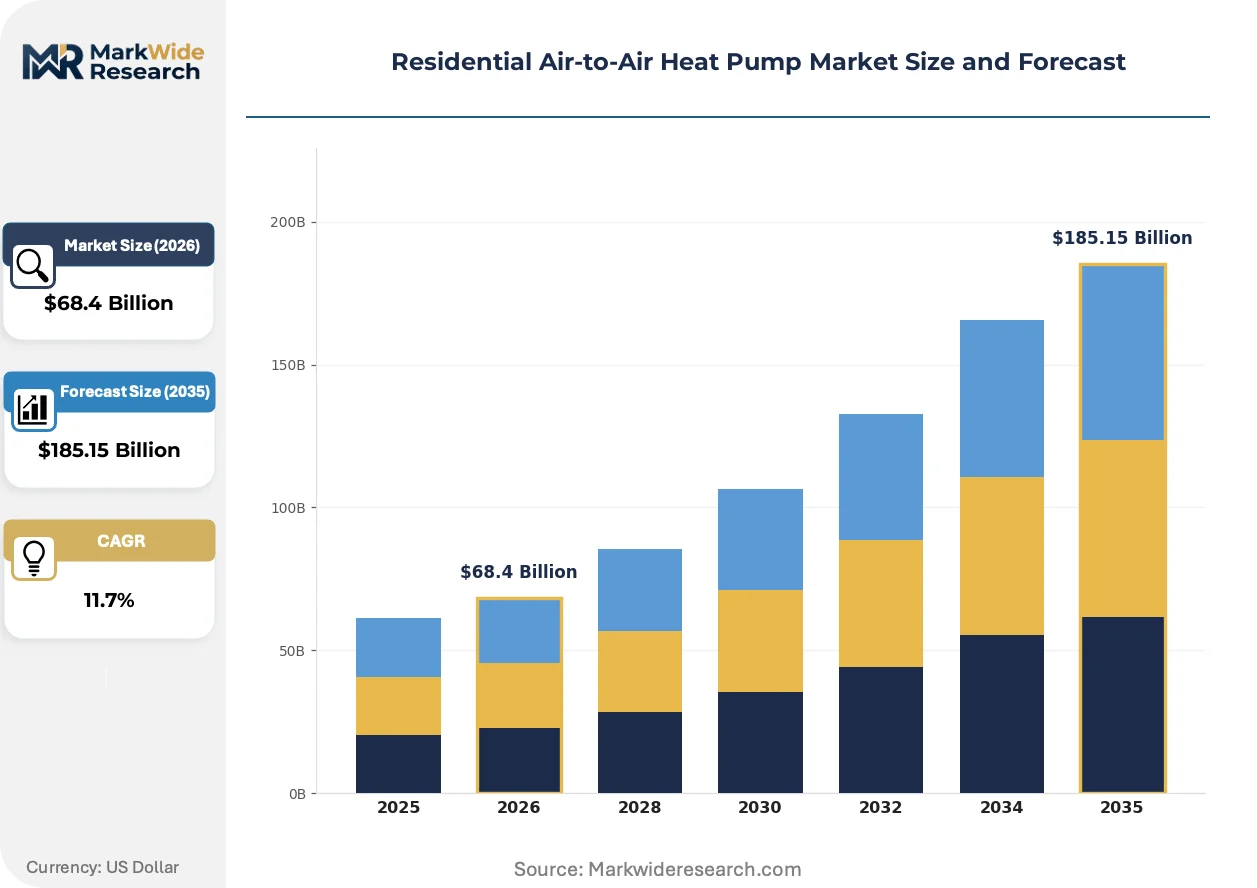
Market Dynamics
The EU F-Gas Regulation and US IRA tax credits are compressing HFC refrigerant use while subsidizing electric heat pump adoption, forcing manufacturers to retool production lines for lower-GWP alternatives ahead of compliance deadlines.
Growth Catalysts
- Electrification mandates:Germany's Building Energy Act requires renewable heating in new construction and major renovations, accelerating fossil fuel displacement in single-family dwellings.
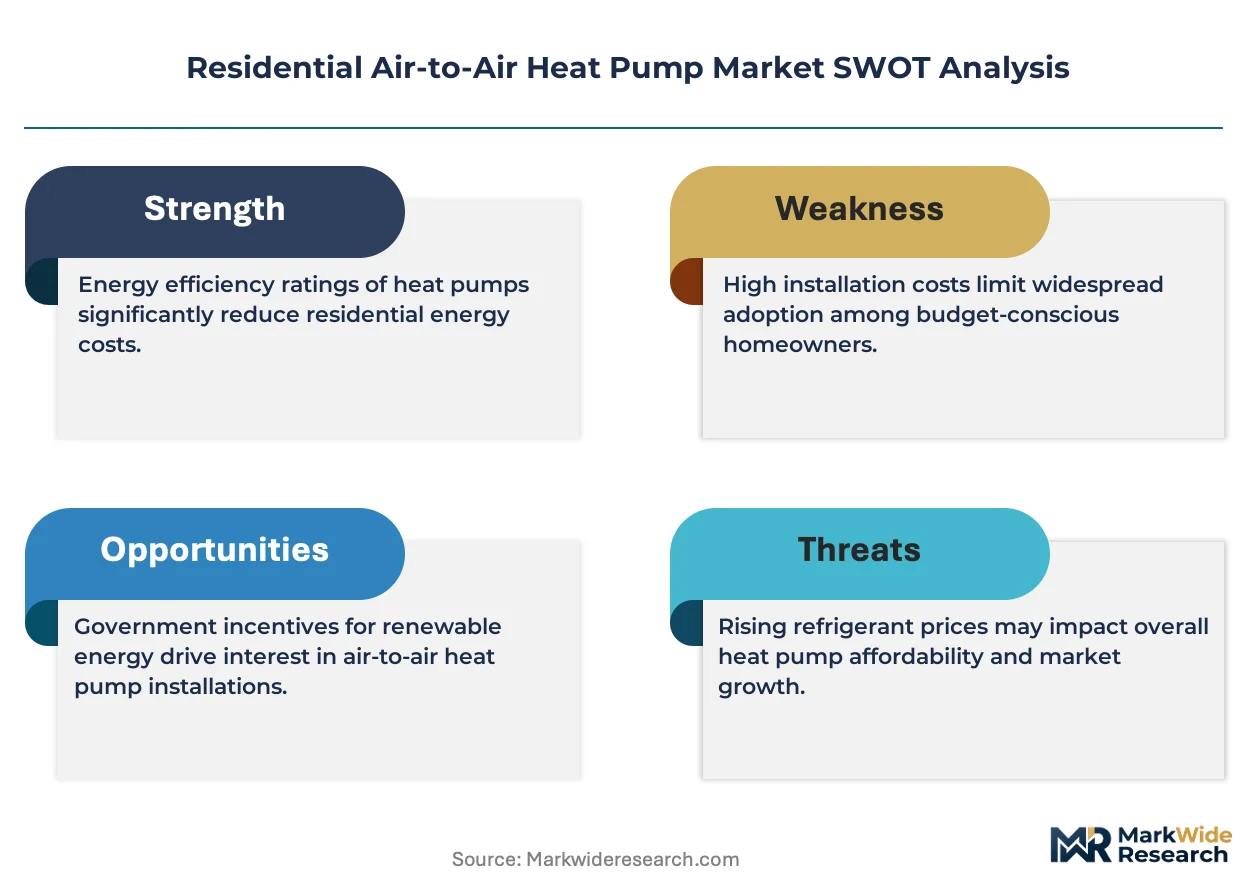
- Refrigerant transition economics:R-32 and R-290 adoption reduces direct emissions intensity, qualifying systems for enhanced utility rebates and green financing programs.
- Cold-climate performance validation:Flash-injection compressor technology extends operational range to minus twenty-five degrees Celsius, unlocking deployment in Nordic and North American heating zones previously served by furnaces.
Market Restraints
- Copper and rare earth input volatility:Compressor motor laminations and heat exchanger tubing face price swings from concentrated Chilean and Chinese supply.
- Installer capacity bottlenecks:Certified technician pools in France, Italy, and Poland lag equipment availability, elongating project timelines.
- Grid infrastructure adequacy:Rural distribution networks in Japan and Germany require reinforcement to handle winter peak loads from mass electrification.
Strategic Opportunities
- Multi-family retrofits:Centralized VRF systems in aging European apartment stock represent underpenetrated volume against dominant single-family deployment.
- Demand-response enrollment:Smart thermostat-integrated heat pumps qualify for utility-controlled load curtailment payments, creating recurring revenue streams.
- Hybrid hydrogen-ready positioning:Dual-fuel system architecture captures transitional installations where building codes permit future fuel switching.
Industry Challenges
- Refrigerant handling certification:R-290 flammability protocols require specialized technician training and equipment upgrades across distribution networks.
- Legacy control integration:Proprietary communication protocols between inverter drives and third-party building management systems create commissioning friction.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Air-to-Air Heat Pump Market Trends and Innovations
Inverter compressor architecture is displacing fixed-speed legacy stock across temperate climate zones, while refrigerant chemistry and control intelligence converge to reshape product positioning and channel economics.
Variable-speed scroll and rotary compressor technology is miniaturizing outdoor unit footprints while maintaining heating capacity ratings. Japanese and South Korean manufacturers are embedding these compact systems into urban multi-family retrofits where space constraints previously blocked installation. The form factor reduction is compressing equipment cost curves and expanding addressable building stock in dense European and East Asian cities.
The US EPA SNAP program and EU F-Gas Regulation are tightening refrigerant global warming potential thresholds, forcing manufacturers toward R-32 and R-290 transitions that reshape product architecture and certification costs. Japan's METI Top Runner program sustains efficiency escalation that exports competitive pressure into North American and European markets. Stakeholders must monitor refrigerant transition timelines against heat pump manufacturing capacity expansion to avoid stranded inventory or supply bottlenecks.
Utility demand-response programs are reshaping procurement criteria for residential buyers. Enrollment-linked rebates from Eversource, Enel, and Tokyo Electric are steering specification toward smart-enabled systems with embedded communication modules. This behavioral shift concentrates volume in channels capable of post-installation commissioning and ongoing connectivity management, favoring national distributors over traditional HVAC wholesalers in Germany, the United States, and Japan.
Residential Air-to-Air Heat Pump Market Segmentation
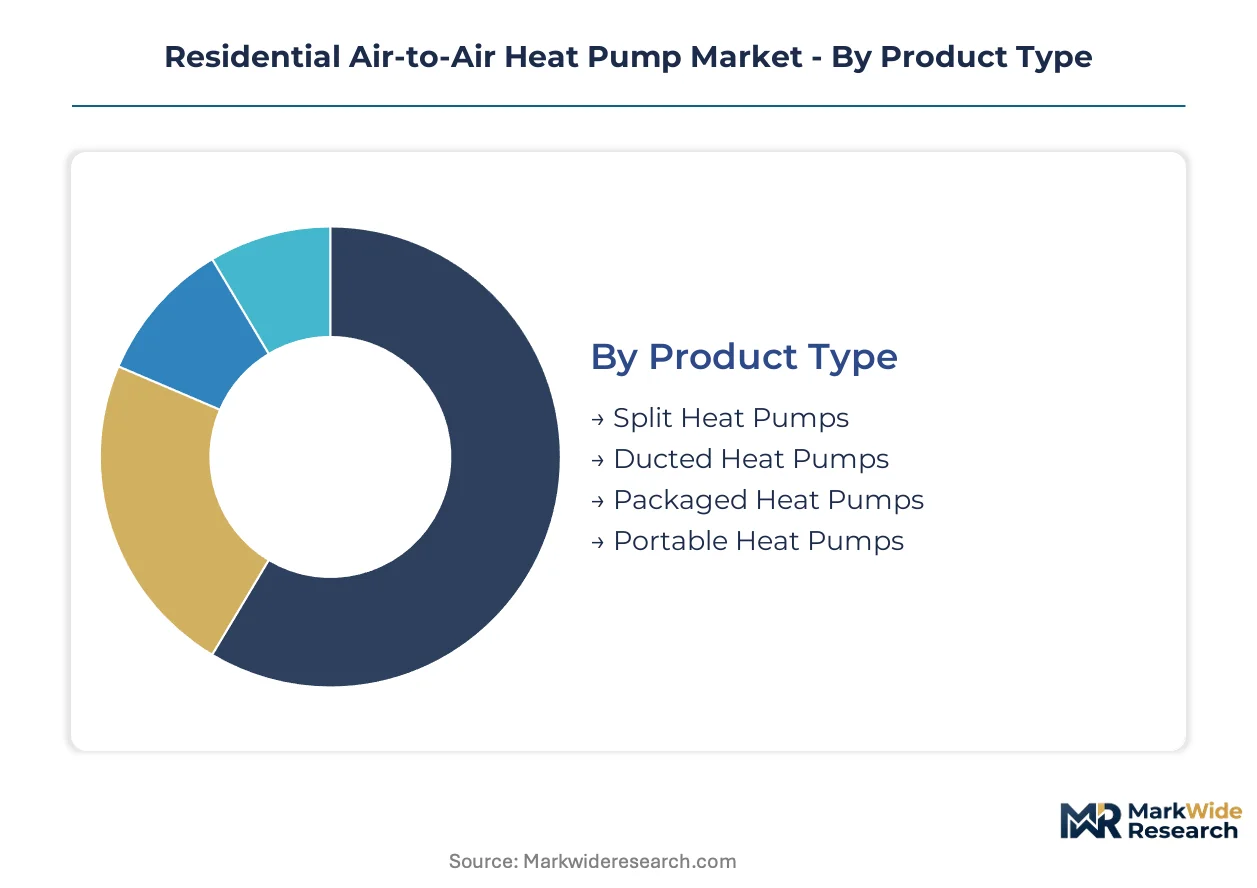
Residential air-to-air heat pump segmentation reveals distinct channel economics and specification requirements across product architectures, control technologies, mounting configurations, and buyer types. Channel specialization—HVAC contractors, national distributors, utility direct programs, and developer bulk procurement—shapes how each segment reaches end users.
Product Type:
Split heat pumps flow predominantly through HVAC contractor channels, while packaged and portable units concentrate in big-box retail and e-commerce.
- Split Heat Pumps:Outdoor condensing units paired with indoor air handlers dominate replacement demand in single-family detached housing. Germany and Japan drive specification toward A-rated efficiency tiers as building codes tighten.
- Ducted Heat Pumps:Central forced-air systems integrate with existing ductwork in North American housing stock. New construction in the United States favors these for whole-home conditioning with minimal indoor equipment visibility.
- Packaged Heat Pumps:Self-contained rooftop and ground-level units serve multi-family and light commercial applications where indoor mechanical space is constrained.
- Portable Heat Pumps:Mobile units with exhaust hoses address supplemental cooling demand in European rental markets and Japanese apartments with installation restrictions.
By volume, Split Heat Pumps leads. By growth pace, Ducted Heat Pumps is climbing the fastest as US new construction electrifies.
Technology:
Technology tiers stratify by margin structure: inverter platforms command premium pricing through part-load efficiency, while smart-enabled systems unlock recurring revenue via utility demand-response enrollment.
- Inverter:Variable-speed compressor drives modulate capacity to match thermal load, cutting energy consumption by 30-50% versus fixed-speed alternatives at part-load conditions. Cold-climate variants with flash-injection circuits extend operational range to minus twenty-five degrees Celsius, opening Nordic and northern Japanese markets.
- Non-Inverter:Fixed-speed compressors cycle on-off to maintain setpoint temperatures. These occupy economy positioning in Southeast Asian markets where first-cost sensitivity dominates and cooling loads outweigh heating demand.
- Variable Refrigerant Flow:Multi-zone systems with individual evaporator control serve multi-family retrofits and high-end single-family custom homes in dense European and East Asian cities.
- Smart Thermostat Enabled:Embedded communication modules enable utility-controlled load curtailment and automated efficiency optimization. Eversource, Enel, and Tokyo Electric enrollment programs steer procurement toward this segment.
Inverter technology captures the dominant revenue share. Smart Thermostat Enabled systems are expanding most quickly as utility rebate programs scale.
Installation Type:
Mounting configuration determines installer skill requirements and project timeline, with wall-mounted units accessible to generalist HVAC contractors while ceiling and rooftop applications demand specialized rigging and structural assessment.
- Wall-Mounted:High-wall indoor units dominate split system installations across European and Asian residential markets. Compact form factors suit retrofit applications in aging building stock.
- Ceiling-Mounted:Cassette and concealed duct units integrate with suspended ceilings in multi-family common areas and open-plan Japanese apartments.
- Floor-Mounted:Low-wall consoles serve spaces with limited upper wall area and cold-climate applications where heated air stratification must be minimized.
- Rooftop Units:Packaged systems on flat roofs serve multi-family and townhouse developments in the United States where ground-level equipment placement is restricted by zoning.
Wall-Mounted units lead by installed base. Ceiling-Mounted configurations are gaining share fastest in urban multi-family renovation.
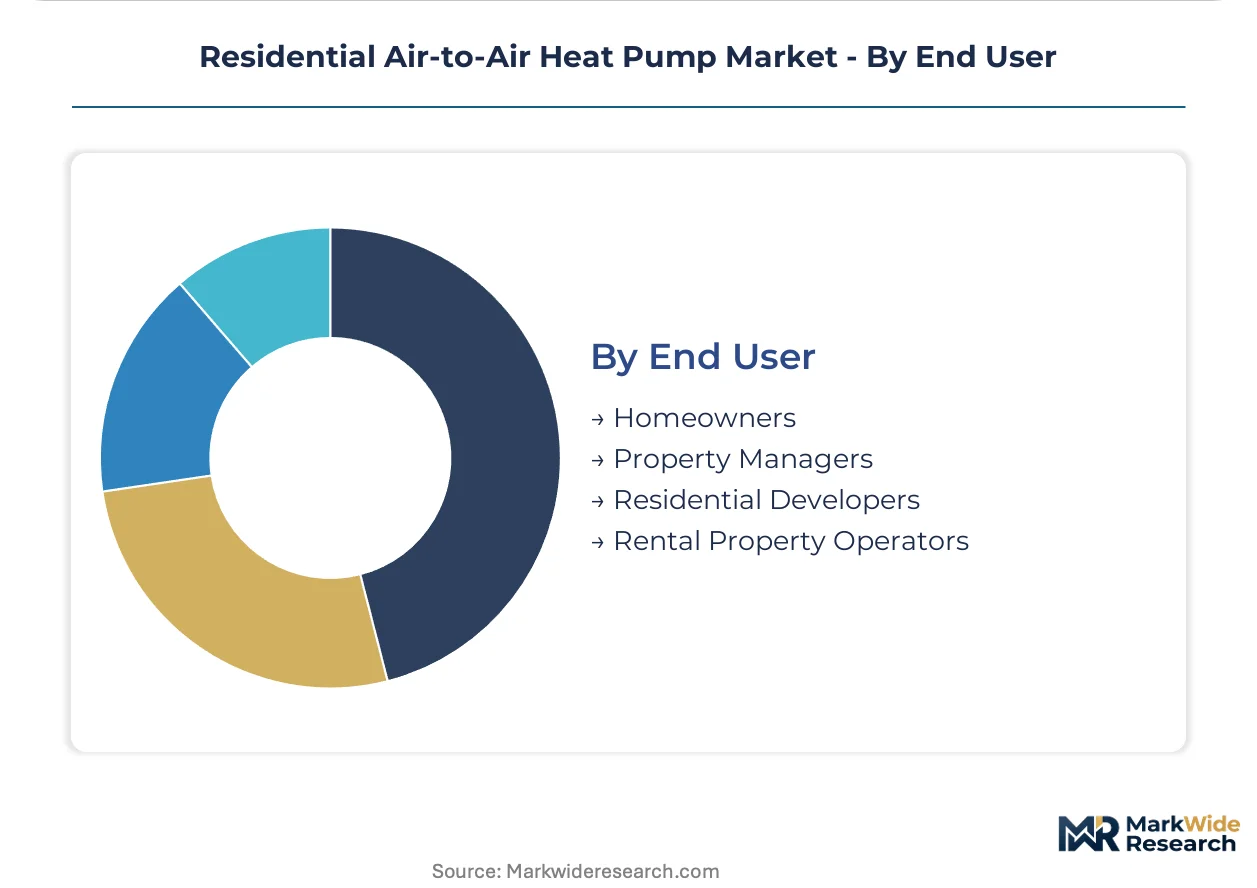
End User:
Buyer type determines procurement channel and specification priority: homeowners prioritize efficiency ratings and warranty terms, while developers optimize for first cost and installation speed.
- Homeowners:Individual purchasers in single-family detached and semi-detached housing drive replacement demand and efficiency-tier upgrades. IRA tax credits in the United States and BAFA subsidies in Germany shape their selection criteria.
- Property Managers:Multi-family portfolio operators prioritize reliability and service network coverage over efficiency premiums. Bulk procurement contracts with national distributors dominate their acquisition pattern.
- Residential Developers:New construction builders in Germany, Japan, and the United States specify systems to meet electrification mandates and green building certification requirements.
- Rental Property Operators:Individual landlords and small portfolio owners in France, Italy, and Poland favor portable and entry-level split systems where tenant turnover limits payback horizon for efficiency investments.
Homeowners represent the largest volume segment. Residential Developers are expanding most quickly as electrification mandates tighten in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor and heat exchanger manufacturing clusters in Japan, South Korea, and eastern China supply the dominant share of heat pump system components. Distribution networks in Germany, the United States, and Japan absorb the highest equipment volumes as electrification policies accelerate replacement cycles.
Germany
The Building Energy Act mandates renewable heating in new construction and major renovations, driving fossil fuel displacement in single-family stock. BAFA subsidies and KfW green financing compress payback periods for A-rated efficiency tiers. Installer capacity bottlenecks in Bavaria and North Rhine-Westphalia elongate project timelines despite strong equipment availability.
United States
IRA tax credits subsidize heat pump adoption while EPA SNAP refrigerant rules compress HFC deployment timelines. Cold-climate performance validation unlocks deployment in Minnesota, Wisconsin, and northern New England zones previously served by furnaces. Eversource and other utilities steer procurement toward demand-response-enabled systems through enrollment-linked rebates.
Japan
METI's Top Runner program sustains efficiency escalation that exports competitive pressure into export markets. Flash-injection compressor technology developed in Osaka-Nagoya industrial corridors extends operational range to minus twenty-five degrees Celsius. Tokyo Electric's demand-response enrollment programs concentrate volume in smart-enabled system channels.
China
Dual carbon goals and building efficiency standards accelerate electrification in new urban residential construction. Yangtze River Delta and Pearl River Delta manufacturing clusters supply rotary and scroll compressor platforms for domestic and export markets. MEE refrigerant regulations align product architecture with R-32 transition timelines.
France
MaPrimeRénov subsidies and RE2020 building codes tighten efficiency requirements in renovation and new build segments. Certified technician pools in Île-de-France and Auvergne-Rhône-Alpes lag equipment availability, creating installation backlogs. National distributors capture volume from traditional HVAC wholesaler channels as utility direct programs scale.
Residential Air-to-Air Heat Pump Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that leverage captive compressor production and multi-region distribution networks. The market structure tiers across premium cold-climate specialists, mid-market inverter platform providers, and economy-positioned volume players. Strategic moves center on refrigerant transition timing alignment and smart thermostat integration partnerships with utility demand-response programs.
Among Japanese diversified industrials, Daikin Industries, Mitsubishi Electric, and Panasonic Holdings exemplify the integrated manufacturer archetype. Daikin Industries anchors premium positioning through proprietary compressor technology. Mitsubishi Electric occupies the cold-climate performance tier. Panasonic Holdings represents price-aggressive inverter platform competition in Southeast Asian growth corridors. These three conglomerates collectively demonstrate how captive component production sustains margin control across divergent regional channel strategies.
| Leading Market Players |
|---|
| Daikin Industries |
| Mitsubishi Electric |
| Panasonic Holdings |
| Carrier Global |
| LG Electronics |
| Samsung Electronics |
| Trane Technologies |
| Fujitsu General |
| Bosch Thermotechnology |
| Others |
Pricing and Supply Chain Analysis
R-32 refrigerant substitution for legacy R-410A simultaneously redraws supplier geography toward Chinese and Japanese chemical producers and compresses margin structures across European and North American assembly operations. This chemistry transition forces equipment manufacturers to absorb certification retooling costs while competing for allocation from concentrated fluorochemical supply.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across the European channel, separating A-rated inverter systems with sub-750 GWP refrigerants from economy fixed-speed stock. Price differentiation hinges on METI Top Runner efficiency certification and cold-climate performance validation. Cost compression in the economy tier is intensifying because Southeast Asian manufacturers are flooding inverter platforms into price-sensitive markets. Residential developers in Germany and Japan exhibit the lowest price sensitivity due to mandate-driven procurement, while rental property operators in France and Poland prioritize first-cost minimization.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Rotterdam and Busan-Long Beach trade lanes expose inventory positioning risks for European and North American distributors awaiting compressor shipments. Manufacturing concentrates in Japan, South Korea, and China, with Osaka-Nagoya and Yangtze River Delta clusters feeding rotary and scroll compressor platforms. The supply chain rests on Chilean copper cathode and Chinese rare earth magnet feedstocks. Single-source vulnerability sits with Japanese inverter drive controller ASICs. Distribution runs through national HVAC wholesalers in Germany, direct utility programs in the United States, and integrated manufacturer channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installer capacity fragmentation across France, Italy, and Poland creates white-space opportunities for service-integrated equipment providers. Electrification mandates are splintering demand across performance tiers, refrigerant chemistries, and control architectures that favor specialized positioning over scale dominance.
For Market Incumbents: Secure captive compressor supply through backward integration into rotary and scroll manufacturing or long-term offtake agreements with Osaka-Nagoya and Yangtze River Delta producers. Defend against emerging cold-climate specialists by accelerating flash-injection circuit R&D and locking exclusive distribution with Germany's BAFA-certified installer networks. Channel control represents the critical lever as utility direct programs displace traditional HVAC wholesalers. For New Entrants and Emerging Players: Differentiate on R-290 hydrocarbon refrigerant platforms that bypass incumbent R-32 conversion timelines and qualify for enhanced French MaPrimeRénov subsidies. The most penetrable white space sits in multi-family VRF retrofits across aging European apartment stock where incumbent coverage remains thin. A service-integrated go-to-market model bundling installation, commissioning, and demand-response enrollment captures recurring revenue streams that pure equipment vendors cannot match. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed HVAC distributors in Germany and the United States that lack refrigerant transition technical capabilities. Long-term viability over the coming decade hinges on smart thermostat integration partnerships and utility demand-response program eligibility. The signal to watch is EPA SNAP refrigerant approval timelines against manufacturer inventory positioning, which will determine which assets face stranded product risk versus accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| R-290 Refrigerant Platform Development | Flammability-certified systems capture French MaPrimeRénov subsidies ahead of F-Gas phase-down deadlines. |
| Flash-Injection Circuit Scale-Up | Cold-climate validation unlocks Minnesota and Nordic markets previously served by fossil fuel furnaces. |
| Utility Demand-Response Partnership | Enrollment-linked rebates from Eversource and Tokyo Electric steer procurement toward smart-enabled channels. |
| Installer Network Acquisition | Certified technician pools in Bavaria and North Rhine-Westphalia reduce project timeline elongation risks. |
| Backward Integration into Compressor Manufacturing | Captive rotary and scroll production insulates margin control against Chinese and Korean supply allocation. |
Research Methodology
The analysis maps split, ducted, packaged, and portable heat pump architectures, each validated through HVAC contractor interviews, utility program administrators, national distributor procurement heads, and building developer specification teams. Primary fieldwork across Germany, the United States, Japan, and China combined with secondary validation from EPA SNAP filings, EU F-Gas Regulation implementation reports, METI efficiency disclosure databases, and BAFA subsidy disbursement records. Bottom-up equipment shipment tracking triangulates against top-down building stock electrification modeling.
Consistency checks against IEA heat pump deployment roadmaps and national building energy act implementation timelines validated projection outputs across the analysis window. Segmentation dimensions modeled include product architecture, compressor technology tier, installation configuration, and buyer type alongside climate zone heating degree-day intensity. CAGRs derive from equipment replacement cycle analysis against electrification mandate enforcement schedules. Forecast inputs incorporate refrigerant transition timelines and utility rebate program scaling assumptions without year-specific event pinning.
Material uncertainties — copper and rare earth price volatility, installer certification bottlenecks, grid infrastructure reinforcement delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and subsidy program continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.