
 Food Grade Calcium Hydroxide Market | 2026-2036
Food Grade Calcium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Calcium Hydroxide Market Foresight
The capital-intensity divergence between integrated quarry-to-dryer operators and toll-processing specialists is bifurcating competitive returns in food-grade calcium hydroxide. Carmeuse Group leverages captive limestone reserves across Belgium and the United States to sustain margin control through volatile energy cycles. Mississippi Lime Company anchors North American supply with deep vertical integration into high-calcium stone deposits in the Mississippi River corridor. Nordkalk Corporation competes through specialized marine logistics that extend reach into Baltic and North Sea food processors.
Food grade calcium hydroxide, also designated E526 under European food additive coding, consists of calcium oxide slaked with purified water to achieve minimum 90% Ca(OH)₂ content and controlled particle size distribution below 45 microns for uniform pH modulation. The compound functions primarily as an acidity regulator, firming agent, and processing aid in corn nixtamalization, sugar refining clarification, and drinking water softening. Powder formulations dominate volume shipments due to established handling infrastructure across beverage manufacturers and sugar refineries, though slurry formats capture expanding share among water utilities seeking automated dosing systems. pH regulation applications in craft brewing and seltzer production represent the fastest-growing demand pocket, while food preservation segments tied to pickled goods maintain mature, price-sensitive procurement patterns.
The FDA enforces 21 CFR 184.1405 purity specifications for direct food contact, while the EU's EFSA validates E526 safety dossiers through re-evaluation cycles that tighten heavy metal thresholds. BIS certification requirements in India and FSSAI additive approvals shape import eligibility for Asian market entrants. Stakeholders must monitor evolving CODEX Alimentarius harmonization talks, as divergent regional purity standards threaten to fragment formulation strategies and complicate cross-border manufacturing footprints.
Market Dynamics
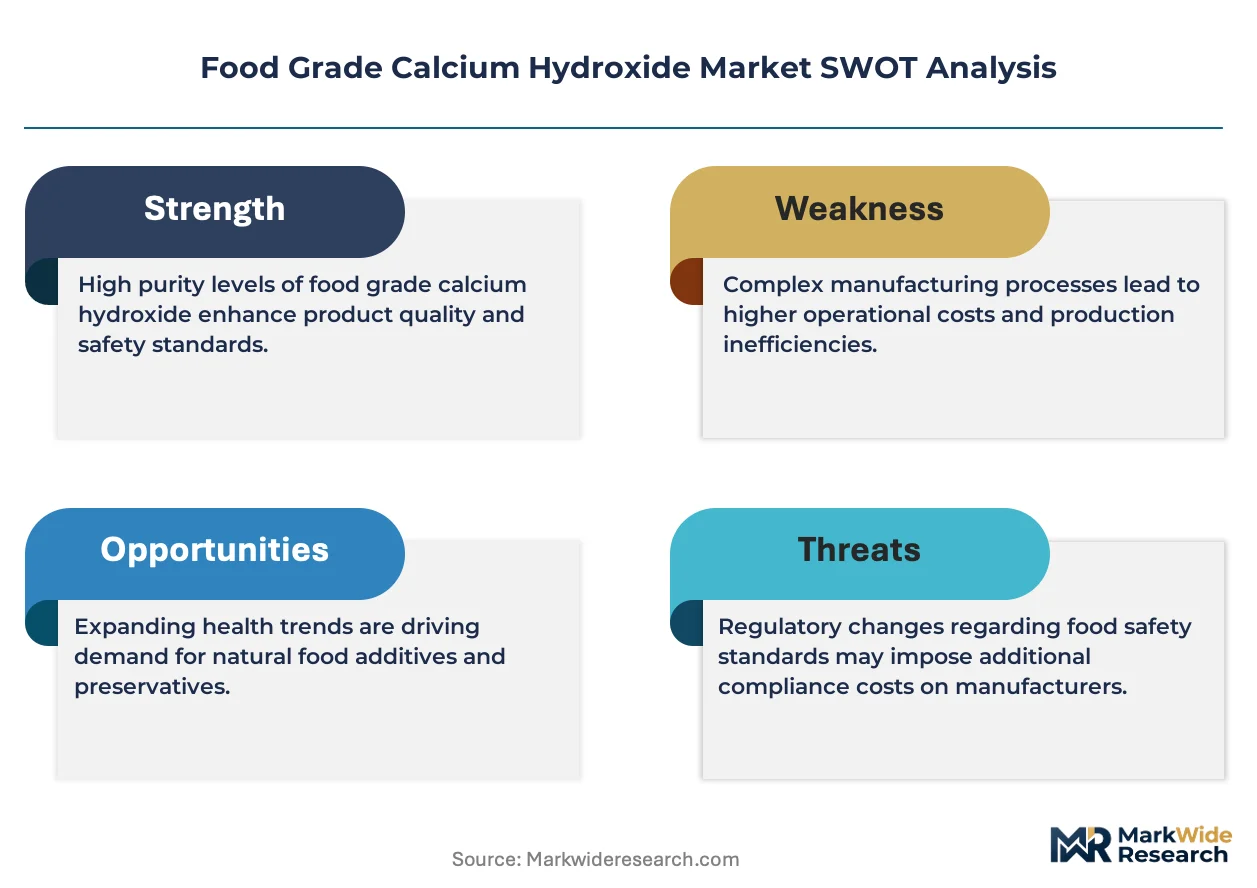
Integrated quarry operators with captive limestone reserves are compressing margins for toll-dependent processors, creating a bifurcated competitive landscape where energy volatility amplifies divergence in cost structures.
Growth Catalysts
- FDA Food Safety Modernization Act:Stringent purity mandates under 21 CFR 184.1405 are consolidating demand toward certified suppliers capable of consistent heavy-metal documentation.
- Craft beverage proliferation:Microbreweries and hard seltzer producers across the United States are adopting automated pH modulation systems that favor standardized slurry formats.
- Nixtamalization heritage preservation:Tortilla manufacturers in Mexico and Guatemala maintain traditional alkali-cooking methods that lock in food-grade calcium hydroxide as irreplaceable process input.
Market Restraints
- Energy cost volatility:Kiln-drying operations consume natural gas at intensity levels that expose non-integrated processors to margin compression during price spikes.
- Quarry reserve concentration:High-calcium limestone deposits cluster along the Mississippi River corridor and Belgian Ardennes, limiting viable new entrant locations.
- Precipitated calcium carbonate substitution:Sugar refiners in Southeast Asia increasingly trial PCC clarification agents that reduce alkali dependency.
Strategic Opportunities
- Water utility automation:Municipal treatment plants in Texas and Arizona are retrofitting legacy lime-slaking systems with pre-mixed slurry injection infrastructure.
- Clean-label preservation:Pickled vegetable processors seeking E526-coded alternatives to synthetic firming agents present reformulation partnership openings.
- CODEX harmonization tailwind:Pending Alimentarius alignment on heavy-metal thresholds would streamline multi-territory formulation for exporters.
Industry Challenges
- Certification timeline compression:EU EFSA re-evaluation cycles for E526 safety dossiers now demand accelerated toxicological data submission from legacy suppliers.
- Particle engineering expertise gap:Sub-45 micron distribution control for uniform pH modulation requires specialized milling talent scarce outside established chemical processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Calcium Hydroxide Market |
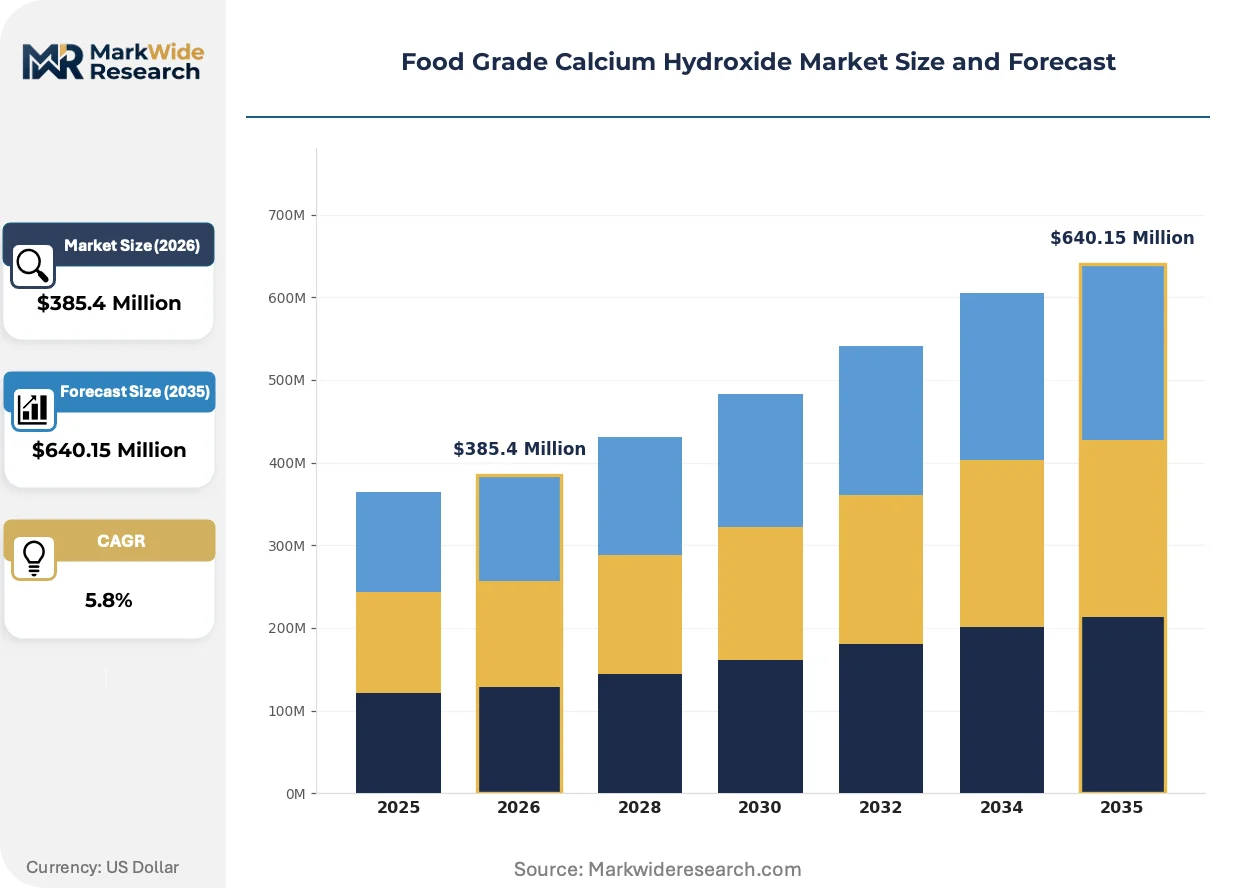
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Pellet, Slurry, Flake, Granules Application: Food Preservation, Water Treatment, Sugar Processing, Beverage Production, pH Regulation End User: Beverage Manufacturers, Food Processors, Water Utilities, Sugar Refineries, Confectionery Producers Packaging Type: Bulk Bags, Paper Bags, Plastic Drums, Jute Sacks, Fiber Drums |
| Companies Covered | Carmeuse Group, Nordkalk Corporation, Mississippi Lime Company, Omya AG, Sibelco, Graymont Limited, Lhoist Group, United States Lime & Minerals Inc., Minerals Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Calcium Hydroxide Market Shifts & Advancements
Pre-mixed slurry delivery systems are reconfiguring buyer-processor relationships, while regulatory tightening on heavy-metal thresholds and shifting procurement accountability are compressing supplier qualification cycles.
Automated slurry dosing equipment with integrated pH feedback loops is supplanting manual powder-handling stations at municipal water treatment facilities. Texas and Arizona utilities lead deployment, driven by labor cost containment targets and OSHA dust-exposure compliance pressures. The shift compresses procurement evaluation criteria toward logistics reliability and batch-to-batch consistency rather than unit chemistry alone.
EFSA's tightened heavy-metal re-evaluation protocols for E526 are forcing reformulation audits across European sugar refineries and beverage processors. Manufacturers must now document lead and arsenic thresholds below legacy CODEX reference levels to maintain additive authorization. Baltic and North Sea food clusters are responding fastest, leveraging marine-logistics proximity to certified Nordic quarries.
Beverage procurement teams now consolidate supplier rosters from fragmented regional sourcing toward single-source national contracts with integrated logistics. Craft brewing cooperatives in the Pacific Northwest and seltzer producers in the Northeast are driving this consolidation, trading price competition for supply security and audit simplification. The pattern concentrates volume toward vertically integrated quarry-to-slurry operators with multi-state distribution licenses.
Food Grade Calcium Hydroxide Market Segmentation
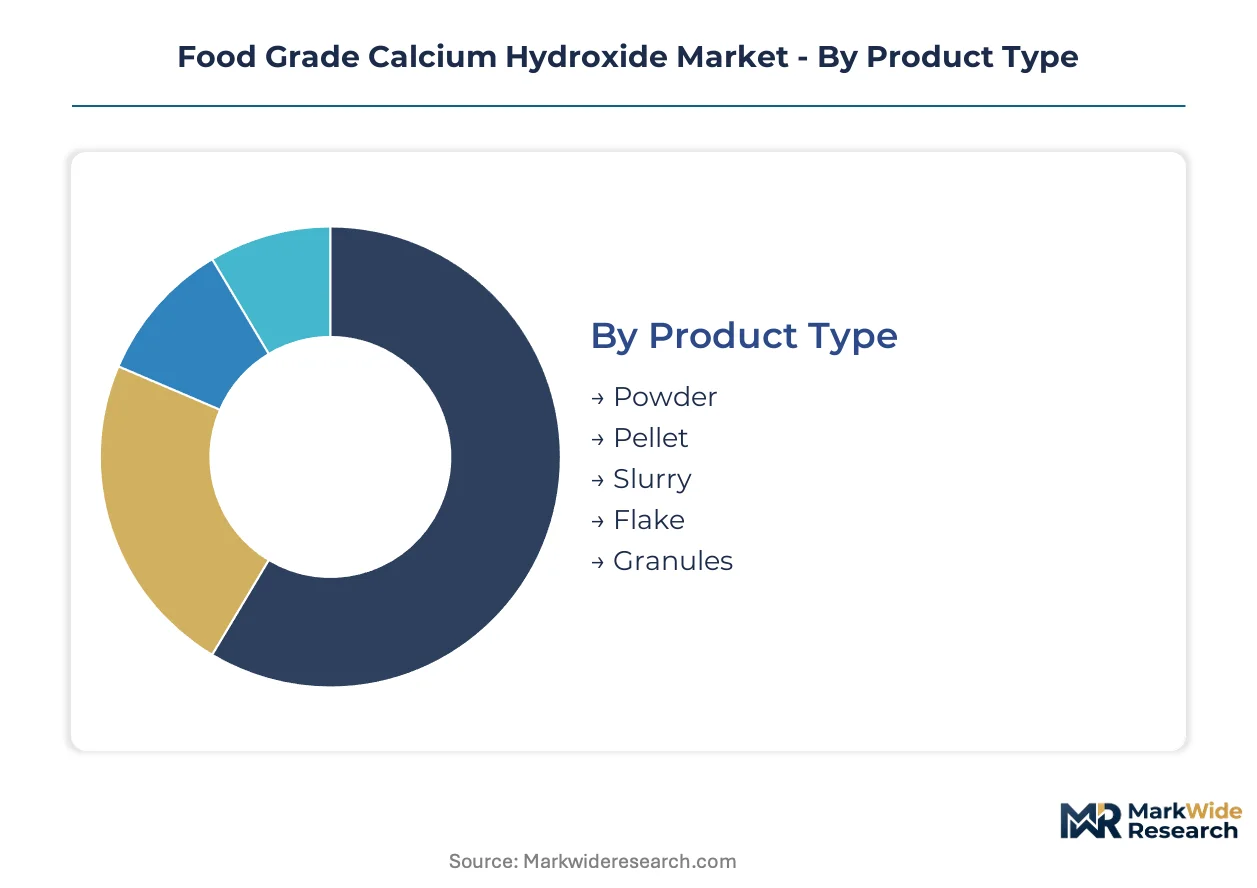
Food grade calcium hydroxide procurement patterns diverge sharply across product formats and end-use specifications, with automated dosing requirements and handling infrastructure dictating supplier selection criteria. Segmentation reveals where formulation flexibility, logistics reliability, and purity certification command pricing power.
Product Type:
Premium margin pools concentrate in slurry formats where technical service bundling and dosing system integration create switching costs for municipal and industrial buyers.
- Slurry:Pre-mixed aqueous suspensions with 20-40% solids content enable automated pH modulation without on-site slaking equipment. Texas and Arizona water utilities are retrofitting legacy systems for slurry injection, trading capital expenditure for operational labor savings and OSHA dust compliance.
- Powder:Dry formulations with sub-45 micron particle distribution dominate established handling infrastructure across beverage manufacturers and sugar refineries. Mexican tortilla producers maintain powder dependency for traditional nixtamalization methods that resist format substitution.
- Pellet:Compressed cylindrical forms reduce dust exposure during manual handling operations at smaller food processing facilities.
- Flake:Thin, irregular fragments dissolve rapidly in batch processing applications requiring quick pH adjustment.
- Granules:Coarse particulate structures suit slow-release applications in water treatment where gradual alkalinity elevation is preferred.
The dominant share belongs to Powder, while Slurry is closing the gap fastest as automation investments accelerate across municipal water infrastructure.
Application:
Volume concentration tracks regulatory enforcement intensity, with FDA purity mandates under 21 CFR 184.1405 consolidating procurement toward certified suppliers in direct food contact segments.
- pH Regulation:Acidity modulation in craft brewing and hard seltzer production demands precise, batch-to-batch consistency. United States microbreweries are consolidating supplier rosters toward single-source national contracts with integrated logistics and audit documentation.
- Water Treatment:Drinking water softening and alkalinity adjustment consume substantial tonnage through municipal procurement channels. Texas utilities lead slurry system deployment driven by labor cost containment targets.
- Food Preservation:Pickled vegetable processing relies on E526-coded firming agents as clean-label alternatives to synthetic additives. Procurement patterns here remain mature and price-sensitive with limited format innovation.
- Sugar Processing:Clarification and juice purification operations in refineries face substitution pressure from precipitated calcium carbonate trials in Southeast Asia.
- Beverage Production:Carbonated and non-carbonated drink formulation uses calcium hydroxide for mineral content adjustment and stability control.
pH Regulation captures the steepest expansion trajectory as craft beverage proliferation outpaces traditional industrial applications, while Water Treatment maintains the largest absolute volume position.
End User:
Customer type determines service intensity requirements, with technical support and certification documentation commanding premium positioning in regulated food contact segments.
- Water Utilities:Municipal treatment plants prioritize logistics reliability and batch consistency over unit chemistry alone. Automated dosing retrofits in Texas and Arizona compress evaluation criteria toward slurry specialists with multi-state distribution licenses.
- Beverage Manufacturers:Craft brewing cooperatives in the Pacific Northwest and seltzer producers in the Northeast are consolidating fragmented regional sourcing toward integrated quarry-to-slurry operators.
- Food Processors:Tortilla manufacturers in Mexico and Guatemala lock in traditional nixtamalization methods that specify food-grade calcium hydroxide as irreplaceable process input.
- Sugar Refineries:European processors face EFSA heavy-metal re-evaluation protocols that demand accelerated toxicological data submission from legacy suppliers.
- Confectionery Producers:Candy and sweet manufacturing uses calcium hydroxide for texture modification and pH control in specific product categories.
Water Utilities command the largest procurement volumes, though Beverage Manufacturers are driving the fastest contract consolidation toward national supplier arrangements.
Packaging Type:
Handling economics and contamination risk shape packaging selection, with bulk formats capturing volume flows and smaller units serving specialty applications.
- Bulk Bags:Flexible intermediate bulk containers dominate high-volume shipments to water utilities and sugar refineries with pneumatic handling systems.
- Paper Bags:Multi-wall kraft constructions serve beverage manufacturers and food processors requiring moderate quantities with established warehouse handling.
- Plastic Drums:Rigid containment suits slurry formats and moisture-sensitive powder grades in humid climates.
- Jute Sacks:Natural fiber packaging addresses sustainability preferences in select European and Asian procurement specifications.
- Fiber Drums:Cylindrical fiberboard containers protect against compression damage in confectionery and specialty food applications.
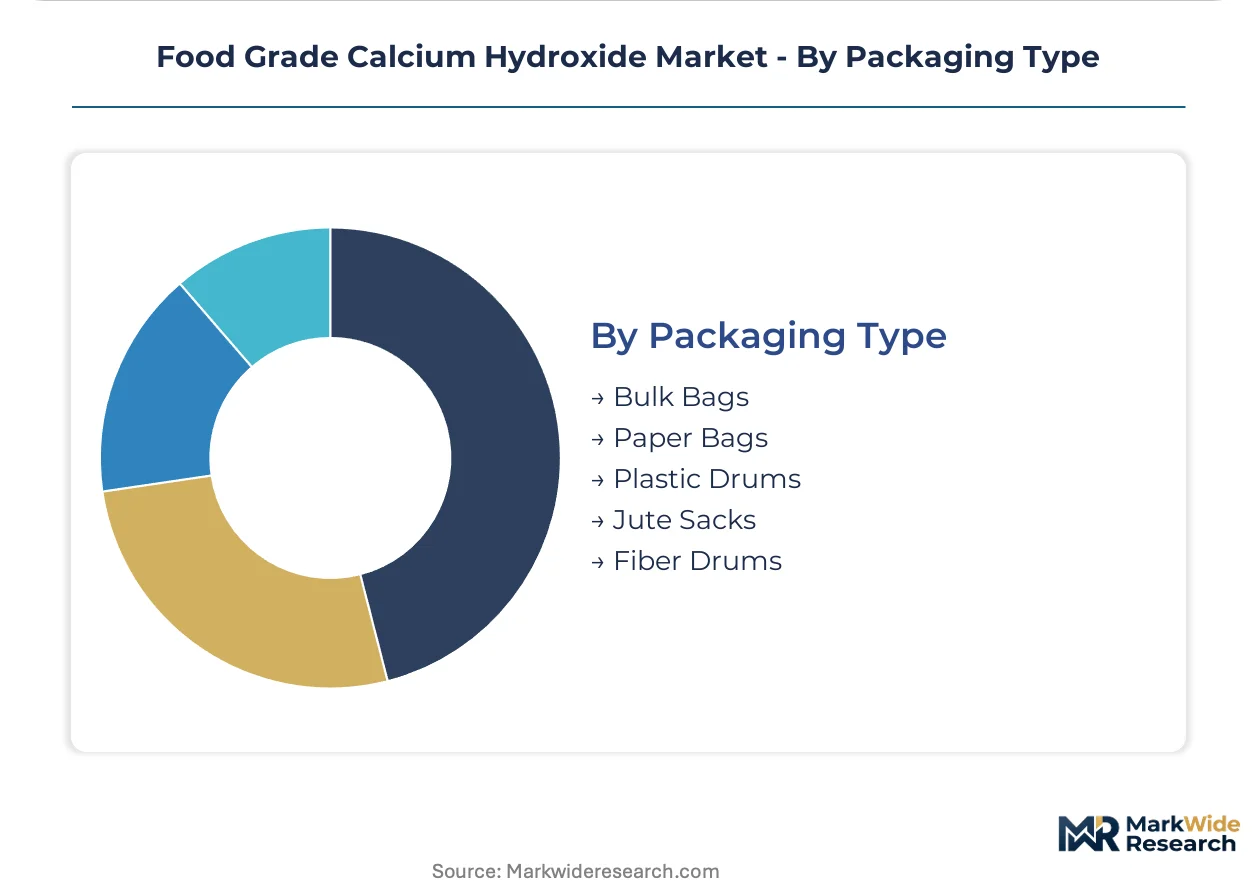
Bulk Bags hold the dominant procurement share, while Plastic Drums are gaining fastest as slurry format adoption expands across automated dosing installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in food-grade calcium hydroxide procurement varies sharply by end-use maturity. Water utilities in Texas and Arizona prioritize logistics reliability over unit cost, while Mexican tortilla producers negotiate aggressively on powder formulations where traditional nixtamalization methods lock in specification requirements.
United States
Craft beverage proliferation across the Pacific Northwest and Northeast drives automated pH modulation system adoption. FDA enforcement of 21 CFR 184.1405 purity specifications consolidates procurement toward certified suppliers with documented heavy-metal compliance. Texas municipal water utilities lead slurry format retrofitting, trading capital expenditure for operational labor savings.
Mexico
Tortilla manufacturers in Mexico City and Guadalajara maintain traditional alkali-cooking methods that specify food-grade calcium hydroxide as irreplaceable process input. COFEPRIS alignment with CODEX Alimentarius standards shapes import eligibility for regional suppliers. The Bajío Region hosts concentrated nixtamalization heritage operations resistant to format substitution.
Belgium
Captive limestone reserves in the Belgian Ardennes sustain margin control for integrated quarry-to-dryer operators through volatile energy cycles. EFSA re-evaluation protocols for E526 safety dossiers demand accelerated toxicological data submission from legacy suppliers. Antwerp marine logistics terminals extend distribution reach into Baltic and North Sea food processing clusters.
India
Sugar refineries in Maharashtra and Uttar Pradesh face substitution pressure from precipitated calcium carbonate clarification trials. BIS certification requirements and FSSAI additive approvals shape import eligibility for Asian market entrants. Gujarat chemical processing hubs develop specialized milling capacity for sub-45 micron particle distribution control.
Germany
Beverage procurement teams in Bavaria and North Rhine-Westphalia consolidate fragmented regional sourcing toward single-source national contracts. EU Green Deal carbon intensity metrics reshape kiln-drying operation economics for limestone processors. Hamburg port infrastructure supports specialized marine logistics for Nordic quarry supply chains.
Food Grade Calcium Hydroxide Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in food-grade calcium hydroxide supply. Integrated quarry operators with captive limestone reserves compress margins for toll-dependent processors, creating a bifurcated structure where energy volatility amplifies divergence in cost structures. Three archetypes dominate: vertically integrated quarry-to-slurry specialists, toll-processing regional distributors, and marine-logistics-integrated Nordic suppliers. Competitive moves concentrate on backward integration into high-calcium stone deposits and automated dosing system partnerships with municipal utilities.
Among European integrated operators, Carmeuse Group and Lhoist Group occupy positions exemplifying captive reserve strategies, while Nordkalk Corporation represents the marine-logistics-integrated archetype extending reach into Baltic and North Sea markets. Mississippi Lime Company anchors North American supply with upstream control over Mississippi River corridor deposits. These three names illustrate how geographic concentration of high-calcium limestone reserves limits viable new entrant locations and reinforces incumbent positioning.
| Leading Market Players |
|---|
| Carmeuse Group |
| Nordkalk Corporation |
| Mississippi Lime Company |
| Omya AG |
| Sibelco |
| Graymont Limited |
| Lhoist Group |
| United States Lime & Minerals Inc. |
| Minerals Technologies Inc. |
| Others |
Supply & Pricing Matrix
Precipitated calcium carbonate substitution trials in Southeast Asian sugar refineries are simultaneously redrawing raw material sourcing maps and compressing alkali-grade pricing premiums as buyers evaluate lower-cost clarification alternatives. This substitution dynamic forces traditional calcium hydroxide suppliers to defend value propositions through certification bundling and technical service differentiation rather than commodity chemistry alone.
Pricing Analysis
Technical service contracts and slurry system maintenance agreements generate the majority of lifetime customer value beyond initial chemical sales. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certification levels separates premium positioning in FDA-compliant segments from price-sensitive water utility procurement. Cost compression in standard-grade powder formulations is intensifying because toll-dependent processors lack captive limestone reserves to buffer energy volatility. Mexican tortilla manufacturers exhibit the highest price sensitivity due to traditional nixtamalization methods that resist format substitution, while Texas municipal utilities prioritize logistics reliability over unit cost.
Supply Chain Analysis
Just-in-time slurry delivery preferences among automated municipal water facilities are displacing strategic stockpile traditions that once dominated powder-based procurement. Geographic supply concentration centers on Belgium, the United States, and Finland where high-calcium limestone deposits cluster. Production draws from captive quarry reserves, natural gas kiln operations, and specialized marine logistics networks. Single-source vulnerability runs through Mississippi River corridor deposits that anchor North American supply. Distribution runs through integrated quarry-to-slurry operators with multi-state licensing rather than fragmented regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as craft beverage proliferation and water utility automation create specialized service niches that reward technical differentiation over scale economics.
For Market Incumbents: Fortify margin control through backward integration into high-calcium stone deposits along the Mississippi River corridor and Belgian Ardennes. Expand slurry-format capacity in Texas and Arizona to capture municipal automation retrofits. Defend against precipitated calcium carbonate substitution by embedding technical service teams within Southeast Asian sugar refinery operations. For New Entrants and Emerging Players: FDA Food Safety Modernization Act certification fast-track programs offer entry pathways into craft brewing cooperatives consolidating toward single-source national contracts. Target underpenetrated pickled vegetable processors seeking E526-coded clean-label alternatives in the Pacific Northwest. Lead with automated dosing system partnerships rather than commodity chemistry to establish switching costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed toll-processing specialists lacking captive limestone reserves and exposed to energy cost volatility. Five-to-ten year viability favors integrated quarry-to-slurry operators with marine logistics capabilities extending into Baltic and North Sea markets. Watch for EFSA E526 re-evaluation outcomes as inflection indicators that would accelerate consolidation toward certified suppliers with documented heavy-metal compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Reserves | Captive limestone supply insulates Carmeuse and Mississippi Lime from natural gas price spikes. |
| Slurry System Automation Partnerships | Pre-mixed delivery contracts with Texas utilities create multi-year revenue visibility and switching costs. |
| FDA Certification Fast-Track Investment | Expedited 21 CFR 184.1405 compliance opens craft beverage procurement consolidation opportunities. |
| Marine Logistics Infrastructure Expansion | Antwerp and Hamburg terminals extend Nordic quarry reach into Baltic sugar refinery clusters. |
| EFSA Re-Evaluation Dossier Preparation | Accelerated toxicological data submission preserves E526 authorization across European food processors. |
Research Methodology
A standing panel of quarry operations managers, municipal water utility procurement directors, beverage manufacturing technical leads, and sugar refinery process engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA 21 CFR filings, EFSA E526 safety dossiers, customs and trade flow data, and SEC 10-K disclosures from listed chemical processors. Bottom-up volume modeling across product formats and applications triangulated against top-down macroeconomic indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product format, application end-use, certification grade tier, and regional production hub. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and substitution technology penetration. Industry-specific forecast inputs incorporated kiln energy cost assumptions and automated dosing system deployment rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of 21 CFR 184.1405 or accelerated EFSA re-evaluation timelines would require recalibration. Forecasts reflect documented assumptions regarding limestone reserve depletion rates and natural gas price normalization. Revision becomes warranted when precipitated calcium carbonate substitution crosses threshold adoption rates in Southeast Asian clarification applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market