
 Potassium Lactate Market | 2026-2036
Potassium Lactate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Lactate Market Analysis
Food ingredient distribution channels are rewriting procurement patterns for potassium lactate buyers across North America and Europe. Cargill Incorporated leverages its integrated corn-processing infrastructure to anchor supply security for downstream lactate derivatives. Jungbunzlauer Suisse AG specializes in fermentation-based organic acid production, sustaining premium positioning in pharmaceutical-grade segments. Corbion N.V. dominates microbial fermentation technology for lactic acid, extending its reach into high-purity potassium salt derivatives.
Potassium lactate is the potassium salt of lactic acid, typically produced through neutralization of lactic acid with potassium carbonate or hydroxide, yielding a clear, odorless liquid with a pH range of 5.0 to 9.0 and minimum assay specifications of 60 percent solution weight by volume. The compound functions primarily as a humectant, pH regulator, and antimicrobial agent in food systems, pharmaceutical formulations, and industrial applications where sodium reduction or enhanced moisture retention is required. Food Grade potassium lactate occupies the largest volume share as meat processors substitute sodium lactate to achieve clean-label sodium reduction while maintaining shelf stability. Pharmaceutical Grade commands the strongest margin pool due to stringent USP and EP monograph compliance requirements that limit qualified suppliers. Industrial Grade applications in chemical intermediates and de-icing formulations represent a mature, price-sensitive segment with slower growth velocity.
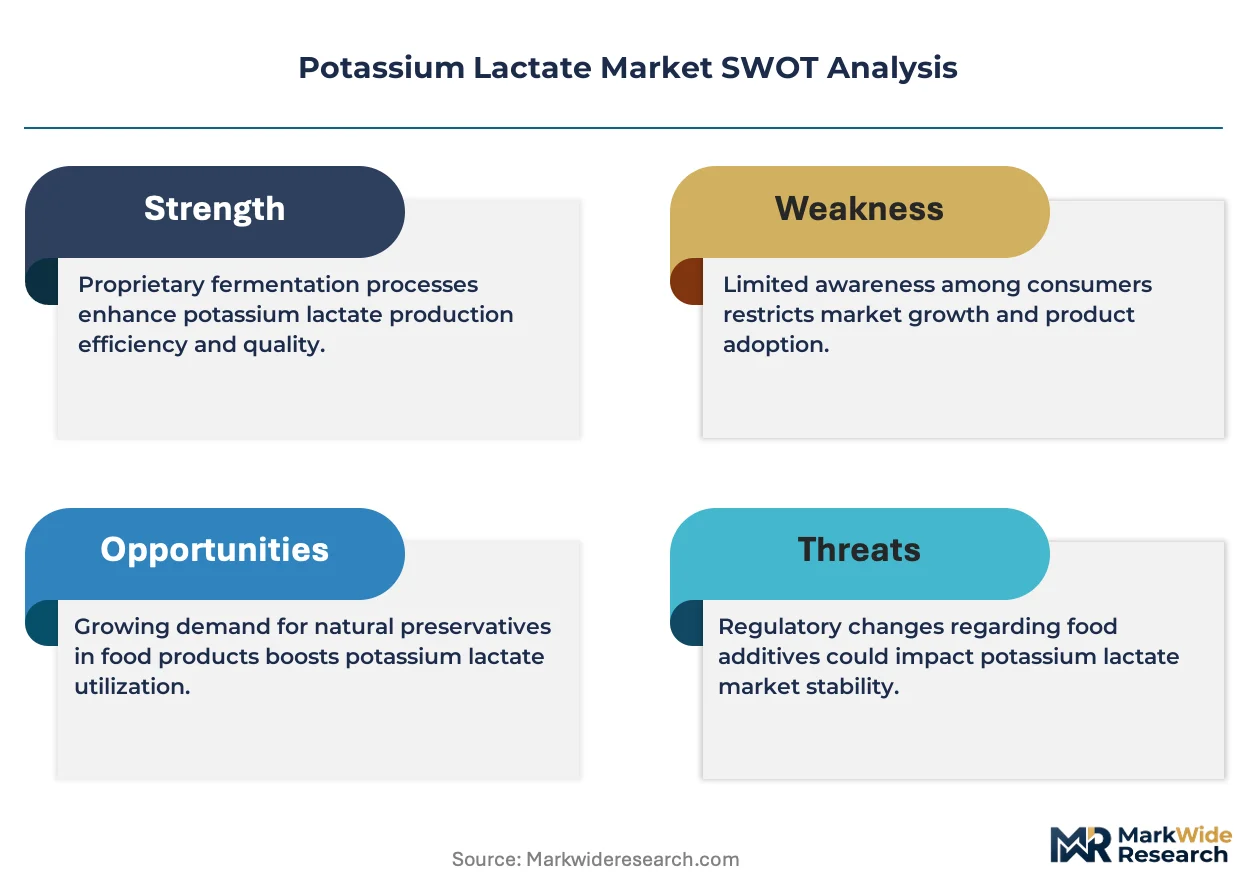
FDA food additive regulations under 21 CFR 184.1639 govern potassium lactate usage levels and labeling requirements in processed foods, while EPA guidelines influence industrial discharge parameters for fermentation-based manufacturing facilities. REACH registration obligations in Europe impose comprehensive toxicological and environmental fate data requirements on importers and manufacturers above one tonne annual volume thresholds. ISO 22000 and FSSC 22000 certifications have become baseline qualifiers for supplier qualification by multinational food manufacturers. Stakeholders must monitor evolving sodium reduction mandates from WHO member states and assess captive fermentation investments versus merchant supply reliance.
Market Dynamics
Meat processors' systematic sodium reduction mandates are compressing demand for traditional salt-based preservatives while elevating potassium lactate's functional role in clean-label formulations. This structural shift is redrawing supplier qualification criteria and fermentation capacity investment priorities across the value chain.
Growth Catalysts
- WHO sodium reduction targets:Member state mandates for processed meat sodium limits are accelerating potassium lactate substitution rates in cured and ready-to-eat protein segments.
- Fermentation technology maturation:Continuous bioprocessing advances are lowering lactic acid production costs and improving potassium salt conversion yields.
- China:Centralized feedstock advantages around corn processing hubs are concentrating derivative manufacturing capacity and export supply.
Market Restraints
- Corn price volatility:Feedstock cost fluctuations directly compress margin structures for fermentation-based producers without long-term supply contracts.
- REACH registration burdens:ECHA data requirements for toxicological dossiers create fixed compliance costs that disproportionately burden sub-tonnage importers.
- Potassium chloride substitution:Lower-cost mineral salts retain share in non-label-sensitive industrial applications where antimicrobial performance thresholds are relaxed.
Strategic Opportunities
- Plant-based protein:Emerging alternative meat formulations require pH regulation and moisture retention without sodium-based additives.
- EU Green Deal bioeconomy incentives:Fermentation-derived organic acids qualify for circular economy funding streams and carbon accounting advantages.
- Direct-to-processor digital platforms:Specialty ingredient distributors are building proprietary procurement portals that bypass traditional chemical merchant networks.
Industry Challenges
- Fermentation engineering talent scarcity:Industrial microbiology and bioprocess optimization expertise concentrates at established lactic acid producers, constraining new entrant scale-up velocity.
- Multi-jurisdiction certification timelines:Simultaneous USP, EP, and FSSC 22000 qualification cycles extend supplier onboarding to 18-24 months for pharmaceutical-grade contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Lactate Market |
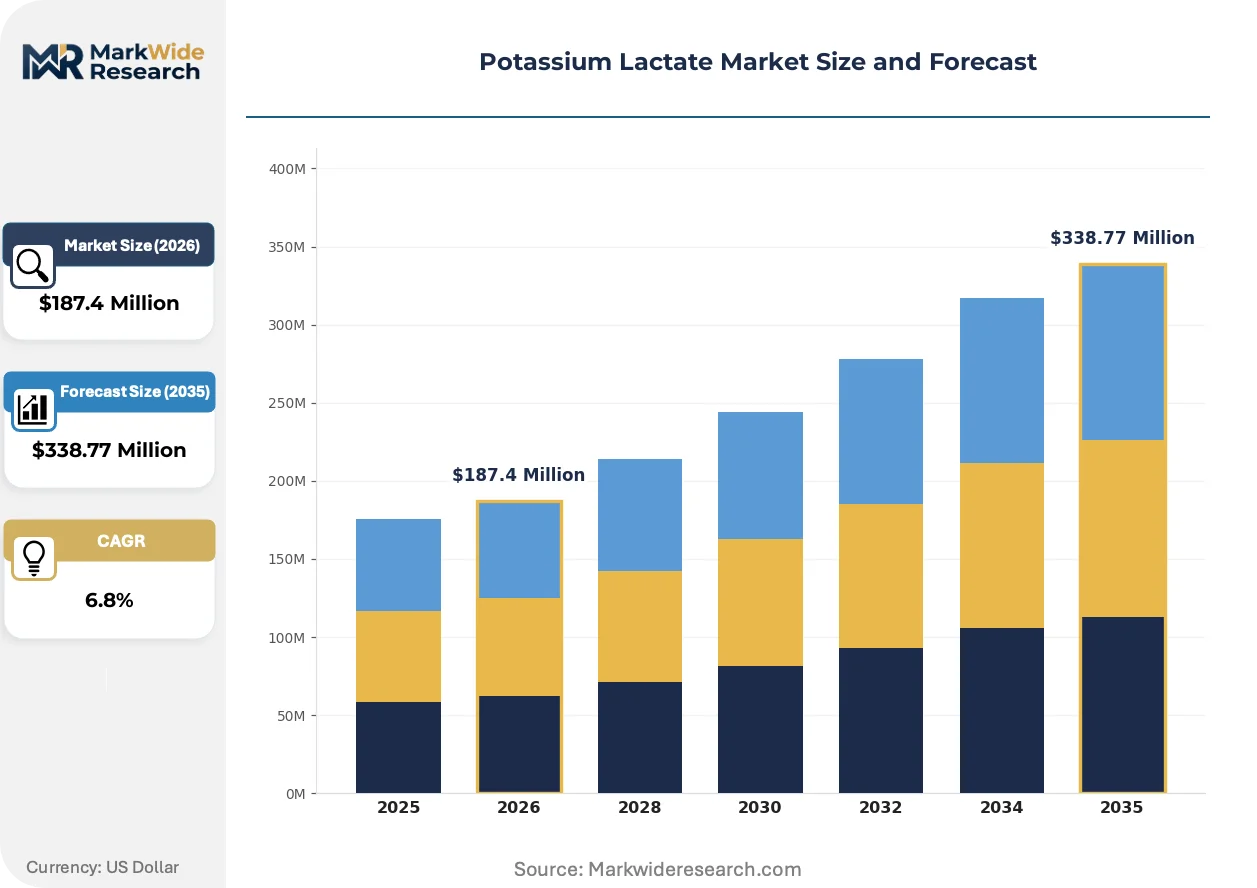
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Laboratory Grade Application: Food Preservation, Nutritional Supplement, Drug Formulation, Chemical Industry End User: Food Manufacturers, Pharmaceutical Companies, Research Institutions, Beverage Industry Packaging Type: Bags, Drums, Bottles, Bulk Containers |
| Companies Covered | Chongqing Bofei Biochemical Products, Cargill Incorporated, Jungbunzlauer Suisse AG, Tate & Lyle, ADM, Henan Jindan Lactic Acid Technology Co., Ltd., Corbion N.V., Lab M Limited, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Lactate Market Emerging Trajectories
Bioprocessing efficiency gains and regulatory chemistry restrictions are converging to reposition potassium lactate from commodity preservative to formulated functional ingredient. These forces are reshaping R&D allocation and customer technical service investment across the supply base.
Continuous fermentation systems with real-time metabolite monitoring are migrating from pilot-scale demonstrations to commercial lactic acid facilities. Mid-tier producers in Germany and the Netherlands are retrofitting batch plants to capture yield improvements and reduce energy intensity per tonne. This technology migration is compressing the cost gap between established suppliers and regional challengers in Eastern Europe.
REACH authorization requirements for substances of very high concern are tightening purity documentation obligations for preservative-grade imports into the European Economic Area. ECHA's 2024 updated guidance on lactic acid derivative classifications is forcing non-EU manufacturers to expand analytical testing capabilities. Food-grade potassium lactate shipments to Rotterdam and Hamburg are now routinely accompanied by third-party assay certificates exceeding baseline customs requirements.
Large meatpackers are consolidating qualified supplier lists from twelve-plus vendors to three or four strategic partners with integrated technical support capabilities. This buyer concentration is displacing spot-market purchasing for sodium reduction formulations in the United States and Brazil. Technical collaboration agreements now specify joint shelf-life testing protocols rather than transactional certificate-of-analysis exchanges.
Potassium Lactate Market Segmentation
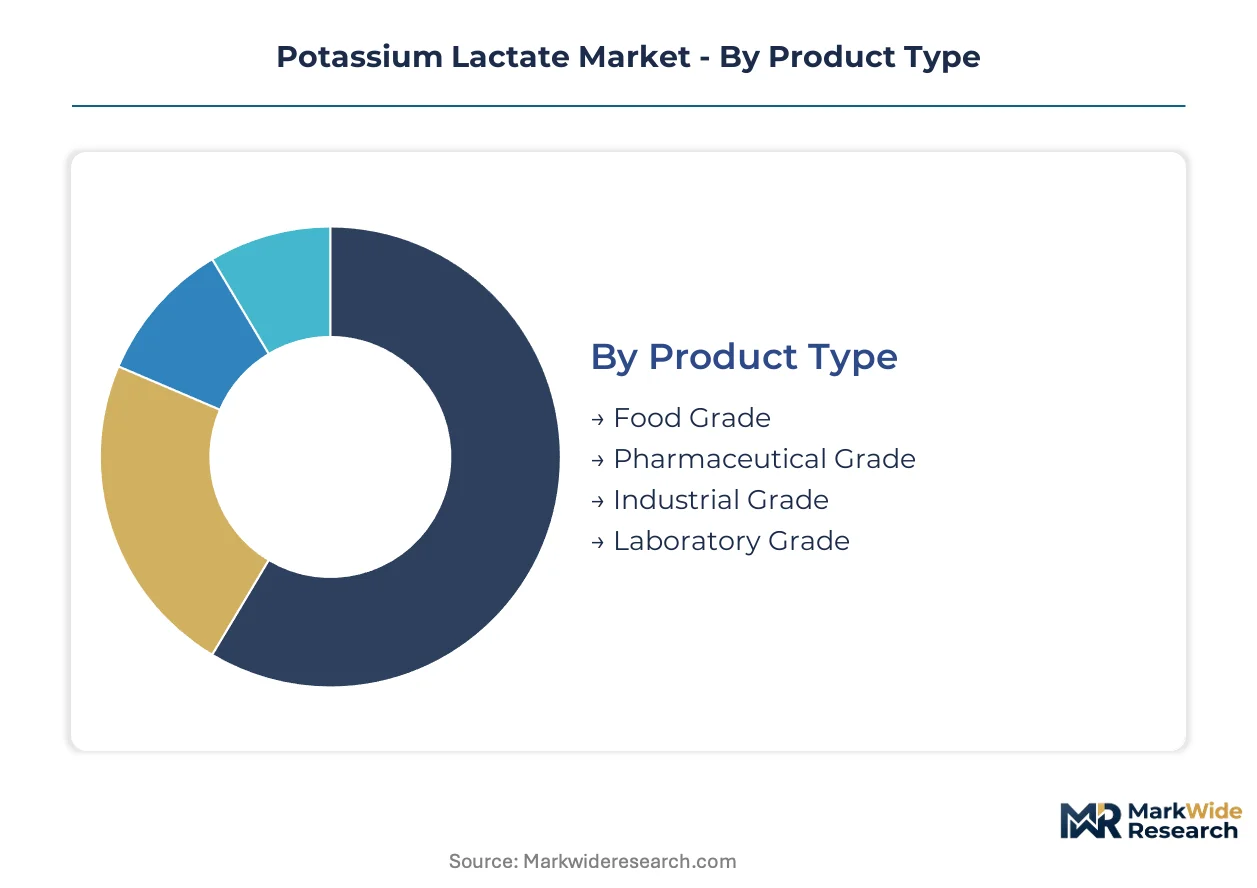
Segmentation in the potassium lactate market determines supplier qualification pathways and technical service intensity. Each category carries distinct regulatory burdens and margin structures that reshape procurement relationships.
Product Type:
After-sales service intensity escalates dramatically from industrial grades through pharmaceutical certifications, with technical support hours per tonne sold varying by an order of magnitude across tiers.
- Food Grade:Minimum 60% solution concentration with pH 5.0-9.0 specification dominates meat processor procurement. Demand concentrates in Germany and China where centralized slaughtering operations require sodium reduction compliance under WHO guidelines.
- Pharmaceutical Grade:USP and EP monograph compliance mandates analytical documentation exceeding food-grade thresholds. USP and EP qualification cycles extend supplier onboarding to 18-24 months, creating captive relationships with qualified fermentation houses.
- Industrial Grade:Chemical intermediate applications in de-icing and metal treatment tolerate broader assay ranges.
- Laboratory Grade:Research-scale volumes with certificate-of-analysis requirements for analytical method validation.
By volume, Food Grade leads. By growth pace, Pharmaceutical Grade is expanding most quickly.
Application:
Application selection drives raw material sourcing strategy, with fermentation feedstock specifications tightening as products move from chemical intermediates toward direct human consumption.
- Food Preservation:Antimicrobial and humectant functions in cured meats and ready-to-eat proteins. Meatpackers in Brazil and the United States are consolidating supplier lists from twelve vendors to four strategic partners with joint shelf-life testing protocols.
- Drug Formulation:Buffer and pH regulation in parenteral and oral dosage forms. FDA 21 CFR 184.1639 and USP monograph compliance limits qualified suppliers to fermentation specialists with documented batch records.
- Nutritional Supplement:Electrolyte replacement and mineral fortification in sports nutrition and clinical formulas.
- Chemical Industry:Intermediate for esterification and polymerization reactions with relaxed purity thresholds.
Food Preservation commands the volume base. Drug Formulation claims the steepest expansion trajectory.
End User:
End user type determines contract structure, with food manufacturers demanding just-in-time delivery while research institutions tolerate extended lead times for certified reference materials.
- Food Manufacturers:Integrated meat and poultry processors with sodium reduction mandates. Technical collaboration agreements now specify joint shelf-life testing rather than transactional certificate exchanges.
- Pharmaceutical Companies:Formulation developers requiring USP-grade materials with full supply chain documentation. Multi-jurisdiction qualification cycles concentrate procurement among established European and North American fermentation houses.
- Beverage Industry:Sports drink and functional beverage formulators seeking electrolyte balance without sodium load.
- Research Institutions:Method development and analytical validation with small-batch, high-documentation requirements.
Food Manufacturers anchor volume demand. Pharmaceutical Companies are gaining share fastest.
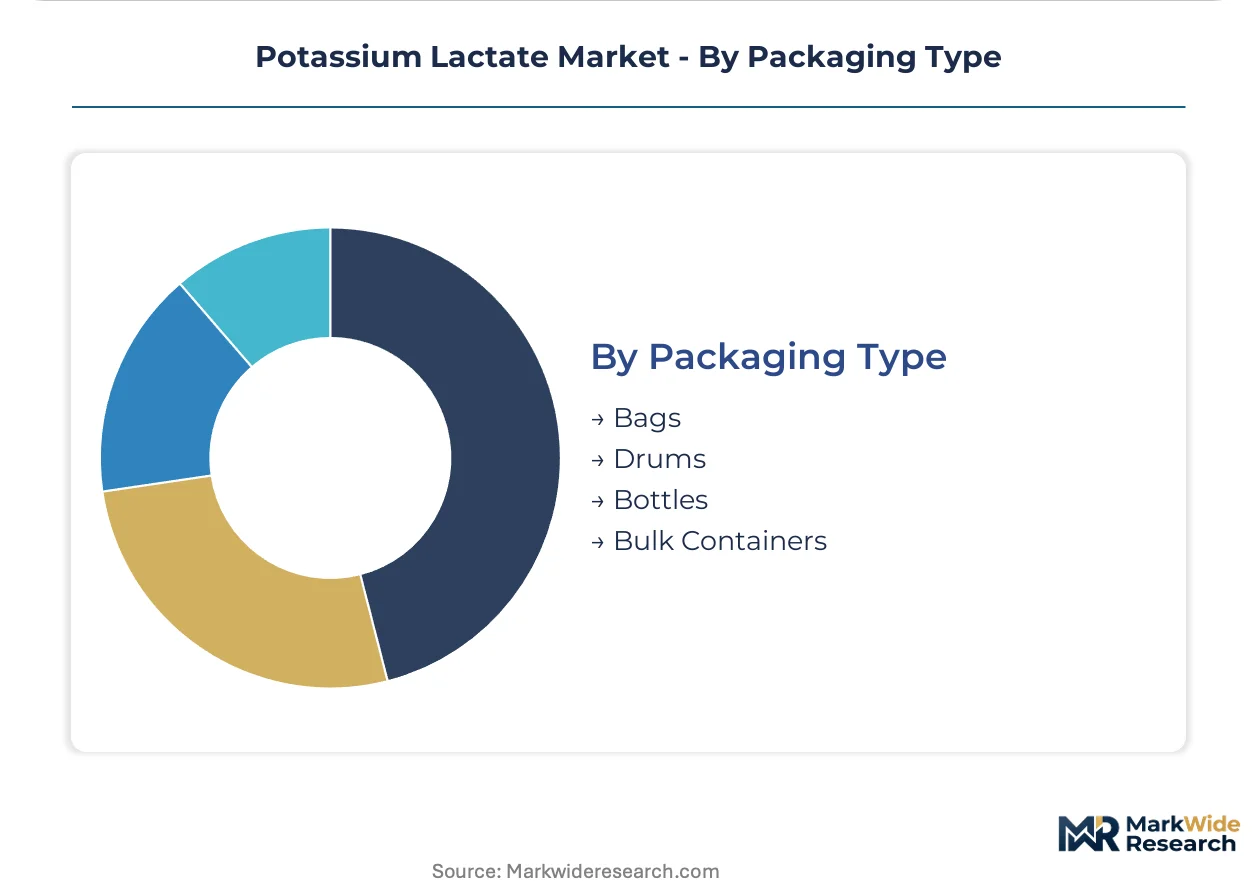
Packaging Type:
Packaging configuration aligns with end-user scale and handling infrastructure, with bulk investments concentrating at integrated processors while distributed research users require unitized shipments.
- Bulk Containers:Tanker and tote deliveries for high-volume meat processors with on-site storage. Direct-to-processor digital platforms are displacing traditional chemical merchant networks for these shipments.
- Drums:Standard 200-liter units for mid-scale pharmaceutical and food compounders.
- Bags:Flexible intermediate bulk containers for powder-grade requirements in nutritional manufacturing.
- Bottles:Laboratory and pilot-scale volumes with tamper-evident closures for analytical use.
Bulk Containers lead by tonnage moved. Bottles are climbing the fastest as research applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between China and Germany defines regional potassium lactate dynamics, with Chinese manufacturers leveraging corn feedstock advantages while German suppliers capture pharmaceutical-grade premiums through REACH-compliant fermentation infrastructure.
China
Centralized corn processing in Shandong and Henan provinces anchors lactic acid derivative manufacturing, with Henan Jindan Lactic Acid Technology Co., Ltd. exemplifying integrated feedstock-to-salt production. SAMR food additive standards under GB 2760 govern potassium lactate purity thresholds for domestic and export markets. The Yangtze River Delta cluster concentrates fermentation capacity expansion, with Zhengzhou and Jinan emerging as export logistics hubs for preservative-grade shipments to Southeast Asia and the Middle East.
Germany
Meat processor sodium reduction mandates under WHO guidelines drive food-grade potassium lactate procurement from domestic fermentation houses. ECHA REACH registration requirements impose toxicological dossier burdens that filter sub-tonnage importers from the EEA market. The North Rhine-Westphalia chemical corridor, centered on Cologne and Düsseldorf, hosts Corbion N.V. and Jungbunzlauer Suisse AG distribution infrastructure serving pharmaceutical-grade contracts across the EU.
United States
Large meatpackers in Nebraska and Iowa consolidate supplier lists from twelve vendors to four strategic partners with joint shelf-life testing protocols. FDA 21 CFR 184.1639 governs usage levels and labeling requirements for processed meat applications. Cargill Incorporated leverages its Minnesota corn-processing infrastructure to anchor supply security for downstream lactate derivatives serving North American cured meat and ready-to-eat protein segments.
Brazil
Beef and poultry export processors in São Paulo and Paraná states adopt potassium lactate for sodium reduction in EU-bound shipments facing WHO-compliant import standards. ANVISA food additive regulations align with Mercosur technical standards for preservative-grade materials. The São Paulo metropolitan cluster concentrates technical collaboration agreements between meatpackers and fermentation suppliers, displacing spot-market purchasing for sodium reduction formulations.
India
Emerging meat processing investments in Maharashtra and Uttar Pradesh generate initial food-grade potassium lactate demand as processors anticipate FSSAI sodium reduction guidelines. BIS quality standards for food-grade lactic acid derivatives remain under harmonization with Codex Alimentarius frameworks. The Mumbai-Pune industrial corridor attracts distributor investments for specialty ingredient procurement portals bypassing traditional chemical merchant networks.
Potassium Lactate Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation technology and feedstock conversion. The supplier base concentrates around three to five qualified fermentation houses with documented USP and EP batch records, while merchant traders and regional compounders occupy fragmented downstream tiers. Two dominant strategic archetypes emerge: integrated corn processors with captive lactic acid supply, and pure-play fermentation specialists with pharmaceutical-grade certification depth. Capacity expansion and strategic technical collaboration agreements constitute the primary competitive moves, with meatpackers demanding joint shelf-life testing protocols rather than transactional certificate exchanges.
Among integrated agribusiness platforms, Cargill Incorporated anchors supply security through corn-processing infrastructure extending into downstream lactate derivatives. Fermentation specialists Corbion N.V. and Jungbunzlauer Suisse AG occupy positions defined by microbial technology depth and multi-jurisdiction certification compliance. Chinese manufacturers Henan Jindan Lactic Acid Technology Co., Ltd. and Chongqing Bofei Biochemical Products represent feedstock-advantaged production anchored in centralized corn processing hubs. Tate & Lyle, ADM, and Lab M Limited sit within ingredient distribution and compounding tiers, while American Elements exemplifies diversified chemical supply positioning across industrial-grade segments.
| Leading Market Players |
|---|
| Chongqing Bofei Biochemical Products |
| Cargill Incorporated |
| Jungbunzlauer Suisse AG |
| Tate & Lyle |
| ADM |
| Henan Jindan Lactic Acid Technology Co., Ltd. |
| Corbion N.V. |
| Lab M Limited |
| American Elements |
| Others |
Supply Flow & Price Mechanics
Corn price volatility in Shandong and Henan provinces compresses margin structures for fermentation-based producers while simultaneously widening the spread between spot-market industrial grades and long-term pharmaceutical contracts. This feedstock instability forces buyers to choose between price-anchored Chinese supply and certification-assured European fermentation houses, reshaping procurement risk allocation across the value chain.
Pricing Analysis
The customization-premium spread separates standard food-grade tanker shipments from configured pharmaceutical-grade deliveries with USP documentation and joint shelf-life testing protocols. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with USP and EP monograph compliance commanding substantial premiums over baseline food-additive specifications. Cost compression in industrial-grade segments is intensifying because potassium chloride substitutes retain share in non-label-sensitive applications. Chemical intermediate buyers exhibit the highest price sensitivity, while pharmaceutical formulators prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between Chinese fermentation hubs and European meat processors dominates supply chain risk calculations for preservative-grade procurement. Manufacturing concentrates in China, Germany, and the United States, with Shandong corn processing and North Rhine-Westphalia fermentation infrastructure anchoring regional supply. The chain draws from corn feedstock, potassium carbonate, and fermentation engineering talent as critical inputs. Single-source vulnerability concentrates at qualified USP-grade fermentation houses with documented batch records. Distribution runs through direct-to-processor digital platforms that displace traditional chemical merchant networks for bulk container shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as meat processor sodium reduction mandates splinter demand across certification tiers, creating specialized niches for fermentation specialists, integrated agribusiness platforms, and regional compounders alike.
For Market Incumbents: Entrench pharmaceutical-grade positioning through USP and EP qualification cycle acceleration, compressing the 18-24 month supplier onboarding timeline that currently protects qualified fermentation houses from merchant challengers. Add continuous fermentation capacity in Germany or the Netherlands to capture bioprocessing efficiency gains before mid-tier Eastern European producers retrofit batch plants. Threat substitution from potassium chloride in industrial applications demands margin defense through grade-tier specialization rather than volume competition. For New Entrants and Emerging Players: Establish a beachhead in plant-based protein pH regulation, where emerging alternative meat formulations require moisture retention without sodium-based additives and qualified supplier lists remain underdeveloped. Target Indian meat processing investments in Maharashtra and Uttar Pradesh ahead of FSSAI sodium reduction guideline implementation, leveraging distributor portal investments in the Mumbai-Pune corridor to bypass entrenched chemical merchant networks. Lead with technical collaboration agreements specifying joint shelf-life testing rather than transactional certificate exchanges. For Investors and Strategic Acquirers: REACH authorization requirements for substances of very high concern reshape the acquisition landscape by forcing toxicological dossier investments that filter sub-tonnage importers from the EEA market. Five-to-ten year viability favors fermentation specialists with multi-jurisdiction certification depth over merchant traders dependent on spot-market purchasing. Target acquisition archetype: pure-play fermentation houses with documented USP batch records and captive corn feedstock arrangements. Signal to monitor: ECHA guidance updates on lactic acid derivative classifications that expand analytical testing obligations for non-EU manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Retrofit | Mid-tier German and Dutch producers capture yield improvements and reduce energy intensity per tonne. |
| USP and EP Qualification Acceleration | Shortened supplier onboarding cycles defend pharmaceutical-grade margin pools from merchant challengers. |
| Direct-to-Processor Digital Platform | Specialty ingredient distributors bypass traditional chemical merchant networks for bulk container shipments. |
| Joint Shelf-Life Testing Protocol | Technical collaboration agreements displace transactional certificate-of-analysis exchanges with large meatpackers. |
| Corn Feedstock Integration | Backward integration into Shandong and Henan corn processing anchors supply security against price volatility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with meat processor procurement directors, pharmaceutical formulation scientists, fermentation plant managers, and specialty ingredient distribution executives. Secondary validation drew from FDA 21 CFR filings, ECHA REACH registration databases, SAMR GB 2760 standards, customs and trade flow data, and SEC disclosures from integrated agribusiness platforms. Bottom-up volume modeling across grade tiers and applications was triangulated against top-down macroeconomic indicators.
Calibration against historical price realizations and capacity utilization rates anchored projections across the analysis window. Segmentation dimensions modeled include product grade tier, end-use application, packaging configuration, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth trajectories. Forecast inputs incorporated WHO sodium reduction mandate adoption curves and fermentation technology yield improvement trajectories.
Stress conditions across corn price volatility bands, REACH authorization timeline extensions, and potassium chloride substitution thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory adoption rates and bioprocessing efficiency gains. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Japan Anti-Caking Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Food Grade Butyric Acid Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market