
 Europe Feed Anti-Caking Agents Market | 2026-2036
Europe Feed Anti-Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Anti-Caking Agents Market Foresight
Aquaculture feed formulation is decoupling from traditional livestock anti-caking specifications as marine protein producers seek specialized flowability solutions. BASF SE leverages its silicate R&D pipeline to serve this divergence, while Kemin Industries Inc anchors its position through livestock feed channel control across Iberian and Nordic markets. Evonik Industries differentiates via phosphate-based nutritional enhancement platforms that integrate anti-caking with mineral delivery.
Feed anti-caking agents are inert powder or granular additives, typically composed of hydrated sodium calcium aluminosilicates or precipitated carbonates, manufactured through controlled precipitation and calcination to achieve specific particle size distributions below 75 microns for optimal surface area coverage. These materials prevent moisture-induced clumping in hygroscopic feed ingredients, preserving free-flow characteristics during pneumatic conveying and automated batching operations. Silicates occupy the largest product category due to their cost efficiency and broad compatibility with thermolabile vitamins, while phosphate variants command premium positioning where nutritional enhancement converges with anti-caking function. Powder formulations dominate volume throughput in centralized feed mills, though granular forms are gaining traction in specialty feed segments requiring dust reduction during handling.
The EU Feed Hygiene Regulation 183/2005 and REACH compliance obligations administered by ECHA shape product approval pathways and substance authorization timelines for anti-caking additives. EFSA safety evaluations for silicate and carbonate feed additives determine maximum permitted levels and species-specific restrictions, directly influencing formulation flexibility across member states. Stakeholders must monitor upcoming EU Green Deal feed sustainability criteria and potential F-Gas Regulation extensions to manufacturing processes, as these frameworks will reshape raw material sourcing and energy-intensive calcination operations.
Market Dynamics
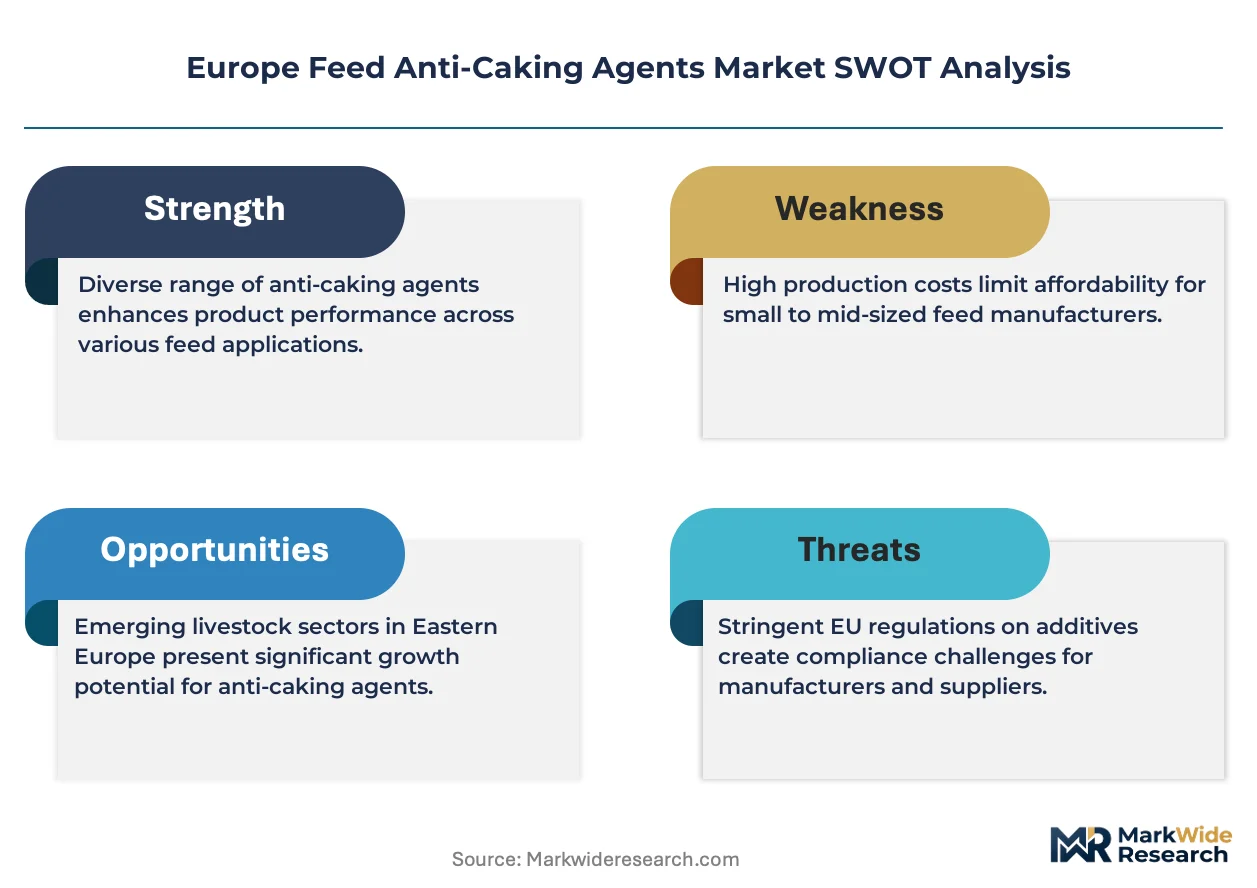
The EU Green Deal feed sustainability criteria are compressing calcination energy intensity thresholds while EFSA species-specific maximum levels force reformulation flexibility trade-offs across member states.
Growth Catalysts
- EU Feed Hygiene Regulation 183/2005:Tighter moisture control mandates in compound feed manufacturing pull silicate-based solutions into German, French, and Dutch premix facilities.
- Aquaculture feed specialization:Marine protein producers in Norway and Spain decouple from livestock specifications, creating dedicated flowability solution demand.
- Phosphate-nutritional convergence:Mineral delivery integration with anti-caking function commands premium positioning in high-value premix channels.
Market Restraints
- Energy-intensive calcination:Natural gas price volatility and F-Gas Regulation extension risks squeeze margins for silicate manufacturers operating thermal processing equipment.
- EFSA authorization timelines:Species-specific safety evaluations and maximum permitted level determinations stretch product approval pathways to 18-24 months.
- Organic acid substitutes:Citric acid and propionic acid blends gain traction in moisture-sensitive applications where mineral anti-caking faces compatibility constraints.
Strategic Opportunities
- Poland and Romania:Underpenetrated compound feed sectors in Eastern Europe present white space for silicate adoption as premix industries mature.
- Granular dust-reduction formats:Specialty feed segments in Denmark and Sweden switch from powder to granular handling systems, opening formulation differentiation.
- REACH authorization streamlining:ECHA substance grouping initiatives for silicates and carbonates promise consolidated compliance costs for multi-product portfolios.
Industry Challenges
- Thermochemical process engineering:Scarcity of calcination specialists with feed-grade mineral experience constrains capacity expansion in Portugal and Italy.
- Legacy pneumatic conveying integration:Retrofitting automated batching systems in 1980s-era feed mills requires custom particle size distribution matching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Anti-Caking Agents Market |
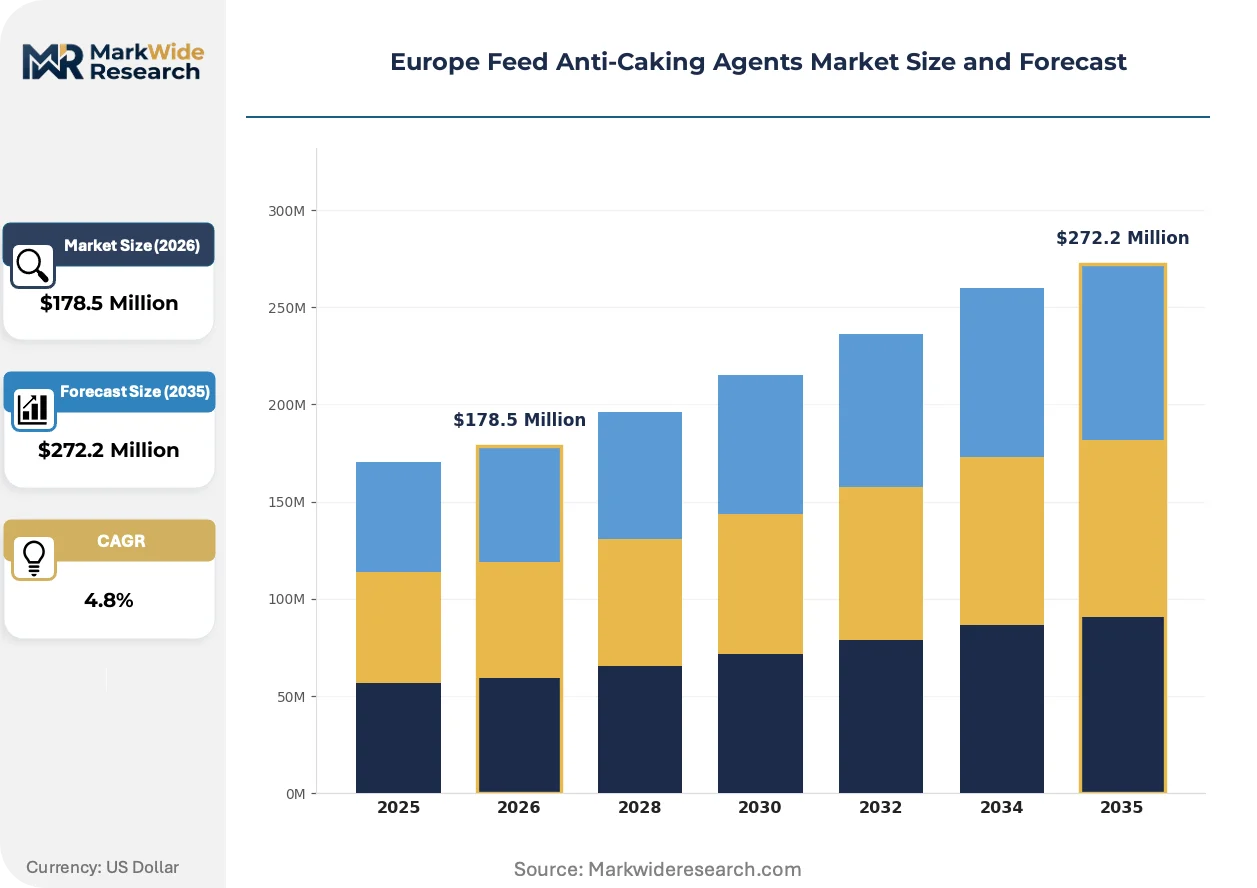
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $272.2 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicates, Carbonates, Talc, Phosphate Form: Powder, Granular, Liquid, Pellets End User: Livestock Feed, Pet Food, Aquaculture, Specialty Feed Application: Moisture Control, Flowability Improvement, Quality Preservation, Nutritional Enhancement |
| Companies Covered | Ecolab, Kemin Industries Inc, BASF SE, W R Grace & Co, Novus International, Archer Daniels Midland Co, PPG Industries, Kao Corporation, Evonik Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Anti-Caking Agents Market Shifts & Advancements
Formulation science is fragmenting along species-specific performance vectors while regulatory energy thresholds and procurement rationalization reshape competitive tooling.
Surface-engineered silicate particles with sub-50-micron distributions are modularizing moisture control architectures. Nordic aquafeed manufacturers adopt these engineered substrates for marine protein stability. The technology is compressing traditional hydrated sodium calcium aluminosilicate volumes into application-specific performance tiers.
EU F-Gas Regulation extensions to industrial thermal processes are elevating calcination energy audit requirements. Feed additive manufacturers face capital allocation decisions between emission control retrofits and process relocation. Iberian silicate producers accelerate heat recovery system deployment ahead of 2027 compliance checkpoints.
Compound feed procurement in the Netherlands and Belgium consolidates through cooperative purchasing alliances. Centralized mills negotiate multi-year anti-caking supply contracts with technical service bundling. Denmark witnesses parallel unbundling as specialty premix houses seek direct silicate sourcing to protect formulation IP.
Europe Feed Anti-Caking Agents Market Segmentation
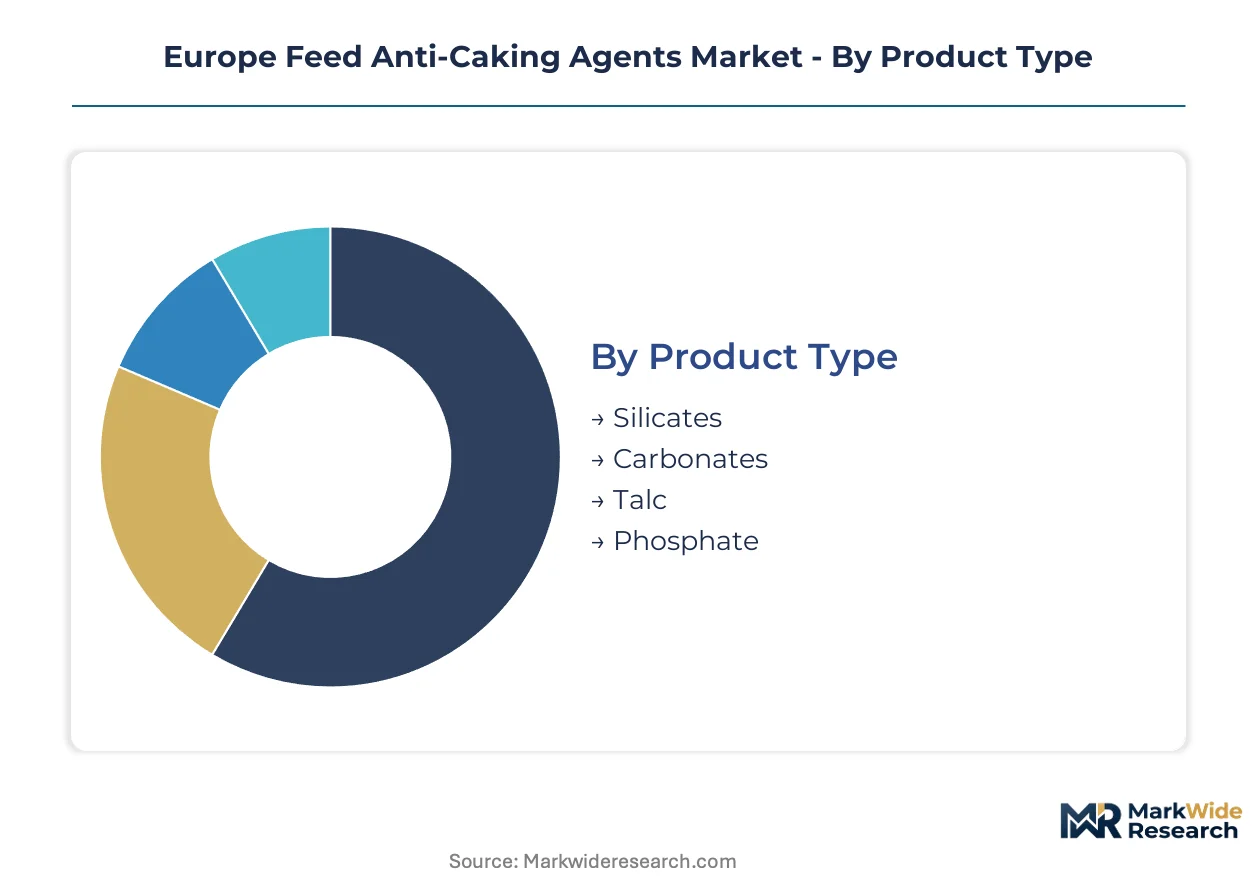
Feed anti-caking agents fragment across technical specifications, physical formats, and end-use requirements. Each dimension carries distinct regulatory footprints and margin structures that shape supplier positioning across European markets.
Product Type:
Supply concentration clusters around silicate manufacturing capacity in Western Europe, where calcination infrastructure and REACH authorization histories create incumbent advantages.
- Silicates:Hydrated sodium calcium aluminosilicates manufactured through controlled precipitation and calcination dominate volume throughput. German and Dutch premix facilities pull silicate volumes under EU Feed Hygiene Regulation 183/2005 moisture control mandates, while energy-intensive thermal processing faces F-Gas Regulation compliance pressures.
- Carbonates:Precipitated calcium and magnesium carbonates serve moisture-sensitive applications requiring neutral pH compatibility. French compound feed mills concentrate demand for carbonate variants where vitamin stability concerns limit silicate adoption.
- Talc:Magnesium silicate hydroxide with lamellar particle structure provides dust suppression in handling-intensive operations.
- Phosphate:Calcium and magnesium phosphates integrate mineral delivery with anti-caking function, commanding premium positioning in high-value premix channels.
Silicates absorb the bulk of installed capacity; phosphate variants are expanding most quickly.
Form:
Physical format selection tracks handling infrastructure maturity and dust exposure regulations across member states.
- Powder:Sub-75-micron particle distributions dominate centralized feed mill throughput in Belgium and the Netherlands, where pneumatic conveying systems require optimal surface area coverage for moisture adsorption.
- Granular:Dust-reduction formats gain traction in Danish and Swedish specialty feed segments where operator exposure limits under national occupational health frameworks drive handling system upgrades.
- Liquid:Suspension formulations serve niche applications requiring uniform coating distribution in high-moisture feed matrices.
- Pellets:Compressed anti-caking substrates enable controlled-release moisture management in extended storage scenarios.
Powder formulations retain the largest volume footprint; granular formats are climbing the fastest as dust control investments accelerate.
End User:
Customer type determines specification stringency and technical service bundling requirements.
- Livestock Feed:Poultry, swine, and ruminant compound feed manufacturers constitute the foundational demand base, with Iberian and Nordic markets channeling volume through established distributor relationships.
- Pet Food:Premium dry pet food producers in France and Germany specify low-dust formulations for palatability-sensitive applications.
- Aquaculture:Norwegian and Spanish marine protein producers decouple from livestock specifications, seeking specialized flowability solutions for hygroscopic marine ingredient matrices.
- Specialty Feed:Equine, rabbit, and exotic animal feed manufacturers require customized particle size distributions for small-batch processing equipment.
Livestock feed absorbs the bulk of installed capacity; aquaculture is gaining share fastest as marine protein output scales.
Application:
Functional positioning determines pricing architecture and formulation integration depth.
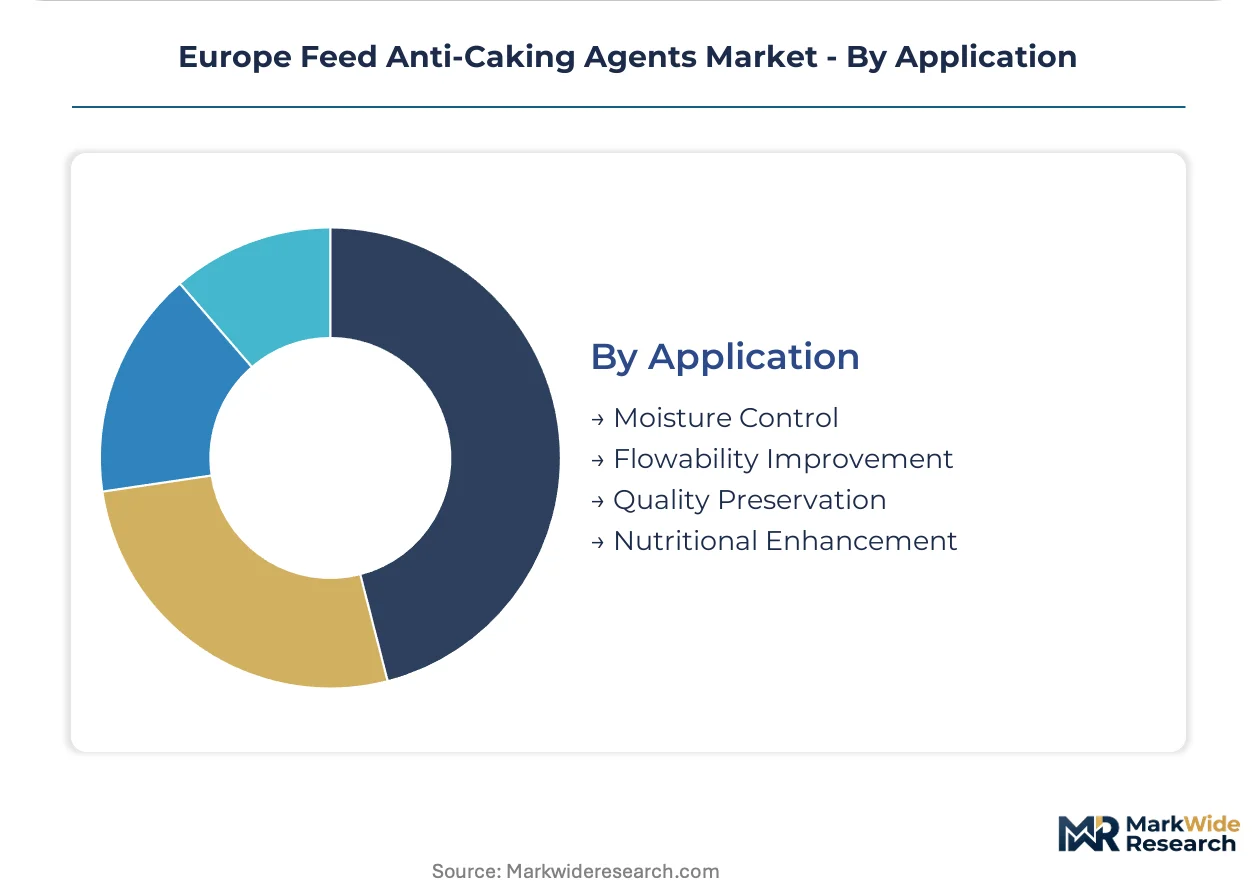
- Moisture Control:Hygroscopic ingredient stabilization represents the core value proposition, with silicate and carbonate solutions preventing clumping during pneumatic conveying and automated batching in German facilities.
- Flowability Improvement:Surface area optimization ensures free-flow characteristics in high-fat premixes, critical for Iberian compound feed operations handling imported oilseed meals.
- Quality Preservation:Thermolabile vitamin protection extends shelf stability in multi-component feed matrices subject to temperature fluctuations during distribution.
- Nutritional Enhancement:Phosphate-based platforms integrate anti-caking with bioavailable mineral delivery, commanding formulation premiums in high-value premix channels.
Moisture control absorbs the bulk of installed capacity; nutritional enhancement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of feed anti-caking agents concentrates in Western European calcination clusters, while consumption spreads across both established premix corridors and emerging compound feed sectors in the East. Germany, France, and the Netherlands anchor manufacturing capacity through integrated silicate operations, yet demand growth now outpaces supply expansion in Poland and Romania.
Germany
Moisture control mandates under EU Feed Hygiene Regulation 183/2005 pull silicate volumes into Bavarian and Lower Saxon premix facilities. EFSA maximum permitted level determinations for species-specific applications stretch reformulation timelines for exporters. The Rhine-Ruhr industrial corridor hosts calcination infrastructure serving centralized feed mills across Benelux.
France
Precipitated carbonate demand clusters around vitamin-sensitive compound feed manufacturing in Brittany and Pays de la Loire. ANSM and national labor inspectorates enforce dust exposure limits that accelerate granular format switching in handling-intensive operations. The Grand Est region anchors cross-border supply relationships with German and Swiss premix houses.
Netherlands
Randstad cooperative purchasing alliances consolidate multi-year anti-caking supply contracts with technical service bundling. REACH authorization timelines administered by ECHA shape substance grouping strategies for silicate portfolios. The Port of Rotterdam corridor enables imported marine ingredient flows that stress-test flowability solutions in aquafeed channels.
Spain
Iberian livestock feed channels channel silicate volumes through established distributor relationships anchored in Catalonia and Aragón. F-Gas Regulation extensions to thermal processes elevate energy audit requirements for calcination operations ahead of 2027 compliance checkpoints. Basque Country producers accelerate heat recovery system deployment to defend margin positions.
Poland
Underpenetrated compound feed sectors in Mazovia and Silesia present white space for silicate adoption as premix industries mature. EU Green Deal feed sustainability criteria compress energy intensity thresholds for imported anti-caking substrates. Warsaw-based feed manufacturers negotiate direct sourcing relationships to bypass legacy distributor markups.
Europe Feed Anti-Caking Agents Market Competitive Landscape
Top-tier vendors anchor calcination capacity and REACH authorization histories, while mid-scale specialists occupy formulation differentiation niches. The market structures around three to five integrated silicate producers controlling Western European supply, complemented by phosphate-nutritional convergence players commanding premix premiums. Strategic archetypes include calcination-integrated mineral processors, phosphate-platform nutrition specialists, and aquaculture-flowability engineers. Competitive moves concentrate on capacity expansion in Iberia and heat recovery retrofits, alongside direct sourcing unbundling in Nordic specialty feed channels.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries exemplify divergent strategic vectors—BASF occupying calcination-integrated silicate production while Evonik anchors phosphate-nutritional convergence platforms. Kemin Industries Inc represents the US-origin nutrition specialist archetype with channel control positions across Iberian and Nordic livestock markets. These three entities collectively illustrate how authorization depth, thermal processing scale, and species-specific formulation expertise partition competitive terrain.
| Leading Market Players |
|---|
| Ecolab |
| Kemin Industries Inc |
| BASF SE |
| W R Grace & Co |
| Novus International |
| Archer Daniels Midland Co |
| PPG Industries |
| Kao Corporation |
| Evonik Industries |
| Others |
Supply & Pricing Matrix
Phosphate-nutritional convergence tiers separate premium mineral delivery platforms from commodity silicate flows, with the former commanding formulation premiums in Dutch and German high-value premix channels while calcination-integrated suppliers absorb energy cost volatility through long-term offtake structures.
Pricing Analysis
Short lead-time premiums apply to engineered silicate substrates with sub-50-micron distributions serving Nordic aquafeed manufacturers, while spot inventory discounts concentrate in standardized hydrated sodium calcium aluminosilicate volumes. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA authorization depth and thermal processing scale. Price differentiation hinges on REACH compliance bundling and species-specific formulation support. Pricing pressure stems from natural gas cost volatility compressing calcination margins in Iberian operations. Large cooperative purchasing alliances in the Netherlands exhibit lowest price sensitivity; small specialty premix houses in Denmark show highest sensitivity as they unbundle from distributor relationships.
Supply Chain Analysis
Direct-to-premix channels handle German and Dutch compound feed demand, while distributor-mediated flows serve Iberian and Nordic livestock markets. Supply concentrates in Germany, France, and the Netherlands through integrated calcination clusters. Raw material dependencies draw from high-purity sodium silicate feedstocks, natural gas for thermal processing, and specialized aluminosilicate ores. Single-source vulnerability sits with calcination specialists possessing feed-grade mineral expertise, constraining capacity expansion in Portugal and Italy. Distribution runs through cooperative purchasing alliances in Benelux and legacy distributor networks in Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around calcination scale and REACH authorization depth, with F-Gas Regulation compliance costs forcing sub-scale mineral processors toward exit or acquisition.
For Market Incumbents: Anchor calcination capacity in the Rhine-Ruhr corridor through heat recovery retrofits ahead of 2027 compliance checkpoints. Deepen backward integration into sodium silicate feedstocks to defend margin positions against natural gas volatility. Prioritize species-specific formulation IP in phosphate-nutritional convergence platforms to resist organic acid substitution threats in moisture-sensitive applications. For New Entrants and Emerging Players: Enter via direct sourcing relationships with Warsaw-based feed manufacturers seeking to bypass legacy distributor markups in Poland's underpenetrated compound feed sector. Target granular dust-reduction formats in Danish and Swedish specialty feed segments where occupational health frameworks drive handling system upgrades. Lead with technical service bundling around REACH authorization streamlining for multi-product silicate portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale calcination-integrated mineral processors with EFSA authorization histories and stranded heat recovery assets. Long-term viability favors suppliers with captive energy sourcing or renewable thermal integration. Acquisition targets include Iberian silicate producers facing 2027 F-Gas compliance cliffs. Watch for EU Green Deal feed sustainability criteria enforcement as inflection indicator for energy intensity threshold compression.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery System Deployment | Defends calcination margins against F-Gas Regulation audit requirements in Spain and Italy. |
| Direct Sourcing Relationship Formation | Bypasses legacy distributor markups for Polish compound feed manufacturers in Mazovia. |
| Phosphate-Nutritional Platform Expansion | Captures premium positioning in Dutch high-value premix channels through mineral delivery integration. |
| Granular Format Capacity Addition | Addresses dust exposure limits under Swedish and Danish occupational health frameworks. |
| REACH Authorization Streamlining | Reduces compliance costs via ECHA substance grouping initiatives for silicate and carbonate portfolios. |
Research Methodology
Document review covered EFSA safety evaluation databases, EU Feed Hygiene Regulation implementation reports, and ECHA REACH authorization records, complemented by interviews with plant managers at German calcination facilities, procurement leads at Dutch premix houses, technical R&D directors at phosphate-nutritional convergence specialists, and distribution channel partners across Iberian livestock markets. Secondary validation drew from Cefic chemical industry reports, customs and trade data for silicate imports, and SEC filings of listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, physical format, and end-use segmentation.
Cross-referencing historical calcination capacity utilization against panel input from feed mill engineering consultants shaped the analytical framework across the analysis window. Segmentation dimensions modeled include silicate versus phosphate versus carbonate chemistry, powder versus granular physical format, and livestock versus aquaculture versus pet food end-use, supplemented by regulatory authorization tier. CAGRs were derived through exponential smoothing of annual volume trajectories, incorporating natural gas price scenario sensitivity and EFSA maximum permitted level revision probabilities as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU Green Deal feed sustainability criteria acceleration or F-Gas Regulation extension to additional thermal process categories. Periodic stress-testing of base assumptions is recommended, particularly regarding calcination energy intensity thresholds and species-specific reformulation flexibility trade-offs across member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Liquid Caramel Color Market