
 Microencapsulation Market | 2026-2036
Microencapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Microencapsulation Market Analysis
REACH is rebalancing the cost-of-entry calculus for European microencapsulation suppliers, forcing reformulation investments that favor incumbents with established toxicology dossiers. BASF SE leverages its polymer science heritage to sustain integrated supply from raw material through finished capsule. Evonik Industries AG anchors high-value pharmaceutical-grade capacity through specialized resorbable excipient platforms. dsm-firmenich competes on aroma and nutrient stability, extending encapsulation into fortified food matrices where thermal protection determines shelf-life performance.
Microencapsulation encloses active ingredients within protective shells measuring 1–1000 micrometers, typically employing biopolymers, lipids, or inorganic matrices to achieve controlled release, taste masking, or environmental isolation. Spray drying dominates volume throughput for food and agricultural applications, while coacervation commands premium positioning in pharmaceutical taste-masking where shell uniformity directly impacts bioavailability. Polymer-based shells lead value generation due to tunable degradation kinetics, whereas lipid-based systems represent the fastest-growing category in cosmetics as brands pursue clean-label emulsion stability without synthetic surfactants.
EMA stability guidelines and FDA dissolution protocols shape product development roadmaps, with both agencies tightening validation requirements for modified-release oral dosage forms. EFSA novel food assessments and EPA pesticide residue frameworks further segment market access, creating distinct compliance pathways across nutrition and crop protection applications. Stakeholders must monitor evolving pharmacopeial monographs and sustainability disclosure mandates to anticipate where formulation investments will yield protected margin pools.
Market Dynamics
Pharmaceutical-grade shell uniformity requirements are compressing the supplier base, as EMA stability guidelines and FDA dissolution protocols force capital-intensive validation investments that favor incumbents with established toxicology dossiers.
Growth Catalysts
- Controlled-release drug delivery:Chronic disease management protocols in oncology and diabetes are accelerating demand for tunable degradation kinetics in polymer-based shells.
- REACH compliance elevation:Reformulation investments mandated by ECHA toxicology dossier requirements are locking in incumbent positions across European pharmaceutical supply chains.
- Lipid-based clean-label cosmetics:Synthetic surfactant avoidance in premium skincare is pulling lipid microencapsulation capacity toward cosmetic emulsion stability applications.
Market Restraints
- Biopolymer feedstock volatility:Alginate and chitosan supply fluctuations from Southeast Asian aquaculture operations create input cost instability for shell manufacturers.
- High-purity excipient concentration:Pharmaceutical-grade resorbable polymer supply concentrates among German and Swiss specialty chemical producers, creating single-source vulnerability.
- Scale-up barrier in coacervation:Batch-to-batch shell uniformity limitations prevent coacervation technology from displacing spray drying in high-volume agricultural applications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO accelerated approval pathways for complex generics are attracting contract microencapsulation investment toward Mumbai-Pune chemical corridors.
- Cell-cultured protein fortification:EFSA novel food assessment frameworks for encapsulated nutrient stability in alternative meat matrices create first-mover positioning for thermal-protection formulations.
- Precision fermentation integration:Convergence of synthetic biology and microencapsulation is enabling bioactive molecule protection through in-situ shell formation during upstream bioprocessing.
Industry Challenges
- Formulation scientist scarcity:Cross-disciplinary expertise spanning polymer science, pharmacokinetics, and regulatory science remains concentrated among Basel and Boston talent pools.
- GMP facility certification timelines:EMA and FDA concurrent validation requirements for modified-release oral dosage forms extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microencapsulation Market |
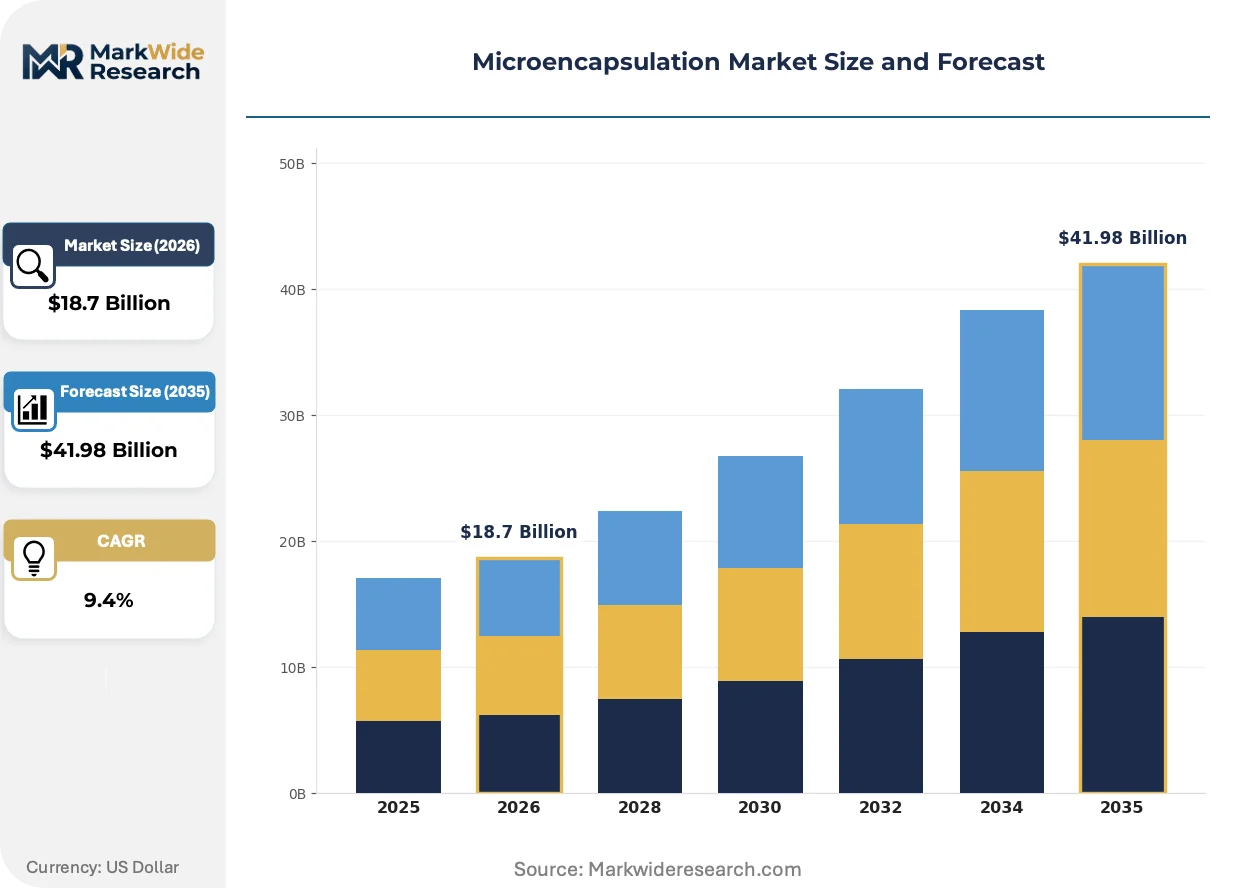
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-based, Lipid-based, Inorganic, Hybrid Formulation Type: Liquid, Powder, Granules, Capsules End Use: Pharmaceuticals, Food & Beverage, Agriculture, Cosmetics Technology: Spray Drying, Coacervation, Fluidized Bed, Extrusion |
| Companies Covered | BASF SE, LycoRed Group, Balchem, International Flavors & Fragrances Inc., AVEKA Group, Encapsys LLC, dsm-firmenich, Givaudan, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microencapsulation Market Emerging Trajectories
Process intensification and regulatory harmonization pressures are compressing traditional technology lifecycles, forcing simultaneous investment in equipment automation and compliance infrastructure.
Electrohydrodynamic atomization is consolidating precision pharmaceutical manufacturing by enabling monodisperse sub-micron capsule production with narrow size distributions. Oncology and biologics developers are adopting this technology for parenteral delivery systems where particle size directly impacts biodistribution. The structural consequence is a bifurcation between high-value pharmaceutical-grade capacity and commodity food-agricultural spray drying infrastructure.
EU MDR Annex I general safety and performance requirements are forcing resubmission of legacy medical device coating formulations that incorporate microencapsulated antimicrobials or drug-eluting components. Manufacturers must regenerate clinical evidence for shell degradation profiles under the new regulatory framework. Cardiovascular stent and orthopedic implant suppliers in Germany and Ireland are prioritizing resorbable polymer platforms that align with MDR biocompatibility timelines.
Long-term offtake agreements are displacing spot market purchasing for pharmaceutical-grade excipients as generic drug makers seek supply security amid raw material concentration. Large-volume oral solid dosage producers in India and the United States are locking in multi-year contracts with integrated polymer suppliers. This behavioral shift is most visible among CDMOs serving the North American generics market, where FDA facility inspection backlogs have amplified supply continuity concerns.
Microencapsulation Market Segmentation
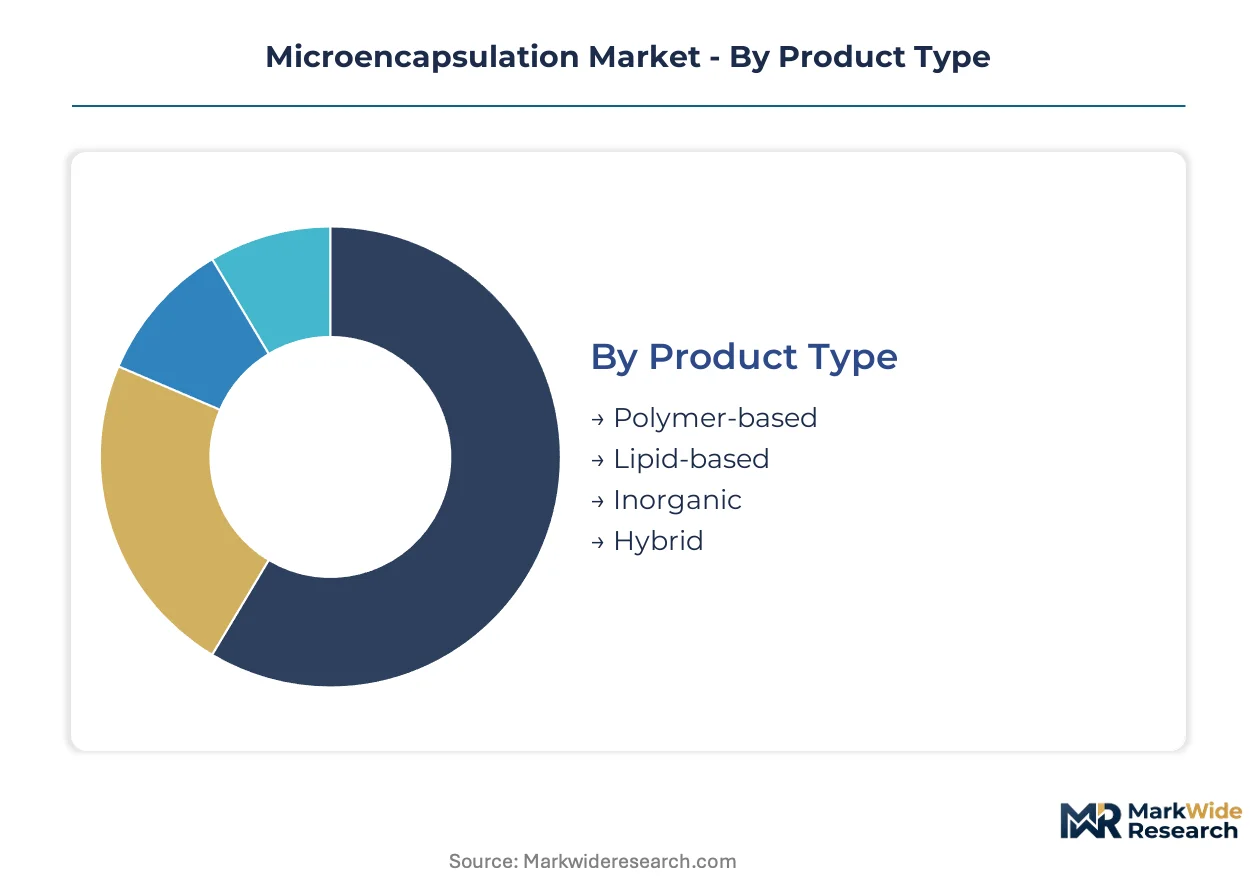
Microencapsulation market segmentation reveals how shell chemistry, physical form, and manufacturing technology dictate regulatory pathways and margin structures. Each dimension carries distinct certification burdens that reshape supplier economics and customer procurement patterns.
Product Type:
FDA dissolution protocols and EMA stability guidelines impose tiered validation requirements across shell chemistries, with pharmaceutical applications demanding the most extensive toxicology dossiers.
- Polymer-based:Synthetic and natural polymers including PLGA, gelatin, and cellulose derivatives enable tunable degradation kinetics for controlled-release pharmaceuticals. German and Swiss specialty chemical producers concentrate high-purity resorbable polymer supply, locking in premium positioning for oncology and diabetes drug delivery systems where shell uniformity directly impacts bioavailability.
- Lipid-based:Phospholipids, waxes, and triglycerides form biodegradable shells without synthetic surfactants, satisfying clean-label cosmetics demand. Premium skincare brands in France and Italy are pulling lipid microencapsulation capacity toward emulsion stability applications as regulatory pressure on synthetic additives intensifies.
- Inorganic:Silica and calcium carbonate matrices provide thermal and oxidative protection for agricultural actives.
- Hybrid:Multi-layer structures combining polymer-lipid or polymer-inorganic compositions balance cost and performance.
Polymer-based formulations sit at the top of the volume ranking, with lipid-based systems climbing the fastest.
Formulation Type:
Physical form selection hinges on downstream processing compatibility and shelf-life requirements, with powder formats dominating high-volume food fortification and liquid suspensions commanding pharmaceutical premiums.
- Liquid:Aqueous or oil-based suspensions suit immediate-use applications in beverages and injectable pharmaceuticals.
- Powder:Free-flowing microparticles integrate into dry mixes for fortified foods and agricultural seed treatments. Spray-dried powders anchor throughput in Southeast Asian aquaculture feed operations where alginate and chitosan shell materials face supply volatility from regional harvest fluctuations.
- Granules:Larger agglomerated particles improve handling in bulk agricultural applications.
- Capsules:Pre-metered single-dose units target pharmaceutical and dietary supplement markets.
Powder formulations dominate volume throughput, while liquid suspensions capture the steepest expansion trajectory in parenteral drug delivery.
End Use:
Application-specific regulatory frameworks fragment market access, with pharmaceutical and food pathways diverging sharply on validation timelines and evidence requirements.
- Pharmaceuticals:Oral solid dosage forms, parenteral delivery systems, and medical device coatings require EMA and FDA concurrent validation for modified-release applications. CDSCO accelerated approval pathways for complex generics are attracting contract manufacturing investment toward Mumbai-Pune corridors.
- Food & Beverage:Nutrient fortification and flavor protection applications face EFSA novel food assessments for encapsulated bioactives.
- Agriculture:Pesticide and fertilizer encapsulation operates under EPA residue frameworks and equivalent national schemes.
- Cosmetics:Skincare and fragrance microencapsulation navigates EU cosmetic regulation annex restrictions on preservative systems.
Pharmaceuticals command the highest value per kilogram, with food and beverage applications scaling the fastest.
Technology:
Process selection determines capital intensity and batch uniformity, with coacervation and electrohydrodynamic methods requiring specialized equipment that limits supplier participation.
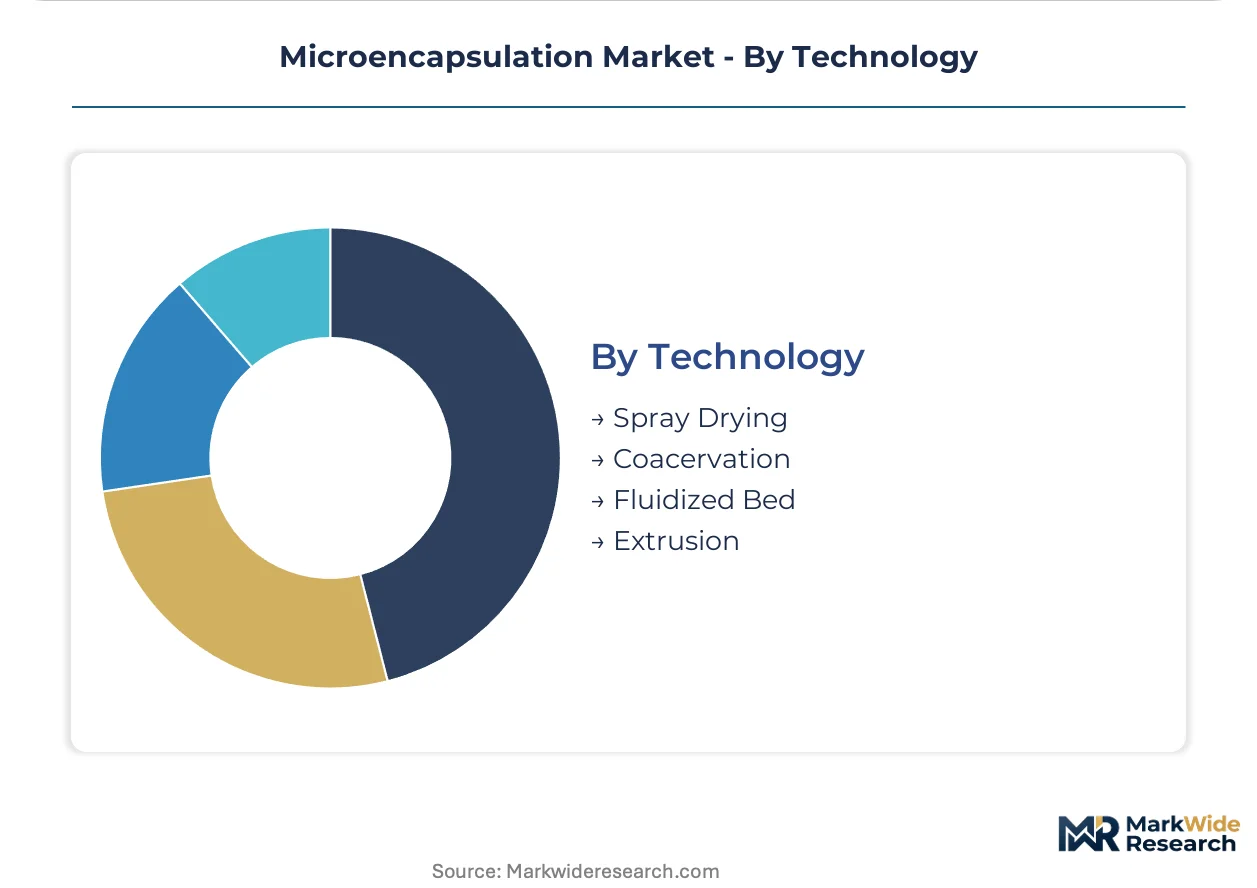
- Spray Drying:Atomization and thermal dehydration dominate throughput for food and agricultural applications. Indian and Chinese manufacturers leverage this technology for high-volume nutrient fortification where cost minimization outweighs particle size precision.
- Coacervation:Phase separation enables shell uniformity critical for pharmaceutical taste-masking and controlled release. Batch-to-batch reproducibility limitations prevent this technology from displacing spray drying in agricultural markets despite superior performance.
- Fluidized Bed:Air-suspension coating applies functional layers to solid cores for multi-particulate dosage forms.
- Extrusion:Melt-based processing suits heat-stable actives in food and feed applications.
Spray drying sits at the top of the volume ranking, with coacervation gaining share fastest in high-value pharmaceutical manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation scientists with cross-disciplinary expertise in polymer science and pharmacokinetics concentrate in Basel and Boston, anchoring high-value pharmaceutical microencapsulation capability in Switzerland and the United States.
United States
Oncology and diabetes drug developers in Massachusetts and New Jersey drive demand for tunable polymer-based shells with narrow size distributions. FDA dissolution protocols for modified-release oral dosage forms extend validation timelines and favor incumbents with established toxicology dossiers. Greater Boston hosts contract research organizations specializing in electrohydrodynamic atomization for parenteral delivery systems.
Germany
Precision manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia anchor pharmaceutical-grade resorbable polymer supply chains. REACH compliance requirements and EU MDR Annex I safety standards elevate barrier-to-entry for new encapsulation suppliers. Contract research organizations in the Rhine-Neckar metropolitan region specialize in medical device coatings incorporating drug-eluting microcapsules.
Switzerland
Specialty chemical producers in Basel concentrate high-purity excipient manufacturing for oncology applications where shell uniformity directly impacts bioavailability. Swissmedic stability guidelines align with EMA requirements, streamlining concurrent validation for European market access. The Basel biotech corridor integrates polymer science heritage with pharmaceutical formulation expertise.
India
Complex generic manufacturers in the Mumbai-Pune chemical corridor attract contract microencapsulation investment through CDSCO accelerated approval pathways. Domestic demand for fortified foods and aquaculture feed drives spray-dried powder throughput using alginate and chitosan shell materials. Formulation development centers in Hyderabad specialize in cost-optimized encapsulation for oral solid dosage forms.
China
Nutrient fortification and agricultural seed treatment applications dominate volume demand in the Yangtze River Delta and Shandong Peninsula. NMPA regulatory frameworks for pharmaceutical excipients are tightening validation requirements for imported polymer platforms. Domestic manufacturers leverage spray drying infrastructure for high-volume food and feed applications where cost minimization outweighs particle size precision.
Microencapsulation Market Vendor Landscape
The competitive structure tilts toward integrated specialty chemical conglomerates with captive polymer supply chains. Incumbents with established REACH dossiers and EMA-validated manufacturing facilities command premium positioning in pharmaceutical-grade segments. Three archetypes dominate: diversified chemical conglomerates with backward integration into raw material production, specialized excipient manufacturers focusing on resorbable polymers, and contract development organizations serving generic drug makers. Capacity expansion in pharmaceutical-grade facilities and technology licensing agreements for electrohydrodynamic atomization represent the primary competitive moves reshaping supplier economics.
Among German and Swiss integrated chemical producers, BASF SE and Evonik Industries AG exemplify the conglomerate archetype with polymer science heritage extending from raw material through finished capsule. dsm-firmenich occupies a position within the nutrition-specialist tier, leveraging aroma and nutrient stability expertise to extend encapsulation into fortified food matrices. These three entities represent how geographic concentration of formulation talent in Basel and Frankfurt translates into sustained competitive positioning across European pharmaceutical supply chains.
| Leading Market Players |
|---|
| BASF SE |
| LycoRed Group |
| Balchem |
| International Flavors & Fragrances Inc. |
| AVEKA Group |
| Encapsys LLC |
| dsm-firmenich |
| Givaudan |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
CDSCO accelerated approval pathways for complex generics in India are pulling contract manufacturing investment away from European REACH-compliant facilities, forcing German and Swiss suppliers to justify premium positioning through EMA-validated toxicology dossiers that commodity producers cannot replicate. This geographic arbitrage in regulatory compliance costs stratifies pricing power between incumbent integrated producers and emerging Asian contract manufacturers.
Pricing Analysis
Pharmaceutical-grade microencapsulation services split between bundled formulation-development contracts and unbundled toll-manufacturing arrangements. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated polymer shells from food-grade spray-dried powders and commodity agricultural formulations. Pricing pressure stems from Indian and Chinese manufacturers capturing high-volume nutrient fortification contracts with cost-optimized alginate and chitosan shell materials. Generic drug makers in North America exhibit highest price sensitivity, while oncology developers in Basel and Boston accept premium positioning for narrow particle-size distributions.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for pharmaceutical-grade excipients, with satellite warehouses in Mumbai and Shanghai serving contract manufacturing clusters. Raw material supply concentrates in Germany, Switzerland, and India, drawing from Southeast Asian aquaculture operations for alginate and chitosan feedstocks. Single-source vulnerability pervades high-purity resorbable polymer supply among Baden-Württemberg specialty chemical producers. Distribution runs through long-term offtake agreements rather than spot markets as generic makers seek supply security amid FDA facility inspection backlogs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO accelerated approval timelines in India undercut European REACH compliance costs by 40-60 percent, redirecting contract manufacturing investment toward Mumbai-Pune chemical corridors while locking premium pharmaceutical-grade margins in Basel and Frankfurt.
For Market Incumbents: Lock in multi-year supply agreements with North American generic drug makers before FDA facility inspection backlogs clear and Asian competitors achieve GMP certification parity. Prioritize electrohydrodynamic atomization capacity additions in Switzerland to defend oncology and biologics positioning against emerging precision fermentation integrators. EMA stability guideline tightening represents the primary regulatory moat; regenerate toxicology dossiers for legacy resorbable polymer platforms before EU MDR Annex I resubmission deadlines compress incumbent advantage windows. For New Entrants and Emerging Players: Direct-to-pharmaceutical-CDMO digital platforms offer the lowest-friction entry vector, bypassing capital-intensive GMP facility construction through toll-manufacturing partnerships with established Indian and Chinese spray-drying infrastructure. Cell-cultured protein fortification in alternative meat matrices presents the most penetrable white-space target, as EFSA novel food assessment frameworks remain unsettled and thermal-protection formulation expertise concentrates among aroma-chemistry specialists. Precision fermentation integration partnerships with synthetic biology startups provide differentiated positioning without proprietary bioprocessing asset ownership. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized excipient manufacturers possessing captive resorbable polymer supply chains and validated EMA manufacturing facilities in Germany or Switzerland. Long-term viability hinges on regulatory compliance infrastructure rather than formulation chemistry alone, favoring targets with concurrent FDA-EMA validation histories over technology-centric entrants. Watch for CDSCO GMP certification acceleration in Indian contract manufacturing as the inflection signal that premium European positioning will erode.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks in pharmaceutical-grade excipient offtake with North American generic makers amid FDA inspection backlogs. |
| Backward Integration | Captures alginate and chitosan supply from Southeast Asian aquaculture operations to stabilize input costs. |
| Capacity Expansion | Adds electrohydrodynamic atomization lines in Basel to serve oncology parenteral delivery system developers. |
| Joint Venture | Combines German polymer science heritage with Indian spray-drying infrastructure for complex generic export markets. |
| Green Manufacturing Transition | Aligns resorbable polymer platforms with EU Green Deal biocompatibility timelines for medical device coatings. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical formulation scientists, CDMO procurement managers, regulatory affairs specialists at EMA-notified bodies, and plant engineers at Southeast Asian alginate processing facilities with secondary validation from FDA dissolution protocol filings, EMA stability guideline updates, CDSCO approval pathway databases, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up capacity estimates across spray drying, coacervation, and electrohydrodynamic atomization infrastructure triangulated against top-down excipient demand projections from oral solid dosage and parenteral delivery forecasts.
Comparable-period anchoring calibrated the projection framework against historical validation timeline data for modified-release oral dosage forms, with segmentation dimensions spanning shell chemistry, formulation type, end-use application, and manufacturing technology. CAGRs derived from regression analysis across pharmaceutical, food and beverage, agriculture, and cosmetics demand trajectories, incorporating EFSA novel food assessment pipeline visibility and EPA pesticide residue framework evolution as industry-specific forecast modifiers.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation-integrated in-situ shell formation would alter the outlook if synthetic biology platforms achieve commercial scale faster than projected. Forecasts reflect stated assumptions regarding REACH compliance cost trajectories and CDSCO GMP certification acceleration timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
North America Feed Additives Market