
 Antistaling Agent Market | 2026-2036
Antistaling Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Antistaling Agent Market Analytics
Specialty ingredient distribution is rewriting how antistaling agents reach industrial bakeries across continents. BASF SE leverages its global emulsifier production network to sustain supply relationships with multinational bread manufacturers. Evonik Industries AG anchors its position through glycerol ester specialization in European dairy and confectionery channels. Croda International Plc differentiates via botanical-derived antistaling solutions that navigate clean-label procurement trends among North American food manufacturers.
Antistaling agents comprise surfactant compounds, modified starches, and lipid-based emulsifiers that retard starch retrogradation and moisture migration in baked matrices, typically functioning at inclusion rates between 0.5% and 3.0% by flour weight to preserve crumb softness and extend commercial shelf life. Emulsifiers dominate current volume flows due to established performance in industrial pan bread, while glycerol esters represent the fastest-expanding product category as processors reformulate for reduced synthetic additive content. Among applications, baked goods command the primary margin pool because large-scale bread and cake operations prioritize consistent antistaling performance over unit ingredient cost.
FDA food additive regulations under 21 CFR govern antistaling agent approvals and labeling requirements in the United States, while EFSA evaluates emulsifier safety thresholds within the European Union's broader food improvement agent framework. China's SAMR and national food safety standards impose distinct GB compliance pathways for imported antistaling formulations, creating divergent market access conditions that shape regional product portfolios. Stakeholders must monitor evolving clean-label certification schemes and regional maximum-permitted-level adjustments to align R&D pipelines with compliance requirements.
Market Dynamics
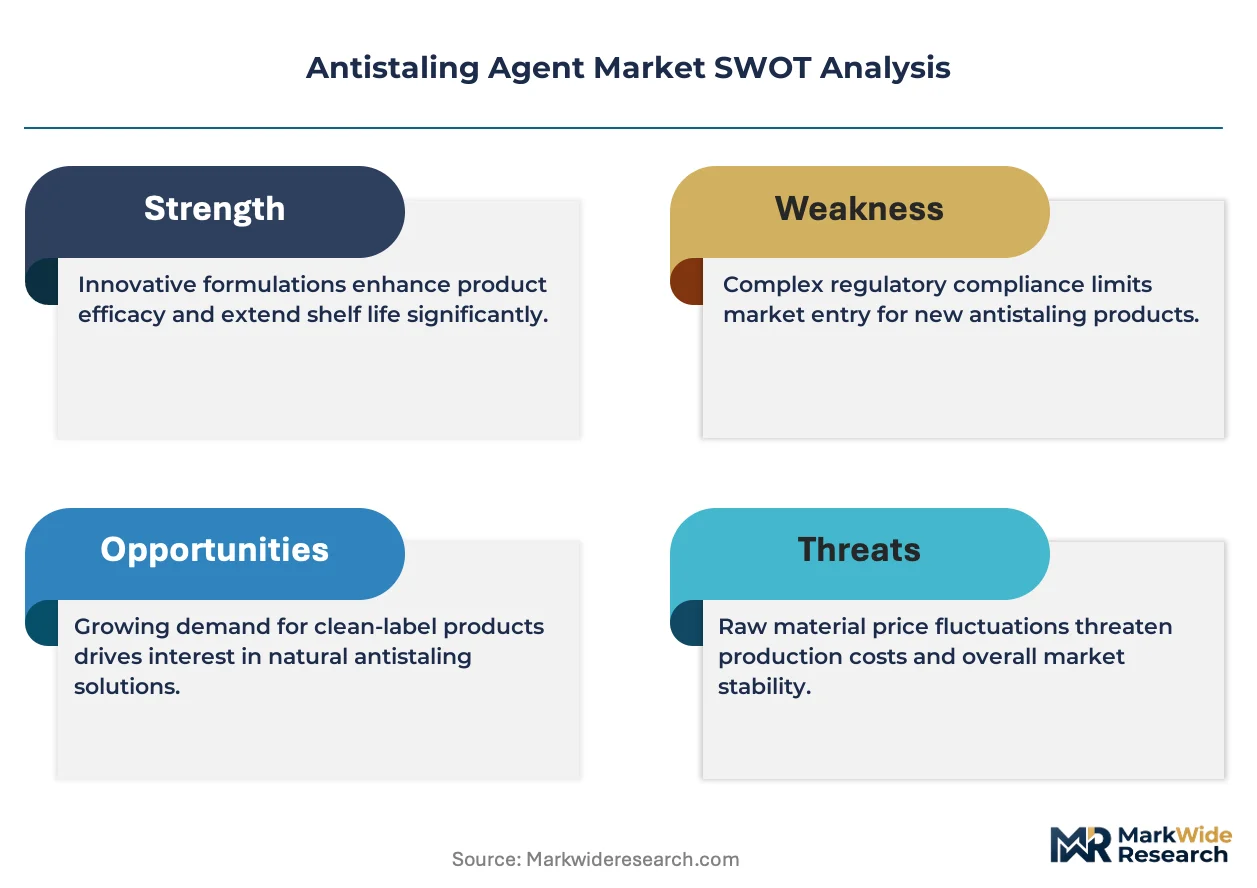
Clean-label mandates from EFSA and FDA are compressing synthetic emulsifier use and forcing accelerated botanical formulation development across industrial bakery supply chains.
Growth Catalysts
- EFSA Emulsifier Re-evaluation:The 2023-2024 safety reassessment of DATEM and SSL is accelerating reformulation demand for plant-derived alternatives in European bread manufacturing.
- Enzymatic Antistaling:Amylase and lipase blends are displacing chemical surfactants in artisan bakery segments seeking shorter ingredient declarations.
- China's GB Standard Modernization:SAMR's updated food additive positive list is expanding approved modified starch categories for domestic cake and pastry processors.
Market Restraints
- Palm Oil Derivative Volatility:Monoglyceride and diglyceride costs fluctuate with Malaysian and Indonesian palm oil export policies and sustainability certification premiums.
- European Supply Concentration:Specialty lipid emulsifier production clusters in Germany and the Netherlands create single-source vulnerability for pan-European bakery chains.
- Clean-Label Performance Gap:Botanical antistaling solutions demonstrate shorter efficacy windows than synthetic benchmarks, limiting full substitution in extended-shelf-life applications.
Strategic Opportunities
- India FSSAI Clean-Label Pathway:The regulator's emerging natural additive recognition framework offers first-mover positioning for enzymatic and fermented ingredient suppliers.
- Frozen Bakery Dough Expansion:Cryoprotectant antistaling systems for unbaked frozen bread and croissant applications represent underpenetrated functionality demand.
- EU Green Deal Bioeconomy Incentives:Circular starch valorization projects qualify for Horizon Europe funding, subsidizing pilot-scale upcycled antistaling agent development.
Industry Challenges
- Reformulation Timeline Compression:Bakery R&D cycles must compress from 18-24 months to 8-12 months to meet retailer clean-label deadlines without sacrificing product consistency.
- Cross-Regulatory Labeling Complexity:Ingredient nomenclature divergences between FDA's 21 CFR common or usual name requirements and EFSA's food additive numbering system complicate multinational product portfolio management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antistaling Agent Market |
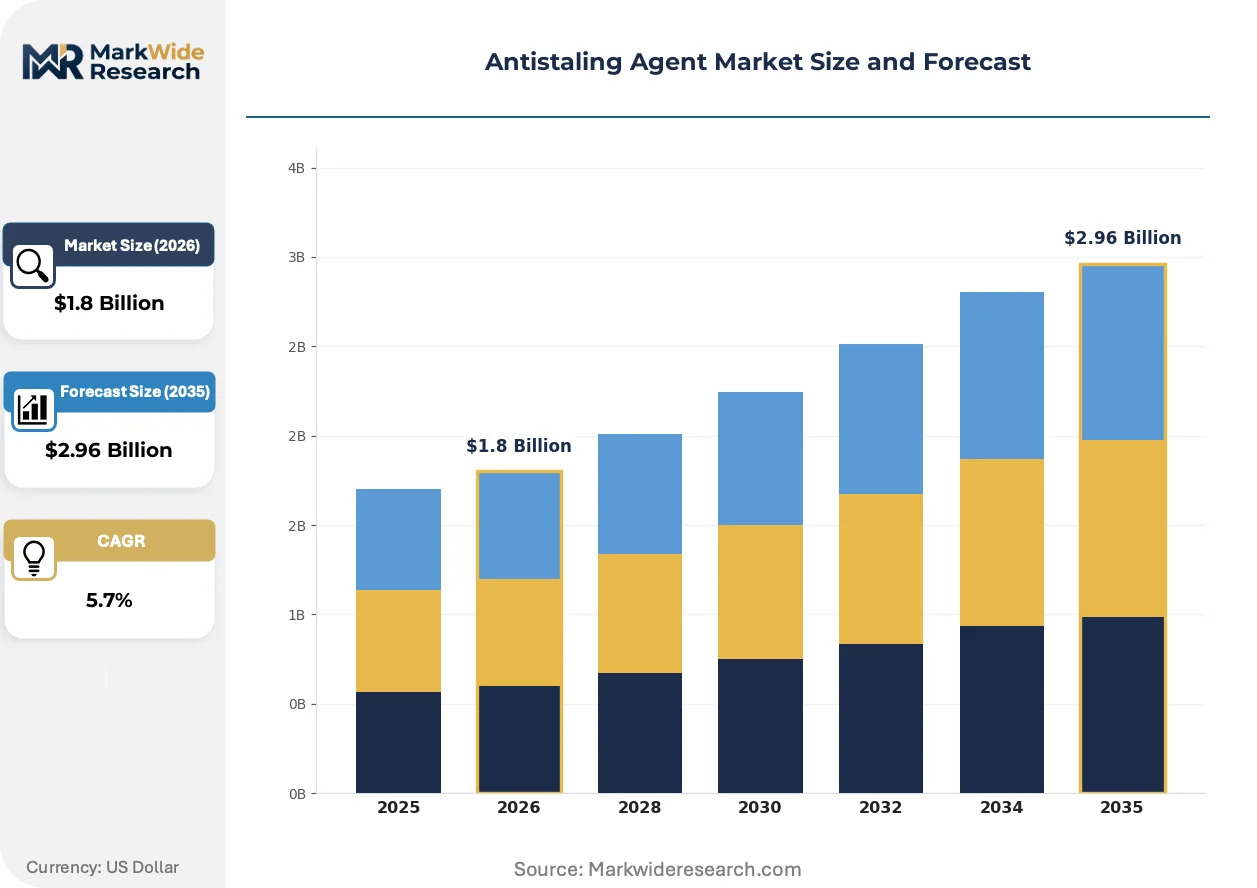
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Glycerol Esters, Vegetable Oils, Starch Esters Application: Baked Goods, Confectionery, Dairy Products, Sauces End User: Food Manufacturers, Restaurants, Catering Services, Retailers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | BASF SE, Evonik Industries AG, Croda International Plc, Penta Manufacturing Company, Huzhou Nanxun Shengtao Botanical Co., Ltd, Shaanxi TOP Pharm Chemical Co., Ltd, Shaanxi Tianrun Phytochemical Co., Ltd, Zhejiang Yiwan Biotechnology Co., Ltd, Lasenor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antistaling Agent Market Evolving Landscape
Biotechnology-derived ingredients and precision fermentation are displacing conventional extraction methods, while regulatory scrutiny of synthetic emulsifiers intensifies formulation complexity.
Precision-fermented phospholipids are virtualizing conventional soy and egg lecithin supply chains. North American plant-based bakery startups are adopting these ingredients at pilot scale within 12-18 month procurement cycles. The technology is virtualizing commodity lipid trading relationships and compressing traditional agricultural commodity hedging strategies in ingredient sourcing.
EFSA's systematic re-evaluation of food additives under the EU food improvement agent framework is narrowing acceptable daily intake thresholds for established emulsifiers. Industrial bread manufacturers in Germany and France are preemptively reformulating with enzyme-based alternatives ahead of potential usage restrictions. The regulatory pressure is most acute in private-label retail bread where ingredient cost sensitivity conflicts with compliance-driven reformulation expenses.
Direct-procurement relationships between bakery cooperatives and specialty ingredient developers are displacing traditional distributor intermediaries in North American markets. Regional flour millers and mid-scale bread producers are consolidating supplier bases to secure technical support for clean-label transitions. This channel restructuring is most visible in the Pacific Northwest and Upper Midwest where cooperative bakery ownership concentrates purchasing leverage.
Antistaling Agent Market Segmentation
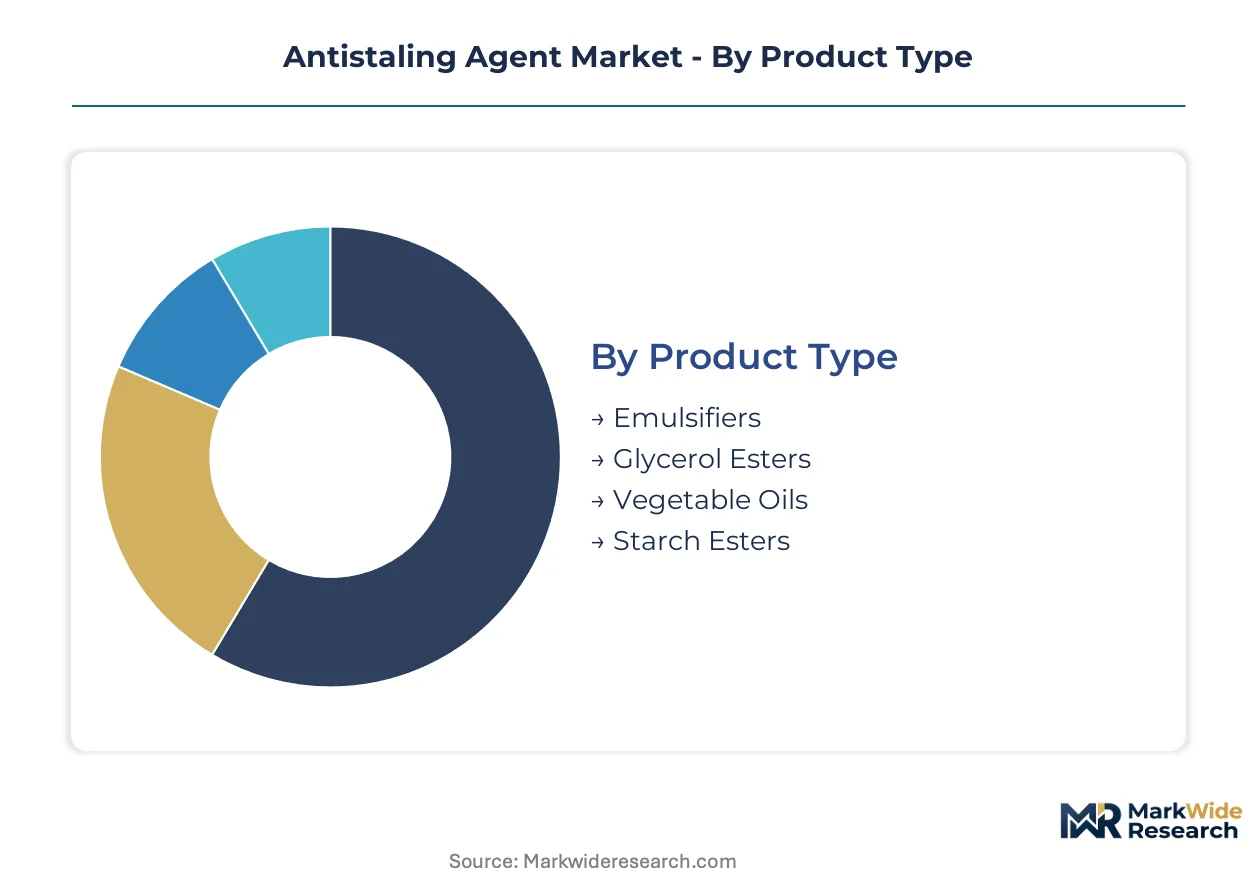
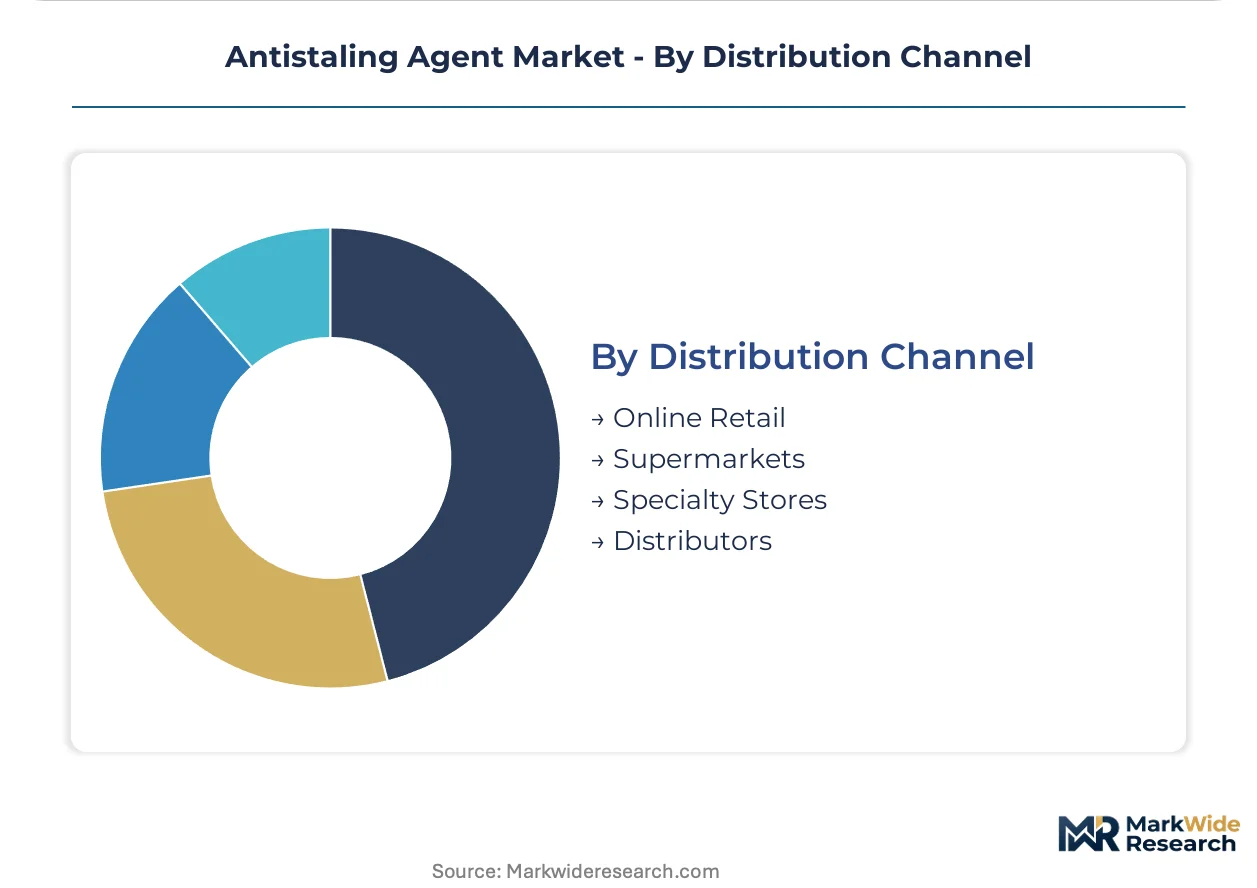
Antistaling agent procurement patterns diverge sharply across product categories and end-use channels, with technical support requirements and formulation complexity driving distinct service intensity levels. Industrial bakeries demand intensive after-sales technical assistance for emulsifier integration, while retail channels prioritize shelf-stable premix solutions with minimal field support.
Product Type:
After-sales service intensity peaks with emulsifier systems requiring precise hydration protocols and compatibility testing against specific flour profiles.
- Emulsifiers:Surfactant compounds including DATEM, SSL, and lecithin derivatives function at 0.5-2.0% inclusion rates to complex with starch and retard retrogradation. Pan bread manufacturers in the United States concentrate procurement here, though EFSA's re-evaluation timeline is compressing reformulation windows. Technical service teams must validate performance across variable water hardness and mixing energy inputs.
- Glycerol Esters:Mono- and diglyceride formulations provide lipid-based moisture retention with cleaner label potential than synthetic surfactants. European dairy and confectionery processors are expanding procurement fastest, drawn by EFSA's favorable stance on naturally derived alternatives. These systems demand less intensive field support but require precise temperature control during dough processing.
- Vegetable Oils:Refined palm and rapeseed oil fractions serve cost-sensitive bakery applications with basic antistaling functionality.
- Starch Esters:Modified starch derivatives from acetylated or hydroxypropyl sources extend shelf life through water-binding rather than surfactant action.
By volume, emulsifiers lead. By growth pace, glycerol esters are climbing the fastest.
Application:
Application-driven cost tiers separate premium-positioned artisan bakery solutions from commodity pan bread formulations.
- Baked Goods:Industrial bread and cake operations command the dominant margin pool, with antistaling performance prioritized over unit ingredient cost. Large-scale manufacturers in Germany and China operate dedicated R&D facilities to optimize emulsifier-starch interactions for 7-14 day shelf life targets. These facilities require continuous technical partnership with ingredient suppliers.
- Confectionery:Chocolate coatings and cream fillings utilize glycerol esters for fat bloom prevention and texture stability. Premium confectionery houses in France and Belgium source specialized lipid systems with documented supply chain traceability.
- Dairy Products:Whipped toppings and processed cheese applications employ antistaling adjuncts to prevent syneresis and maintain mouthfeel.
- Sauces:Starch-based thickening systems in ready-to-serve applications incorporate esterified starches for freeze-thaw stability.
Baked goods generate highest absolute demand, while confectionery applications show steepest expansion trajectory among premium price tiers.
End User:
Customer type determines procurement scale and relationship structure, from multinational food manufacturers to fragmented foodservice operators.
- Food Manufacturers:Industrial bakery and dairy processors with captive R&D capabilities negotiate direct supply agreements and technical service contracts. These relationships span 3-5 year horizons with volume commitments and joint formulation development.
- Restaurants:Chain bakery concepts and central kitchens source through redistributors with limited technical support.
- Catering Services:Institutional foodservice procurement emphasizes cost control over performance optimization.
- Retailers:Private-label bread programs at major grocery chains are consolidating supplier bases to secure clean-label transition support.
Food manufacturers dominate volume procurement, with retailers gaining share fastest through private-label expansion.
Distribution Channel:
Channel maturity varies by geography, with direct procurement displacing traditional intermediaries in developed markets.
- Distributors:Specialty ingredient distributors retain dominance in mid-scale bakery supply, offering technical support and inventory management. German and Dutch distribution clusters serve pan-European bakery chains with consolidated logistics.
- Online Retail:E-procurement platforms are penetrating small-to-medium bakery segments with standardized emulsifier premixes and rapid fulfillment.
- Supermarkets:Mass-market retail channels carry consumer-facing antistaling premixes for home baking applications.
- Specialty Stores:Artisan bakery supply shops cater to craft producers with niche enzyme and botanical solutions.
Distributors maintain volume leadership, while online retail channels show steepest growth curve among emerging procurement modes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulations under 21 CFR govern antistaling agent approvals in the United States, while EFSA's additive reassessment timeline compresses reformulation windows across European industrial bakeries. China's SAMR maintains distinct GB compliance pathways that fragment regional product portfolios.
United States
Industrial bread manufacturers in Chicago and Kansas City procurement clusters prioritize DATEM and SSL emulsifiers for extended-shelf-life pan bread. FDA's 21 CFR labeling requirements mandate common or usual name declarations that complicate clean-label transitions. Midwest flour millers operate dedicated R&D facilities to optimize emulsifier integration against variable regional water hardness profiles.
Germany
EFSA's 2023-2024 emulsifier safety reassessment accelerates demand for enzyme-based alternatives in private-label retail bread manufacturing. The country's federal food safety authority enforces maximum permitted levels that diverge from FDA thresholds. North Rhine-Westphalia hosts concentrated specialty lipid emulsifier production serving pan-European bakery chains with consolidated logistics.
China
SAMR's updated food additive positive list expands approved modified starch categories for domestic cake and pastry processors in Shanghai and Guangzhou. National GB standards impose distinct compliance pathways for imported formulations that favor domestic suppliers. Yangtze River Delta baking clusters drive procurement volume for glycerol ester systems in premium confectionery applications.
France
Premium confectionery houses in Paris and Lyon source specialized lipid systems with documented supply chain traceability for chocolate coating applications. ANSM coordinates with EFSA on additive safety evaluations that shape regional formulation preferences. Île-de-France hosts artisan bakery supply networks adopting enzymatic antistaling ahead of anticipated regulatory restrictions.
India
FSSAI's emerging natural additive recognition framework offers first-mover positioning for enzymatic suppliers targeting Mumbai and Bangalore industrial bakeries. The regulator's clean-label pathway remains under development, creating uncertainty for multinational ingredient approvals. Maharashtra and Karnataka baking clusters expand procurement of botanical-derived shelf-life extenders for domestic bread brands.
Antistaling Agent Market Competitive Landscape
Global chemical conglomerates and regional botanical specialists split the market along technology and geography vectors. European-headquartered multinationals anchor supply relationships through captive emulsifier production networks, while Asia-Pacific ingredient developers concentrate on cost-optimized modified starch categories. Three archetypes dominate: diversified chemical majors with bakery ingredient divisions, lipid emulsifier specialists with European dairy channel focus, and China-based botanical extract suppliers serving clean-label demand. Competitive intensity centers on M&A activity consolidating regional distribution capabilities and strategic partnerships securing precision-fermentation technology access.
Among diversified chemical majors, BASF SE and Evonik Industries AG exemplify the integrated-supply archetype through global production footprints and established industrial bakery technical service relationships. Croda International Plc occupies a position within the botanical-specialist tier, leveraging plant-derived formulation capabilities that align with North American clean-label procurement trends. Chinese ingredient developers including Zhejiang Yiwan Biotechnology Co., Ltd represent the regional-cost-optimization archetype, supplying modified starch and glycerol ester systems to domestic baking clusters under SAMR compliance frameworks.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Croda International Plc |
| Penta Manufacturing Company |
| Huzhou Nanxun Shengtao Botanical Co., Ltd |
| Shaanxi TOP Pharm Chemical Co., Ltd |
| Shaanxi Tianrun Phytochemical Co., Ltd |
| Zhejiang Yiwan Biotechnology Co., Ltd |
| Lasenor |
| Others |
Value Network & Pricing Analysis
Overcapacity in Malaysian palm oil derivative production is compressing monoglyceride contract margins and forcing European emulsifier suppliers toward aggressive volume discounting to defend mill utilization rates. This utilization-driven pricing posture cascades through industrial bakery procurement clusters in Germany and the United States, where long-term supply agreements now embed sliding-scale mechanisms tied to named feedstock indices.
Pricing Analysis
Geographic price spreads between Rotterdam and Shanghai glycerol ester quotations reflect divergent regulatory compliance burdens rather than intrinsic production cost differentials. The dominant structure is contract-based long-term offtake with quarterly price adjustments, where price differentiation hinges on EFSA versus FDA certification tiers and volume scale commitments exceeding 500 metric tons annually. Pricing pressure stems from Indonesian export duty volatility, which compresses margins for buyers locked into fixed-price structures. Small-scale artisan bakeries exhibit highest price sensitivity, while multinational bread manufacturers prioritize performance consistency over unit cost.
Supply Chain Analysis
Upstream palm oil and rapeseed feedstock dependencies anchor antistaling agent production in Malaysia, Indonesia, and Germany, with specialty lipid refinement concentrated in Rotterdam-Antwerp chemical clusters. Raw material supply draws from Malaysian crude palm oil exports, European rapeseed crushing capacity, and Brazilian soy lecithin streams. Single-source vulnerability pervades the European market, where 60% of DATEM and SSL emulsifier capacity resides in North Rhine-Westphalia production sites. Distribution runs through specialty chemical distributors with pan-European logistics networks, though direct procurement relationships are displacing intermediaries in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as clean-label mandates splinter procurement requirements across incompatible regulatory jurisdictions, creating niche openings for botanical specialists and enzymatic developers.
For Market Incumbents: Pre-empt EFSA emulsifier restrictions by accelerating enzyme-based formulation pipelines and securing backward integration into precision-fermented phospholipid capacity. BASF SE and Evonik Industries AG must defend technical service relationships through captive R&D partnerships with Midwest flour millers, while insulating margin pools from Indonesian palm oil volatility via long-term supply contracts with Malaysian plantation groups. For New Entrants and Emerging Players: India's FSSAI clean-label pathway offers underpenetrated white-space for enzymatic suppliers targeting Mumbai and Bangalore industrial bakeries with shortened ingredient declarations. Frozen bakery dough cryoprotectant systems represent a second penetrable segment, where functionality demands outpace established supplier technical support capacity. Go-to-market positioning should emphasize direct technical partnership with regional flour millers rather than distributor intermediation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty lipid emulsifier suppliers with multi-year technical service contracts to pan-European bakery chains. Long-term viability over the next decade rests on regulatory agility rather than scale economies alone. Acquisition targets should demonstrate precision-fermentation technology access or established SAMR compliance pathways for Chinese market entry. The critical inflection signal is EFSA's final DATEM usage threshold determination, which would trigger accelerated reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive palm oil sourcing insulates margin pools from Indonesian export policy volatility. |
| Precision-Fermentation Technology Licensing | Virtualized phospholipid production compresses agricultural commodity hedging requirements for North American buyers. |
| Joint Venture with Regional Flour Millers | Direct R&D partnerships secure clean-label transition support and displace distributor intermediaries. |
| Green Manufacturing Certification Program | EU Green Deal bioeconomy incentives subsidize upcycled starch valorization pilot projects. |
| Long-Term Supply Agreement with Multinational Bakeries | Volume commitments spanning 3-5 years lock in utilization rates against spot market volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR additive registrations, EFSA food improvement agent safety assessments, SAMR GB standard publications, and trade customs data for emulsifier and modified starch categories. Primary interviews engaged technical R&D directors at industrial bakery operations, procurement leads at multinational bread manufacturers, specialty ingredient distribution channel partners, and regulatory affairs specialists navigating EFSA re-evaluation timelines. Bottom-up demand modeling triangulated against top-down chemical industry production capacity assessments.
Forecast inputs span product type segmentation across emulsifiers, glycerol esters, and enzymatic systems; application dimensions including baked goods, confectionery, and frozen dough; end-user archetypes from captive R&D manufacturers to private-label retailers; and regional regulatory cluster divergence. CAGRs derive from regression analysis of historical procurement volume patterns against projected clean-label transition timelines. Industry-specific inputs include EFSA additive reassessment schedules, SAMR positive list expansion trajectories, and palm oil futures curve volatility.
Macroeconomic conditions sit as an overlay; deviation in energy costs, currency exchange rates, or agricultural commodity indices would shift the trajectory. Forecasts reflect assumptions regarding regulatory implementation pacing and substitution elasticity between synthetic and botanical alternatives. Material shifts in EFSA final determinations, FSSAI framework finalization, or Indonesian palm oil export policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Pyranose Oxidase Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
United Kingdom Food Colorants Market