
 Canada Food Colorants Market | 2026-2036
Canada Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Colorants Market Outlook
Plant-based food manufacturers are redrawing colorant procurement priorities across Canada. D.D. Williamson leverages its natural extraction portfolio to anchor supply relationships with clean-label brands. CHR Hansen sustains technical leadership in fermentation-derived pigments. Sensient Technologies competes through specialized beverage color systems that dominate the high-volume carbonated segment.
Food colorants comprise pigments and dyes added to edible products to restore color lost in processing, enhance visual appeal, or standardize appearance across batches; natural variants derive from anthocyanins, carotenoids, and chlorophyllin sources, while synthetics rely on azo and triphenylmethane chemistries with defined maximum permissible limits. Natural dyes now lead product type demand as reformulation mandates from major retail chains reshape supplier qualification criteria. Gel and paste forms command premium positioning within confectionery applications where precision dosing protects margin pools.
Health Canada and the Canadian Food Inspection Agency jointly administer colorant approvals under the Food and Drugs Act, with the Safe Food for Canadians Regulations imposing traceability obligations that elevate compliance costs for imported synthetic portfolios. The CFIA's updated guidelines on plant-based labeling are forcing manufacturers to verify colorant provenance claims through documented supply chain audits. Stakeholders must monitor pending amendments to the List of Permitted Colouring Agents as these revisions will determine which synthetic chemistries retain market access against accelerating natural substitution.
Market Dynamics
Clean-label reformulation mandates from major Canadian grocery retailers are compressing synthetic colorant procurement windows while concentrating supplier qualification decisions within Ontario's food manufacturing corridor.
Growth Catalysts
- Health Canada List of Permitted Colouring Agents updates:Accelerating natural dye approvals for bakery and confectionery applications creates compliant pathways for manufacturers seeking shelf-space with Loblaw and Sobeys.
- Fermentation-derived pigment platforms:Precision fermentation technologies are expanding chromophore yields from microbial hosts, reducing batch-to-batch variability that plagued early natural colorant generations.
- Plant-based protein expansion:Meat and dairy analog producers require color-masking and browning systems that simulate cooked muscle tissue, pulling carotenoid and caramel color volumes upward.
Market Restraints
- Anthocyanin raw material volatility:Grape skin and purple carrot concentrate supplies fluctuate with vintage yields in British Columbia's Okanagan Valley and Ontario's Niagara Peninsula.
- Import dependency for high-purity synthetics:Tariff exposure on azo dye precursors from Asian manufacturing clusters elevates working capital requirements for Canadian distributors.
- CFIA traceability audit costs:Safe Food for Canadians Regulations impose documented supply chain verification burdens that disproportionately burden small-scale natural extract importers.
Strategic Opportunities
- Quebec artisanal food sector:Specialty cheese and craft chocolate producers in Montreal and Quebec City represent underpenetrated demand for premium natural colorant portfolios.
- Precision dosing gel systems:Confectionery manufacturers seek paste-form colorants with embedded viscosity modifiers that eliminate weighing errors on high-speed depositing lines.
- Health Canada novel food ingredient pathway:Accelerated review timelines for fermentation-derived pigments create first-mover advantages for domestic biotech colorant developers.
Industry Challenges
- Natural colorant stability expertise:Formulation chemists capable of managing pH-dependent anthocyanin degradation and light-sensitive carotenoid oxidation remain scarce in Prairie province food science programs.
- Legacy synthetic inventory transitions:Manufacturers holding substantial azo dye stocks face write-down pressure as retail clean-label deadlines compress without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Colorants Market |
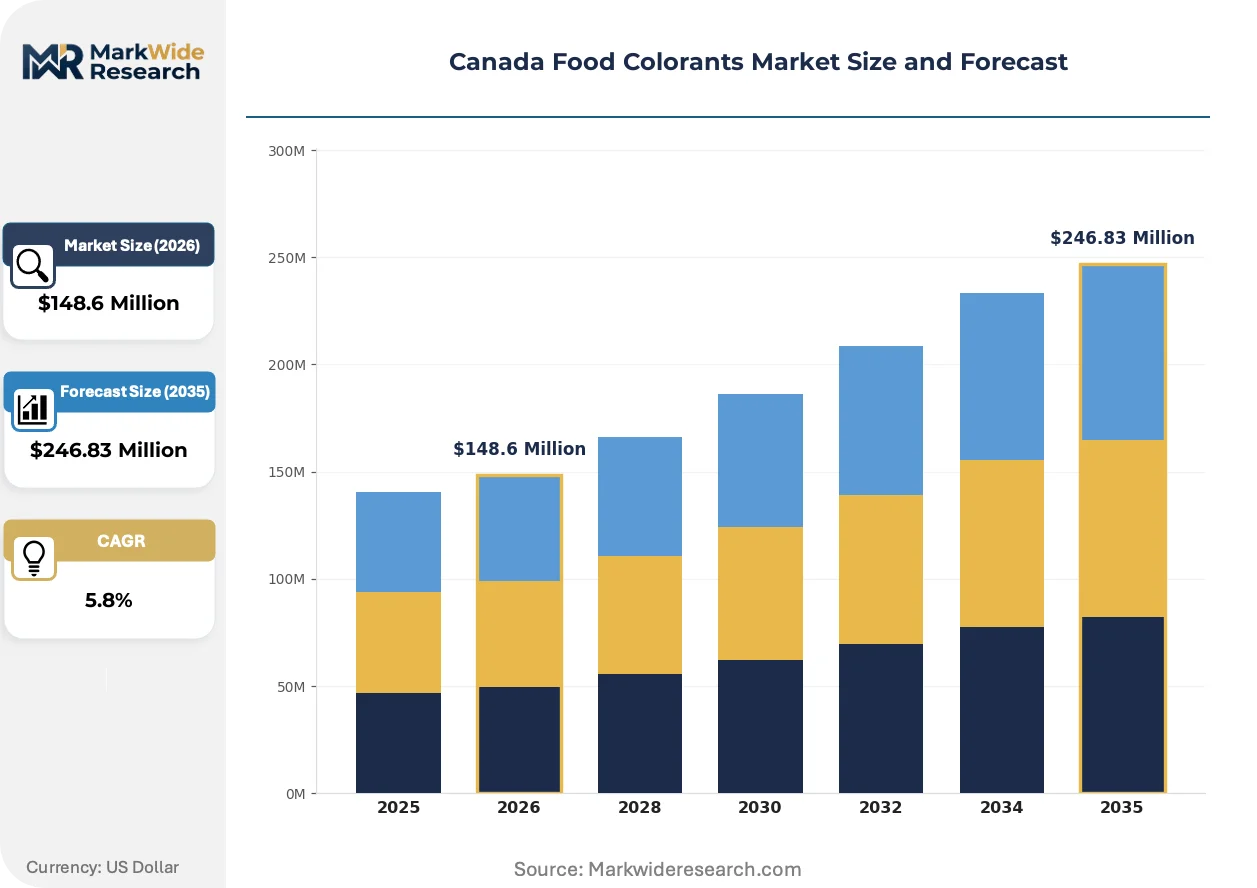
| Market Size in 2026 | $148.6 Million |
| Market Size in 2035 | $246.83 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dyes, Synthetic Dyes, Liquids, Powders Form: Gel, Paste, Liquid, Granular Application: Beverages, Bakery, Confectionery, Dairy End User: Food Manufacturers, Catering Services, Retail Chains, Restaurants |
| Companies Covered | Dohler Group, BASF, CHR Hansen, Naturex, D.D. Williamson, Koninklijke DSM N.V, The Archer Daniels Midland Company, Kalsec, Sensient Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Colorants Market Strategic Shifts
Microencapsulation technologies are resolving the historical trade-off between natural colorant stability and clean-label positioning that constrained bakery and beverage applications for decades.
Encapsulated carotenoid and anthocyanin systems now shield chromophores from oxygen and thermal degradation during extrusion and UHT processing. Large-scale bread and cracker manufacturers in Ontario are adopting these platforms at pilot scale. The technology is displacing unprotected natural dyes that required excessive loading rates and produced off-flavors.
Health Canada's pending amendments to the List of Permitted Colouring Agents will narrow maximum permissible limits for select triphenylmethane synthetics. Reformulation timelines for affected confectionery and beverage SKUs are compressing to eighteen-month windows. Ontario-based contract manufacturers are front-loading natural alternative trials to secure uninterrupted retail distribution.
Direct procurement relationships between colorant suppliers and national grocery private-label divisions are shortening traditional distributor channels. Bakery and plant-based meat categories are most affected, with buyers demanding batch-level certificates of analysis and origin documentation. Western Canada co-manufacturers report the tightest qualification timelines as retail consolidation concentrates purchasing authority.
Canada Food Colorants Market Segmentation
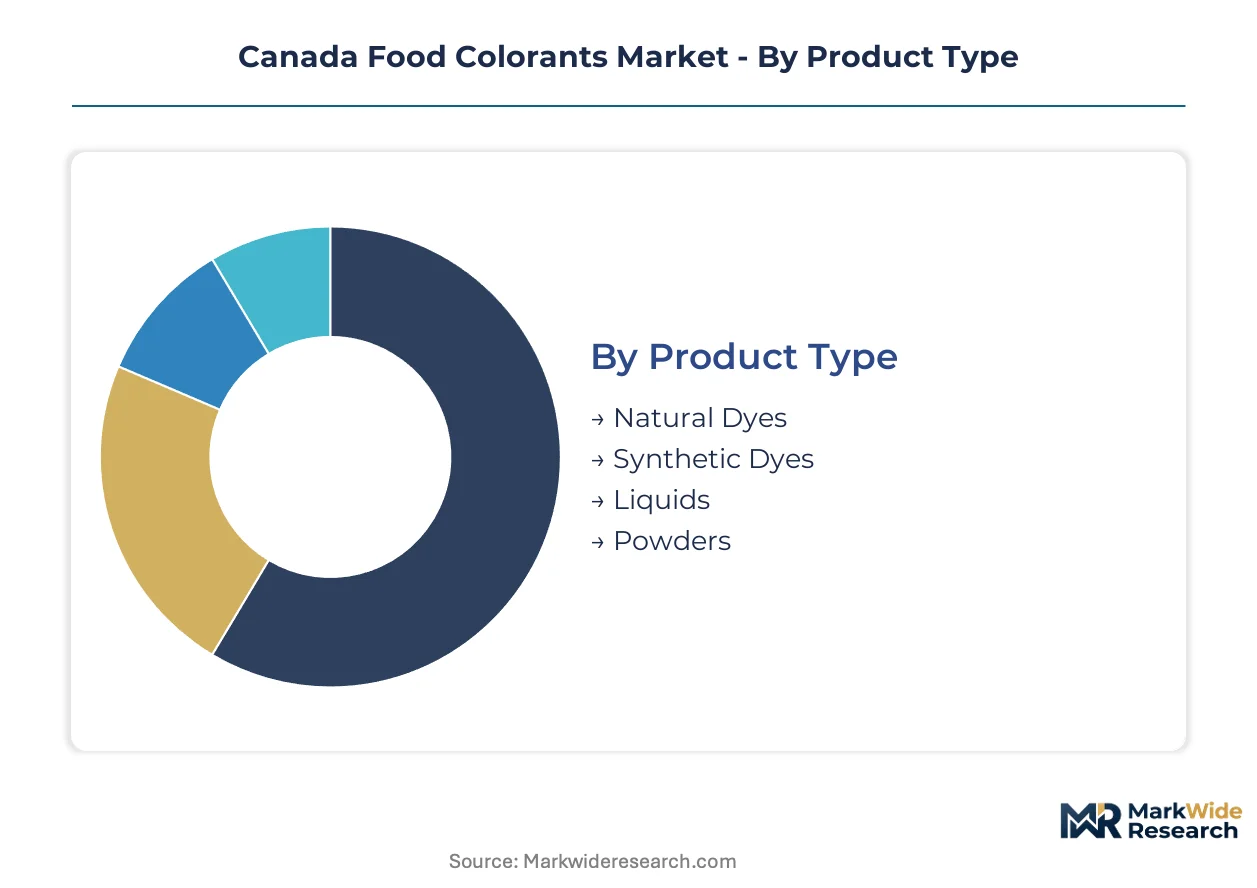
Colorant segmentation in Canada reflects divergent compliance burdens across Health Canada's regulatory tiers. Procurement patterns cluster around reformulation deadlines imposed by major retail chains, with natural alternatives commanding qualification priority.
Product Type:
Health Canada maintains distinct approval pathways for natural versus synthetic colorants under the Food and Drugs Act, creating procurement bifurcation.
- Natural Dyes:Anthocyanin, carotenoid, and chlorophyllin extracts from grape skin, purple carrot, and spirulina sources. Bakery and plant-based meat manufacturers in Ontario's food corridor are accelerating procurement as Loblaw and Sobeys enforce clean-label deadlines without grandfathering provisions.
- Synthetic Dyes:Azo and triphenylmethane chemistries including Allura Red and Tartrazine with defined maximum permissible limits. Confectionery manufacturers face compressed eighteen-month reformulation windows as Health Canada narrows permissible thresholds for select compounds.
- Liquids:Pre-dispersed colorant solutions with standardized viscosity for direct dosing into beverage and dairy processing lines.
- Powders:Dry concentrated pigments requiring reconstitution; preferred by industrial bakeries for extended shelf stability and reduced freight costs.
Natural dyes handle the majority of new qualification activity; synthetic dyes retain volume leadership in legacy confectionery applications.
Form:
Physical form selection correlates directly with manufacturing automation levels and precision requirements across Canadian processing facilities.
- Gel:Viscous semi-solid systems with embedded stabilizers enabling precise volumetric dosing on high-speed confectionery depositing lines. Quebec craft chocolate producers and Ontario industrial candy manufacturers specify gel formats to eliminate weighing errors and protect margin pools.
- Paste:Intermediate viscosity formulations optimized for bakery cream and icing applications where color uniformity must survive mechanical shear during high-speed mixing.
- Liquid:Pumpable dispersions dominating beverage manufacturing in British Columbia and Alberta where continuous-flow processing demands seamless integration with CIP systems.
- Granular:Free-flowing solid particles for dry-blend applications in flour-based mixes and seasoning blends; Prairie province pasta and snack manufacturers favor this form for dust-free handling.
Liquid formats command the highest throughput volumes; gel systems are expanding most quickly as confectionery automation upgrades accelerate.
Application:
End-use segmentation tracks divergent stability requirements across thermal processing regimes and pH environments.
- Beverages:Acid-stable colorant systems for carbonated soft drinks, juices, and functional waters. Microencapsulated carotenoid platforms are displacing unprotected natural dyes in Ontario-based UHT processing operations.
- Bakery:Heat-stable pigments surviving extrusion and oven thermal profiles. Large-scale bread and cracker manufacturers are adopting encapsulated anthocyanin systems at pilot scale to resolve historical off-flavor generation.
- Confectionery:Precision color matching for hard candies, gummies, and coated chocolates where light-fastness and sugar-matrix compatibility determine specification.
- Dairy:Fat-dispersible colorants for cheese, yogurt, and ice cream applications; caramel colors and annatto dominate this segment.
Beverage applications absorb the greatest colorant volumes; bakery represents the steepest expansion trajectory as clean-label bread reformulation spreads.
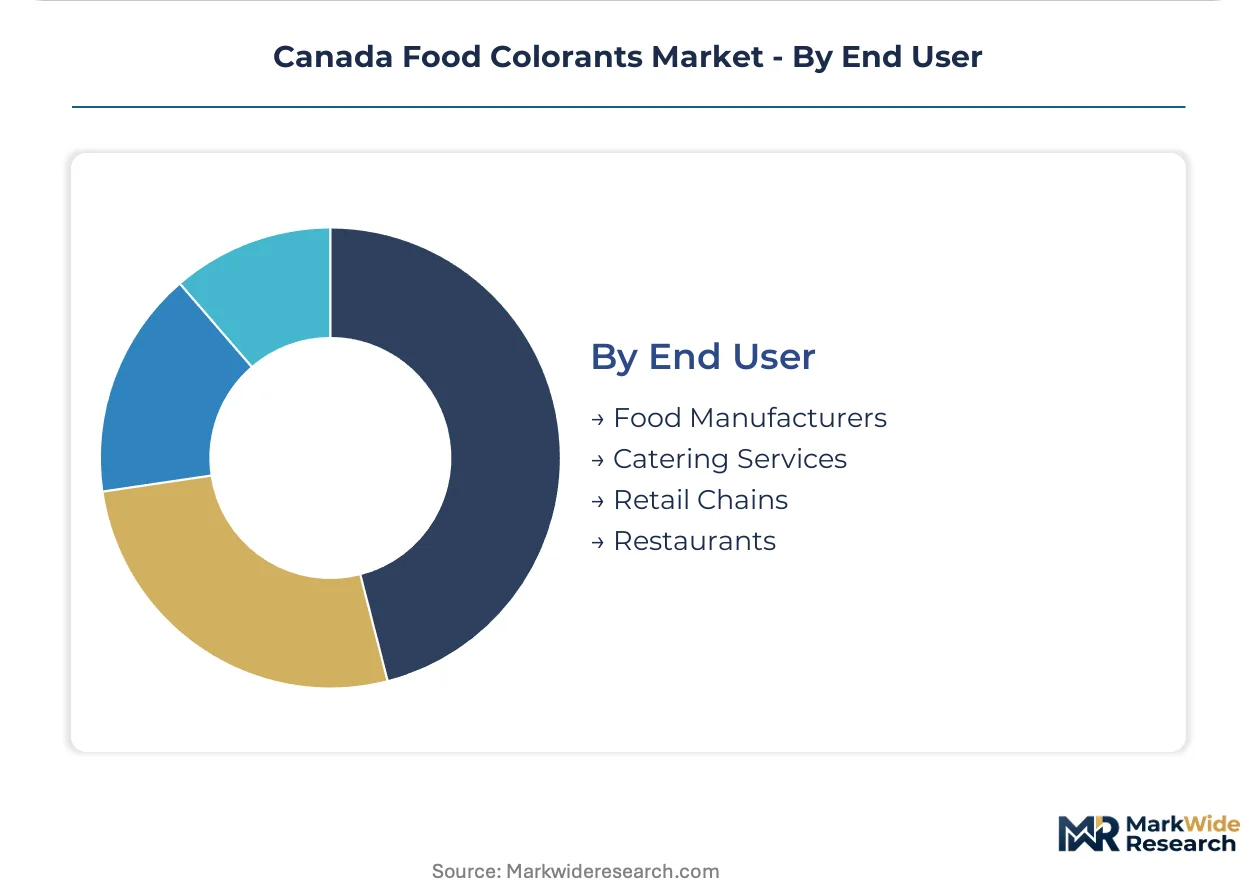
End User:
Customer type segmentation reveals procurement authority concentration within Ontario's manufacturing corridor and retail consolidation effects.
- Food Manufacturers:Industrial-scale processors with direct supplier relationships and batch-level certificate of analysis requirements. Contract manufacturers in the Golden Horseshoe report tightening qualification timelines as grocery private-label divisions centralize purchasing authority.
- Retail Chains:Grocery banners including Loblaw, Sobeys, and Metro imposing clean-label mandates on supplier bases. Direct procurement relationships with colorant suppliers are shortening traditional distributor channels.
- Catering Services:Institutional and event-focused foodservice operations with lower volume requirements and spot purchasing patterns.
- Restaurants:Independent and chain dining establishments sourcing through broadline distributors with limited technical specification involvement.
Food manufacturers dominate procurement volumes; retail chains are gaining share fastest as private-label expansion concentrates specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's food manufacturing corridor concentrates national procurement authority, with Loblaw and Sobeys headquarters driving clean-label mandates that cascade through supplier networks across provincial boundaries.
Ontario
Bakery and plant-based meat manufacturers in the Golden Horseshoe accelerate natural dye procurement as retail deadlines compress without grandfathering provisions. Health Canada's List of Permitted Colouring Agents updates create compliant pathways for reformulation. Toronto and Mississauga host the densest concentration of contract manufacturers front-loading alternative trials.
Quebec
Artisanal cheese and craft chocolate producers in Montreal and Quebec City generate underpenetrated demand for premium natural colorant portfolios. The province's distinct food culture supports specialty ingredient premiums unavailable in mass-market channels. Laval's flavor houses are expanding technical service capabilities to serve these precision applications.
British Columbia
Okanagan Valley grape skin supplies fluctuate with vintage yields, creating raw material volatility for anthocyanin extractors serving national markets. UHT beverage processors in the Lower Mainland adopt microencapsulated carotenoid platforms at pilot scale. Vancouver's functional beverage startups pull novel natural dye volumes upward.
Alberta
Prairie province pasta and snack manufacturers favor granular colorant forms for dust-free handling in dry-blend operations. Cattle feedlot proximity supports annatto demand for dairy applications. Calgary's food ingredient distributors report tightening qualification timelines as retail consolidation concentrates purchasing authority.
Atlantic Canada
Specialty seafood processors require color-masking systems for value-added products, though volumes remain modest against central Canadian benchmarks. Regional distributors face disproportionate CFIA traceability audit cost burdens. Halifax serves as the maritime logistics node for imported natural extract portfolios.
Canada Food Colorants Market Competitive Environment
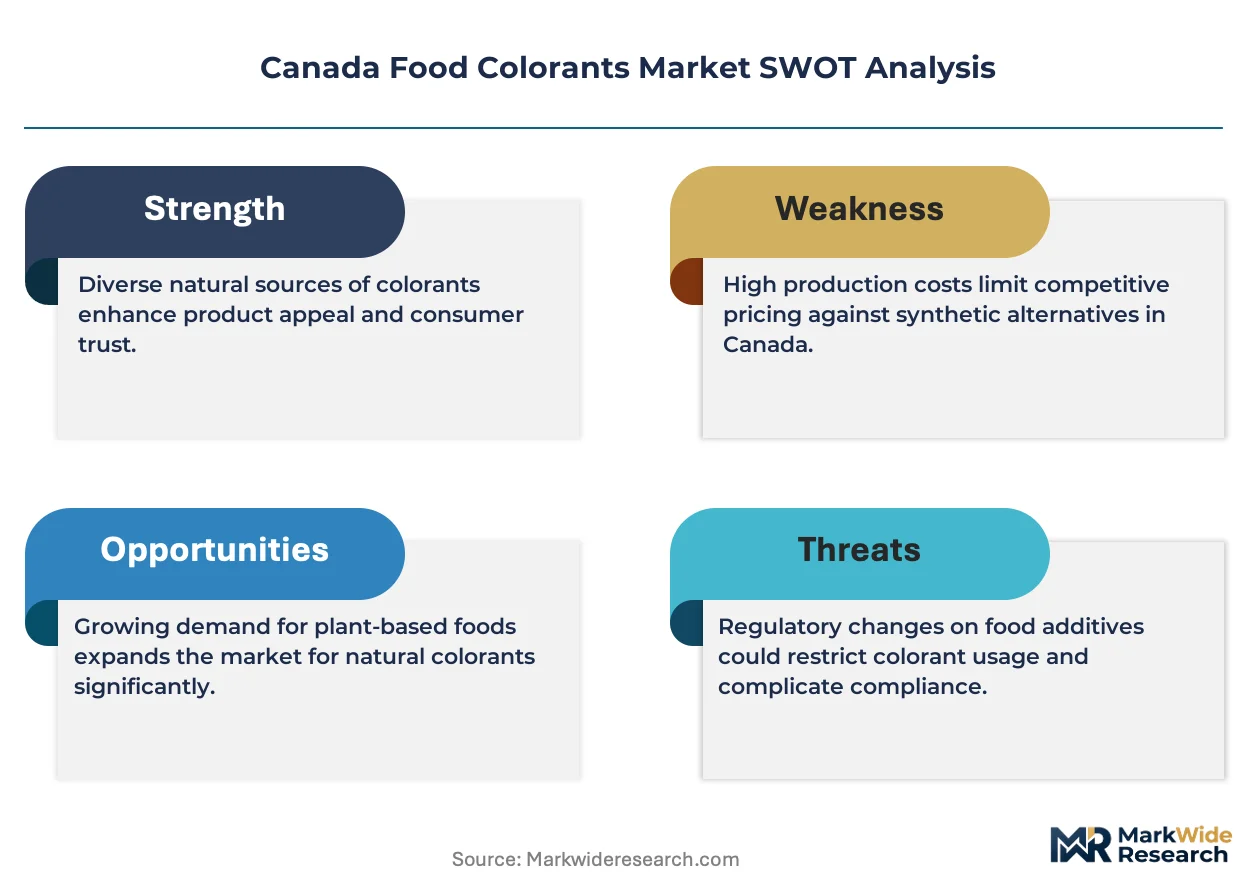
Player mix skews toward multinational ingredient houses with fermentation and extraction capabilities anchoring supply relationships. Market structure concentrates around three strategic tiers: global colorant specialists with full natural-synthetic portfolios, regional natural extractors serving clean-label niches, and diversified nutrition conglomerates integrating colorants within broader ingredient systems. Dominant competitive moves include backward integration into raw material sourcing and technology licensing agreements for precision fermentation platforms.
Among the fermentation-derived pigment specialists, CHR Hansen exemplifies technical leadership in microbial chromophore production, while Sensient Technologies occupies a position within beverage color system specialization. D.D. Williamson represents the natural extraction archetype with its portfolio of plant-derived colorants. These three entities anchor distinct competitive vectors that shape supplier qualification criteria across Ontario's food manufacturing corridor.
| Leading Market Players |
|---|
| Dohler Group |
| BASF |
| CHR Hansen |
| Naturex |
| D.D. Williamson |
| Koninklijke DSM N.V |
| The Archer Daniels Midland Company |
| Kalsec |
| Sensient Technologies |
| Others |
Value Chain & Pricing Dynamics
Health Canada's List of Permitted Colouring Agents gates both supplier qualification and price differentiation simultaneously, with natural dye portfolios commanding premium positioning against synthetic alternatives facing narrowing compliance windows. CFIA traceability audits impose fixed compliance costs that compress margin pools for small-scale importers while concentrating procurement authority with scaled distributors.
Pricing Analysis
Cost-plus contracts with grape skin and purple carrot indexation dominate raw material procurement for anthocyanin extractors serving Ontario's bakery sector. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with organic-certified natural dyes capturing the widest spreads. Cost compression in synthetic portfolios is intensifying because Health Canada's pending amendments are compressing reformulation timelines without grandfathering provisions. Private-label divisions at Loblaw and Sobeys exhibit the highest price sensitivity, while Quebec's artisanal cheese producers demonstrate inelastic demand for specialty colorant portfolios.
Supply Chain Analysis
Inventory cycles for grape skin concentrates extend twelve to eighteen months given vintage dependency in British Columbia's Okanagan Valley and Ontario's Niagara Peninsula. Supply draws from China, India, and the United States for high-purity synthetic precursors, with Canadian distributors maintaining buffer stocks against tariff exposure. Single-source vulnerability concentrates in fermentation-derived pigment platforms where precision fermentation capacity remains tethered to CHR Hansen's Danish production network. Distribution runs through Ontario-based ingredient distributors with direct technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's food colorant market is approaching a platform-economics inflection as retail clean-label mandates force interoperability between supplier certification systems and grocery private-label data architectures.
For Market Incumbents: Compound technical service capabilities in Ontario's Golden Horseshoe to defend against emerging precision fermentation entrants from domestic biotech startups. Deepen backward integration into British Columbia grape skin sourcing to secure captive supply of anthocyanin feedstocks. Lock in multi-year offtake agreements with Loblaw and Sobeys private-label divisions before Health Canada's List of Permitted Colouring Agents amendments narrow synthetic pathways further. For New Entrants and Emerging Players: Health Canada's novel food ingredient fast-track creates compliant pathways for fermentation-derived pigment developers seeking first-mover positioning. Quebec's artisanal cheese and craft chocolate segments represent the most penetrable white-space, with Montreal flavor houses actively expanding technical service bandwidth. Lead with gel-form colorant systems embedding viscosity modifiers that eliminate weighing errors on high-speed depositing lines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation platforms as bioreactor scale-up demands intensify. Target acquisition archetypes include regional natural extractors with established CFIA audit compliance and existing relationships with Ontario contract manufacturers. Watch Health Canada's amendment timeline for the List of Permitted Colouring Agents as the signal indicating acceleration in natural substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive supply of Okanagan grape skins secures anthocyanin extraction capacity against vintage volatility. |
| Precision Fermentation Platform Licensing | Technology transfer agreements with CHR Hansen accelerate domestic microbial pigment production timelines. |
| Direct Retail Procurement Relationships | Bypassing traditional distributors captures margin pools within Loblaw and Sobeys private-label divisions. |
| Microencapsulation Technology Adoption | Ontario bread manufacturers pilot encapsulated carotenoid systems to resolve thermal degradation failures. |
| CFIA Traceability System Investment | Documented supply chain verification satisfies Safe Food for Canadians Regulations audit requirements. |
Study Parameters
The analysis maps natural dye extraction, synthetic colorant formulation, and fermentation-derived pigment platforms, each validated through procurement directors at Ontario contract manufacturers, Quebec flavor house technical leads, and CFIA regulatory affairs specialists. Primary interviews with bakery and beverage plant managers, colorant distributor sales heads, and retail private-label category buyers combined with secondary validation against Health Canada regulatory filings, CFIA enforcement notices, and Canadian Food Inspection Agency trade data. Bottom-up volume estimates from individual processing facilities triangulated against top-down market sizing from ingredient import records.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including colorant source type, physical form, thermal stability grade, and end-use application complexity. CAGRs were derived from regression analysis of historical procurement patterns and projected reformulation timelines. Industry-specific forecast inputs incorporated Health Canada's pending regulatory amendments and retail clean-label deadline schedules.
Underlying assumptions cover stable vintage yields in British Columbia and Ontario grape-growing regions, with deviation risk concentrated in tariff exposure on Asian synthetic dye precursors. Forecasts reflect these assumptions with explicit sensitivity to regulatory timeline acceleration. Revision becomes warranted when Health Canada amendment schedules compress beyond modeled scenarios or when precision fermentation yields inflect materially above baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Semi-Finished Pastry Ingredients Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Australia Food Enzymes Market