
 Motion Positioning Stages Market | 2026-2036
Motion Positioning Stages Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Positioning Stages Market Outlook
Modular platform configurations is recalibrating buyer choice across the precision automation sector. PI Physik Instrumente GmbH & Co. KG leverages its vertically integrated piezoelectric actuator manufacturing to dominate high-resolution positioning. Aerotech Inc. anchors its competitive stance through in-house motion controller development and direct servo drive specialization. Newport Corporation differentiates via optical integration expertise that extends its reach into laser micromachining and semiconductor metrology workflows.
Motion positioning stages are electromechanical assemblies engineered to deliver sub-micron positional accuracy through ball-screw, linear-motor, or piezoelectric drive mechanisms, with travel ranges spanning millimeters to meters depending on application load and precision requirements. These systems serve as foundational infrastructure for semiconductor lithography, microscopy, laser processing, and automated optical inspection where nanometer-scale repeatability determines yield outcomes. Linear stages capture the dominant share of current demand due to their ubiquity in wafer-handling and inspection axes, while multi-axis stages represent the fastest-expanding category as tool builders consolidate degrees of freedom to reduce footprint and alignment complexity. Piezoelectric actuators command premium positioning within the technology hierarchy, particularly in applications demanding picometer-scale resolution where servo and stepper motor alternatives face fundamental noise-floor limitations.
The US Food and Drug Administration's 21 CFR Part 820 quality system requirements shape medical device positioning stage specifications, compelling manufacturers to document traceable calibration protocols and electromagnetic compatibility testing. Europe's REACH regulation and CE marking directives restrict hazardous substance content in electromechanical components while mandating conformity assessment for machinery safety. China's GB standards and Ministry of Industry and Information Technology certification pathways govern domestic equipment procurement, creating parallel compliance tracks for foreign suppliers. Stakeholders must weigh regulatory divergence against platform standardization economics when configuring global product portfolios and regional assembly strategies.
Market Dynamics
Semiconductor lithography tool builders are consolidating multi-axis positioning architectures to compress footprint and eliminate alignment drift between discrete stages, forcing drive technology suppliers to integrate piezoelectric and linear motor capabilities into unified platforms rather than discrete component sales.
Growth Catalysts
- China's domestic lithography buildout:Ministry of Industry and Information Technology procurement mandates for 14nm and below process nodes are creating captive demand for high-precision stages in Shanghai and Beijing equipment clusters.
- REACH substance restrictions:ECHA enforcement against lead and cadmium in electromechanical assemblies is accelerating piezoelectric actuator substitution in European semiconductor and microscopy installations.
- Multi-axis consolidation:Tool builders are collapsing XY-theta configurations into single-platform designs, expanding specification requirements for stages with integrated motion controllers and reduced cabling complexity.
Market Restraints
- Piezoelectric ceramic supply concentration:Lead zirconate titanate feedstock and finished actuator manufacturing concentrate in Japanese and Chinese suppliers, creating vulnerability to export control disruptions.
- Ball-screw precision limitations:Mechanical drive stages face fundamental noise-floor and wear constraints below 100nm repeatability, restricting their addressable market in advanced node lithography.
- CE machinery safety compliance costs:European conformity assessment for multi-axis stages with integrated safety functions adds 12-18 month certification timelines and substantial third-party testing expenditure.
Strategic Opportunities
- Vacuum-compatible stage architectures:EUV lithography and electron microscopy tool builders require outgassing-controlled positioning systems, opening premium positioning for stages with integrated thermal management and particle suppression.
- Laser micromachining convergence:Ultrafast laser processing of medical devices and flexible electronics is creating demand for stages combining high-speed linear motor traverse with piezoelectric fine positioning in single platforms.
- US CHIPS Act facility incentives:Department of Commerce funding for Arizona, Texas, and New York semiconductor fabrication plants is accelerating localization requirements for precision automation suppliers.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of mechanical precision, servo control algorithms, and real-time embedded systems requires specialized talent concentrated in German, Swiss, and Japanese industrial clusters.
- Cleanroom integration complexity:Stage installation in active fabrication facilities demands contamination protocols, vibration isolation, and alignment verification that extend deployment timelines and require specialized field service capabilities.
- Intellectual property fragmentation:Piezoelectric drive patents, linear motor commutation algorithms, and motion control firmware are distributed across Japanese, European, and US holders, complicating platform development freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Positioning Stages Market |
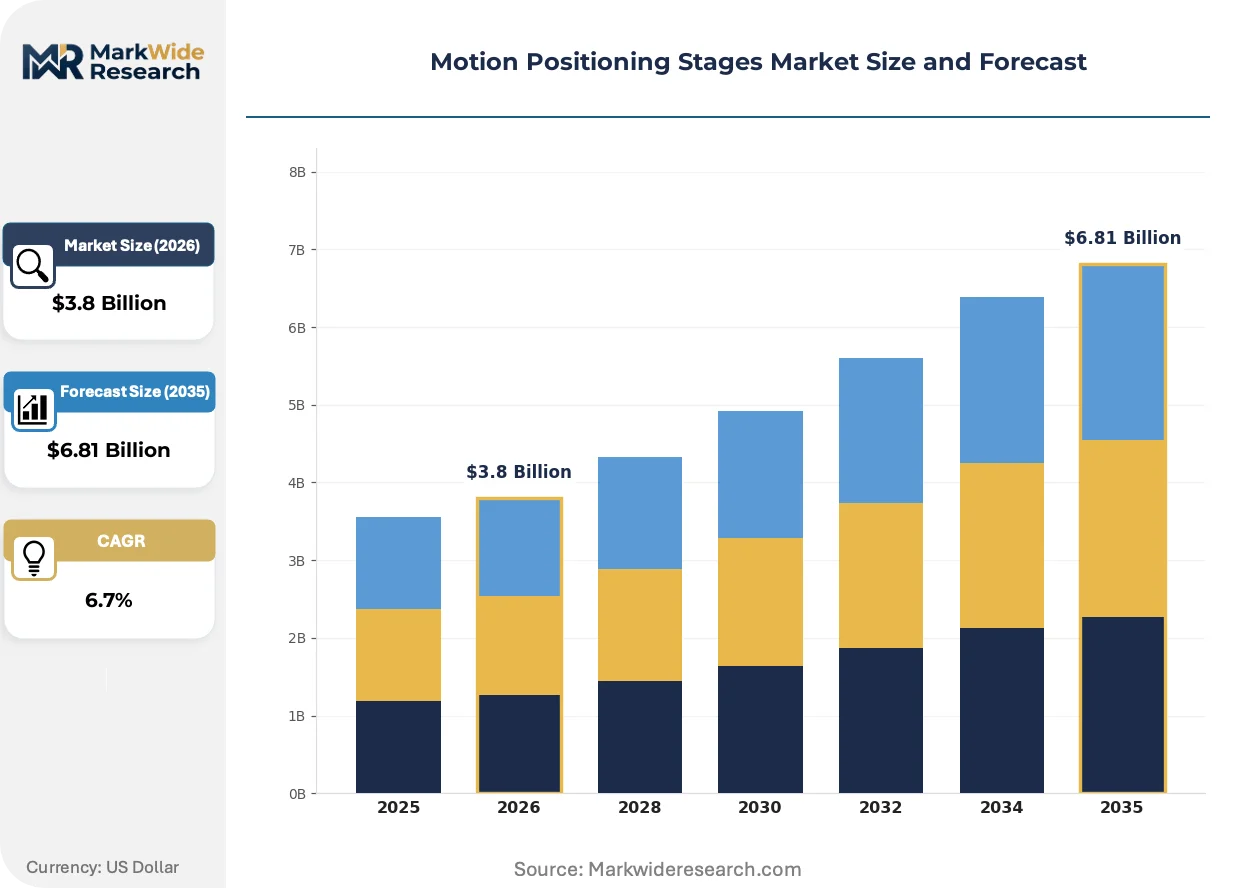
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Stages, Rotary Stages, Goniometric Stages, Multi-Axis Stages End User: Manufacturing, Aerospace, Medical Devices, Research Laboratories Technology: Servo Motors, Stepper Motors, Piezoelectric Actuators, Electromechanical Drives Installation: Table-Top, Rack-Mount, Embedded, Custom Solutions |
| Companies Covered | PI Physik Instrumente GmbH & Co. KG, Aerotech Inc., Newport Corporation, Parker Hannifin Corporation, Thorlabs Inc., MISUMI Corporation, Dover Motion, OWIS GmbH, Zaber Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Positioning Stages Market Strategic Shifts
Positioning stage architectures are converging around integrated mechatronics platforms where mechanical, drive, and control subsystems co-develop rather than assemble from discrete supplier tiers, compressing development cycles and raising performance floors across semiconductor and life science applications.
Magnetic levitation linear drives are expanding into semiconductor wafer-handling and inspection axes where contact-free motion eliminates particle generation and mechanical wear limitations. Leading lithography tool builders in Taiwan and South Korea are specifying maglev stages for critical layer alignment systems. This technology is expanding into adjacent metrology and defect inspection workflows previously served by air-bearing and mechanical drive alternatives.
Europe's REACH regulation and RoHS directive amendments are restricting hexavalent chromium in bearing surfaces and certain rare earth magnet formulations in stage motors, compelling suppliers to qualify alternative coatings and ferrite magnet architectures. Stage manufacturers with European installed bases are restructuring supply chains to document substance compliance across multi-tier component sourcing. The regulatory pressure is most acute in medical device and analytical instrument applications where CE marking mandates cascade through OEM specifications.
Buyers are consolidating vendor relationships around platforms offering unified motion controller ecosystems rather than mixing stage hardware and control electronics across suppliers. Semiconductor capital equipment procurement teams in China and the United States are specifying single-source accountability for multi-axis positioning performance, displacing the prior practice of sourcing mechanical stages and controllers separately. This concentration is most visible in advanced packaging and inspection tool buildouts where system-level warranty terms require integrated subsystem responsibility.
Motion Positioning Stages Market Segmentation
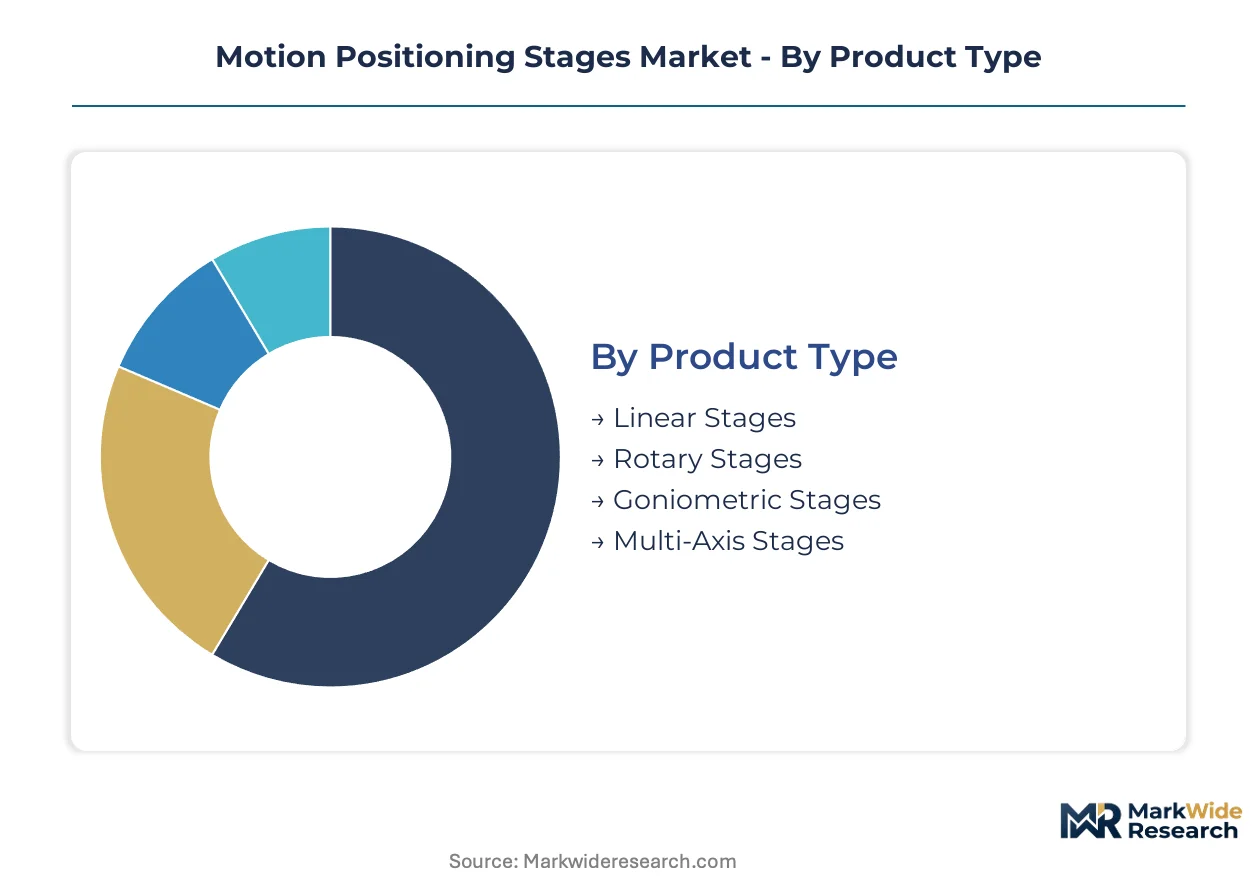
Motion positioning stage buyers prioritize precision specifications, integration complexity, and total cost of ownership differently across application contexts. Semiconductor tool builders demand nanometer repeatability with unified controller ecosystems, while research laboratories trade absolute precision for configurability and capital efficiency.
Product Type:
Application precision requirements and axis-count consolidation drive platform selection across semiconductor, microscopy, and laser processing workflows.
- Linear Stages:Ball-screw and linear-motor driven assemblies deliver X-Y traverse for wafer handling and inspection axes. Demand concentrates in Taiwan and South Korea lithography tool supply chains where sub-100nm repeatability specifications dominate procurement criteria.
- Multi-Axis Stages:Integrated XY-theta and XYZ configurations collapse discrete degrees of freedom into unified platforms with embedded motion controllers. China's domestic equipment buildout for 14nm lithography and advanced packaging is absorbing these systems fastest as tool builders eliminate alignment drift between separate stages.
- Rotary Stages:Direct-drive and worm-gear mechanisms provide theta positioning for sample orientation and optical alignment in metrology workflows.
- Goniometric Stages:Dual-axis angular positioning systems enable cone-angle sampling in X-ray diffraction and electron microscopy specimen manipulation.
Volume sits with Linear Stages; growth tilts toward Multi-Axis Stages.
End User:
Regulatory intensity and contamination tolerance separate buyer segments across capital equipment and analytical instrumentation markets.
- Manufacturing:Semiconductor fabrication and laser micromachining operations demand stages with vacuum compatibility, thermal stability, and particle suppression. REACH substance restrictions in European manufacturing facilities are accelerating piezoelectric actuator substitution for electromechanical drives in precision automation fleets.
- Research Laboratories:Universities and government facilities prioritize modularity, software accessibility, and capital cost containment over absolute performance specifications. US National Science Foundation and Department of Energy facility grants are sustaining procurement volume for configurable table-top configurations.
- Medical Devices:FDA 21 CFR Part 820 quality system requirements compel traceable calibration protocols and electromagnetic compatibility documentation for surgical robotics and diagnostic imaging subsystems.
- Aerospace:Satellite component testing and optical payload alignment require stages with vibration isolation and thermal vacuum operational envelopes.
Manufacturing commands the largest installed base; Medical Devices exhibits the steepest specification escalation.
Technology:
Resolution floor, speed bandwidth, and force density determine drive selection across precision and throughput requirements.
- Piezoelectric Actuators:Lead zirconate titanate ceramic stacks and flexure-guided mechanisms achieve picometer-scale resolution with millisecond response times. EUV lithography and super-resolution microscopy in Japanese and German equipment clusters absorb premium volumes despite Japanese and Chinese supply concentration risks.
- Servo Motors:Brushless DC and direct-drive linear motors deliver high-speed traverse with closed-loop encoder feedback for wafer-handling and inspection axes.
- Stepper Motors:Open-loop positioning suffices for low-speed indexing and coarse alignment where cost containment outweighs dynamic performance.
- Electromechanical Drives:Ball-screw and belt-driven stages serve cost-sensitive applications above 100nm repeatability tolerance.
Piezoelectric Actuators anchor premium positioning; Servo Motors span the broadest application range.
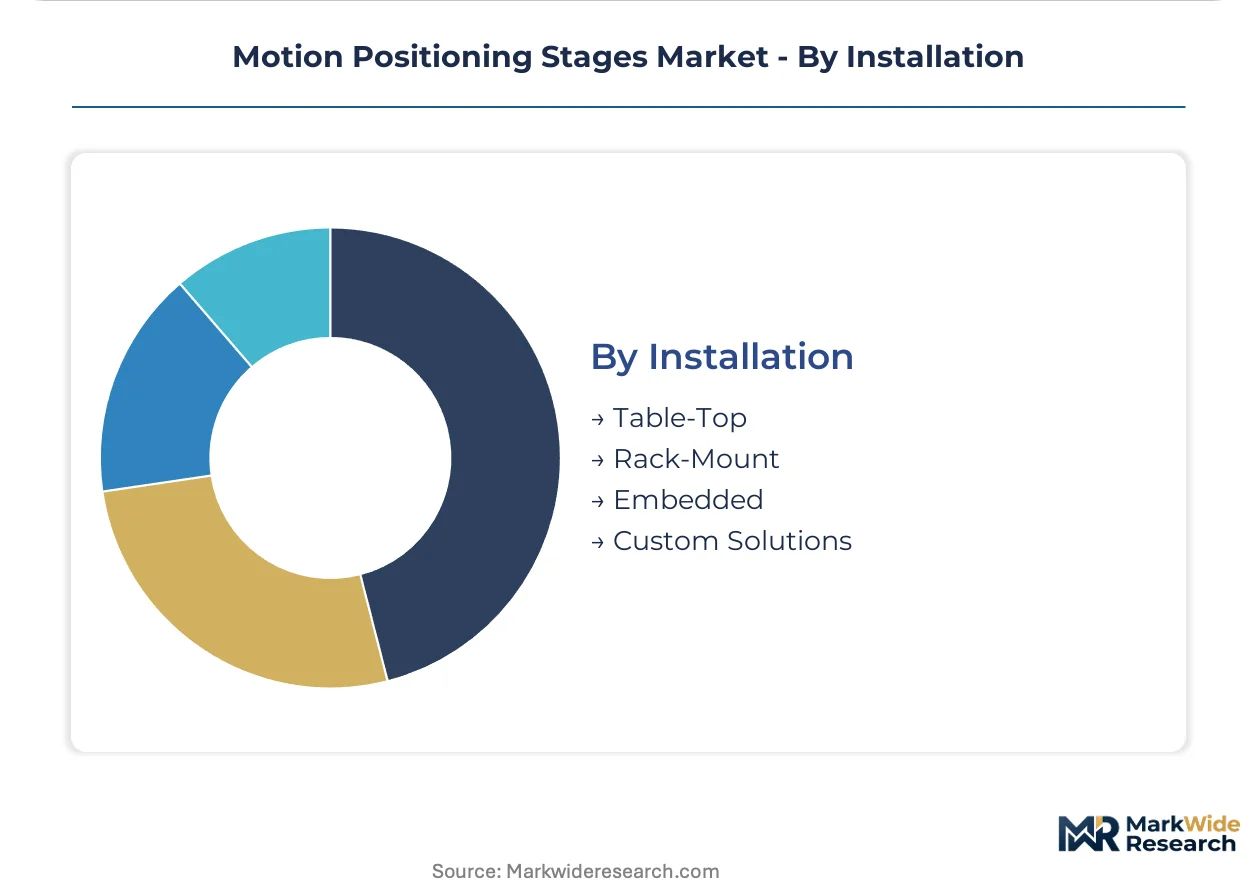
Installation:
Integration depth and field service requirements differentiate procurement approaches across OEM and end-user specifications.
- Embedded:Stage mechanics integrated directly into tool architectures with custom cable management and thermal interfaces. Semiconductor capital equipment builders in China and the United States are specifying embedded configurations with single-source subsystem accountability.
- Table-Top:Self-contained stages with standalone controllers serve research and prototyping environments requiring rapid reconfiguration.
- Rack-Mount:Electronics-separated architectures isolate motion controllers and amplifiers from vibration and thermal sources in cleanroom installations.
- Custom Solutions:Application-specific kinematics, vacuum envelopes, and materials selection for electron microscopy and synchrotron beamline integration.
Embedded configurations dominate semiconductor procurement; Custom Solutions capture the highest engineering margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German, Swiss, and Japanese precision engineering clusters while consumption tilts toward semiconductor fabrication buildouts in Taiwan, South Korea, and China. Equipment procurement patterns diverge sharply between advanced-node lithography investments and legacy node expansions.
United States
CHIPS Act facility incentives in Arizona, Texas, and New York are accelerating localization requirements for precision automation suppliers. FDA 21 CFR Part 820 quality system requirements shape medical device positioning stage specifications. Greater Boston and Silicon Valley clusters absorb premium volumes for semiconductor metrology and life science instrumentation.
Germany
REACH substance restrictions and CE machinery safety directives are pushing manufacturers toward piezoelectric drive alternatives. ECHA enforcement against lead and cadmium in electromechanical assemblies is reshaping procurement criteria. Stuttgart and Munich industrial corridors anchor precision mechatronics engineering talent concentration.
China
Ministry of Industry and Information Technology procurement mandates for 14nm and below process nodes are creating captive demand for high-precision stages. GB standards and MIIT certification pathways govern domestic equipment procurement. Shanghai and Beijing equipment clusters are absorbing multi-axis stage volumes fastest.
Taiwan
Semiconductor fabrication lines are expanding precision automation fleets for advanced packaging and EUV lithography integration. The island's central bank and industrial development bureau coordinate capital equipment financing. Hsinchu Science Park and Tainan Technology Industrial Park host lithography tool builder supply chains.
South Korea
Memory and logic foundry expansions by Samsung and SK Hynix are specifying maglev stages for critical layer alignment systems. MFDS medical device regulations create parallel compliance tracks for surgical robotics applications. Pyeongtaek and Yongin semiconductor clusters drive multi-axis stage procurement.
Motion Positioning Stages Market Competitive Environment
The competitive structure tilts toward vertically integrated specialists with captive piezoelectric actuator manufacturing and in-house motion controller development. Three archetypes dominate: German precision mechatronics houses with full-stack capabilities, US-based laser integration specialists, and Japanese component-scale fabricators. Consolidation pressure is intensifying through strategic partnerships between stage mechanics suppliers and controller firmware developers, while geographic expansion into CHIPS Act beneficiary states accelerates.
Within the premium-tier vector, PI Physik Instrumente GmbH & Co. KG exemplifies the vertically integrated German archetype through its captive piezoelectric actuator production. Aerotech Inc. and Newport Corporation occupy positions among North American specialists with deep optical integration expertise. These three anchors represent contrasting strategic postures: full-stack control, laser micromachining convergence, and semiconductor metrology workflow penetration.
| Leading Market Players |
|---|
| PI Physik Instrumente GmbH & Co. KG |
| Aerotech Inc. |
| Newport Corporation |
| Parker Hannifin Corporation |
| Thorlabs Inc. |
| MISUMI Corporation |
| Dover Motion |
| OWIS GmbH |
| Zaber Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Magnetic levitation linear drive adoption in Taiwan and South Korean lithography tool chains is simultaneously compressing cost curves for contact-free positioning architectures and concentrating procurement leverage among integrated mechatronics suppliers with captive controller development.
Pricing Analysis
Price erosion across standard electromechanical drive tiers traces to Chinese domestic equipment buildout and REACH-mandated piezoelectric substitution in European installations. Three-tier pricing structure across premium maglev configurations, standard servo-motor platforms, and economy ball-screw assemblies separates buyers by repeatability specification and vacuum compatibility requirements. Cost-down pressure on mechanical drive suppliers accelerates because semiconductor tool builders are collapsing multi-axis configurations into unified platforms with embedded controllers. Research laboratories exhibit highest price sensitivity due to grant-funded capital constraints, while EUV lithography tool builders accept premium positioning for picometer-scale resolution.
Supply Chain Analysis
Freight cost volatility and specialized cleanroom logistics requirements are elevating total landed cost for precision stages sourced across German, Swiss, and Japanese production clusters. Lead zirconate titanate ceramic feedstock and finished piezoelectric actuator manufacturing concentrate in Japanese and Chinese suppliers, creating single-source vulnerability to export control disruptions. Stage mechanics production draws from German precision engineering corridors, Swiss mechatronics specialists, and Japanese component fabricators. Distribution runs through semiconductor capital equipment OEMs and analytical instrument builders rather than direct end-user channels. Tariff exposure on precision bearings and rare-earth magnet formulations compounds supply chain fragility for European and North American assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as multi-axis platform specifications force subsystem accountability onto fewer vertically integrated suppliers capable of unified mechanical, drive, and controller co-development.
For Market Incumbents: Extend captive piezoelectric actuator manufacturing advantages into vacuum-compatible stage architectures for EUV lithography applications. Deepen controller firmware development to capture motion control accountability that semiconductor tool builders now demand. Defend against emerging Chinese domestic suppliers by accelerating certification pathways under MIIT and GB standards for Shanghai and Beijing equipment clusters. For New Entrants and Emerging Players: Begin with laser micromachining convergence applications where ultrafast processing of medical devices and flexible electronics demands novel combinations of linear motor traverse and piezoelectric fine positioning. Target research laboratory procurement sustained by US National Science Foundation and Department of Energy facility grants, where modularity and software accessibility outweigh absolute precision specifications. Pursue partnership routes with established motion controller developers rather than competing on full-stack development. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of German and Swiss precision mechatronics houses with captive piezoelectric manufacturing and established semiconductor OEM relationships. Long-term viability over the coming decade hinges on positioning for CHIPS Act facility localization requirements in Arizona, Texas, and New York. Monitor MIIT procurement mandate acceleration for 14nm and below process nodes as the critical inflection signal for captive Chinese supply chain development.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Ceramics | Captive lead zirconate titanate supply secures resolution premium against Japanese and Chinese feedstock concentration. |
| Unified Motion Controller Ecosystem Development | Single-source subsystem accountability displaces prior discrete sourcing of stages and controllers in semiconductor procurement. |
| Vacuum-Compatible Stage Architecture Qualification | EUV lithography and electron microscopy specifications open premium positioning for outgassing-controlled thermal management. |
| CHIPS Act Beneficiary State Facility Establishment | Arizona, Texas, and New York semiconductor fabrication incentives accelerate localization requirements for precision automation. |
| Multi-Axis Platform Consolidation | XY-theta configuration collapse into unified platforms eliminates alignment drift and raises specification barriers for competitors. |
Study Parameters
Multi-period observation of semiconductor capital equipment procurement patterns, REACH regulatory enforcement timelines, and piezoelectric actuator supply concentration anchored the trend analysis, supplemented by interviews with lithography tool builder procurement directors, precision stage design engineers, cleanroom integration specialists, and motion controller firmware developers. Secondary validation drew from SEC filings of listed precision automation suppliers, MIIT equipment certification databases, ECHA substance restriction updates, and customs trade data for precision electromechanical components. Bottom-up segment sizing and top-down market reconciliation triangulated volume and value estimates.
Input-output matrices mapping drive technology selection to end-use precision requirements, regulatory compliance tiers, and geographic procurement mandates structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, drive technology, and installation configuration alongside semiconductor process node specification as an industry-specific demand determinant. CAGRs were derived from fitted growth curves applied to equipment buildout schedules and replacement cycle analysis. Forecast inputs incorporated lithography tool builder capital expenditure plans and domestic equipment substitution rates in China.
Underlying measurement precision varies by segment; piezoelectric actuator and maglev stage volumes carry tighter precision than legacy ball-screw configurations given concentrated supplier visibility. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, export control stability, and semiconductor fabrication capacity expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America and Europe Retail Automation Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Intralogistics Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Monitor Arm Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
North America Human Machine Interface Market